
 Cosmetology Market | 2026-2036
Cosmetology Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetology Market Analysis
ISO 22716 Good Manufacturing Practices certification is rotating as the baseline qualification for contract manufacturers serving premium beauty brands. L'Oréal S.A. leverages integrated R&D pipelines across dermatology and fragrance divisions to sustain innovation velocity. Shiseido anchors its competitive position through biotechnology-driven ingredient discovery platforms. Coty Inc. competes by controlling licensed fragrance portfolios tied to luxury fashion houses.
Cosmetology encompasses the professional practice and commercial supply of products and services for skin health, hair modification, and aesthetic enhancement, relying on emulsion chemistry, active delivery systems, and thermal or mechanical treatment modalities to achieve targeted biological or cosmetic outcomes. Skincare commands the largest revenue pool due to repeat purchase frequency and clinical positioning, while natural and organic ingredient formulations capture the fastest expansion as clean-label expectations migrate from food to personal care. Specialty stores and department stores retain higher margin profiles than mass retail channels because of assisted selling environments and exclusive brand access.
FDA oversight of cosmetic safety under the Modernization of Cosmetics Regulation Act, EU REACH chemical registration requirements administered by ECHA, and state-level cosmetology board licensing in California, New York, and Florida collectively elevate compliance costs while restricting market entry for unqualified operators. Stakeholders must monitor evolving ingredient prohibition lists and pre-market notification timelines to align product development with enforcement trajectories.
Market Dynamics
Reformulation mandates under the EU Green Deal are compressing product development cycles and forcing ingredient substitution across European cosmetology supply chains. Manufacturers face simultaneous pressure from California's Proposition 65 expansion and REACH chemical registration requirements.
Growth Catalysts
- Biotechnology platforms:Enzyme-catalyzed synthesis and fermentation-derived actives reduce petrochemical dependency while meeting clean-label certification standards.
- Spa and wellness center expansion:Service providers in California, New York, and Florida are adding medical-grade aesthetic treatments to capture higher-margin repeat clientele.
- ISO 22716 GMP certification:Premium beauty brands now require this baseline qualification from contract manufacturers, elevating quality barriers and consolidating supplier relationships.
Market Restraints
- Raw material concentration:Specialty emulsifiers and active peptides depend on concentrated production in China's Yangtze River Delta chemical corridor.
- Regulatory friction:FDA pre-market notification timelines under the Modernization of Cosmetics Regulation Act extend launch schedules by 12-18 months for novel ingredients.
- Substitution pressure:Synthetic preservatives face displacement by natural alternatives with shorter shelf stability, increasing spoilage risk and return rates.
Strategic Opportunities
- Underpenetrated men's grooming:Professional service adoption among male demographics in Germany and South Korea remains below saturation thresholds.
- Regulatory tailwind:India's PLI scheme for personal care manufacturing offers capital subsidies for domestic formulation facilities serving ASEAN markets.
- Technology convergence:AI-driven skin diagnostic hardware paired with personalized serum compounding creates subscription revenue models in premium channels.
Industry Challenges
- Formulation chemist scarcity:Qualified professionals capable of navigating simultaneous EU REACH and FDA compliance requirements command premium compensation.
- Certification timeline compression:ECHA substance evaluation deadlines force parallel rather than sequential market registration strategies.
- Legacy ERP integration:Batch record digitization for GMP traceability conflicts with established manufacturing execution systems at mid-sized facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetology Market |
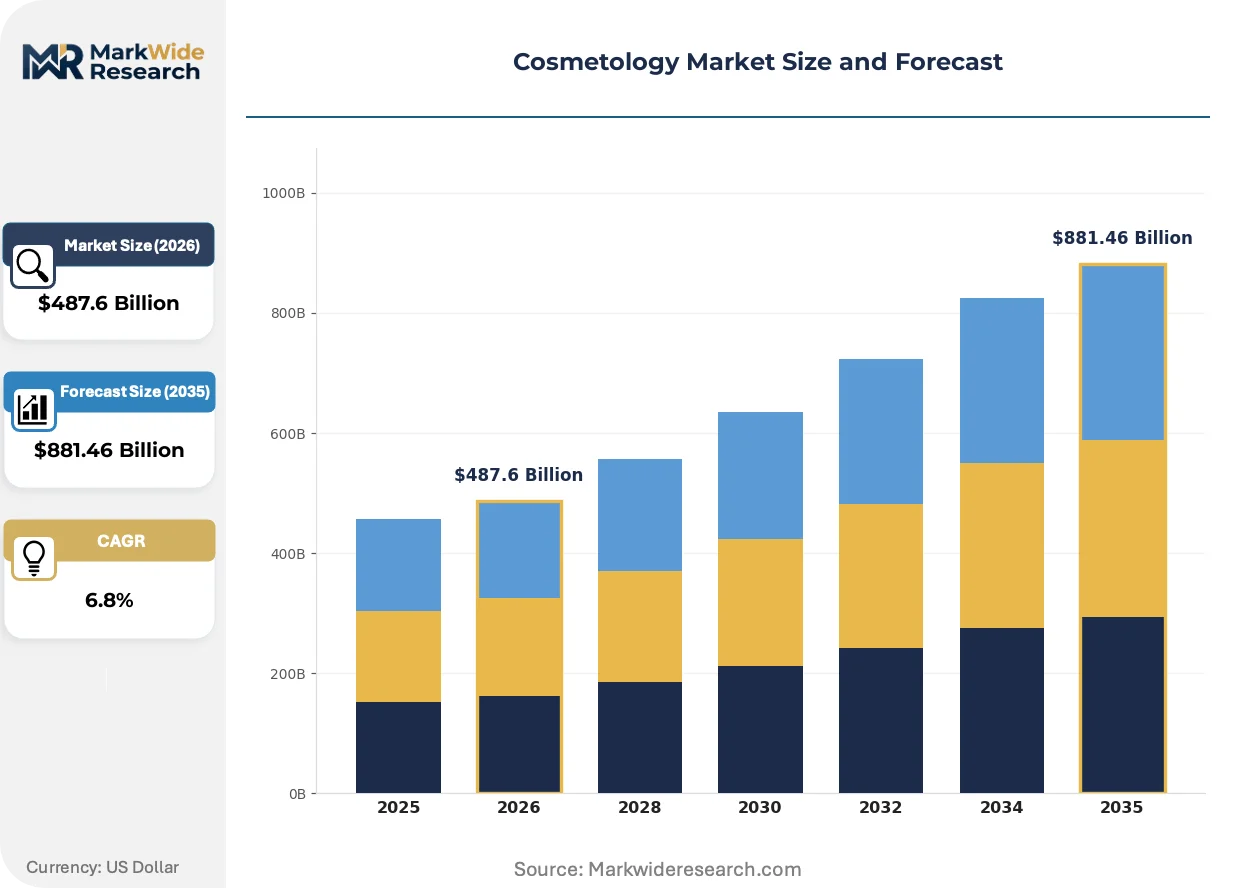
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $881.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Haircare, Fragrances End User: Salons, Spas, Individuals, Retailers Distribution Channel: Online, Offline, Specialty Stores, Department Stores Ingredient Type: Natural, Synthetic, Organic, Mineral |
| Companies Covered | Procter & Gamble, Coty Inc., L'Oréal S.A., Beiersdorf, Kao Corporation, Unilever, Shiseido, Revlon, The Estée Lauder Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetology Market Emerging Trajectories
Biotechnology-derived ingredients and AI-enabled personalization are restructuring competitive advantage away from scale manufacturing toward precision formulation capabilities. Regulatory divergence between major markets is fragmenting global product architectures.
Microbiome-targeted skincare actives produced through precision fermentation are displacing conventional preservative systems and broad-spectrum antimicrobials. Prestige dermatology clinics in Seoul and Manhattan have adopted these formulations for post-procedure recovery protocols. The technology compresses differentiation timelines as patented strain libraries become the primary competitive moat.
EU REACH authorization requirements for endocrine-disrupting candidates are forcing systematic ingredient substitution across sun care and anti-aging categories. Formulators must validate replacement efficacy through clinical testing while maintaining price positioning. German and French manufacturers face the steepest compliance curves given their concentration of heritage brand portfolios.
Subscription-based personalized skincare regimens calibrated through at-home diagnostic devices are capturing high-lifetime-value consumers from traditional retail replenishment cycles. Direct-to-consumer brands in California and Tokyo lead adoption, while department store assisted-selling environments respond with in-store skin analysis services. The shift concentrates customer data ownership with brands rather than retail intermediaries.
Cosmetology Market Segmentation
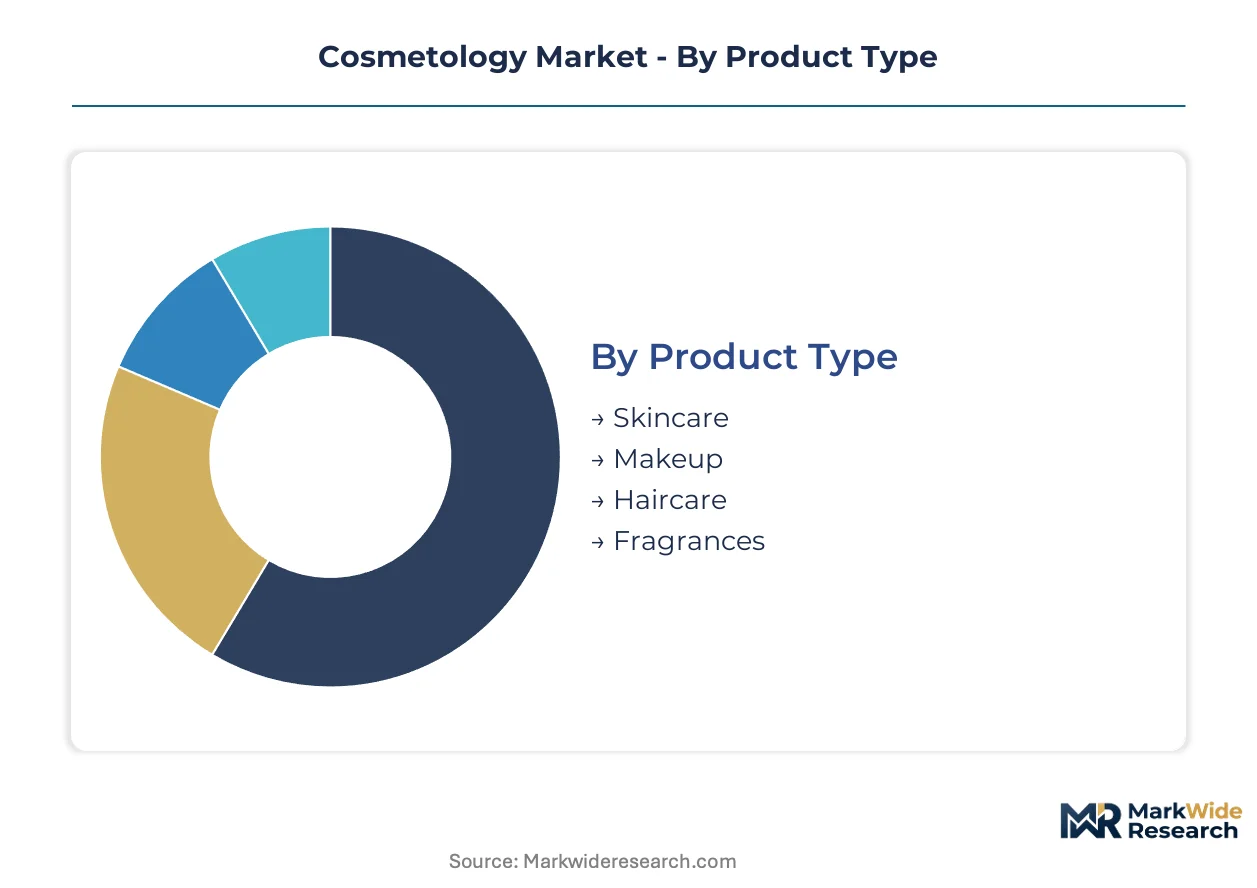
Segmentation in cosmetology separates high-frequency replenishment categories from occasion-driven purchases. Margin capture varies dramatically across these divides, with clinical positioning and assisted selling environments commanding premium pricing power.
Product Type:
Margin pools concentrate in categories with repeat purchase velocity and clinical credibility, while fragrance and color cosmetics compete on brand equity and limited-edition releases.
- Skincare:Emulsion-based formulations with active delivery systems for targeted biological outcomes. Dermatology clinics in California and Seoul drive demand for medical-grade recovery protocols, compressing differentiation timelines around patented active libraries.
- Makeup:Pigment suspension systems and long-wear film formers for aesthetic enhancement. Metropolitan service clusters across New York and Paris anchor professional artistry demand, though social commerce is fragmenting brand loyalty cycles.
- Haircare:Surfactant and conditioning polymer systems for fiber modification and scalp health.
- Fragrances:Alcohol-based volatile compositions with licensed fashion house tie-ins dominating prestige positioning.
Skincare holds installed capacity. Makeup is rotating up the share rankings through social commerce velocity.
End User:
Volume concentration sits with professional service providers who compound product application with technical expertise, while individual consumers drive replenishment frequency through direct channels.
- Salons:Licensed operators delivering chemical and mechanical hair modification services. California, New York, and Florida state cosmetology boards enforce competency standards that elevate service pricing power.
- Spas:Wellness centers integrating advanced aesthetic treatments into service menus. Medical-grade protocol adoption in Seoul and Manhattan captures higher-margin repeat clientele through membership structures.
- Individuals:Direct purchasers for at-home maintenance and personal use.
- Retailers:Intermediary purchasers for inventory stocking across assisted-selling and self-service environments.
Salons command established appointment density. Spas are climbing the fastest through medical-aesthetic convergence.
Distribution Channel:
Assisted-selling environments retain margin superiority through exclusive access and diagnostic services, while digital channels concentrate customer data ownership with brands.
- Online:Direct-to-consumer platforms with AI-driven skin diagnostic integration. Subscription revenue models in California and Tokyo are displacing traditional replenishment cycles through personalized serum compounding.
- Offline:Physical retail encompassing mass and prestige door placements.
- Specialty Stores:Assisted-selling environments with trained beauty advisors. Sephora and Ulta Beauty door placements in the United States sustain higher margin profiles through exclusive brand access.
- Department Stores:Heritage retail formats with in-store skin analysis services responding to digital competition.
Specialty stores defend installed traffic. Online is gaining share fastest through data-capture advantages.
Ingredient Type:
Clean-label migration from food to personal care is restructuring procurement priorities, with biotechnology platforms reducing petrochemical dependency.
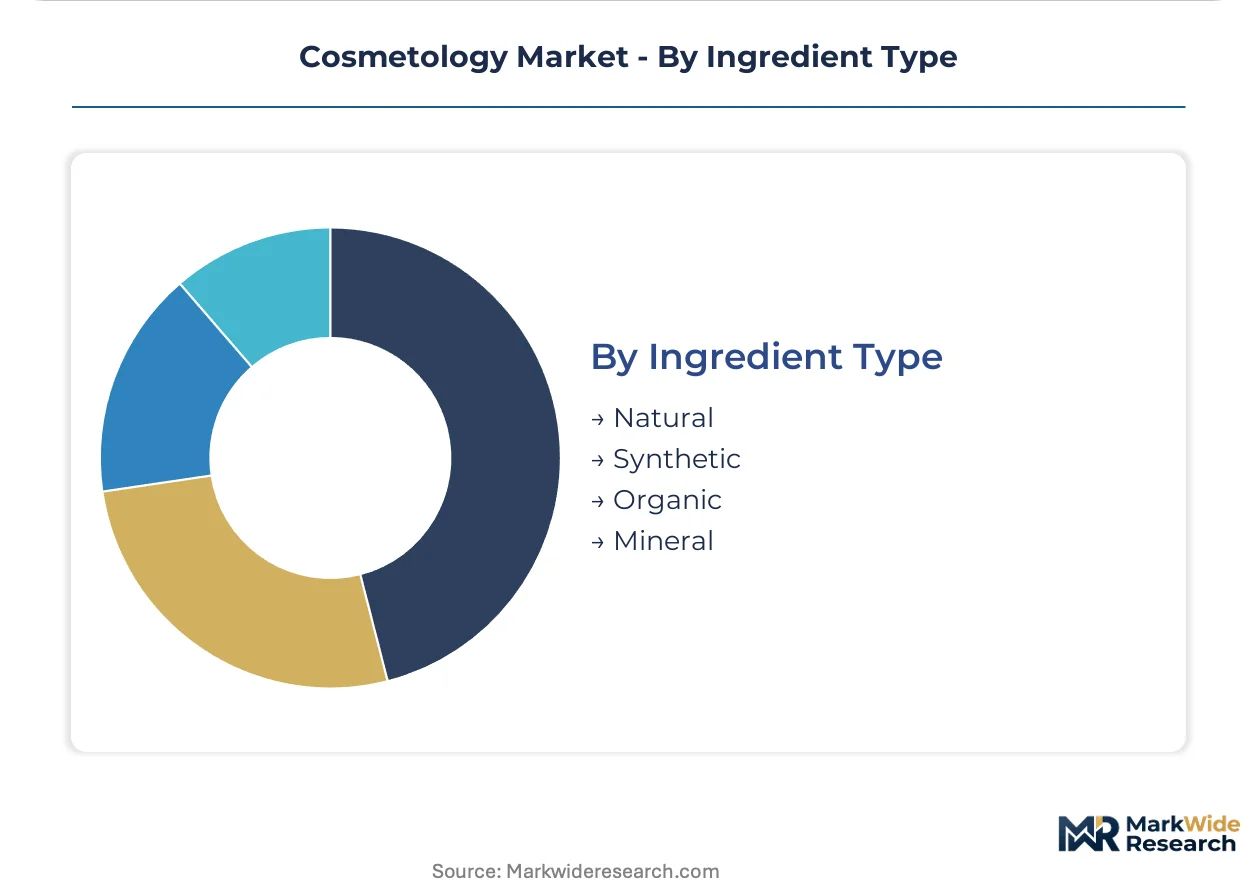
- Natural:Botanically derived actives and carrier oils from cultivated or wild-harvested sources. EU REACH chemical registration requirements are accelerating substitution away from synthetic alternatives.
- Synthetic:Petrochemically derived emulsifiers, preservatives, and performance polymers. China's Yangtze River Delta chemical corridor concentrates specialty emulsifier and active peptide production.
- Organic:Certified cultivation standard ingredients meeting USDA or ECOCERT specifications.
- Mineral:Inorganic UV filters and colorants with reef-safe positioning for sun care formulations.
Natural ingredients hold certified volume. Organic is rotating up the share rankings through premium channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites European formulation supply chains, while the Yangtze River Delta's integrated chemical corridor anchors Asian ingredient production. These logistics assets concentrate procurement decisions and compress delivery timelines for finished goods.
United States
California's Proposition 65 expansion drives reformulation costs for national brands. FDA oversight under the Modernization of Cosmetics Regulation Act extends pre-market notification timelines. Metropolitan service clusters across Los Angeles, New York City, and Miami concentrate professional salon licensing and medical-aesthetic protocol adoption.
Germany
Heritage brand portfolios anchor demand for clinical-positioned skincare. EU REACH authorization requirements administered by ECHA force systematic substitution of endocrine-disrupting candidates. The Rhine-Ruhr chemical corridor concentrates specialty emulsifier and active peptide manufacturing capacity.
China
Domestic consumption of premium skincare outpaces mass-market expansion. NMPA cosmetic registration requirements compress foreign brand entry timelines. The Yangtze River Delta chemical corridor dominates global production of surfactants, conditioning polymers, and fermentation-derived actives.
India
Professional service adoption in tier-2 cities accelerates equipment and consumables demand. The PLI scheme for personal care manufacturing offers capital subsidies for domestic formulation facilities. Maharashtra and Gujarat host emerging contract manufacturing clusters serving ASEAN export markets.
South Korea
Prestige dermatology clinics in Seoul drive medical-grade protocol adoption. MFDS cosmetic safety standards elevate barrier requirements for novel biotech actives. The Seoul Capital Area concentrates R&D facilities for microbiome-targeted and fermentation-derived ingredient platforms.
Cosmetology Market Vendor Landscape
Listed leaders compete with private specialists across portfolio breadth and geographic reach. The vendor base clusters around three structural tiers: integrated conglomerates with dermatology-to-fragrance pipelines, regional specialists anchored in single-category dominance, and private-label contract manufacturers serving retail intermediaries. M&A activity concentrates on biotech ingredient platforms, while capacity expansion targets India's PLI-subsidized manufacturing zones.
Within the integrated conglomerate tier, L'Oréal S.A. and Shiseido occupy positions defined by biotechnology-driven discovery platforms and cross-divisional R&D pipelines. Coty Inc. exemplifies the licensed-portfolio archetype, controlling fragrance distribution rights tied to luxury fashion houses. These three entities represent divergent competitive strategies: vertical integration into ingredient science, horizontal expansion across beauty categories, and exclusive access to fashion-brand equity.
| Leading Market Players |
|---|
| Procter & Gamble |
| Coty Inc. |
| L'Oréal S.A. |
| Beiersdorf |
| Kao Corporation |
| Unilever |
| Shiseido |
| Revlon |
| The Estée Lauder Companies |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between premium beauty brands and contract manufacturers lock in ISO 22716 GMP-certified capacity while anchoring price visibility across California, New York, and Florida service clusters. These arrangements insulate formulation costs from raw material volatility in China's Yangtze River Delta chemical corridor.
Pricing Analysis
Certification level creates the primary spread, with ISO 22716 GMP-grade formulations commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium dermatology clinics, standard professional salons, and economy mass retail channels reflects assisted-selling intensity and clinical positioning. Cost compression in synthetic preservative tiers is intensifying because EU REACH authorization timelines accelerate natural substitution. Individual consumers through direct channels exhibit highest price sensitivity, while medical-aesthetic clinics in Seoul and Manhattan show lowest elasticity due to membership-locked replenishment cycles.
Supply Chain Analysis
Inventory cycles for fermentation-derived actives and specialty peptides extend lead times beyond conventional petrochemical feedstocks. China's Yangtze River Delta chemical corridor, Germany's Rhine-Ruhr industrial zone, and India's Maharashtra-Gujarat emerging clusters concentrate global surfactant, conditioning polymer, and biotechnology platform production. Formulation chemistry draws from concentrated emulsifier and active peptide manufacturing. Single-source vulnerability in China's chemical corridor exposes brands to export license unpredictability under NMPA and dual carbon policy implementation. Distribution runs through contract manufacturing networks serving premium brands, direct-to-consumer platforms, and assisted-selling retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive advantage as AI-driven skin diagnostic hardware converges with personalized serum compounding, creating subscription revenue models that disintermediate traditional retail intermediaries.
For Market Incumbents: Compound defensive moats through captive biotechnology discovery platforms and exclusive strain libraries for microbiome-targeted actives. Backward integration into fermentation-derived ingredient production counters supply concentration risk in China's Yangtze River Delta. ISO 22716 GMP certification investment elevates barriers against mid-tier contract manufacturer encroachment. For New Entrants and Emerging Players: Men's professional grooming service gaps in Germany and South Korea present underexploited white-space with below-threshold penetration rates. India's PLI-subsidized manufacturing zones offer lowest-cost entry for ASEAN export positioning. Direct-to-consumer launch with at-home diagnostic device bundling captures customer data ownership from established retail intermediaries. For Investors and Strategic Acquirers: Biotechnology-enabled contract manufacturers with patented fermentation platforms represent the highest-conviction acquisition archetype for medium-term consolidation. Long-term viability hinges on regulatory navigation capabilities across simultaneous FDA and EU REACH compliance requirements. Watch for ECHA substance evaluation deadline clustering as inflection signal for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Platform Acquisition | Patented strain libraries for microbiome actives displace conventional preservative systems in Seoul and Manhattan clinics. |
| ISO 22716 GMP Certification Investment | Baseline qualification requirement from L'Oréal S.A. and Shiseido consolidates supplier relationships and excludes uncertified competitors. |
| Direct-to-Consumer Diagnostic Launch | AI-driven skin analysis hardware paired with personalized serum compounding captures subscription revenue from traditional retail cycles. |
| India PLI Manufacturing Footprint | Capital subsidies for domestic formulation facilities serving ASEAN markets reduce tariff exposure and logistics costs. |
| Men's Grooming Service Expansion | Professional protocol adoption in Germany and South Korea remains below saturation thresholds with premium pricing potential. |
Methodological Framework
Cross-validation between primary interviews with formulation chemists, spa operations directors, and retail category buyers anchors the qualitative findings against secondary validation. Regulatory affairs specialists at ECHA and FDA-experienced compliance consultants provided enforcement trajectory perspectives. Secondary sources include EU REACH substance evaluation databases, FDA Modernization of Cosmetics Regulation Act guidance documents, and California Proposition 65 chemical listings. Bottom-up service provider capacity estimates and top-down ingredient production volumes triangulate market sizing.
Sensitivity analysis across biotechnology adoption rates, regulatory timeline compression scenarios, and raw material cost volatility bounds the projection range. Segmentation dimensions modeled encompass product type, end user archetype, distribution channel format, and ingredient certification tier across the analysis window. CAGRs derive from installed base growth, replenishment frequency shifts, and premium channel expansion patterns. Forecast inputs incorporate EU Green Deal reformulation mandates and India's PLI scheme uptake trajectories.
Forecasts assume regulatory continuity in FDA, ECHA, and NMPA regimes; material policy shifts would require re-modeling. Specific risks include REACH authorization deadline clustering, Proposition 65 chemical list expansion, and NMPA cosmetic registration timeline unpredictability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
Brazil Dermocosmetics Market
Beauty & Personal Care
South Korea Beauty Fridges Market
Beauty & Personal Care
Hand Care Products Market
Beauty & Personal Care
Mens Intimate Care Products Market
Beauty & Personal Care
Germany Beauty Industry Market
Beauty & Personal Care
Facial Makeup Setting Spray Market
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
Pore Strips Market
Beauty & Personal Care
Anti Stretch Mark Products Market
Beauty & Personal Care
Europe and Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
Lip and Cheek Tint Market
Beauty & Personal Care
Face Oil Market
Beauty & Personal Care
Facial Wipes Market
Beauty & Personal Care
Intimate Hygiene Products Market
Beauty & Personal Care
Cosmetics Foundation Market