
 Europe Sustainable Personal Care Market | 2026-2036
Europe Sustainable Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sustainable Personal Care Market Analytics
REACH is decoupling petrochemical-derived formulations from shelf eligibility across European retail channels. Unilever PLC leverages its Home Care and Personal Care divisions to sustain integrated supply chains for biodegradable surfactants. L'Oréal Group anchors its competitive stance through biotechnology R&D platforms that cultivate lab-synthesized active ingredients. Weleda AG specializes in biodynamic cultivation contracts that control raw material provenance from field to finished good.
Europe sustainable personal care encompasses formulations manufactured with renewable feedstocks, biodegradable chemistries, and packaging designed for circular recovery, typically meeting ISO 16128 natural and organic cosmetic criteria. The segment serves consumers seeking reduced aquatic toxicity profiles and supply chain traceability verified through third-party certification. Ingredient source segmentation shows organic and natural claims commanding premium shelf positioning, while synthetic-free formulations attract regulatory preference under ECHA hazard assessment protocols. Packaging type segmentation reveals refillable systems capturing urban retail growth, with bioplastic and glass formats competing for dominance in prestige and masstige channels respectively.
EMA cosmetic ingredient guidelines, ECHA REACH restrictions on microplastics, and EU Green Deal carbon border adjustments collectively elevate compliance costs for non-conforming suppliers. The CSRD disclosure mandate further binds corporate reporting to verified environmental impact metrics across personal care portfolios. Stakeholders must monitor regulatory alignment between national transpositions and Brussels-level enforcement to anticipate which formulation classes retain market access.
Market Dynamics
REACH restrictions on microplastics and the EU Green Deal's carbon border adjustments are decoupling petrochemical-derived formulations from shelf eligibility across European retail channels. This regulatory compression is forcing rapid supply chain reconfiguration toward biodegradable feedstocks and circular packaging systems.
Growth Catalysts
- EU Green Deal carbon border adjustments:These mechanisms penalize high-carbon imports, creating competitive advantage for domestic bioplastic and bio-based surfactant producers serving German and French retailers.
- Biodegradable surfactant chemistry:Enzymatic and fermentation-derived cleaning agents now match petrochemical performance at scale, enabling mass-market adoption across body wash and shampoo categories.
- Urban refill infrastructure:Concentrated retail networks in London, Paris, and Berlin are installing in-store dispensing systems that cut packaging intensity by over half per consumer.
Market Restraints
- Organic feedstock price volatility:Coconut and palm kernel oil derivatives fluctuate with tropical harvest cycles and El Niño patterns, compressing margin predictability for natural surfactant formulators.
- Bioplastic production concentration:European capacity for PLA and PHA packaging materials clusters in Italy and the Netherlands, creating single-source vulnerability for brands seeking domestic supply.
- REACH registration timelines:Novel biodegradable preservatives face 18-36 month safety dossier reviews, delaying product launches versus conventional chemistry alternatives.
Strategic Opportunities
- CSRD disclosure mandate:Mandatory sustainability reporting creates service revenue for certification bodies and software platforms verifying supply chain carbon intensity across personal care portfolios.
- Eastern European retail penetration:Poland, Romania, and Czech Republic maintain underdeveloped sustainable personal care shelf space relative to Western European saturation levels.
- Biotechnology-platform ingredient synthesis:Lab-cultured squalane and hyaluronic acid bypass agricultural land use, appealing to vegan-positioned brands in the United Kingdom and Scandinavian markets.
Industry Challenges
- ISO 16128 certification backlog:Third-party auditors face 6-9 month queues for natural and organic cosmetic standard verification, delaying product launches and seasonal marketing windows.
- Legacy equipment retrofit costs:Converting filling lines from rigid bottles to flexible refill pouches requires capital outlays that strain mid-tier brand cash flows.
- Biodynamic cultivation expertise scarcity:Qualified agronomists for controlled raw material provenance contracts remain concentrated in Germany and Switzerland, limiting geographic expansion of field-to-finished-good models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sustainable Personal Care Market |
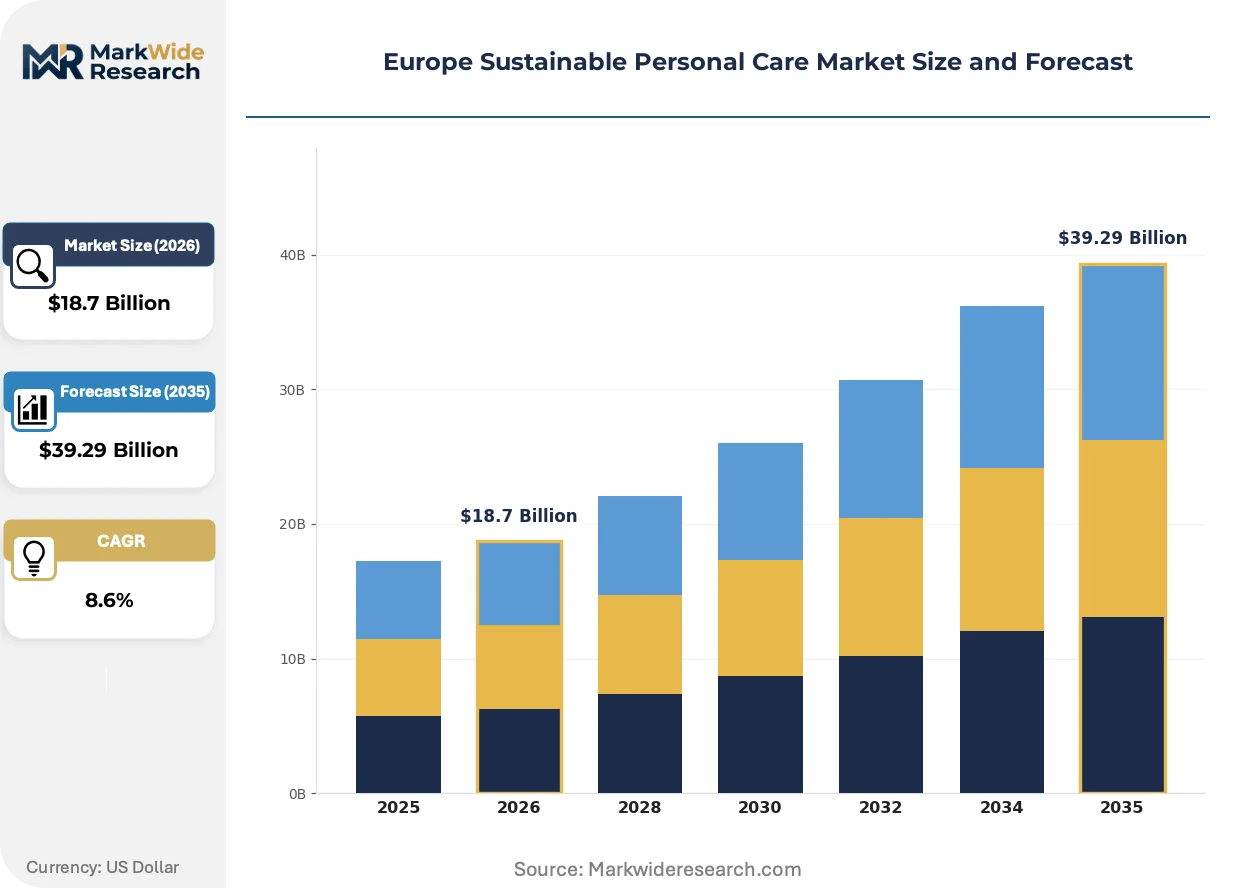
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Body Wash, Face Creams Consumer Base: Millennials, Gen Z, Eco-Conscious Consumers, Luxury Shoppers Ingredient Source: Organic, Natural, Synthetic-Free, Biodegradable Packaging Type: Recyclable, Bioplastic, Glass, Refillable |
| Companies Covered | L'Oréal Group, Unilever PLC, The Procter and Gamble Company, Beiersdorf AG, The Colgate-Palmolive Company, Estee Lauder Companies, Inc., Coty, Inc., L'OCCITANE Group, Weleda AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sustainable Personal Care Market Evolving Landscape
Biotechnology-derived actives and circular packaging formats are compressing the cost-performance gap between sustainable and conventional personal care. These shifts are reconfiguring competitive advantage around supply chain transparency and carbon-verified manufacturing rather than marketing claims alone.
Precision fermentation platforms for cosmetic actives are expanding into commercial scale operations across the Netherlands and Denmark. Mid-market brands in France and Germany are adopting these biosynthesized ingredients at twice the pace of prestige labels. This technology is expanding into territory previously dominated by botanical extraction, collapsing the premium pricing structure for natural-origin claims.
ECHA's microplastic restriction under REACH Annex XVII is eliminating synthetic glitter, microbeads, and certain film-forming polymers from rinse-off cosmetics. Formulators are pivoting toward cellulose-based exfoliants and mineral alternatives, with German manufacturers investing most aggressively in compliant ingredient pipelines. The restriction hits body scrub and toothpaste segments hardest, where visual texture historically drove consumer preference.
Urban consumers are consolidating purchases around ESG-verified brands accessible through direct-to-subscription channels. Traditional drugstore and supermarket shelf space in London and Stockholm is losing traffic to refill-at-home models and brand-owned digital storefronts. This behavioral pivot concentrates demand among digitally native brands that control their own carbon accounting and ingredient storytelling.
Europe Sustainable Personal Care Market Segmentation
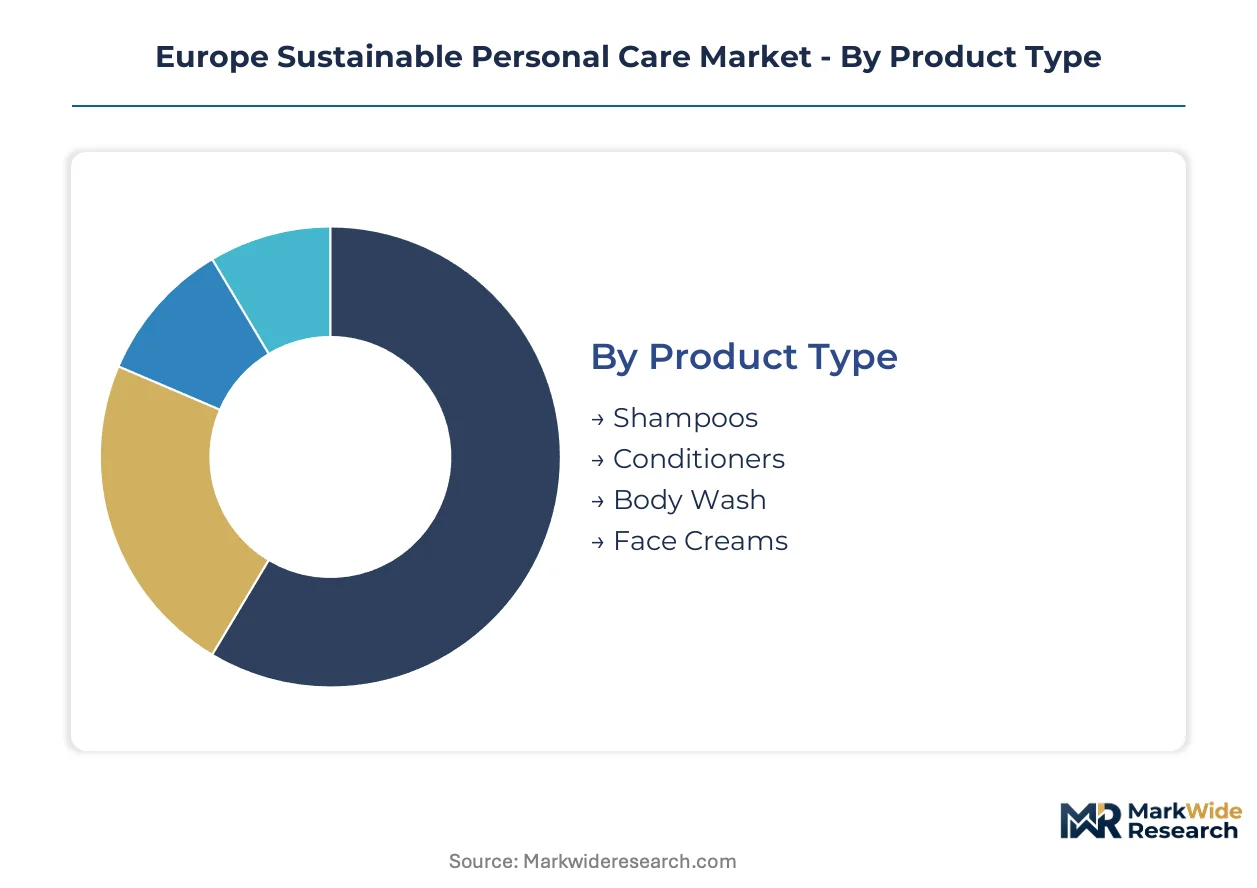
Segmentation in European sustainable personal care reveals how regulatory pressure and generational purchasing patterns split demand across formulation chemistry, material provenance, and circular packaging infrastructure. Distinct consumer cohorts and compliance requirements create non-overlapping addressable markets within the same geographic footprint.
Product Type:
Formulation chemistry and rinse-off versus leave-on exposure profiles determine regulatory scrutiny intensity and shelf positioning economics.
- Shampoos:Biodegradable surfactant formulations dominate R&D investment, with German and French manufacturers prioritizing enzymatic-derived cleaning agents that satisfy ECHA REACH aquatic toxicity thresholds. Urban refill infrastructure in Berlin and Paris concentrates demand for concentrated formats that reduce packaging mass per wash cycle.
- Face Creams:Leave-on applications face stricter preservative safety dossier requirements under ECHA protocols, extending registration timelines. Biotechnology-platform actives from Netherlands-based fermentation facilities are displacing botanical extracts in premium positioning across UK and Scandinavian markets.
- Conditioners:Cationic surfactant alternatives from renewable feedstocks match silicone performance in masstige channels.
- Body Wash:Highest volume category with compressed margins; microplastic-free exfoliant reformulations dominate compliance-focused development pipelines.
Shampoos lead on scale; face creams lead on momentum.
Consumer Base:
Purchasing authority clusters around digitally native cohorts with elevated willingness-to-pay for verified carbon accounting and ingredient traceability.
- Gen Z:Subscription-native buyers consolidate spending around direct-to-consumer brands with transparent supply chain storytelling. Refill-at-home models in London and Stockholm capture disproportionate share of this cohort's personal care expenditure versus traditional retail.
- Eco-Conscious Consumers:Certification-driven purchasers prioritize ISO 16128-verified natural and organic claims, accepting price premiums for third-party audited provenance. Demand concentrates in German-speaking markets where biodynamic cultivation narratives resonate with established wellness retail networks.
- Millennials:Transitioning from conventional to sustainable formulations through masstige brand line extensions.
- Luxury Shoppers:Prestige channel buyers seeking biotechnology-derived actives with performance parity to synthetic benchmarks.
Eco-conscious consumers anchor volume stability; Gen Z drives channel restructuring fastest.
Ingredient Source:
Raw material provenance determines compliance pathway under EU Green Deal carbon border adjustments and ECHA hazard assessment protocols.
- Biodegradable:Formulations engineered for rapid aquatic decomposition command regulatory preference as ECHA microplastic restrictions eliminate conventional polymer alternatives. German manufacturers lead commercial scale production of fermentation-derived surfactants that match petrochemical performance.
- Organic:Certified cultivation contracts with controlled field-to-finished-good traceability support premium shelf positioning. Supply concentrates in biodynamic farming clusters across Germany and Switzerland, constraining geographic expansion of verified organic claims.
- Natural:ISO 16128-compliant botanical extracts facing certification backlog delays at third-party auditors.
- Synthetic-Free:Positioning strategy avoiding petrochemical-derived inputs entirely; narrowest addressable market with highest price realization.
Organic claims dominate premium positioning; biodegradable specifications gain regulatory tailwind fastest.
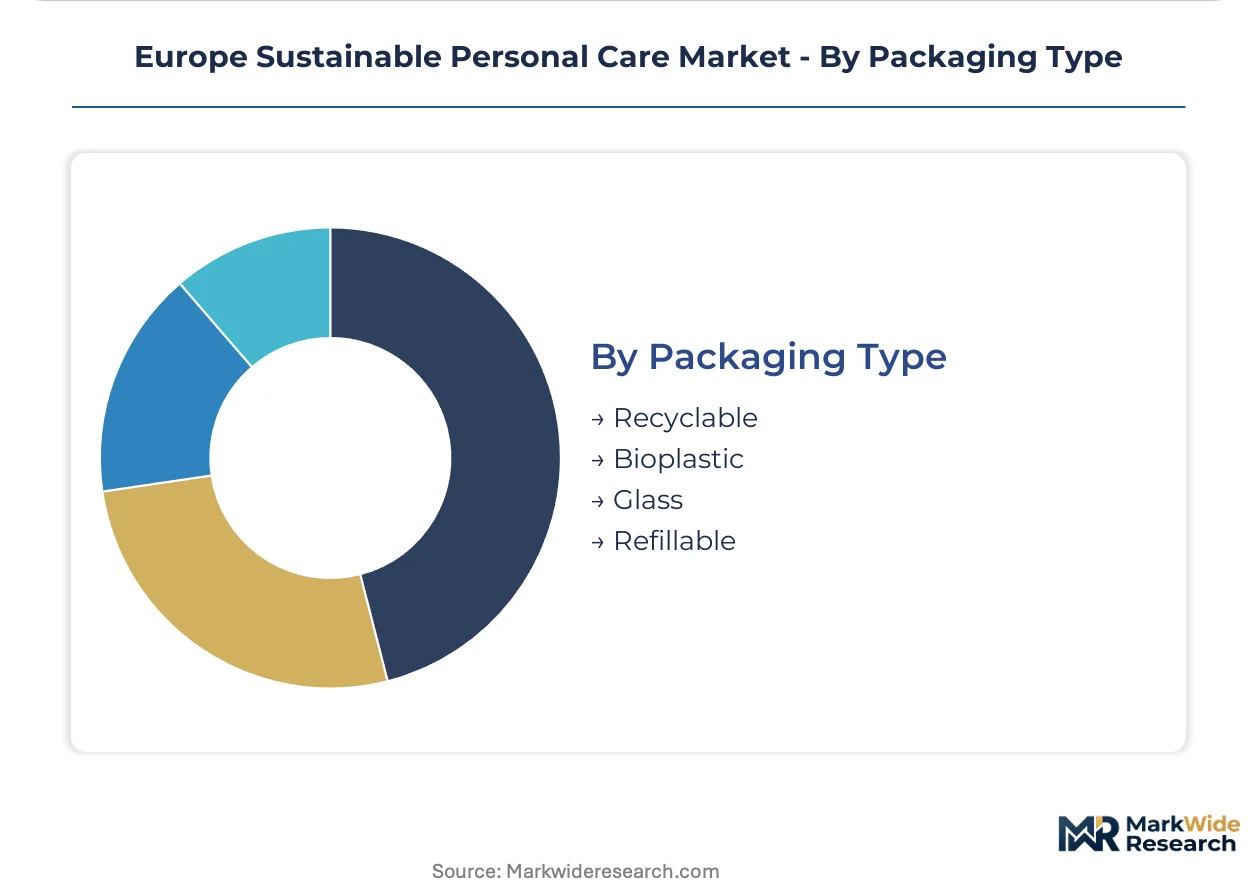
Packaging Type:
Material recovery infrastructure and carbon intensity of production determine competitive viability under EU Green Deal circular economy mandates.
- Refillable:In-store dispensing systems and at-home concentrate formats cut packaging intensity per consumer by over half. Urban retail networks in London, Paris, and Berlin are installing dedicated infrastructure that locks in repeat purchase patterns.
- Bioplastic:PLA and PHA formats compete for masstige channel dominance, though European production capacity clusters in Italy and Netherlands create single-source supply vulnerability. Carbon border adjustments favor domestic bioplastic producers serving French and German retailers.
- Glass:Prestige channel standard with established recycling loops; weight penalties limit expansion beyond premium positioning.
- Recyclable:Conventional rPET and aluminum formats facing competitive pressure from refillable and bioplastic alternatives in ESG-verified positioning.
Recyclable formats maintain volume base; refillable systems capture urban retail expansion steepest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biodynamic cultivation traditions rooted in German-speaking regions established the foundation for Europe's sustainable personal care industry. Early field-to-finished-good models scaled through wellness retail networks before regulatory frameworks codified these practices into compliance standards.
Germany
Urban refill infrastructure in Berlin and Hamburg concentrates demand for concentrated shampoo formats that reduce packaging mass per wash cycle. The CSRD disclosure mandate binds corporate reporting to verified environmental impact metrics across personal care portfolios. Bavarian biodynamic farming clusters supply controlled raw material provenance contracts that constrain geographic expansion of verified organic claims.
France
Parisian retail networks prioritize ESG-certified offerings through dedicated in-store dispensing systems that lock in repeat purchase patterns. REACH restrictions on microplastics eliminate synthetic glitter and film-forming polymers from rinse-off cosmetics manufactured for French consumers. Biotechnology R&D platforms in the Île-de-France region cultivate lab-synthesized active ingredients that displace botanical extracts in premium positioning.
United Kingdom
Subscription-native Gen Z buyers consolidate spending around direct-to-consumer brands with transparent supply chain storytelling accessible through London-based digital storefronts. The F-Gas Regulation decouples conventional formulations from market access by mandating carbon-transparent supply chains. Precision fermentation facilities in the Greater Southeast anchor biosynthesized ingredient production for vegan-positioned brands.
Italy
Masstige channel demand for PLA and PHA bioplastic packaging concentrates production capacity in Northern Italian industrial zones. EU Green Deal carbon border adjustments favor domestic bioplastic producers serving retailers across the peninsula. Milan's urban retail networks compete with direct-to-subscription channels by installing dedicated refill infrastructure for body wash and shampoo categories.
Netherlands
Enzymatic and fermentation-derived cleaning agents from Dutch facilities now match petrochemical performance at scale for body wash and shampoo distribution. ECHA REACH aquatic toxicity thresholds accelerate commercial production of biodegradable surfactants. Rotterdam-area logistics clusters support circular packaging recovery systems that serve refillable format demand across Northwestern Europe.
Europe Sustainable Personal Care Market Competitive Landscape
The competitive structure tilts toward diversified consumer goods conglomerates with integrated Home Care and Personal Care divisions. Tiered positioning separates biotechnology-platform specialists from biodynamic cultivation contract holders and mass-market surfactant scale players. Strategic archetypes include fermentation-derived active ingredient developers, field-to-finished-good provenance controllers, and urban refill infrastructure operators. Dominant competitive moves encompass backward integration into biodegradable feedstock supply and technology licensing agreements for enzymatic surfactant production.
Among diversified European-headquartered conglomerates, Unilever PLC and L'Oréal Group occupy positions that exemplify contrasting strategic archetypes. Unilever PLC represents integrated supply chain operators sustaining captive production of biodegradable surfactants across Home Care and Personal Care divisions. L'Oréal Group anchors the biotechnology-platform tier through fermentation-derived active ingredient development. Weleda AG sits within the biodynamic cultivation specialist category, controlling raw material provenance through field-to-finished-good contracts concentrated in German-speaking supply clusters.
| Leading Market Players |
|---|
| L'Oréal Group |
| Unilever PLC |
| The Procter and Gamble Company |
| Beiersdorf AG |
| The Colgate-Palmolive Company |
| Estee Lauder Companies, Inc. |
| Coty, Inc. |
| L'OCCITANE Group |
| Weleda AG |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between ISO 16128-verified organic claims and conventional natural positioning manifests in divergent margin structures and supply chain control requirements across European personal care. Premium tiers command field-to-finished-good provenance contracts concentrated in German biodynamic clusters, while masstige brands absorb volatile organic feedstock costs from tropical supply zones.
Pricing Analysis
Subscription-at-home versus single-purchase retail splits dominate pricing architecture across the European market. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification depth and carbon accounting transparency, with ESG-verified brands capturing least price-sensitive Gen Z subscribers in London and Stockholm. Cost compression in masstige surfactant categories intensifies as enzymatic-derived alternatives achieve petrochemical cost parity. Eco-conscious consumers in German-speaking markets exhibit lowest price sensitivity, while volume-driven body wash buyers in Southern Europe resist organic premiums.
Supply Chain Analysis
Direct-to-consumer digital storefronts handle subscription-native demand from Gen Z buyers, while urban refill infrastructure in Berlin, Paris, and Milan serves concentrated metropolitan populations. Biodegradable surfactant production concentrates in Germany and the Netherlands, with bioplastic packaging capacity clustering in Italy. Raw material dependencies include coconut and palm kernel oil derivatives from Southeast Asia, fermentation feedstocks from Dutch biotech facilities, and biodynamic botanicals from Swiss-German cultivation zones. Single-source vulnerability in PLA and PHA domestic supply creates exposure for brands seeking EU Green Deal compliance. Distribution runs through wellness retail networks in German-speaking regions and direct-to-subscription channels in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European sustainable personal care functions as a regulatory-arbitrage play, where compliance investments in REACH biodegradable standards and CSRD disclosure infrastructure create sustainable competitive moats against non-conforming imports facing carbon border adjustment penalties.
For Market Incumbents: Deploy backward integration into captive fermentation-derived surfactant production to defend against biotechnology-platform specialists eroding masstige positioning. Lock in biodynamic cultivation contracts across Bavarian and Swiss supply clusters before qualified agronomist scarcity constrains organic claim expansion. Channel control through owned refill infrastructure in Berlin, Paris, and London insulates against direct-to-consumer entrants capturing Gen Z subscription spend. For New Entrants and Emerging Players: Subscription-fatigued millennials in Poland, Romania, and Czech Republic represent the most penetrable buyer archetype, with sustainable personal care shelf space underdeveloped relative to Western European saturation. Precision fermentation-derived actives bypass agricultural land use constraints, appealing to vegan-positioned brand launches in Scandinavian markets. A digital-first, carbon-accounting-transparent go-to-market model collapses traditional retail gatekeeper barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with biotechnology-platform ingredient developers possessing commercial-scale fermentation capacity in the Netherlands and Denmark. Five-to-ten year viability hinges on regulatory tailwinds from ECHA microplastic restrictions and EU Green Deal enforcement deepening competitive moats for compliant formulations. Monitor ISO 16128 certification queue lengths as an inflection signal—backlogs beyond nine months indicate demand outstripping auditor capacity, favoring acquisition targets with existing verified portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biodegradable Surfactant Production | Captive enzymatic-derived supply insulates margin pressure from organic feedstock volatility in coconut and palm kernel markets. |
| Biotechnology-Platform R&D Expansion | Precision fermentation facilities in the Netherlands and Denmark displace botanical extraction premiums with lab-cultured squalane and hyaluronic acid. |
| Urban Refill Infrastructure Deployment | In-store dispensing systems in Berlin, Paris, and London cut packaging intensity and lock repeat purchase patterns against digital entrants. |
| Biodynamic Cultivation Contract Securement | Field-to-finished-good provenance control in German-speaking clusters constrains competitor access to ISO 16128 organic certification. |
| CSRD Disclosure Capability Buildout | Verified carbon accounting infrastructure captures service revenue from mid-tier brands lacking in-house sustainability reporting expertise. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with brand managers, category buyers at German and French retailers, supply planners, and sustainability officers at fermentation facilities with secondary validation. Primary inputs included ECHA REACH registration databases, EU Green Deal policy documentation, CSRD implementation guidance, and customs records tracking bioplastic import flows. Nielsen retail audit data and Circana subscription commerce metrics provided volume benchmarks. Bottom-up SKU-level modeling and top-down category sizing triangulated market estimates across the analysis window.
Segment-weighting approaches distributed value and volume across formulation chemistry, ingredient provenance, packaging format, and consumer cohort dimensions. Shampoo, face cream, and body wash categories received distinct modeling parameters reflecting rinse-off versus leave-on regulatory scrutiny intensity. CAGRs derived from historical trajectory analysis and regulatory impact scoring, with biotechnology-platform adoption curves and refill infrastructure penetration rates serving as industry-specific forecast inputs.
Inputs from primary interviews and ECHA regulatory filings were available through the study window; gaps in real-time bioplastic production capacity utilization introduce uncertainty bands around packaging format share projections. Forecasts reflect assumptions regarding REACH enforcement consistency and EU Green Deal carbon border adjustment implementation timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Over-Night Hair Treatment Products Market
Beauty & Personal Care
Saudi Arabia Hair Care Market
Beauty & Personal Care
Anti Stretch Mark Products Market
Beauty & Personal Care
LAMEA Hair Removal Wax Market
Beauty & Personal Care
US Color Cosmetics Market
Beauty & Personal Care
Handmade False Eyelash Market
Beauty & Personal Care
Spain Sustainable Personal Care Market
Beauty & Personal Care
US Natural Personal Care Market
Beauty & Personal Care
South America Hair Styling Products Market
Beauty & Personal Care
Elastomer Gel in Personal Care Market
Beauty & Personal Care
Middle East Herbal Shampoo Market
Beauty & Personal Care
Facial Oil Market
Beauty & Personal Care
Natural Cosmetics Market
Beauty & Personal Care
At Home Hair Dye Market
Beauty & Personal Care
Europe Cosmeceuticals Market
Beauty & Personal Care
Dry Shampoo Market