
 New Zealand Sports Tourism Market | 2026-2036
New Zealand Sports Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Sports Tourism Market Foresight
Queenstown's adventure infrastructure expansion is reconfiguring visitor flow patterns across the South Island. HAKA SPORTS TOURS leverages its school team relationships to anchor multi-day tournament circuits in Rotorua and Wellington. Sportsnet Holidays competes through exclusive All Blacks hospitality packaging that extends premium yield per visitor. Active Adventures specializes in backcountry trekking integrations that differentiate beyond conventional stadium tourism.
Sports tourism encompasses travel where participation in or attendance at sporting events constitutes the primary motivation, requiring coordinated logistics across accommodation, transport, venue access, and activity insurance. The sector operates through high fixed-cost event infrastructure balanced against perishable inventory, making yield management critical to operator viability. Adventure Sports commands the largest activity-type share due to New Zealand's terrain accessibility and established safety certification protocols. Weekend Events represent the fastest-growing duration segment as domestic and Australian visitors prioritize compressed itineraries. Luxury Packages within Visitor Experience concentrate margin pools through bundled helicopter access, private guiding, and lodge accommodation.
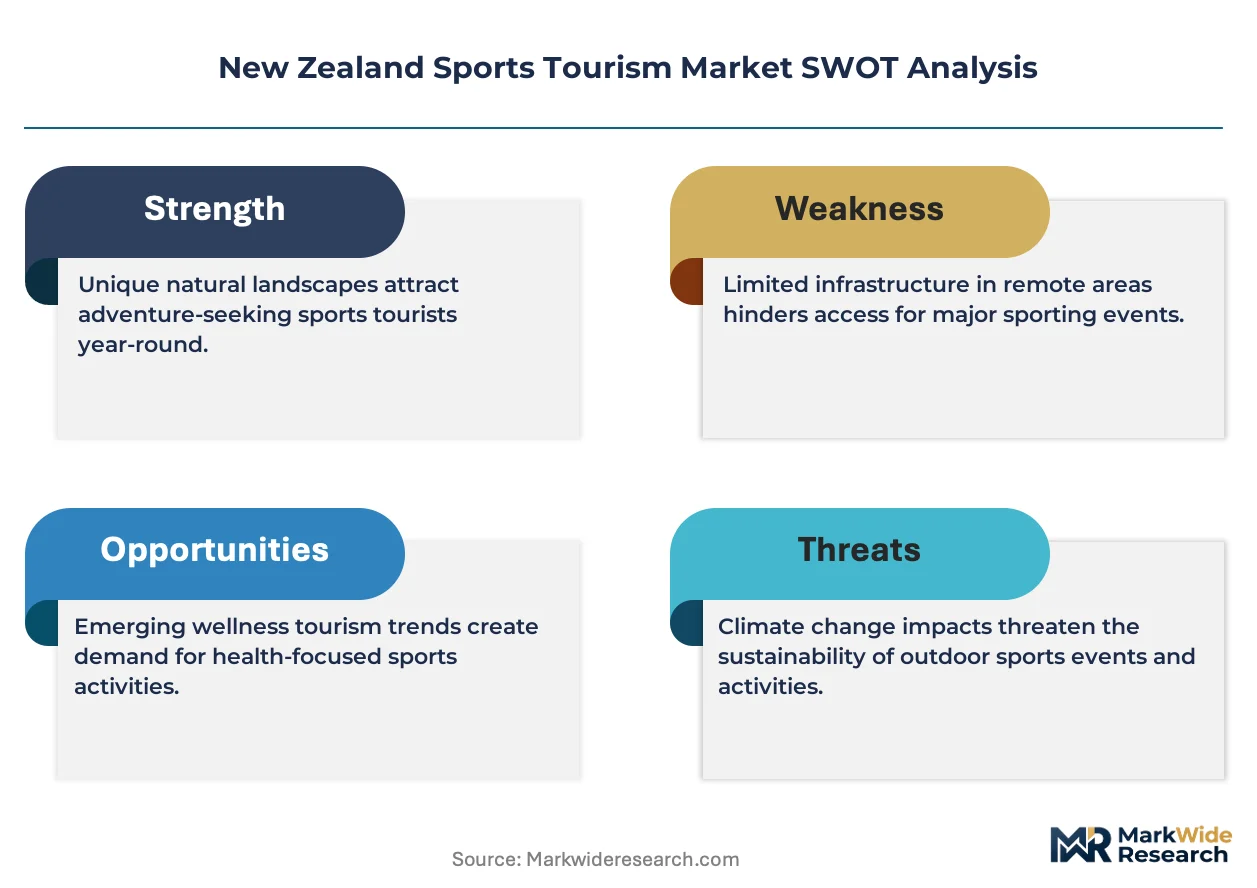
Tourism New Zealand's Tiaki Promise framework and the Department of Conservation's commercial concession system shape operator access to protected landscapes, creating regulated capacity ceilings that preserve experience quality. Health and safety obligations under WorkSafe New Zealand and adventure activity auditing standards mandate certified guide ratios and equipment inspection protocols that elevate operational costs but reduce liability exposure. Stakeholders must monitor concession renewal timelines and evolving biosecurity requirements for international team equipment imports.
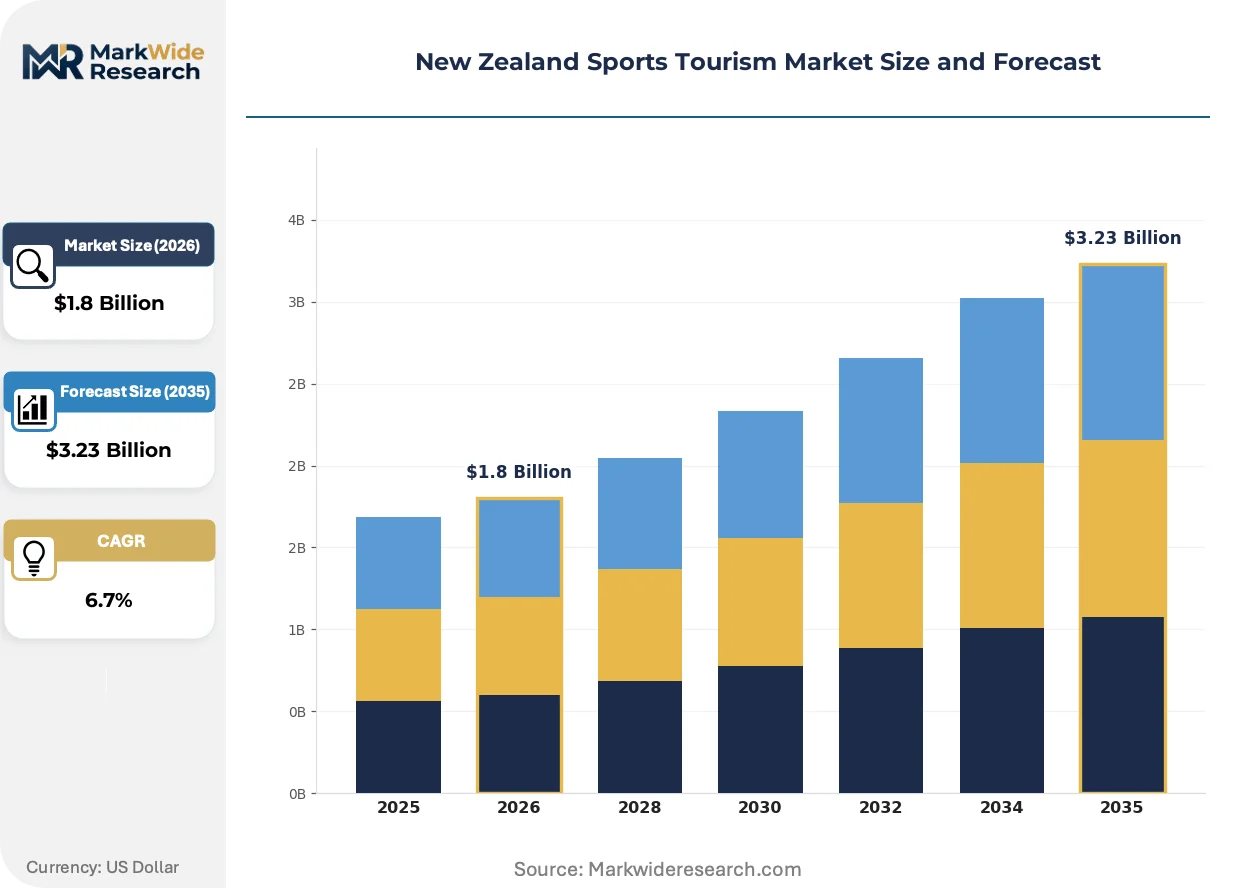
Market Dynamics
Tourism New Zealand's Tiaki Promise framework and the Department of Conservation's concession system are tightening capacity ceilings across protected adventure corridors, forcing operators to compete on yield-per-visitor rather than volume scaling.
Growth Catalysts
- Department of Conservation concession streamlining:The commercial concession system is reducing approval timelines for adventure operators seeking access to national parks and protected landscapes.
- International school team expansion:Australian and Asian educational institutions are anchoring multi-day tournament circuits in secondary cities beyond Queenstown.
- Adventure activity safety certification:WorkSafe New Zealand's auditing protocols are elevating operator credibility and reducing liability premiums for compliant businesses.
Market Restraints
- Guide certification cost inflation:WorkSafe New Zealand's mandated certified guide ratios are elevating operational costs across backcountry trekking and alpine activities.
- Southern Lakes accommodation concentration:Queenstown's limited high-yield lodging inventory creates bottleneck effects during peak tournament seasons.
- Biosecurity equipment inspection delays:Ministry for Primary Industries protocols for international team gear imports are extending pre-arrival logistics timelines.
Strategic Opportunities
- Rotorua geothermal-adventure bundling:Underdeveloped thermal corridor experiences offer white space for operators integrating Maori cultural tourism with endurance events.
- Helicopter-accessed lodge networks:Fiordland and West Coast regions present expansion terrain for ultra-premium multi-day itineraries beyond existing Southern Lakes saturation.
- Tourism New Zealand quality assurance tiering:The Tiaki Promise framework creates regulatory tailwind for operators achieving higher sustainability and experience credentials.
Industry Challenges
- Adventure guide talent pipeline gaps:Technical mountaineering and swiftwater rescue certifications face supply shortages relative to operator expansion timelines.
- Legacy booking system integration:Established operators struggle to synchronize proprietary reservation platforms with emerging aggregator distribution channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Sports Tourism Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Activity Type: Adventure Sports, Team Sports, Individual Sports, Water Sports Event Duration: One-Day Events, Weekend Events, Multi-Day Tournaments, Year-Round Events Participation Level: Amateur Participants, Professional Athletes, Spectators, School Teams Visitor Experience: Outdoor Experiences, Cultural Tours, Luxury Packages, Local Engagement |
| Companies Covered | HAKA SPORTS TOURS, Sportsnet Holidays, Williment, All Blacks Tours, Dragonfish, Estilo Sports Travel, Real New Zealand Tours Limited, Active Adventures, World Expeditions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Sports Tourism Market Shifts & Advancements
Digital yield management tools and immersive pre-booking experiences are compressing decision cycles and elevating price transparency across the sports tourism value chain.
Virtual reality pre-immersion platforms are hybridizing the sales funnel for high-commitment adventure packages. Premium inbound operators are deploying VR trail previews to reduce booking abandonment. This technology is hybridizing destination marketing with direct conversion, collapsing the traditional inspiration-to-booking timeline.
Tourism New Zealand's Tiaki Promise sustainability framework is mandating carbon offset disclosure and visitor impact education across all licensed operators. The framework is elevating compliance costs for smaller adventure providers while creating certification-driven market segmentation. Southern Lakes operators are responding fastest due to concentrated international scrutiny.
School and club procurement teams are consolidating tournament bookings through specialized sports tour aggregators rather than direct venue negotiations. This channel shift is compressing operator margins while expanding market access for secondary-city destinations. Wellington and Christchurch are capturing disproportionate share of this consolidated demand.
New Zealand Sports Tourism Market Segmentation
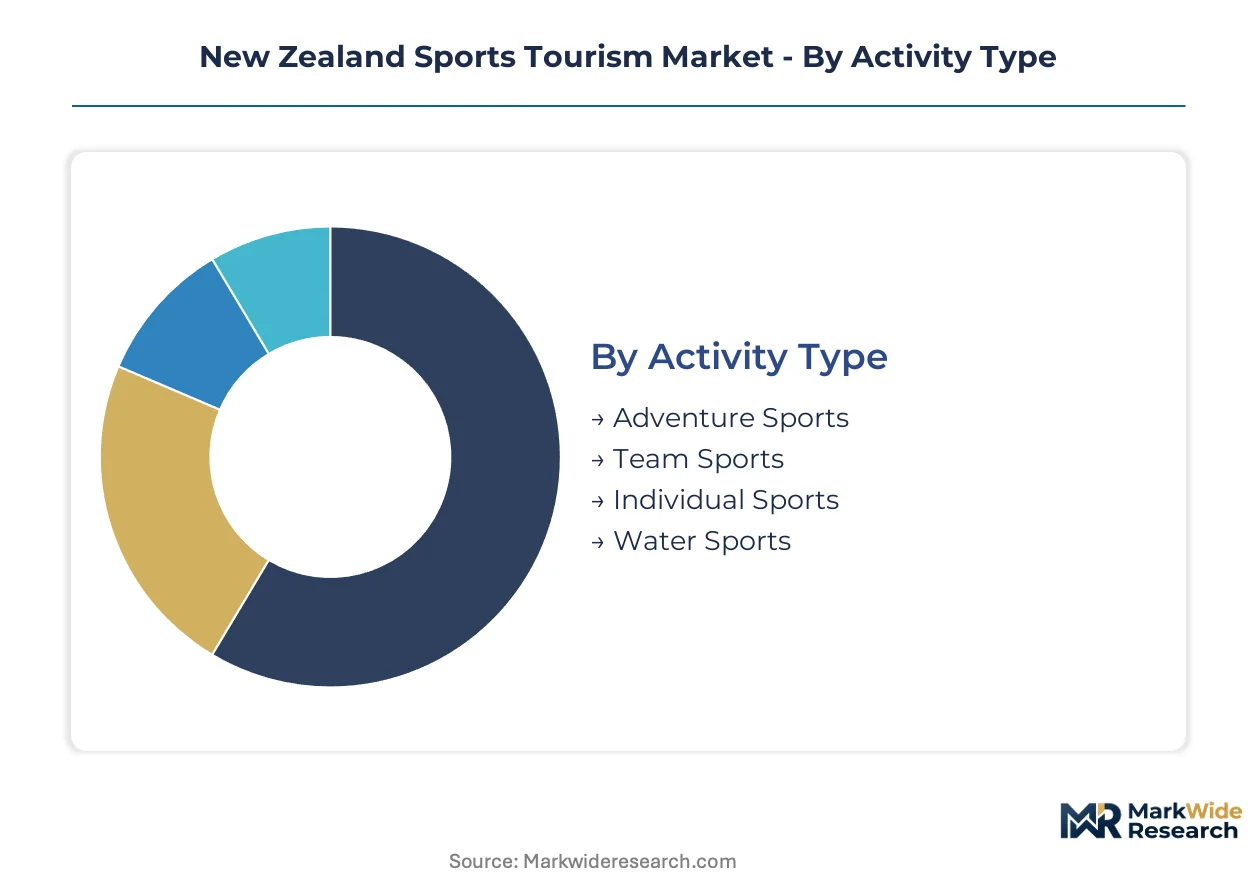
New Zealand's sports tourism market segments around four operational dimensions that determine booking patterns, infrastructure requirements, and margin structures. Activity type and event duration drive fixed-cost allocation decisions, while participation level and visitor experience shape yield-per-visitor optimization strategies.
Activity Type:
After-sales service intensity varies sharply across activity categories, with adventure sports demanding continuous guide availability and equipment maintenance protocols that elevate operational overhead.
- Adventure Sports:Technical mountaineering, bungee jumping, and alpine trekking operations require WorkSafe New Zealand-certified guide ratios and mandatory equipment inspection cycles. Queenstown and the Southern Lakes district concentrate premium demand due to terrain accessibility and established safety certification infrastructure.
- Team Sports:Rugby, cricket, and netball tournament circuits anchor multi-day itineraries across Rotorua and Wellington. Australian school teams and Asian educational institutions are expanding bookings beyond traditional Queenstown corridors.
- Individual Sports:Marathon running, cycling, and golf tournaments operate with lower guide-to-participant ratios. Rotorua's geothermal corridor presents white space for endurance event expansion.
- Water Sports:Kayaking, sailing, and jet boating leverage New Zealand's coastline and lake systems. Fiordland and West Coast regions offer underdeveloped capacity for ultra-premium multi-day itineraries.
By volume, Adventure Sports leads. By growth pace, Team Sports is climbing the fastest.
Event Duration:
Cost tier differentiation separates infrastructure-heavy multi-day circuits from compressed weekend formats that maximize perishable inventory utilization.
- One-Day Events:Single-match attendances and day-trip adventure bookings concentrate around Auckland and Christchurch metropolitan catchments. Corporate hospitality packages drive premium yield compression in these formats.
- Weekend Events:Compressed itineraries prioritize Queenstown and Wellington corridors for Australian and domestic visitors. This segment is expanding most quickly as procurement teams consolidate tournament bookings through specialized aggregators.
- Multi-Day Tournaments:School and club circuits require coordinated accommodation blocks across secondary cities. HAKA SPORTS TOURS leverages these relationships to anchor Rotorua and Wellington bookings.
- Year-Round Events:Permanent training facilities and seasonal residency programs operate through Southern Lakes saturation. Department of Conservation concession ceilings limit volume scaling in protected adventure corridors.
By participant volume, Multi-Day Tournaments dominates. By booking velocity expansion, Weekend Events is ahead.
Participation Level:
Customer type stratification creates distinct margin pools across amateur mass-market participation and premium professional athlete services.
- Amateur Participants:Recreational adventure seekers and social sports competitors form the volume base. Tourism New Zealand's Tiaki Promise framework mandates carbon offset disclosure across this broad segment.
- Professional Athletes:Elite training camps and pre-season conditioning programs command premium facility access. WorkSafe New Zealand auditing protocols elevate operational credibility for compliant operators serving this tier.
- Spectators:All Blacks hospitality packaging and stadium tourism extend yield per visitor through bundled accommodation and transport. Sportsnet Holidays competes through exclusive premium offerings in this space.
- School Teams:Australian and Asian educational institutions are anchoring multi-day tournament circuits beyond traditional Queenstown saturation. Biosecurity equipment inspection delays from the Ministry for Primary Industries extend pre-arrival logistics timelines for this segment.
By absolute participant numbers, Amateur Participants leads. By revenue per booking, Professional Athletes is gaining share fastest.
Visitor Experience:
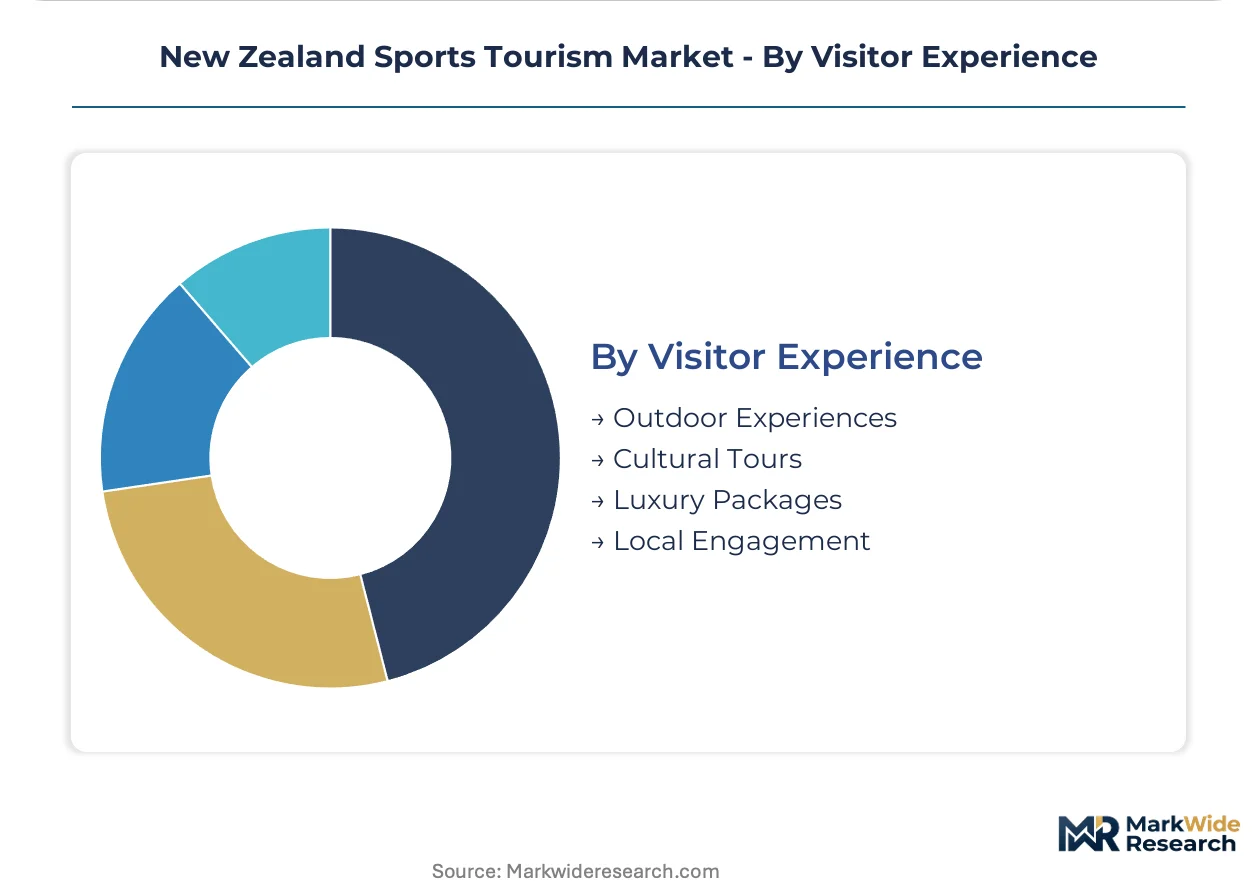
Application focus separates outdoor adventure infrastructure from cultural tourism bundling that integrates Maori heritage programming.
- Outdoor Experiences:Backcountry trekking and alpine activities differentiate beyond conventional stadium tourism. Active Adventures specializes in these integrations across the South Island.
- Cultural Tours:Maori heritage programming and geothermal corridor experiences offer bundling potential with endurance events. Rotorua presents specific white space for this integration.
- Luxury Packages:Helicopter access, private guiding, and lodge accommodation concentrate margin pools. Fiordland helicopter-accessed lodge networks present expansion terrain beyond Southern Lakes saturation.
- Local Engagement:Community-hosted events and volunteer tourism components align with Tourism New Zealand's quality assurance tiering. The Tiaki Promise framework creates regulatory tailwind for operators achieving higher sustainability credentials.
By booking volume, Outdoor Experiences leads. By margin expansion trajectory, Luxury Packages is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tourism New Zealand's Tiaki Promise framework and the Department of Conservation's concession system anchor regulatory oversight across the dominant South Island corridor. These mechanisms concentrate visitor flow management and capacity allocation decisions within specific sub-regional clusters.
Southern Lakes
Queenstown's adventure infrastructure expansion drives high-yield outdoor experience demand across bungee jumping, alpine trekking, and helicopter-accessed activities. WorkSafe New Zealand's certified guide ratio mandates elevate operational compliance costs for operators concentrated here. The district's limited premium lodging inventory creates bottleneck effects during peak tournament seasons, forcing yield-per-visitor optimization over volume scaling.
Rotorua
Geothermal corridor experiences and Maori cultural tourism bundling attract expanding Australian and Asian school team bookings. HAKA SPORTS TOURS leverages educational institution relationships to anchor multi-day tournament circuits in this secondary city. The underdeveloped thermal-adventure integration presents white space for endurance event operators seeking differentiation beyond conventional stadium tourism.
Wellington
Consolidated procurement patterns through specialized sports tour aggregators are capturing disproportionate tournament booking share. Weekend Events duration segments prioritize this corridor for compressed Australian and domestic visitor itineraries. The city's accommodation and venue infrastructure supports school team expansion beyond traditional Queenstown saturation.
Fiordland and West Coast
Helicopter-accessed lodge networks and ultra-premium multi-day itineraries target expansion terrain beyond Southern Lakes capacity ceilings. Department of Conservation concession ceilings limit volume scaling in these protected adventure corridors. Active Adventures specializes in backcountry trekking integrations that differentiate through terrain accessibility rather than conventional hospitality packaging.
New Zealand Sports Tourism Market Competitive Landscape
Capability concentration sits with specialized adventure operators; scale advantage sits with diversified tour aggregators. The market structures around tiered service intensity, with premium hospitality packagers competing against technical activity specialists for distinct visitor segments. Three archetypes dominate: school-team circuit anchors, exclusive sporting event hospitality bundlers, and backcountry trekking integrators. Competitive moves concentrate on exclusive venue access partnerships and multi-day itinerary bundling across secondary cities.
Within the school-team circuit anchor tier, HAKA SPORTS TOURS represents the archetype of educational institution relationship leverage. Among premium hospitality packagers, Sportsnet Holidays occupies a position exemplifying exclusive All Blacks experience bundling. At the technical specialization end, Active Adventures sits within the backcountry trekking integrator archetype, differentiating through terrain-access expertise rather than conventional stadium-adjacent offerings.
| Leading Market Players |
|---|
| HAKA SPORTS TOURS |
| Sportsnet Holidays |
| Williment |
| All Blacks Tours |
| Dragonfish |
| Estilo Sports Travel |
| Real New Zealand Tours Limited |
| Active Adventures |
| World Expeditions |
| Others |
Supply & Pricing Matrix
Auckland-Queenstown freight corridors carry equipment and perishable hospitality inventory across the North-South divide, with route cost inflation feeding directly into operator margin structures. This logistics backbone concentrates pricing power among Southern Lakes incumbents who control helicopter-accessed lodge networks and premium accommodation blocks, while compressing margins for secondary-city operators competing on volume.
Pricing Analysis
Price spreads between Queenstown and Wellington corridors reach three-to-one for equivalent adventure packages, with Southern Lakes operators commanding premiums through Department of Conservation concession scarcity. Three-tier pricing structure across premium helicopter-access, standard guided trekking, and economy self-drive formats stratifies the market. Cost compression in economy tiers is intensifying because school-team procurement teams consolidate bookings through aggregators. Amateur school teams exhibit highest price sensitivity; luxury package buyers show least elasticity.
Supply Chain Analysis
Extended payment terms from international school procurement teams are forcing domestic operators to carry 90-120 day receivables, straining working capital across the sector. Equipment manufacturing concentrates in China, Australia, and the United States, with technical mountaineering gear and swiftwater rescue equipment drawing from these hubs. Single-source vulnerability runs through certified guide training pipelines, where WorkSafe New Zealand accreditation bottlenecks create hiring delays. Distribution runs through specialized sports tour aggregators rather than direct venue relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical guide certification scarcity constrains expansion timelines across all operator tiers, with WorkSafe New Zealand-mandated ratios creating a binding capacity ceiling that rewards early credential investment. This skills gap favors incumbents who secured certification pipeline access before demand acceleration.
For Market Incumbents: Build exclusive concession moats by securing Department of Conservation renewal priority through Tiaki Promise sustainability tiering ahead of competitor applications. Anchor multi-day tournament circuits in Rotorua and Wellington before HAKA SPORTS TOURS consolidates educational institution relationships. Channel control through proprietary booking platforms defends against aggregator margin compression.
For New Entrants and Emerging Players: Pursue geothermal-adventure bundling white space in Rotorua's underdeveloped thermal corridor, where Maori cultural tourism integration remains fragmented. Helicopter-accessed lodge networks in Fiordland present the most penetrable premium segment beyond Southern Lakes saturation. A direct school-team sales approach bypasses aggregator fees and captures procurement team attention.
For Investors and Strategic Acquirers: Technical-specialist operators with certified guide pipelines and established concession relationships represent the highest-conviction acquisition archetype. Long-term viability hinges on regulatory compliance infrastructure rather than volume scaling capability. Watch WorkSafe New Zealand certification timeline extensions as the inflection signal for operator distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Concession Portfolio Expansion | Department of Conservation priority renewal secures protected corridor access before capacity ceilings bind. |
| Guide Certification Pipeline Investment | WorkSafe New Zealand-accredited training partnerships lock in scarce technical talent ahead of competitor hiring. |
| Aggregator Channel Bypass | Direct school-team procurement relationships recover margin compression from consolidated booking platforms. |
| Helicopter-Accessed Lodge Network Buildout | Fiordland and West Coast ultra-premium infrastructure escapes Southern Lakes saturation pricing pressure. |
| Tiaki Promise Tiering Achievement | Tourism New Zealand sustainability credentials create regulatory tailwind for concession renewal priority. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with adventure activity directors, school sports tour coordinators, Department of Commerce concession administrators, and WorkSafe New Zealand compliance officers. Secondary validation drew from Tourism New Zealand visitor statistics, Department of Conservation commercial permit disclosures, WorkSafe New Zealand audit publication records, and accommodation inventory databases. Bottom-up operator revenue modeling and top-down tourism sector aggregation were triangulated to reconcile segment estimates.
Calibration against historical concession issuance patterns and accommodation occupancy fluctuations anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include activity type, event duration, participation level, and visitor experience tier, with regional regulatory cluster effects layered across each. CAGRs were derived from capacity-constrained growth assumptions tied to guide certification pipeline throughput and concession ceiling trajectories. Helicopter fleet expansion schedules and international school enrollment trends fed industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive concession consolidation moves by backcountry trekking specialists would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Europe Tourism Vehicle Rental Market
Travel and Tourism
Bleisure Tourism Market
Travel and Tourism
Africa Wellness Tourism Market
Travel and Tourism
GCC Outbound Tourism Market
Travel and Tourism
Sustainable Traveling Market
Travel and Tourism
China Outbound Travel Market
Travel and Tourism
Tourism Security Market
Travel and Tourism
Yacht Charter Market
Travel and Tourism
Greece Tourism Market
Travel and Tourism
B2B Travel Market
Travel and Tourism
Travel Intermediaries Business Market
Travel and Tourism
Asia-Pacific MICE Tourism Market
Travel and Tourism
Latin America Inflight Services Market
Travel and Tourism
Agritourism Market
Travel and Tourism
Wedding Tourism Market
Travel and Tourism
Indonesia Sustainable Tourism Market