
 Singapore Tourism Market | 2026-2036
Singapore Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Tourism Market Analytics
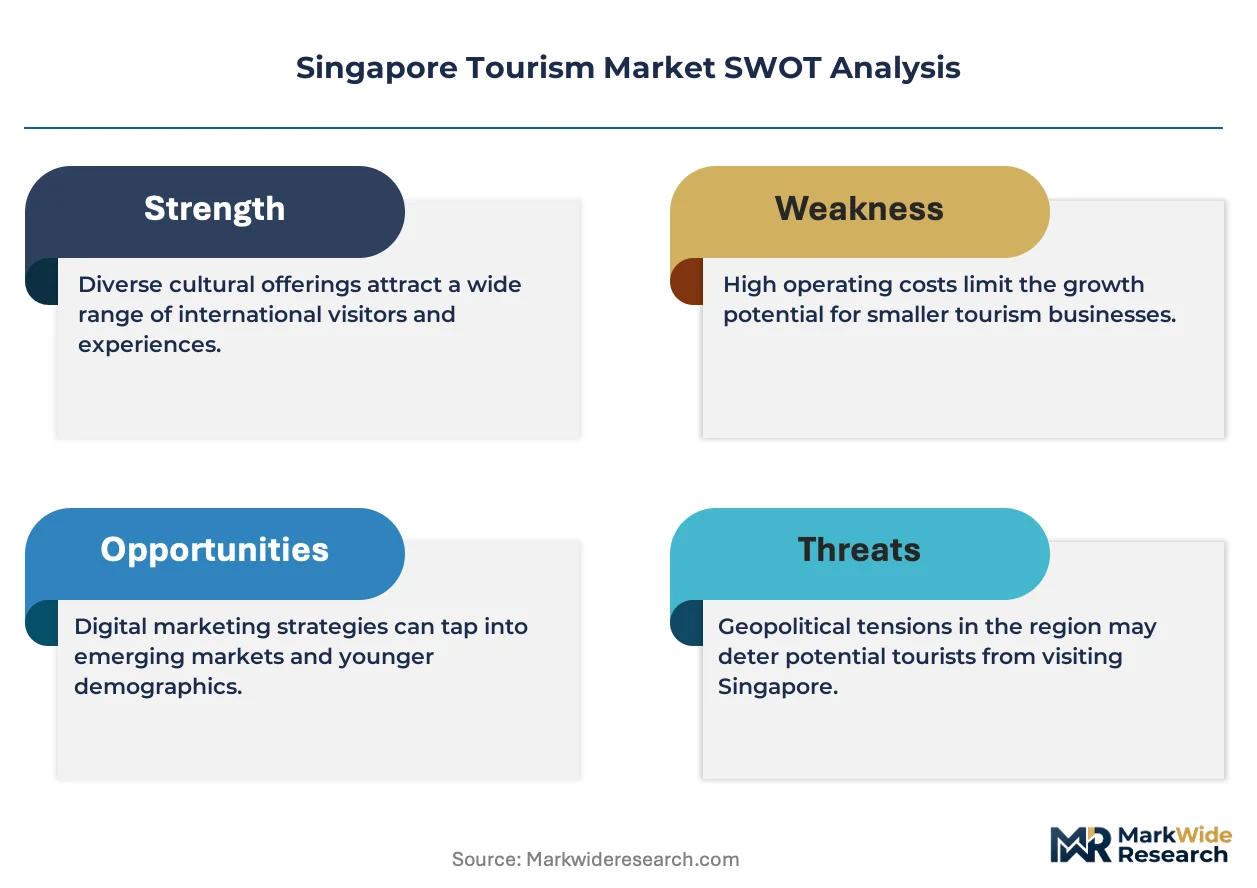
Premium-tier experiential offerings is redrawing competitive boundaries in Singapore's tourism landscape. Marina Bay Sands leverages its integrated resort model to anchor luxury demand across accommodation and entertainment verticals. Singapore Airlines sustains network dominance through hub-and-spoke connectivity that feeds visitor inflows from Europe, Australia, and North Asia. Klook competes on digital aggregation, controlling last-mile activity bookings that capture spending before arrival.
Singapore tourism encompasses destination services, visitor infrastructure, and experience curation delivered through a city-state framework of limited land area and high service-density requirements. The sector operates on yield-per-visitor metrics where average length of stay and daily expenditure determine economic contribution, with primary commercial purpose centered on foreign exchange generation and employment in hospitality, retail, and transport. Leisure travelers represent the deepest visitor pool, though business travelers command higher per-trip spending and shoulder-season occupancy. Cultural landmarks attract repeat visitation, while entertainment venues concentrate capital investment and integrated resort economics. Dining experiences increasingly drive itinerary design, with hawker heritage recognition and fine-dining density creating differentiation against regional competitors.
The Singapore Tourism Board shapes demand through destination marketing mandates and industry development grants, while the Infocomm Media Development Authority enforces digital service standards that affect booking platforms and visitor-facing applications. Singapore's Building and Construction Authority imposes green mark certification on new hospitality developments, elevating operational compliance costs while creating preference among sustainability-conscious travelers. Stakeholders must monitor how ASEAN open-sky agreements and bilateral visa facilitation reshape source-market competitiveness against Bangkok and Kuala Lumpur.
Market Dynamics
Singapore's Smart Nation infrastructure investments are compressing visitor service delivery timelines while elevating digital experience benchmarks across accommodation, transit, and attraction touchpoints.
Growth Catalysts
- IMDA Digital Service Standards:The Infocomm Media Development Authority mandates API interoperability for booking platforms, reducing friction in itinerary planning and payment processing for inbound travelers.
- Integrated Resort Economics:Marina Bay Sands and Resorts World Sentosa anchor yield-per-visitor optimization through bundled entertainment-dining-accommodation packages that extend average length of stay.
- India and China Outbound Affluence:Rising discretionary spending among upper-middle-class households in Mumbai, Delhi, Shanghai, and Shenzhen is redirecting regional leisure flows toward Singapore's premium-tier positioning.
Market Restraints
- Labor Cost Escalation:Hospitality wage pressures in Singapore's tight employment market compress operating margins for F&B and housekeeping functions.
- Land Scarcity Constraints:The city-state's fixed territorial boundaries limit greenfield resort development and force capital-intensive vertical construction or brownfield redevelopment.
- Regional Hub Competition:Bangkok and Kuala Lumpur leverage lower cost structures and comparable flight connectivity to capture price-sensitive segments from ASEAN source markets.
Strategic Opportunities
- BCA Green Mark Certification:New hospitality developments face mandatory sustainability benchmarks, creating preference capture among carbon-conscious travelers from Northern Europe and Australia.
- Last-Mile Digital Aggregation:Mobile-native booking platforms now control pre-arrival activity spend, opening channel control points for experience curators targeting Gen Z and millennial cohorts.
- Hawker Heritage Recognition:UNESCO-inscribed street food culture enables itinerary differentiation against regional competitors lacking comparable intangible cultural asset density.
Industry Challenges
- Skills Pipeline Compression:The Singapore Tourism Board's workforce development grants struggle to offset attrition in guest-facing service roles post-pandemic.
- Legacy Property Retrofit Costs:Older hotel stock requires capital deployment to meet BCA energy efficiency mandates without disrupting operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Tourism Market |
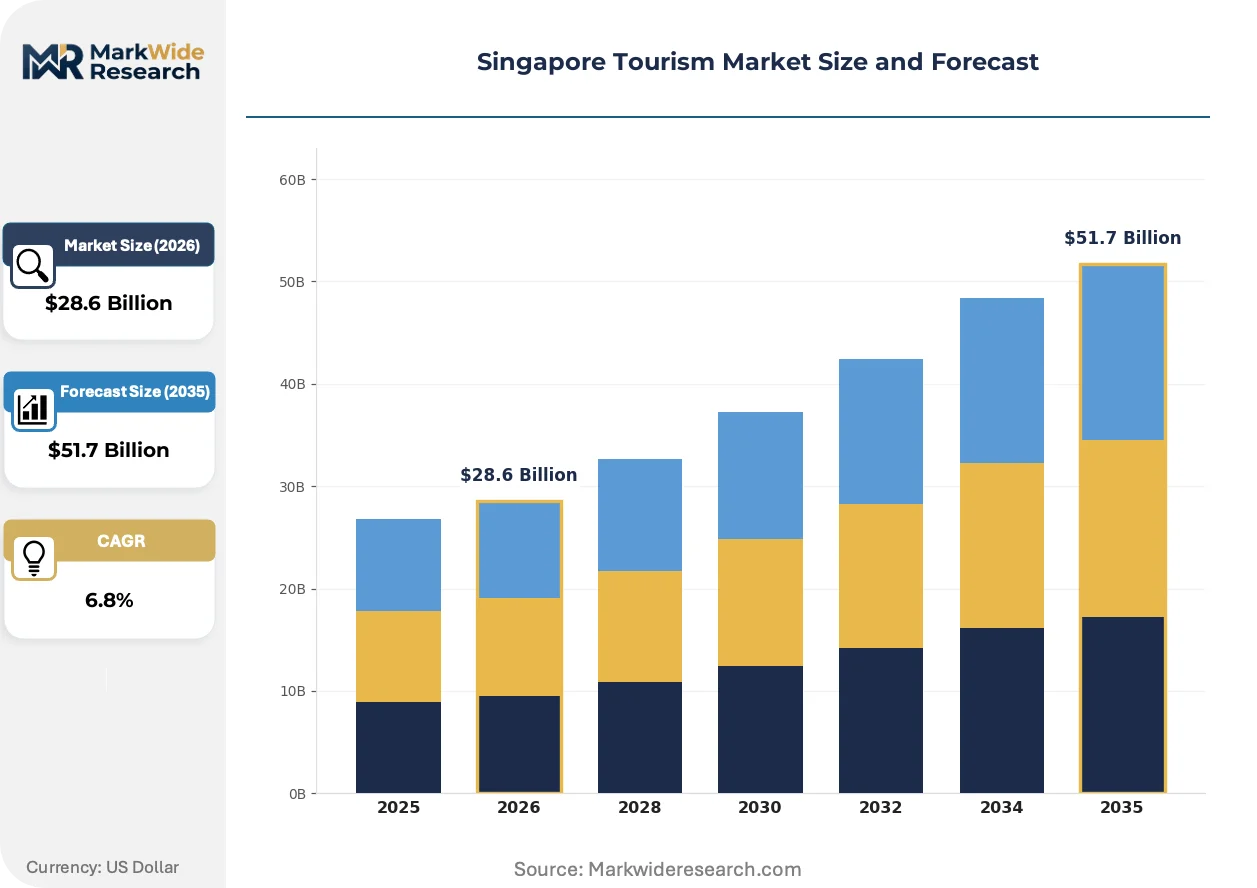
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Visitor Type: Leisure Travelers, Business Travelers, Family Vacations, Solo Travelers Attraction Type: Cultural Landmarks, Shopping Districts, Natural Parks, Entertainment Venues Service Offering: Guided Tours, Accommodation Packages, Transportation Services, Dining Experiences Travel Purpose: Recreation, Conference Attendance, Cultural Immersion, Culinary Experience |
| Companies Covered | Klook, Wego.com, Singapore Airlines, Trafalgar, Intrepid Travel, Marina Bay Sands, RedDoorz, Singapore Tourism Board, GlobalTix, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Tourism Market Evolving Landscape
Digital-native service delivery models are compressing traditional travel agency intermediation while biometric transit systems and AI-curated itineraries reset visitor expectation baselines.
Contactless biometric clearance at Changi Airport is displacing passport-based manual processing, with the Immigration and Checkpoints Authority expanding facial recognition lanes across all terminals. Business travelers and frequent visitors now expect sub-10-minute airside-to-curbside transit. This infrastructure compression is forcing competing regional hubs to accelerate comparable automation investments.
Singapore's Building and Construction Authority Green Mark certification mandates now cover all new hospitality developments above 5,000 square meters, with tiered ratings from Certified to Platinum driving capital allocation toward low-carbon materials and renewable energy integration. Developers targeting the premium segment pursue Platinum ratings to capture corporate travel procurement policies with embedded sustainability screens. The compliance timeline compresses project delivery schedules by 8-12 months.
Pre-arrival mobile booking for dining and attractions now captures 60-70 percent of visitor activity spend before physical arrival, with Klook and similar platforms disintermediating traditional concierge services and hotel direct booking. This channel shift concentrates yield control with digital aggregators rather than property-level revenue management. The behavioral pivot is most pronounced among first-time visitors from China and India under age 35.
Singapore Tourism Market Segmentation
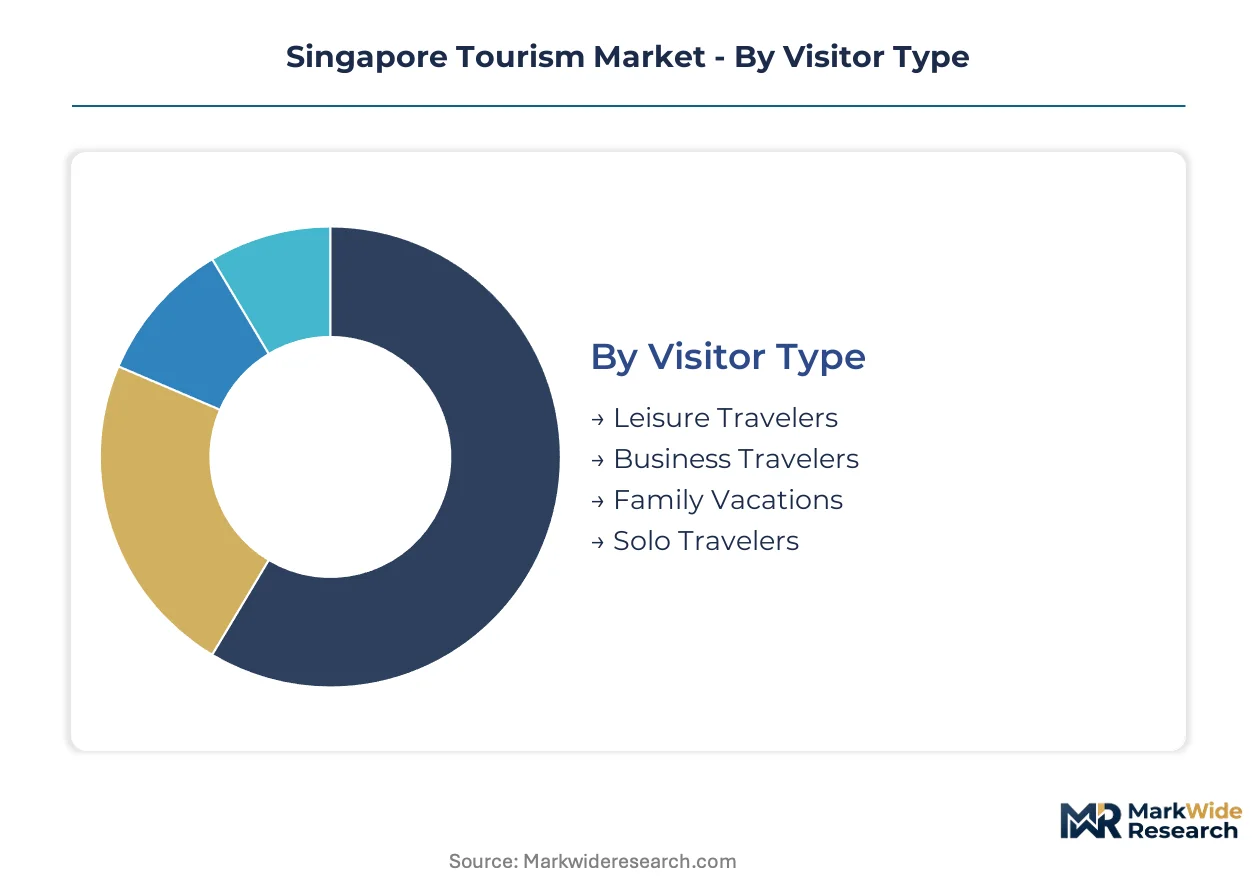
Yield-per-visitor optimization in Singapore's tourism economy depends on precise segment targeting across visitor profiles, attraction formats, and service delivery modes. The city-state's fixed land area intensifies competition for wallet share across discrete traveler microsegments with divergent spending patterns.
Visitor Type:
Margin pools concentrate in business and luxury leisure cohorts where per-trip expenditure multipliers exceed mass-market visitor economics.
- Leisure Travelers:Discretionary holiday visitors from India and China drive integrated resort package demand. Marina Bay Sands and Resorts World Sentosa capture extended-stay bookings through bundled entertainment-dining-accommodation offerings that lift average daily spend above regional benchmarks.
- Business Travelers:Corporate delegates attending MICE events command premium accommodation rates and shoulder-season occupancy stability. Singapore Tourism Board's convention subsidies attract association meetings that fill weekday hotel inventory left vacant by leisure patterns.
- Family Vacations:Multi-generational groups prioritize attraction density and transit accessibility. Universal Studios Singapore and S.E.A. Aquarium anchor itinerary clustering in Sentosa.
- Solo Travelers:Independent explorers under 35 favor mobile-native booking platforms and hawker center dining. Klook captures pre-arrival activity spend in this cohort.
Business travelers hold installed capacity through corporate rate agreements. Leisure travelers are rotating up the share rankings as China and India outbound affluence redirects regional flows.
Attraction Type:
Capital deployment intensity varies sharply across attraction categories, with entertainment venues absorbing the largest integrated resort investments.
- Entertainment Venues:Casino-anchored integrated resorts concentrate yield-per-visitor optimization through captive spend ecosystems. Marina Bay Sands and Resorts World Sentosa deploy loyalty programs that extend visitor dwell time across gaming, retail, and F&B touchpoints.
- Cultural Landmarks:UNESCO-inscribed hawker culture and heritage precincts enable repeat visitation with minimal capital intensity. National Gallery Singapore and Peranakan Museum capture cultural immersion demand from European and Australian source markets.
- Shopping Districts:Orchard Road luxury retail and Jewel Changi Airport transit commerce compete for tax-free spending from short-haul ASEAN visitors.
- Natural Parks:Bukit Timah Nature Reserve and Gardens by the Bay provide low-carbon itinerary alternatives. BCA Green Mark certification of new attractions elevates sustainability preference capture.
Entertainment venues absorb the heaviest capital allocation. Cultural landmarks are climbing the fastest in visitor satisfaction metrics with minimal reinvestment requirements.
Service Offering:
Digital intermediation is compressing margins in traditional service categories while creating yield control points for platform-native aggregators.
- Accommodation Packages:Integrated resort bundling extends length-of-stay through entertainment and dining inclusions. Revenue management systems optimize dynamic pricing across Marina Bay Sands and boutique hotel inventory.
- Dining Experiences:Hawker heritage recognition and Michelin-density positioning differentiate Singapore against Bangkok and Kuala Lumpur. Pre-arrival mobile booking now captures majority of restaurant spend before physical arrival.
- Guided Tours:Walking tours of ethnic precincts and heritage trails serve first-time visitors with limited independent navigation confidence.
- Transportation Services:Grab and Gojek displace traditional taxi and coach segments through app-based booking convenience.
Accommodation packages retain the largest revenue pool. Dining experiences are gaining share fastest as itinerary design centers on culinary destination positioning.
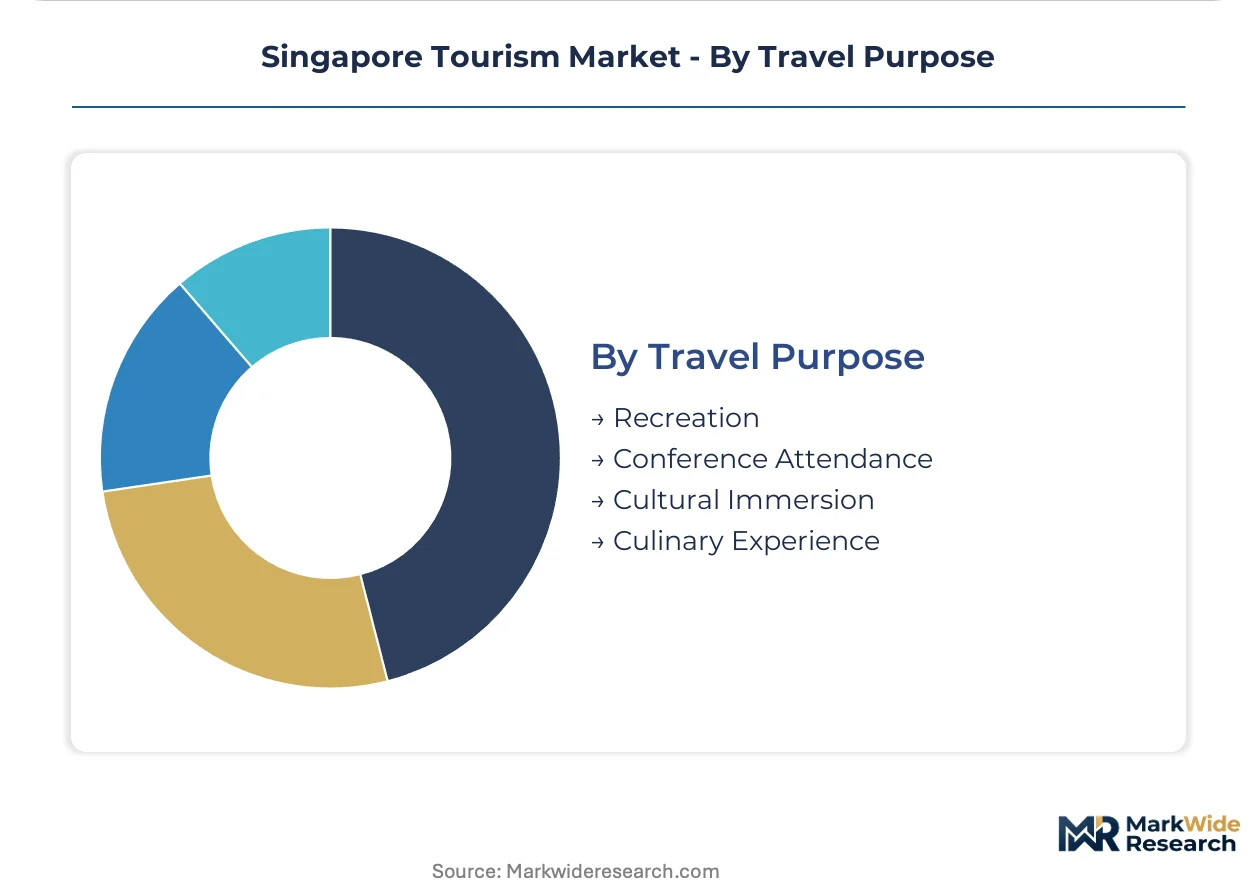
Travel Purpose:
Purpose-driven segmentation determines advance booking windows, cancellation flexibility demands, and cross-selling attach rates.
- Conference Attendance:MICE delegates generate compressed high-value stays with minimal leisure extension. Singapore Tourism Board's venue subsidies compete with Bangkok and Kuala Lumpur for association meeting contracts.
- Culinary Experience:Gastronomy-focused travelers from Hong Kong, Taiwan, and Australia drive fine-dining reservation demand and hawker center exploration. Michelin Guide density supports premium positioning.
- Recreation:Beach and wellness seekers concentrate in Sentosa with limited mainland penetration.
- Cultural Immersion:Ethnic precinct tourism and heritage trail walking serve repeat visitors seeking depth beyond landmark checklist itineraries.
Conference attendance secures contracted block bookings. Culinary experience is rotating up the share rankings as destination marketing emphasizes hawker UNESCO inscription and chef-driven dining density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's tourism economy generates substantial service exports that outweigh inbound visitor spending deficits against neighboring markets. The city-state's yield-per-visitor model depends on capturing high-value segments from regional source markets while managing competitive pressure from lower-cost ASEAN alternatives.
China
Upper-middle-class households in Shanghai and Shenzhen drive premium leisure demand for integrated resort packages. The country's national tourism administration promotes bilateral visa facilitation agreements that compress entry processing timelines. Singapore's Mandarin-language service infrastructure concentrates in Marina Bay and Orchard Road precincts.
India
Affluent travelers from Mumbai and Delhi command per-trip expenditure multiples above ASEAN mass-market averages. The Reserve Bank of India's liberalized outward remittance rules expand discretionary travel budgets for high-net-worth individuals. Singapore Airlines anchors connectivity through daily nonstop services from six Indian metros.
Indonesia
Jakarta and Surabaya business travelers sustain weekday corporate rate agreements across Singapore's central business district hotels. The country's investment coordination board promotes MICE delegation subsidies that compete for regional association meetings. Batam-Bintan ferry links concentrate same-day excursion demand.
Malaysia
Kuala Lumpur's lower cost structure captures price-sensitive leisure segments that Singapore's premium positioning excludes. The Malaysia Digital Economy Corporation mandates platform interoperability standards that rival Singapore's IMDA requirements. Johor Bahru's proximity enables spillover shopping and entertainment day-trips.
Australia
Sustainability-conscious travelers from Sydney and Melbourne respond to BCA Green Mark certification signals in hotel procurement decisions. The country's trade and investment commission promotes bilateral tourism marketing funds that amplify destination awareness. Qantas and Jetstar maintain dense frequency on the Kangaroo Route through Changi.
Singapore Tourism Market Competitive Landscape
Concentration sits with integrated resort operators and network carriers that control yield-per-visitor optimization through captive spend ecosystems. The market structure tiers between premium hospitality anchors and digital-native aggregators that disintermediate traditional booking channels. Strategic archetypes include yield-managed resort conglomerates, hub-dominant full-service airlines, and mobile-first experience platforms. Dominant competitive moves center on bundled packaging extensions and last-mile digital aggregation capture.
Within the integrated resort tier, Marina Bay Sands anchors luxury demand through entertainment-dining-accommodation bundling that extends visitor dwell time. Singapore Airlines exemplifies network-carrier dominance through hub-and-spoke connectivity that feeds inbound flows from Europe, Australia, and North Asia. Klook occupies a position among digital aggregators that control pre-arrival activity spend, particularly among first-time visitors from China and India under age 35.
| Leading Market Players |
|---|
| Klook |
| Wego.com |
| Singapore Airlines |
| Trafalgar |
| Intrepid Travel |
| Marina Bay Sands |
| RedDoorz |
| Singapore Tourism Board |
| GlobalTix |
| Others |
Value Network & Pricing Analysis
Pre-arrival booking windows of 45-60 days compress revenue management cycles while concentrating yield control with digital aggregators that intermediate between hospitality inventory and price-sensitive leisure segments from India and China.
Pricing Analysis
Affluent leisure travelers from Mumbai and Delhi anchor Singapore's premium-tier pricing structure through integrated resort bundling that extends average length of stay. Three-tier pricing stratifies across luxury hospitality, boutique accommodation, and economy lodging segments based on BCA Green Mark certification status and proximity to Marina Bay entertainment clusters. Pricing pressure stems from Kuala Lumpur and Bangkok's lower cost structures capturing price-sensitive ASEAN segments. Corporate MICE delegates exhibit lowest price sensitivity through contracted block bookings, while solo travelers under 35 demonstrate highest elasticity to mobile-native platform discounts.
Supply Chain Analysis
Malaysia and Indonesia anchor Singapore's visitor inflow infrastructure through dense short-haul flight connectivity and ferry links that feed same-day excursion demand. Hospitality service delivery draws from Philippines and Myanmar for guest-facing labor, while F&B supply chains rest on Australian agricultural imports and regional seafood procurement from Vietnam and Thailand. Single-source vulnerability concentrates in labor recruitment pipelines post-pandemic. Distribution runs through Singapore Airlines' hub-and-spoke network and digital platforms including Klook and Wego.com that control pre-arrival activity spend.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's tourism economy is approaching a platform-economics inflection as IMDA-mandated API interoperability forces traditional hospitality operators to cede yield control to mobile-native aggregators that intermediate visitor touchpoints.
For Market Incumbents: Consolidate captive spend ecosystems through deeper entertainment-dining-accommodation bundling at Marina Bay Sands and Resorts World Sentosa to offset Klook's disintermediation of pre-arrival bookings. Defend against Bangkok and Kuala Lumpur's price competition by accelerating BCA Platinum certification to capture corporate travel procurement with embedded sustainability screens. Prioritize loyalty program investments that extend visitor dwell time across gaming, retail, and F&B touchpoints. For New Entrants and Emerging Players: Last-mile experience curation gaps in heritage trail digitization and hawker center booking infrastructure present white-space targets where incumbent operators under-serve independent explorers. Penetrate the solo traveler under-35 segment through Mandarin and Hindi-language mobile interfaces that Klook has not fully optimized. Deploy AI-curated itinerary tools that compress planning friction for first-time visitors from tier-two Chinese and Indian cities. For Investors and Strategic Acquirers: Carve-out targets emerge from regional airline loyalty programs and boutique hotel management contracts that lack integrated resort scale to compete for premium leisure demand. Long-term viability hinges on yield-per-visitor optimization rather than volume growth given Singapore's fixed territorial constraints. Monitor IMDA enforcement actions on platform interoperability as the signal indicating regulatory pressure on digital aggregator dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Resort Bundling Extension | Marina Bay Sands and Resorts World Sentosa capture extended-stay bookings through entertainment-dining-accommodation packages that lift daily spend above regional benchmarks. |
| BCA Green Mark Certification Investment | Platinum-rated developments capture corporate travel procurement policies with embedded sustainability screens from Australian and Northern European source markets. |
| Last-Mile Digital Aggregation Partnership | Pre-arrival mobile booking platforms now control 60-70 percent of visitor activity spend, concentrating yield with Klook and similar aggregators. |
| Workforce Development Grant Utilization | Singapore Tourism Board subsidies offset post-pandemic attrition in guest-facing service roles that threaten hospitality service quality. |
| Biometric Transit Infrastructure Expansion | Immigration and Checkpoints Authority facial recognition lanes at Changi Airport compress airside-to-curbside transit below 10 minutes, resetting regional hub benchmarks. |
Research Methodology
A standing panel of revenue management directors at integrated resorts, Singapore Tourism Board destination marketing leads, airline network planning executives, and digital platform product managers provided ongoing calibration throughout the study. Primary interviews combined with secondary validation against Singapore Tourism Board visitor arrival statistics, Changi Airport passenger traffic disclosures, and IMDA digital service standard compliance filings. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators from the Monetary Authority of Singapore and Reserve Bank of India outward remittance data.
Consistency checks validated volume and value outputs against external benchmarks including ASEAN tourism arrival aggregates and hotel occupancy indices from the Singapore Hotel Association. The analytical framework modeled visitor type, attraction format, and service delivery mode segmentation across the projection horizon. CAGRs derived from trend extrapolation of yield-per-visitor metrics and average length of stay patterns, incorporating Singapore's Smart Nation infrastructure deployment timeline and bilateral visa facilitation agreements with China and India as industry-specific inputs.
Material uncertainties — pandemic resurgence, regional geopolitical friction affecting China outbound flows, and abrupt shifts in ASEAN open-sky agreements — sit outside the modeled envelope. Forecasts reflect assumptions about sustained affluence growth in Mumbai, Delhi, Shanghai, and Shenzhen source markets. Recalibration cycles align with material shifts in IMDA enforcement actions, BCA certification mandate expansions, and Singapore Tourism Board convention subsidy allocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
South Korea Tourism Market
Travel and Tourism
Japan Sports Tourism Market
Travel and Tourism
Asia Pacific Wellness Travel Market
Travel and Tourism
Sustainable Traveling Market
Travel and Tourism
Customised Holidays Market
Travel and Tourism
Leisure Travel Market
Travel and Tourism
Global Enotourism Market
Travel and Tourism
Yacht Charter Market
Travel and Tourism
Asia-Pacific MICE Tourism Market
Travel and Tourism
Global Golf Travel Market
Travel and Tourism
Travel Intermediaries Business Market
Travel and Tourism
US and Canada Travel Market
Travel and Tourism
USA Sports Tourism Market
Travel and Tourism
Indonesia Sustainable Tourism Market
Travel and Tourism
France Culinary Tourism Market
Travel and Tourism
India Outbound Tourism Market