
 Wellness Tourism Market | 2026-2036
Wellness Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Wellness Tourism Market Intelligence
Buyer concentration among corporate wellness purchasers is repositioning procurement power toward employer-funded retreat packages and incentive travel planners. Marriott International leverages its Bonvoy loyalty ecosystem to anchor extended-stay wellness programming across resort portfolios. Canyon Ranch specializes in clinical-grade integrative health immersions that differentiate it from conventional hospitality offerings. Hyatt Hotels Corporation controls premium urban wellness center placements through its Exhale brand integration.
Wellness tourism encompasses travel explicitly motivated by the pursuit of physical, mental, or spiritual well-being through structured services delivered at dedicated destinations. Core offerings integrate evidence-based therapies—halotherapy, hydrothermal circuits, mindfulness training—with biometric assessment protocols and nutrition programming designed to produce measurable health outcomes. Spa retreats and nature immersion segments command the deepest margin pools due to higher per-guest spending and longer average lengths of stay. Solo travelers and professionals represent the fastest-expanding customer demographic as burnout prevention and work-life boundary restoration drive booking intent.
FDA oversight of wellness claims in medical-adjacent spa services shapes product boundary definitions, while EU Green Deal destination certification requirements mandate carbon accounting and biodiversity protection standards for coastal and rural properties. Japan's METI promotes onsen thermal bath standards that preserve traditional mineral content specifications while accommodating international visitor expectations. Stakeholders must monitor how emerging digital health passport frameworks will interface with existing booking channel infrastructure and destination type eligibility criteria.
Market Dynamics
Employer-funded retreat procurement is concentrating purchasing power among corporate wellness directors, reshaping how coastal properties negotiate group bookings and package pricing. This buyer consolidation is forcing destination operators to restructure commission frameworks and loyalty integrations.
Growth Catalysts
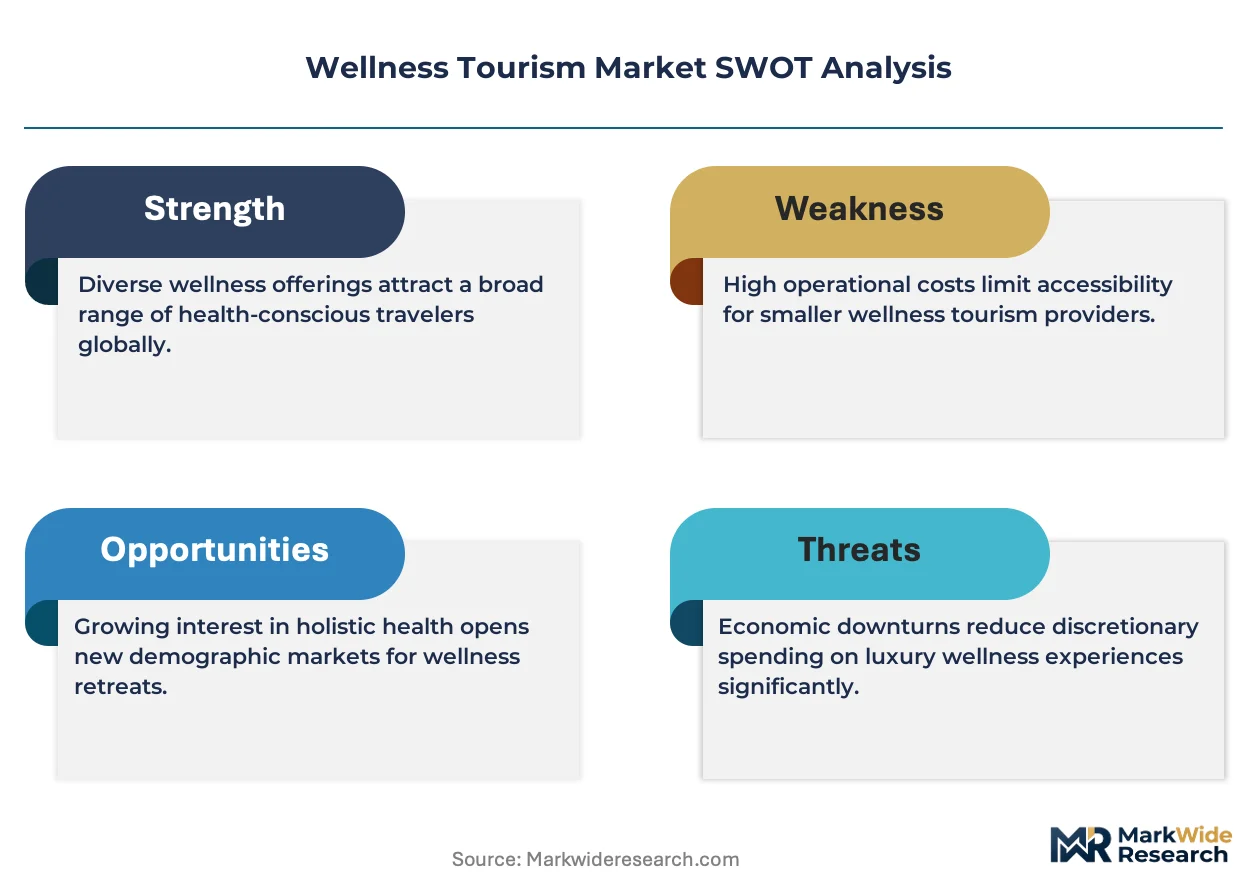
- EU Green Deal certification mandates:Properties achieving carbon-accounted biodiversity standards command premium positioning in corporate RFPs, accelerating capital allocation toward retrofitting coastal facilities.
- Biometric assessment protocols:Wearable-integrated health programming allows retreats to demonstrate measurable guest outcomes, satisfying corporate procurement requirements for ROI documentation.
- Portugal-Spain-Greece coastal clustering:Concentrated thermal bath and halotherapy infrastructure in these markets creates network effects for multi-destination itinerary planners.
Market Restraints
- Specialized clinical staffing shortages:Integrative health practitioners require dual certification in hospitality and medical-adjacent protocols, constraining property expansion timelines.
- Input cost volatility in organic supply chains:Nutrition programming depends on certified organic sourcing that faces weather-driven price swings and limited supplier bases.
- FDA wellness claim boundaries:Medical-adjacent spa services operate under strict promotional limitations that prevent outcome guarantees in consumer-facing materials.
Strategic Opportunities
- Japan METI onsen standard harmonization:Properties adapting traditional mineral bath specifications for international visitor expectations access underserved East Asian corporate retreat demand.
- Digital health passport integration:Biometric data portability between booking platforms and destination health systems creates stickiness for loyalty ecosystem participants.
- Extended-stay urban wellness centers:Hybrid work policies enable month-long residential programming that blends remote employment with structured health interventions.
Industry Challenges
- Cross-functional talent acquisition:Properties struggle to recruit staff fluent in both hospitality operations and clinical-grade service delivery protocols.
- Multi-jurisdiction certification complexity:Operators pursuing simultaneous EU Green Deal, FDA-adjacent, and national thermal bath credentials face divergent audit timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wellness Tourism Market |
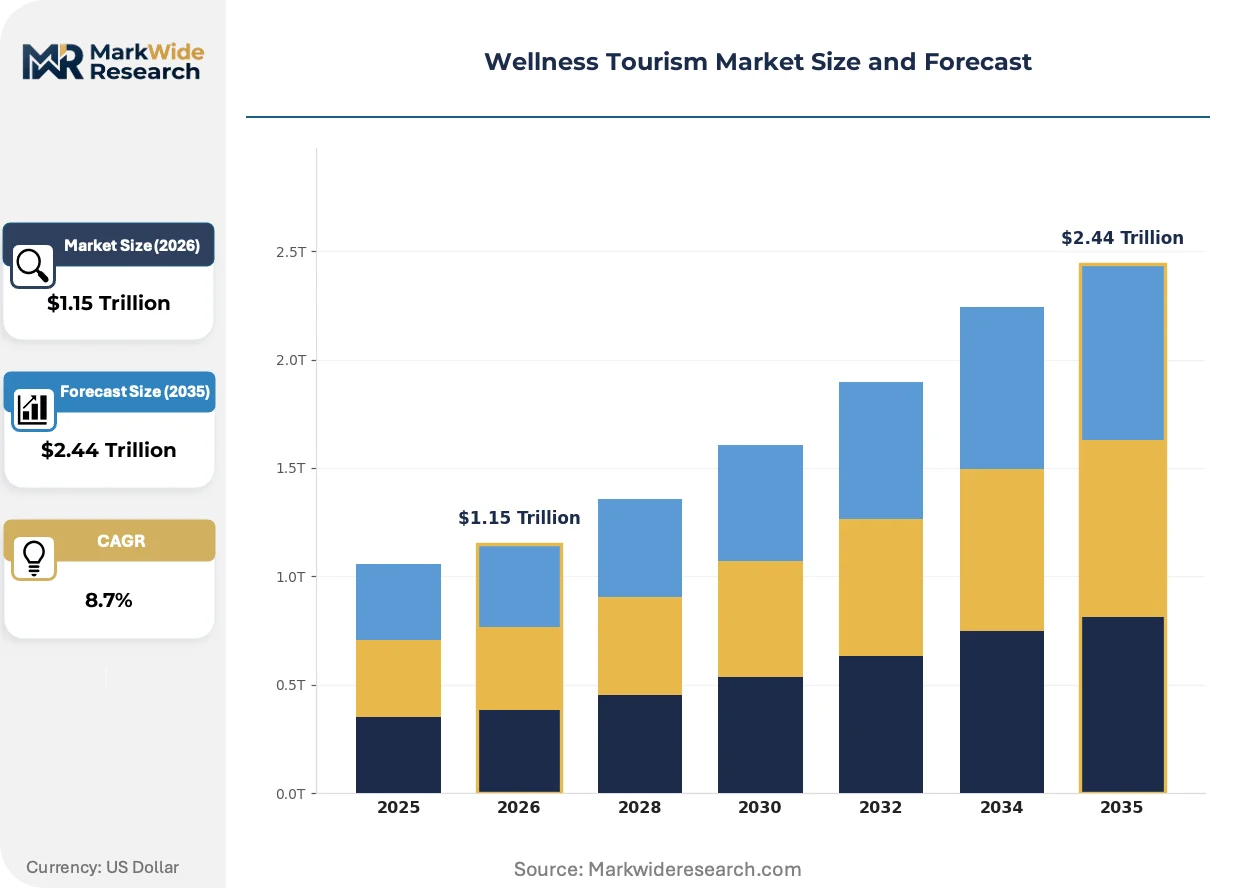
| Market Size in 2026 | $1.15 Trillion |
| Market Size in 2035 | $2.44 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Spa Retreats, Yoga Holidays, Meditation Tours, Detox Programs, Nature Immersion, Thermal Baths Customer Demographic: Millennials, Baby Boomers, Professionals, Retirees, Couples, Solo Travelers Booking Channel: Online Travel Agencies, Direct Bookings, Travel Agents, Wellness Platforms, Corporate Packages, Specialty Boutiques Destination Type: Mountain Resorts, Coastal Retreats, Rural Sanctuaries, Urban Wellness Centers, Cultural Sites, Adventure Zones |
| Companies Covered | Accor, InterContinental Hotels Group, Hilton Worldwide, Aman Resorts, Radisson Hotel Group, Marriott International, Hyatt Hotels Corporation, Canyon Ranch, Four Seasons Hotels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wellness Tourism Market Strategic Shifts & Innovations
Technology-enabled health outcome verification is displacing subjective wellness promises, while regulatory pressure on sustainability claims accelerates capital deployment toward certified properties. These forces are compressing margins for uncertified competitors.
Biometric monitoring infrastructure is consolidating guest health data across pre-arrival assessments, on-property interventions, and post-departure tracking. Corporate wellness purchasers now mandate this data continuity for contract renewal. The technology is consolidating procurement decisions around platforms demonstrating longitudinal outcome metrics rather than episodic experience quality.
EU Green Deal destination certification requirements are mandating carbon accounting and biodiversity protection standards for coastal and rural properties. Operators face retrofitting timelines that compress development windows. Mediterranean facilities are responding fastest, leveraging existing solar thermal and water reclamation investments to meet audit thresholds ahead of Northern European competitors.
Solo travelers and professionals are booking longer stays with explicit burnout-prevention objectives, displacing traditional leisure-weekend segmentation. Corporate incentive travel planners are capturing this demand through extended-stay packages that blend remote work infrastructure with scheduled health interventions. Portugal and Spain report the strongest concentration of this behavioral shift among technology sector employers.
Wellness Tourism Market Segmentation
Buyer decision pathways in wellness tourism diverge sharply between corporate procurement officers seeking measurable ROI documentation and individual travelers prioritizing subjective restoration outcomes. Service architecture and booking infrastructure must align with these divergent evaluation frameworks.
Service Type:
Corporate wellness directors prioritize services with quantifiable biometric endpoints and longitudinal health tracking capabilities.
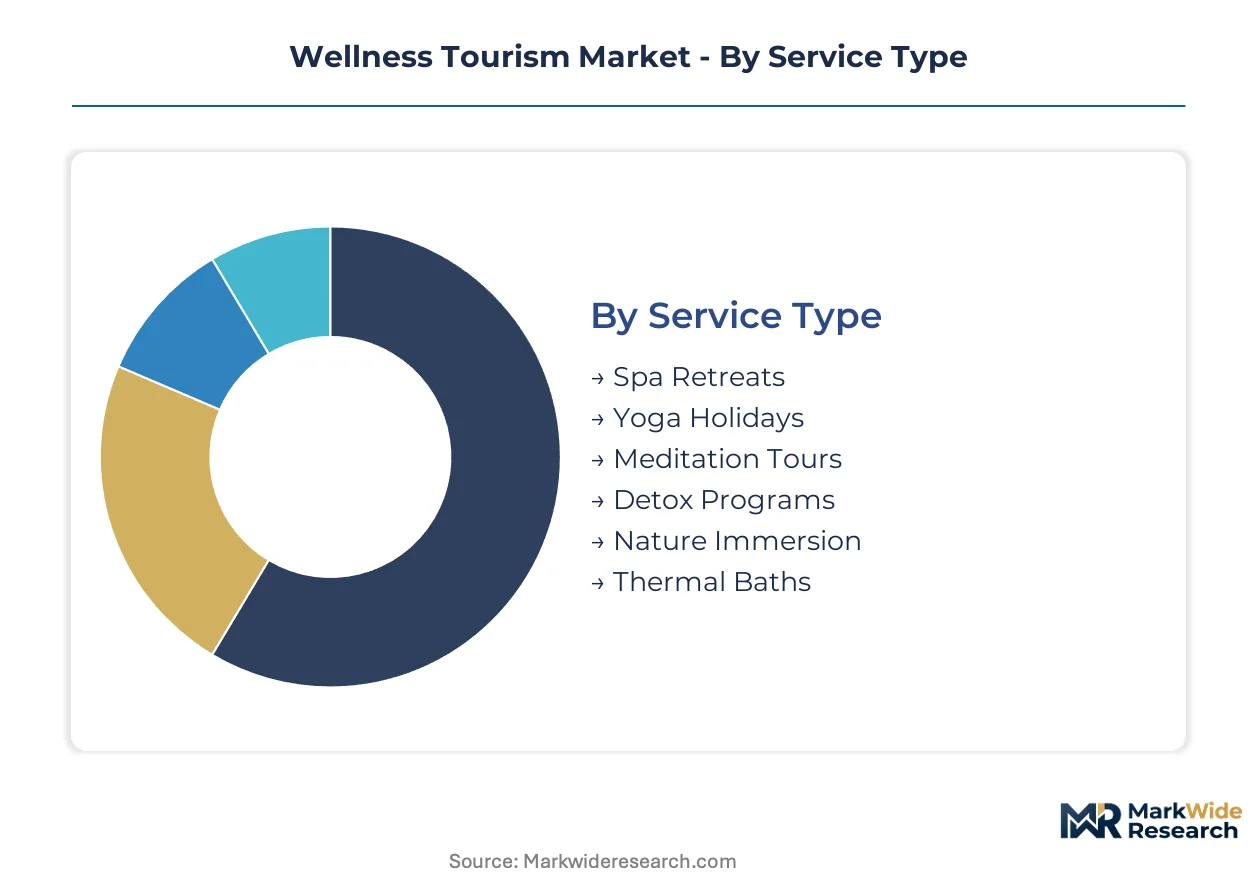
- Spa Retreats:Comprehensive facilities integrate hydrothermal circuits, halotherapy chambers, and clinical-grade massage protocols with pre-arrival health assessments. Demand concentrates among employer-funded group bookings in Portugal and Spain where thermal infrastructure density supports multi-destination corporate itineraries.
- Nature Immersion:Structured wilderness programming combines biometric stress monitoring with guided forest bathing and digital detox protocols. Solo professionals from technology sector employers represent the fastest-expanding customer base as hybrid work policies enable extended rural stays.
- Yoga Holidays:Instructor-led intensive programs blending asana practice with Ayurvedic nutrition planning.
- Meditation Tours:Structured mindfulness training delivered across multiple destination stops with teacher continuity.
- Detox Programs:Medically supervised nutrition interventions with laboratory biomarker verification.
- Thermal Baths:Traditional mineral water therapies adhering to Japan METI content specifications or EU thermal spa standards.
Spa Retreats leads on scale; Nature Immersion leads on momentum.
Customer Demographic:
Booking value and length-of-stay patterns vary dramatically by life stage and employment status.
- Solo Travelers:Individual bookers pursuing explicit burnout prevention objectives through extended-stay programming. Technology sector employers in Portugal and Spain fund these placements as retention instruments, displacing traditional weekend leisure segmentation.
- Professionals:Employed individuals leveraging hybrid work policies to combine remote employment with structured health interventions. Corporate incentive travel planners capture this demand through month-long residential packages.
- Millennials:Younger travelers prioritizing Instagram-compatible aesthetic experiences and social wellness programming.
- Baby Boomers:Affluent older travelers seeking clinical-grade integrative health services with medical oversight.
- Retirees:Extended-stay guests with flexible calendars and chronic condition management priorities.
- Couples:Paired travelers booking relationship-focused retreats with shared accommodation preferences.
Professionals command the highest per-guest revenue; Solo Travelers exhibit the steepest expansion trajectory.
Booking Channel:
Commission structures and data ownership terms determine operator channel strategy.
- Corporate Packages:Employer-funded retreat procurement concentrates purchasing power among wellness directors who mandate biometric outcome documentation and loyalty ecosystem integration. Properties restructure commission frameworks to secure multi-year contracts.
- Wellness Platforms:Specialized aggregators curating clinical-grade properties with verified practitioner credentials and standardized health assessment protocols. These platforms capture solo professional demand through subscription-based booking privileges.
- Online Travel Agencies:Generalist platforms with limited wellness-specific filtering and outcome verification capabilities.
- Direct Bookings:Property-controlled reservations enabling maximum guest data capture and loyalty program enrollment.
- Travel Agents:Traditional intermediaries serving retiree and couple segments with package customization.
- Specialty Boutiques:High-touch advisors placing ultra-premium clients in exclusive properties.
Corporate Packages dominate volume concentration; Wellness Platforms gain share fastest.
Destination Type:
Certification requirements and infrastructure retrofit costs shape geographic investment decisions.
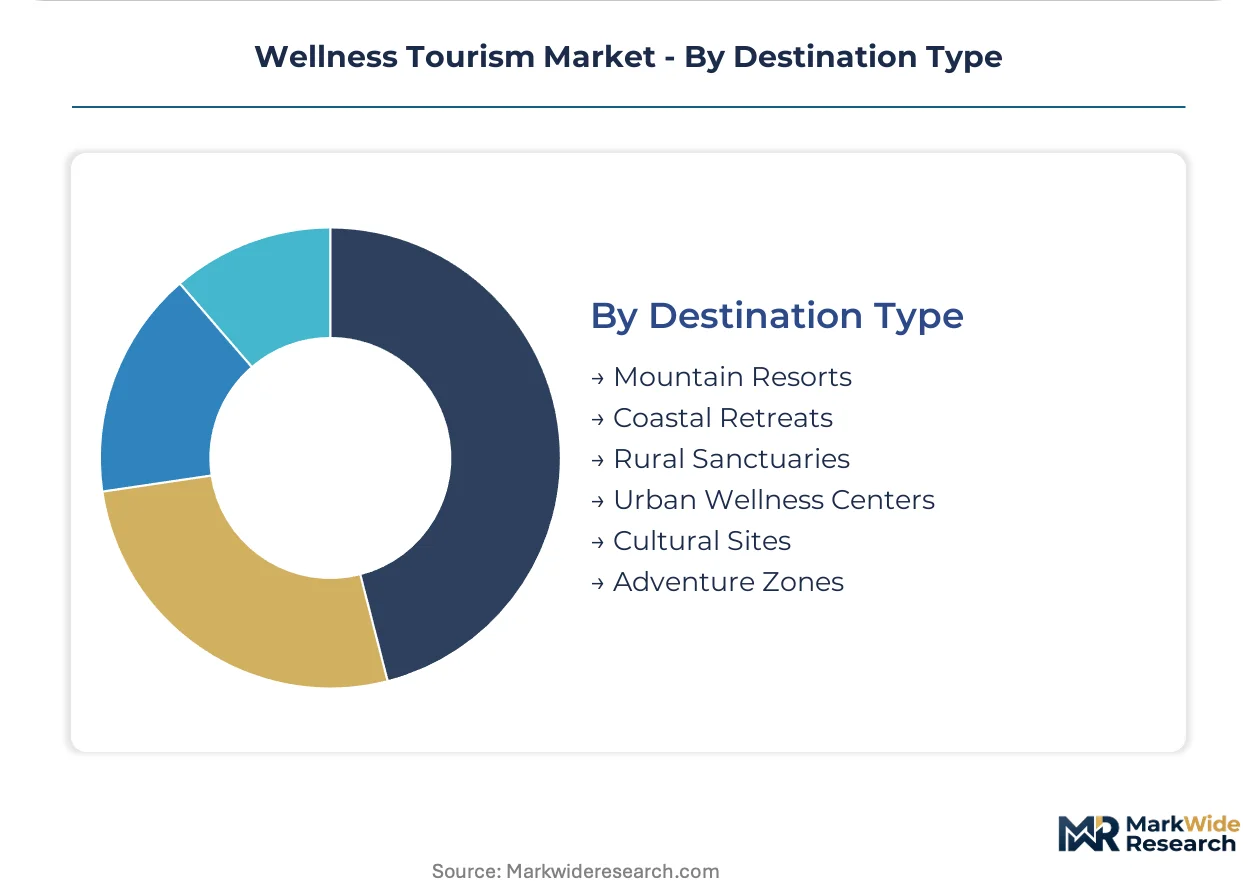
- Coastal Retreats:Mediterranean facilities in Portugal, Spain, and Greece leverage existing solar thermal and water reclamation investments to meet EU Green Deal audit thresholds ahead of schedule. Corporate RFPs increasingly mandate carbon-accounted biodiversity standards that these properties satisfy.
- Urban Wellness Centers:City-based facilities integrating remote work infrastructure with scheduled health interventions. Extended-stay residential programming targets professionals whose employers fund month-long placements.
- Mountain Resorts:Alpine properties emphasizing altitude training and outdoor adventure programming.
- Rural Sanctuaries:Agricultural and forest settings requiring significant EU Green Deal compliance investment.
- Cultural Sites:Heritage properties combining wellness programming with historical and artistic immersion.
- Adventure Zones:Activity-intensive destinations pairing physical challenge with recovery services.
Coastal Retreats anchor current supply; Urban Wellness Centers climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate wellness directors and hybrid work professionals cluster in specific coastal and urban corridors, driving destination investment toward properties with EU Green Deal certification and biometric outcome capabilities.
Portugal
Employer-funded retreat procurement from technology sector companies concentrates purchasing power in Lisbon and Algarve coastal properties. EU Green Deal carbon-accounted biodiversity standards accelerate retrofitting timelines for thermal bath facilities. The Algarve region leverages existing solar thermal infrastructure to meet audit thresholds ahead of Northern European competitors.
Spain
Corporate incentive travel planners capture extended-stay demand from professionals combining remote work with structured health interventions. National thermal spa standards interface with EU destination certification requirements for coastal properties. Barcelona and Costa del Sol anchor the densest concentration of halotherapy and hydrothermal circuit infrastructure.
Greece
Solo travelers pursuing explicit burnout prevention objectives drive booking volume in Aegean island retreats. EU Green Deal mandates reshape capital allocation toward water reclamation and biodiversity protection investments. Crete and the Cyclades report the steepest expansion in employer-funded month-long residential programming.
Japan
METI onsen thermal bath standards preserve traditional mineral content specifications while accommodating international visitor expectations. Corporate retreat demand from East Asian technology employers accesses underserved extended-stay segments. Kyushu and Hokkaido onsen clusters adapt infrastructure for biometric-integrated health programming.
United States
FDA oversight of wellness claims in medical-adjacent spa services shapes product boundary definitions for clinical-grade integrative health offerings. Employer wellness program expansion drives retreat procurement concentration among Fortune 500 wellness directors. Arizona and California desert properties anchor the domestic clinical-grade wellness immersion segment.
Wellness Tourism Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered service architectures. Consolidation patterns favor hospitality conglomerates with loyalty ecosystem integration capabilities over standalone retreat operators. Three strategic archetypes dominate: integrated resort-hospitality conglomerates, clinical-grade wellness specialists, and urban wellness center operators. Competitive moves concentrate on M&A for biometric technology capabilities and strategic partnerships for corporate wellness contract access.
Within the integrated hospitality tier, Marriott International and Hyatt Hotels Corporation exemplify loyalty-anchored wellness programming across extended-stay portfolios. Canyon Ranch occupies a specialist position representing clinical-grade integrative health immersions differentiated from conventional hospitality offerings. These three anchors illustrate the competitive tension between scale-driven ecosystem integration and outcome-focused specialization.
| Leading Market Players |
|---|
| Accor |
| InterContinental Hotels Group |
| Hilton Worldwide |
| Aman Resorts |
| Radisson Hotel Group |
| Marriott International |
| Hyatt Hotels Corporation |
| Canyon Ranch |
| Four Seasons Hotels |
| Others |
Cost & Logistics Intelligence
Certification-tier divergence between EU Green Deal-compliant coastal properties and uncertified competitors manifests in divergent pricing power and supply chain sourcing patterns. Premium-tier retreats command rate premiums through carbon-accounted biodiversity credentials that require certified organic nutrition programming and specialized clinical staffing, while standard-tier operators face margin compression from input cost volatility in organic supply chains.
Pricing Analysis
Capacity additions in Portugal and Spain are reshaping price floors for employer-funded retreat packages as thermal bath infrastructure density intensifies competitive pressure. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and biometric outcome verification capabilities. Pricing pressure stems from organic supply chain cost volatility constraining nutrition programming margins. Corporate wellness directors exhibit lowest price sensitivity due to ROI documentation requirements, while individual leisure travelers face highest sensitivity.
Supply Chain Analysis
Regional distribution centers in Lisbon, Barcelona, and Athens anchor hub-and-spoke patterns for clinical-grade equipment and certified organic provisions. Supply concentrates in Portugal, Spain, and Greece for thermal infrastructure components and halotherapy chamber systems. Raw material dependencies include certified organic produce, specialized mineral bath compounds, and biometric monitoring hardware. Single-source vulnerability runs through limited bases of dual-certified integrative health practitioners. Distribution runs through corporate incentive travel planners and wellness platform aggregators with loyalty ecosystem integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wellness tourism functions as a geographic-arbitrage play where EU Green Deal compliance costs in Northern Europe exceed retrofitting investments in Mediterranean solar thermal infrastructure, redirecting capital toward Portugal and Spain.
For Market Incumbents: Cement loyalty ecosystem stickiness through biometric data portability investments that satisfy corporate procurement requirements for longitudinal outcome tracking. Defend against pure-play clinical specialists by accelerating EU Green Deal certification timelines ahead of regulatory mandates. Prioritize vertical integration into organic supply chains to buffer margin pressure from weather-driven input volatility.
For New Entrants and Emerging Players: Biometric-integrated health programming offers a technology-first wedge into underserved urban wellness center segments where hybrid work policies enable month-long residential placements. Target extended-stay urban properties in technology sector corridors with employer-funded procurement concentration. Pursue white-label partnerships with corporate incentive travel planners lacking outcome verification capabilities.
For Investors and Strategic Acquirers: Consolidation pressure builds where loyalty ecosystem integration capabilities determine corporate contract access, favoring hospitality conglomerates over standalone operators. Five-to-ten-year viability hinges on biometric technology ownership and EU Green Deal credential portfolios. Target acquisition archetypes include clinical-grade wellness specialists with METI onsen standard harmonization capabilities. Monitor digital health passport framework adoption as inflection indicator for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| EU Green Deal Certification Acceleration | Properties achieving carbon-accounted biodiversity standards command premium positioning in corporate RFPs ahead of competitors. |
| Biometric Technology Acquisition | Wearable-integrated health programming satisfies corporate procurement requirements for longitudinal outcome documentation. |
| Extended-Stay Urban Center Development | Month-long residential programming captures hybrid work professionals combining remote employment with structured interventions. |
| Organic Supply Chain Integration | In-house certified organic sourcing buffers margin pressure from weather-driven price swings and limited supplier bases. |
| Digital Health Passport Partnership | Biometric data portability between booking platforms and destination systems creates stickiness for loyalty ecosystem participants. |
Research Approach
Multiple input streams — corporate wellness director interviews, thermal facility operator assessments, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged retreat procurement officers, integrative health practitioners, incentive travel planners, and EU destination certification auditors. Secondary validation drew from EU Green Deal implementation documents, METI onsen standard publications, FDA wellness claim guidance, and hospitality sector SEC disclosures.
Data-stream reconciliation across supply-side capacity tracking and demand-side booking pattern analysis shaped the analytical framework. Segmentation dimensions modeled include service type architecture, customer demographic life stage, booking channel commission structures, and destination certification tier. CAGRs were derived from geometric progression linking baseline market valuation to projected endpoint across the modeling period. Forecast inputs incorporated EU retrofitting timeline assumptions and corporate wellness program expansion trajectories.
The model holds under sustained employer-funded retreat procurement growth; deviation in hybrid work policy reversal or EU Green Deal enforcement delays would shift trajectory. Forecasts reflect documented assumptions about biometric technology adoption curves and organic supply chain stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Wedding Tourism Market
Travel and Tourism
Customised Holidays Market
Travel and Tourism
GCC Outbound Tourism Market
Travel and Tourism
Germany Outbound Tourism Market
Travel and Tourism
UK Outbound Travel Market
Travel and Tourism
Europe Wellness Tourism Market
Travel and Tourism
Domestic Tourism Market
Travel and Tourism
Agritourism Market
Travel and Tourism
Airline Retailing Market
Travel and Tourism
Camping and Caravanning Market
Travel and Tourism
Inflight Shopping Market
Travel and Tourism
India Sustainable Tourism Market
Travel and Tourism
France Culinary Tourism Market
Travel and Tourism
Water Park Market
Travel and Tourism
Travel Intermediaries Business Market
Travel and Tourism
Cycle Tourism Market