
 Europe Flavors and Fragrances Market | 2026-2036
Europe Flavors and Fragrances Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Flavors and Fragrances Market Foresight
Buyer concentration among European food and beverage multinationals is expanding as private-label growth and retailer consolidation reshape procurement volumes. Givaudan leverages its integrated flavor creation platforms to serve these consolidated buyers across Western Europe. Symrise AG anchors its position through deep specialization in natural extracts and regional taste preferences. DSM-Firmenich competes by combining nutrition science with fragrance innovation, creating cross-category synergies that smaller suppliers cannot replicate.
Flavors and fragrances comprise volatile and semi-volatile organic compounds—including esters, terpenoids, and aldehydes—synthesized or extracted to impart sensory characteristics to consumer products, with formulations typically optimized for stability at specific pH ranges and thermal processing conditions. Essential oils and aroma chemicals represent mature, high-volume categories where margin compression from commoditization pressures suppliers toward premium natural positioning. Fragrance oils command stronger pricing power in cosmetics and personal care applications where brand differentiation depends on proprietary scent signatures. Flavoring agents for baking and confectionery applications show structural momentum as clean-label reformulations require complex taste modulation to compensate for reduced sugar and salt content.
EMA, ECHA under REACH, and EFSA frameworks govern ingredient safety assessments, allergen labeling, and novel substance approvals across European flavor and fragrance applications. These regulations raise compliance costs but also create barriers that favor established suppliers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving restrictions on synthetic musks and allergen thresholds while building flexible formulation pipelines that can adapt to substance bans without disrupting customer supply agreements.
Market Dynamics
REACH compliance and the EU Green Deal are forcing European flavor and fragrance suppliers to rebuild formulation pipelines around bio-based feedstocks while maintaining performance parity with legacy synthetic portfolios.
Growth Catalysts
- Clean-label reformulation mandates:Packaged food manufacturers across France and Germany require complex taste modulation systems to compensate for reduced sugar and salt content without synthetic additives.
- ECHA substance screening acceleration:Streamlined novel ingredient approvals under evolving REACH frameworks enable faster market entry for fermentation-derived aroma molecules.
- Cosmetic production clustering:Concentrated manufacturing in the Grasse region and Milan corridor generates captive demand for high-value fragrance oils with proprietary scent signatures.
Market Restraints
- Natural extract supply volatility:Weather-dependent yields of lavender, rose, and citrus essential oils from Southern European agricultural zones create input cost instability.
- Biocatalytic process scale-up barriers:Enzymatic synthesis routes for chiral aroma chemicals remain trapped at pilot scale due to fermentation infrastructure gaps.
- Synthetic musk substitution pressure:ECHA restrictions on nitro musks and polycyclic musks force rapid reformulation of legacy fragrance bases without equivalent cost alternatives.
Strategic Opportunities
- Poland and Czech Republic manufacturing expansion:Underpenetrated Central European markets offer greenfield sites for flavor production serving emerging private-label retail chains.
- Personalized fragrance subscription channels:Direct-to-consumer scent profiling platforms bypass traditional wholesale distribution to capture margin and consumer data.
- CSRD-aligned carbon accounting:Mandatory sustainability disclosure creates competitive differentiation for suppliers with verified bio-based supply chains and blockchain traceability.
Industry Challenges
- Flavorist and perfumer talent scarcity:Specialized formulation expertise combining sensory science with regulatory navigation commands premium compensation and retention risk.
- Multi-jurisdiction allergen labeling complexity:Divergent threshold definitions between EFSA, BfR, and ANSES create packaging compliance friction for pan-European product lines.
- Legacy ERP integration with batch tracking:Proprietary manufacturing execution systems resist interoperability with modern supply chain visibility platforms demanded by consolidated buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Flavors and Fragrances Market |
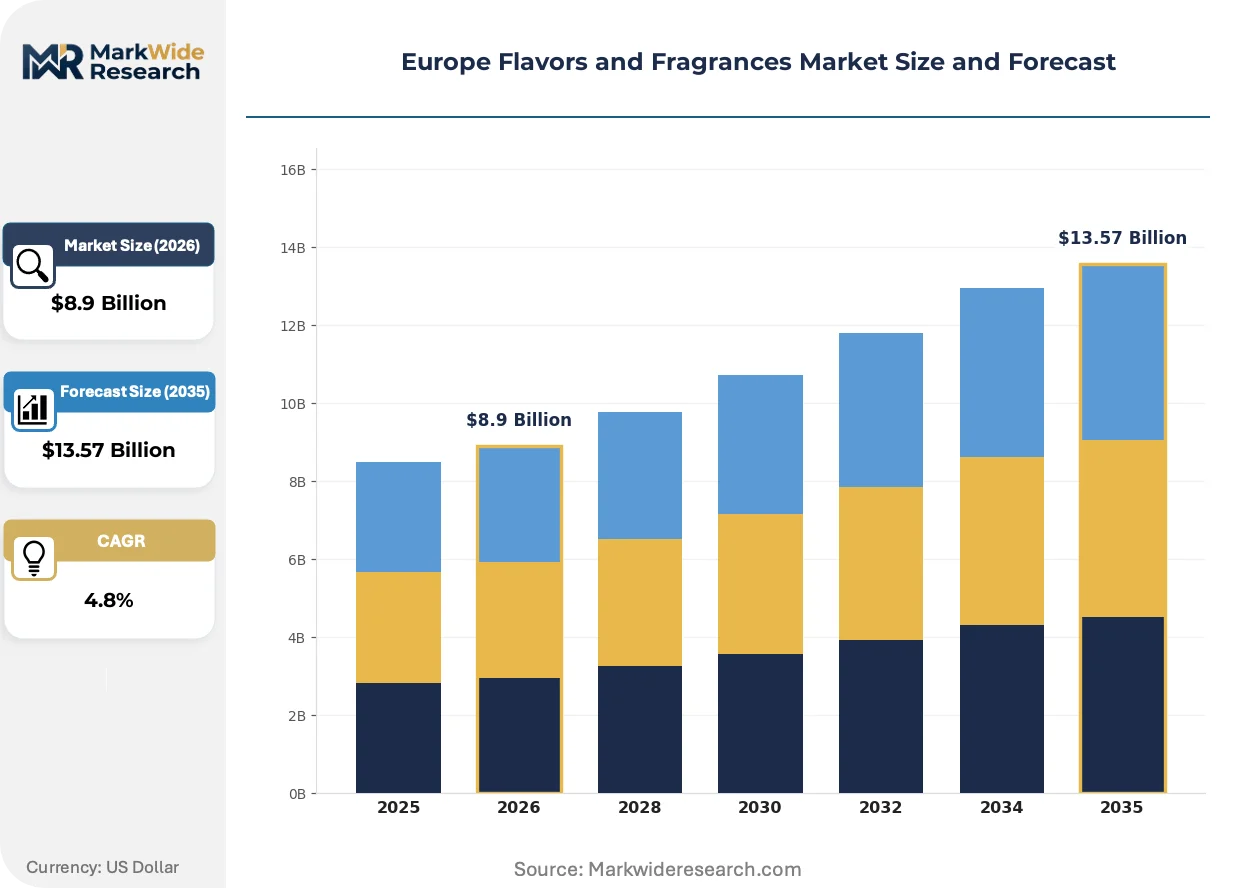
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $13.57 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavoring Agents, Fragrance Oils, Essential Oils, Aroma Chemicals End User: Food & Beverage, Cosmetics, Household Products, Pharmaceuticals Application: Baking, Confectionery, Personal Care, Cleaning Products Form: Liquid, Powder, Granular, Paste |
| Companies Covered | Givaudan, Symrise AG, DSM-Firmenich, International Flavors & Fragrances, Robertet, Mane, Takasago, Sensient Technologies, Bell Flavors and Fragrances, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Flavors and Fragrances Market Shifts & Advancements
Digital biology tools and precision fermentation are compressing development cycles for natural-identical molecules while regulatory disclosure requirements reshape competitive transparency across the value chain.
Precision fermentation platforms for producing natural-identical vanillin, nootkatone, and sandalwood molecules are consolidating technical capabilities among specialized biotech suppliers. Mid-tier fragrance houses in Italy and Spain adopt these inputs to bypass agricultural supply constraints. The technology is consolidating price-setting power away from traditional botanical extract traders toward engineered biology patent holders.
CSRD implementation through 2024 mandates granular Scope 3 emissions disclosure for flavor and fragrance ingredients, forcing suppliers to map carbon intensity across multi-tier agricultural and chemical supply chains. Large cosmetic manufacturers in France now require verified lifecycle data as a procurement gate. Fragrance oil categories face the steepest compliance burden due to complex international sourcing of rare botanicals.
Retailer consolidation across German and UK grocery channels has compressed supplier negotiation cycles from annual to quarterly frameworks. Category managers now demand real-time inventory visibility and flexible minimum order quantities. This pattern is most visible in savory flavor procurement for ready-meal applications, where private-label volume concentration enables aggressive price benchmarking against branded alternatives.
Europe Flavors and Fragrances Market Segmentation
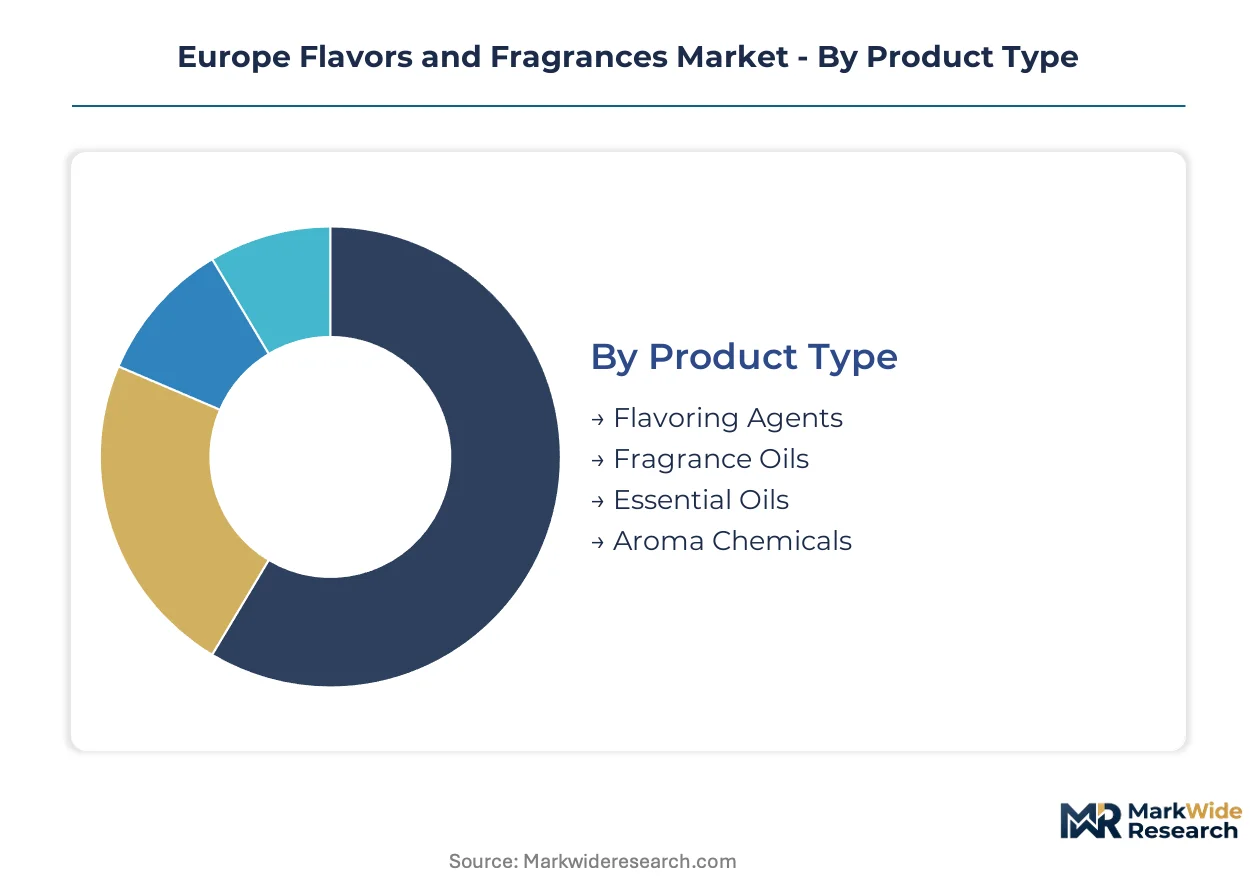
Segmentation in the Europe flavors and fragrances market reveals how formulation complexity, regulatory compliance burdens, and end-use performance requirements create distinct competitive arenas with divergent margin profiles and supplier capabilities.
Product Type:
Customization intensity spans from commodity aroma chemicals to bespoke fragrance oils, with bio-based positioning now cutting across all tiers.
- Flavoring Agents:Complex taste modulation systems compensate for reduced sugar and salt in clean-label reformulations across French and German packaged food manufacturing. EFSA allergen thresholds and novel food approvals govern ingredient portfolios, forcing suppliers to maintain parallel synthetic and natural-identical pipelines.
- Fragrance Oils:Proprietary scent signatures command premium pricing in cosmetics applications, with concentrated demand from Grasse and Milan production clusters. ECHA restrictions on nitro musks and polycyclic musks accelerate reformulation cycles without cost-equivalent synthetic alternatives.
- Essential Oils:Lavender, rose, and citrus extracts from Southern European agricultural zones face weather-dependent yield volatility.
- Aroma Chemicals:High-volume esters, terpenoids, and aldehydes face margin compression from commoditization pressures.
Leading the category by volume: Aroma Chemicals. Expanding most quickly: Flavoring Agents.
End User:
Buyer consolidation intensity varies sharply, with retailer-driven private-label growth reshaping procurement power across segments.
- Food & Beverage:Quarterly negotiation cycles now dominate German and UK grocery procurement, with real-time inventory visibility demanded for savory flavor applications in ready-meals. Clean-label mandates from major retail chains force complex taste modulation without synthetic additives.
- Cosmetics:CSRD-aligned carbon accounting and Scope 3 disclosure requirements from French manufacturers create procurement gates favoring suppliers with verified bio-based supply chains.
- Household Products:Mass-market cleaning applications prioritize cost-efficient fragrance delivery systems.
- Pharmaceuticals:EMA stability and purity standards govern excipient-grade flavor incorporation.
Food & Beverage generates the largest procurement volumes. Cosmetics commands the steepest sustainability compliance burden.
Application:
Processing conditions—thermal stability, pH tolerance, and release kinetics—determine formulation specifications across use cases.
- Baking:Heat-stable encapsulated flavors maintain sensory integrity through Maillard reaction temperatures, with demand concentrating in industrial bakery operations across Germany and Italy.
- Confectionery:Sugar reduction mandates drive complex taste modulation requirements for reduced-calorie candy and chocolate applications.
- Personal Care:Skin-safe fragrance bases with documented allergen profiles serve cream, lotion, and serum formulations.
- Cleaning Products:Aggressive alkaline environments require specialized fragrance encapsulation for stability.
Baking applications lead by formulation complexity. Personal Care shows the strongest pricing power for proprietary scent signatures.
Form:
Physical state selection hinges on manufacturing integration, storage economics, and controlled-release requirements.
- Liquid:Standard solvent-based delivery dominates high-volume fragrance compounding and flavor emulsion production, with flexible dosing integration into continuous manufacturing lines.
- Powder:Spray-dried encapsulates serve dry mix applications where moisture sensitivity prevents liquid incorporation.
- Granular:Controlled particle size distribution enables uniform dispersion in bulk dry blends.
- Paste:High-viscosity concentrates suit small-batch artisanal production and specialized confectionery applications.
Liquid forms dominate by production volume. Powder formats gain share fastest in clean-label dry mix segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetics and packaged food production clusters in France, Germany, and Italy concentrate regional demand for flavor and fragrance inputs. REACH compliance and CSRD disclosure mandates reshape supplier qualification criteria across procurement networks.
France
Grasse hosts the world's densest concentration of fragrance compounding facilities serving luxury cosmetics houses. ANSM enforces allergen labeling thresholds that exceed EFSA baselines, forcing reformulation of legacy scent bases. L'Oréal and LVMH procurement teams now require blockchain-verified botanical sourcing documentation from Grasse-based suppliers.
Germany
Industrial bakery and ready-meal manufacturers in Bavaria and North Rhine-Westphalia drive savory flavor demand for clean-label applications. BfR operates stricter additive approval timelines than EFSA, creating compliance friction for novel fermentation-derived molecules. Cologne and Hamburg harbor specialized aroma chemical distributors serving Central European private-label retail chains.
Italy
Milan's cosmetics production corridor generates captive demand for high-value fragrance oils with proprietary signatures. ECHA substance restrictions on synthetic musks accelerate reformulation cycles among Lombardy-based perfumers. Turin and Bologna concentrate flavor production for confectionery and gelato applications where sugar reduction mandates require complex taste modulation.
Spain
Citrus essential oil extraction from Valencia and Murcia agricultural zones supplies regional fragrance compounders. Spanish national implementation of REACH diverges on enforcement intensity for small-volume natural extract importers. Barcelona hosts mid-tier fragrance houses adopting precision fermentation inputs to bypass agricultural yield volatility.
Poland
Emerging private-label retail chains in Warsaw and Kraków create greenfield demand for flavor production serving Central European markets. Polish chemical regulator inspections focus on imported aroma chemical documentation gaps. Wrocław and Łódź industrial zones attract German and French suppliers establishing secondary manufacturing footprints.
Europe Flavors and Fragrances Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based molecule specialization and direct-to-consumer fragrance platforms. The supplier base concentrates among integrated Swiss-German conglomerates with dedicated regulatory affairs capabilities. Three archetypes dominate: integrated flavor-fragrance platforms, natural extract specialists, and biotech-enabled precision fermentation suppliers. Consolidation through acquisition of regional botanical traders and enzymatic synthesis patent portfolios accelerates.
Within the integrated platform tier, Givaudan and DSM-Firmenich occupy positions combining nutrition science with fragrance innovation. Symrise AG exemplifies the natural extract specialist archetype through deep regional taste preference knowledge. These three anchors represent the competitive standard against which mid-tier Italian and Spanish fragrance houses benchmark bio-based feedstock adoption and CSRD-aligned carbon accounting capabilities.
| Leading Market Players |
|---|
| Givaudan |
| Symrise AG |
| DSM-Firmenich |
| International Flavors & Fragrances |
| Robertet |
| Mane |
| Takasago |
| Sensient Technologies |
| Bell Flavors and Fragrances |
| Others |
Supply & Pricing Matrix
Lavender and rose essential oil harvests from Southern French agricultural zones feed directly into three-tier pricing structures across premium, standard, and economy fragrance tiers, with weather-induced yield volatility compressing margins at the commodity end while proprietary scent signatures retain pricing power in Grasse compounding facilities serving LVMH and L'Oréal procurement teams.
Pricing Analysis
High-volume aroma chemicals trade on thin margins while bespoke fragrance oils command substantial premiums. Price differentiation hinges on botanical certification grade and volume scale, with organic and blockchain-verified inputs earning tier premiums. Pricing pressure stems from retailer consolidation across German and UK grocery channels demanding quarterly price benchmarking. Private-label savory flavor buyers exhibit highest price sensitivity; luxury cosmetics houses show lowest.
Supply Chain Analysis
Citrus terpenoid feedstock rests on Spanish Valencia and Murcia agricultural zones, Indian sandalwood plantations, and Indonesian patchouli cultivation. Key dependencies include fermentation-derived vanillin precursors, chiral enzymatic catalysts, and cold-pressed essential oil fractions. Single-source vulnerability concentrates in rare botanicals subject to ECHA substance restrictions. Distribution runs through Grasse fragrance compounders, Milan cosmetics manufacturers, and Cologne aroma chemical distributors serving Central European retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
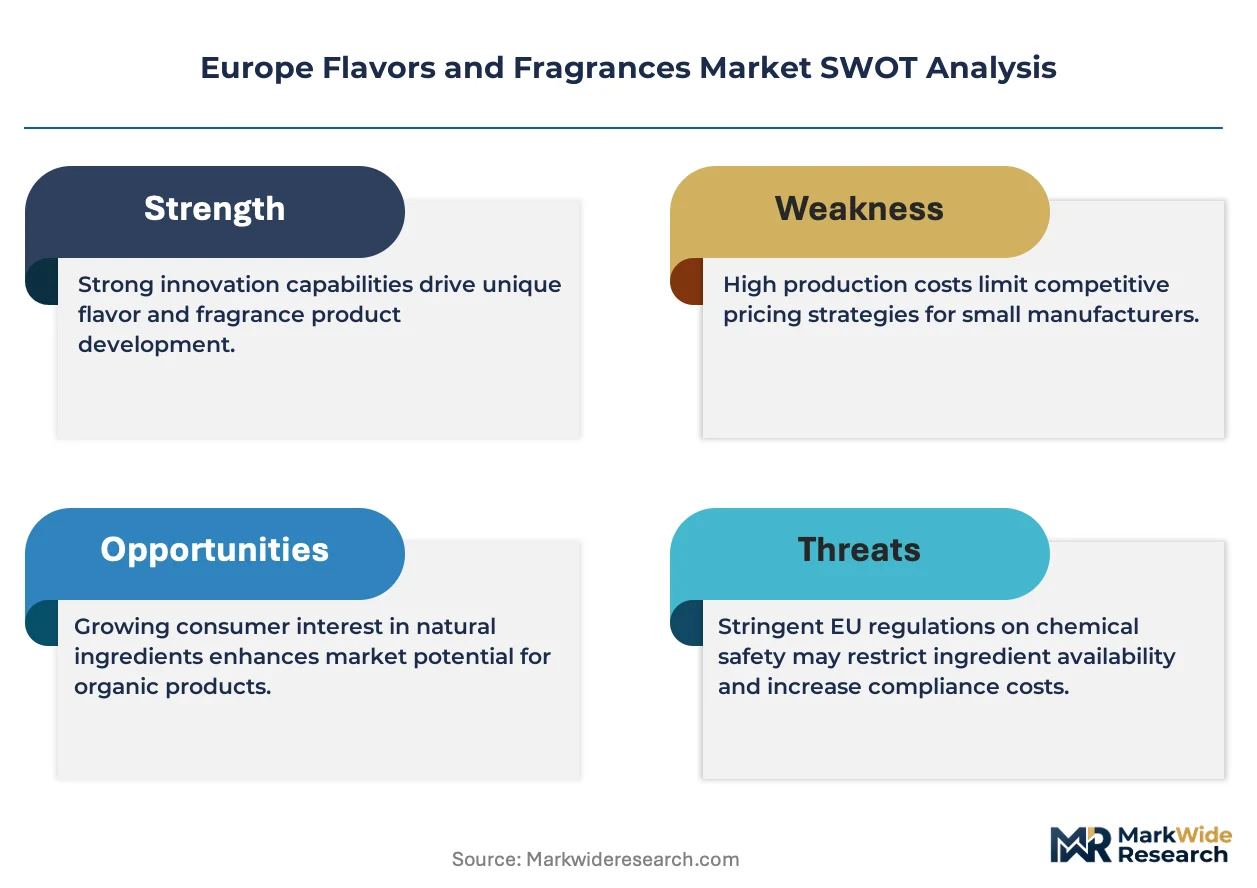
REACH compliance and CSRD disclosure mandates function as a cost-of-compliance moat, with ECHA substance screening timelines and novel ingredient approval costs creating barriers that favor established suppliers with dedicated regulatory affairs capabilities over undercapitalized entrants.
For Market Incumbents: Extend blockchain traceability investments to capture CSRD-aligned procurement gates from French cosmetics manufacturers. Deepen backward integration into precision fermentation platforms to secure natural-identical molecule supply against agricultural yield volatility. Consolidate regional botanical traders in Italy and Spain to lock in bio-based feedstock access before patent holders consolidate price-setting power. For New Entrants and Emerging Players: Precision fermentation specialization offers a technology-first wedge into fragrance oil categories where traditional botanical traders face supply constraints. Target Poland and Czech Republic private-label retail chains with greenfield flavor production capacity serving underpenetrated Central European markets. Pursue direct-to-consumer scent profiling platforms to bypass wholesale distribution capture margin and consumer data simultaneously. For Investors and Strategic Acquirers: ECHA acceleration of novel fermentation-derived aroma molecule approvals is the leading indicator that engineered biology patent holders will consolidate price-setting power away from agricultural extract traders. Long-term viability favors suppliers with verified Scope 3 carbon accounting and multi-tier supply chain visibility. Watch for CSRD implementation triggering procurement gate requirements from consolidated French and German buyers as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Fermentation | Secures natural-identical molecule supply bypassing lavender and rose yield volatility from Southern France. |
| Blockchain-Verified Botanical Sourcing | Meets L'Oréal and LVMH procurement documentation requirements originating from ANSM allergen thresholds. |
| Greenfield Manufacturing in Poland | Captures private-label flavor demand from emerging Warsaw and Kraków retail chains before incumbent footprint expansion. |
| Direct-to-Consumer Fragrance Platforms | Bypasses traditional Grasse wholesale distribution to capture margin and build proprietary consumer scent preference data. |
| CSRD-Aligned Carbon Accounting Certification | Creates competitive differentiation for suppliers with verified bio-based supply chains serving French cosmetics manufacturers. |
Research Methodology
Document review covered ECHA substance restriction databases, EFSA novel food approval filings, and CSRD implementation guidance, complemented by interviews with fragrance compounders in Grasse, flavor procurement directors at German ready-meal manufacturers, regulatory affairs leads at Swiss-German integrated platforms, and botanical traders in Southern Spain. Secondary validation drew from customs trade data, SEC 10-K disclosures from listed suppliers, and Cefic chemical industry reports. Bottom-up segment sizing triangulated against top-down market consolidation analysis.
Model outputs span value and volume projections across the analysis window, with segmentation by product type, end user, application, and form. CAGRs derived from historical trajectory analysis adjusted for REACH compliance cost absorption and CSRD disclosure implementation timelines. Forecast inputs incorporated precision fermentation platform adoption curves, retailer consolidation patterns in German grocery channels, and ECHA substance restriction phase-out schedules.
Several conditions sit outside the modeled scope, including unscheduled ECHA substance bans, extreme weather events disrupting Southern European essential oil harvests, and geopolitical disruptions to Indian sandalwood or Indonesian patchouli supply. Forecasts reflect assumptions around regulatory timeline adherence and fermentation infrastructure buildout rates. A small set of named triggers warrants ongoing watch: ECHA acceleration of novel ingredient approvals, CSRD procurement gate enforcement intensity from French cosmetics manufacturers, and precision fermentation patent litigation outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
North America Aroma Chemicals Market
Flavor and Fragrance Chemicals
Gel Air Fresheners Market
Flavor and Fragrance Chemicals
Global Natural Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
Deodorant Market
Flavor and Fragrance Chemicals
Hydroxycitronellal Market
Flavor and Fragrance Chemicals
Cedarwood Oil Market
Flavor and Fragrance Chemicals
Nonanal Market
Flavor and Fragrance Chemicals
Middle East and Africa Deodorants Market
Flavor and Fragrance Chemicals
Linalool Market
Flavor and Fragrance Chemicals
Essential Oils Market
Flavor and Fragrance Chemicals
Asia-Pacific Deodorants Market
Flavor and Fragrance Chemicals
4-Allylanisole Market
Flavor and Fragrance Chemicals
Semiochemicals Market
Flavor and Fragrance Chemicals
Global Terpene Market
Flavor and Fragrance Chemicals
Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
India Aroma Chemicals Market