
 Flavor and Fragrance Market | 2026-2036
Flavor and Fragrance Market Size, Share, and Industry Trends Forecast 2026-2036
Flavor and Fragrance Market Insights
The gap between premium botanical extracts and commodity synthetic compounds is realigning procurement strategies across the value chain. Givaudan S.A. anchors its position through captive sourcing of rare raw materials in Madagascar and Grasse. DSM-Firmenich AG leverages integrated biotechnology platforms to reduce batch-to-batch variability in fermentation-derived molecules. Symrise AG competes on scale in aroma chemicals while building specialty positions in natural isolates.
Flavor and fragrance compounds are volatile organic formulations—typically comprising esters, terpenoids, aldehydes, and ketones—engineered to deliver specific sensory profiles at parts-per-million thresholds in finished goods. Their primary commercial purpose is to mask off-notes, enhance palatability, or confer brand-identifiable scent signatures across consumer packaged goods. Natural flavors and essential oils command premium positioning as food manufacturers reformulate away from artificial additives, while aroma chemicals retain volume dominance in mass-market detergents and personal care. Synthetic flavors face margin compression as clean-label expectations spread from premium tiers into mainstream retail channels.
REACH in Europe mandates full substance registration and safety dossiers for fragrance ingredients crossing volume thresholds, while FDA oversight under FEMA GRAS and Food Additive Regulations governs flavor safety assessments in the United States. China's SAMR enforces GB standards for food flavor usage limits and labeling transparency, creating compliance complexity for multinational suppliers. Stakeholders must monitor regulatory divergence between jurisdictions as biotech-derived novel molecules challenge traditional classification frameworks and testing requirements.
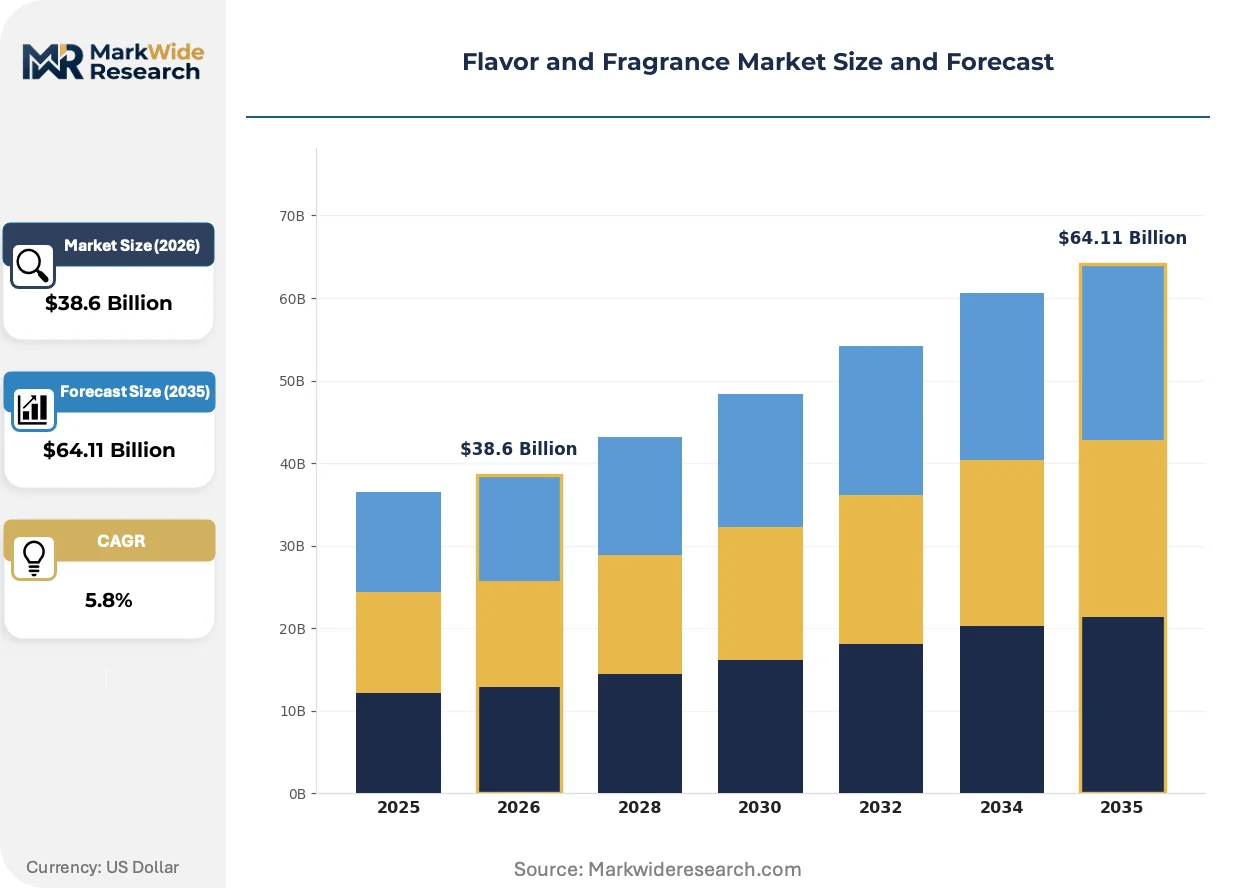
Market Dynamics
Clean-label reformulation mandates from major retailers are compressing synthetic flavor margins while biotechnology platforms reduce production costs for natural alternatives, redrawing competitive boundaries across the value chain.
Growth Catalysts
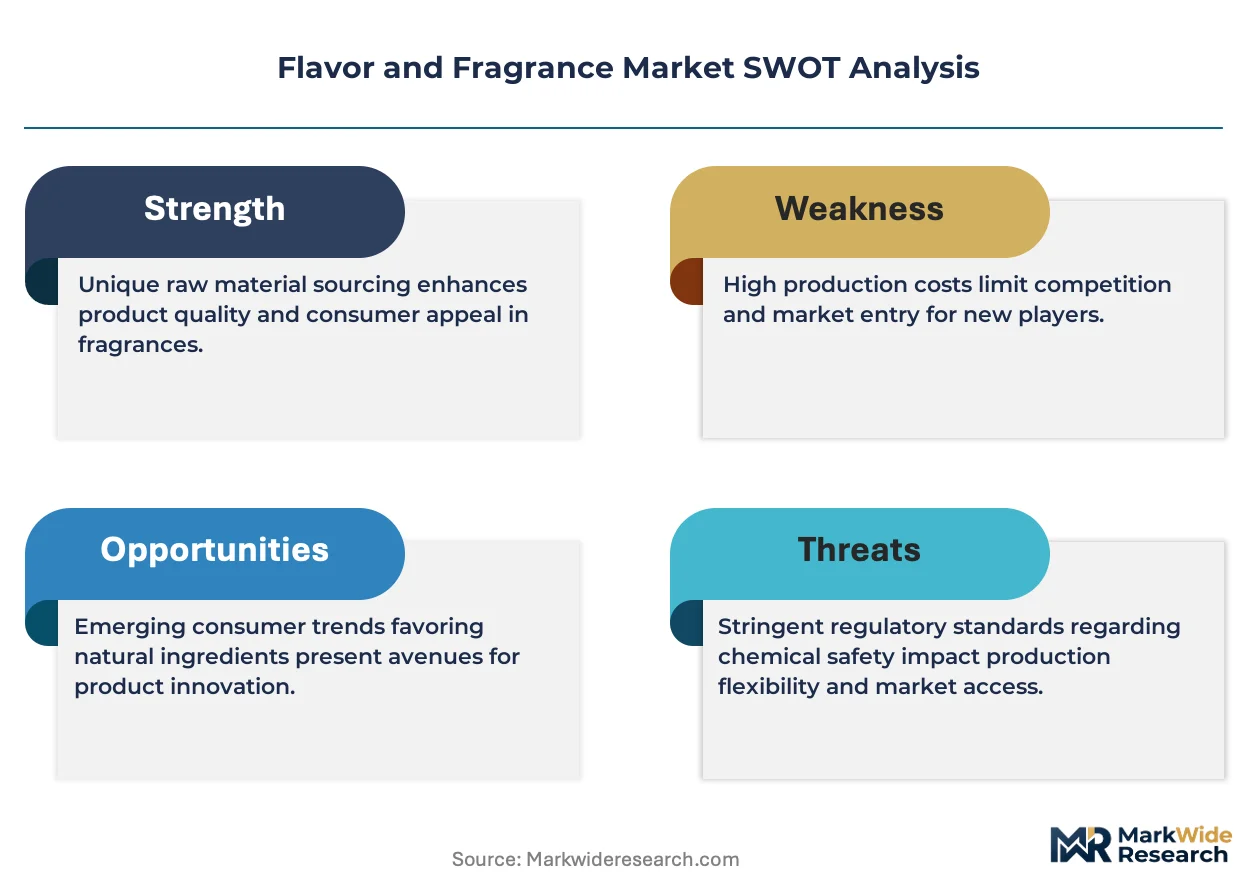
- REACH substance registration:Full safety dossier requirements in Europe accelerate consolidation among compliant suppliers and favor established players with regulatory infrastructure.
- Fermentation-derived molecules:Biotechnology platforms cut batch-to-batch variability in natural isolates, enabling cost parity with synthetics in mid-tier applications.
- China cosmetic brand expansion:Domestic fragrance portfolio growth concentrates demand for premium botanical extracts and custom scent development services.
Market Restraints
- Vanilla and citrus supply concentration:Madagascar cyclone exposure and Florida citrus greening disease create recurring raw material volatility for natural extract portfolios.
- REACH compliance costs:Safety testing and registration fees for novel molecules exceed thresholds accessible to mid-scale specialty producers, raising barriers to innovation.
- Biotech-derived substitutes:Precision fermentation of rare terpenoids threatens traditional cultivation-dependent supply chains for botanical extracts.
Strategic Opportunities
- India personal care penetration:Underdeveloped fragrance adoption in mass-market Indian cosmetics offers expansion space for regional formulation partnerships.
- EU Green Deal biomanufacturing incentives:Carbon accounting advantages for fermentation-based production create regulatory tailwinds for biotechnology investments.
- Direct-to-brand digital platforms:AI-assisted scent matching tools bypass traditional distributor networks, compressing customer acquisition costs for indie fragrance houses.
Industry Challenges
- Flavorist and perfumer talent scarcity:Specialized sensory evaluation expertise concentrates among aging professionals in Grasse and Geneva, constraining R&D scaling.
- Clean-label certification timelines:FEMA GRAS self-determination and FDA notification processes extend go-to-market cycles for novel natural molecules.
- Legacy ERP integration:Batch tracking requirements for REACH substance volumes clash with outdated manufacturing execution systems at mid-tier compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavor and Fragrance Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Synthetic Flavors, Essential Oils, Aroma Chemicals Application: Food & Beverages, Cosmetics, Household Products, Pharmaceuticals End User: Food Manufacturers, Beverage Producers, Cosmetic Companies, Pharma Companies Distribution Channel: Direct Sales, Distributors, Online Retail, Specialty Stores |
| Companies Covered | DSM-Firmenich AG, Takasago International Corporation, Givaudan S.A., Mane, Sensient Technologies, International Flavors & Fragrances, Firmenich SA, Robertet Group, Symrise AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavor and Fragrance Market Trends and Innovations
Biotechnology platforms, regulatory disclosure mandates, and procurement digitization are converging to compress traditional supply hierarchies and enable direct manufacturer-brand relationships.
Precision fermentation is modularizing the production of rare terpenoids and aldehydes previously dependent on agricultural cultivation. Mid-tier personal care manufacturers in South Korea and Brazil adopt these biotech inputs to meet clean-label specifications without premium botanical pricing. The technology is modularizing supply chain risk by decoupling fragrance production from climate-dependent crop yields and geographic concentration.
REACH Annex XVII restrictions on allergen labeling and the EU's expanding list of fragrance sensitizers tighten formulation transparency requirements. Compounders must now disclose full substance portfolios down to parts-per-million thresholds in consumer-facing documentation. Fine fragrance houses in France face the steepest adaptation costs, reformulating legacy scents to eliminate newly restricted molecules while preserving brand-identifiable scent signatures.
Direct sourcing platforms connecting fragrance houses with biotechnology producers bypass traditional distributor markups. Indie cosmetic brands in California and New York contract directly with fermentation specialists for custom molecule development, compressing traditional three-tier supply structures. This channel disintermediation is most visible in North American clean beauty, where venture-backed brands prioritize supply chain storytelling over incumbent supplier relationships.
Flavor and Fragrance Market Segmentation
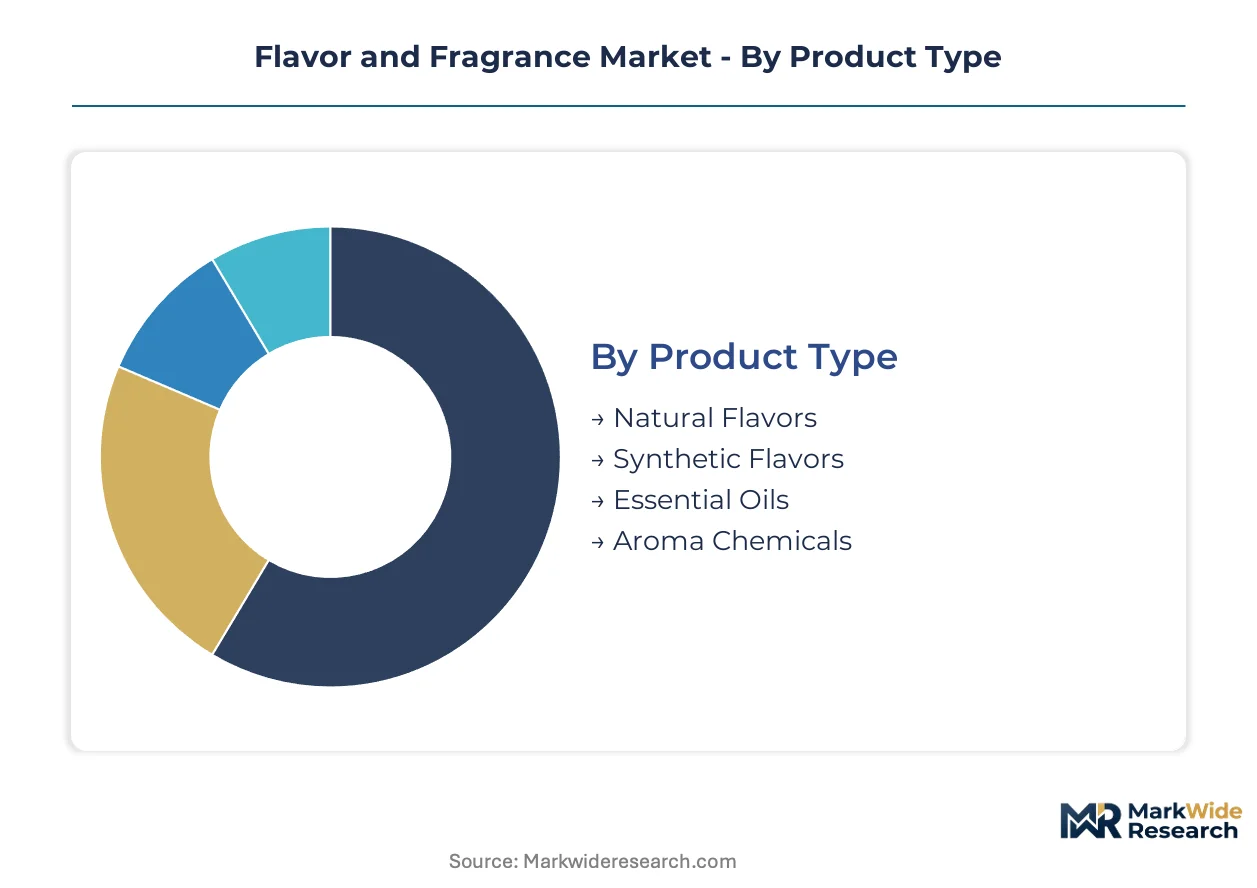
Segmentation in the flavor and fragrance market reveals divergent capital requirements and margin structures across production technologies. Procurement patterns vary sharply between fermentation-derived naturals and petrochemical-based synthetics, with regulatory disclosure mandates reshaping channel economics.
Product Type:
Capital intensity concentrates in biotechnology infrastructure for natural isolates, while aroma chemicals leverage existing chemical plant assets with lower incremental investment barriers.
- Natural Flavors:Fermentation-derived and extracted formulations from botanical sources command premium positioning in clean-label food applications. Demand concentrates among North American and European food manufacturers reformulating away from artificial additives as retailer mandates tighten.
- Synthetic Flavors:Petrochemical-derived esters, aldehydes, and ketones engineered for cost-efficient sensory delivery at parts-per-million thresholds. Volume dominance persists in mass-market beverages and processed foods where margin compression limits natural alternative adoption.
- Essential Oils:Steam-distilled or cold-pressed concentrated plant extracts requiring agricultural sourcing relationships and climate-dependent inventory management.
- Aroma Chemicals:Standardized synthetic molecules produced at scale for detergent and personal care applications with batch-to-batch consistency advantages.
Most installed capacity flows through Aroma Chemicals. Expansion is steepest in Natural Flavors.
Application:
Application mix determines formulation complexity and regulatory exposure, with cosmetics and pharmaceuticals facing the steepest disclosure requirements.
- Food & Beverages:Largest volume outlet encompassing processed foods, carbonated drinks, and alcoholic beverages where flavor masking and palatability enhancement drive formulation decisions. Clean-label reformulation in premium retail tiers accelerates natural flavor procurement.
- Cosmetics:Fine fragrance and personal care applications requiring allergen labeling compliance under REACH Annex XVII and brand-identifiable scent signatures. Domestic Chinese cosmetic houses expand fragrance portfolios fastest.
- Household Products:Detergents and cleaning formulations prioritizing cost-efficient aroma chemical delivery over natural positioning.
- Pharmaceuticals:Masking agents for oral dosage forms and excipient applications governed by pharmacopeial standards and FDA oversight.
Food & Beverages absorbs the majority of production volume. Cosmetics demonstrates the steepest expansion trajectory.
End User:
End-user scale determines procurement leverage, with multinational food manufacturers consolidating supplier relationships while indie cosmetic brands pursue direct biotech sourcing.
- Food Manufacturers:Processed food and snack producers with consolidated procurement teams negotiating long-term supply agreements for high-volume synthetic and natural flavor inputs.
- Beverage Producers:Carbonated soft drink and alcoholic beverage formulators requiring consistent batch quality and rapid flavor innovation cycles for seasonal product launches.
- Cosmetic Companies:Fine fragrance houses and personal care brands spanning mass-market to luxury tiers, with clean beauty startups in California and New York bypassing traditional distributor networks.
- Pharma Companies:Dosage form developers sourcing excipient-grade flavors under pharmacopeial certification requirements with extended qualification timelines.
Food Manufacturers command the largest procurement volumes. Cosmetic Companies are gaining share fastest through direct biotechnology partnerships.
Distribution Channel:
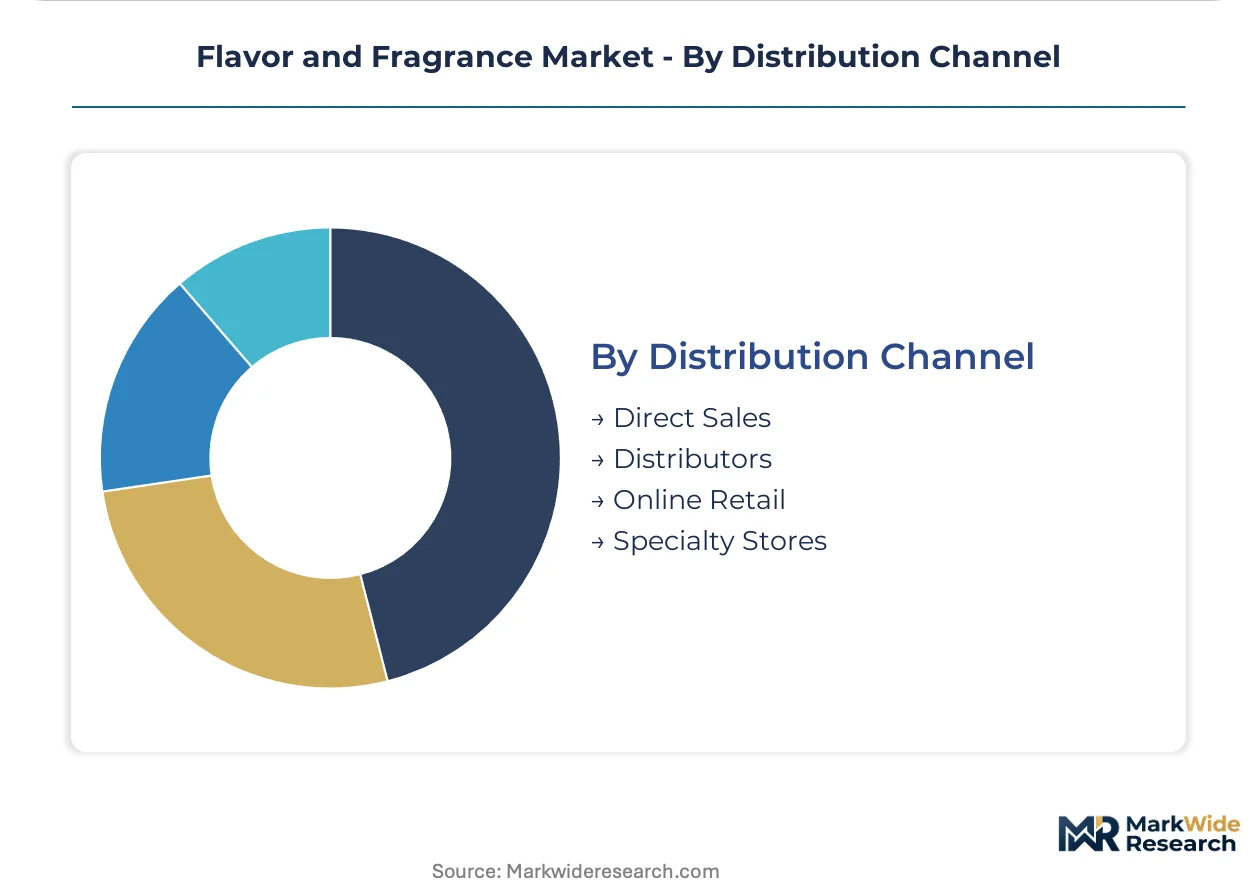
Channel structure is compressing as digital platforms enable manufacturer-brand direct relationships, eroding traditional distributor margins.
- Direct Sales:Long-term supply contracts between major compounders and multinational food and beverage manufacturers with dedicated account management and technical service support.
- Distributors:Regional chemical and ingredient distributors serving mid-tier compounders with inventory consolidation and logistics services facing margin pressure from platform disintermediation.
- Online Retail:E-commerce platforms for small-batch essential oils and specialty aroma chemicals targeting indie cosmetic formulators and craft food producers.
- Specialty Stores:Physical retail for consumer-facing essential oil and fragrance ingredient sales with limited commercial scale relative to B2B channels.
Direct Sales captures the majority of value flow. Online Retail is climbing the fastest as venture-backed clean beauty brands prioritize supply chain transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Perfumers and flavorists trained in Grasse, Geneva, and New York anchor the industry's geographic concentration, with regulatory divergence across jurisdictions reshaping where production capacity expands.
United States
Clean-label reformulation by beverage manufacturers and direct-to-brand sourcing by indie cosmetic startups concentrate demand in California and New York. FDA oversight through FEMA GRAS and Food Additive Regulations governs flavor safety assessments, extending go-to-market timelines for novel natural molecules. New Jersey hosts major compounding facilities serving mass-market personal care brands.
France
Fine fragrance houses in Paris and Grasse drive premium botanical extract procurement while facing steep adaptation costs from REACH Annex XVII allergen restrictions. ANSM and CNIL enforce cosmetic ingredient transparency alongside ECHA substance registration requirements. The Grasse cluster specializes in rose and jasmine cultivation for luxury scent development.
China
Domestic cosmetic brands expanding fragrance portfolios concentrate demand in Shanghai and Guangzhou for custom scent development services. SAMR enforces GB standards for food flavor usage limits and labeling transparency, creating compliance complexity for multinational suppliers. Yangtze River Delta biotech parks incubate precision fermentation startups targeting terpenoid production.
Switzerland
Integrated biotechnology platforms serving global food manufacturers cluster around Geneva and Basel, leveraging Swissmedic and EFSA-aligned regulatory infrastructure for novel molecule qualification. DSM-Firmenich AG anchors captive fermentation capacity for natural isolates. The Lake Geneva region concentrates sensory evaluation expertise and R&D investment.
India
Underdeveloped fragrance adoption in mass-market personal care offers expansion space for regional formulation partnerships targeting Mumbai and Delhi-NCR. FSSAI governs food additive safety assessments while BIS standards apply to cosmetic ingredient quality. Karnataka's biotech corridor attracts contract fermentation investments for essential oil substitutes.
Flavor and Fragrance Market Competitive Landscape
Top-tier vendors anchor integrated biotechnology and captive raw material sourcing, while mid-scale compounders face margin compression from clean-label mandates and REACH compliance costs. The vendor base stratifies across three tiers: global integrated houses with fermentation platforms, regional botanical extract specialists with agricultural supply relationships, and commodity aroma chemical producers with petrochemical feedstock access. Dominant competitive moves include backward integration into rare raw material cultivation and strategic partnerships with precision fermentation startups.
Among Switzerland-based integrated houses, DSM-Firmenich AG and Givaudan S.A. exemplify the biotechnology-platform archetype, while Symrise AG occupies a position spanning scale-driven aroma chemicals and specialty natural isolates. Takasago International Corporation represents the Japan-based fermentation specialist model. These named entities anchor industry commentary on competitive positioning without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| DSM-Firmenich AG |
| Takasago International Corporation |
| Givaudan S.A. |
| Mane |
| Sensient Technologies |
| International Flavors & Fragrances |
| Firmenich SA |
| Robertet Group |
| Symrise AG |
| Others |
Pricing and Supply Chain Analysis
Premium-mid-economy pricing differentiation across fermentation-derived naturals and petrochemical synthetics manifests in divergent margin structures and sourcing configurations. Botanical extract procurement in Madagascar and Grasse anchors premium tiers with captive agricultural relationships, while commodity aroma chemicals leverage spot-market petrochemical feedstocks with minimal vertical control.
Pricing Analysis
Service bundling separates formulation development from molecule supply across the value chain. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade under REACH and FEMA GRAS, with volume scale discounts compressing margins for mid-tier compounders. Cost compression in synthetic flavors is intensifying because clean-label mandates from North American retailers force reformulation investments. Mass-market household product manufacturers exhibit highest price sensitivity, while fine fragrance houses in France absorb premium botanical premiums without volume negotiation.
Supply Chain Analysis
Domestic-content mandates under China's GB standards and India's PLI scheme for biomanufacturing are reshaping regional sourcing patterns for multinational compounders. Supply concentrates in Madagascar for vanilla, India for mint and spice extracts, and Switzerland for integrated fermentation platforms. Raw material flows draw from cyclone-exposed agricultural zones, citrus groves afflicted by greening disease, and precision fermentation bioreactors. Single-source vulnerability in Madagascar vanilla creates recurring inventory disruption. Distribution runs through direct sales contracts with multinational food manufacturers, bypassing traditional chemical distributors for high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on biotechnology platforms achieving cost parity with synthetics, while premium-tier shifts toward clean-label naturals capture pricing power from reformulation mandates.
For Market Incumbents: Cement captive supply relationships in climate-vulnerable sourcing zones before biotech substitutes displace agricultural cultivation. Expand fermentation capacity in Swiss and Chinese biotech corridors to reduce batch-to-batch variability. Lock in long-term offtake agreements with domestic cosmetic brands in Shanghai and Guangzhou. For New Entrants and Emerging Players: Begin with direct-to-brand digital platforms targeting venture-backed clean beauty startups in California and New York that prioritize supply chain transparency over incumbent relationships. White-space penetration in mass-market Indian personal care offers lowest competitive density. Lead with AI-assisted scent matching tools that compress customer acquisition costs relative to traditional distributor networks. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs exceed thresholds accessible to mid-scale specialty producers, favoring acquisition of fermentation-platform specialists over commodity aroma chemical assets. Long-term viability frames around biotechnology-derived molecule pipelines displacing cultivation-dependent supply chains. Watch precision fermentation yield improvements as the inflection signal for accelerated natural isolate cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Raw Material Cultivation | Madagascar vanilla and Grasse jasmine sourcing secures premium tier supply against climate volatility. |
| Precision Fermentation Capacity Expansion | Swiss and Chinese biotech parks enable cost parity with synthetics under EU Green Deal carbon accounting. |
| Direct-to-Brand Digital Platform Launch | AI-assisted scent matching bypasses distributor markups for indie cosmetic houses in North America. |
| Long-term Supply Agreement with Domestic Cosmetic Brands | Shanghai and Guangzhou fragrance portfolio expansion locks in demand for custom development services. |
| REACH Compliance Infrastructure Investment | ECHA substance registration capabilities raise barriers against mid-scale competitors in European markets. |
Research Methodology
Multiple input streams — regulatory filing analysis, trade flow databases, and executive interview transcripts — were reconciled to construct this assessment. Primary discussions with flavorists and perfumers in Grasse and Geneva, procurement directors at multinational food manufacturers, fermentation platform engineers in Swiss biotech clusters, and regulatory affairs specialists navigating REACH and FDA frameworks informed qualitative judgments. Secondary validation drew from ECHA substance registration databases, FEMA GRAS determinations, customs records for essential oil imports, and SEC filings of integrated compounders. Bottom-up volume modeling and top-down market sizing were cross-referenced for triangulation.
Historical shipment data was cross-referenced against panel input from industry participants to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include production technology tier, application end-use, geographic regulatory cluster, and customer scale archetype. CAGRs were derived from growth rate reconciliation across these segment trajectories. Forecast inputs incorporated biotechnology yield improvement curves, clean-label reformulation penetration rates, and domestic cosmetic brand expansion patterns in China.
Caveats apply where Madagascar cyclone frequency, Florida citrus greening progression, or biotech regulatory reclassification could materially shift the outlook. Forecasts embed assumptions about REACH enforcement consistency and FEMA GRAS timeline stability that may require revision. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Pocket Perfume Market
Flavor and Fragrance Chemicals
Massoia Bark Essential Oil Market
Flavor and Fragrance Chemicals
United States Aroma Chemicals Market
Flavor and Fragrance Chemicals
Citral Market
Flavor and Fragrance Chemicals
Phenethyl Alcohol Market
Flavor and Fragrance Chemicals
Estragole Market
Flavor and Fragrance Chemicals
Gamma Decalactone Market
Flavor and Fragrance Chemicals
Perfumes and Deodorants Market
Flavor and Fragrance Chemicals
Deodorant Market
Flavor and Fragrance Chemicals
North America Aroma Chemicals Market
Flavor and Fragrance Chemicals
Camphor Market
Flavor and Fragrance Chemicals
Aroma Chemicals Market
Flavor and Fragrance Chemicals
Scent Eliminators Market
Flavor and Fragrance Chemicals
Coumarin Market
Flavor and Fragrance Chemicals
Tangerine Oil Market
Flavor and Fragrance Chemicals
Alpha Ionone Market