
 Neryl Acetate Market | 2026-2036
Neryl Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Neryl Acetate Market Foresight
The capital-intensity gap between integrated aroma-chemical producers and small-batch compounders is collapsing as synthesis automation lowers fixed-cost barriers. Takasago International Corporation leverages captive biotechnology capabilities to secure fermentation-derived precursors. Privi Speciality Chemicals Limited anchors its position through backward integration into Indian terpene feedstock supply. Prodasynth SAS differentiates via continuous-flow manufacturing for pharmaceutical-grade batches.
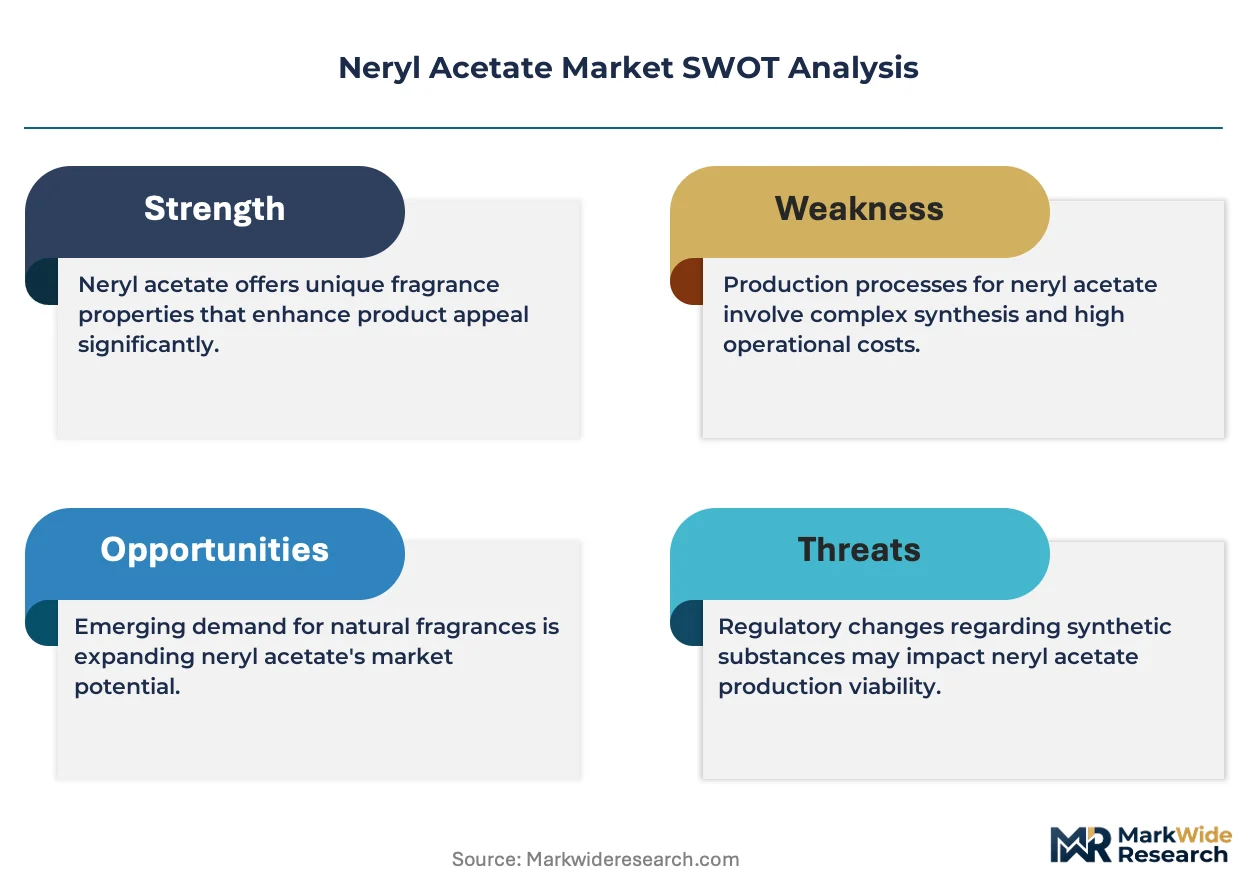
Neryl acetate is an acetic ester of nerol, a monoterpene alcohol with the molecular formula C12H20O2, typically characterized by a fresh, floral odor profile with citrus-rose notes and a boiling point near 134°C at 15 mmHg; manufacturers produce it through acetylation of nerol using acetic anhydride or acetyl chloride with acid catalysis, primarily for use in fine fragrance compositions, flavor formulations, and active pharmaceutical ingredient intermediates. The natural segment commands premium positioning in European luxury perfumery, while synthetic material captures volume in mass-market personal care. Pharmaceutical-grade neryl acetate represents the fastest-expanding margin pool as FDA and EMA filing requirements drive purity certification costs upward.
REACH registration in Europe, FDA food additive regulations in the United States, and FSSAI flavor standards in India collectively elevate compliance expenditure for cross-border suppliers. ECHA substance evaluation protocols now require chronic toxicity datasets previously absent from neryl acetate dossiers, forcing reformulation investments across cosmetic applications. Stakeholders must monitor evolving pharmaceutical excipient monographs and biobased content thresholds in EU Green Deal procurement guidelines to preserve market access.
Market Dynamics
Continuous-flow synthesis automation is collapsing fixed-cost barriers between integrated aroma-chemical producers and small-batch compounders, redistributing competitive advantage toward firms with captive biotechnology capabilities rather than legacy petrochemical assets.
Growth Catalysts
- REACH substance evaluation protocols:ECHA's chronic toxicity dataset requirements for neryl acetate dossiers are forcing cosmetic reformulation investments that favor certified suppliers with existing compliance infrastructure.
- Biotechnology-derived precursors:Fermentation-based nerol production is displacing traditional steam-distilled feedstocks, lowering batch-to-batch variability for pharmaceutical-grade specifications.
- Indian specialty chemical clusters:Concentrated terpene processing capacity in Maharashtra and Gujarat anchors backward-integrated supply for global fragrance houses seeking natural-grade material security.
Market Restraints
- Citronella oil price volatility:Weather-driven harvest fluctuations in Indonesia and Sri Lanka transmit directly to nerol feedstock costs, compressing margins for non-integrated compounders.
- European purity threshold escalation:F-Gas Regulation and REACH tightening create dual compliance burdens that disproportionately burden cross-border suppliers without EU-based certification laboratories.
- Synthetic substitute penetration:Isobornyl acetate and linalyl acetate blends capture volume in mass-market personal care, constraining pricing power for standard-grade neryl acetate.
Strategic Opportunities
- Pharmaceutical excipient monographs:FDA and EMA filing requirements for active pharmaceutical ingredient intermediates create certified-grade margin pools inaccessible to commodity producers.
- EU Green Deal biobased thresholds:Procurement guidelines mandating renewable content percentages favor fermentation-derived material in institutional fragrance contracts.
- Direct-to-compounder digital platforms:Specialty chemical marketplaces are disintermediating traditional distributor networks for small-batch perfumery customers in France and Switzerland.
Industry Challenges
- Continuous-flow engineering talent scarcity:Pharmaceutical-grade batch production requires process chemists with microreactor expertise, a skill set concentrated among contract research organizations.
- Dual-use export licensing complexity:Neryl acetate's scheduled precursor status under national chemical weapons conventions creates documentation friction for cross-border shipments to Middle Eastern and North African destinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neryl Acetate Market |
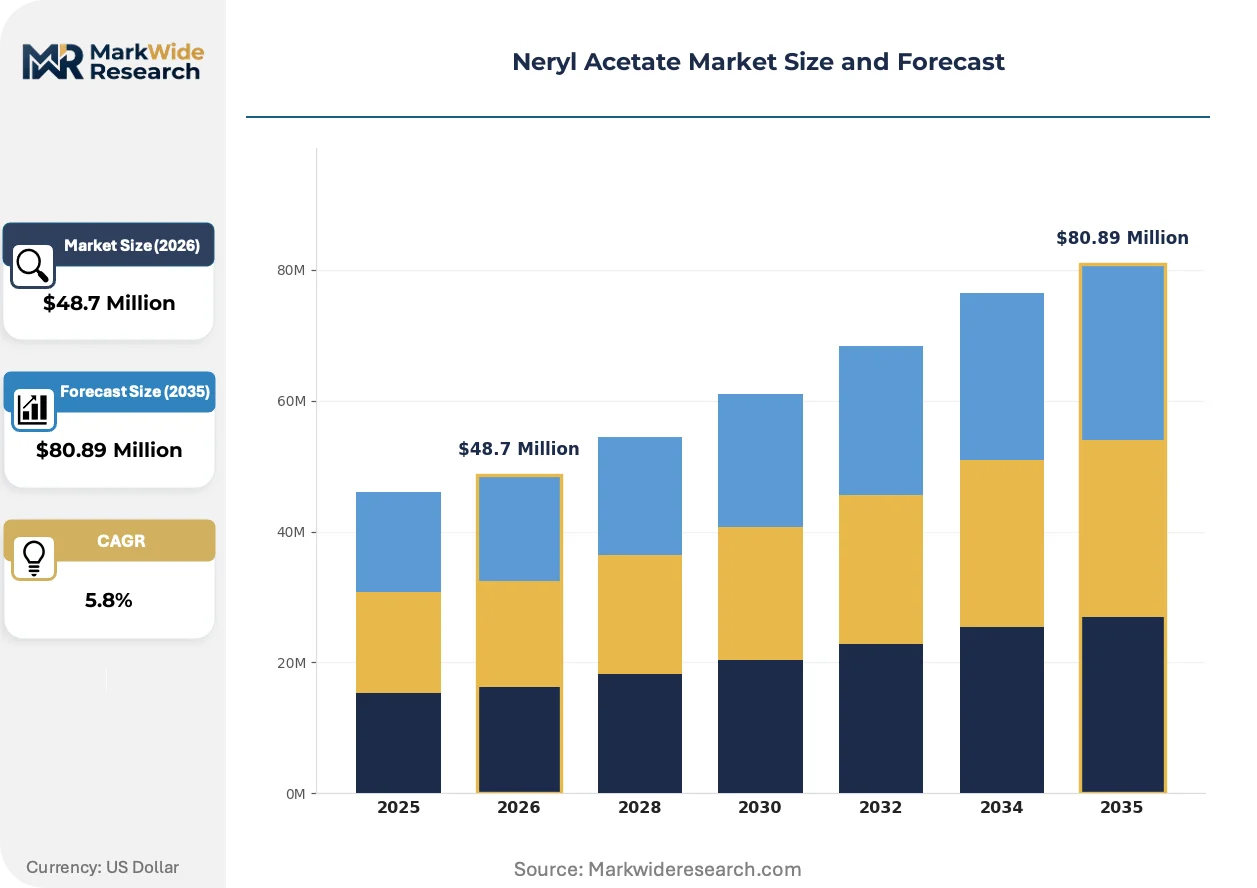
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $80.89 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Organic, Inorganic Application: Fragrance, Flavoring, Cosmetic, Pharmaceutical Form: Liquid, Solid, Powder, Solution Grade: Food Grade, Cosmetic Grade, Industrial Grade, Pharmaceutical Grade |
| Companies Covered | Takasago International Corporation, Privi Speciality Chemicals Limited, Prasol Chemicals Pvt. Ltd, The Good Scents Company, Prodasynth SAS, Citrus and Allied Essences Ltd, Berje Inc., Acros Organics N.V., Solventis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neryl Acetate Market Shifts & Advancements
Automation and regulatory precision are converging to transform how neryl acetate is synthesized, certified, and procured, with biotechnology and continuous manufacturing displacing established petrochemical process economics.
Microreactor-based continuous-flow acetylation is miniaturizing production footprints while tightening purity control for pharmaceutical-grade batches. Fragrance houses in Grasse and Geneva are adopting these systems for captive specialty production, compressing the minimum efficient scale for in-house manufacturing and eroding the volume advantage of legacy batch reactors.
EMA's evolving pharmaceutical excipient guidelines are mandating elemental impurity profiling and forced degradation studies previously absent from cosmetic-grade specifications. European compounders serving both fragrance and pharmaceutical markets are dual-certifying production lines, while Asian exporters without EU-based testing partnerships face extended qualification timelines.
Buyer consolidation among global luxury fragrance houses is compressing supplier negotiation cycles and unbundling technical service from material pricing. French and Swiss compounders now source neryl acetate through centralized procurement platforms that benchmark fermentation-derived against synthetic material on carbon footprint metrics, rewarding suppliers with verified biobased content documentation.
Neryl Acetate Market Segmentation
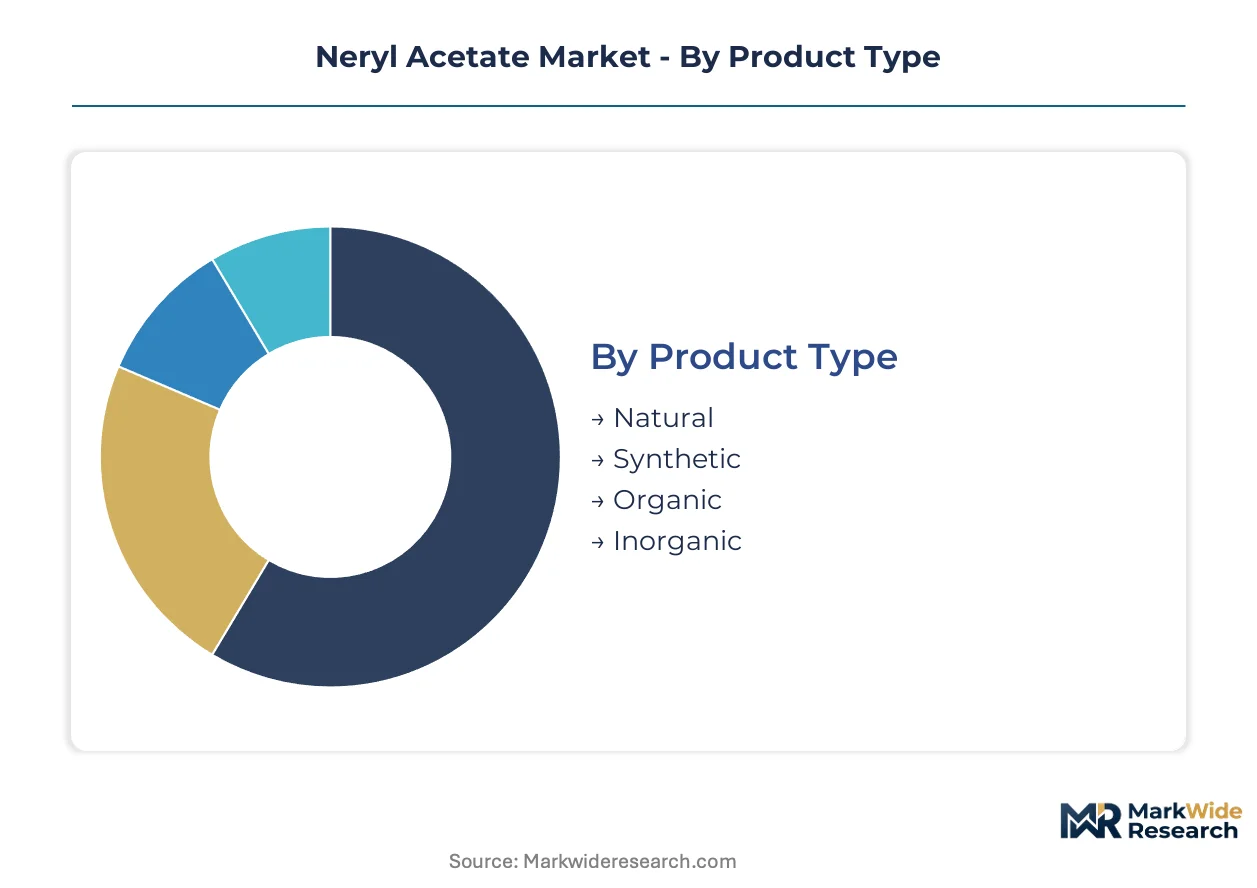
Segmentation in neryl acetate reveals how purity thresholds and procurement specifications fragment supply chains across fragrance, pharmaceutical, and food-grade channels. Each tier demands distinct certification infrastructure that reshapes supplier economics.
Product Type:
Natural-grade neryl acetate concentrates procurement in European fragrance houses seeking biobased content verification, while synthetic material serves volume markets through distributed Asian supply.
- Natural:Steam-distilled from citronella and neroli sources with batch-to-batch terpene profile variation. Grasse and Geneva fragrance houses anchor procurement, with EU Green Deal biobased thresholds forcing documentation investments that favor integrated terpene processors in Maharashtra and Gujarat.
- Synthetic:Petrochemical-derived via acetylation of synthetic nerol with tighter specification control. Mass-market personal care manufacturers in the United States and Southeast Asia drive volume, though REACH chronic toxicity dossier requirements now elevate compliance costs for cross-border suppliers.
- Organic:Certified organic feedstock with restricted pesticide residue limits. Demand clusters in Swiss and French premium perfumery with institutional procurement contracts.
- Inorganic:Mineral-catalyzed synthesis pathways for industrial solvent applications. Limited fragrance relevance; serves chemical intermediate markets.
Natural commands the established base. The steepest expansion runs through Synthetic as fermentation-derived precursors displace petrochemical routes.
Application:
Cost-tier stratification separates luxury fragrance formulations from commodity flavor and cosmetic volume, with pharmaceutical intermediates capturing certification-premium pricing.
- Fragrance:Fine perfumery compositions requiring olfactory consistency across harvest cycles. European luxury houses in France and Switzerland concentrate procurement through centralized platforms that benchmark carbon footprint metrics.
- Flavoring:Food additive applications under FDA and FSSAI jurisdiction with stringent purity protocols. Indian and US flavor houses drive specification standardization.
- Cosmetic:Personal care formulations with REACH cosmetic product regulation compliance. Mid-tier pricing pressure from synthetic substitute blends constrains margin expansion.
- Pharmaceutical:Active pharmaceutical ingredient intermediates with FDA and EMA filing requirements. Elemental impurity profiling and forced degradation studies create certified-grade margin pools inaccessible to commodity producers.
Fragrance retains volume leadership. Pharmaceutical is climbing the fastest as excipient monograph compliance deepens supplier qualification barriers.
Form:
Volume concentration favors liquid delivery for continuous manufacturing integration, with solid and powder formats serving niche stability requirements.
- Liquid:Standard delivery format for fragrance compounding and pharmaceutical synthesis. Microreactor-based continuous-flow production in Grasse and Geneva compresses minimum efficient scale for captive manufacturing.
- Solid:Encapsulated or adsorbed formats for controlled-release applications. Limited demand in flavor microencapsulation.
- Powder:Spray-dried formulations for dry mix convenience. Food-grade specifications under FSSAI and FDA food additive regulations.
- Solution:Pre-diluted concentrations for laboratory and small-batch compounder convenience. Direct-to-compounder digital platforms in France and Switzerland disintermediate traditional distributor networks.
Liquid commands the established base. Solution is gaining share fastest through specialty chemical marketplace procurement centralization.
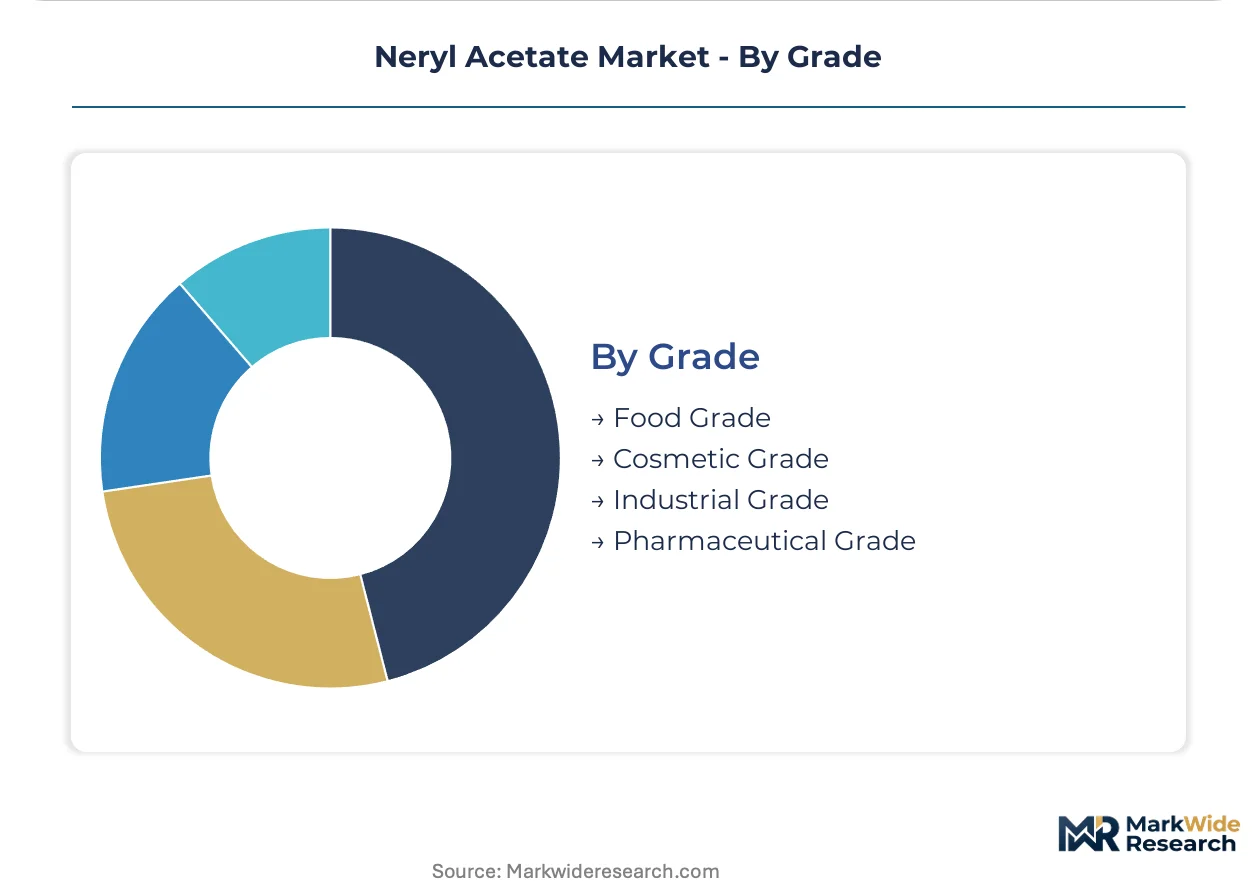
Grade:
Margin structure stratifies sharply across certification tiers, with pharmaceutical and food grades demanding analytical infrastructure that excludes commodity compounders.
- Food Grade:FSSAI flavor standards and FDA food additive regulations govern purity thresholds. Indian and US flavor houses concentrate procurement with documented supply chain traceability.
- Cosmetic Grade:REACH cosmetic product regulation and ECHA substance evaluation protocols mandate chronic toxicity datasets. European compounders dual-certify production lines to serve both fragrance and pharmaceutical markets.
- Industrial Grade:Solvent and chemical intermediate applications with minimal regulatory burden. Price-tolerant volume segment with synthetic material dominance.
- Pharmaceutical Grade:FDA and EMA excipient monographs with elemental impurity profiling requirements. Fermentation-derived precursors from biotechnology-integrated producers capture premium positioning.
Cosmetic Grade commands the established base. Pharmaceutical Grade is expanding most quickly as filing requirements drive purity certification costs upward.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France consumes neryl acetate predominantly for fine fragrance compounding, while India processes the bulk of natural-grade feedstock for export, and the United States drives pharmaceutical-grade certification demand.
France
Grasse-based fragrance houses anchor European procurement of natural-grade material. REACH substance evaluation protocols from ECHA mandate chronic toxicity datasets that favor established compounders with existing compliance infrastructure. The Provence-Alpes-Côte d'Azur cluster concentrates captive microreactor installations for pharmaceutical-grade specialty production.
India
Maharashtra and Gujarat terpene processors supply backward-integrated natural-grade material to global perfumery customers. FSSAI flavor standards govern food additive specifications for domestic flavor houses. Mumbai-Pune chemical corridor anchors distillation capacity serving European luxury fragrance procurement platforms.
United States
FDA food additive regulations drive pharmaceutical-grade certification investments for active ingredient intermediates. New Jersey and Pennsylvania flavor clusters standardize specification protocols for cross-border suppliers. Greater Boston biotech corridor experiments with fermentation-derived nerol precursors for reduced batch variability.
Switzerland
Geneva fragrance compounders benchmark carbon footprint metrics through centralized procurement platforms. Swissmedic pharmaceutical guidelines elevate elemental impurity profiling requirements for excipient-grade material. Basel-Lake Geneva axis concentrates dual-certified production lines serving both fragrance and pharmaceutical markets.
Japan
METI industrial policy supports biotechnology-derived precursor development for pharmaceutical specifications. Kansai region aroma-chemical producers leverage captive fermentation capabilities. Osaka-Kobe chemical corridor integrates continuous-flow manufacturing for reduced production footprints.
Neryl Acetate Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper layer commanding fermentation-derived feedstock security and the lower layer competing on batch flexibility and regional proximity. The structure rewards backward integration into terpene supply and penalizes non-integrated compounders exposed to citronella oil volatility. Three archetypes dominate: biotechnology-integrated producers with captive precursor supply, Indian terpene processors with natural-grade feedstock control, and European continuous-flow specialists with pharmaceutical-grade certification infrastructure. Capacity expansion and strategic partnerships represent the dominant competitive moves, with firms securing fermentation technology licensing or regional distribution alliances.
Within the biotechnology-integrated tier, Takasago International Corporation exemplifies captive fermentation capabilities, while Privi Speciality Chemicals Limited anchors Indian natural-grade supply. Prodasynth SAS occupies a position among European continuous-flow specialists serving pharmaceutical-grade specifications.
| Leading Market Players |
|---|
| Takasago International Corporation |
| Privi Speciality Chemicals Limited |
| Prasol Chemicals Pvt. Ltd |
| The Good Scents Company |
| Prodasynth SAS |
| Citrus and Allied Essences Ltd |
| Berje Inc. |
| Acros Organics N.V. |
| Solventis |
| Others |
Supply & Pricing Matrix
Fermentation-derived nerol precursors displacing steam-distilled citronella feedstocks are redrawing supply geography toward Indian biotech corridors and compressing price premiums for natural-grade material as synthetic routes achieve parity on carbon-footprint benchmarks.
Pricing Analysis
Long-term offtake contracts dominate procurement between Grasse fragrance houses and Maharashtra terpene processors, insulating integrated suppliers from spot-market citronella volatility while spot transactions concentrate among non-integrated compounders exposed to harvest fluctuations. Price differentiation rests on certification tier—pharmaceutical-grade commands substantial premiums for elemental impurity documentation, while cosmetic-grade faces compression from synthetic substitute blends. Pricing pressure intensifies in standard-grade segments as linalyl acetate alternatives capture mass-market personal care volume. Small-batch perfumery customers in Switzerland exhibit lowest price sensitivity, prioritizing biobased content verification over unit economics.
Supply Chain Analysis
Strategic stockpiling of citronella oil concentrates among Indian terpene processors buffers against Indonesian and Sri Lankan harvest volatility, whereas European fragrance houses prefer just-in-time microreactor production for pharmaceutical-grade batches. Supply concentrates in India, France, and Switzerland, with raw material dependencies on citronella oil, acetic anhydride, and fermentation-derived nerol. Single-source vulnerability in Indonesian citronella cultivation transmits weather-driven shocks directly to feedstock costs. Distribution runs through centralized procurement platforms that disintermediate traditional distributor networks for specialty chemical marketplace access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital platform intermediation in fragrance procurement is creating platform-economics dynamics where supplier certification data interoperability determines marketplace access, rewarding compounders with verified biobased documentation APIs.
For Market Incumbents: Consolidate backward integration into Indian terpene feedstock supply to secure natural-grade material security against citronella price volatility, while dual-certifying production lines for REACH cosmetic regulation and EMA pharmaceutical excipient standards to capture margin pools inaccessible to commodity producers. Captive fermentation capabilities and microreactor installations defend positioning against biotechnology-integrated entrants. For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade certification infrastructure with elemental impurity profiling capabilities, targeting the fastest-expanding margin pool in active pharmaceutical ingredient intermediates where FDA and EMA filing requirements exclude commodity compounders. White-space exists in direct-to-compounder digital platforms for small-batch Swiss and French perfumery customers, with go-to-market anchored on carbon-footprint benchmarking tools. For Investors and Strategic Acquirers: ECHA chronic toxicity dataset requirements reshapes the acquisition landscape toward certified suppliers with existing compliance infrastructure, favoring targets with EU-based testing partnerships and fermentation technology licensing. Long-term viability centers on biotechnology-integrated producers with captive precursor supply over legacy petrochemical assets. Watch for REACH substance evaluation protocol enforcement intensity as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Terpene Feedstock | Maharashtra and Gujarat processors secure natural-grade supply against Indonesian harvest volatility. |
| Dual-Certification Investment | European compounders capture pharmaceutical-grade margin pools with EMA elemental impurity documentation. |
| Fermentation Technology Licensing | Biotechnology-derived nerol reduces batch-to-batch variability for pharmaceutical specifications. |
| Microreactor Installation | Grasse and Geneva houses compress minimum efficient scale for captive specialty production. |
| Digital Platform Integration | Centralized procurement marketplaces disintermediate traditional distributor networks in France and Switzerland. |
Research Methodology
The analysis maps natural-grade, synthetic, pharmaceutical-grade, and cosmetic-grade supply channels, each validated through fragrance house procurement directors, terpene processing plant managers, pharmaceutical regulatory affairs leads, and specialty chemical distribution partners. Primary interview data triangulates against customs and trade flow records, ECHA substance evaluation dossiers, FDA food additive filings, and SEC disclosures from listed aroma-chemical producers. Bottom-up volume builds from identified production capacity and utilization rates reconcile with top-down demand estimates from end-use consumption patterns.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon, with segmentation modeling across grade tier, application channel, and regional production hub dimensions. CAGRs derive from fitted growth curves incorporating pharmaceutical excipient monograph adoption rates, biobased procurement threshold implementation timelines, and fermentation technology diffusion patterns. Industry-specific forecast inputs include citronella oil harvest cycle data and REACH compliance investment trajectories.
Material uncertainties—regulatory enforcement intensity, biotechnology scale-up success rates, and citronella cultivation disruption events—sit outside the modeled envelope. Forecasts reflect documented assumptions on substitution elasticity between natural and synthetic routes. Revision becomes warranted when EMA pharmaceutical excipient guideline implementation crosses enforcement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Sensory Modifiers Market
Flavor and Fragrance Chemicals
Coumarin Market
Flavor and Fragrance Chemicals
Asia Pacific Essential Oils Market
Flavor and Fragrance Chemicals
Citral Market
Flavor and Fragrance Chemicals
Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Guaiacwood Essential Oil Market
Flavor and Fragrance Chemicals
Flavor and Fragrance Market
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Smoke Ingredients Market
Flavor and Fragrance Chemicals
Immortelle Oil Market
Flavor and Fragrance Chemicals
Deodorization Systems Market
Flavor and Fragrance Chemicals
Europe Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Global Perfume Ingredients Chemicals Market
Flavor and Fragrance Chemicals
Linalool Market
Flavor and Fragrance Chemicals
Natural Vanillin Market
Flavor and Fragrance Chemicals
United States Aroma Chemicals Market