
 Sage Essential Oil Market | 2026-2036
Sage Essential Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Sage Essential Oil Market Analysis
Market Context
Multi-source botanical procurement is broadening across the sage essential oil supply base as distillation capacity fragments across Mediterranean and Indian growing belts. Robertet anchors its position through captive cultivation partnerships in southeastern France. Aromatics International leverages direct farmer networks in India and Oregon to secure wildcrafted feedstock. Augustus Oils Ltd competes on steam distillation expertise and custom extraction protocols for pharmaceutical-grade contracts.
Technical Definition and Segment Structure
Sage essential oil is a volatile aromatic extract derived primarily from Salvia officinalis through steam distillation, yielding a complex terpenoid profile dominated by thujone, camphor, and cineole in concentrations that vary sharply by chemotype and harvest timing. The oil serves as an active functional ingredient in antimicrobial formulations, flavor systems, and therapeutic blends where oxidative stability and standardization matter. Organic sage oil commands premium positioning as cosmetic and pharmaceutical buyers enforce residue-free specifications, while aromatherapy applications sustain volume throughput through health food shops and direct practitioner channels. Wildcrafted sage oil occupies a narrowing specialty tier as sustainable harvesting certifications become gatekeeping requirements for EU and North American access.
Regulatory Framework and Outlook
EMA botanical drug guidelines, REACH substance registration thresholds, and ISO 4720 essential oil standards collectively shape extraction methods, labeling claims, and cross-border shipment eligibility for sage oil producers. FDA GRAS status for food flavoring applications and EPA pesticide tolerance rules for cultivated sage further segment compliance burdens by end-use destination. Stakeholders must monitor evolving thujone concentration limits in cosmetic and ingestible applications as toxicological reviews proceed across multiple jurisdictions.
Market Dynamics
Clean-label mandates from cosmetic and pharmaceutical formulators are compressing synthetic ingredient margins while elevating botanical certification requirements, forcing distillation operations to reconfigure solvent systems and traceability infrastructure.
Growth Catalysts
- EU Green Deal solvent restrictions:REACH-compliant extraction methods are becoming table stakes for European market access, pulling investment into steam distillation upgrades and closed-loop solvent recovery systems.
- Aromatherapy practitioner networks:Direct-to-practitioner channels are bypassing traditional wholesale layers, building recurring volume through subscription-based supply relationships with clinical and wellness practitioners.
- Thujone-standardized chemotypes:Pharmaceutical-grade contracts now specify precise terpenoid profiles, rewarding producers with gas chromatography capabilities and batch-to-batch consistency protocols.
Market Restraints
- Wild sage harvest limitations:Sustainable harvesting certifications from the Union for Ethical BioTrade are narrowing legal supply from uncultivated sources, constraining specialty-grade volumes.
- Climate volatility in Provence:Drought cycles in southeastern France are compressing Salvia officinalis yields and fragmenting harvest windows, forcing processors to diversify sourcing to less predictable Indian and Oregon belts.
- Synthetic antimicrobial substitutes:Petrochemical-derived alternatives in industrial cleaning and preservation applications are undercutting sage oil on unit cost in price-sensitive institutional contracts.
Strategic Opportunities
- India's organized cultivation expansion:Contract farming networks in Rajasthan and Himachal Pradesh are scaling irrigated sage production for export-grade distillation, capturing share from Mediterranean wildcrafting.
- Biotechnology-enabled terpenoid synthesis:Precision fermentation platforms are converging with traditional agriculture to produce standardized sage aroma compounds for fragrance houses seeking batch consistency.
- Direct-to-formulator e-commerce:Specialty chemical marketplaces are disintermediating traditional essential oil brokers, enabling smaller distillers to access cosmetic R&D labs with sample-to-bulk workflows.
Industry Challenges
- Gas chromatography-mass spectrometry technician scarcity:Analytical chemists capable of terpenoid profiling and adulteration detection are concentrated in fragrance hub regions, limiting quality assurance scaling in emerging production zones.
- Organic certification timeline compression:Three-year conversion periods for conventional sage fields are misaligned with buyer demand surges, creating supply gaps during transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sage Essential Oil Market |
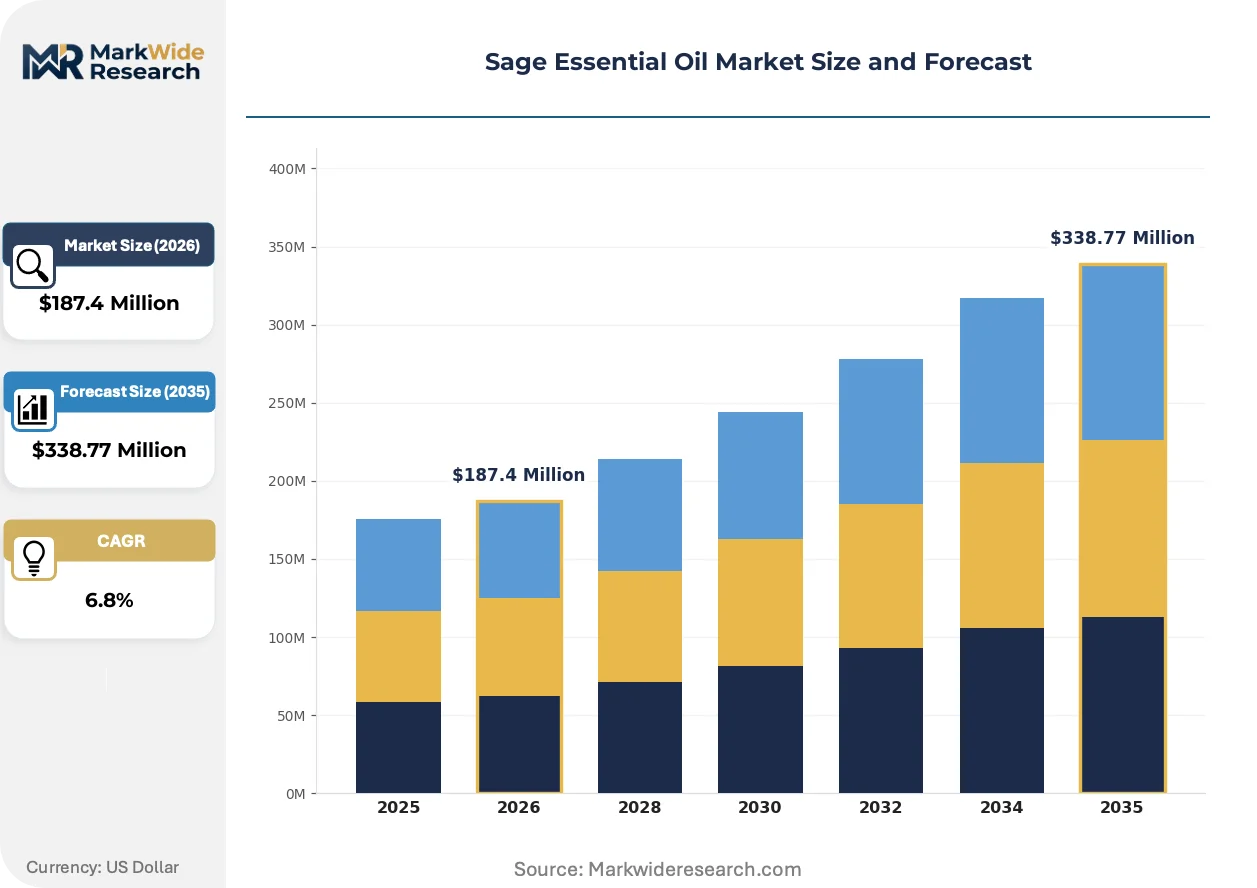
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Sage Oil, Conventional Sage Oil, Wildcrafted Sage Oil, Extracted Sage Oil Application: Aromatherapy, Cosmetics, Pharmaceuticals, Food Flavoring Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Food Shops End User: Individual Consumers, Manufacturers, Health Practitioners, Spa Owners |
| Companies Covered | India Essential Oils, Aromatics International, Robertet, Augustus Oils Ltd, Bontoux S.A, Saje Natural Wellness, The Essential Oil Company, Lluch Essence S.L., Stratum Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sage Essential Oil Market Emerging Trajectories
Extraction technology and certification protocols are the primary vectors of competitive differentiation, with producers racing to align laboratory capabilities with tightening residue and authenticity standards across pharmaceutical and cosmetic procurement specifications.
Supercritical CO2 extraction is converging with traditional steam distillation in hybrid processing facilities, enabling selective fractionation of thujone and camphor for customized pharmaceutical applications. Mid-scale distillers in France and India are retrofitting equipment to offer both methods from single facilities. This dual-capability configuration is compressing lead times for bespoke chemotype requests and capturing contract volumes that previously required multiple suppliers.
EMA botanical drug guidelines are mandating enhanced documentation of cultivation origin and harvest timing for ingredients entering medicinal product pathways. Compliance burdens are falling most heavily on wildcrafted supply chains lacking batch traceability infrastructure. Producers with captive cultivation partnerships are securing preferential access to pharmaceutical procurement channels as documentation requirements harden.
Certification-driven purchasing is elevating residue-free specifications above price in cosmetic formulator sourcing decisions. Clean beauty brands are bypassing traditional wholesale markets to establish direct supply relationships with certified organic distillers. This channel migration is most visible in French and German cosmetic R&D clusters, where procurement teams now require third-party organic verification before sample evaluation.
Sage Essential Oil Market Segmentation
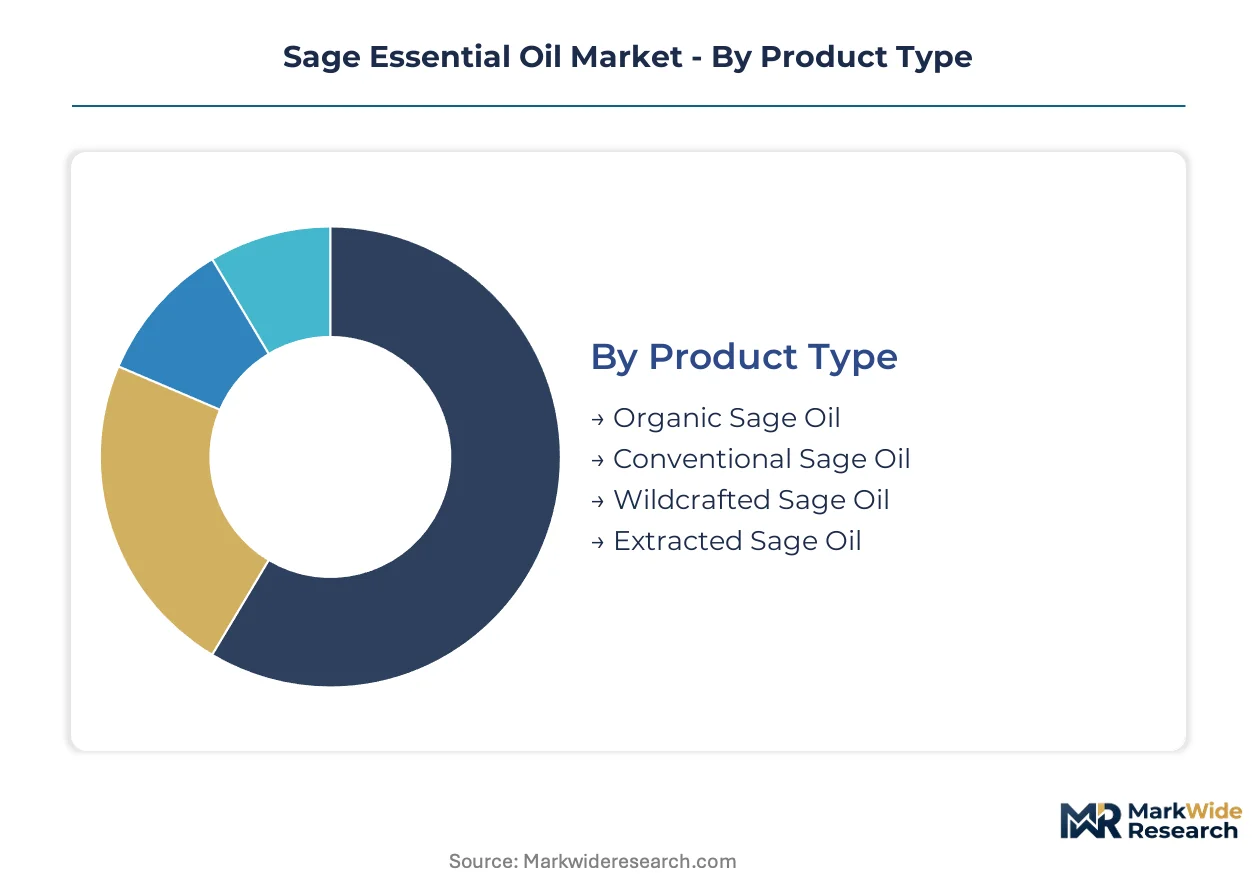
Sage essential oil segmentation reflects divergent certification standards and extraction protocols that determine channel eligibility and pricing power. Buyers sort supply into tiered quality grades that map directly to end-use restrictions in cosmetics, pharmaceuticals, and food applications.
Product Type:
Integration depth varies sharply across product types, with organic and conventional grades serving as standalone ingredients while wildcrafted and extracted variants embed into specialized formulations requiring traceability documentation.
- Organic Sage Oil:Steam-distilled from certified organic Salvia officinalis with thujone levels typically below 25% and zero synthetic pesticide residues. Cosmetic formulators in France and Germany now require Ecocert or USDA Organic verification before sample evaluation, locking conventional supply out of premium clean-beauty channels.
- Conventional Sage Oil:Cultivated sage processed through standard steam distillation without organic certification. Volume concentrates in institutional aromatherapy and mid-tier personal care where price sensitivity outweighs residue concerns, though REACH registration costs are compressing margins for smaller distillers.
- Wildcrafted Sage Oil:Harvested from uncultivated populations in Oregon and Provence with Union for Ethical BioTrade certification. Supply volumes are contracting as sustainable harvesting quotas tighten.
- Extracted Sage Oil:Supercritical CO2 or solvent-extracted concentrates for pharmaceutical fractionation. Batch consistency requirements favor producers with captive gas chromatography capabilities.
Conventional sage oil leads volumes today; organic certification is gaining share fastest as clean-label mandates harden across European cosmetic procurement.
Application:
End-use segmentation tracks regulatory intensity, with pharmaceutical and food pathways demanding documentation infrastructure that aromatherapy and cosmetic channels only partially enforce.
- Aromatherapy:Diffuser and topical applications driving volume through practitioner networks and health food retail. ISO 4720 standards govern labeling claims, though enforcement varies by distribution channel.
- Cosmetics:Active ingredient in antimicrobial and antioxidant formulations where thujone concentration limits apply. EMA botanical drug guidelines are elevating cultivation documentation requirements for medicinal cosmetic claims.
- Pharmaceuticals:Standardized chemotypes for therapeutic blends with specified terpenoid profiles. FDA GRAS status enables food-adjacent applications but drug pathway entry requires EMA-compliant master files.
- Food Flavoring:Sage oil in savory flavor systems with thujone caps regulated by EFSA and FDA. Volume growth tracks clean-label seasoning trends in European prepared foods.
Cosmetics applications anchor current revenue; pharmaceutical-grade contracts are expanding most quickly as documentation-hardened supply chains secure preferential access.
Distribution Channel:
Channel structure reflects buyer sophistication gradients, with direct-to-formulator e-commerce disintermediating traditional wholesale layers for certified organic supply.
- Online Retail:Direct-to-consumer and practitioner subscription models bypassing distributor markups. Specialty chemical marketplaces now enable sample-to-bulk workflows for cosmetic R&D labs.
- Specialty Stores:Dedicated essential oil retailers serving aromatherapy practitioners with batch-specific certificates of analysis. Inventory depth favors established French and Indian distillers with consistent supply.
- Supermarkets:Mass-market personal care and home fragrance products with minimal terpenoid specification. Price competition from synthetic alternatives constrains sage oil penetration.
- Health Food Shops:Practitioner-adjacent retail with organic certification as primary quality signal. Staff training gaps limit technical differentiation between chemotypes.
Specialty stores dominate premium organic volumes; online retail channels are climbing the fastest as direct procurement bypasses traditional broker layers.
End User:
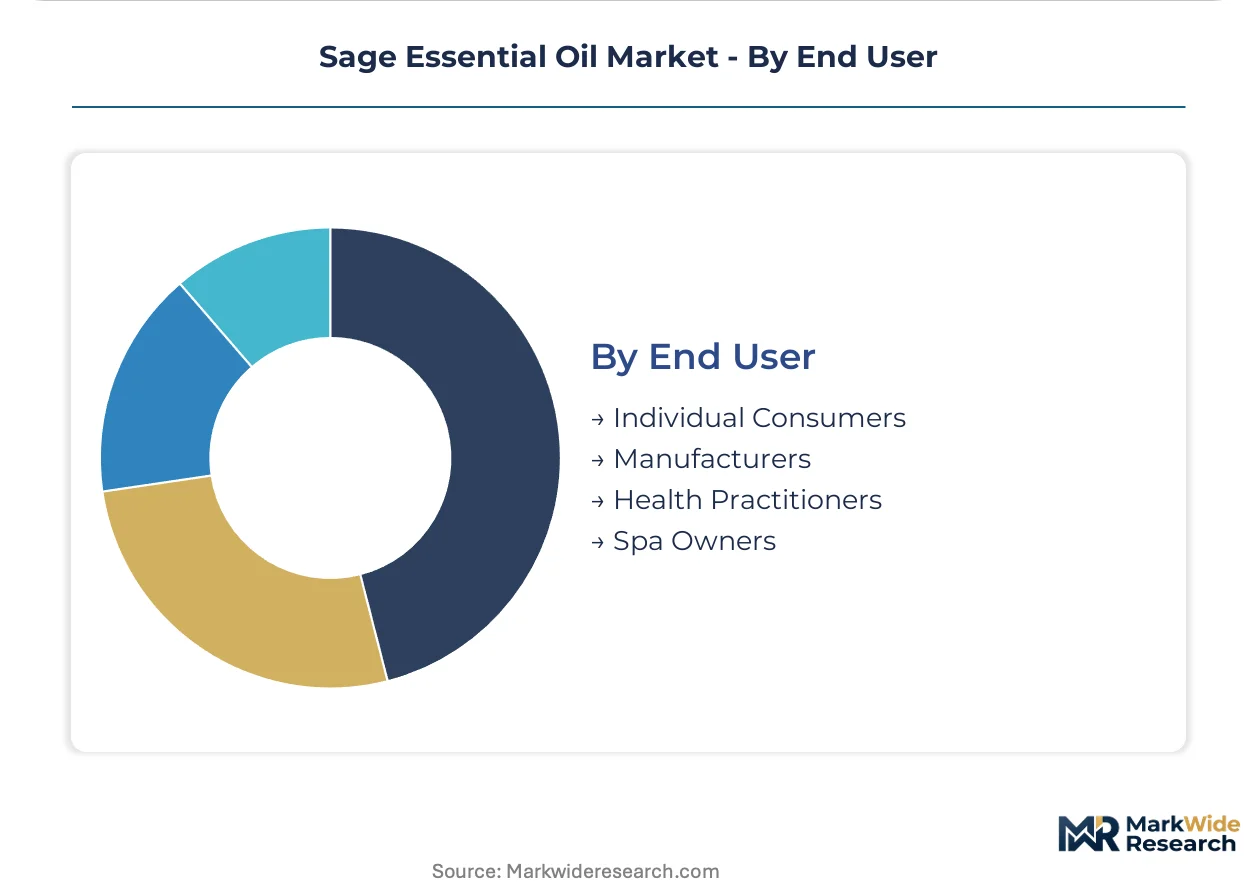
User segmentation maps to purchase scale and specification intensity, with manufacturers and health practitioners driving standardization while individual consumers and spa owners prioritize availability over batch documentation.
- Individual Consumers:Home aromatherapy and personal care use with limited technical evaluation capacity. Price sensitivity concentrates demand in conventional and wildcrafted tiers.
- Manufacturers:Cosmetic, pharmaceutical, and food companies with incoming quality testing and supplier audit programs. REACH and FDA compliance documentation is non-negotiable for contract eligibility.
- Health Practitioners:Clinical aromatherapists and naturopaths requiring consistent chemotype profiles for therapeutic protocols. Subscription relationships with certified distillers provide supply security.
- Spa Owners:Wellness service providers using sage oil in treatment blends with brand positioning around natural ingredients. Certification requirements lag cosmetic manufacturers but are tightening.
Manufacturers represent the largest volume block; health practitioners are expanding most quickly as clinical aromatherapy gains reimbursement traction in select European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provence-Alpes-Côte d'Azur anchors global sage essential oil distillation capacity, with southeastern France's processing cluster handling the majority of pharmaceutical-grade extraction. Climate volatility and regulatory tightening are redistributing cultivation investment toward irrigated belts in India and the western United States.
France
Cosmetic formulators in Grasse and pharmaceutical buyers in Lyon drive demand for certified organic sage oil with sub-25% thujone profiles. REACH registration requirements and EU Green Deal solvent restrictions compel distillers to upgrade steam infrastructure and implement closed-loop recovery systems. The Provence-Alpes-Côte d'Azur region concentrates both Salvia officinalis cultivation and supercritical CO2 processing facilities.
India
Contract farming networks in Rajasthan and Himachal Pradesh are scaling irrigated sage production for export-grade distillation, displacing Mediterranean wildcrafting volumes. FSSAI export certification and DGFT trade facilitation support organized cultivation expansion. Jaipur and surrounding districts host emerging distillation capacity serving European cosmetic and aromatherapy channels.
United States
Wildcrafted sage harvesting in Oregon supplies specialty aromatherapy and natural wellness brands with Union for Ethical BioTrade-certified material. EPA pesticide tolerance rules and FDA GRAS status for food applications segment compliance requirements by end-use destination. The Pacific Northwest maintains concentrated wildcrafting operations despite tightening sustainable harvest quotas.
Germany
Cosmetic R&D labs in Hamburg and Frankfurt enforce residue-free specifications that lock conventional sage oil out of premium procurement channels. EMA botanical drug guidelines and BfR thujone assessments shape ingredient documentation requirements for medicinal product pathways. North Rhine-Westphalia hosts quality testing infrastructure that batch-verifies terpenoid profiles for downstream formulators.
United Kingdom
Aromatherapy practitioner networks and health food retail channels sustain volume throughput for mid-tier conventional sage oil. Trading relationships with French and Indian distillers dominate supply procurement as domestic cultivation remains minimal. London-based specialty chemical distributors intermediate between certified producers and cosmetic formulation houses.
Sage Essential Oil Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue certified organic and pharmaceutical-grade specialization. The market structure fragments across captive cultivation partnerships, direct farmer networks, and toll distillation arrangements. Three archetypes dominate: integrated French distillers with Provencal land control, Indian contract farming aggregators, and mid-scale North American wildcrafting specialists. Competitive moves center on organic certification acquisition and gas chromatography capability installation for batch consistency documentation.
Among French integrated producers, Robertet exemplifies the captive cultivation archetype through southeastern France land partnerships. Aromatics International occupies a position bridging Indian and Oregon sourcing networks for wildcrafted feedstock security. Augustus Oils Ltd represents the analytical-specialist tier, with British incorporation signaling pharmaceutical-grade contract orientation. These three anchors illustrate the geographic and functional stratification pressuring smaller conventional distillers.
| Leading Market Players |
|---|
| India Essential Oils |
| Aromatics International |
| Robertet |
| Augustus Oils Ltd |
| Bontoux S.A |
| Saje Natural Wellness |
| The Essential Oil Company |
| Lluch Essence S.L. |
| Stratum Nutrition |
| Others |
Supply Flow & Price Mechanics
Cosmetic formulators in France and Germany anchor pricing power through residue-free procurement mandates that stratify supply into certification-locked tiers. Their collective buying concentration forces distillers to absorb organic conversion costs while passing through only partial premiums to mid-tier aromatherapy channels.
Pricing Analysis
Steam distillation feedstock costs pass through unevenly across the value chain, with organic sage oil commanding premium-mid-economy pricing differentiation based on Ecocert verification and thujone standardization. Price differentiation hinges on gas chromatography documentation and REACH registration status. Cost compression in conventional grades is intensifying because Indian contract farming is expanding irrigated supply. Institutional aromatherapy buyers exhibit highest price sensitivity; pharmaceutical contract buyers show least.
Supply Chain Analysis
Salvia officinalis biomass supply rests on cultivation partnerships in France's Provence-Alpes-Côte d'Azur region, irrigated contract farms in Rajasthan and Himachal Pradesh, and wildcrafted harvesting in Oregon. Key inputs include certified seed stock, steam distillation equipment, and supercritical CO2 processing capacity. Single-source vulnerability concentrates in analytical chemist talent for terpenoid profiling. Distribution runs through specialty chemical marketplaces disintermediating traditional broker layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sage essential oil market reads as a late-cycle quality story where clean-label cosmetic procurement is displacing conventional supply through certification-mandatory sourcing protocols.
For Market Incumbents: Anticipate biotechnology-enabled terpenoid synthesis eroding batch-consistency premiums by securing captive gas chromatography capabilities and deepening backward integration into certified organic cultivation in southeastern France. Prioritize EMA-compliant master file documentation to defend pharmaceutical contract eligibility against emerging Indian distillers. For New Entrants and Emerging Players: Direct-to-formulator e-commerce platforms offer the most penetrable route for Rajasthan-based distillers to bypass established French broker networks. Target health practitioner subscription channels in Germany and the United Kingdom with sample-to-bulk workflows and third-party organic verification preceding price negotiation. For Investors and Strategic Acquirers: Fragrance houses with captive cultivation deficits are the most active acquirer in this space, seeking analytical-specialist distillers with pharmaceutical-grade contract books. The long-term viability window favors producers with dual steam distillation and supercritical CO2 capabilities. Watch biotechnology fermentation cost curves as the signal for synthetic substitution inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Acquisition | Ecocert and USDA Organic verification unlocks French and German cosmetic procurement channels. |
| Dual-Extraction Capability Installation | Hybrid steam distillation and supercritical CO2 facilities capture bespoke pharmaceutical fractionation contracts. |
| Direct-to-Practitioner Channel Buildout | Subscription relationships with clinical aromatherapists generate recurring volume insulated from spot price volatility. |
| Captive Cultivation Partnership Expansion | Land control in Provence or Rajasthan secures biomass supply against climate-driven yield fragmentation. |
| Gas Chromatography-Mass Spectrometry Laboratory Investment | In-house terpenoid profiling capabilities satisfy EMA botanical drug guideline documentation requirements. |
Methodological Framework
Multiple input streams — distiller procurement directors, cosmetic R&D formulators, aromatherapy practitioner networks, and regulatory affairs specialists — were reconciled against secondary sources including EMA botanical drug guideline submissions, REACH registration databases, FSSAI export certifications, and EU Green Deal solvent restriction impact assessments. Bottom-up volume modeling from cultivation acreage and distillation capacity was triangulated against top-down value estimates from trade flow analysis.
Data-stream reconciliation anchored projections across the analysis window through segmentation by product type (organic, conventional, wildcrafted, extracted), application pathway (cosmetics, pharmaceuticals, aromatherapy, food flavoring), and distribution channel (direct e-commerce, specialty retail, wholesale broker). CAGRs were derived from trend extrapolation of certification adoption rates and biotechnology substitution timelines. Forecast inputs incorporated climate volatility scenarios for Mediterranean growing belts and organic conversion pipeline dynamics.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation terpenoid synthesis would alter the outlook. Forecasts reflect assumptions about sustained EU regulatory tightening and stable fragrance house demand for standardized chemotypes. A small set of triggers — biotechnology cost breakthroughs, thujone limit revisions, and climate shocks in Provence — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Essential Oil Blends Market
Flavor and Fragrance Chemicals
Nonanal Market
Flavor and Fragrance Chemicals
Global Natural Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
Citral Market
Flavor and Fragrance Chemicals
Tangerine Oil Market
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Deodorization Systems Market
Flavor and Fragrance Chemicals
Natural Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Camphor Market
Flavor and Fragrance Chemicals
Synthetic Musk Market
Flavor and Fragrance Chemicals
Gel Air Fresheners Market
Flavor and Fragrance Chemicals
Anisole Market
Flavor and Fragrance Chemicals
Fragrance Fixatives Market
Flavor and Fragrance Chemicals
Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Ferulic Acid Market
Flavor and Fragrance Chemicals
3-Methyl Valeric Acid Market