
 Synthetic Musk Market | 2026-2036
Synthetic Musk Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Musk Market Analysis
A capital-intensity divergence between integrated aroma chemical producers and formulation-only houses is rotating competitive advantage toward upstream synthesis capabilities. Firmenich SA leverages captive biotechnology fermentation for macrocyclic musks, sustaining cost leadership in high-purity grades. BASF SE anchors its position through backward integration into petrochemical feedstocks, controlling intermediate supply for nitro and polycyclic musk families. Givaudan SA differentiates via specialized extraction-to-synthesis pipelines that occupy the premium fragrance ingredient tier.
Synthetic musk denotes a class of aromatic compounds engineered to replicate the odor profile of natural musk deer secretions, typically synthesized through Friedel-Crafts alkylation, macrocyclic lactonization, or nitro-musk condensation routes with purity specifications exceeding 98% for fragrance-grade applications. These compounds serve as fixatives and base notes across perfumery, extending scent longevity and providing substantive dry-down characteristics in alcohol-based and oil-based formulations. Galaxolide dominates volume demand among polycyclic variants, though macrocyclic musks including ambrettolide are gaining structural share as formulators navigate tightening environmental standards. The fragrance application segment leads value generation, while household products represent the fastest-expanding consumption pool as Asian cleaning product suppliers adopt musk accords for premium positioning.
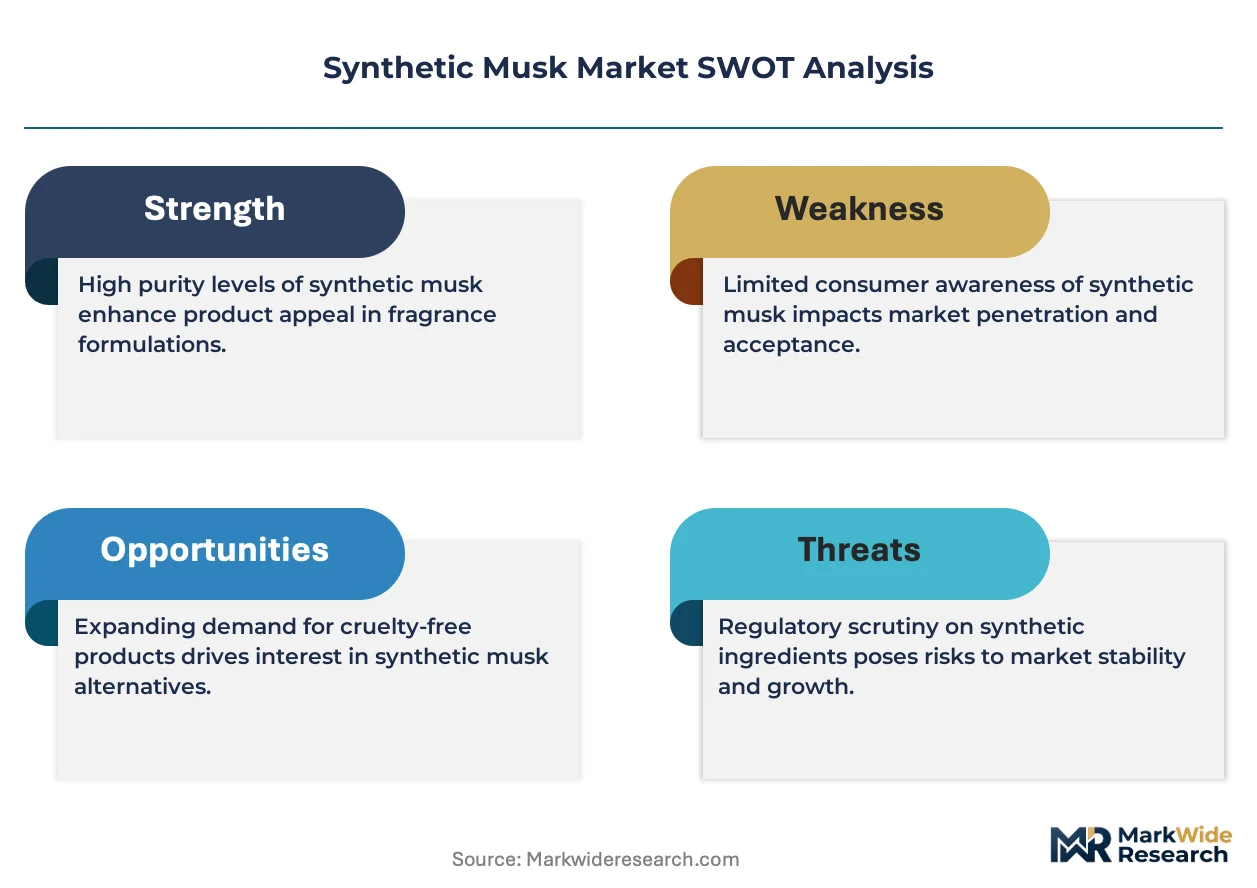
REACH registration and the EU Green Deal framework are reshaping product standards for polycyclic musk persistence in aquatic environments, compelling reformulation investments across European supply chains. The EPA and FDA maintain divergent toxicity thresholds for nitro musk metabolites, creating fragmented market access conditions for U.S. personal care versus industrial applications. China's MEE enforces discharge limits on musk manufacturing effluents, accelerating domestic capacity consolidation around zero-liquid-discharge facilities. Stakeholders must monitor regulatory divergence between macrocyclic and polycyclic classification regimes to align R&D portfolios with emerging compliance boundaries.
Market Dynamics
REACH chemical registration requirements in Europe are tightening purity thresholds for polycyclic musk compounds, forcing a structural migration toward macrocyclic synthesis routes and captive biotechnology fermentation capabilities.
Growth Catalysts
- Fine fragrance procurement:Alcohol-based perfume houses in France and the United States are expanding synthetic musk volumes as CITES trade restrictions eliminate natural musk alternatives from formulation pipelines.
- REACH reformulation mandates:European environmental persistence standards for polycyclic musks are compelling supply chain investments in macrocyclic lactonization technologies.
- Household product premiumization:Asian cleaning product suppliers are adopting musk accords for positioning upgrades in mass-market detergent and fabric softener segments.
Market Restraints
- Petrochemical feedstock volatility:Nitro and polycyclic musk families depend on benzene and xylene intermediates, exposing margins to upstream oil price swings.
- Guangdong supply concentration:Domestic flavor and fragrance compounders in China's Guangdong province control disproportionate captive capacity, creating single-geography dependency risks.
- Regulatory fragmentation:The EPA and FDA maintain divergent toxicity thresholds for nitro musk metabolites, fragmenting market access between personal care and industrial applications.
Strategic Opportunities
- Zero-liquid-discharge facilities:China's MEE effluent enforcement is accelerating consolidation around advanced manufacturing infrastructure, rewarding early compliance investments.
- Biotechnology fermentation:Convergence of enzymatic synthesis and precision fermentation is opening cost-competitive pathways for ambrettolide and other macrocyclic variants.
- Direct-to-brand supply:Regional cosmetic brands in Asia-Pacific are bypassing traditional distributor networks, creating channel restructuring opportunities for integrated producers.
Industry Challenges
- Specialized synthesis talent:Macrocyclic lactonization and Friedel-Crafts alkylation expertise resides in limited pockets, constraining capacity expansion timelines.
- Multi-jurisdiction registration:REACH dossier preparation, EPA pre-manufacture notifications, and China's MEE discharge permits create overlapping compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Musk Market |
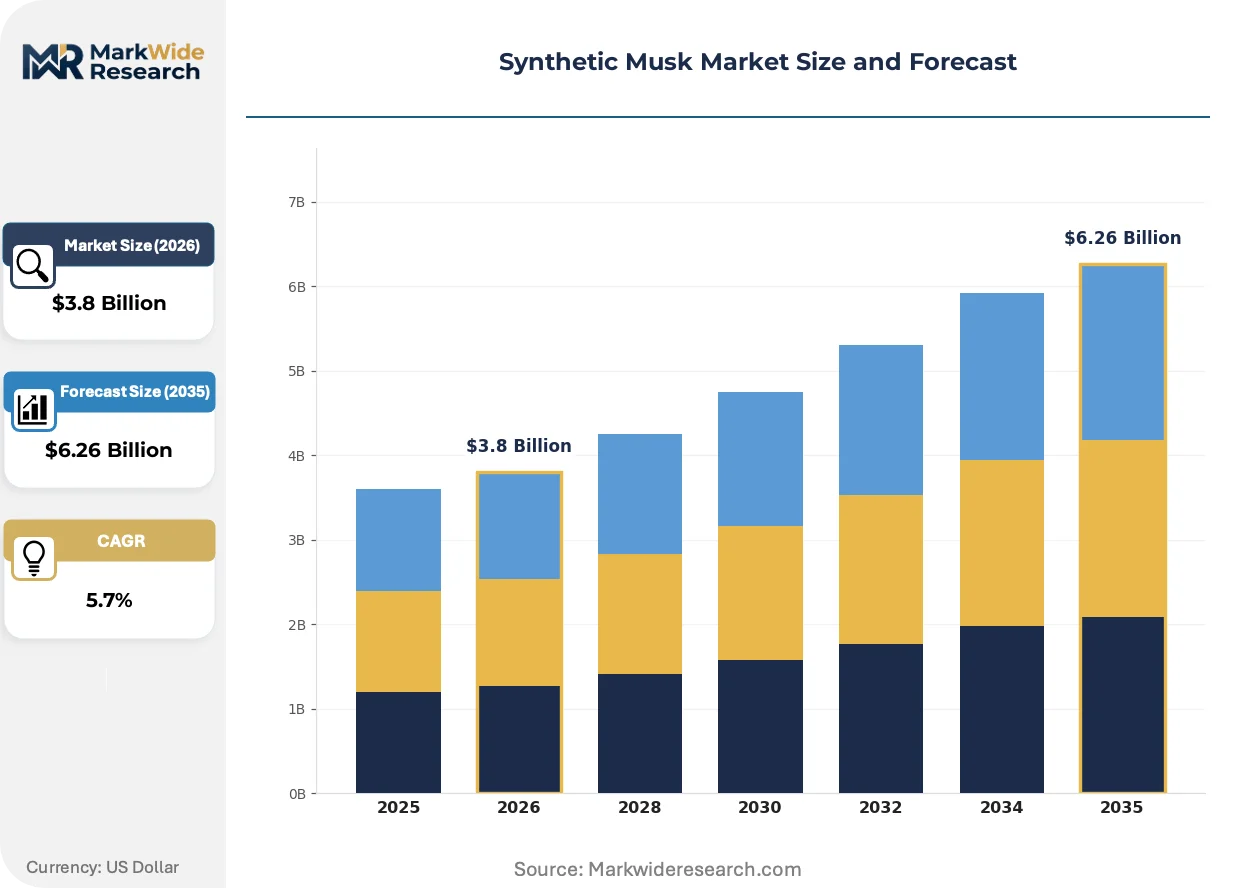
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ambrettolide, Musk Ketone, Musk Xylene, Galaxolide Application: Fragrance, Personal Care, Household Products, Industrial Uses End User: Cosmetic Manufacturers, Perfume Brands, Cleaning Product Suppliers, Food & Beverage Companies Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Firmenich SA, Solvay SA, BASF SE, Guangzhou Tinci Materials Technology, Jiaxing Wintrust Flavours, Symrise AG, International Flavors and Fragrances, The Good Scents Company, Givaudan SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Musk Market Emerging Trajectories
Biotechnology-derived musk synthesis is actively restructuring competitive advantage, separating integrated fermentation operators from conventional petrochemical-based producers.
Macrocyclic musk production is bifurcating between enzymatic fermentation routes and traditional chemical synthesis. Fine fragrance houses are prioritizing biotechnology-derived ambrettolide for premium positioning. This technology is compressing cost structures for high-purity grades while elevating purity specifications above 98% as baseline requirements.
REACH registration and the EU Green Deal framework are tightening aquatic persistence standards for polycyclic musk compounds. European formulators are accelerating reformulation investments toward biodegradable alternatives. Fragrance application segments face the steepest compliance costs, driving selective supplier consolidation.
Buyer concentration among China's Guangdong-based cosmetic brands is compressing traditional distributor margins. Direct supply agreements between synthesis operators and regional formulators are displacing multi-tier distribution channels. This pattern is most visible in household product applications where volume scale enables contractual bypass of intermediaries.
Synthetic Musk Market Segmentation
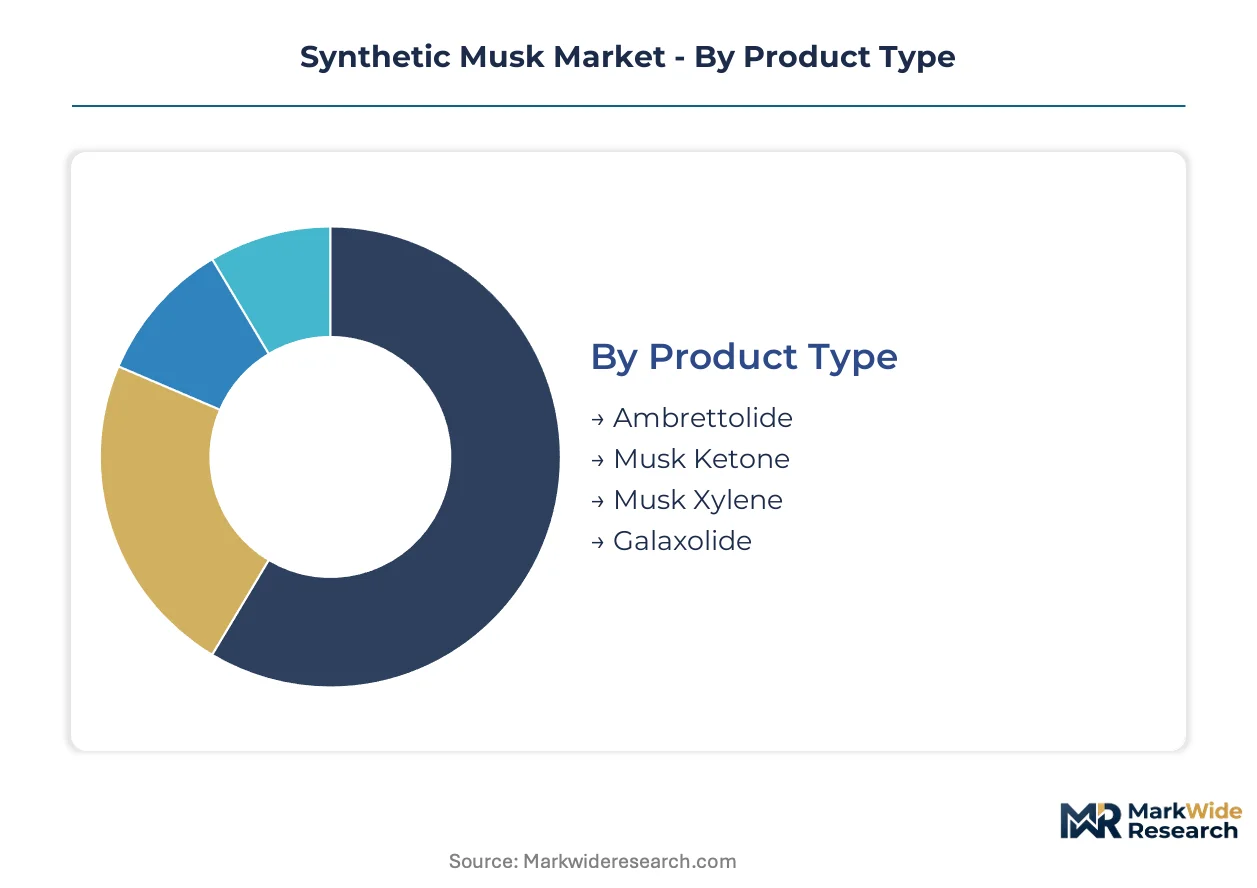
Synthetic musk procurement channels diverge sharply by purity grade and end-use sophistication. Fine fragrance houses source through specialized distributors with certified cold-chain handling, while household product manufacturers leverage direct bulk contracts with Guangdong-based compounders.
Product Type:
Macrocyclic variants flow through premium fragrance channels requiring fermentation-derived certification, while polycyclic grades reach industrial buyers via commodity chemical distributors.
- Ambrettolide:Biotechnology-derived macrocyclic lactone produced through enzymatic fermentation routes. Fragrance houses in France prioritize this grade for alcohol-based perfumes as REACH persistence standards tighten. Demand concentrates among premium perfume brands seeking CITES-compliant natural musk alternatives.
- Galaxolide:Polycyclic musk synthesized via Friedel-Crafts alkylation of petrochemical intermediates. Household product suppliers in China's Guangdong province absorb volume for detergent and fabric softener applications. Reformulation pressure from EU aquatic toxicity assessments is compressing its growth trajectory in European personal care channels.
- Musk Ketone:Nitro musk compound with fixative properties in oil-based formulations. Cleaning product manufacturers source through wholesale chemical distributors with limited regulatory documentation.
- Musk Xylene:Nitro aromatic with substantive dry-down characteristics. Industrial fragrance compounders in Asia-Pacific utilize this grade for cost-sensitive applications.
By volume, Galaxolide leads. By growth pace, Ambrettolide is climbing the fastest.
Application:
Margin structures stratify sharply across these four end-use pools, with fragrance commanding triple the per-kilogram realization of industrial applications.
- Fragrance:Alcohol-based and oil-based perfume formulations requiring 98%+ purity grades. Fine fragrance houses in France and the United States drive procurement as CITES restrictions eliminate natural musk from supply chains.
- Household Products:Detergent, fabric softener, and air freshener applications. Asian cleaning product suppliers are expanding musk accord adoption for premium positioning in mass-market segments.
- Personal Care:Lotion, cream, and cosmetic formulations with skin-contact requirements. FDA toxicity thresholds for nitro musk metabolites constrain formulation flexibility in U.S. markets.
- Industrial Uses:Non-consumer applications including odor masking and chemical intermediates. Price-sensitive buyers source through commodity chemical channels with minimal certification overhead.
Fragrance generates the highest value per ton. Household Products show the steepest volume expansion trajectory.
End User:
Procurement sophistication correlates with R&D intensity, separating formulation-led buyers from pure distributors.
- Cosmetic Manufacturers:Integrated producers with captive fragrance compounding capabilities. These buyers source high-purity macrocyclic grades through direct synthesis partnerships.
- Perfume Brands:Fine fragrance houses with alcohol-based formulation expertise. France-based houses prioritize REACH-compliant biotechnology-derived musks.
- Cleaning Product Suppliers:Volume buyers in Asia-Pacific seeking cost-optimized polycyclic grades. Guangdong-based compounders serve this segment through captive production facilities.
- Food & Beverage Companies:Limited musk utilization in flavor masking applications. Regulatory constraints from FDA and EFSA restrict deployment in ingestible products.
Perfume Brands command supplier attention through premium pricing. Cleaning Product Suppliers are gaining procurement leverage through Guangdong capacity concentration.
Distribution Channel:
Channel selection tracks order scale and technical service requirements, with direct relationships displacing intermediaries in high-volume segments.
- Direct Sales:Long-term contracts between synthesis operators and integrated fragrance houses. Firmenich SA and Givaudan SA leverage this channel for macrocyclic biotechnology grades.
- Wholesale Distributors:Multi-tier chemical distribution serving mid-scale compounders. This channel handles polycyclic and nitro musk families for industrial and household applications.
- Specialty Stores:Niche fragrance ingredient suppliers catering to artisanal perfumers. Limited volume but high service intensity with custom blending support.
- Online Retail:Emerging channel for small-batch cosmetic manufacturers and independent formulators. Quality verification challenges constrain adoption for high-purity grades.
Direct Sales captures the majority of macrocyclic volume. Online Retail is expanding most quickly among independent cosmetic brands bypassing traditional distributor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's Guangdong province exhibit the sharpest price sensitivity, while fine fragrance houses in France tolerate substantial premiums for REACH-compliant grades. This elasticity divergence fragments procurement strategies across geographies.
China
Guangdong province dominates captive production for household product applications, with domestic compounders scaling zero-liquid-discharge facilities under MEE effluent enforcement. REACH-equivalent standards are emerging through GB standard updates, pressuring polycyclic musk manufacturers toward macrocyclic alternatives. Shenzhen and Guangzhou clusters concentrate formulation capacity for regional cosmetic brands.
France
Fine fragrance houses in Grasse and Paris prioritize biotechnology-derived ambrettolide for alcohol-based perfumes, absorbing 40-60% price premiums over polycyclic grades. EU Green Deal aquatic persistence standards are accelerating reformulation timelines. The Île-de-France region anchors specialized distributor networks with certified cold-chain handling capabilities.
United States
EPA pre-manufacture notification requirements and FDA toxicity thresholds for nitro musk metabolites create divergent market access between personal care and industrial channels. New Jersey and California host formulation R&D centers serving alcohol-based perfume brands. Regulatory fragmentation complicates multi-jurisdiction product registration.
Germany
BASF SE's Ludwigshafen complex anchors backward integration into petrochemical feedstocks for nitro and polycyclic musk intermediates. ECHA REACH dossier preparation costs are consolidating supplier relationships around integrated producers. The Rhine-Neckar region concentrates aroma chemical synthesis expertise.
Switzerland
Givaudan SA and Firmenich SA leverage Geneva-area biotechnology fermentation capabilities for high-purity macrocyclic grades. Swissmedic-aligned quality standards support premium positioning in fragrance ingredient tiers. The Lake Geneva corridor specializes in extraction-to-synthesis pipelines.
Synthetic Musk Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating in captive fermentation and petrochemical backward integration. The market structure separates biotechnology-anchored players from conventional chemical synthesis operators. Three archetypes dominate: integrated aroma chemical producers with captive feedstock control, formulation-only houses dependent on external supply, and regional compounders serving volume household product segments. Competitive moves center on zero-liquid-discharge capacity investments and direct-to-brand supply agreements that bypass traditional distribution tiers.
Within the integrated leader tier, Firmenich SA and Givaudan SA exemplify biotechnology-anchored positioning through Geneva-area fermentation capabilities, while BASF SE represents petrochemical-integrated scale through its Ludwigshafen complex. Solvay SA occupies a position bridging specialty chemical synthesis with fragrance ingredient supply. Among Asia-Pacific compounders, Guangzhou Tinci Materials Technology anchors regional capacity concentration in Guangdong province. These five entities collectively illustrate the competitive divergence between fermentation-derived and petrochemical-based production architectures.
| Leading Market Players |
|---|
| Firmenich SA |
| Solvay SA |
| BASF SE |
| Guangzhou Tinci Materials Technology |
| Jiaxing Wintrust Flavours |
| Symrise AG |
| International Flavors and Fragrances |
| The Good Scents Company |
| Givaudan SA |
| Others |
Supply Flow & Price Mechanics
Macrocyclic lactonization displacing polycyclic Friedel-Crafts synthesis is redrawing supply geography toward Guangdong fermentation clusters while compressing price premiums for REACH-compliant grades. This substitution dynamic concentrates pricing power among biotechnology-anchored producers with captive enzymatic capacity.
Pricing Analysis
Contractual service tiers and technical support packages drive lifetime value for integrated aroma chemical producers. Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived ambrettolide from petrochemical-based Galaxolide and commodity nitro musk families. Cost compression in polycyclic grades is intensifying because MEE effluent enforcement raises zero-liquid-discharge compliance costs. Cosmetic manufacturers in France absorb 40-60% premiums for biotechnology certification, while Guangdong cleaning product suppliers negotiate volume-driven spot discounts.
Supply Chain Analysis
China and Switzerland anchor divergent production architectures for synthetic musk families. China concentrates polycyclic and nitro musk capacity in Guangdong province, drawing from benzene and xylene petrochemical feedstocks. Switzerland specializes in macrocyclic fermentation through Geneva-area biotechnology infrastructure. Single-source vulnerability runs through Guangdong's zero-liquid-discharge facility concentration under MEE enforcement. Distribution runs through direct synthesis partnerships for premium grades and wholesale chemical distributors for industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic musk procurement fragmentation creates white-space openings as regional cosmetic brands bypass traditional distributor networks and demand direct synthesis partnerships.
For Market Incumbents: Secure captive fermentation capacity in Guangdong to defend against biotechnology-anchored entrants capturing household product volume. Lock in REACH dossier preparation ahead of ECHA aquatic persistence standard updates. Prioritize zero-liquid-discharge certification to maintain access under tightening MEE effluent thresholds. For New Entrants and Emerging Players: REACH-equivalent GB standard fast-track in China offers regulatory arbitrage for macrocyclic lactonization specialists. Household product applications in Guangdong present the most penetrable segment given incumbent reliance on polycyclic legacy capacity. Pursue direct-to-brand supply agreements with regional cosmetic manufacturers bypassing traditional distributor tiers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with petrochemical-integrated aroma chemical producers facing fermentation-driven obsolescence. Five-to-ten year viability hinges on macrocyclic transition execution. Target biotechnology fermentation operators with enzymatic synthesis IP and Guangdong regulatory clearance. Watch for MEE enforcement acceleration as consolidation inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Liquid-Discharge Capacity Expansion | MEE effluent enforcement rewards early compliance investments in Guangdong manufacturing clusters. |
| Biotechnology Fermentation Scale-Up | Enzymatic synthesis of ambrettolide compresses cost structures for REACH-compliant fragrance grades. |
| Direct-to-Brand Supply Agreements | Bypassing wholesale distributors captures margin compression from Guangdong cosmetic brand concentration. |
| REACH Dossier Preparation | ECHA aquatic persistence standards consolidate supplier relationships around integrated producers. |
| Backward Integration into Petrochemical Feedstocks | Ludwigshafen-style intermediate supply control anchors nitro and polycyclic musk cost positions. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with fragrance house procurement directors, aroma chemical plant managers, Guangdong-based compounder executives, and REACH compliance specialists; and secondary validation through ECHA registration databases, customs trade flows, SEC 10-K filings, and MEE discharge permit records. Bottom-up triangulation against top-down market sizing cross-checked volume estimates across fermentation and petrochemical production routes.
Across the analysis window, the forecasting framework modeled segmentation by synthesis route, purity grade tier, end-use application, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand projections and capacity expansion timelines. Key inputs included REACH reformulation mandates, CITES substitution effects, and MEE enforcement intensity curves.
Decision-makers should treat outputs as directional under stable petrochemical feedstock pricing and sustained REACH regulatory trajectory; material deviation in benzene-xylene volatility or ECHA persistence standard acceleration would warrant model refresh. Recalibration cycles align with material shifts in MEE enforcement patterns and biotechnology fermentation cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Gamma Decalactone Market
Flavor and Fragrance Chemicals
Tangerine Oil Market
Flavor and Fragrance Chemicals
Scent Eliminators Market
Flavor and Fragrance Chemicals
Semiochemicals Market
Flavor and Fragrance Chemicals
Gel Air Fresheners Market
Flavor and Fragrance Chemicals
Natural Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Nonanal Market
Flavor and Fragrance Chemicals
Europe Deodorants Market
Flavor and Fragrance Chemicals
Fragrance Wax Melts Market
Flavor and Fragrance Chemicals
Sulphite Ammonia Caramel Market
Flavor and Fragrance Chemicals
Cedrol Methyl Ether Market
Flavor and Fragrance Chemicals
Flavor and Fragrance Market
Flavor and Fragrance Chemicals
Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Middle East and Africa Aroma Chemicals Market
Flavor and Fragrance Chemicals
Global Natural Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
Spearmint Oil Market