
 Cinnamic Aldehyde Market | 2026-2036
Cinnamic Aldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Cinnamic Aldehyde Market Analysis
Premium fragrance-grade cinnamic aldehyde is decoupling from commodity industrial grades on purity thresholds and extraction traceability. Givaudan SA leverages captive botanical sourcing networks to secure consistent natural supply. Symrise AG anchors its position through integrated R&D labs in Holzminden. Takasago International Corporation differentiates via biotechnology-derived routes that reduce batch-to-batch variation.
Cinnamic aldehyde, or 3-phenyl-2-propenal, is an α,β-unsaturated aromatic aldehyde with a characteristic cinnamon odor, typically synthesized via aldol condensation of benzaldehyde and acetaldehyde or extracted from cinnamon bark essential oil containing 70-90% cinnamaldehyde by mass; it serves primarily as a fragrance precursor, flavoring agent, and pharmaceutical intermediate. The natural product type segment commands margin premiums where EU Regulation 1334/2008 on flavorings restricts synthetic additive labeling, while pharmaceutical applications show structural momentum as cinnamaldehyde derivatives advance through anti-inflammatory and antimicrobial compound pipelines. Synthetic grades retain volume dominance in industrial chemical production where cost efficiency outweighs provenance claims.
REACH registration requirements in Europe, FDA 21 CFR 182.60 designation for synthetic flavor use, and FSSAI standards in India collectively determine market access thresholds and formulation compliance costs. The EU Green Deal chemical sustainability targets are pressuring producers to document carbon intensity across extraction and synthesis pathways. Stakeholders must monitor regulatory divergence between jurisdictions where natural-label claims carry enforceable legal weight versus markets with permissive synthetic additive frameworks.
Market Dynamics
REACH registration dossiers and evolving EU Green Deal chemical sustainability targets are forcing cinnamic aldehyde producers to document carbon intensity across extraction and synthesis pathways, compressing margins for non-compliant suppliers.
Growth Catalysts
- EU Regulation 1334/2008:Restrictions on synthetic additive labeling in flavorings create margin premiums for natural-extraction grades, pulling investment toward botanical sourcing networks.
- Pharmaceutical pipelines:Anti-inflammatory and antimicrobial cinnamaldehyde derivatives advancing through clinical stages generate structural demand for high-purity pharmaceutical intermediates.
- China's fine-chemical scaling:Domestic producers in Shandong and Jiangsu provinces are expanding natural-extraction capabilities to serve export markets in Europe and North America.
Market Restraints
- Benzaldehyde input volatility:Petroleum-derived benzaldehyde price swings directly compress synthetic cinnamic aldehyde margins, with no viable bio-based alternative at scale.
- Sri Lankan cinnamon supply concentration:Seventy percent of true Ceylon cinnamon bark sourcing clusters in Sri Lanka's southern districts, exposing fragrance houses to climate and political disruption.
- FDA 21 CFR 182.60 threshold constraints:Synthetic flavor use ceilings in food applications cap volume expansion for petrochemical-derived grades regardless of cost efficiency.
Strategic Opportunities
- Biotechnology-derived routes:Yeast-based fermentation of cinnamic acid to aldehyde reduces batch-to-batch variation and opens natural-label positioning without agricultural land constraints.
- India's FSSAI standard evolution:Tightening domestic flavor additive rules create first-mover advantage for producers with pre-validated natural-extraction documentation.
- Clean-label fragrance expansion:Personal care brands in Germany and France are reformulating to exclude synthetic aldehydes, expanding addressable market for certified-natural grades.
Industry Challenges
- Analytical chemist scarcity:GC-MS and carbon-14 dating expertise for natural-origin verification is concentrated among retiring specialists in European fragrance houses.
- REACH compliance timelines:Extended substance evaluation periods for new extraction solvents delay product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cinnamic Aldehyde Market |
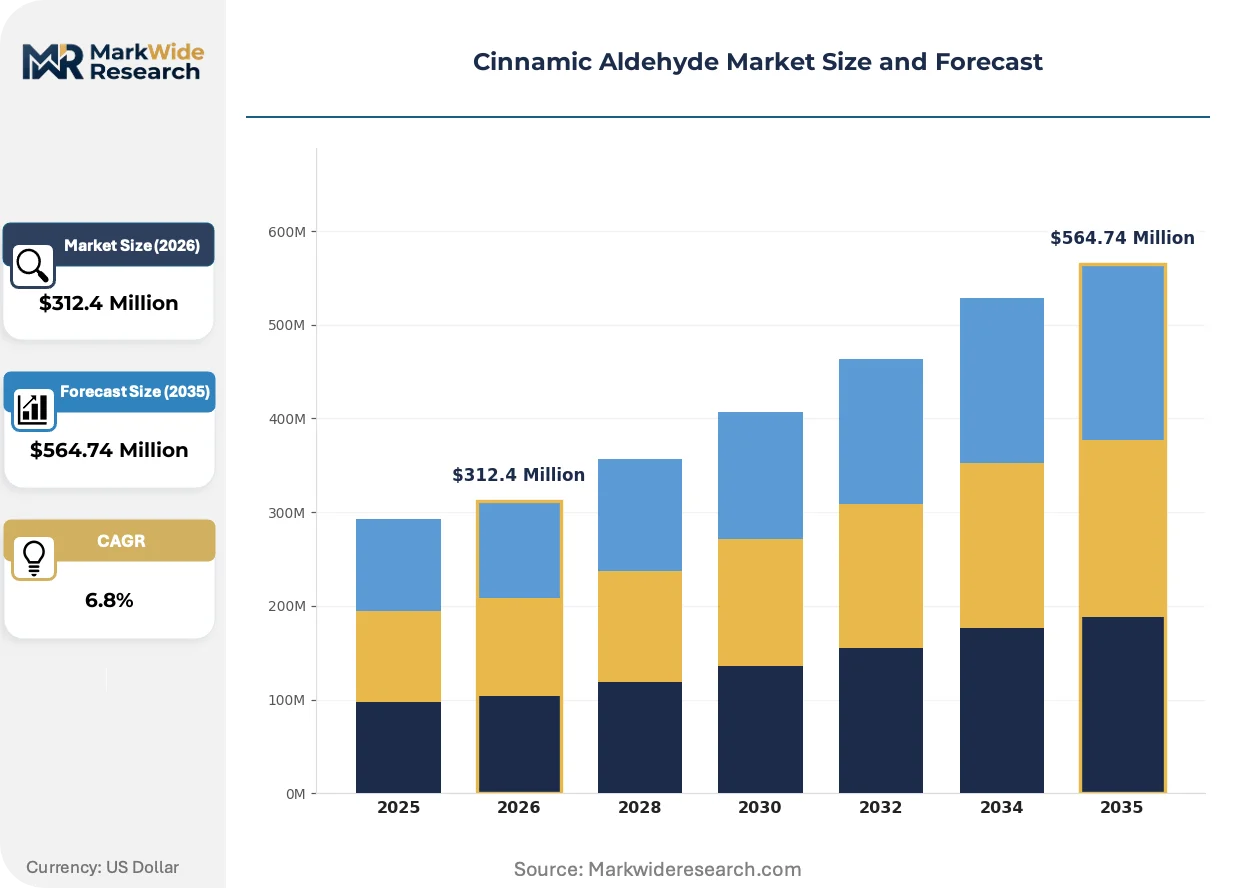
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Blended, Organic Application: Fragrance, Flavoring, Cosmetic, Pharmaceutical End User: Food Industry, Cosmetic Manufacturers, Pharmaceutical Companies, Chemical Producers Distribution Channel: Online Retail, Distributors, Direct Sales, Wholesalers |
| Companies Covered | Givaudan SA, Merck KGaA Sigma-Aldrich, LANXESS, Solvay S.A., BASF, Emerald Kalama Chemical, Takasago International Corporation, Kao Corporation, Symrise AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cinnamic Aldehyde Market Emerging Trajectories
Bioprocess engineering and regulatory transparency requirements are fragmenting the traditional synthetic-natural binary in cinnamic aldehyde supply, creating new competitive axes around traceability and carbon accounting.
Precision fermentation of cinnamic aldehyde using engineered yeast strains is decentralizing production geography by enabling fermentation facilities in temperate zones to compete with tropical cinnamon agriculture. Fragrance houses in Germany and Switzerland are piloting these routes to reduce dependency on Sri Lankan bark supply. The technology is decentralizing value capture toward biotechnology specialists and away from traditional agricultural commodity traders.
REACH Article 33 disclosure obligations for Substances of Very High Concern are tightening documentation requirements across the full extraction-to-formulation chain. Suppliers must now provide SCIP database entries for cinnamic aldehyde-containing articles, adding administrative overhead. Fragrance compounders serving EU cosmetic brands are most affected, with several reformulating to exclude borderline-classified aldehyde derivatives.
Fragrance houses are unbundling after-sales technical service from material supply contracts, shifting toward standalone formulation consulting fees. Specialty distributors in the Netherlands and Singapore are capturing this value by hiring in-house perfumery chemists. The model is most visible in North American personal care, where mid-sized brands lack internal formulation expertise but resist long-term supply commitments.
Cinnamic Aldehyde Market Segmentation
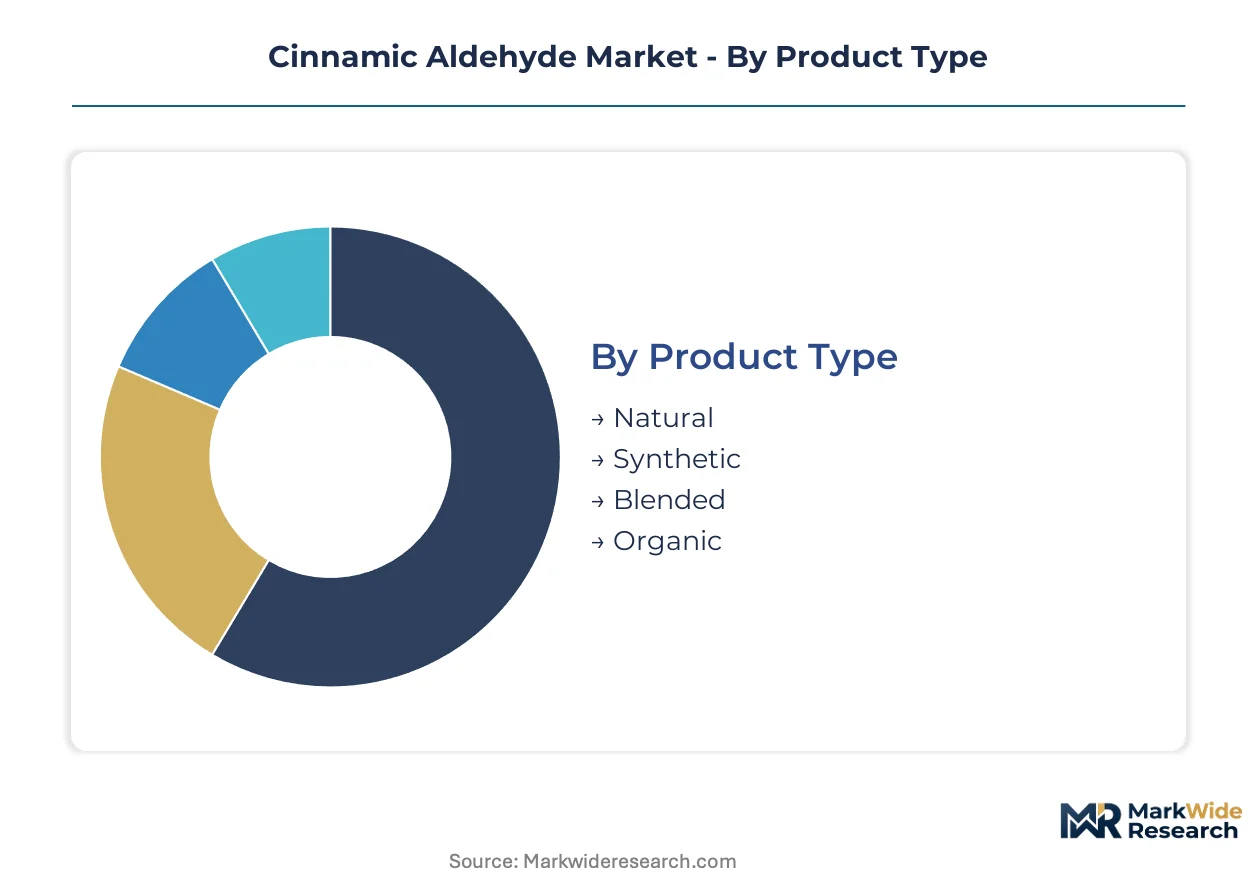
Cinnamic aldehyde segmentation reflects divergent purity requirements and regulatory positioning strategies. Natural-extraction grades command certification premiums in EU flavorings, while synthetic volumes anchor industrial chemical production.
Product Type:
Volume concentration favors petrochemical synthesis, yet margin capture clusters in certified-natural grades where EU Regulation 1334/2008 restricts synthetic labeling.
- Natural:Extracted from Cinnamomum verum bark essential oil containing 70-90% cinnamaldehyde by mass. Fragrance houses in France and Germany source through captive Sri Lankan botanical networks to secure EU-compliant natural-label positioning.
- Synthetic:Manufactured via aldol condensation of benzaldehyde and acetaldehyde. Chemical producers in China's Shandong province dominate export volumes for industrial applications where provenance claims carry no regulatory weight.
- Blended:Standardized mixtures balancing cost efficiency with partial natural content for mid-tier fragrance formulations.
- Organic:Certified organic extraction meeting USDA NOP or EU 2018/848 standards for premium personal care brands.
Mature deployment sits with Synthetic. Newer deployment is concentrated in Natural.
Application:
Customer procurement patterns separate fragrance-grade purity specifications from pharmaceutical intermediate tolerances.
- Fragrance:High-purity grades for fine perfumery and personal care formulations. German and Swiss fragrance houses prioritize carbon-14 verified natural origin for clean-label product lines.
- Flavoring:Food-grade additives subject to FDA 21 CFR 182.60 thresholds in the US and FSSAI standards in India. Natural-extraction documentation determines market access in jurisdictions with enforceable natural-label claims.
- Cosmetic:Skin-care and hair-care formulations where REACH Article 33 disclosure obligations for aldehyde derivatives drive reformulation trends.
- Pharmaceutical:Anti-inflammatory and antimicrobial cinnamaldehyde derivatives advancing through clinical pipelines generate structural demand for batch-consistent high-purity intermediates.
Procurement consolidation is most advanced in Fragrance. Procurement fragmentation persists in Pharmaceutical.
End User:
Supply relationships range from spot-market chemical purchasing to multi-year fragrance house partnerships with embedded technical service.
- Food Industry:Beverage and confectionery manufacturers sourcing flavor additives under FDA and FSSAI compliance frameworks.
- Cosmetic Manufacturers:Personal care brands in Germany and France reformulating to exclude synthetic aldehydes, expanding addressable market for certified-natural grades.
- Pharmaceutical Companies:Drug developers requiring pharmaceutical intermediate documentation for cinnamaldehyde derivative pipelines.
- Chemical Producers:Industrial compounders utilizing synthetic grades where cost efficiency outweighs provenance requirements.
Contract duration extends longest with Cosmetic Manufacturers. Spot purchasing dominates among Chemical Producers.
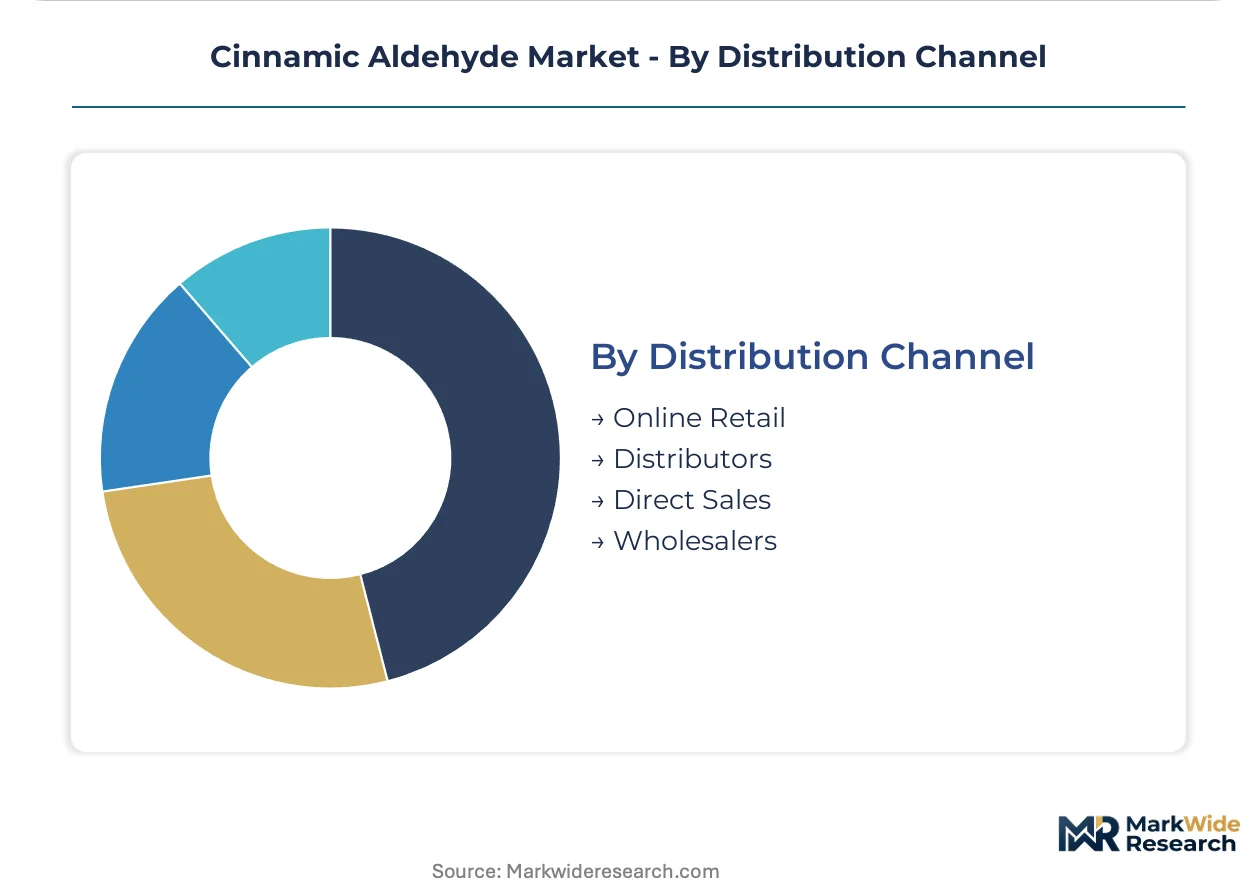
Distribution Channel:
Channel selection correlates with buyer technical sophistication and volume scale, with direct relationships capturing premium formulation support.
- Online Retail:Small-volume specialty chemical sales to independent formulators and research laboratories.
- Distributors:Netherlands and Singapore-based specialty distributors hiring in-house perfumery chemists to capture unbundled technical service value.
- Direct Sales:Long-term supply agreements between fragrance houses and botanical sourcing networks, particularly for Sri Lankan cinnamon bark extraction.
- Wholesalers:Volume commodity movement of synthetic grades for industrial chemical production.
Relationship depth is greatest in Direct Sales. Transactional efficiency peaks in Wholesalers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province anchors global cinnamic aldehyde synthesis capacity, with domestic fine-chemical producers scaling natural-extraction capabilities for export markets in Europe and North America.
China
Fragrance-grade cinnamic aldehyde production concentrates in Shandong and Jiangsu provinces, where chemical producers expand natural-extraction capabilities to serve European clean-label demand. SAMR's evolving food additive standards and dual carbon goals pressure documentation of carbon intensity across synthesis pathways. Qingdao and Nantong host the dominant extraction and fermentation pilot facilities.
United States
Personal care brands in New York and California drive reformulation toward certified-natural grades as FDA 21 CFR 182.60 thresholds constrain synthetic flavor expansion. The EPA monitors benzaldehyde derivative emissions from petrochemical production corridors. New Jersey's fragrance compounding cluster imports high-purity natural grades for premium perfume manufacturing.
Germany
REACH registration dossiers and EU Green Deal chemical sustainability targets compress margins for non-compliant suppliers, favoring producers with verified carbon accounting. ECHA substance evaluation periods delay new extraction solvent approvals by 18-24 months. Holzminden anchors integrated R&D operations for biotechnology-derived fragrance precursors.
Sri Lanka
Seventy percent of true Ceylon cinnamon bark sourcing clusters in southern districts, exposing fragrance houses to climate disruption and political instability. The country's export development board promotes certified organic extraction for premium EU markets. Galle and Matara districts concentrate smallholder bark harvesting and primary distillation operations.
India
FSSAI standard evolution creates first-mover advantage for producers with pre-validated natural-extraction documentation as domestic flavor additive rules tighten. Maharashtra and Gujarat states attract investment in botanical processing infrastructure. Mumbai's specialty distributors capture unbundled technical service value by hiring in-house perfumery chemists.
Cinnamic Aldehyde Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the cinnamic aldehyde value chain. Integrated fragrance houses with captive botanical sourcing networks face competition from specialized chemical manufacturers and biotechnology specialists. Three archetypes dominate: vertically integrated fragrance compounders, commodity chemical producers, and precision fermentation startups. Consolidation pressures favor M&A activity among mid-scale extraction specialists, while capacity expansion concentrates in China's Shandong chemical corridor.
Within the integrated fragrance house tier, Givaudan SA and Symrise AG exemplify archetypes built on captive supply networks and integrated R&D infrastructure. Takasago International Corporation occupies a position representing biotechnology-derived production routes. Among commodity chemical producers, LANXESS and BASF anchor the synthetic-grade volume segment. Emerald Kalama Chemical sits within the specialty intermediate tier serving pharmaceutical derivative pipelines.
| Leading Market Players |
|---|
| Givaudan SA |
| Merck KGaA Sigma-Aldrich |
| LANXESS |
| Solvay S.A. |
| BASF |
| Emerald Kalama Chemical |
| Takasago International Corporation |
| Kao Corporation |
| Symrise AG |
| Others |
Supply Flow & Price Mechanics
Fragrance house procurement consolidation in Germany and Switzerland anchors value-based pricing for certified-natural grades, with EU Regulation 1334/2008 enforcement creating tiered premiums that separate carbon-14 verified extraction from synthetic alternatives.
Pricing Analysis
Carbon-14 verified natural origin anchors value-based pricing for fragrance-grade cinnamic aldehyde, with certification premiums widening between EU-compliant extraction and petrochemical synthesis. Price differentiation hinges on REACH documentation depth and botanical traceability to Sri Lankan source districts. Cost compression in synthetic grades is intensifying because benzaldehyde input volatility transmits directly from petroleum feedstock markets. Chemical producers exhibit highest price sensitivity, while fragrance houses absorb premiums for clean-label positioning.
Supply Chain Analysis
Freight cost differentials between Sri Lankan bark shipments and Shandong synthetic output reshape procurement economics for European fragrance compounders. Supply concentrates in China's Shandong and Jiangsu provinces for synthetic grades, and Sri Lanka's Galle and Matara districts for natural extraction. Raw material dependencies rest on petroleum-derived benzaldehyde, Cinnamomum verum bark harvests, and fermentation feedstocks for biotech routes. Single-source vulnerability clusters in Sri Lankan cinnamon agriculture exposed to climate disruption. Distribution runs through Netherlands-based specialty distributors for EU fragrance houses and direct sales agreements for captive botanical networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH registration dossiers and EU Green Deal chemical sustainability targets erect barrier-to-entry moats favoring producers with pre-validated carbon accounting infrastructure.
For Market Incumbents: Lock in captive Sri Lankan botanical sourcing networks before climate disruption intensifies supply concentration risk. Deepen backward integration into precision fermentation capabilities in Holzminden and Qingdao to reduce dependency on agricultural land constraints. Prioritize GC-MS and carbon-14 dating expertise retention as analytical chemist scarcity threatens natural-origin verification capacity. For New Entrants and Emerging Players: Enter via India's FSSAI standard evolution, where tightening domestic flavor additive rules create first-mover advantage for producers with pre-validated natural-extraction documentation. Target Maharashtra and Gujarat states for botanical processing infrastructure investment. Pursue standalone formulation consulting fees as fragrance houses unbundle technical service from material supply contracts. For Investors and Strategic Acquirers: The window for entry favors precision fermentation startups with yeast-based cinnamic acid-to-aldehyde routes, biotechnology specialists decentralizing production geography away from tropical agriculture. Long-term viability hinges on carbon intensity documentation capabilities across extraction and synthesis pathways. Watch for ECHA substance evaluation period extensions as inflection indicators for competitive launch timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Sourcing | Givaudan SA secures Sri Lankan cinnamon bark through captive networks, insulating supply from climate disruption. |
| Precision Fermentation Scale-Up | Takasago International Corporation pilots yeast-based routes in Holzminden to reduce batch-to-batch variation. |
| REACH Compliance Infrastructure Investment | Symrise AG anchors integrated R&D labs to compress substance evaluation period delays for new extraction solvents. |
| Technical Service Unbundling | Netherlands-based specialty distributors hire in-house perfumery chemists to capture standalone formulation consulting fees. |
| Carbon-14 Verification Capability Buildout | Fragrance houses in Germany and Switzerland invest in analytical expertise as retiring specialists concentrate verification risk. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with fragrance house procurement directors, fine-chemical plant managers in Shandong and Jiangsu, Sri Lankan cinnamon export development officials, and Netherlands-based specialty chemical distributors. Secondary sources included ECHA substance evaluation databases, FDA 21 CFR 182.60 threshold documentation, FSSAI standard evolution notices, and EU Green Deal chemical sustainability target publications. Bottom-up volume estimates from extraction and synthesis capacity triangulated against top-down demand segmentation from fragrance, flavoring, and pharmaceutical end-use applications.
Data-stream reconciliation across production capacity surveys, import-export customs records, and fragrance house procurement disclosures shaped the analytical framework. Segmentation dimensions modeled included natural-synthetic-biotech grade tier, fragrance-flavoring-pharmaceutical end-use industry, and regional production hub concentration in China, Sri Lanka, and Germany. CAGRs derived from trajectory fitting across historical volume trends and projected regulatory enforcement intensity. Industry-specific forecast inputs incorporated REACH registration timeline assumptions and precision fermentation pilot scale-up rates from biotechnology specialists.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Sri Lankan political instability, benzaldehyde price spike scenarios, or ECHA substance evaluation period extensions beyond standard 18-24 month windows. Stakeholders should weight assumptions against their own operating context for compliance cost absorption and supply chain redundancy planning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Encapsulated Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Ferulic Acid Market
Flavor and Fragrance Chemicals
Gel Air Fresheners Market
Flavor and Fragrance Chemicals
Global Bio Vanillin Market
Flavor and Fragrance Chemicals
Spearmint Oil Market
Flavor and Fragrance Chemicals
Ethyl Vanillin Market
Flavor and Fragrance Chemicals
Carnosic Acid Market
Flavor and Fragrance Chemicals
Guaiacwood Essential Oil Market
Flavor and Fragrance Chemicals
North America Aroma Chemicals Market
Flavor and Fragrance Chemicals
Musk Aroma Chemicals Market
Flavor and Fragrance Chemicals
Coumarin Market
Flavor and Fragrance Chemicals
Dihydrocitronellol Market
Flavor and Fragrance Chemicals
Essential Oils Market
Flavor and Fragrance Chemicals
Anisic Aldehyde Market
Flavor and Fragrance Chemicals
Pocket Perfume Market
Flavor and Fragrance Chemicals
Gamma Decalactone Market