
 Cloud Management for the Openstack Market | 2026-2036
Cloud Management for the Openstack Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Management for the Openstack Market Analysis
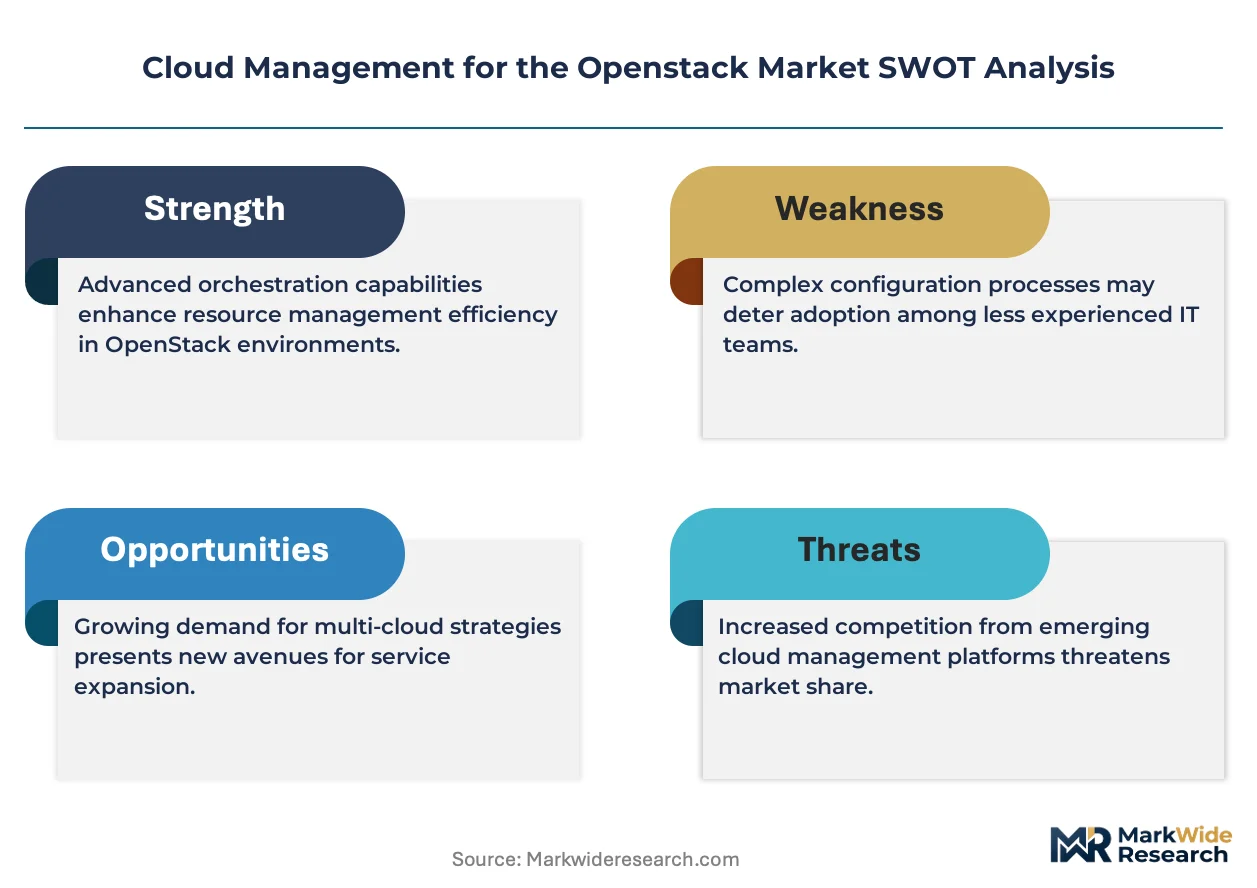
GDPR is restructuring the cost-of-entry calculus for OpenStack cloud management across European enterprises, compelling organizations to prioritize data-sovereign infrastructure over hyperscaler dependency. Red Hat leverages its enterprise Linux heritage to anchor hybrid cloud deployments with integrated OpenStack support. Canonical competes through aggressive upstream stewardship of Ubuntu OpenStack, sustaining a cost-position advantage for budget-conscious operators. VMware differentiates by bridging vSphere-native tooling with OpenStack APIs, extending its virtualization dominance into cloud-native orchestration.
Cloud Management for the OpenStack encompasses software frameworks that provision, monitor, and govern compute, storage, and networking resources across OpenStack-based private and hybrid cloud environments, typically interfacing through REST APIs and Keystone identity services to enforce multi-tenant resource isolation. Its primary commercial purpose centers on enabling organizations to emulate public cloud agility while retaining direct infrastructure control for security, latency, or regulatory reasons. Managed Services within the Service Type dimension leads current revenue contribution as enterprises outsource operational complexity, while Hybrid Cloud deployments across the Deployment Model dimension represent the fastest structural expansion as organizations straddle on-premises and edge capacity. Containerization under the Technology dimension is maturing rapidly as Kubernetes integration becomes table stakes rather than differentiation.
The EU AI Act and Europe's F-Gas Regulation intersect with OpenStack infrastructure decisions, the former mandating traceable compute environments for high-risk AI systems and the latter restricting cooling-intensive data center expansion. Germany's BSI and France's ANSSI publish hardened security profiles that shape procurement specifications for government and critical infrastructure buyers. Stakeholders must monitor whether emerging sovereign cloud certification schemes fragment interoperability standards or create premium tiers around compliance-verified distributions.
Market Dynamics
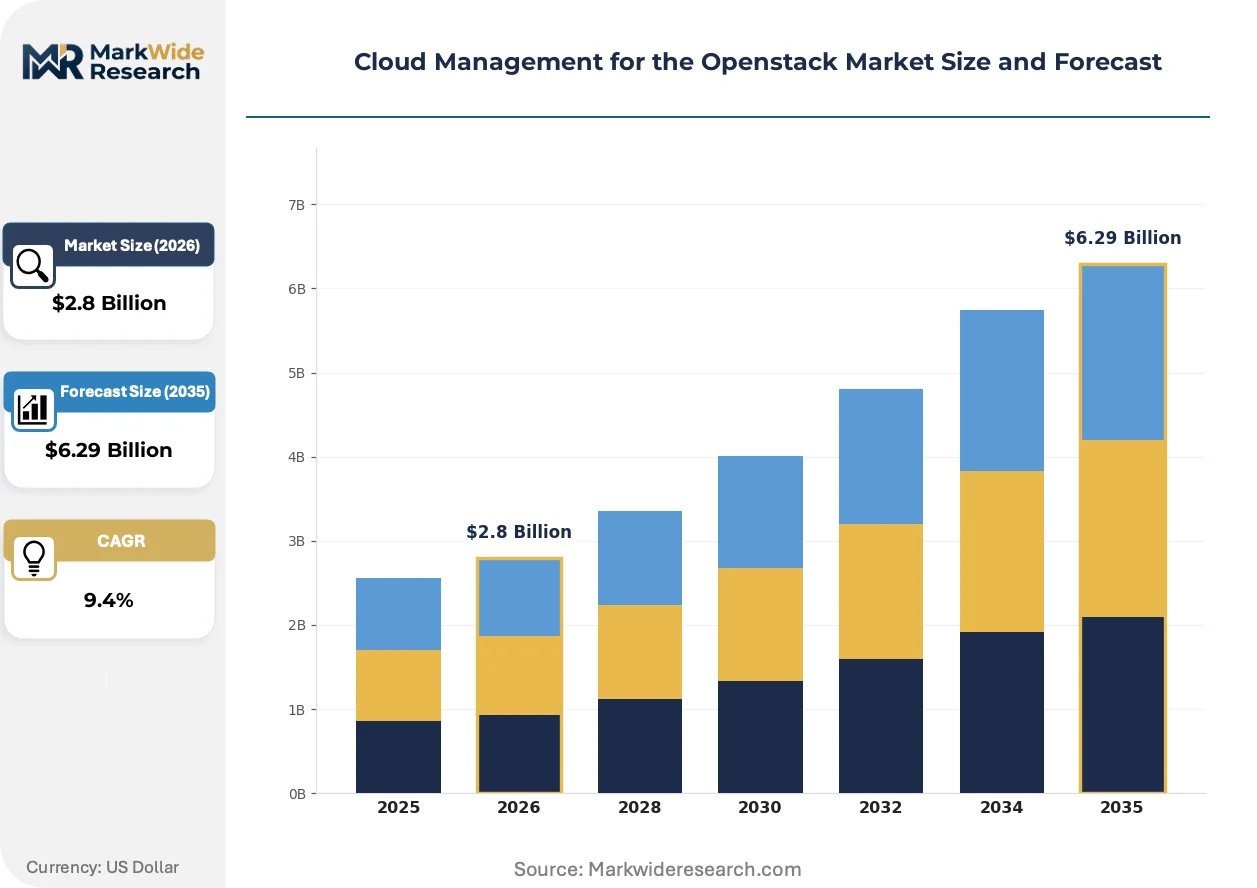
Europe's CSRD and GDPR compliance requirements are restructuring enterprise infrastructure decisions, compelling organizations to abandon hyperscaler dependency in favor of self-managed, auditable OpenStack deployments that retain direct data sovereignty control.
Growth Catalysts
- EU AI Act traceability mandates:High-risk AI systems require documented compute environments, pushing financial services and healthcare toward OpenStack's transparent infrastructure layers.
- Telecommunications network modernization:5G core virtualization and edge computing rollouts favor OpenStack's NFV architecture for latency-sensitive network functions.
- Germany's sovereign cloud preference:Industrial conglomerates in Baden-Württemberg and Bavaria prioritize domestic data residency, driving managed OpenStack procurement.
Market Restraints
- Specialized engineering talent scarcity:OpenStack deployment requires certified cloud architects and Python automation engineers, creating recruitment bottlenecks in secondary markets.
- Legacy VMware estate lock-in:Enterprises with substantial vSphere investments face migration friction and sunk-cost resistance when evaluating OpenStack alternatives.
- Upstream release velocity:Six-month OpenStack release cycles strain operational teams, forcing either costly continuous integration investment or security patch lag.
Strategic Opportunities
- France's ANSSI-certified distributions:Government security profiles create premium procurement channels for hardened OpenStack variants serving defense and critical infrastructure.
- Kubernetes-CNI convergence:Container network interface standardization enables unified overlay networking across OpenStack VMs and Kubernetes pods.
- Edge computing micro-datacenters:Manufacturing facilities and smart city deployments require lightweight OpenStack control planes for distributed resource orchestration.
Industry Challenges
- Multi-release compatibility testing:Operators must validate application performance across divergent OpenStack distributions, extending deployment timelines.
- Keystone identity federation complexity:Integrating corporate Active Directory with OpenStack's authentication service requires specialized LDAP and SAML expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Management for the Openstack Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Managed Services Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: SMBs, Enterprises, Government Agencies, Educational Institutions Technology: Containerization, Virtualization, Orchestration, Automation |
| Companies Covered | Red Hat, Canonical, VMware, IBM, SUSE, Mirantis, Rackspace, Dell Technologies, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Management for the Openstack Market Emerging Trajectories
Container-native infrastructure is absorbing traditional virtualization workloads, while regulatory pressure and procurement model evolution reshape how enterprises acquire and operate cloud management platforms.
Software-defined networking is absorbing hardware-centric network provisioning, collapsing switch configuration into API-driven Neutron orchestration. Telecommunications providers and large financial institutions are adopting this shift fastest, replacing manual CLI-based network operations with infrastructure-as-code pipelines. The technology is absorbing mid-tier network engineering roles, compressing operational headcount while demanding upstream Python and Ansible automation skills.
Europe's F-Gas Regulation restricts hydrofluorocarbon-based cooling systems in new datacenter construction, limiting expansion options for hyperscale facilities. This constraint accelerates investment in liquid-cooled, high-density OpenStack racks designed for edge and metro deployments. German and Dutch operators are responding by retrofitting existing facilities with immersion cooling and direct-to-chip thermal management.
Enterprise procurement teams are consolidating vendor relationships, favoring managed service providers who bundle OpenStack operations with adjacent security and observability functions. Traditional license-plus-support contracts are yielding to consumption-based arrangements indexed to provisioned vCPU-hours. This pattern is most pronounced in DACH region manufacturing, where procurement functions report directly to CFO organizations seeking operational expenditure predictability.
Cloud Management for the Openstack Market Segmentation
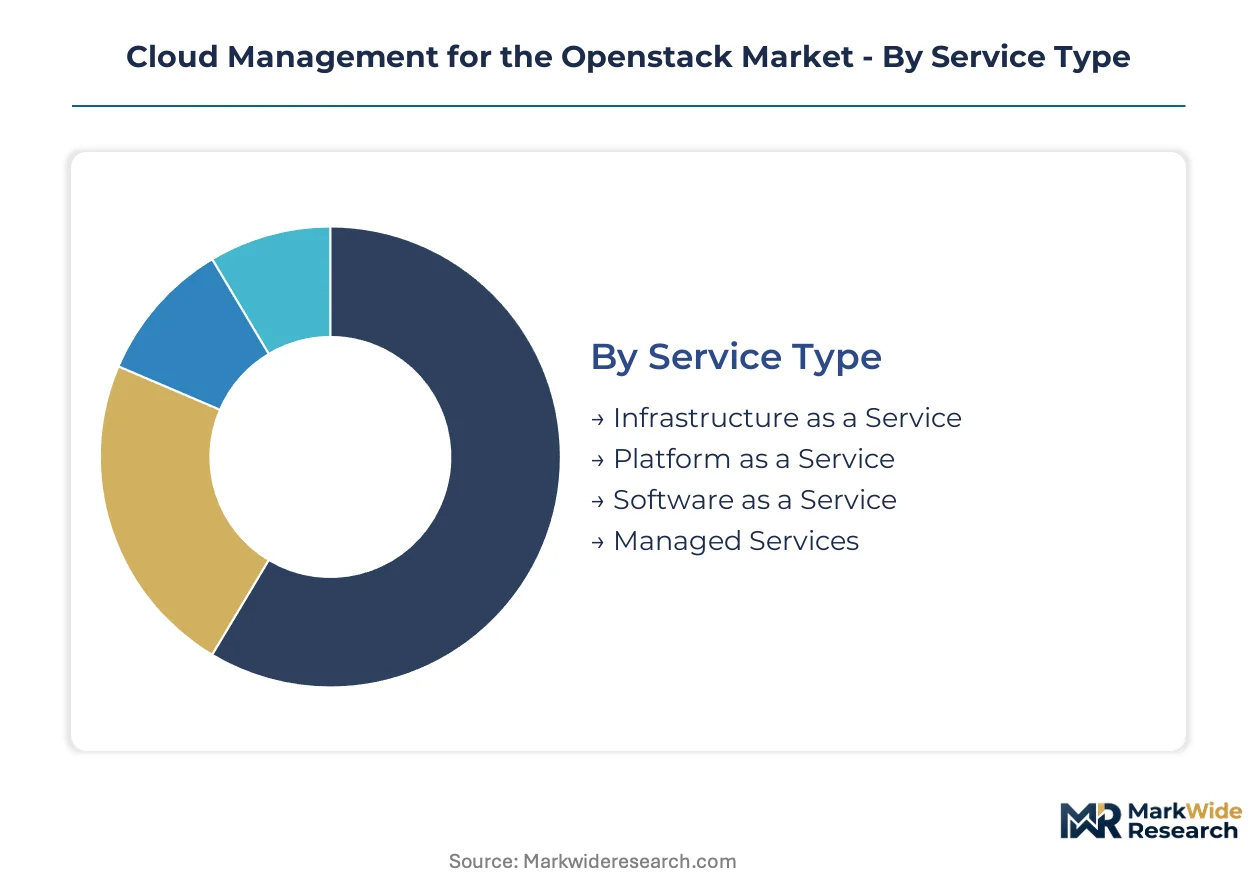
OpenStack cloud management platforms fragment across service delivery modes, infrastructure ownership models, and operational technologies. Procurement patterns diverge sharply between regulated industries demanding sovereign control and digital-native enterprises prioritizing deployment velocity.
Service Type:
Service delivery architecture determines operational responsibility allocation and capital commitment structure.
- Managed Services:Third-party operators assume full lifecycle responsibility for OpenStack control plane maintenance, patch management, and capacity scaling. German industrial conglomerates in Baden-Württemberg favor this model to satisfy BSI compliance requirements without building internal platform engineering teams.
- Infrastructure as a Service:Raw compute, storage, and networking resources provisioned through OpenStack APIs with tenant-managed workload layers. Telecommunications providers modernizing 5G core infrastructure drive IaaS procurement for network function virtualization.
- Platform as a Service:Abstracted application deployment environments with pre-integrated middleware and runtime frameworks.
- Software as a Service:Fully managed application workloads with OpenStack operating as the invisible substrate.
Mature deployment sits with Managed Services. Newer deployment is concentrated in Infrastructure as a Service.
Deployment Model:
Infrastructure ownership topology shapes data residency guarantees and latency performance boundaries.
- Hybrid Cloud:Workload portability across on-premises OpenStack estates and public cloud overflow capacity. Financial services institutions in Frankfurt deploy hybrid architectures to retain transaction data locally while bursting analytics workloads to external capacity.
- Private Cloud:Dedicated OpenStack infrastructure under single-tenant operational control. France's ANSSI-certified government deployments mandate private cloud for defense and critical infrastructure applications.
- Multi-Cloud:Orchestration across heterogeneous cloud platforms with OpenStack as one node in a broader topology.
- Public Cloud:Shared OpenStack infrastructure operated by commercial providers with standardized service catalogs.
Established procurement concentrates in Private Cloud. Expanding most quickly is Hybrid Cloud.
End User:
Organizational scale and regulatory exposure drive divergent platform requirements and support sophistication.
- Enterprises:Large organizations with dedicated platform engineering functions and complex multi-tenant governance requirements. European automotive manufacturers deploy OpenStack for sovereign product development environments insulated from foreign jurisdiction exposure.
- Government Agencies:Public sector entities with mandatory security certification and audit trail obligations.
- SMBs:Small and medium businesses with constrained technical staffing and preference for outsourced operational models.
- Educational Institutions:Universities and research organizations with episodic compute demand and grant-funded procurement cycles.
Revenue concentration rests with Enterprises. Government Agencies are gaining share fastest.
Technology:
Underlying infrastructure abstraction mechanisms determine workload portability and resource efficiency boundaries.
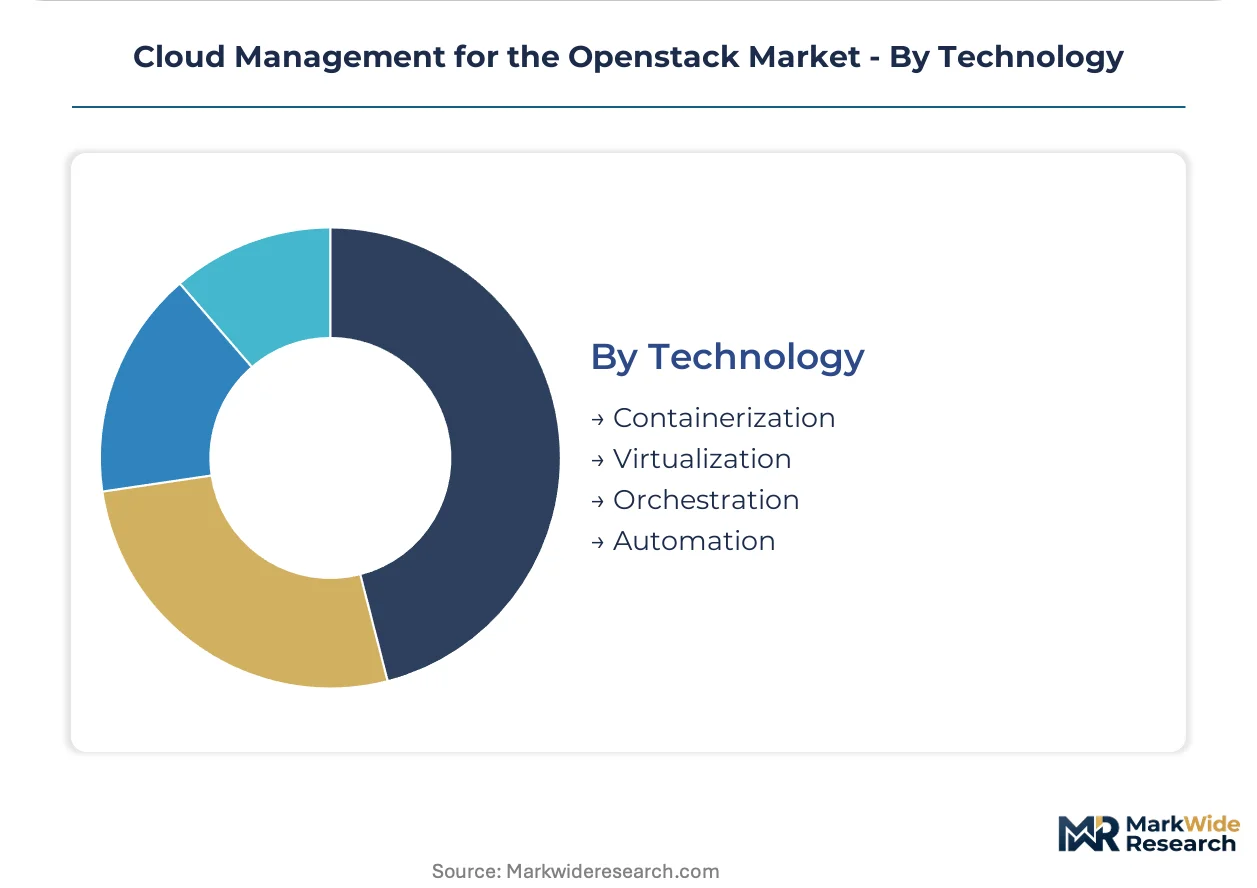
- Containerization:Kubernetes integration with OpenStack through Kuryr-CNI and Magnum services enabling unified VM and pod orchestration. Dutch cloud operators deploy containerized OpenStack control planes for edge micro-datacenter density.
- Virtualization:Kernel-based VM isolation through KVM with Nova compute scheduling. Legacy enterprise workloads continue relying on virtualization for Windows Server and traditional relational database deployments.
- Orchestration:Multi-resource automation through Heat templates and Terraform providers.
- Automation:Infrastructure-as-code pipelines with Ansible and Puppet configuration management.
Production stability sits with Virtualization. Steepest expansion trajectory belongs to Containerization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Gaia-X initiative and France's national cloud sovereignty program are concentrating OpenStack investment in Western European industrial corridors, while telecommunications modernization drives parallel demand across North American and Asian-Pacific metropolitan zones.
Germany
Industrial conglomerates in Baden-Württemberg and Bavaria demand sovereign cloud infrastructure for automotive and machinery digitalization. The BSI publishes hardened security profiles that shape procurement specifications for government and critical infrastructure buyers. Stuttgart's manufacturing cluster anchors managed OpenStack deployments serving Mercedes-Benz and Bosch supply chains.
France
Defense contractors and financial institutions require traceable compute environments for high-risk AI systems under EU AI Act mandates. ANSSI-certified security profiles create premium procurement channels for hardened OpenStack variants. The Île-de-France region concentrates procurement from Thales, BNP Paribas, and public sector entities seeking domestic data residency.
United States
Telecommunications providers modernizing 5G core virtualization favor OpenStack's NFV architecture for latency-sensitive network functions. FCC infrastructure policies and NIST cybersecurity frameworks influence procurement specifications. Dallas-Fort Worth and Northern Virginia data center corridors host edge computing micro-datacenter deployments for distributed resource orchestration.
United Kingdom
Financial services institutions in the City of London deploy hybrid architectures to retain transaction data locally while bursting analytics workloads. Post-Brexit data sovereignty concerns accelerate self-managed infrastructure decisions independent of EU hyperscaler frameworks. Canary Wharf banking clusters drive managed service provider consolidation.
Netherlands
Dutch cloud operators deploy containerized OpenStack control planes for edge micro-datacenter density serving smart port and logistics applications. F-Gas Regulation restrictions on cooling-intensive data center expansion accelerate liquid-cooled, high-density rack investment. The Amsterdam metropolitan zone anchors retrofit programs with immersion cooling and direct-to-chip thermal management.
Cloud Management for the Openstack Market Vendor Landscape
North American enterprise software vendors anchor one tier; European open-source specialists hold differentiated positions in sovereign cloud segments. Market structure consolidates around three strategic archetypes: distribution-backed platform vendors, pure-play managed service operators, and hardware-integrated systems providers. Dominant competitive moves include strategic partnerships with telecommunications carriers and geographic expansion through compliance-certified distribution channels.
Within the distribution-backed tier, Red Hat and Canonical exemplify contrasting commercialization approaches for enterprise Linux heritage and upstream stewardship respectively. VMware occupies a position bridging virtualization dominance with cloud-native orchestration. SUSE represents the European specialist archetype with concentrated presence in DACH-region manufacturing procurement.
| Leading Market Players |
|---|
| Red Hat |
| Canonical |
| VMware |
| IBM |
| SUSE |
| Mirantis |
| Rackspace |
| Dell Technologies |
| Hewlett Packard Enterprise |
| Others |
Supply Flow & Price Mechanics
Germany's BSI-certified procurement mandates are forcing hardened OpenStack distributions into premium pricing tiers, compelling supply chains to absorb certification costs while tier-one vendors capture margin expansion through compliance bundling.
Pricing Analysis
Lead-time compression commands premium pricing for ANSSI-certified deployments with sub-90-day delivery windows, while spot inventory of standard Ubuntu OpenStack distributions trades at discounted rates. Subscription-based SaaS pricing dominates, with differentiation anchored in certification grade and geographic support proximity. Cost compression in mid-tier managed services is intensifying because telecommunications carriers are consolidating vendor panels. SMBs exhibit acute price sensitivity, whereas defense contractors accept substantial premiums for sovereign-cloud guarantees.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Paris, and Amsterdam anchor hub-and-spoke fulfillment for certified OpenStack hardware stacks. Supply concentrates in Germany, the Netherlands, and the United States for high-density server chassis and liquid-cooled rack systems. Component sourcing draws from Taiwan for specialized NICs, Ireland for firmware development, and South Korea for memory modules. Single-source vulnerability around BSI-validated security modules creates procurement bottlenecks. Distribution runs through systems integrators with direct-to-datacenter logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OpenStack cloud management is consolidating around compliance-certified platforms, with upstream release velocity and talent scarcity forcing sub-scale operators toward acquisition or exit.
For Market Incumbents: Extend platform engineering investments into Kubernetes-CNI convergence to neutralize container-native substitution threats. Deepen upstream control over Magnum and Kuryr projects to shape API standards before emerging rivals gain traction. Anchor capacity expansion in Stuttgart and Île-de-France industrial corridors where BSI and ANSSI procurement specifications create captive demand. For New Entrants and Emerging Players: Edge-native micro-datacenter orchestration offers the most penetrable white-space, with manufacturing facilities in Baden-Württemberg demanding lightweight control planes for distributed deployments. Target smart port and logistics applications in Rotterdam-Amsterdam corridor where F-Gas cooling restrictions favor liquid-cooled, high-density racks. Lead with consumption-based vCPU-hour pricing to bypass incumbent subscription lock-in. For Investors and Strategic Acquirers: Re-rating potential sits with ANSSI-certified distribution specialists given EU AI Act traceability mandates expanding addressable market into high-risk AI infrastructure. Long-term viability favors operators with hardened security profiles and telecommunications carrier channel control. Watch ANSSI certification backlog duration as inflection indicator for sovereign-cloud demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified VM and Kubernetes orchestration through Magnum services captures telecommunications modernization budgets. |
| Geographic Expansion | BSI-certified distribution channels in Stuttgart industrial cluster anchor sovereign-cloud procurement pipelines. |
| Strategic Partnership | Telecommunications carrier alliances for 5G core virtualization secure multi-year NFV deployment contracts. |
| Acquisition of Specialist Firm | Edge micro-datacenter operators in Netherlands smart port corridor add liquid-cooled deployment expertise. |
| Product Launch | ANSSI-hardened control planes open premium procurement channels for French defense and critical infrastructure. |
Methodological Framework
SEC filings, telecommunications carrier capex disclosures, and EU regulatory databases formed the secondary backbone, supplemented by primary interviews with OpenStack platform engineers, cloud procurement officers at industrial conglomerates, and managed service provider operations directors. Bottom-up triangulation against top-down macroeconomic indicators validated segment-level demand estimates.
Historical trendline analysis across deployment model and service type dimensions established baseline growth patterns, with CAGR derivation incorporating technology substitution curves and regulatory compliance cost trajectories. Segmentation modeling spanned service delivery architecture, infrastructure ownership topology, organization scale, and underlying abstraction mechanism. Forecast inputs included telecommunications NFV rollout schedules and sovereign-cloud certification pipeline data.
Forecast precision tightens around the base case; tail outcomes carry wider variance under F-Gas Regulation enforcement intensity and Keystone identity federation complexity delays. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Latin America Cloud Computing Market
Cloud Computing
Cloud CDN Market
Cloud Computing
Cloud Orchestration Market
Cloud Computing
Cloud Backup Market
Cloud Computing
Cloud-Based Repository Services Market
Cloud Computing
UAE Cloud Computing Market
Cloud Computing
South Korea Cloud Computing Market
Cloud Computing
Global Cloud Management Software Market
Cloud Computing
Global Cloud Computing Iaas in Life Science Market
Cloud Computing
Middle East and Africa Cloud Infrastructure Services Market
Cloud Computing
Cloud Infrastructure-As-A-Service Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
GPU Virtualization Market
Cloud Computing
Germany Cloud Computing Market
Cloud Computing
Cloud Directory Services Market
Cloud Computing
Cloud Management Market