
 Asia-Pacific Botanical Extract Market | 2026-2036
Asia-Pacific Botanical Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Botanical Extract Market Outlook
Subscription-based botanical ingredient sourcing is shifting procurement from spot-market purchasing toward multi-year supply agreements with guaranteed terpene profiles. Synthite Industries anchors India's spice-derived extract capacity through backward integration into Kerala's clove and pepper estates. Givaudan SA leverages Swiss R&D protocols to compete on standardized phytochemical consistency for cosmetic clients. Martin Bauer Group dominates European-origin botanical supply chains that feed into Asia-Pacific nutraceutical contract manufacturers.
Botanical extracts comprise concentrated bioactive compounds derived from plant matrices through solvent extraction, supercritical CO2 processing, or steam distillation, yielding specified marker compound levels for industrial formulation. These extracts serve as functional inputs where precise phytochemical activity replaces raw botanical material in dosage-controlled products. Essential oils command premium positioning in cosmetics applications where fragrance houses demand batch-to-batch chromatographic consistency. Herbal extracts sustain volume leadership across pharmaceutical and nutraceutical channels where Ayurvedic and Traditional Chinese Medicine protocols require documented active compound ranges. Standardized extracts capture expanding share in dietary supplements as regulators tighten label-claim verification requirements.
FSSAI in India enforces progressive botanical contaminant limits that elevate testing costs for imported raw materials while privileging domestic GMP-certified processors. China's NMPA aligns traditional medicine extract monographs with pharmacopeial standards that restrict market access to facilities meeting GB-specified heavy metal thresholds. Australia's TGA equivalency agreements with several ASEAN regulators streamline export pathways for certified Australian botanical suppliers. Stakeholders must monitor divergence between harmonized ASEAN traditional medicine standards and country-specific purity mandates that fragment compliance architectures.
Market Dynamics
Subscription-based sourcing agreements are displacing spot-market purchasing across Asia-Pacific botanical supply chains, locking processors into multi-year contracts with guaranteed terpene profiles and chromatographic consistency requirements.
Growth Catalysts
- India's FSSAI purity mandates:Tightening contaminant limits for imported botanical raw materials are accelerating domestic GMP-certified processing capacity expansion in Kerala and Karnataka.
- Functional beverage manufacturing:Southeast Asian drink formulators are integrating standardized herbal extracts into ready-to-drink wellness products at industrial scale.
- Supercritical CO2 extraction:This solvent-free processing technology is capturing share from ethanol-based methods in premium cosmetic oil production across China's Guangdong corridor.
Market Restraints
- Raw material cost volatility:Climate-induced yield fluctuations in Indonesian clove and Vietnamese star anise estates are compressing processor margins.
- Supply concentration risk:European-origin botanical feedstock dependence leaves Asia-Pacific formulators exposed to euro-denominated input price swings.
- Heavy metal compliance thresholds:China's NMPA GB-specified limits for lead and cadmium in traditional medicine extracts are disqualifying small-scale harvesters from qualified supplier lists.
Strategic Opportunities
- Vietnamese highlands cultivation:Underdeveloped agro-climatic zones in Lam Dong and Dak Lak provinces offer expansion terrain for certified organic botanical estates.
- Cosmetic microbiome applications:Polyphenol-rich extracts from Camellia sinensis and Centella asiatica are penetrating prestige skincare formulations targeting barrier function claims.
- Australia-ASEAN TGA equivalency:Streamlined export pathways for Australian-certified suppliers are opening procurement diversification channels for Thai and Malaysian nutraceutical contract manufacturers.
Industry Challenges
- Phytochemical standardization expertise gap:Shortages of analytical chemists proficient in HPLC marker compound verification are extending batch release timelines at mid-tier processors.
- Multi-jurisdiction certification complexity:Divergent ASEAN traditional medicine standards versus country-specific FSSAI and NMPA purity mandates are fragmenting compliance architectures and elevating testing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Botanical Extract Market |
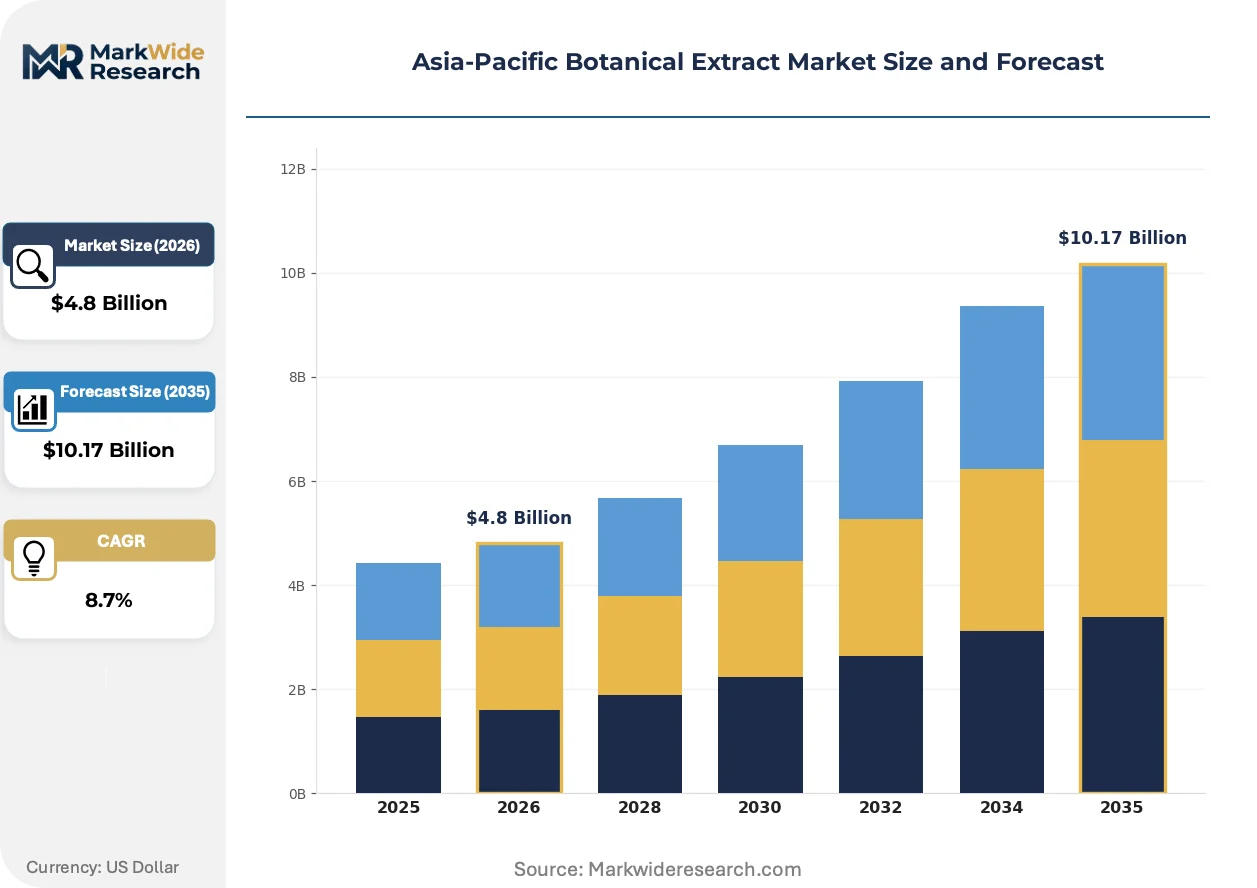
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extracts, Essential Oils, Standardized Extracts, Phytochemicals End User: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Application: Skin Care, Dietary Supplements, Flavoring, Medicinal Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Synthite Industries, Döhler GmbH, Givaudan SA, Martin Bauer Group, Kalsec Inc., Symrise AG, Sensient Technologies, Indena S.p.A., International Flavors & Fragrances, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Botanical Extract Market Strategic Shifts
Digital traceability infrastructure and green extraction chemistry are converging to reshape how botanical provenance is verified and how bioactive compounds are isolated at commercial scale.
Supercritical CO2 extraction with integrated online terpene profiling is unifying quality control with processing operations in real-time. Cosmetic fragrance houses operating from Shanghai and Singapore are adopting these closed-loop systems to compress batch-to-batch variation. The technology is unifying previously separate extraction and analytical validation steps into continuous manufacturing workflows.
FSSAI's progressive tightening of pesticide residue and heavy metal limits for botanical imports is elevating testing costs while privileging domestic GMP-certified processors. India's herbal medicine and nutraceutical formulators are responding by consolidating supplier bases around Kerala and Madhya Pradesh estates with documented cultivation histories. The regulatory pressure is compressing import dependence for critical Ayurvedic inputs.
Long-term supply agreements with guaranteed phytochemical specifications are displacing spot-market purchasing among functional beverage manufacturers. Southeast Asian drink brands are locking in three-to-five-year contracts with Kerala-based spice extract processors to secure clove and black pepper oil supply. This contracting shift is most visible in Thailand and Vietnam where ready-to-drink herbal wellness categories are expanding manufacturing capacity.
Asia-Pacific Botanical Extract Market Segmentation
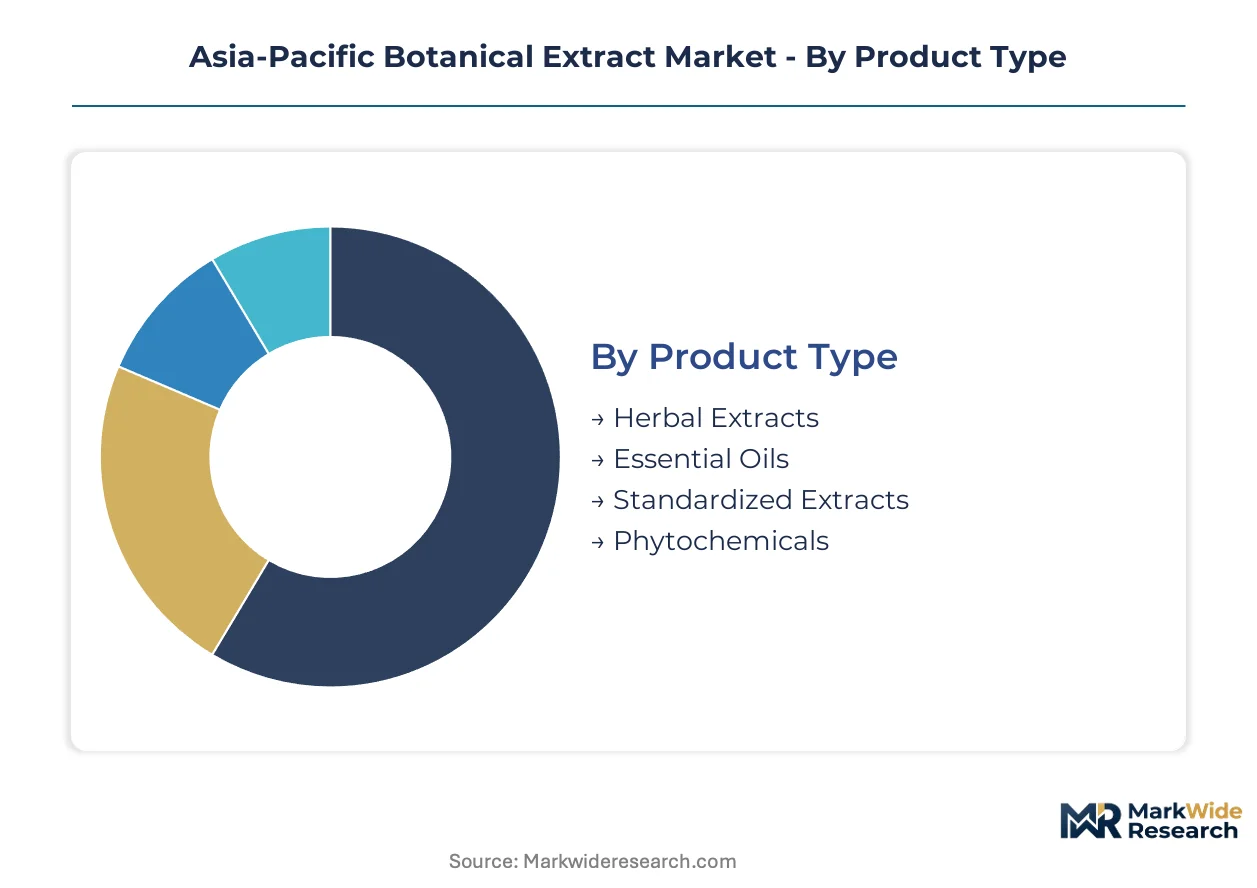
Segmentation in Asia-Pacific botanical extracts reveals how extraction chemistry, end-use specifications, and channel economics partition value capture across the supply chain. Each dimension carries distinct regulatory footprints and margin structures that shape supplier positioning.
Product Type:
Standalone extracts command premium positioning where formulation control demands precise phytochemical activity, while embedded botanical inputs serve commodity-scale manufacturing with looser specification windows.
- Herbal Extracts:Complex matrices of water-soluble and alcohol-soluble compounds derived from traditional medicinal plants, typically specified by botanical origin rather than single-marker quantification. India's Ayurvedic manufacturing belts in Kerala and Karnataka concentrate procurement here, driven by FSSAI's progressive tightening of contaminant documentation requirements for import substitution.
- Essential Oils:Volatile terpene fractions recovered through steam distillation or cold-pressing, defined by gas chromatography fingerprinting for fragrance and antimicrobial applications. Cosmetic formulators across China's Guangdong corridor and Thailand's Bangkok industrial zones drive specification intensity, with batch-to-batch chromatographic consistency now a contractual baseline.
- Standardized Extracts:Concentrated preparations with guaranteed minimum levels of specified marker compounds, typically 5-95% purity ranges. China's NMPA pharmacopeial alignment for traditional medicine extracts elevates demand for documented active compound ranges in pharmaceutical channels.
- Phytochemicals:Isolated single-compound fractions such as alkaloids, flavonoids, or saponins produced through sequential solvent partitioning and chromatographic purification. Nutraceutical contract manufacturers in Vietnam and Indonesia are expanding procurement of these high-purity inputs for dietary supplement label-claim verification.
Herbal extracts lead volumes today; standardized extracts are gaining share fastest.
End User:
Cost tier stratification separates premium-positioned channels with specification intensity from volume-driven segments where price-per-kilogram dominates supplier selection.
- Food & Beverage:Flavoring and coloring applications utilizing oleoresins, vanilla extracts, and natural colorants with sensory performance specifications. Southeast Asian functional beverage manufacturers represent the steepest expansion trajectory, locking processors into multi-year supply agreements with guaranteed terpene profiles.
- Pharmaceuticals:Active pharmaceutical ingredients and excipients meeting pharmacopeial monographs for heavy metals, microbial limits, and residual solvents. China's NMPA GB-specified thresholds for lead and cadmium are disqualifying small-scale harvesters from qualified supplier lists.
- Cosmetics:Fragrance, preservation, and bioactive functional claims in prestige and mass skincare formulations. Australian TGA-certified suppliers leverage equivalency agreements with ASEAN regulators to penetrate Thai and Malaysian procurement channels.
- Nutraceuticals:Dietary supplement inputs with structure-function label claims requiring documented bioactive ranges. India's domestic GMP-certified processors are capturing share from European-origin feedstock as FSSAI elevates import testing costs.
Pharmaceuticals capture the highest unit margins; nutraceuticals are expanding most quickly.
Application:
Application maturity separates established therapeutic categories with codified monographs from emerging functional claims still navigating regulatory substantiation pathways.
- Skin Care:Barrier function, antioxidant, and anti-inflammatory claims utilizing polyphenol-rich extracts from Camellia sinensis and Centella asiatica. Prestige formulators in Shanghai and Singapore drive demand for microbiome-targeted botanical actives.
- Dietary Supplements:Capsule, tablet, and powder formats with standardized extract dosing for immune, cognitive, and metabolic health positioning. Label-claim verification requirements are compressing supplier bases toward chromatography-capable processors.
- Flavoring:Natural taste and aroma modulation in processed foods and ready-to-drink beverages. Clove and black pepper oil from Kerala estates anchor supply for Thai and Vietnamese drink manufacturers.
- Medicinal:Traditional medicine protocols including Ayurvedic and Traditional Chinese Medicine formulations with documented active compound ranges. China's herbal medicine corridors and India's manufacturing belts concentrate demand.
Medicinal applications anchor volume; skin care is climbing the fastest.
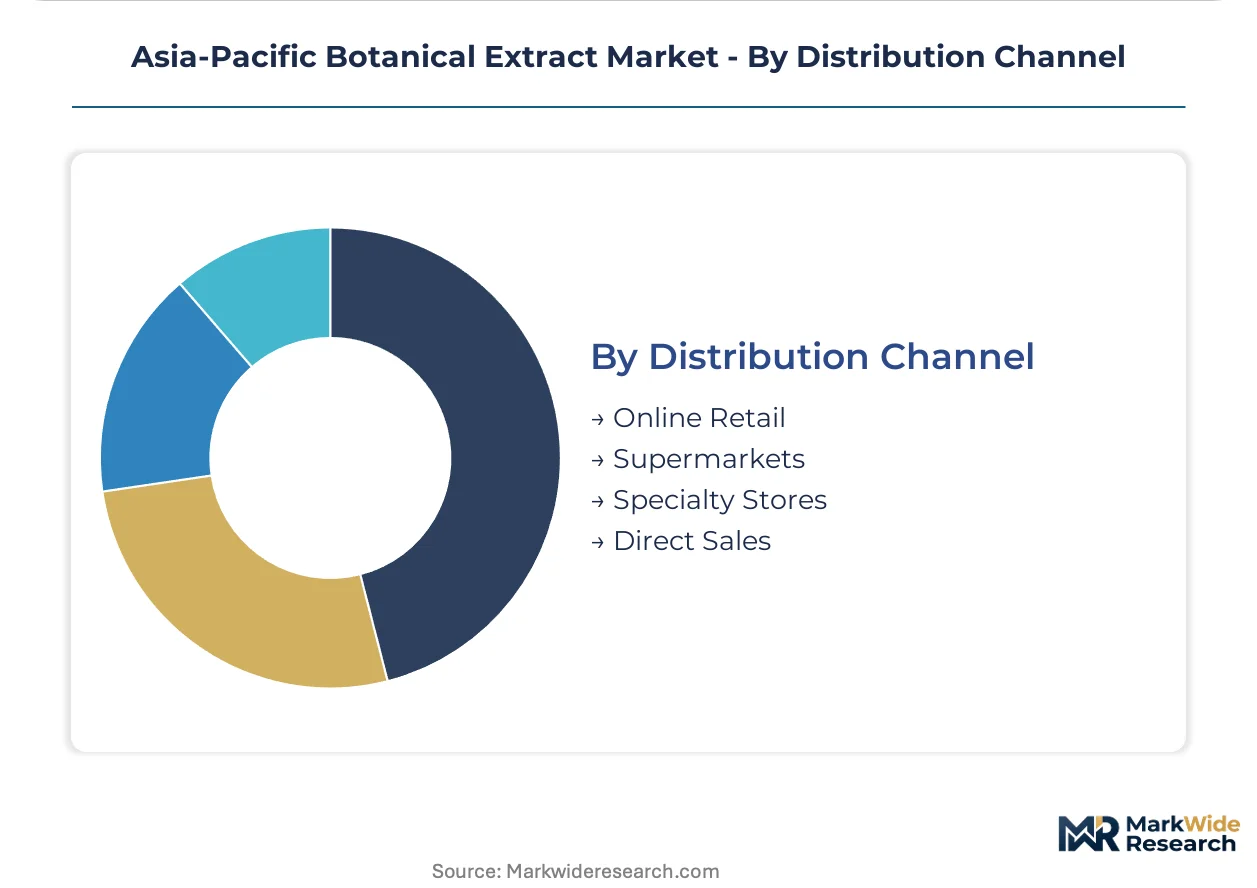
Distribution Channel:
Channel concentration reflects customer scale and specification complexity, with direct relationships dominating industrial procurement and intermediaries serving fragmented small-batch buyers.
- Online Retail:E-commerce platforms serving small-scale formulators, artisanal producers, and research institutions with gram-to-kilogram quantities. Digital traceability infrastructure is emerging as a competitive differentiator for provenance verification.
- Supermarkets:Mass-market consumer-facing botanical products including essential oil kits and herbal supplement ranges. Shelf-space economics favor established brands with compliance documentation.
- Specialty Stores:Professional-grade extracts targeting cosmetic chemists, aromatherapists, and traditional medicine practitioners. Technical specification support and batch certificates of analysis drive loyalty.
- Direct Sales:Long-term supply agreements between extract processors and industrial formulators with guaranteed phytochemical specifications and volume commitments. Subscription-based sourcing is displacing spot-market purchasing across Southeast Asian functional beverage supply chains.
Direct sales dominates industrial volumes; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production maps as processors migrate toward jurisdictions with lower compliance costs or stronger domestic certification privileges. FSSAI's escalating import testing burdens and China's NMPA GB-standard enforcement are accelerating capacity shifts within the region.
China
Traditional medicine extract demand concentrates in Guangdong's cosmetic manufacturing corridor and Sichuan's herbal processing zones. NMPA's pharmacopeial alignment for heavy metal thresholds is disqualifying small-scale harvesters from qualified supplier lists. Guangzhou fragrance houses now mandate batch-to-batch chromatographic consistency for essential oil procurement.
India
Ayurvedic manufacturing belts in Kerala and Karnataka are absorbing import-substitution investment as FSSAI tightens pesticide residue limits for foreign botanicals. The regulator's progressive contaminant documentation requirements privilege domestic GMP-certified processors. Synthite Industries anchors clove and pepper oil capacity through backward integration into Kerala estates.
Vietnam
Functional beverage manufacturers in Ho Chi Minh City and Hanoi are locking processors into multi-year supply agreements with guaranteed terpene profiles. The underdeveloped agro-climatic zones of Lam Dong and Dak Lak provinces offer expansion terrain for certified organic botanical estates. Thai and Vietnamese drink brands source clove and black pepper oils from Indian processors.
Thailand
Ready-to-drink herbal wellness categories are expanding manufacturing capacity around Bangkok industrial zones. Australia's TGA equivalency agreements with ASEAN regulators streamline export pathways for certified Australian botanical suppliers. Thai nutraceutical contract manufacturers leverage these channels to diversify procurement beyond European-origin feedstock.
Australia
TGA-certified extract processors are penetrating Thai and Malaysian procurement channels through streamlined ASEAN export pathways. The country's botanical suppliers compete on documented cultivation histories and heavy metal compliance. Melbourne and Sydney processing facilities serve as quality benchmarks for regional contract manufacturers.
Asia-Pacific Botanical Extract Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with fragrance houses and nutraceutical formulators demanding divergent specification intensities. The vendor base clusters around three archetypes: integrated spice estate operators, Swiss-German precision processors, and European-origin supply chain intermediaries. Competitive moves concentrate on backward integration into cultivation assets and multi-year contracting with guaranteed phytochemical specifications.
Within the integrated estate tier, Synthite Industries represents Kerala-based backward integration into clove and pepper cultivation. Among Swiss-German precision processors, Givaudan SA and Symrise AG exemplify standardized phytochemical consistency for cosmetic applications. Martin Bauer Group anchors European-origin botanical supply chains feeding Asia-Pacific nutraceutical contract manufacturers. These three archetypes occupy distinct competitive positions based on control over cultivation assets versus R&D-intensive standardization capabilities.
| Leading Market Players |
|---|
| Synthite Industries |
| Döhler GmbH |
| Givaudan SA |
| Martin Bauer Group |
| Kalsec Inc. |
| Symrise AG |
| Sensient Technologies |
| Indena S.p.A. |
| International Flavors & Fragrances |
| Others |
Value Chain & Pricing Dynamics
Indonesian clove and Vietnamese star anise spot-price volatility cascades through Asia-Pacific botanical extract supply chains, compressing processor margins at the mid-tier while concentrating pricing power among backward-integrated Kerala estate operators with captive raw material supply.
Pricing Analysis
Distributor margins of 15-25% separate premium cosmetic-grade essential oils from commodity nutraceutical inputs. Three-tier pricing structure across premium, standard, and economy levels reflects chromatographic certification intensity, with FSSAI-compliant GMP-certified processors commanding 30-40% premiums over uncertified competitors. Price differentiation hinges on terpene-profile consistency and heavy metal documentation. Cost compression in standard-grade herbal extracts is intensifying because climate-induced yield fluctuations in Indonesian estates are feeding raw material price spikes. Functional beverage manufacturers exhibit lowest price sensitivity due to multi-year contract lock-ins, while small-scale Ayurvedic formulators in Madhya Pradesh face acute margin pressure.
Supply Chain Analysis
Certification gating through FSSAI, NMPA, and TGA standards fragments supplier qualification across the region. Geographic concentration centers on India's Kerala and Karnataka processing belts, China's Guangdong cosmetic corridor, and Vietnam's emerging Lam Dong cultivation zones. Raw material supply draws from Indonesian clove estates, Vietnamese star anise harvests, and Kerala pepper plantations. Single-source vulnerability in European-origin botanical feedstock exposes Asia-Pacific formulators to euro-denominated input price swings. Distribution runs through direct long-term supply agreements for industrial volumes, with specialty stores and online retail serving fragmented small-batch buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate among processors with captive cultivation assets and chromatography-capable standardization infrastructure, as regulatory documentation requirements elevate cost-to-serve for import-dependent competitors.
For Market Incumbents: Lock in multi-year supply agreements with Southeast Asian functional beverage manufacturers before Australian TGA-certified suppliers penetrate Thai and Vietnamese procurement channels. Deepen backward integration into certified organic estates in Lam Dong and Dak Lak provinces to secure terpene-profile consistency. Invest in supercritical CO2 extraction capacity with integrated online profiling to compress batch-to-batch variation for Guangzhou fragrance houses.
For New Entrants and Emerging Players: Begin with white-space targeting of microbiome-focused cosmetic applications in Shanghai and Singapore, where polyphenol-rich Camellia sinensis and Centella asiatica extracts command specification premiums. Vietnamese highlands cultivation offers lowest competitive density for certified organic estate development. A go-to-market angle anchored to Australia's TGA-ASEAN equivalency pathways streamlines regulatory access for Thai and Malaysian nutraceutical contract manufacturers.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier Indian processors holding FSSAI GMP certification and documented Kerala cultivation histories, positioned to capture import-substitution share as contaminant documentation requirements tighten. Long-term viability rests on regulatory compliance infrastructure rather than commodity scale. The signal to watch is divergence between harmonized ASEAN traditional medicine standards and country-specific purity mandates that fragment compliance architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Assets | Kerala estate control secures terpene-profile consistency for clove and pepper oil supply. |
| Supercritical CO2 Extraction Scale-Up | Guangdong cosmetic manufacturers demand solvent-free processing with real-time chromatographic validation. |
| Multi-Year Supply Agreement Lock-In | Thai and Vietnamese functional beverage brands seek guaranteed phytochemical specifications. |
| FSSAI GMP Certification Investment | Domestic processors capture share from European-origin feedstock as import testing costs rise. |
| Australia-ASEAN Equivalency Leverage | TGA-certified suppliers penetrate Thai and Malaysian procurement channels through streamlined export pathways. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with extract processors in Kerala and Karnataka, procurement managers at Thai functional beverage manufacturers, regulatory affairs specialists navigating FSSAI and NMPA compliance, and cosmetic formulators in Guangdong with secondary validation. Secondary sources included FSSAI contaminant limit notifications, NMPA pharmacopeial monographs, Australian TGA equivalency agreements with ASEAN regulators, and customs trade data for clove, pepper, and star anise imports. Bottom-up volume modeling and top-down value reconciliation triangulated segment estimates.
Segment-weighting across product type, end user, application, and distribution channel dimensions shaped the analytical framework over the projection horizon. Herbal extracts, essential oils, standardized extracts, and phytochemicals carried distinct margin assumptions. Food and beverage, pharmaceutical, cosmetic, and nutraceutical end-use specifications drove price-tier differentiation. CAGRs derived from historical trajectory analysis and regulatory catalyst mapping, with supercritical CO2 adoption curves and FSSAI compliance cost escalation as industry-specific forecast inputs.
Caveats apply where NMPA heavy metal threshold enforcement or FSSAI pesticide residue limit tightening could materially shift the outlook for small-scale harvester qualification. Forecasts reflect assumptions around climate-induced yield stability in Indonesian and Vietnamese estates. A model refresh is warranted upon material change in ASEAN traditional medicine harmonization progress or Australian TGA equivalency agreement expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Nigella Sativa Extract Market
Extracts
Natural Rosemarine Extract Market
Extracts
Potassium Hydrogen Tartrate Market
Extracts
Plum Extract Market
Extracts
Antioxidants Reagent Market
Extracts
Aloe Vera Derivatives Market
Extracts
Gelatin Hydrolysates Market
Extracts
Global Marigold Flower Extract Market
Extracts
Salvia Miltiorrhiza Extract Market
Extracts
Saffron Extract Market
Extracts
Irish Moss Market
Extracts
Sage Extract Market
Extracts
Basil Extracts Market
Extracts
India Retail Mineral Turpentine Oil Market
Extracts
Polygonum Cuspidatum Extract Market
Extracts
Hesperidin Market