
 Hesperidin Market | 2026-2036
Hesperidin Market Size, Share, and Industry Trends Forecast 2026-2036
Hesperidin Market Intelligence
Compliance with United States Pharmacopeia (USP) and European Pharmacopoeia (EP) monographs for purity and assay is bifurcating the supplier landscape into distinct tiers. Major pharmaceutical firms like Lupin leverage extensive regulatory expertise to compete in high-purity grades for prescription drugs. Zhejiang Conler Pharmaceutical specializes in large-scale extraction, anchoring the supply of standardized powders for the global supplement industry. Benepure Corporation differentiates through its development of micronized and complexed forms with enhanced bioavailability.
Hesperidin is a flavanone glycoside predominantly extracted from the peels and pith of unripe citrus fruits, particularly from the species Citrus aurantium. Its poor water solubility is a key technical challenge, often addressed through micronization to reduce particle size and improve bioavailability. The dietary supplements application represents the largest end-use, where standardized powders are widely incorporated into capsules and tablets. In contrast, the pharmaceuticals segment demands higher-margin micronized hesperidin for treating conditions like chronic venous insufficiency.
The US Food and Drug Administration (FDA) and European Medicines Agency (EMA) establish the primary quality and safety frameworks for hesperidin. These regulations dictate purity levels for pharmaceutical-grade material and acceptable health claims for supplements. China's National Medical Products Administration (NMPA) also imposes strict controls on domestic production and exports. Future competitiveness depends on a supplier's capacity to generate clinical data that substantiates specific health benefits.
Market Dynamics
The hesperidin market is defined by a structural bifurcation driven by pharmacopoeia compliance. Stringent purity mandates from the United States Pharmacopeia (USP) and European Pharmacopoeia (EP) are segmenting suppliers into distinct tiers, separating high-purity pharmaceutical grades from standardized supplement powders.
Growth Catalysts
- Dietary Supplement Expansion:Growing consumer focus on preventative health and circulatory support is expanding the use of hesperidin in dietary supplements, particularly for venous health and antioxidant formulations.
- Regulatory Substantiation:Frameworks like the European Medicines Agency's guidance on herbal medicinal products encourage clinical research, which in turn substantiates health claims and opens new therapeutic applications.
- Processing Advancements:Advances in extraction and purification technologies, particularly in China's citrus-growing regions, are improving yields and cost-efficiency, making standardized hesperidin more accessible for mass-market products.
Market Restraints
- Poor Bioavailability:Hesperidin's inherent poor water solubility presents a significant technical barrier, requiring costly secondary processing like micronization to be effective in pharmaceutical and premium supplement applications.
- Supply Chain Concentration:Heavy reliance on raw material from specific citrus-growing provinces in China creates supply chain vulnerability, exposing the market to risks from regional agricultural policies and climate events.
- Bioflavonoid Substitution:Competition from other bioflavonoids like diosmin and quercetin, which offer similar antioxidant and anti-inflammatory benefits, can limit hesperidin's penetration in certain supplement formulations.
Strategic Opportunities
- Functional Food Integration:Incorporation into functional foods and beverages represents a significant growth vector, moving beyond traditional capsules and tablets to reach a broader consumer base interested in fortified nutrition.
- Novel Delivery Systems:Developing new delivery systems, such as lipid-based carriers or complexation with other molecules, offers a path to create premium, high-bioavailability products that can command higher prices.
- Geographic Expansion:The expanding middle class and nascent but growing supplement market in India present an underpenetrated geography for standardized hesperidin powders, particularly for circulatory and immune health products.
Industry Challenges
- Compliance and Certification Costs:Achieving and maintaining compliance with evolving USP and EP monograph standards requires significant investment in analytical testing, quality control, and regulatory documentation, posing a high barrier for smaller producers.
- Clinical Data Generation:The high cost and long timelines associated with generating robust clinical data to substantiate specific health claims for regulators like the FDA or EMA are a major operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hesperidin Market |
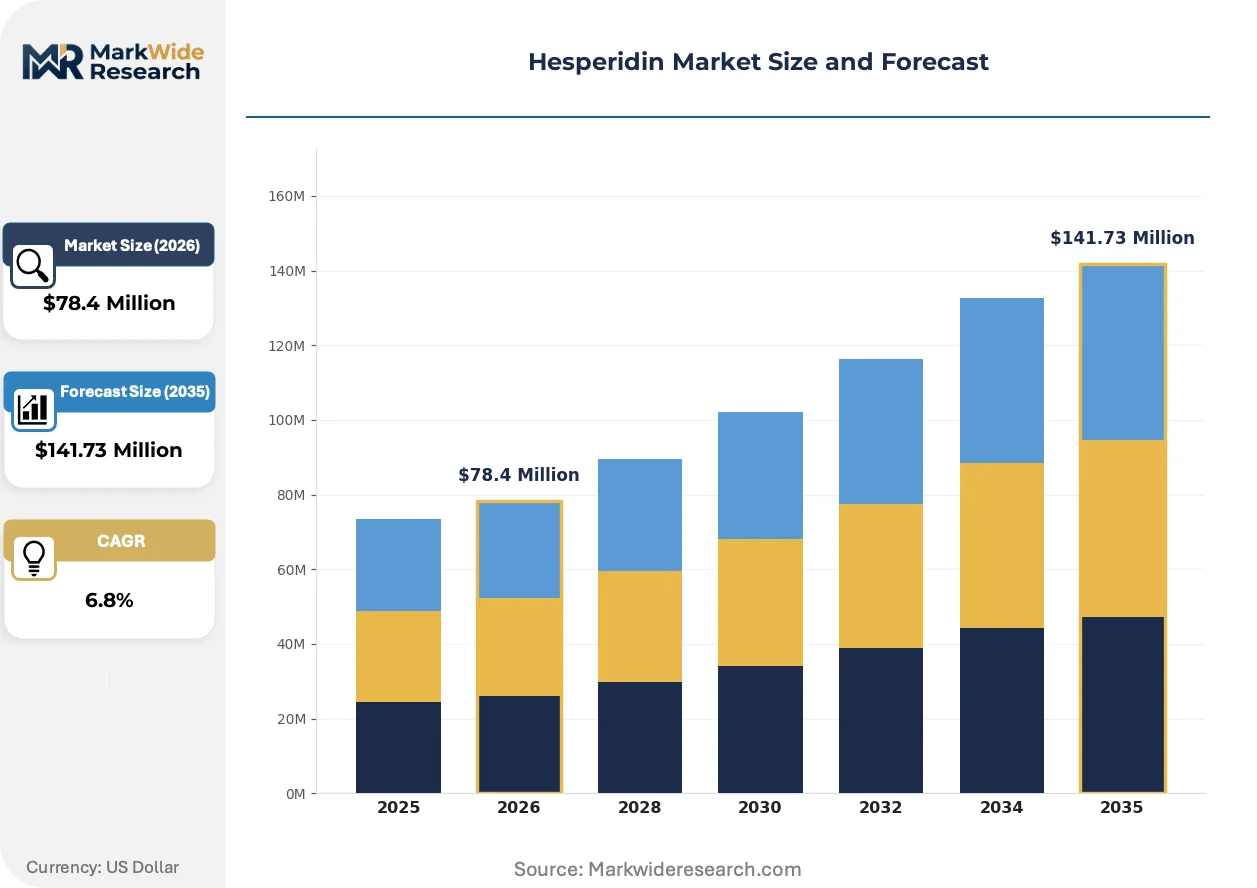
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $141.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Extract, Standardized Powder, Micronized Hesperidin, Hesperidin Complex Application: Dietary Supplements, Pharmaceuticals, Cosmetics, Functional Foods, Veterinary Use End User: Nutrition Companies, Pharmaceutical Manufacturers, Personal Care Brands, Animal Nutraceutical Producers Form: Powder, Capsules, Tablets, Liquid Concentrate, Cream |
| Companies Covered | Chengdu Runde Pharmaceutical, Lupin, Zhejiang Conler Pharmaceutical, Shanghai Shyndec Pharmaceutical, Toyo Hakko Company, Chengdu Okay, Sunpharam, Swanson Health, Benepure Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hesperidin Market Strategic Shifts & Innovations
Technological advancements in particle engineering and a stricter regulatory environment are pushing the hesperidin market toward value-added, functionally enhanced ingredients. This evolution prioritizes bioavailability and clinical substantiation over raw commodity supply.
Micronization technology directly addresses hesperidin's poor solubility by drastically reducing its particle size. Pharmaceutical manufacturers are the primary adopters, using it to formulate drugs for conditions like chronic venous insufficiency. This process is miniaturizing the active pharmaceutical ingredient, enabling superior bioavailability and the creation of more effective, lower-dosage oral solid forms.
European Medicines Agency (EMA) guidance on herbal medicinal products is imposing stricter quality controls on hesperidin used in pharmaceuticals. These regulations mandate tighter specifications for purity and assay, effectively creating a higher barrier to entry for the prescription drug segment. Suppliers aiming for the European market must now invest heavily in advanced analytical chemistry and process validation to meet these stringent monograph requirements.
A notable shift in purchasing criteria is evident, as brand owners in the dietary supplement sector prioritize verifiable quality certifications. This moves procurement decisions beyond price, favoring suppliers who provide documented proof of non-GMO, allergen-free, and third-party verified materials. This demand for supply chain transparency is most pronounced in the North American and European markets.
Hesperidin Market Segmentation
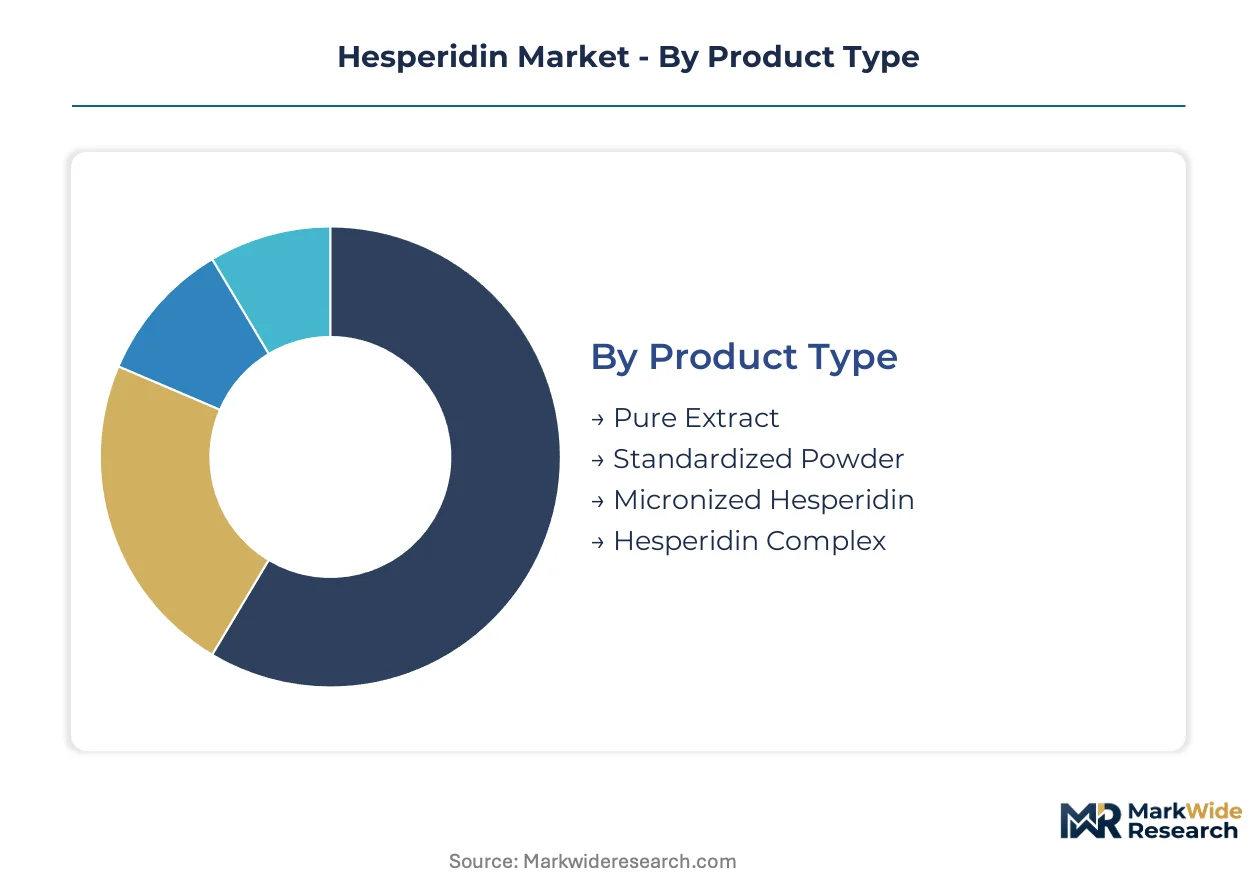
The hesperidin market segments reflect the diverse purity requirements, functional applications, and end-user demands across various industries. Understanding these distinct segments is crucial for suppliers to tailor product offerings and navigate the complex regulatory landscape effectively.
Product Type:
The varied product forms of hesperidin dictate distinct distribution channels, from bulk ingredient suppliers to specialized pharmaceutical distributors.
- Micronized Hesperidin:This form features drastically reduced particle sizes, significantly enhancing water solubility and bioavailability. Pharmaceutical manufacturers are the primary adopters, using it to formulate prescription drugs for conditions like chronic venous insufficiency and premium dietary supplements.
- Standardized Powder:This common form contains a guaranteed minimum percentage of hesperidin, ensuring consistent potency for mass-market applications. The dietary supplement industry widely incorporates standardized powders into capsules and tablets for general health and antioxidant formulations.
- Pure Extract:This high-purity form serves as a raw material for further processing or for applications demanding minimal excipients.
- Hesperidin Complex:This form combines hesperidin with other molecules or delivery systems to further improve its absorption and efficacy.
Standardized Powder dominates the installed base. Micronized Hesperidin is where expansion concentrates.
Application:
Hesperidin's diverse functional properties enable its integration across multiple end-use sectors, each with specific efficacy and regulatory requirements.
- Dietary Supplements:This application segment incorporates hesperidin into capsules, tablets, and softgels for circulatory support, antioxidant benefits, and immune modulation. Growing consumer focus on preventative health in North America and Europe drives demand.
- Pharmaceuticals:This segment demands high-purity, often micronized hesperidin for prescription drugs targeting conditions like chronic venous insufficiency and hemorrhoids. European Medicines Agency (EMA) standards heavily influence product development in this area.
- Functional Foods:Hesperidin is integrated into fortified beverages, snacks, and dairy products to offer enhanced nutritional benefits.
- Cosmetics:Personal care brands use hesperidin in anti-aging creams, serums, and other dermatological formulations for its antioxidant and anti-inflammatory properties.
- Veterinary Use:Animal nutraceutical producers incorporate hesperidin into feed supplements for livestock and pets, supporting immune function and overall animal health.
Dietary Supplements represents the largest volume segment. Pharmaceuticals exhibits strong value growth due to premium pricing.
End User:
The distinct operational models of hesperidin's end users shape their procurement strategies and quality demands.
- Pharmaceutical Manufacturers:These companies require hesperidin meeting stringent United States Pharmacopeia (USP) and European Pharmacopoeia (EP) monographs, necessitating extensive quality control and regulatory documentation. They often purchase high-purity, micronized forms for drug production.
- Nutrition Companies:This segment includes firms producing dietary supplements and health-focused products, often sourcing standardized hesperidin powders in bulk. Their purchasing criteria increasingly prioritize verifiable quality certifications like non-GMO and third-party testing.
- Personal Care Brands:These end users integrate hesperidin into their cosmetic and skincare product lines, focusing on its topical benefits.
- Animal Nutraceutical Producers:Companies in this sector formulate animal feed supplements and veterinary health products using hesperidin.
Nutrition Companies drive significant volume throughput. Pharmaceutical Manufacturers command higher-margin product specifications.
Form:
The final physical form of hesperidin reflects varying processing requirements and suitability for specific delivery methods.
- Powder:This is the most common bulk form, providing versatility for manufacturers to incorporate into various product types. The dietary supplement industry heavily relies on powder for encapsulation and blending into formulations.
- Capsules:Pre-dosed and convenient, capsules are a popular consumer-ready form for dietary supplements. Retail markets in North America and Europe show high demand for hesperidin in capsule format.
- Tablets:Compressed powder forms, often coated for ease of swallowing, stability, or controlled release, are prevalent in both pharmaceutical and supplement applications.
- Liquid Concentrate:Soluble forms of hesperidin are utilized in functional beverages, specialized liquid supplements, and other innovative delivery systems.
- Cream:Hesperidin is formulated into topical creams for cosmetic and dermatological applications, leveraging its skin health benefits.
Powder forms represent the traditional market entry point. Liquid Concentrate and Cream forms are gaining traction through product innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European Medicines Agency (EMA) guidance encourages clinical research for herbal medicinal products. This policy drives demand for high-purity hesperidin with substantiated health claims. Regulatory frameworks across major economies shape product development and market access.
China
China's robust raw material processing capabilities meet global demand for hesperidin. The National Medical Products Administration (NMPA) enforces strict quality controls on domestic production and exports. Citrus-growing regions in Sichuan and Zhejiang provinces anchor large-scale extraction and purification operations.
United States
Consumer focus on preventative health drives substantial demand for hesperidin in US dietary supplements. The US Food and Drug Administration (FDA) sets primary quality and safety standards for both supplement and pharmaceutical grades. Major pharmaceutical firms and nutrition companies in the Northeast and Midwest prioritize high-purity, often micronized, hesperidin.
Germany
Germany's pharmaceutical sector demands high-purity hesperidin for prescription drugs treating chronic venous insufficiency. European Pharmacopoeia (EP) monographs enforce stringent purity and assay standards for pharmaceutical-grade material. Advanced manufacturing facilities in regions like North Rhine-Westphalia and Bavaria focus on micronized hesperidin formulations.
India
The expanding middle class in India presents a significant underpenetrated market for standardized hesperidin powders. The Central Drugs Standard Control Organization (CDSCO) regulates pharmaceutical and nutraceutical ingredients within the country. Major pharmaceutical and nutraceutical manufacturers in Maharashtra and Gujarat are exploring hesperidin integration into new products.
Hesperidin Market Key Industry Players
Player mix skews toward specialized ingredient manufacturers and pharmaceutical-grade suppliers. The hesperidin market exhibits a tiered structure, separating high-purity pharmaceutical grades from standardized supplement powders. Strategic archetypes include large-scale extractors dominating commodity supply, high-purity pharmaceutical ingredient specialists, and innovators focusing on enhanced bioavailability. Companies actively pursue strategic partnerships for R&D and geographic expansion into emerging markets, alongside capacity expansion to meet demand.
Specialists in high-purity pharmaceutical ingredients, such as India-based Lupin, leverage extensive regulatory expertise for prescription drug applications. These firms navigate complex compliance landscapes, including United States Pharmacopeia (USP) and European Pharmacopoeia (EP) monographs. At the scale-driven end, China-based Zhejiang Conler Pharmaceutical anchors the supply of standardized powders for the global supplement industry, focusing on cost-efficient, large-volume extraction. Benepure Corporation, another key player, differentiates through its development of micronized and complexed forms, exemplifying innovation in enhanced bioavailability solutions for premium products. These firms collectively represent the diverse capabilities driving market segmentation and product differentiation.
| Leading Market Players |
|---|
| Chengdu Runde Pharmaceutical |
| Lupin |
| Zhejiang Conler Pharmaceutical |
| Shanghai Shyndec Pharmaceutical |
| Toyo Hakko Company |
| Chengdu Okay |
| Sunpharam |
| Swanson Health |
| Benepure Corporation |
Cost & Logistics Intelligence
United States Pharmacopeia (USP) and European Pharmacopoeia (EP) monographs gate both supply qualification and price differentiation in the hesperidin market. These stringent standards bifurcate the supplier base, impacting product pricing across tiers.
Pricing Analysis
Certification level (USP/EP compliance) creates the primary spread across hesperidin product pricing, with purity and particle size serving as key differentiation drivers. The market operates on a contract-based long-term offtake model for pharmaceutical grades; standardized powders often follow commodity spot pricing. Pricing pressure stems from intense competition among Chinese extractors for standardized powders. Pharmaceutical manufacturers exhibit low price sensitivity for high-purity, micronized forms, whereas nutrition companies are more sensitive to costs for bulk standardized powders.
Supply Chain Analysis
Inventory strategies vary, with pharmaceutical manufacturers often maintaining strategic stockpiles of high-purity hesperidin, while supplement producers prefer just-in-time delivery for standardized powders. Global supply concentration centers heavily in China, particularly from citrus-growing provinces like Sichuan and Zhejiang. The market relies on unripe citrus fruits, especially Citrus aurantium, as its primary raw material. Single-source vulnerability from China's agricultural policies poses a significant structural risk. Distribution runs through specialized ingredient distributors and direct sales channels to large end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hesperidin market presents a service-attach opportunity, with advanced analytical testing and regulatory documentation services expanding faster than the underlying ingredient sales. Suppliers can differentiate by offering comprehensive compliance support.
For Market Incumbents: Shield core pharmaceutical-grade market share by deepening regulatory expertise and investing in clinical data generation. This protects against margin erosion from emerging low-cost producers and bioflavonoid substitution. Expand production capacity in established regions while optimizing extraction efficiency in China. Leverage vertical integration to secure consistent raw material supply and maintain quality control.
For New Entrants and Emerging Players: A service-layer gap exists in providing specialized micronization services and novel delivery system development for smaller brands. Target the burgeoning dietary supplement market in India with standardized, clinically-backed hesperidin powders. Focus on a direct-to-consumer go-to-market strategy emphasizing transparency and verifiable quality certifications. Partner with local nutraceutical manufacturers to accelerate market penetration.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the pharmaceutical-grade hesperidin segment due to advanced processing and regulatory compliance requirements. The market offers long-term viability for players with robust clinical data and strong IP. Target acquisition archetypes include specialized micronization technology firms and companies with established regulatory approvals for novel delivery systems. Watch for increased M&A activity in China's extraction sector as a signal of consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Micronization Facilities | This allows pharmaceutical manufacturers to produce higher-bioavailability hesperidin for prescription drug formulations. |
| Secure Long-Term Raw Material Contracts | Nutrition companies ensure supply stability and cost predictability for standardized hesperidin powders amidst agricultural volatility. |
| Expand Clinical Data Generation for Health Claims | This provides regulatory substantiation for hesperidin's benefits, opening new applications for dietary supplements. |
| Develop Lipid-Based Delivery Systems | Benepure Corporation can enhance hesperidin's absorption and efficacy, commanding premium pricing in supplements. |
| Establish Regulatory Compliance Hubs in Europe | Lupin strengthens market access for pharmaceutical-grade hesperidin by navigating EMA guidelines effectively. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews. These included pharmaceutical R&D leads, nutraceutical product managers, regulatory affairs specialists, and citrus extractors. Secondary validation drew from FDA filings, EMA guidance documents, NMPA reports, and trade association publications. A rigorous bottom-up and top-down triangulation process ensured data accuracy and market sizing integrity.
The forecast analysis projects market trajectories across the analysis window, utilizing a robust analytical framework. Segmentation dimensions modeled include product type, application, end-user, and regional regulatory compliance. Compound Annual Growth Rates (CAGRs) were derived from historical data trends and projected demand elasticity. Key inputs included citrus crop yields and evolving pharmacopoeia standards.
Forecasts assume regulatory continuity in US FDA, EMA, and NMPA regimes; material policy shifts would require re-modeling. Geopolitical tensions affecting China's supply chain or significant climate events impacting citrus harvests represent key risk factors. Revision becomes warranted when these conditions cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Black Fungus Extract Market
Extracts
Aloe Vera Derivatives Market
Extracts
Eucommia Extract Market
Extracts
Labdanum Market
Extracts
Global Aphrodisiac Powder Market
Extracts
Functional Extract Market
Extracts
Laurel Oil Market
Extracts
Agmatine Market
Extracts
Myrrh Powder Market
Extracts
Bidens Pilosa Extract Market
Extracts
Aloe Vera Extract Market
Extracts
Patchouli Oil Market
Extracts
Essential Oil Isolates Market
Extracts
Valerian Root Powder Market
Extracts
Kelp Extracts Market
Extracts
Organic Herbal Extracts Market