
 Plum Extract Market | 2026-2036
Plum Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Plum Extract Market Insights
Ingredient refinement margins is narrowing as standardized extract production displaces basic commodity processing. Hunan Nutramax Inc. leverages its position in polyphenol-standardized manufacturing to capture premium pricing in dietary supplement supply chains. Shaanxi Sinuote Biotech Co. anchors the powder extract segment through backward integration into plum cultivation across northwestern China. The SICOLY cooperative differentiates via its Rhône Valley sourcing network and controlled-atmosphere extraction protocols for European cosmetic brands.
Plum extract comprises concentrated bioactive compounds—primarily phenolic acids, flavonoids, and anthocyanins—derived from Prunus domestica or Prunus mume fruit through solvent extraction, supercritical CO2 processing, or aqueous infusion methods, yielding standardized preparations for functional incorporation. Powder extract formulations command the largest volume position due to stability advantages in bulk manufacturing and extended shelf compatibility, while liquid extract variants register the fastest trajectory as beverage manufacturers seek clean-label flavor and color integration without synthetic additives. Dietary supplements represent the most mature application channel with established clinical positioning, whereas cosmetics applications concentrate margin pools around antioxidant and skin-brightening claims in premium dermocosmetic lines.
FDA dietary supplement labeling requirements and EFSA health claims regulations constrain permissible efficacy messaging and mandate substantiation dossiers for cross-border trade. China's NMPA and SAMR enforce dual-use food-medicine ingredient classifications that affect plum extract registration pathways and import clearance procedures. Organic certification under USDA National Organic Program and EU 2018/848 standards increasingly governs raw material eligibility for North American and European finished product placement. Stakeholders must monitor evolving pharmacovigilance reporting obligations and adapt extraction documentation to preempt supply exclusion from regulated channels.
Market Dynamics
Clean-label certification requirements are compressing ingredient sourcing flexibility while concentrating procurement power among vertically integrated extractors capable of documenting full chain-of-custody from orchard to finished powder.
Growth Catalysts
- EU 2018/848 organic standards:Mandatory organic certification for raw material eligibility in European nutraceutical formulations is pulling supply toward certified cultivation networks in France and Italy.
- Supercritical CO2 extraction:Adoption of solvent-free processing technology by Japanese functional beverage manufacturers preserves heat-sensitive anthocyanin profiles for ume-based health drinks.
- Dietary supplement channel:Established clinical positioning of plum polyphenols for cardiovascular and metabolic health claims sustains procurement volumes from North American contract manufacturers.
Market Restraints
- Prunus mume cultivation concentration:Overreliance on specific Japanese and Chinese growing regions for ume plum varieties creates weather-dependent supply volatility.
- FDA substantiation requirements:Mandatory efficacy dossiers for structure-function claims impose documentation burdens that exclude smaller extractors from cross-border trade.
- Synthetic antioxidant substitution:Butylated hydroxytoluene and ascorbic acid derivatives compete on cost in mass-market food preservation applications.
Strategic Opportunities
- Brazilian dermocosmetic market:Underpenetrated positioning of plum seed oil extracts in premium skin-brightening formulations offers first-mover advantage for ANVISA-registered suppliers.
- China dual-use registration:SAMR food-medicine ingredient classifications create pathway for plum extract inclusion in traditional medicine-inspired functional foods.
- Direct-to-brand digital procurement:Bypassing traditional ingredient distributors allows extractors to capture margin from mid-sized cosmetic brands seeking traceable antioxidant sourcing.
Industry Challenges
- Polyphenol standardization expertise:Scarce analytical chemistry talent capable of validating consistent chlorogenic acid and quercetin concentrations across harvest batches.
- USDA organic certification timelines:Three-year transition periods for conventional orchard conversion delay raw material eligibility for premium supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plum Extract Market |
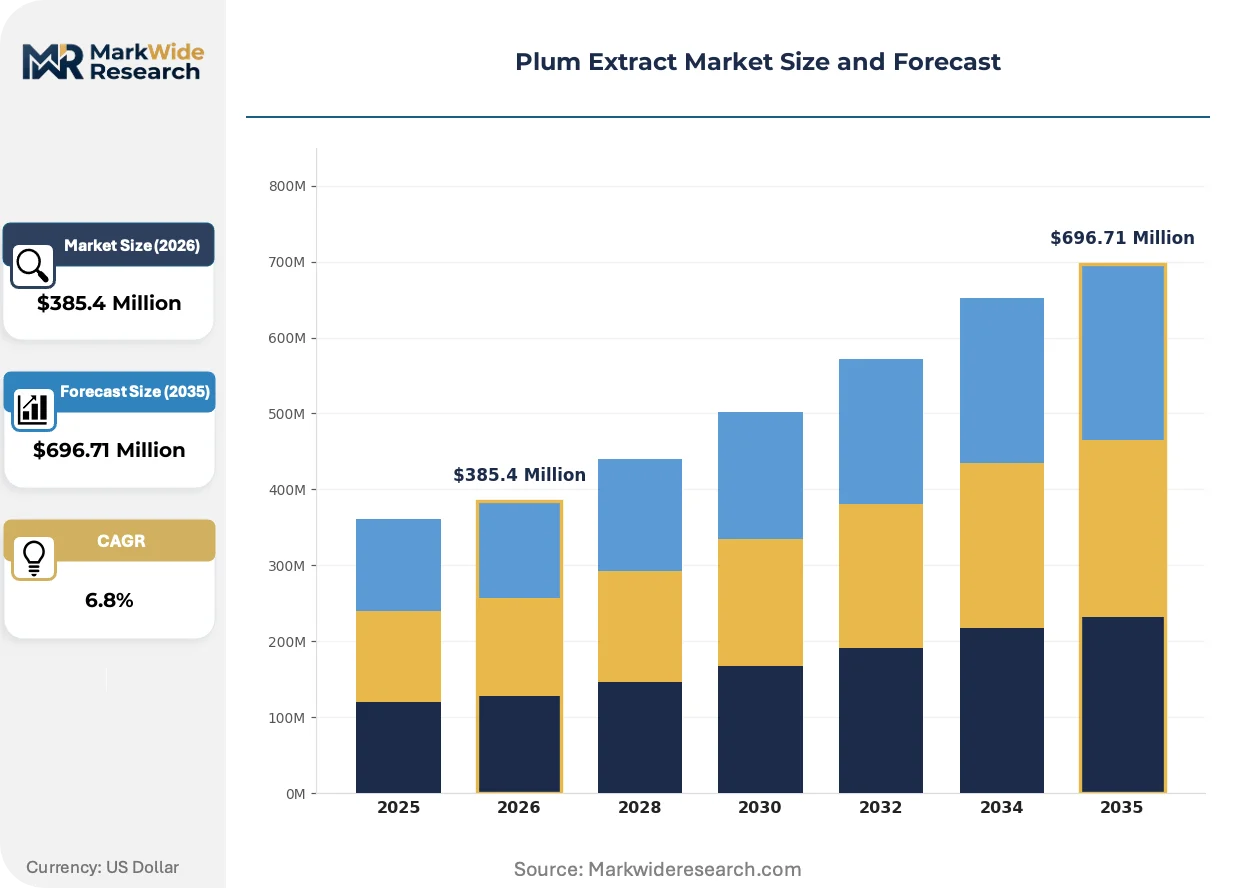
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powder Extract, Capsule, Tincture Application: Food & Beverage, Dietary Supplements, Cosmetics, Pharmaceuticals End User: Healthcare Providers, Food Manufacturers, Cosmetic Brands, Nutraceutical Companies Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | The SICOLY cooperative, Hunan Nutramax Inc., Shaanxi Sinuote Biotech Co., Aston Chemicals Limited, Swanson Health Products, Shenzhen Evergreen Bio-Health Technology Limited, Yiherb Bioscience Co. Limited, Changsha Herbal Ingredient Co. Limited, MIKI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plum Extract Market Trends and Innovations
Extraction technology convergence with digital traceability systems is redefining competitive differentiation, while regulatory tightening in major consumption markets elevates documentation capabilities above commodity pricing.
Supercritical CO2 extraction equipment paired with inline spectroscopic monitoring is virtualizing quality assurance protocols that previously required separate laboratory validation. Japanese beverage manufacturers deploy these integrated systems to certify real-time anthocyanin stability without batch destruction. The technology is virtualizing traditional separation between production and analytical functions, compressing lead times for custom-standardized extracts.
EFSA health claims regulations now mandate randomized controlled trial evidence for antioxidant-related cardiovascular benefit statements in finished products. This evidentiary burden filters supplier eligibility toward extractors with clinical research partnerships and published polyphenol bioavailability studies. Dietary supplement brands targeting European distribution are consolidating procurement around dossier-complete ingredient sources.
Cosmetic formulators now specify chain-of-custody documentation from named cultivation cooperatives rather than accepting generic botanical certificates. This preference shift disintermediates commodity traders and rewards extractors with captive orchard relationships or exclusive harvest agreements. French and Italian cosmetic houses lead this specification tightening, requiring GPS-tagged harvest records and controlled-atmosphere processing logs.
Plum Extract Market Segmentation
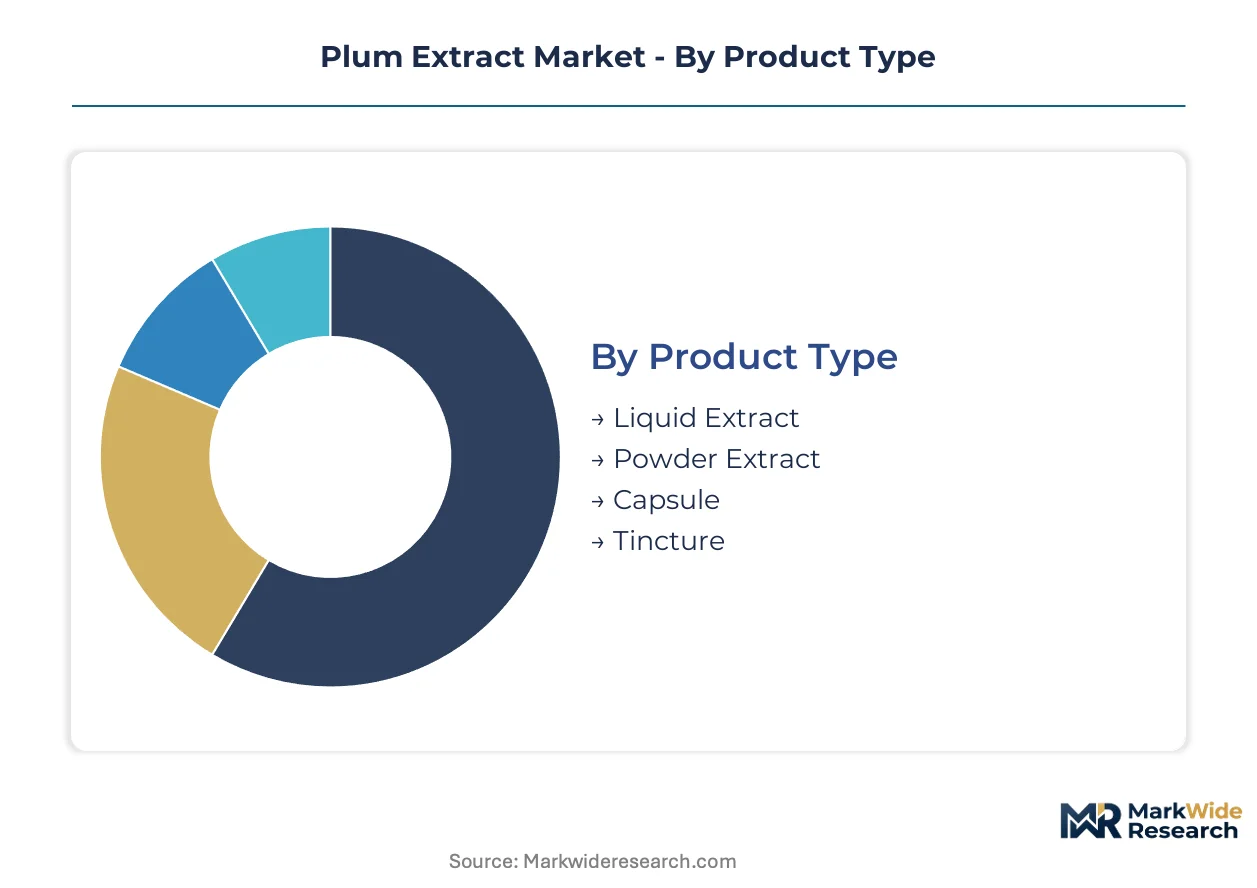
Segmentation in the plum extract market determines procurement cycles, margin capture, and regulatory pathway complexity. Product form dictates shelf-life economics and manufacturing integration depth, while application channels separate commodity-grade from clinical-grade value capture.
Product Type:
Cycle times vary dramatically across product forms, with liquid extracts requiring refrigerated logistics and powder extracts offering multi-year stability windows.
- Liquid Extract:Aqueous or ethanol-based solutions retaining volatile aromatic compounds and heat-sensitive anthocyanins for beverage integration. Japanese functional drink manufacturers in Tokyo and Osaka prefectures drive procurement for ume-based formulations requiring clean-label color stability without synthetic additives.
- Powder Extract:Spray-dried or freeze-dried preparations standardized to specific polyphenol concentrations, favored by contract manufacturers for dietary supplement tableting and encapsulation. Shaanxi province extraction facilities supply bulk volumes to North American nutraceutical brands seeking extended shelf compatibility.
- Capsule:Pre-measured gelatin or vegetable-based shells containing standardized plum extract powder for direct consumer dosing. Health food retailers in Germany and France stock these for antioxidant positioning claims.
- Tincture:Alcohol-infused concentrated preparations targeting traditional medicine applications and herbalist channels. Small-batch producers in Provence and Tuscany serve European apothecary networks.
Powder extract anchors the volume base while liquid extract gains share at the steepest rate.
Application:
Margin stratification separates mass-market food preservation from premium dermocosmetic positioning.
- Food & Beverage:Natural colorant and flavoring applications in juices, jams, and functional drinks, competing with synthetic alternatives on cost-per-unit-color basis. Brazilian and Mexican beverage formulators increasingly specify plum-derived alternatives to meet clean-label export requirements for US retail placement.
- Dietary Supplements:Capsule, tablet, and softgel formats delivering standardized polyphenol doses for cardiovascular and metabolic health claims. FDA structure-function claim substantiation requirements favor suppliers with published clinical bioavailability studies.
- Cosmetics:Antioxidant serum, brightening cream, and anti-aging formulations leveraging anthocyanin skin penetration properties. ANVISA-registered suppliers target São Paulo and Rio de Janeiro dermocosmetic manufacturers with seed oil extract variants.
- Pharmaceuticals:Investigational and traditional medicine applications requiring GMP-certified extraction and documented heavy metal screening. China's NMPA dual-use classification creates registration complexity for cross-border supply.
Dietary supplements anchor the revenue base while cosmetics climbs the fastest on premium pricing expansion.
End User:
Procurement sophistication tiers separate specification-driven buyers from price-sensitive commodity purchasers.
- Healthcare Providers:Clinics and integrative medicine practices recommending plum extract for patient protocols, requiring batch-specific certificates of analysis and allergen documentation.
- Food Manufacturers:Industrial-scale buyers integrating extract into processed foods, prioritizing volume pricing and consistent colorimetric specifications across harvest seasons.
- Cosmetic Brands:Premium formulators demanding chain-of-custody documentation from named cultivation cooperatives with GPS-tagged harvest records.
- Nutraceutical Companies:Dietary supplement brands requiring organic certification compliance and published polyphenol standardization for structure-function claim support.
Food manufacturers anchor procurement volume while cosmetic brands expand specification requirements most aggressively.
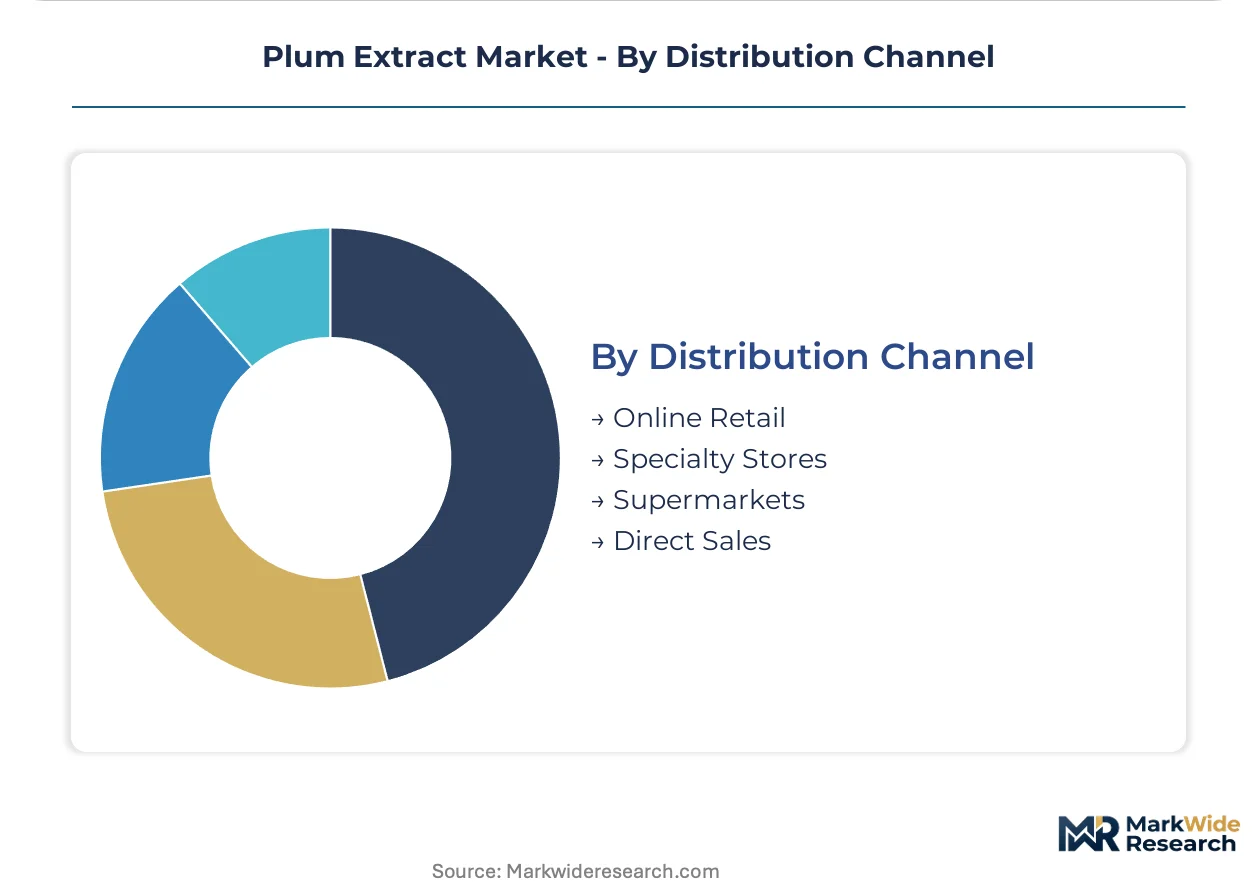
Distribution Channel:
Channel selection determines margin retention and customer relationship depth for extractors of varying scale.
- Online Retail:Direct-to-consumer platforms enabling mid-sized extractors to bypass distributor markups and capture end-user pricing power.
- Specialty Stores:Health food and apothecary channels serving educated consumers seeking traditional medicine applications and organic-certified options.
- Supermarkets:Mass retail placement for finished supplement and functional food products, requiring significant marketing investment and slotting fees.
- Direct Sales:B2B procurement relationships between extractors and brand manufacturers, favored for custom-standardized volumes and exclusive supply agreements.
Direct sales anchors B2B volume while online retail expands most quickly for mid-tier extractors seeking margin recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese buyers absorb premium-grade ume extracts with minimal price elasticity, while Brazilian and Mexican beverage formulators face acute cost pressure from synthetic colorant alternatives.
Japan
Functional beverage manufacturers in Tokyo and Osaka prefectures drive procurement for heat-sensitive anthocyanin formulations. METI guidelines on health food manufacturing impose documentation standards that favor suppliers with integrated supercritical CO2 capabilities. Wakayama Prefecture's ume orchards supply raw material to extraction facilities serving both domestic drink brands and traditional medicine channels.
China
NMPA and SAMR enforce dual-use food-medicine classifications that create registration complexity for cross-border extract shipments. Shaanxi province extraction clusters anchor powder extract supply to North American nutraceutical contract manufacturers. Hunan-based processors leverage polyphenol standardization expertise to capture premium pricing in dietary supplement supply chains.
United States
FDA structure-function claim substantiation requirements filter supplier eligibility toward extractors with published clinical bioavailability studies. California and New York-based dietary supplement brands consolidate procurement around dossier-complete organic-certified sources. USDA National Organic Program three-year orchard conversion timelines delay raw material eligibility for premium supply contracts.
France
EFSA health claims regulations mandate randomized controlled trial evidence for antioxidant-related cardiovascular benefit statements in finished products. The SICOLY cooperative's Rhône Valley sourcing network supplies controlled-atmosphere extraction protocols to Paris-based dermocosmetic houses. Cosmetic formulators specify GPS-tagged harvest records and chain-of-custody documentation from named cultivation cooperatives.
Brazil
ANVISA registration requirements create barrier-to-entry for seed oil extract variants targeting São Paulo and Rio de Janeiro dermocosmetic manufacturers. Beverage formulators specify plum-derived colorants to meet clean-label export requirements for US retail placement. Underpenetrated positioning in premium skin-brightening formulations offers first-mover advantage for compliant suppliers.
Plum Extract Market Competitive Landscape
Polyphenol-standardized specialists and backward-integrated cultivators split the market between premium dietary supplement supply and commodity powder volumes. The vendor base concentrates around extraction facilities with captive orchard relationships or exclusive harvest agreements. Three archetypes dominate: vertically integrated Chinese processors with in-house cultivation control, European cooperatives with geographic indication sourcing networks, and North American brands with direct-to-consumer distribution infrastructure. Competitive moves center on M&A targeting analytical chemistry capabilities and strategic partnerships with clinical research institutions for bioavailability dossiers.
Among Chinese fabricators, Hunan Nutramax Inc. and Shaanxi Sinuote Biotech Co. exemplify the backward-integrated archetype, occupying positions that leverage provincial cultivation networks for volume supply to North American nutraceutical channels. The SICOLY cooperative represents the European cooperative model, anchoring premium positioning through controlled-atmosphere extraction protocols and named-origin documentation for French cosmetic houses.
| Leading Market Players |
|---|
| The SICOLY cooperative |
| Hunan Nutramax Inc. |
| Shaanxi Sinuote Biotech Co. |
| Aston Chemicals Limited |
| Swanson Health Products |
| Shenzhen Evergreen Bio-Health Technology Limited |
| Yiherb Bioscience Co. Limited |
| Changsha Herbal Ingredient Co. Limited |
| MIKI Corporation |
| Others |
Pricing and Supply Chain Analysis
Shanghai-to-Los Angeles container freight corridors absorb volatile fuel surcharges that cascade through plum extract supply chains, compressing margins for non-integrated processors while amplifying price differentiation between certified-organic and conventional grades. This logistics cost dynamic concentrates procurement power among extractors with captive orchard networks capable of absorbing freight volatility without passing full cost through to downstream buyers.
Pricing Analysis
After-sales technical service contracts and batch-specific analytical validation drive lifetime value capture for premium extractors. Three-tier pricing structure across certified-organic, conventional-standard, and commodity-economy levels separates Hunan Nutramax Inc.'s polyphenol-standardized offerings from Shaanxi Sinuote Biotech Co.'s bulk powder volumes. Price differentiation centers on USDA organic certification status and published chlorogenic acid standardization dossiers. Cost compression in the commodity tier is intensifying because Brazilian beverage formulators face acute substitution pressure from synthetic colorants. Food manufacturers show highest price sensitivity; French dermocosmetic houses demonstrate lowest elasticity due to specification-driven procurement.
Supply Chain Analysis
Export-control restrictions on supercritical CO2 extraction equipment limit technology transfer to Chinese facilities, constraining capacity expansion for solvent-free anthocyanin processing. Geographic supply concentration centers on China, Japan, and France for distinct variety specializations—Prunus mume cultivation in Wakayama Prefecture, Prunus domestica orchards in Shaanxi province, and Rhône Valley sourcing for European cosmetic networks. Raw material flows draw from ume plum harvests, polyphenol-rich fruit varieties, and GMP-certified extraction solvents. Single-source vulnerability runs through Wakayama Prefecture's weather-dependent ume crop cycles. Distribution runs through direct B2B procurement relationships and specialty ingredient distributors serving nutraceutical contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plum extract incumbents face sustained substitution pressure from synthetic antioxidants—particularly butylated hydroxytoluene and ascorbic acid derivatives—in mass-market food preservation applications. Defense requires building moats around certification and analytical capabilities that commodity substitutes cannot replicate.
For Market Incumbents: Build analytical chemistry moats through captive polyphenol standardization laboratories capable of validating consistent chlorogenic acid concentrations across harvest batches. Secure exclusive harvest agreements with named cultivation cooperatives in Wakayama Prefecture and the Rhône Valley to preempt competitor access to premium raw material streams. Capacity expansion in Shaanxi province extraction clusters captures volume demand from North American nutraceutical contract manufacturers facing FDA substantiation requirements. For New Entrants and Emerging Players: Pursue white-space positioning in Brazilian dermocosmetic seed oil extracts, where ANVISA registration requirements have kept penetration low relative to antioxidant demand from São Paulo and Rio de Janeiro formulators. Target direct-to-brand digital procurement channels that bypass traditional ingredient distributors and capture margin from mid-sized cosmetic brands seeking traceable sourcing. Lead with GPS-tagged harvest documentation and controlled-atmosphere processing logs as differentiated go-to-market collateral. For Investors and Strategic Acquirers: Polyphenol-standardization specialists with published clinical bioavailability studies represent the priority acquisition archetype, as EFSA health claims regulations and FDA structure-function requirements filter supplier eligibility toward dossier-complete sources. Long-term viability across the analysis window rests on regulatory compliance capabilities rather than commodity scale. Monitor SAMR dual-use registration pathway developments for plum extract inclusion in traditional medicine-inspired functional foods as inflection indicator for Chinese market access premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Japanese beverage manufacturers METI documentation standards favor solvent-free anthocyanin preservation capabilities. |
| Organic Certification Investment | USDA three-year orchard conversion timelines lock in premium supply contract eligibility for early movers. |
| Clinical Research Partnership | EFSA randomized controlled trial requirements filter European distribution toward bioavailability-study-backed suppliers. |
| Backward Integration into Cultivation | Captive orchard control in Shaanxi and Hunan provinces secures volume positioning for North American nutraceutical channels. |
| Direct-to-Brand Digital Procurement | Bypassing ingredient distributors captures margin from French and Italian cosmetic houses demanding chain-of-custody documentation. |
Research Methodology
A standing panel of extraction facility operations directors, nutraceutical contract manufacturing procurement leads, cosmetic formulator R&D heads, and regulatory affairs specialists provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from NMPA registration databases, FDA structure-function claim filings, EFSA health claims opinions, and USDA organic certification records. Bottom-up volume modeling from named cultivation cooperatives and extraction facilities triangulated against top-down demand estimates from dietary supplement and dermocosmetic finished product channels.
Scenario-bracketing around organic certification adoption rates, supercritical CO2 equipment deployment timelines, and synthetic antioxidant substitution elasticity framed the projection horizon. Segmentation dimensions modeled include product form stability requirements, application channel regulatory pathway complexity, end-user procurement sophistication tiers, and geographic certification standard clusters. CAGRs derived from normalized historical volume trajectories and elasticity-adjusted demand curves, with specific inputs from Japanese functional beverage anthocyanin specification trends and Brazilian ANVISA registration pipeline developments.
Macroeconomic conditions sit as an overlay; deviation in container freight rates, agricultural input costs, and currency exchange volatility would shift the trajectory of cross-border procurement patterns. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and clean-label certification adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Fig Glycolic Extract Market
Extracts
Amla Extract Market
Extracts
Laurel Oil Market
Extracts
Pullulan Market
Extracts
Copaiba Essential Oil Market
Extracts
Peppermint Oil Market
Extracts
Flower Extract Market
Extracts
Gum Turpentine Oil Market
Extracts
Ovalbumin Powder Market
Extracts
Orange Oil Market
Extracts
Passion Flower Extracts Market
Extracts
Belladonna Market
Extracts
Yucca Extract Material Market
Extracts
Bee Venom Extract Market
Extracts
Natural Morocco Argan Oil Market
Extracts
Hesperidin Market