
 Nigella Sativa Extract Market | 2026-2036
Nigella Sativa Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Nigella Sativa Extract Market Foresight
Pharmaceutical-grade thymoquinone concentration is rotating toward higher purity thresholds as buyers in regulated markets demand certificate-of-analysis documentation for every batch. Sabinsa Corporation leverages its India-based extraction infrastructure to supply standardized actives to European and North American nutraceutical formulators. FLAVEX Naturextrakte GmbH anchors its position through German-engineered supercritical CO2 extraction systems that preserve volatile oil integrity. Indena competes via its phytosome delivery technology, which enhances bioavailability for pharmaceutical applications.
Nigella sativa extract is a concentrated botanical preparation derived from black cumin seeds, typically standardized to thymoquinone content ranging from one percent to five percent and produced through cold-pressing, solvent extraction, or supercritical fluid methods for use in therapeutic, nutritional, and topical formulations. Oil-based extracts command premium positioning due to superior thymoquinone retention and broader pharmaceutical acceptance, while powder formats occupy volume-driven segments in functional food fortification. Nutraceutical applications lead current offtake, though cosmetics is registering accelerated interest as formulators incorporate the extract into anti-inflammatory skin care protocols.
FDA dietary supplement GMPs, EFSA Novel Food approvals, and India's FSSAI functional food regulations collectively determine market access velocity and label claim permissibility for Nigella sativa extract products across major consumption zones. EMA quality guidelines for herbal medicinal products are tightening assay requirements for thymoquinone content and heavy metal limits, forcing extractors to upgrade analytical capabilities or exit regulated supply chains. Stakeholders must monitor evolving pharmacopeial monograph developments and decide whether to pursue drug-master-file submissions or remain within the less regulated but lower-margin nutraceutical channel.
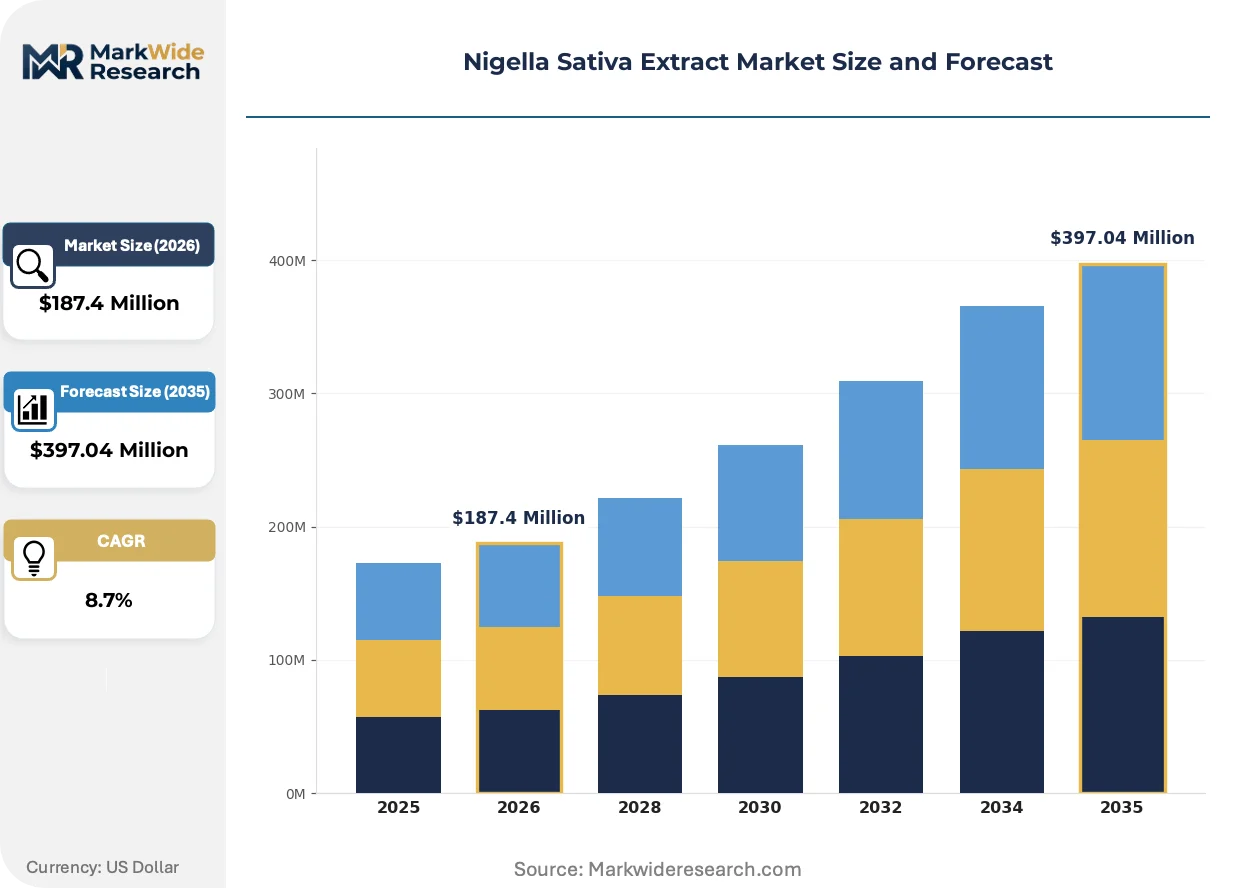
Market Dynamics
Pharmaceutical-grade thymoquinone standardization is concentrating procurement power among buyers demanding certificate-of-analysis documentation for every batch, forcing extractors to upgrade analytical capabilities or exit regulated supply chains entirely.
Growth Catalysts
- EMA Quality Guidelines:Tightening assay requirements for thymoquinone content and heavy metal limits are accelerating facility upgrades among European extractors seeking herbal medicinal product status.
- Ayurvedic Manufacturing Scale-Up:India's domestic formulators are expanding cold-press and supercritical CO2 processing capacity to serve export markets demanding standardized actives.
- Pharmaceutical Formulation Demand:Buyers in regulated markets are rotating procurement toward higher purity thresholds, pulling thymoquinone-standardized extracts into therapeutic development pipelines.
Market Restraints
- Input Cost Volatility:Nigella sativa seed prices fluctuate with climatic conditions in major cultivation zones, compressing margins for solvent-based extractors lacking backward integration into farming.
- Regulatory Friction:The European Union's Novel Food regulation creates multi-year approval pathways for botanical extracts, delaying market access for new entrants lacking existing dossiers.
- Substitution Threat:Synthetic thymoquinone production methods are advancing in pharmaceutical research settings, potentially displacing botanical extraction for pure active sourcing.
Strategic Opportunities
- Phytosome Delivery Convergence:Combining liposomal encapsulation with standardized extract production creates differentiated positioning for pharmaceutical applications demanding enhanced bioavailability.
- Cosmetic Anti-Inflammatory Protocols:Formulators are accelerating incorporation of Nigella sativa extract into skin care, opening volume channels beyond traditional nutraceutical offtake.
- India PLI Scheme Tailwinds:Production-linked incentives for botanical processing infrastructure are reducing capital intensity for domestic extractors scaling export-oriented capacity.
Industry Challenges
- Analytical Talent Scarcity:Extractors face acute shortages of chromatography specialists capable of validating thymoquinone assays to pharmacopeial standards required by EMA and FDA.
- Certification Timeline Compression:Drug-master-file preparation for pharmaceutical channel entry demands 18-24 month documentation cycles, straining working capital for mid-cap processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigella Sativa Extract Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil, Powder, Capsules, Tinctures Application: Food & Beverage, Nutraceuticals, Cosmetics, Pharmaceuticals Form: Liquid, Granular, Solid, Extract End User: Retail, Wholesale, Online, Healthcare Providers |
| Companies Covered | Sabinsa Corporation, Indena, Amazing Herbs, FLAVEX Naturextrakte GmbH, Arjuna Natural Extracts, Alpspure Lifesciences Private Limited, Herbo Nutra, Earth Root Spices and Herbs, Manish Agro Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigella Sativa Extract Market Shifts & Advancements
Extraction technology diversification is fragmenting competitive positioning across the value chain, with method-specific capabilities becoming the primary basis for supplier differentiation rather than raw material access alone.
Supercritical CO2 extraction systems are fragmenting the premium extract segment by preserving volatile oil integrity that solvent methods degrade. Pharmaceutical formulators in Germany and Switzerland are specifying CO2-derived materials for inflammatory disorder research. This capability concentration is compressing margins for conventional hexane extractors serving commodity nutraceutical channels.
EMA's tightening herbal medicinal product quality guidelines are reshaping compliance investments across European supply chains. Extractors must now maintain in-house HPLC-UV validation capabilities for every production batch. German-engineered analytical infrastructure is becoming a mandatory cost of entry for suppliers targeting prescription-adjacent positioning.
Buyer consolidation among North American nutraceutical brands is shortening supplier qualification cycles and unbundling technical service from material supply. Large formulators are deploying direct sourcing teams to Indian extraction clusters, bypassing traditional distributor intermediaries. This channel compression is most visible in Arizona and Utah, where contract manufacturers are building captive supplier audit programs.
Nigella Sativa Extract Market Segmentation
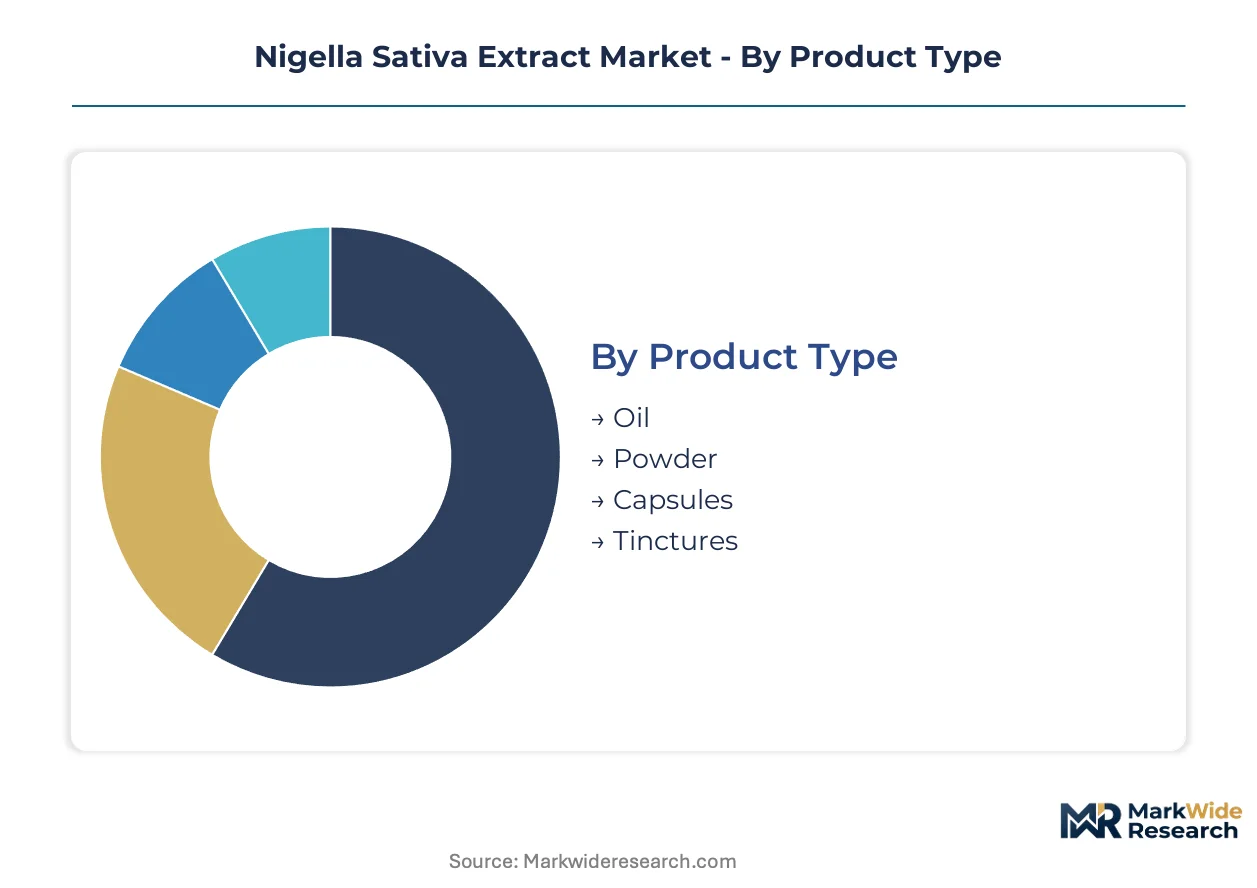
Nigella sativa extract procurement patterns diverge sharply across product formats and end-use channels, with pharmaceutical buyers demanding certificate-of-analysis documentation while nutraceutical formulators prioritize cost efficiency. Understanding these segment boundaries clarifies where synthetic thymoquinone substitutes pose the greatest displacement risk.
Product Type:
Synthetic thymoquinone production methods threaten oil-based segments most severely, while powder and capsule formats retain defensible positioning through formulation convenience and consumer accessibility.
- Oil:Cold-pressed and supercritical CO2-derived oils retain volatile terpenoid fractions including thymoquinone, thymohydroquinone, and thymol in concentrations ranging from one to five percent. Pharmaceutical formulators in Germany and Switzerland specify CO2-derived oils for inflammatory disorder research pipelines, though advancing synthetic thymoquinone synthesis in academic and contract research settings threatens long-term botanical sourcing for pure active applications.
- Powder:Spray-dried and maltodextrin-encapsulated powders standardize to lower thymoquinone thresholds, typically 0.5 to 2 percent, serving functional food fortification and bulk supplement manufacturing. Indian Ayurvedic processors in Gujarat and Rajasthan are scaling spray-drying capacity to serve export markets demanding free-flowing, shelf-stable formats for tablet and capsule compression.
- Capsules:Softgel and two-piece hardshell formats combine standardized oil or powder with excipient carriers for direct-to-consumer positioning. North American nutraceutical brands in Arizona and Utah are shortening supplier qualification cycles for pre-encapsulated materials, bypassing raw extract procurement entirely.
- Tinctures:Hydroalcoholic extracts target traditional medicine practitioners and apothecary retail channels with lower standardization requirements.
Oil anchors the volume base while capsules gain share at the steepest rate.
Application:
Regulatory pathway complexity and margin structure vary dramatically across end-use categories, with pharmaceutical channels demanding multi-year dossier preparation while cosmetics offers faster commercialization timelines.
- Food & Beverage:Novel Food approvals under EFSA jurisdiction create multi-year barriers for new entrants, favoring established suppliers with existing dossiers. European functional food manufacturers concentrate procurement on thymoquinone-standardized powders for bakery and beverage fortification.
- Nutraceuticals:Dietary supplement GMPs under FDA jurisdiction dominate current offtake volume, with buyers rotating toward higher purity thresholds and certificate-of-analysis documentation for every batch. Indian export-oriented extractors serve this channel through backward integration into Nigella sativa cultivation in Madhya Pradesh and Uttar Pradesh.
- Cosmetics:Anti-inflammatory skin care protocols are accelerating incorporation rates as formulators target sensitive skin and atopic dermatitis positioning. German and French cosmetic laboratories specify supercritical CO2-derived materials to preserve volatile oil integrity in topical formulations.
- Pharmaceuticals:Drug-master-file preparation demands 18-24 month documentation cycles and pharmacopeial-grade HPLC-UV validation capabilities, straining working capital for mid-cap processors seeking prescription-adjacent positioning.
Nutraceuticals captures the dominant revenue share while cosmetics expands most quickly.
Form:
Processing method and stability requirements determine logistics economics and customer switching costs across physical state categories.
- Liquid:Oil-based liquids command premium positioning through superior thymoquinone retention and broader pharmaceutical acceptance, though cold-chain requirements limit distribution reach.
- Granular:Free-flowing agglomerated particles suit automated manufacturing lines in functional food and supplement compression applications.
- Solid:Tablet and compressed formats serve institutional and clinical trial supply channels with precise dosing standardization.
- Extract:Concentrated resinous or paste preparations target traditional medicine compounding and veterinary applications.
Liquid forms dominate pharmaceutical procurement while granular solids capture functional food volume.
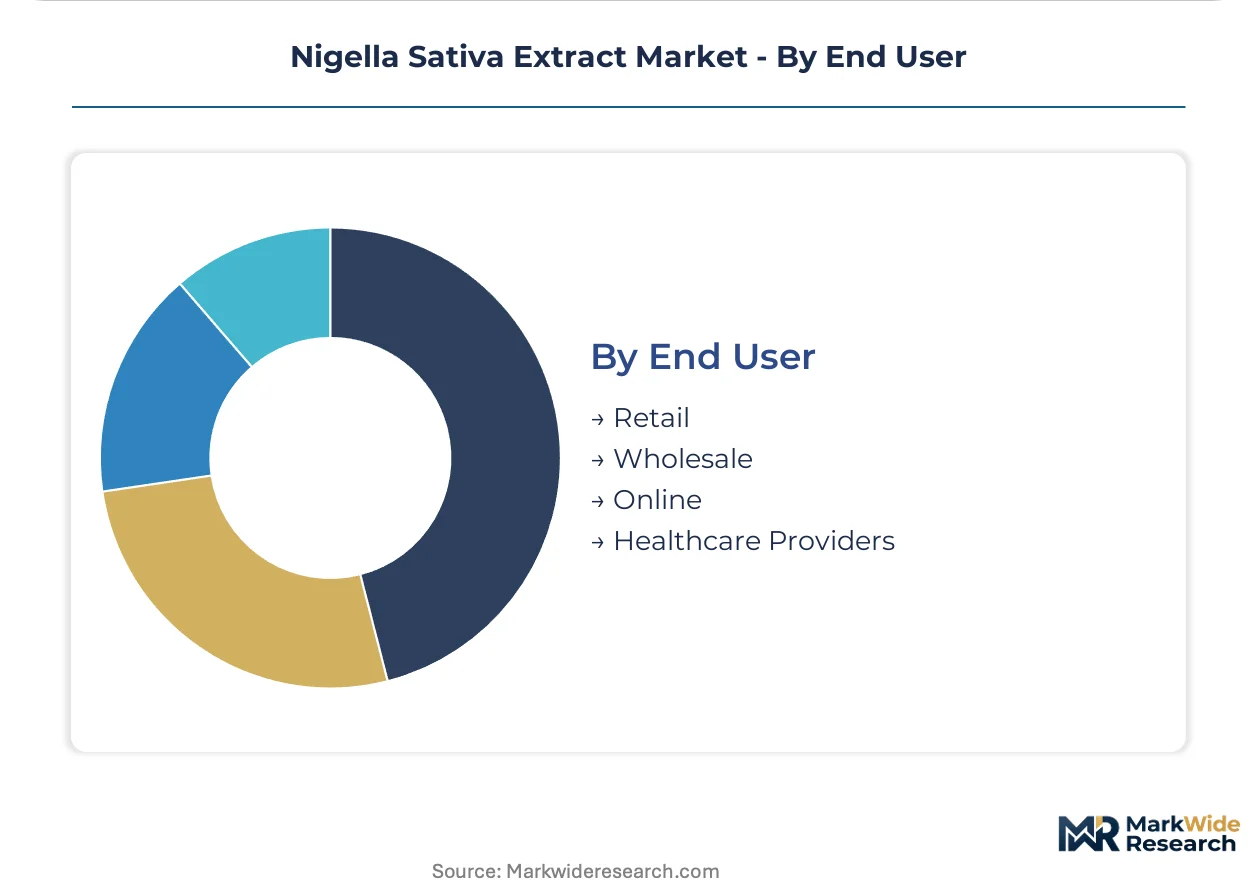
End User:
Channel structure and buyer consolidation patterns reshape supplier relationships and pricing power distribution across customer types.
- Retail:Health food stores and apothecary channels emphasize provenance storytelling and organic certification, favoring smaller batch artisanal producers.
- Wholesale:Distributor intermediaries face compression as large North American formulators deploy direct sourcing teams to Indian extraction clusters.
- Online:Direct-to-consumer brands demand turnkey private-label solutions including encapsulation, packaging, and regulatory documentation.
- Healthcare Providers:Integrative medicine practitioners and Ayurvedic clinics specify practitioner-grade materials with batch-specific assay reports.
Wholesale channels anchor current volume while online direct-to-consumer routes climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extraction capacity clusters in India and Germany, with regulatory divergence between EMA jurisdictions and FDA oversight creating distinct qualification pathways for suppliers targeting pharmaceutical versus nutraceutical channels.
India
Ayurvedic manufacturers in Gujarat and Rajasthan scale cold-press and supercritical CO2 infrastructure to serve export markets demanding thymoquinone-standardized actives. FSSAI functional food regulations govern domestic label claims while DGFT export incentives accelerate international shipment volumes. Madhya Pradesh and Uttar Pradesh cultivation belts anchor backward-integrated supply chains for seed procurement.
Germany
EMA quality guidelines for herbal medicinal products tighten assay requirements, forcing extractors to maintain in-house HPLC-UV validation capabilities for every batch. FLAVEX Naturextrakte GmbH anchors German-engineered supercritical CO2 extraction systems that preserve volatile oil integrity. Bavarian pharmaceutical clusters specify CO2-derived materials for inflammatory disorder research pipelines.
United States
FDA dietary supplement GMPs dominate procurement standards, with buyers rotating toward certificate-of-analysis documentation for every batch. Arizona and Utah contract manufacturers build captive supplier audit programs, deploying direct sourcing teams to Indian extraction clusters. Nutraceutical brands shorten qualification cycles for pre-encapsulated materials.
Switzerland
Swissmedic oversight of pharmaceutical-grade botanicals creates premium positioning for extractors meeting pharmacopeial monograph standards. Basel-area formulators specify thymoquinone concentrations above three percent for therapeutic development. Zurich-based analytical laboratories validate heavy metal limits to EMA-equivalent thresholds.
France
ANSM regulation of herbal medicines converges with EFSA Novel Food pathways for botanical extracts entering functional food channels. Parisian cosmetic laboratories accelerate incorporation of Nigella sativa extract into anti-inflammatory skin care protocols. Provence-Alpes-Côte d'Azur processing facilities specialize in hydroalcoholic tinctures for apothecary retail.
Nigella Sativa Extract Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with supercritical CO2 specialists commanding pharmaceutical premiums while solvent extractors serve volume-driven nutraceutical segments. The vendor base stratifies across three tiers: India-based integrated processors with captive cultivation, European precision extraction specialists with pharmacopeial-grade capabilities, and North American brand marketers outsourcing production entirely. Dominant competitive moves include capacity expansion in Indian processing clusters and technology licensing agreements for phytosome delivery systems.
Within the precision extraction tier, FLAVEX Naturextrakte GmbH and Indena exemplify European specialists leveraging German-engineered supercritical CO2 infrastructure and proprietary delivery technologies respectively. Sabinsa Corporation anchors India-based integrated supply, representing the backward-cultivation archetype with extraction capacity scaled for regulated export markets. These three entities occupy positions across distinct competitive vectors—technology licensing, cultivation integration, and pharmaceutical-grade processing—rather than competing directly for identical customer segments.
| Leading Market Players |
|---|
| Sabinsa Corporation |
| Indena |
| Amazing Herbs |
| FLAVEX Naturextrakte GmbH |
| Arjuna Natural Extracts |
| Alpspure Lifesciences Private Limited |
| Herbo Nutra |
| Earth Root Spices and Herbs |
| Manish Agro Industries |
| Others |
Supply & Pricing Matrix
Supercritical CO2 capacity utilization in German and Swiss extraction facilities anchors premium price floors, while solvent-based hexane processors in India compete on volume economics. Scale concentration among EMA-compliant extractors creates tiered pricing separation between pharmacopeial-grade materials and commodity nutraceutical inputs.
Pricing Analysis
EMA quality guidelines dictate the pricing tier structure across European supply chains, separating CO2-derived pharmaceutical grades from solvent-extracted nutraceutical volumes. Three-tier pricing stratifies across premium supercritical extracts, standard cold-pressed oils, and economy solvent-based powders. Cost compression in the solvent tier is intensifying because Indian processors lack backward integration into Madhya Pradesh cultivation belts. Contract manufacturers in Arizona and Utah exhibit highest price sensitivity, while Basel-area pharmaceutical formulators accept premiums for validated heavy metal documentation.
Supply Chain Analysis
Inventory lead times stretch 12-18 weeks for EMA-validated batches, compressing working capital for mid-cap processors pursuing drug-master-file submissions. Supply concentrates in India, Germany, and Switzerland, with seed procurement drawing from Madhya Pradesh and Uttar Pradesh cultivation belts. Raw material dependencies center on Nigella sativa seed quality, thymoquinone assay reagents, and supercritical CO2 equipment spare parts. Single-source vulnerability runs through German-engineered analytical infrastructure. Distribution feeds from Indian extraction clusters through direct sourcing teams to North American contract manufacturers, bypassing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nigella sativa extract sits in early-cycle expansion as pharmaceutical formulators accelerate thymoquinone-standardized procurement for inflammatory disorder pipelines. Penetration tailwinds from India's PLI scheme for botanical processing infrastructure reduce capital barriers for export-oriented capacity scaling.
For Market Incumbents: Secure pharmacopeial-grade HPLC-UV validation capabilities as defensive moats against EMA assay tightening. Deepen backward integration into Madhya Pradesh cultivation belts to buffer seed price volatility. Synthetic thymoquinone advancement in academic research settings threatens long-term displacement for pure active applications. For New Entrants and Emerging Players: EFSA Novel Food fast-track dossiers offer white-space entry into European functional food fortification. Target cosmetic anti-inflammatory protocols in German and French laboratories as the most penetrable application segment. Deploy turnkey private-label encapsulation services to capture direct-to-consumer brand demand in North American online channels. For Investors and Strategic Acquirers: India-based integrated processors with captive cultivation and supercritical CO2 infrastructure represent the priority acquisition archetype. Long-term viability hinges on pharmaceutical channel migration versus nutraceutical margin compression. Monitor synthetic thymoquinone production method advancement as inflection signal for botanical sourcing displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | German-engineered systems preserve volatile oil integrity for pharmaceutical acceptance. |
| Phytosome Delivery Technology Licensing | Indena's liposomal encapsulation enhances bioavailability for therapeutic applications. |
| Backward Integration into Cultivation | Madhya Pradesh seed procurement anchors margin control for Indian export processors. |
| Drug-Master-File Preparation | EMA herbal medicinal product status unlocks prescription-adjacent pricing premiums. |
| Cosmetic Channel Partnership | Parisian skin care laboratories accelerate incorporation into anti-inflammatory protocols. |
Research Methodology
A standing panel of extraction facility managers, pharmaceutical procurement leads, Ayurvedic formulators, and regulatory affairs specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from EMA quality guideline updates, FSSAI functional food regulation filings, DGFT export incentive disclosures, and pharmacopeial monograph developments. Bottom-up capacity assessments across Gujarat and Rajasthan processing clusters were triangulated against top-down demand estimates from North American nutraceutical brands.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product format, application channel, processing method, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating thymoquinone standardization adoption rates, EMA compliance investment cycles, and India PLI scheme capacity buildout timelines. Industry-specific inputs included supercritical CO2 equipment installation data and synthetic thymoquinone research publication velocity.
The analysis sits within stated boundaries; outcomes outside EMA guideline stability, seed harvest yield consistency, or pharmaceutical formulation pipeline advancement would require recalibration. Forecasts reflect documented assumptions about regulatory pathway timelines and technology substitution curves. Synthetic production method maturation, climatic disruption in Uttar Pradesh cultivation zones, or EFSA Novel Food pathway acceleration represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Wild Yam Powder Market
Extracts
Hibiscus Flower Powder Market
Extracts
Global Azadirachtin Market
Extracts
Industrial Extractor Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
Phytochemicals Market
Extracts
Aloe Vera Extract Market
Extracts
Gelatin Hydrolysates Market
Extracts
Organic Extracts Market
Extracts
Pectinase Market
Extracts
Irish Moss Market
Extracts
Ovalbumin Powder Market
Extracts
CO2 Extract Market
Extracts
Asia-Pacific Spirulina Extract Market
Extracts
Glycerol Extracts Market
Extracts
Hesperidin Market