
 UK Ecommerce Market | 2026-2036
UK Ecommerce Market Size, Share, and Industry Trends Forecast 2026-2036
UK Ecommerce Market Insights
Multi-source fulfillment is recalibrating how UK retailers balance owned warehouses against third-party logistics networks. Amazon UK dominates last-mile infrastructure through captive delivery stations. Ocado leverages proprietary automated warehouse robotics to sustain premium grocery positioning. ASOS competes on fast-fashion turnaround through in-house sourcing control.
UK ecommerce denotes commercial transactions conducted through internet-enabled platforms, encompassing web-based storefronts, mobile applications, and integrated payment gateways that process digital orders for physical or digital goods. The ecosystem relies on real-time inventory APIs, PCI-DSS compliant encryption protocols, and algorithmic recommendation engines to match buyers with sellers. Apparel and electronics anchor transaction volumes, though beauty products represent the fastest-expanding margin pool as subscription replenishment models take hold. Online marketplaces capture the largest share of consumer visits, while buy now pay later integration across brand websites is restructuring checkout conversion economics.
The UK Online Safety Bill, enforced by Ofcom, imposes duty-of-care obligations on platforms regarding fraudulent seller listings and consumer harm. The Competition and Markets Authority scrutinizes marketplace fee structures for anti-competitive effects. GDPR and the UK Data Protection Act govern cross-border data flows underlying personalized recommendation engines. Stakeholders must weigh regulatory compliance investments against the revenue upside of embedded finance and social commerce checkout features.
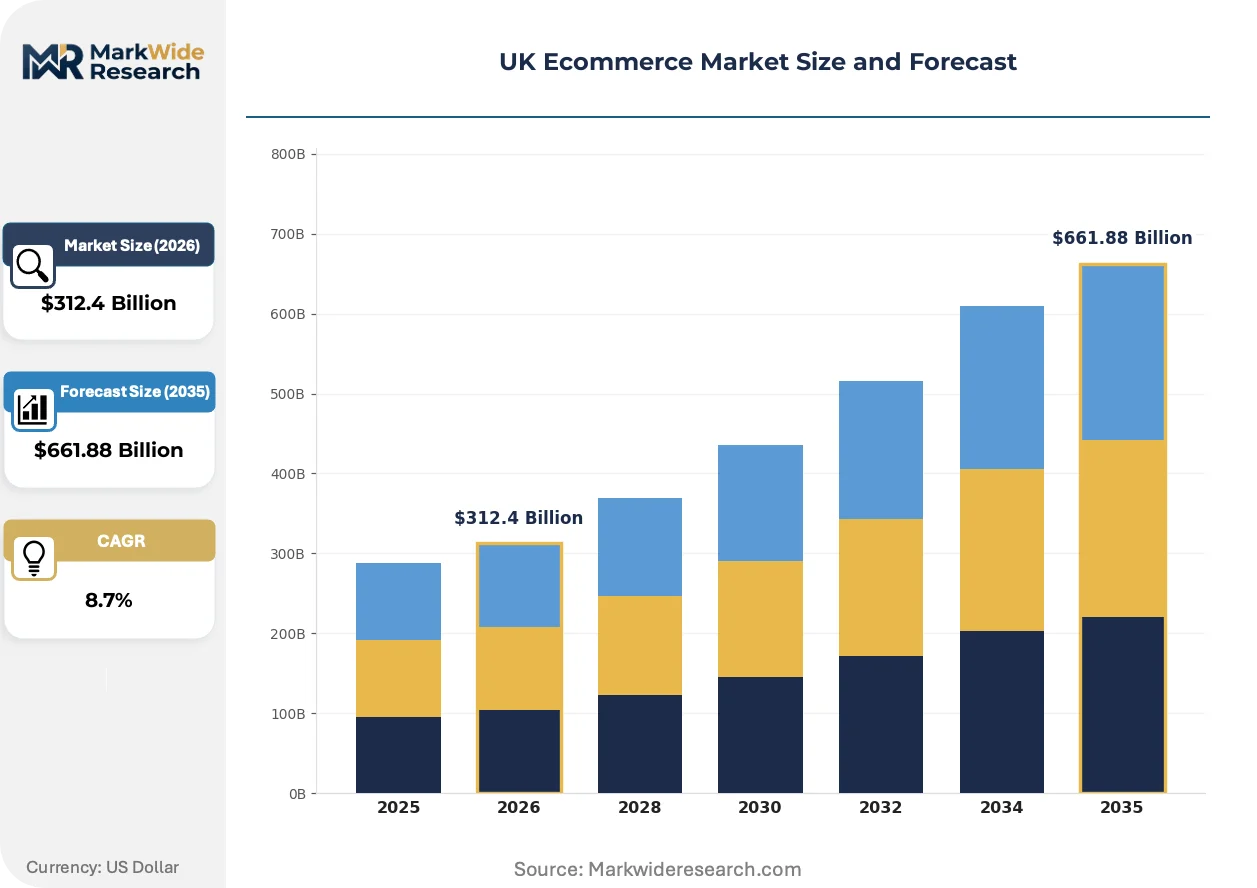
Market Dynamics
The UK Ecommerce Market is restructuring around same-day fulfillment density, where automated micro-fulfillment centers within Greater London's M25 corridor are compressing delivery windows and raising fixed-cost barriers for national entrants.
Growth Catalysts
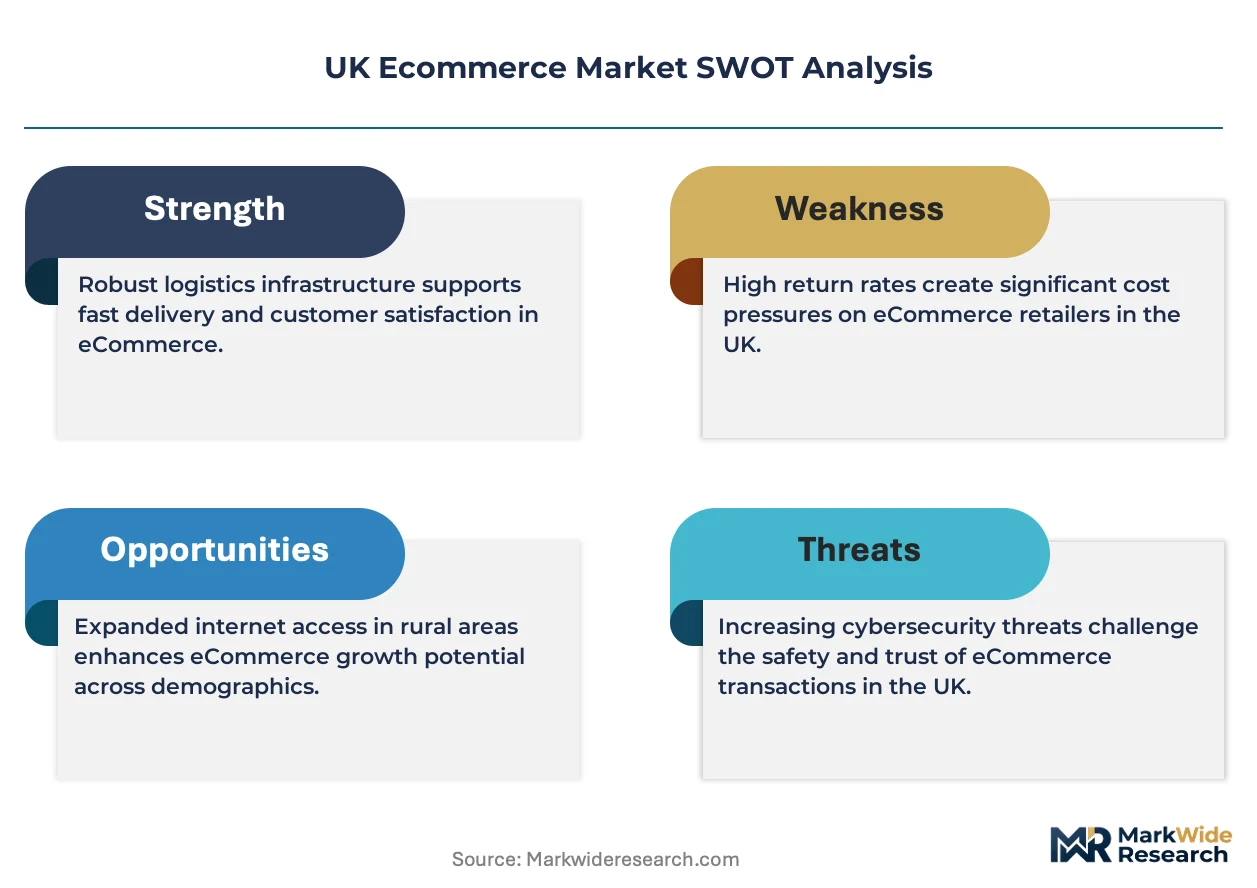
- Ofcom's Online Safety Bill enforcement:Duty-of-care obligations on fraudulent seller listings are forcing platform investments in verification infrastructure, indirectly benefiting compliant third-party merchants through trust premiums.
- Grocery subscription replenishment:UK households are locking into recurring delivery slots for ambient and fresh categories, embedding predictable demand into fulfillment network planning.
- Automated warehouse robotics:Proprietary picking systems are reducing unit labor costs in ambient grocery, enabling margin expansion in categories previously constrained by wage inflation.
Market Restraints
- Last-mile labor cost volatility:Driver availability fluctuations in Greater London and the Southeast are forcing surge pricing during peak windows, eroding unit economics on low-margin grocery orders.
- Payment processor concentration:Heavy reliance on a narrow set of PCI-DSS certified gateway providers creates systemic vulnerability during peak transaction periods such as Black Friday.
- GDPR compliance friction:Cross-border data restrictions on personalized recommendation engines limit algorithmic sophistication for UK retailers serving EU customers post-Brexit.
Strategic Opportunities
- Northern England logistics corridors:Manchester and Leeds present underexploited same-day delivery catchments with lower real estate costs than Greater London saturation zones.
- Embedded finance integration:Buy-now-pay-later checkout features are restructuring conversion economics for apparel and electronics, capturing incremental basket value from credit-constrained segments.
- Beauty subscription models:Replenishment automation for skincare and cosmetics represents the fastest-expanding margin pool as UK consumers lock into predictable consumption patterns.
Industry Challenges
- Warehouse automation talent scarcity:Robotics maintenance engineers and fulfillment software specialists command premium wages, constraining rollout velocity for mid-tier retailers.
- Legacy inventory API integration:Real-time stock synchronization between owned warehouses and third-party logistics networks requires expensive middleware development for established multichannel operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Ecommerce Market |
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $661.88 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Electronics, Home Goods, Beauty Products Customer Type: Individual Consumers, Small Businesses, Corporates, Educational Institutions Sales Channel: Online Marketplaces, Brand Websites, Social Media Shops, Subscription Services Payment Method: Credit Cards, Digital Wallets, Bank Transfers, Buy Now Pay Later |
| Companies Covered | Tesco Online, Ocado, Amazon UK, Zalando UK, OnBuy, eBay UK, Argos, Etsy UK, ASOS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Ecommerce Market Trends and Innovations
Three forces are actively restructuring UK ecommerce: algorithmic personalization tightening around GDPR constraints, fulfillment automation compressing labor dependency, and embedded finance rewiring checkout conversion paths.
Automated micro-fulfillment centers deploying robotic picking and AI-driven slot optimization are electrifying last-mile economics in Greater London. Grocery specialists and fast-fashion operators are adopting these systems at accelerated cadence to defend margin against wage inflation. The structural consequence is a bifurcation between capital-rich platforms capable of captive infrastructure and asset-light marketplace sellers dependent on third-party logistics pricing.
Ofcom's phased enforcement of the Online Safety Bill is mandating proactive fraud detection and age-verification infrastructure across UK-hosted marketplaces. The industrial consequence is a compliance cost wedge favoring large platforms with dedicated trust-and-safety teams over smaller merchant aggregators. Apparel and electronics categories with high return fraud incidence are responding fastest, deploying automated seller verification and transaction monitoring systems.
Subscription replenishment models are displacing transactional purchasing in beauty and personal care categories across UK households. Direct-to-consumer brands with proprietary apps are capturing recurring revenue previously flowing through retail intermediaries. This pattern is most visible in Greater London and the Southeast, where delivery density supports economically viable replenishment cycles.
UK Ecommerce Market Segmentation
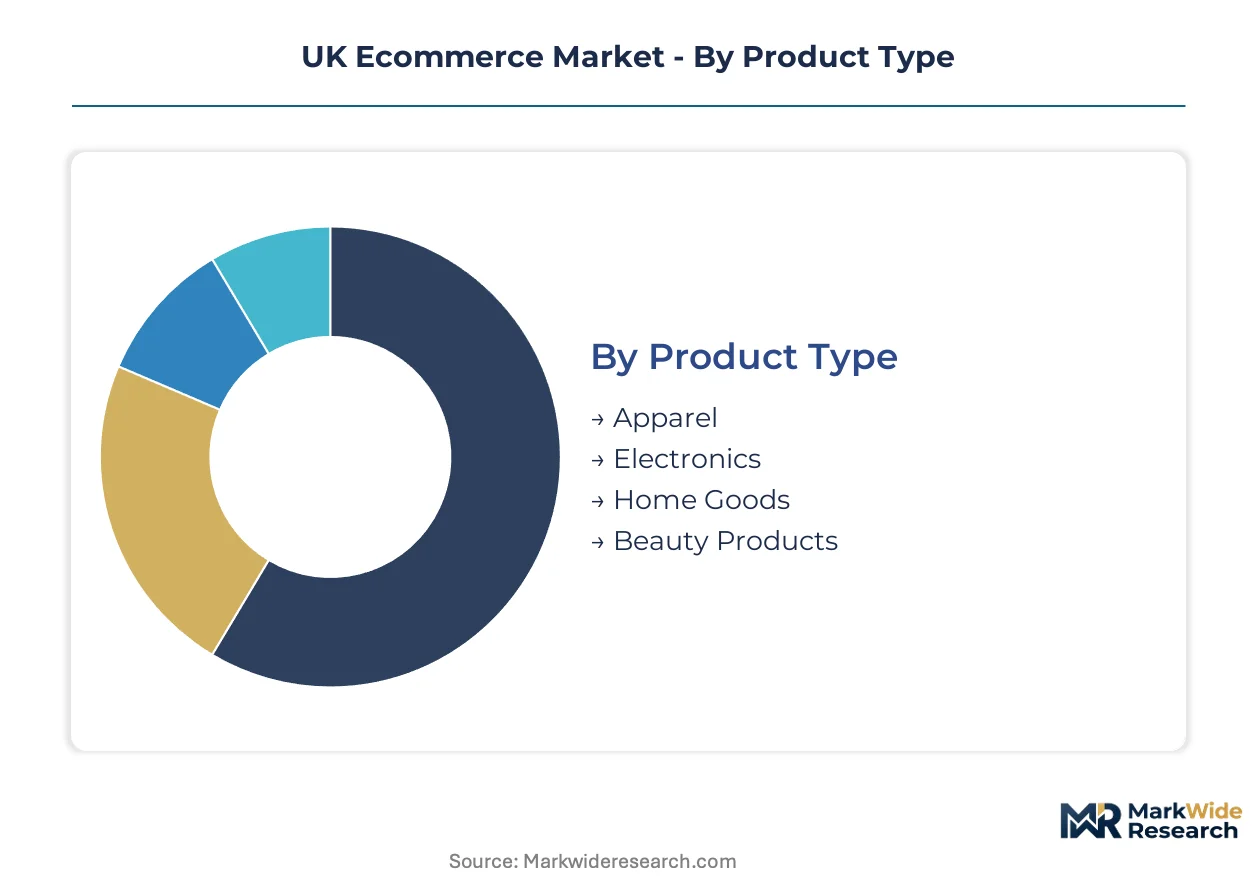
UK ecommerce segmentation reveals how regulatory obligations, fulfillment economics, and payment infrastructure reshape competitive positioning across product categories and customer types. Distinct compliance burdens and margin profiles separate segments capable of absorbing Ofcom verification costs from those dependent on third-party infrastructure.
Product Type:
GDPR data handling and Online Safety Bill seller verification requirements vary sharply across product categories, with electronics facing stricter conformity documentation and beauty products navigating ingredient disclosure rules.
- Apparel:Fast-fashion SKUs with high return rates demand sophisticated reverse-logistics networks. Demand concentrates in Greater London's same-day corridors where ASOS and Boohoo compete on turnaround velocity, though margin pressure from free returns policies erodes profitability on lower basket values.
- Electronics:High-value items requiring CE marking and WEEE compliance documentation. Demand clusters among individual consumers in the Southeast, constrained by PCI-DSS payment security investments required for high-ticket transactions.
- Home Goods:Bulky items with compressed margins dependent on third-party delivery pricing.
- Beauty Products:Subscription replenishment models capturing recurring revenue through proprietary apps.
Leading the category by volume: Apparel. Growing fastest: Beauty Products.
Customer Type:
Procurement scale and invoice complexity separate segments, with corporates and educational institutions demanding VAT-compliant purchase order systems that smaller merchants struggle to support.
- Individual Consumers:Transactional purchasers driving marketplace traffic through mobile-first discovery. Greater London households exhibit highest buy-now-pay-later adoption rates for discretionary purchases, embedding credit risk into merchant fee structures.
- Small Businesses:B2B procurement through Amazon Business and specialist wholesalers requiring trade account verification. Demand concentrates in Northern England logistics corridors where real estate costs enable competitive pricing on bulk orders.
- Corporates:Volume purchasers with negotiated contract terms and dedicated account management.
- Educational Institutions:Procurement governed by public sector tendering rules with extended payment cycles.
Volume leadership: Individual Consumers. Steepest expansion trajectory: Small Businesses.
Sales Channel:
Fulfillment control and customer data ownership divide channels, with captive infrastructure enabling margin capture that marketplace-dependent sellers sacrifice for traffic access.
- Online Marketplaces:Aggregator platforms capturing consumer visits through algorithmic search and recommendation engines. Amazon UK dominates through captive delivery stations, though Ofcom's duty-of-care obligations are forcing verification infrastructure investments that favor scaled operators.
- Brand Websites:Direct-to-consumer channels preserving first-party data for personalization. Ocado's proprietary grocery platform exemplifies vertical control, though GDPR restrictions on cross-border data flows limit algorithmic sophistication for EU customers.
- Social Media Shops:Checkout integration within Meta and TikTok environments reducing friction for impulse purchases.
- Subscription Services:Recurring revenue models embedding predictable demand into fulfillment planning.
Traffic concentration: Online Marketplaces. Gaining share fastest: Subscription Services.
Payment Method:
PCI-DSS certification requirements and fraud liability allocation structure competitive dynamics, with concentrated gateway providers creating systemic vulnerability during peak transaction windows.
- Credit Cards:Dominant payment rail for high-value transactions with established chargeback protections. Corporate procurement in the Southeast relies heavily on commercial card programs, though interchange fees compress margins on low-ticket purchases.
- Digital Wallets:Apple Pay and Google Pay reducing checkout friction for mobile-first apparel purchases. Greater London consumers show highest adoption rates, enabled by NFC infrastructure density in urban retail environments.
- Bank Transfers:Preferred for B2B invoices with extended settlement timelines.
- Buy Now Pay Later:Klarna and Clearpay restructuring conversion economics for credit-constrained segments.
Transaction volume leader: Credit Cards. Expanding most quickly: Buy Now Pay Later.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics real estate density within Greater London's M25 corridor anchors UK ecommerce infrastructure investment, with automated fulfillment nodes radiating outward through regional distribution networks.
London and the Southeast
Same-day delivery demand concentrates in Greater London's urban core, where Ocado operates proprietary automated warehouses. Ofcom's Online Safety Bill enforcement mandates seller verification infrastructure investments. Fulfillment automation clusters in Enfield and Erith, compressing delivery windows for grocery and fast-fashion orders.
Midlands
Birmingham and Leicester serve as central distribution hubs connecting northern and southern markets. The region benefits from lower industrial real estate costs than London. Amazon UK operates major fulfillment centers in Coventry and Rugeley, anchoring national delivery networks with rail-connected logistics corridors.
North England
Manchester and Leeds present underexploited same-day delivery catchments with expanding logistics development. The Competition and Markets Authority scrutinizes marketplace fee structures affecting regional merchant participation. Automated micro-fulfillment pilots in Trafford Park test grocery robotics outside capital markets.
Scotland
Edinburgh and Glasgow sustain distinct consumer demand patterns with higher delivery cost thresholds. GDPR compliance friction affects cross-border data flows for personalized recommendation engines serving Scottish consumers. Distribution centers in Motherwell and Eurocentral link Scottish retailers to English fulfillment networks.
Wales
South Wales corridors through Cardiff and Newport function as logistics bridges to southwest England. The region exhibits lower ecommerce penetration rates than English counterparts, creating expansion opportunities for subscription replenishment models. Third-party logistics providers concentrate in Magor and Wentloog near Severn crossings.
UK Ecommerce Market Competitive Landscape
Global majors compete with regional champions across fulfillment infrastructure ownership, where captive delivery networks separate scaled platforms from marketplace-dependent merchants. The UK market exhibits tiered concentration with dominant generalists, vertical specialists, and niche aggregators coexisting. Three archetypes prevail: technology-integrated grocers with proprietary robotics, fast-fashion operators controlling in-house sourcing, and marketplace platforms leveraging third-party logistics density. Competitive moves center on warehouse automation deployment and embedded finance integration at checkout.
Among UK-based operators, Ocado and ASOS exemplify vertical control strategies, while Amazon UK anchors the marketplace tier through captive last-mile infrastructure. Ocado represents the technology-integrated grocer archetype with automated warehouse systems. ASOS occupies the fast-fashion specialist position with in-house sourcing control. Amazon UK sits within the platform aggregator tier, dominating consumer visits through algorithmic recommendation engines and fulfillment network density.
| Leading Market Players |
|---|
| Tesco Online |
| Ocado |
| Amazon UK |
| Zalando UK |
| OnBuy |
| eBay UK |
| Argos |
| Etsy UK |
| ASOS |
| Others |
Pricing and Supply Chain Analysis
Individual consumers concentrated in Greater London's same-day delivery corridors anchor the dominant subscription-plus-transactional hybrid pricing model, where grocery replenishment services bundle fixed delivery slots against per-order fast-fashion markups.
Pricing Analysis
Service bundling separates subscription-inclusive grocery pricing from unbundled per-order apparel and electronics transactions. Three-tier pricing structure across premium, standard, and economy levels reflects fulfillment speed guarantees and brand positioning, with Ocado's proprietary robotics commanding subscription premiums against Amazon's marketplace fee compression. Pricing pressure stems from last-mile labor cost volatility in the Southeast, eroding margins on low-ticket grocery orders. Small businesses in Northern England corridors exhibit highest price sensitivity due to competitive third-party logistics pricing, while corporate procurement shows lowest sensitivity through negotiated contract terms.
Supply Chain Analysis
Post-Brexit domestic-content considerations and Ofcom's verification mandates are reshaping seller onboarding and fulfillment node placement. Warehouse robotics and automated picking systems draw from German engineering suppliers and Chinese component manufacturers, with software integration anchored in domestic technology vendors. Single-source vulnerability concentrates in PCI-DSS certified payment gateway providers, creating systemic risk during peak transaction windows. Distribution runs through captive Amazon delivery stations in Greater London, third-party logistics networks in the Midlands, and emerging micro-fulfillment pilots in Northern England corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK ecommerce market sits in a technology-transition phase where automated warehouse robotics displaces legacy manual fulfillment systems, compressing labor dependency and restructuring competitive economics.
For Market Incumbents: Lock in proprietary fulfillment infrastructure through accelerated robotics deployment in Greater London saturation zones, defending against margin erosion from wage inflation. Ocado's automated warehouse model demonstrates how vertical control over picking systems preserves premium positioning. Counter the threat from embedded finance disruptors by integrating buy-now-pay-later features at owned-checkout touchpoints.
For New Entrants and Emerging Players: Small businesses in Northern England logistics corridors represent the most penetrable buyer archetype, underserved by same-day delivery density and receptive to competitive bulk pricing. Target Manchester and Leeds catchments with automated micro-fulfillment pilots testing grocery robotics outside capital markets. Establish go-to-market traction through trade account verification systems that simplify B2B procurement complexity.
For Investors and Strategic Acquirers: The window for entry favors technology-integrated fulfillment specialists with proprietary robotics IP and established Northern England real estate positions. Long-term viability hinges on five-to-ten year automation deployment runways as labor cost volatility intensifies. Watch for inflection signals in Ofcom enforcement patterns affecting marketplace verification cost burdens and compliance wedge dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Warehouse Deployment | Proprietary robotics at Ocado's Erith facility compress unit labor costs in ambient grocery picking. |
| Embedded Finance Integration | Klarna checkout features at ASOS capture incremental basket value from credit-constrained Greater London households. |
| Regional Logistics Expansion | Amazon UK's Coventry fulfillment center anchors national delivery networks with rail-connected Midlands corridors. |
| Subscription Service Buildout | Beauty replenishment apps embed predictable demand into fulfillment planning for direct-to-consumer brands. |
| Compliance Infrastructure Investment | Ofcom-mandated seller verification systems at eBay UK create trust premiums benefiting compliant third-party merchants. |
Research Methodology
Document review covered Ofcom regulatory filings, Competition and Markets Authority decisions, and customs trade data, complemented by interviews with fulfillment network directors at major grocery and fast-fashion operators, trust-and-safety leads at marketplace platforms, procurement managers at third-party logistics providers, and payment gateway compliance officers. Secondary validation drew from SEC filings of UK-listed ecommerce operators, real estate investment trust logistics disclosures, and retail audit data from Nielsen. Bottom-up merchant volume estimates triangulated against top-down consumer expenditure surveys.
Segment-level projections across product type, customer type, sales channel, and payment method dimensions were generated through econometric modeling of fulfillment cost curves, regulatory compliance burden trajectories, and embedded finance adoption patterns. CAGRs were derived from logistic diffusion curves fitted to same-day delivery penetration rates and subscription service uptake timelines. The analytical framework incorporated warehouse automation deployment schedules, PCI-DSS certification pipeline constraints, and GDPR cross-border data friction coefficients.
Revisions become necessary when Ofcom enforcement intensity shifts, automated robotics talent scarcity accelerates wage premiums, or payment processor concentration triggers systemic reliability failures. Forecasts reflect documented assumptions regarding fulfillment density economics and regulatory compliance cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Egypt E-Commerce Market
E-Commerce Solutions
Netherlands E-Commerce Market
E-Commerce Solutions
Alcohol E-Commerce Market
E-Commerce Solutions
France E-Commerce Market
E-Commerce Solutions
Social Commerce Market
E-Commerce Solutions
Saudi Arabia Delivery Apps Market
E-Commerce Solutions
United Arab Emirates E-Commerce Market
E-Commerce Solutions
US SMS Marketing Market
E-Commerce Solutions
Greece E-Commerce Market
E-Commerce Solutions
Global B2B E-Commerce Market
E-Commerce Solutions
Germany E-Commerce Market
E-Commerce Solutions
Quick Commerce Market
E-Commerce Solutions
Asia-Pacific FMCG B2B E-Commerce Market
E-Commerce Solutions
United Kingdom Same Day Delivery Market
E-Commerce Solutions
Africa E-Commerce Market
E-Commerce Solutions
Global Subscription E-Commerce Platform Market