
 E-Commerce Software Market | 2026-2036
E-Commerce Software Market Size, Share, and Industry Trends Forecast 2026-2036
E-Commerce Software Market Intelligence
Platform sourcing is realigning from single-vendor lock-in toward composable, multi-provider architectures. Shopify anchors the mid-market with its app ecosystem and native payment rails. Salesforce competes through its CRM-embedded commerce cloud, while commercetools differentiates via API-first modularity for enterprise headless deployments.
E-commerce software encompasses the digital infrastructure enabling online transaction processing, inventory synchronization, and multi-channel order orchestration through cloud-native or on-premise application layers. Cloud-based deployment leads in new installations due to elastic scaling and reduced capital overhead, though hybrid configurations retain share among large corporations with legacy ERP dependencies. B2B customer type segments are expanding fastest as manufacturers and distributors replace EDI portals with self-service digital storefronts.
FCC guidelines govern payment data transmission standards for US-based platforms, while GDPR and the EU AI Act shape cross-border data handling and automated pricing transparency requirements in Europe. India's BIS certification mandates and the RBI's digital payment security framework are tightening vendor compliance for SaaS providers serving domestic merchants. Stakeholders must track how fragmented privacy regimes and emerging AI disclosure rules will alter platform architecture decisions and geographic rollout sequencing.
Market Dynamics
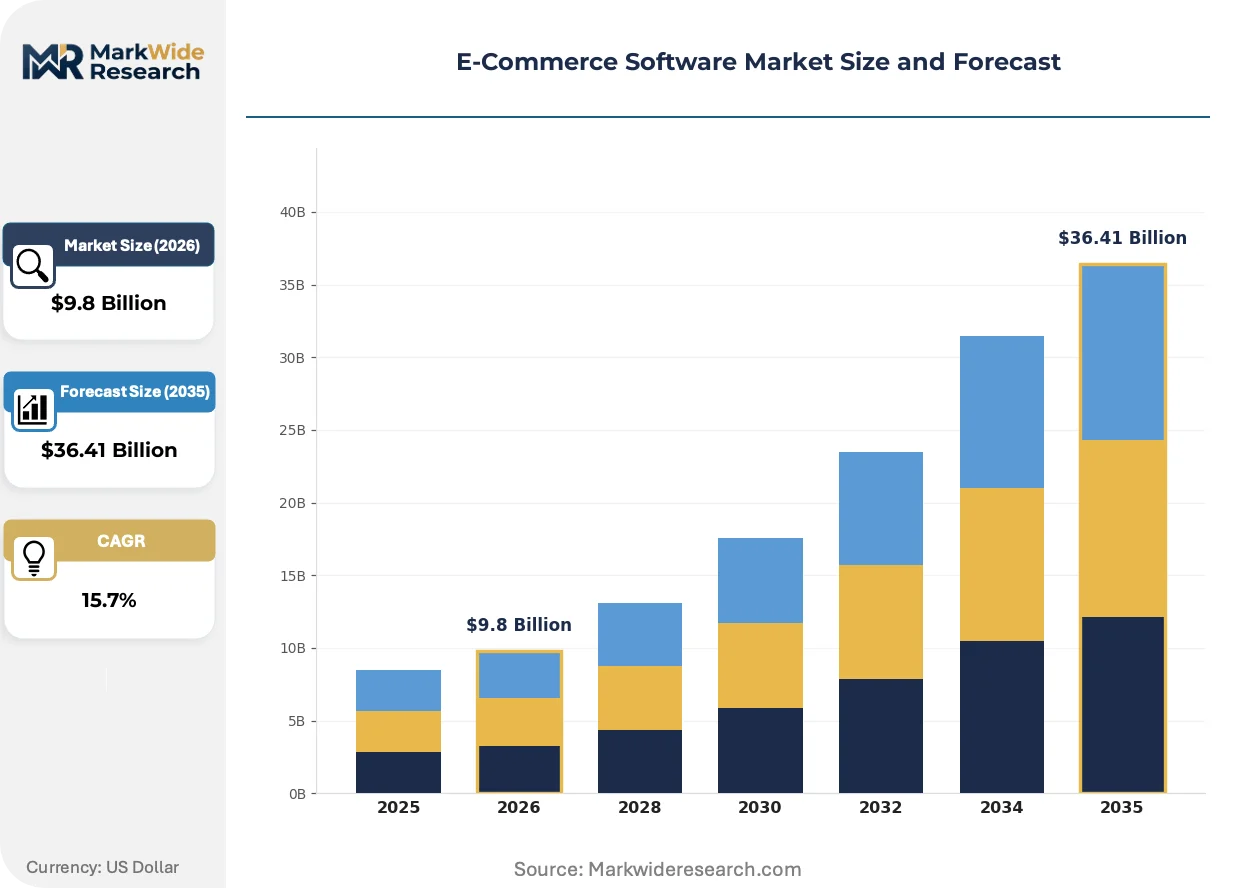
Composable commerce architectures are dismantling monolithic platform dominance as mid-market retailers demand API-first flexibility over single-vendor lock-in. This structural shift forces vendors to modularize core functions while maintaining interoperability with legacy ERP systems.
Growth Catalysts
- India's Digital Payment Infrastructure:The RBI's unified payments interface and PLI scheme for software exports are accelerating merchant onboarding at scale across tier-2 and tier-3 cities.
- GDPR Certification Mandates:European data residency requirements are compelling platform vendors to invest in regional cloud regions, creating compliance-driven upgrade cycles among existing customers.
- Headless Commerce APIs:Decoupled frontend-backend architectures are enabling manufacturers to deploy B2B self-service portals without forklift ERP replacements.
Market Restraints
- Cloud Concentration Risk:Hyperscaler dependency for elastic compute creates vendor lock-in and egress cost volatility for mid-market retailers with thin margins.
- Fragmented Privacy Regimes:Divergent state-level laws across US jurisdictions multiply compliance engineering overhead, particularly for SaaS providers serving cross-border merchants.
- Legacy ERP Entrenchment:On-premise inventory systems with decades of customization resist API-based synchronization, delaying unified commerce deployments.
Strategic Opportunities
- B2B Marketplace Convergence:Industrial distributors in Germany and Japan are replacing EDI portals with digital storefronts, opening greenfield deployments for API-first platforms.
- EU AI Act Transparency:Automated pricing algorithm disclosure requirements create demand for explainable AI modules as premium add-ons.
- Embedded Finance Integration:Native lending and insurance APIs within checkout flows unlock new revenue streams beyond subscription SaaS models.
Industry Challenges
- Composable Skill Scarcity:Enterprise IT teams lack expertise in microservices orchestration and event-driven architecture, slowing headless implementations.
- Multi-Cloud Integration Complexity:Stitching best-of-breed components across payment, inventory, and CRM systems requires specialized integration engineering that strains mid-market IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Commerce Software Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $36.41 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shopping Cart, Payment Gateway, Analytics, Inventory Management Deployment: Cloud-based, On-premise, Hybrid, SaaS End User: Small Businesses, Medium Enterprises, Large Corporations, Startups Customer Type: B2B, B2C, C2C, D2C |
| Companies Covered | Shopify, Adobe, Salesforce, SAP, BigCommerce, Oracle, VTEX, HCL, commercetools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Commerce Software Market Strategic Shifts & Innovations
Artificial intelligence is penetrating transaction processing layers, shifting competitive advantage from feature breadth toward predictive automation and real-time personalization engines.
Generative AI copilots are rewriting merchant operations by automating product description generation, customer service responses, and inventory forecasting. Mid-market apparel retailers are deploying these tools fastest, compressing content production cycles from weeks to hours. This capability is rewriting how smaller merchants compete with enterprise-scale marketing operations without proportional headcount expansion.
The EU AI Act's risk-based classification system is mandating algorithmic audits for automated pricing and recommendation engines. Vendors serving European merchants must now document training data provenance and decision logic, raising engineering costs but creating differentiation for compliant platforms. German and French retailers are prioritizing vendors with pre-certified transparency modules to accelerate procurement.
Merchant buying committees are consolidating vendor relationships around unified commerce stacks rather than point solutions. B2B manufacturers in the United States are replacing fragmented channel management tools with single-platform deployments spanning direct, distributor, and marketplace sales. This consolidation is most visible among industrial distributors seeking to collapse EDI, portal, and e-commerce investments into one architecture.
E-Commerce Software Market Segmentation
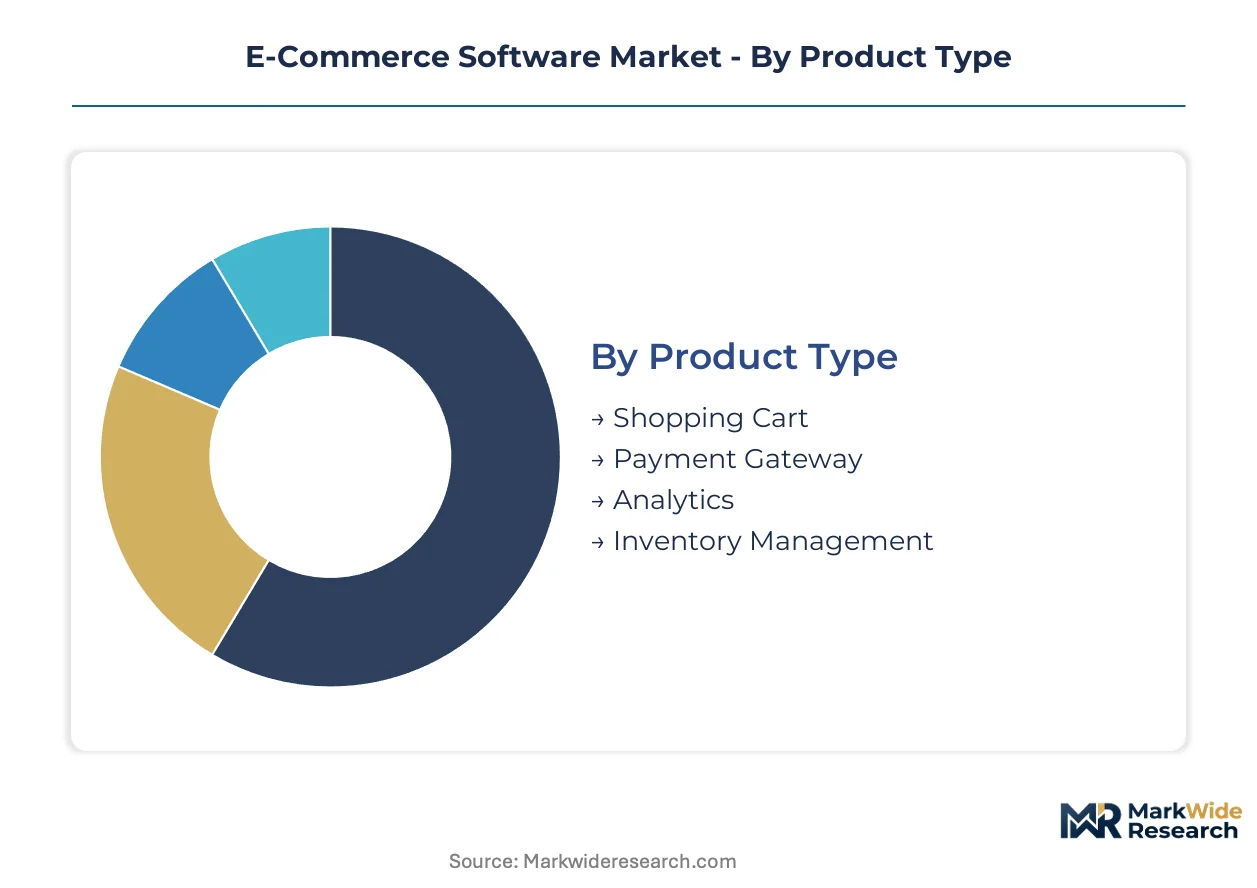
E-commerce software segmentation reveals how platform architectures align with merchant maturity and transaction complexity. Upgrade cycles vary dramatically across deployment modes and customer types, with legacy system replacement driving the largest contract values.
Product Type:
Platform refreshes concentrate where transaction volumes strain existing infrastructure, forcing modular replacements rather than full-stack overhauls.
- Shopping Cart:Core transaction orchestration layer handling checkout flows, tax calculation, and shipping rule enforcement. Mid-market apparel retailers in Germany and France are prioritizing cart modules with built-in GDPR consent management and EU AI Act-compliant recommendation engines.
- Payment Gateway:Encrypted transaction processing layer integrating card networks, digital wallets, and buy-now-pay-later services. India's tier-2 merchant expansion under RBI's UPI framework is concentrating demand for gateways with native rupee settlement and BIS-certified data localization.
- Analytics:Customer behavior tracking and conversion funnel visualization tools. Manufacturing distributors leverage these for B2B procurement pattern identification.
- Inventory Management:Real-time stock synchronization across warehouse, marketplace, and retail channels. Hybrid deployments dominate among large corporations with legacy ERP dependencies.
Payment Gateway sits at the top of the volume ranking, with Inventory Management climbing the fastest as unified commerce consolidation accelerates.
Deployment:
Cost tier structures separate capital-light subscription models from infrastructure-heavy owned deployments, with migration patterns revealing IT budget elasticity.
- Cloud-based:Elastic compute architecture with usage-based billing and automatic scaling. Small businesses and startups across Brazil and Southeast Asia default to these configurations to avoid data center capital expenditure.
- On-premise:Self-hosted server infrastructure with direct hardware control. Large corporations in Japan and Germany retain these for sensitive B2B contract data under METI and national data sovereignty frameworks.
- Hybrid:Split architecture keeping transactional data on-premise while leveraging cloud elasticity for frontend scaling. Financial services merchants in Singapore and Switzerland favor this for regulatory compartmentalization.
- SaaS:Fully managed subscription platforms with vendor-controlled infrastructure updates. Medium enterprises represent the core adoption cohort as they outgrow entry-level tools.
SaaS commands the largest installed base, though Hybrid configurations are expanding most quickly among compliance-sensitive sectors.
End User:
Customer type maturity determines feature depth requirements, with procurement sophistication scaling from self-service onboarding to custom integration engineering.
- Small Businesses:Merchants with sub-$10 million annual revenue requiring template-driven storefronts and minimal IT overhead. These users dominate Shopify's merchant base in Canada and Australia.
- Medium Enterprises:Regional retailers and manufacturers with dedicated e-commerce teams and ERP integration needs. This segment drives composable commerce adoption as they outgrow single-vendor limitations.
- Large Corporations:Multi-brand conglomerates with global tax complexity and marketplace diversification requirements. Their procurement cycles favor vendors with regional cloud presence and certified compliance modules.
- Startups:Venture-funded digital-native brands prioritizing speed-to-market over customization depth. Embedded finance integration and generative AI copilots rank highest in their platform evaluations.
Medium Enterprises anchor current platform revenue, while Startups are gaining share fastest as venture deployment into direct-to-consumer brands accelerates.
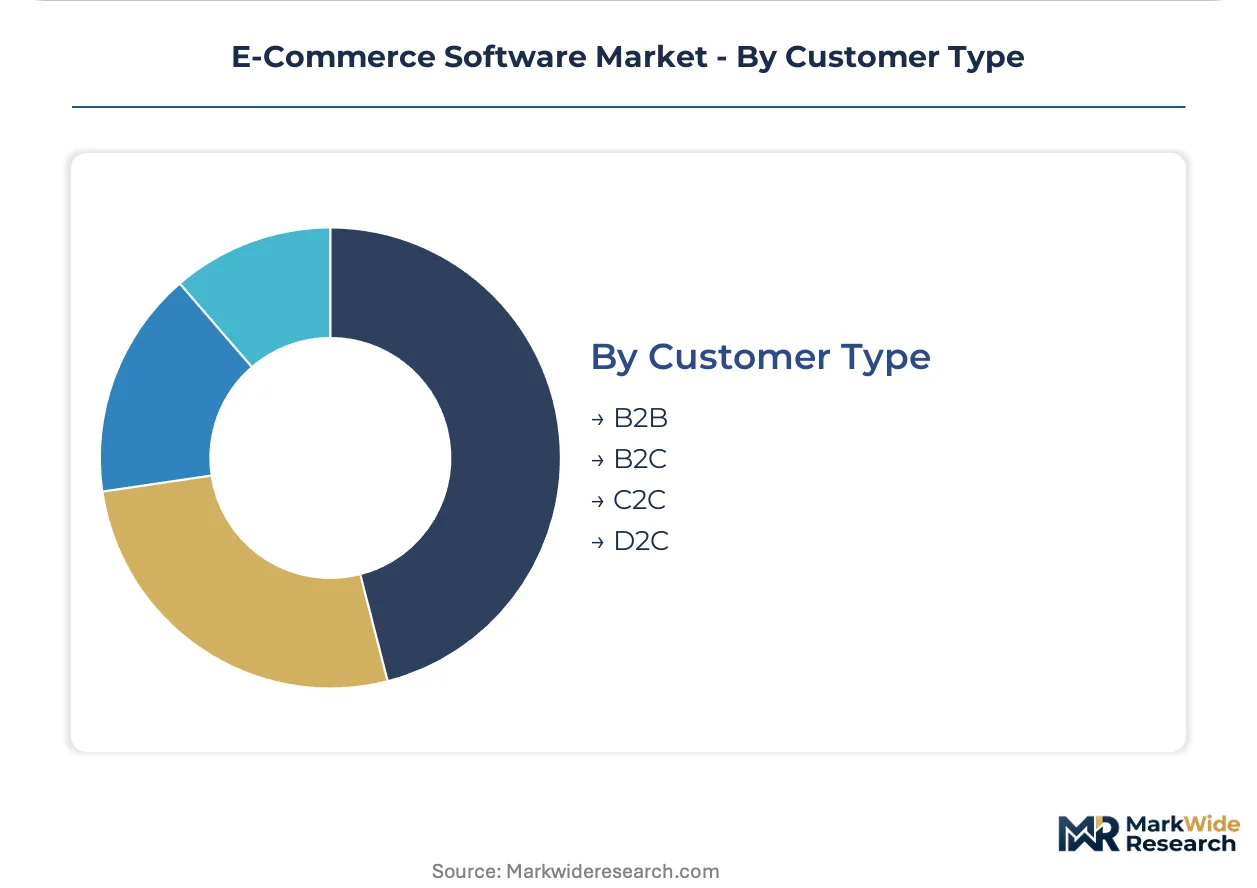
Customer Type:
Application complexity separates consumer-facing simplicity from B2B negotiation workflows, with margin profiles diverging sharply across transaction archetypes.
- B2B:Business procurement portals with contract pricing, approval workflows, and punchout catalog integration. Industrial distributors in the United States and Germany are replacing EDI systems with these self-service architectures.
- B2C:Direct consumer retail with recommendation engines, flash sale orchestration, and subscription management. This remains the largest addressable market by transaction volume.
- C2C:Peer-to-peer marketplace infrastructure enabling individual seller storefronts and escrow services. Platform fees concentrate in emerging markets with informal retail sectors.
- D2C:Brand-owned channels bypassing wholesale intermediaries with first-party data capture and community-building tools. Beauty and wellness brands in South Korea and France deploy these for margin recovery and customer relationship control.
B2C retains volume leadership, yet B2B demonstrates the steepest expansion trajectory as manufacturers digitize procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangalore's technology corridor anchors merchant onboarding velocity for e-commerce software, with India's tier-2 city expansion and Germany's industrial B2B digitization forming complementary demand poles across the analysis window.
United States
Mid-market retailers in Chicago and Austin are consolidating fragmented channel management tools into unified commerce stacks. State-level privacy laws across California, Virginia, and Colorado multiply compliance engineering overhead for SaaS providers. Dallas-Fort Worth hosts the largest concentration of B2B manufacturers replacing EDI portals with self-service digital storefronts.
Germany
Industrial distributors in Munich and Stuttgart are accelerating headless commerce deployments for procurement digitization. The EU AI Act's risk-based classification mandates algorithmic audits for automated pricing engines, compelling vendors to document training data provenance. The Rhine-Ruhr corridor concentrates demand for API-first platforms serving manufacturing supply chains.
India
Tier-2 and tier-3 cities including Jaipur, Indore, and Coimbatore are driving merchant onboarding at scale under RBI's unified payments interface. The BIS certification mandates and PLI scheme for software exports tighten vendor compliance for domestic SaaS providers. Bangalore's technology parks host the highest density of platform engineering talent for export-oriented development.
Japan
Large corporations in Tokyo and Osaka retain hybrid deployment configurations for sensitive B2B contract data under METI data sovereignty frameworks. On-premise inventory systems with decades of customization resist API-based synchronization, delaying unified commerce timelines. The Nagoya industrial cluster shows emerging demand for composable architectures among automotive parts distributors.
United Kingdom
Beauty and wellness D2C brands in London and Manchester deploy first-party data capture tools for margin recovery and customer relationship control. GDPR certification requirements drive regional cloud region investments from platform vendors serving British merchants. The Cambridge technology cluster incubates embedded finance integration startups targeting checkout flow monetization.
E-Commerce Software Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue API-first modularity and embedded finance adjacencies. The vendor base concentrates around three maturity tiers: legacy ERP-integrated suites, SaaS-native platforms with app ecosystems, and composable commerce specialists. Strategic archetypes include CRM-embedded commerce clouds, headless API providers, and payment-rail-integrated storefront builders. Dominant competitive moves encompass geographic cloud region expansion for compliance localization and generative AI copilot integration for merchant operations automation.
Within the SaaS-native tier, Shopify and BigCommerce exemplify platform builders with embedded payment ecosystems, while commercetools occupies a position among composable specialists serving enterprise headless deployments. Salesforce represents the CRM-embedded archetype, leveraging customer data infrastructure for commerce cloud differentiation. SAP and Oracle anchor the legacy-integrated tier, maintaining share among large corporations with decades of ERP customization. Adobe sits within the content-commerce convergence space, connecting creative tooling with transactional infrastructure.
| Leading Market Players |
|---|
| Shopify |
| Adobe |
| Salesforce |
| SAP |
| BigCommerce |
| Oracle |
| VTEX |
| HCL |
| commercetools |
| Others |
Cost & Logistics Intelligence
API-first modularization is compressing implementation timelines while fragmenting vendor concentration across hyperscaler-dependent infrastructure layers. This dual shift simultaneously reduces upfront capital barriers for mid-market retailers and concentrates backend compute pricing power among AWS, Azure, and Google Cloud. European GDPR-driven data residency requirements and India's BIS certification mandates are adding compliance premiums that reshape total cost of ownership calculations across deployment architectures.
Pricing Analysis
Input-cost pass-through from hyperscaler infrastructure feeds directly into SaaS subscription tiers, with elastic compute egress fees representing the fastest-growing cost component for mid-market retailers. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade compliance modules from self-service onboarding tools. Pricing pressure stems from cloud concentration risk as thin-margin retailers face egress cost volatility. Small businesses exhibit highest price sensitivity, while large corporations prioritize certified compliance over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for payment processing infrastructure mandate multi-cloud qualification among merchants with transaction volume exceeding RBI's tiered threshold guidelines. Engineering talent concentrates in India, Germany, and the United States, with Bangalore's technology corridor feeding export-oriented platform development. Raw material dependencies span open-source frameworks, proprietary AI training datasets, and hyperscaler compute credits. Single-source vulnerability runs through AWS's dominance in elastic scaling infrastructure. Distribution runs through direct vendor sales for enterprise deployments and self-service marketplaces for mid-market adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, where the EU AI Act's algorithmic audit mandates are creating sustained demand for transparency-certified platforms across European merchant procurement cycles.
For Market Incumbents: Lock in regional cloud presence to satisfy data residency requirements under GDPR and RBI frameworks before compliance premiums erode competitive positioning. Invest in generative AI copilot modules to defend against API-first specialists attacking the mid-market content automation layer. Prioritize embedded finance integration as a revenue diversification lever beyond subscription SaaS models. For New Entrants and Emerging Players: The price-point gap between premium enterprise suites and economy self-service tools opens white-space targeting for mid-market manufacturers in Germany's Rhine-Ruhr corridor and India's tier-2 cities. Composable commerce skill scarcity creates penetrable demand among industrial distributors replacing EDI portals. Lead with headless API deployments requiring minimal forklift ERP replacement to accelerate procurement cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid-deployment specialists with legacy ERP integration capabilities and certified compliance modules for European data residency. Long-term viability favors vendors with embedded payment rails and multi-cloud orchestration expertise. Watch merchant onboarding velocity in India's tier-2 cities as the primary inflection signal for platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Cloud Expansion | GDPR and RBI data residency mandates require localized infrastructure for merchant compliance. |
| Generative AI Copilot Integration | Mid-market apparel retailers in Germany deploy automated content tools to compress production cycles. |
| Embedded Finance Partnership | Native lending APIs within checkout flows unlock revenue streams beyond subscription SaaS models. |
| Headless API Platform Launch | Industrial distributors in the United States replace EDI portals with self-service procurement architectures. |
| Acquisition of Compliance Specialist | EU AI Act transparency modules create differentiation for pre-certified algorithmic audit vendors. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary conversations with CTOs, IT procurement officers, platform engineers, and integration specialists with secondary validation from SEC filings, hyperscaler capex disclosures, App Annie mobile commerce data, and EU regulatory filings. Bottom-up merchant onboarding velocity models and top-down TAM calculations triangulated across deployment mode, organization size, vertical specialization, and regional adoption pattern dimensions.
Comparable-period anchoring tied projection assumptions to historical platform migration cycles and compliance-driven upgrade patterns observed across the analysis window. Segmentation modeling incorporated deployment architecture, customer type maturity, integration complexity tier, and geographic regulatory cluster. CAGRs derived from elasticity-adjusted merchant acquisition curves and average revenue per user expansion trajectories specific to B2B self-service portal deployments.
Caveats apply where hyperscaler pricing volatility, fragmented state-level privacy law proliferation, or legacy ERP API resistance could materially shift the outlook. Forecasts reflect documented assumptions about merchant technology refresh cadence and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
North America FMCG B2B E-Commerce Market
E-Commerce Solutions
Philippines E-Commerce Market
E-Commerce Solutions
South Africa E-Commerce Market
E-Commerce Solutions
Digital Gift Cards (Egift Cards) Market
E-Commerce Solutions
Asia-Pacific Automotive E-Commerce Market
E-Commerce Solutions
Metaverse in E-Commerce Market
E-Commerce Solutions
Mobile Commerce Market
E-Commerce Solutions
Global Online Book Services Market
E-Commerce Solutions
United States E-Invoicing Market
E-Commerce Solutions
Online on-Demand Laundry Service Market
E-Commerce Solutions
India Digital Gift Card Market
E-Commerce Solutions
Cross Border Ecommerce Market
E-Commerce Solutions
Global Shopping Cart Market
E-Commerce Solutions
Czech Republic E-Commerce Market
E-Commerce Solutions
Norway E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Market