
 Global Chemical Software Market | 2026-2036
Global Chemical Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chemical Software Market Foresight
German chemical engineering houses is rebalancing software procurement toward predictive process modeling suites. Aspen Technology Inc. leverages decades of refinery optimization heritage to anchor its position in polymer simulation. Siemens AG competes through tight coupling between its process control hardware and digital twin environments. Dassault Systemes SE differentiates via molecular modeling capabilities inherited from BIOVIA's materials science lineage.
Chemical software denotes computational platforms that model reaction kinetics, thermodynamic equilibria, and transport phenomena using numerical solvers with equation-of-state parameters calibrated to industrial operating conditions. These systems enable virtual experimentation, regulatory batch documentation, and real-time yield optimization across continuous and batch processes. Process simulation solutions dominate current spending as petrochemical firms modernize distillation and reactor design workflows. Cloud-based deployment is expanding fastest among mid-sized specialty chemical producers seeking to avoid capital-intensive server infrastructure. Compliance management platforms command premium pricing due to embedded audit trails required by EMA and EPA submissions.
EPA mandates under TSCA and the EU REACH framework administered by ECHA are forcing reformulation of legacy inventory databases into structured substance-tracking architectures. FDA 21 CFR Part 11 compliance for electronic records further constrains software validation requirements in pharmaceutical manufacturing environments. Procurement teams must weigh interoperability against vendor lock-in as process simulation, laboratory information management, and regulatory reporting modules converge onto unified platforms.
Market Dynamics
Process simulation vendors face structural pressure from cloud-native deployment models that slash implementation timelines from months to weeks while fragmenting buyer power across mid-sized specialty chemical houses previously locked out of enterprise licensing tiers.
Growth Catalysts
- EU REACH substance registration deadlines:Chemical manufacturers must restructure legacy inventory databases into auditable digital architectures, forcing wholesale replacement of paper-based compliance workflows.
- Polymer simulation for advanced materials:Battery electrolyte developers and composite manufacturers demand molecular-scale modeling to accelerate formulation cycles.
- EPA TSCA reporting mandates:United States facilities face escalating documentation requirements for new chemical notifications, driving demand for automated regulatory batch documentation systems.
Market Restraints
- Cloud infrastructure dependency:Mid-sized producers confront recurring SaaS expenditures that compound over multi-year horizons versus depreciated on-premise servers.
- Specialized talent scarcity:Chemical engineering graduates with combined domain and computational expertise command premium compensation, constraining implementation velocity.
- Interoperability friction:Legacy DCS hardware from incumbent automation suppliers resists seamless API integration with third-party simulation platforms.
Strategic Opportunities
- India specialty chemical expansion:CDSCO-aligned pharmaceutical manufacturers seek validated electronic batch records as export volumes to regulated markets climb.
- Digital twin convergence with IoT sensor networks:Real-time yield optimization becomes feasible when process simulation layers ingest live temperature, pressure, and flow data.
- Sustainability-linked procurement incentives:EU Green Deal carbon accounting requirements create demand for embedded emissions tracking within formulation software.
Industry Challenges
- FDA 21 CFR Part 11 validation timelines:Pharmaceutical software deployments require extensive IQ/OQ/PQ documentation, stretching implementation cycles.
- Hybrid cloud integration complexity:Firms struggle to synchronize sensitive proprietary reaction kinetics data between on-premise secure enclaves and cloud compute nodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chemical Software Market |
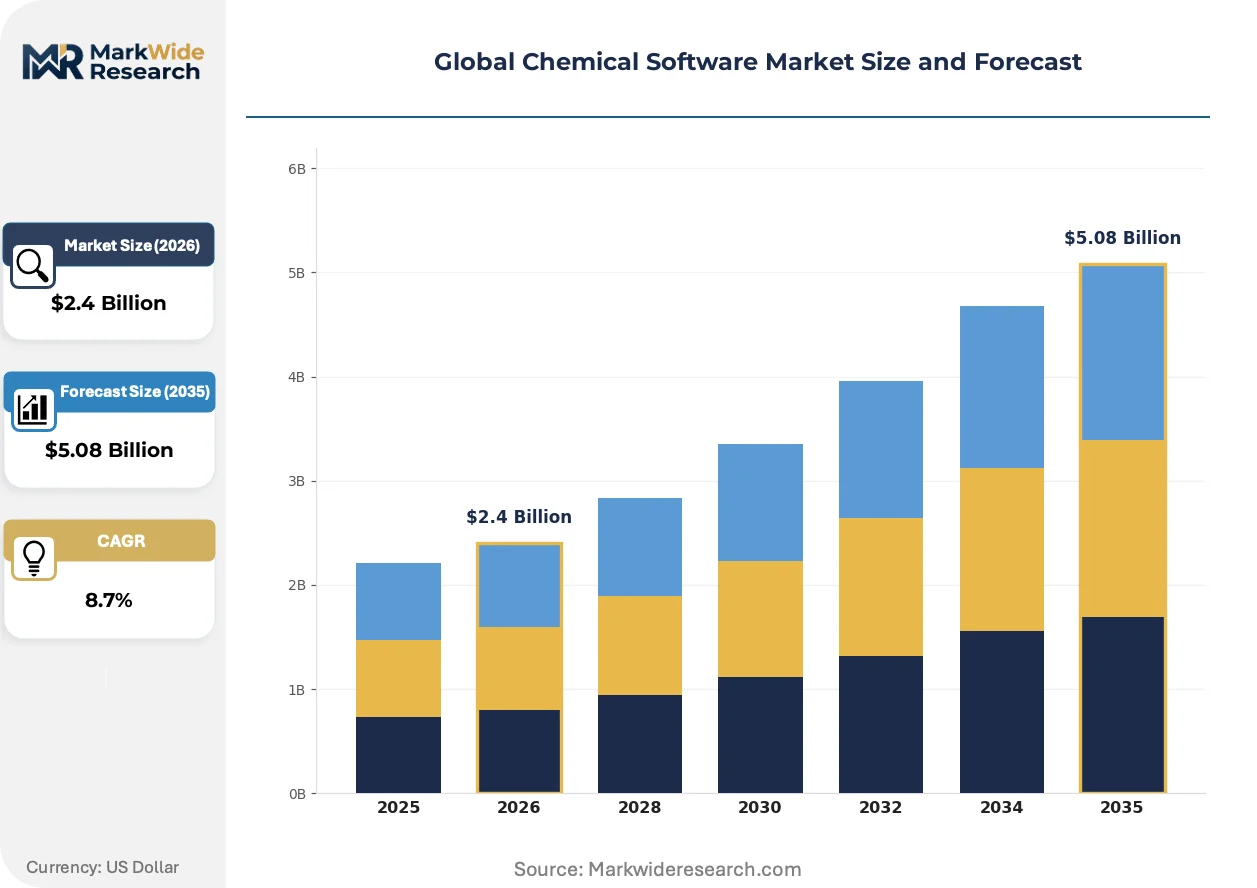
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
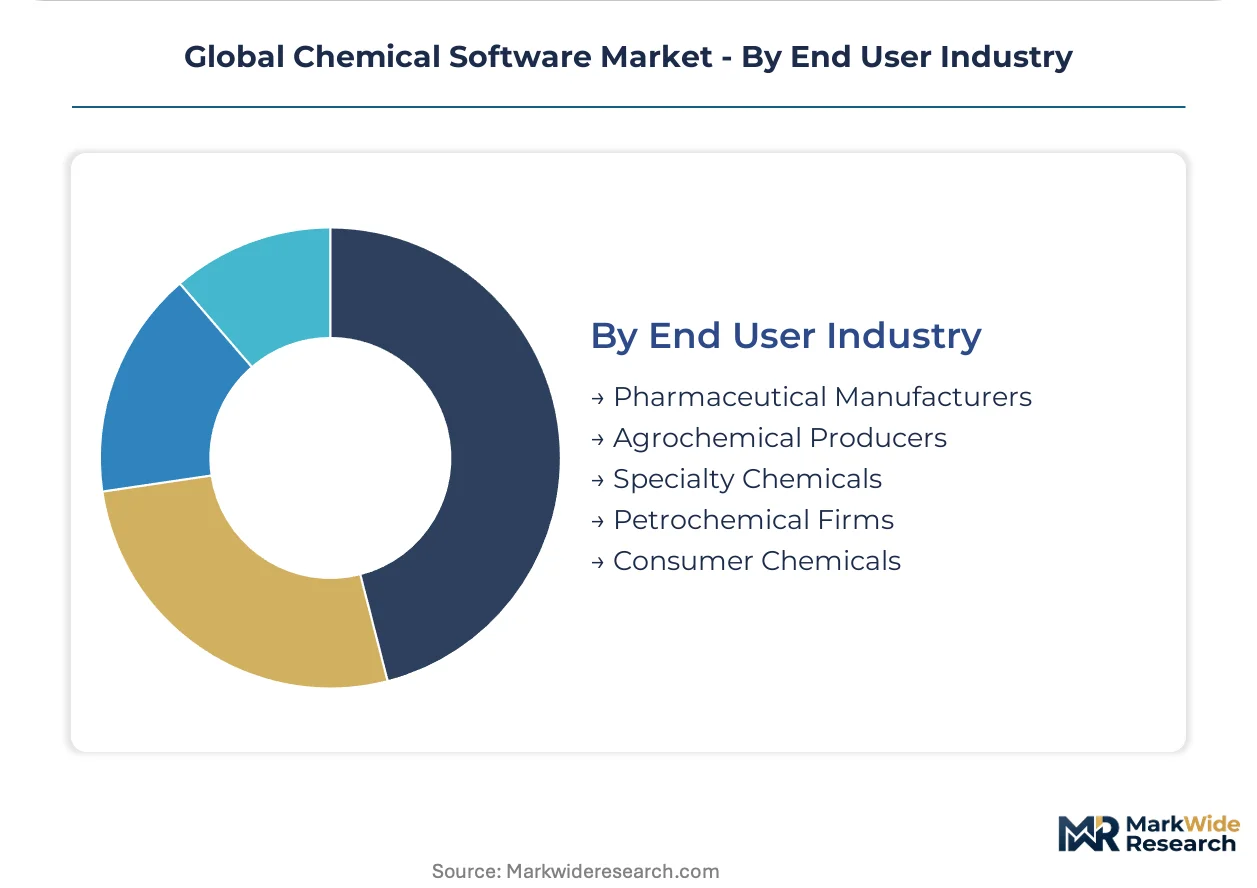
| Segmentation | Solution Type: Laboratory Information Management System, Process Simulation, Data Analytics, Compliance Management, Inventory Management Deployment Mode: Cloud-Based, On-Premises, Hybrid, Hosted, Software as a Service Application: Formulation Development, Quality Control, Regulatory Reporting, Research & Development, Supply Chain Optimization End User Industry: Pharmaceutical Manufacturers, Agrochemical Producers, Specialty Chemicals, Petrochemical Firms, Consumer Chemicals |
| Companies Covered | ANSYS Inc., Aspen Technology Inc., Schneider Electric SE, Siemens AG, SAP SE, Dassault Systemes SE, Oracle Corporation, ChemAxon Ltd., Frontline Data Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chemical Software Market Shifts & Advancements
Computational chemistry platforms are pivoting from offline design tools toward real-time decision systems embedded within manufacturing execution layers, compressing the feedback loop between laboratory discovery and production scale-up.
Cloud-native molecular modeling suites are expanding into continuous process industries previously dominated by steady-state simulation packages. Specialty chemical producers in Germany and the United States adopt these platforms to virtualize experimentation, reducing pilot plant runs. The technology is expanding into regulatory submission workflows by embedding automated structure-activity relationship documentation.
ECHA's SCIP database requirements for SVHC-containing articles are forcing downstream users to implement substance-tracking architectures that trace chemicals through complex supply chains. Industrial consequence includes mandatory supplier data exchange protocols that legacy ERP systems cannot accommodate. Battery manufacturers and polymer compounders in the European Union face the steepest compliance burden, responding through dedicated compliance management module procurement.
Subscription pricing models are displacing perpetual licenses across formulation-intensive segments. Mid-sized producers in Japan and South Korea favor operational expenditure structures that align software costs with production volumes rather than capital budgets. This shift is most visible among contract manufacturers serving pharmaceutical and agrochemical end-uses, where project-based revenue volatility makes fixed-cost software ownership untenable.
Global Chemical Software Market Segmentation
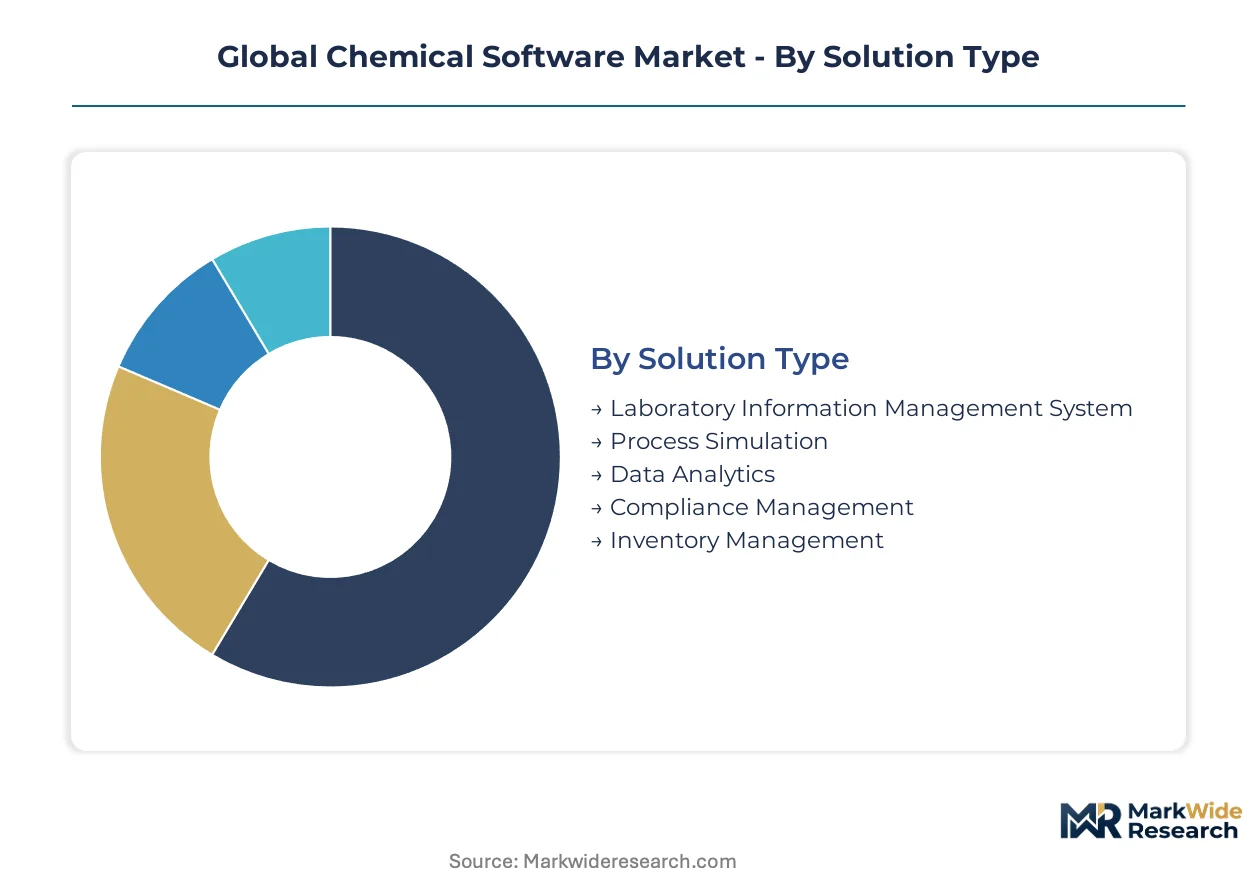
Chemical software procurement fragments across four dimensions that determine integration complexity and pricing architecture. Solution type dictates technical validation requirements, while deployment mode shapes total cost of ownership across multi-year contracts. Application focus and end-user industry together determine regulatory stringency and implementation timelines.
Solution Type:
Standardization dominates laboratory data capture, whereas process modeling demands extensive customization to proprietary reaction kinetics.
- Process Simulation:Platforms deploy numerical solvers with equation-of-state parameters calibrated to industrial operating conditions. Petrochemical firms in Germany and the United States anchor demand as they modernize distillation and reactor design workflows. EPA TSCA documentation mandates compress procurement cycles.
- Laboratory Information Management System:Systems automate sample tracking, instrument integration, and batch documentation across formulation-intensive operations. Specialty chemical producers in Germany concentrate procurement to satisfy ECHA REACH audit trail requirements. FDA 21 CFR Part 11 validation stretches implementation timelines.
- Compliance Management:Architectures embed substance-tracking databases for regulatory submissions.
- Data Analytics:Platforms aggregate historical batch data for yield optimization and predictive maintenance.
- Inventory Management:Modules track raw material flows and lot genealogy for recall readiness.
Most installed capacity flows through Process Simulation. Expansion is steepest in Compliance Management.
Deployment Mode:
Cost tier stratification separates capital-intensive on-premise infrastructure from operational expenditure models favored by mid-sized producers.
- Cloud-Based:Deployment slashes implementation timelines from months to weeks while fragmenting buyer power across specialty chemical houses. Mid-sized producers in Japan and South Korea favor subscription structures that align costs with production volumes.
- Software as a Service:Pricing compounds over multi-year horizons versus depreciated servers, creating tension for budget-constrained procurement teams.
- On-Premises:Installations retain sensitive proprietary reaction kinetics data within secure enclaves.
- Hybrid:Configurations synchronize data between on-premise secure nodes and cloud compute layers.
- Hosted:Arrangements outsource server maintenance to third-party data centers.
Revenue concentrates in Cloud-Based deployment. SaaS models are gaining share fastest among contract manufacturers.
Application:
Maturity gradients separate established quality control workflows from emerging supply chain optimization implementations.
- Formulation Development:Molecular modeling suites virtualize experimentation, reducing pilot plant runs for battery electrolyte developers. EU Green Deal carbon accounting requirements create demand for embedded emissions tracking.
- Regulatory Reporting:Automated batch documentation systems satisfy EPA and EMA submission mandates.
- Quality Control:Systems enforce specification compliance through statistical process control.
- Research & Development:Platforms compress feedback loops between laboratory discovery and production scale-up.
- Supply Chain Optimization:Modules trace chemicals through complex supplier networks for ECHA SCIP database compliance.
Transaction volume flows through Quality Control. Regulatory Reporting shows the steepest expansion trajectory.
End User Industry:
Margin structure varies dramatically between high-value pharmaceutical validation and commodity petrochemical optimization.
- Pharmaceutical Manufacturers:CDSCO-aligned producers in India seek validated electronic batch records as export volumes to regulated markets climb. FDA 21 CFR Part 11 compliance constrains vendor selection to specialized validation partners.
- Petrochemical Firms:Continuous process industries dominate steady-state simulation spending.
- Specialty Chemicals:Formulation-intensive operations require integrated laboratory and process modeling platforms.
- Agrochemical Producers:Facilities manage complex multi-step synthesis with seasonal demand volatility.
- Consumer Chemicals:Manufacturers prioritize rapid formulation iteration for fast-moving consumer goods.
Deployment value concentrates in Pharmaceutical Manufacturers. Specialty Chemicals are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping chemical software procurement as manufacturers migrate formulation operations toward jurisdictions with clearer digital compliance pathways. Cost-of-compliance gaps between the EU REACH framework and emerging economy reporting regimes concentrate investment in established regulatory zones.
United States
EPA TSCA notification mandates and FDA 21 CFR Part 11 requirements drive replacement of paper-based batch documentation. Houston and Gulf Coast petrochemical corridors anchor process simulation spending as distillation modernization accelerates. Pharmaceutical manufacturers in New Jersey and Massachusetts prioritize validated electronic records systems.
Germany
ECHA REACH audit trail requirements and EU Green Deal carbon accounting reshape laboratory information management procurement. BASF and Bayer anchor dense formulation clusters around Ludwigshafen and Leverkusen requiring integrated molecular modeling platforms. Specialty chemical houses in North Rhine-Westphalia consolidate software stacks onto unified compliance architectures.
China
NMPA pharmaceutical data integrity guidelines and MIIT industrial software promotion policies expand domestic platform adoption. Yangtze River Delta battery electrolyte developers deploy molecular-scale simulation to compress formulation cycles. Shanghai and Jiangsu province specialty chemical producers virtualize experimentation to reduce pilot plant runs.
India
CDSCO export compliance requirements and DGFT traceability mandates push pharmaceutical manufacturers toward validated electronic batch records. Gujarat and Maharashtra chemical corridors concentrate procurement as contract manufacturers scale regulated-market exports. Hyderabad and Mumbai formulation houses adopt cloud-native suites to avoid capital-intensive server infrastructure.
Japan
METI digital transformation subsidies and PMDA quality management system updates accelerate legacy system replacement. Osaka and Kansai region polymer compounders invest in predictive process modeling for advanced materials development. Tokyo Bay specialty chemical producers favor subscription pricing structures that align software costs with production volumes.
Global Chemical Software Market Competitive Landscape
United States software houses anchor the process simulation tier; European engineering conglomerates hold the digital twin integration layer. Market structure concentrates around three strategic archetypes: specialized chemical modeling vendors, diversified industrial software conglomerates, and cloud-native compliance platforms. M&A activity targets molecular modeling capabilities; strategic partnerships link simulation engines to manufacturing execution systems.
Within the diversified industrial technology tier, Siemens AG and Schneider Electric SE exemplify tight coupling between process control hardware and software environments. Aspen Technology Inc. occupies a specialized position in polymer and refinery optimization heritage. These three anchors represent distinct competitive vectors: hardware-software integration, domain-specific simulation depth, and enterprise resource planning breadth.
| Leading Market Players |
|---|
| ANSYS Inc. |
| Aspen Technology Inc. |
| Schneider Electric SE |
| Siemens AG |
| SAP SE |
| Dassault Systemes SE |
| Oracle Corporation |
| ChemAxon Ltd. |
| Frontline Data Solutions |
| Others |
Supply & Pricing Matrix
Cloud compute infrastructure costs cascade through subscription pricing tiers as hyperscaler data center investments in Germany and the United States determine SaaS margin structures for mid-sized specialty chemical houses.
Pricing Analysis
Distributor margins compress as direct-to-OEM licensing expands. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 21 CFR Part 11 validation depth. Pricing pressure stems from cloud-native entrants undercutting perpetual license maintenance fees. Contract manufacturers exhibit highest price sensitivity; pharmaceutical multinationals prioritize compliance over cost.
Supply Chain Analysis
Specialized chemical engineering talent supply rests on German technical universities and Indian Institutes of Technology pipelines. Raw material dependencies include equation-of-state parameter libraries, molecular force field datasets, and validated regulatory content packs. Single-source vulnerability concentrates in ECHA REACH database access and EPA TSCA submission portals. Distribution runs through direct vendor relationships and specialized systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Chemical Software Market compounds steadily as regulatory digitization mandates create irreversible replacement cycles across formulation-intensive industries.
For Market Incumbents: Anchor position through backward integration into cloud infrastructure and captive supply of regulatory content databases. Deepen FDA validation partnerships to raise switching costs. Defend against cloud-native entrants by embedding simulation engines within manufacturing execution systems from Siemens and Schneider Electric.
For New Entrants and Emerging Players: AI-powered molecular property prediction offers entry wedge into battery electrolyte formulation segments underserved by legacy steady-state packages. Target Indian CDSCO-aligned contract manufacturers seeking validated electronic batch records without capital-intensive server infrastructure. Pursue channel partnerships with regional systems integrators over direct enterprise sales.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented molecular modeling specialists lack scale to serve ECHA SCIP database compliance mandates. Long-term viability favors platforms combining process simulation, laboratory information management, and regulatory reporting modules. Watch EPA TSCA notification volume and EU REACH substance registration deadlines as demand inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying process simulation with laboratory information management reduces ECHA audit preparation time for German specialty chemical producers. |
| Acquisition of Specialist Firm | Molecular modeling capabilities from BIOVIA lineage strengthen Dassault Systemes positioning in battery electrolyte development workflows. |
| Geographic Expansion | India CDSCO compliance investments open pharmaceutical export corridors for validated electronic batch record platforms. |
| Strategic Partnership | Coupling Aspen Technology solvers with Siemens hardware tightens digital twin integration for polymer compounders. |
| Product Launch | Cloud-native deployment compresses implementation timelines from months to weeks for mid-sized Japanese specialty chemical houses. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged process simulation vendors, laboratory information management providers, regulatory affairs directors at pharmaceutical manufacturers, procurement leads at specialty chemical houses, and systems integration specialists. Secondary validation drew from ECHA substance registration databases, EPA TSCA submission records, SEC 10-K software segment disclosures, and Cefic industry statistics. Bottom-up deployment counts and top-down spending estimates were cross-referenced for triangulation.
Segment-weighting approaches distributed value across solution type, deployment mode, application focus, and end-user industry dimensions. Growth trajectories were derived from regulatory deadline calendars, cloud adoption curves among mid-sized producers, and polymer simulation demand from battery material developers. The analytical framework incorporated FDA 21 CFR Part 11 validation timelines, EU REACH audit trail requirements, and hybrid cloud integration complexity as industry-specific forecast inputs.
The model holds under steady regulatory enforcement intensity; deviation in EPA or ECHA mandate postponement would shift procurement cycles. Forecasts assume continued hyperscaler infrastructure investment and sustained chemical engineering graduate pipeline flow. A small set of named triggers warrants ongoing watch: REACH substance registration deadline delays, cloud security breach incidents, and pharmaceutical export license restrictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Chemical Manufacturing Software Market
Software & Services
Global Linux Operating System Market
Software & Services
Freight Management Software Market
Software & Services
Global Driving School Software Market
Software & Services
Global Appointment Reminder Software Market
Software & Services
Global Restaurant Management Software Market
Software & Services
Sales Training Software Market
Software & Services
Application Virtualization Market
Software & Services
Manufacturing Quoting and Estimating Software Market
Software & Services
Europe HR Payroll Software Market
Software & Services
Global Version Control Systems Market
Software & Services
Global Self-Service BI Market
Software & Services
Global Construction Punch List Software Market
Software & Services
Mobile Tracking Software Market
Software & Services
Freight Forwarding Software Market
Software & Services
Public Financial Management Software Market