
 Middle East and Africa Deodorants Market | 2026-2036
Middle East and Africa Deodorants Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Deodorants Market Foresight
The gym and active lifestyle segment is hardening as a core demand pillar across the Middle East and Africa deodorants landscape. Procter & Gamble Co. leverages its mass-market infrastructure to sustain shelf dominance in hypermarket channels throughout South Africa and Nigeria. Beiersdorf AG anchors its regional position through Nivea's established brand equity in climate-adapted formulations. Godrej Consumer Products competes aggressively on value-tier positioning in East African markets.
Deodorants for the Middle East and Africa comprise antiperspirant and non-antiperspirant formulations delivered via aerosol propellants, roll-on ball applicators, or solid wax bases, typically incorporating aluminum salts, fragrance compounds, and skin-conditioning agents to inhibit bacterial growth and mask odor in high-temperature environments. Spray formats dominate volume throughput in Gulf markets where aerosol familiarity runs deep, while roll-on products command stronger loyalty in South African pharmacies where consumers prioritize precision application. The unisex target consumer segment is expanding fastest as gender-neutral fragrance profiles gain shelf space, though men-specific woody and spicy variants still capture the largest margin pool.
Saudi Food and Drug Authority (SFDA) and Emirates Authority for Standardization and Metrology (ESMA) enforce ingredient disclosure and halal compliance standards that determine market access across Gulf Cooperation Council states. South Africa's National Regulator for Compulsory Specifications (NRCS) mandates safety testing for aerosol propellants, creating a compliance threshold that filters smaller importers. Stakeholders must monitor evolving fragrance allergen labeling requirements and decide whether to reformulate legacy SKUs or retire them ahead of regulatory deadlines.
Market Dynamics
Halal certification mandates from Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology are forcing wholesale reformulation of legacy product lines, while aerosol propellant restrictions in South Africa filter import competition and concentrate supply among compliant domestic manufacturers.
Growth Catalysts
- SFDA Halal Compliance:Mandatory alcohol-free formulation standards across Gulf Cooperation Council states create protected demand pools for certified domestic producers and deter unqualified importers.
- Urban Gym Culture:Fitness center proliferation in Dubai, Johannesburg, and Lagos extends daily usage occasions beyond morning hygiene into post-workout reapplication routines.
- Aluminum Salt Alternatives:Natural mineral-based odor inhibitors are gaining shelf space as younger consumers in Nigerian and Kenyan cities seek perceived safer chemistry profiles.
Market Restraints
- Propellant Cost Volatility:Liquefied petroleum gas and compressed gas input prices fluctuate with crude oil benchmarks, compressing margins on aerosol formats dominant in Gulf markets.
- Import Concentration Risk:Fragrance compound supply clusters in European specialty chemical houses expose regional formulators to euro-denominated cost swings and extended lead times.
- Water Scarcity Formulation Limits:Roll-on emulsion chemistry requires aqueous bases that conflict with manufacturing sustainability targets in water-stressed UAE and Saudi production zones.
Strategic Opportunities
- Ethiopia Retail Penetration:Modern trade format expansion in Addis Ababa and Dire Dawa creates first-mover advantage for brands establishing pharmacy and supermarket distribution before competitive saturation.
- ESMA Blockchain Traceability:Emirates Authority for Standardization and Metrology pilot programs for ingredient provenance tracking reward early adopters with expedited certification pathways.
- E-Commerce Subscription Models:Direct-to-consumer replenishment platforms bypass fragmented traditional wholesale networks in East African markets with underdeveloped modern retail infrastructure.
Industry Challenges
- Fragrance Chemist Talent Scarcity:Formulation expertise for climate-adapted, halal-compliant scent profiles concentrates in European and Southeast Asian training institutions, requiring regional producers to sponsor expatriate hires or long-distance development programs.
- Dual Certification Timelines:Parallel SFDA and ESMA approval processes for new SKUs extend product launch cycles, forcing inventory pre-positioning before revenue realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Deodorants Market |
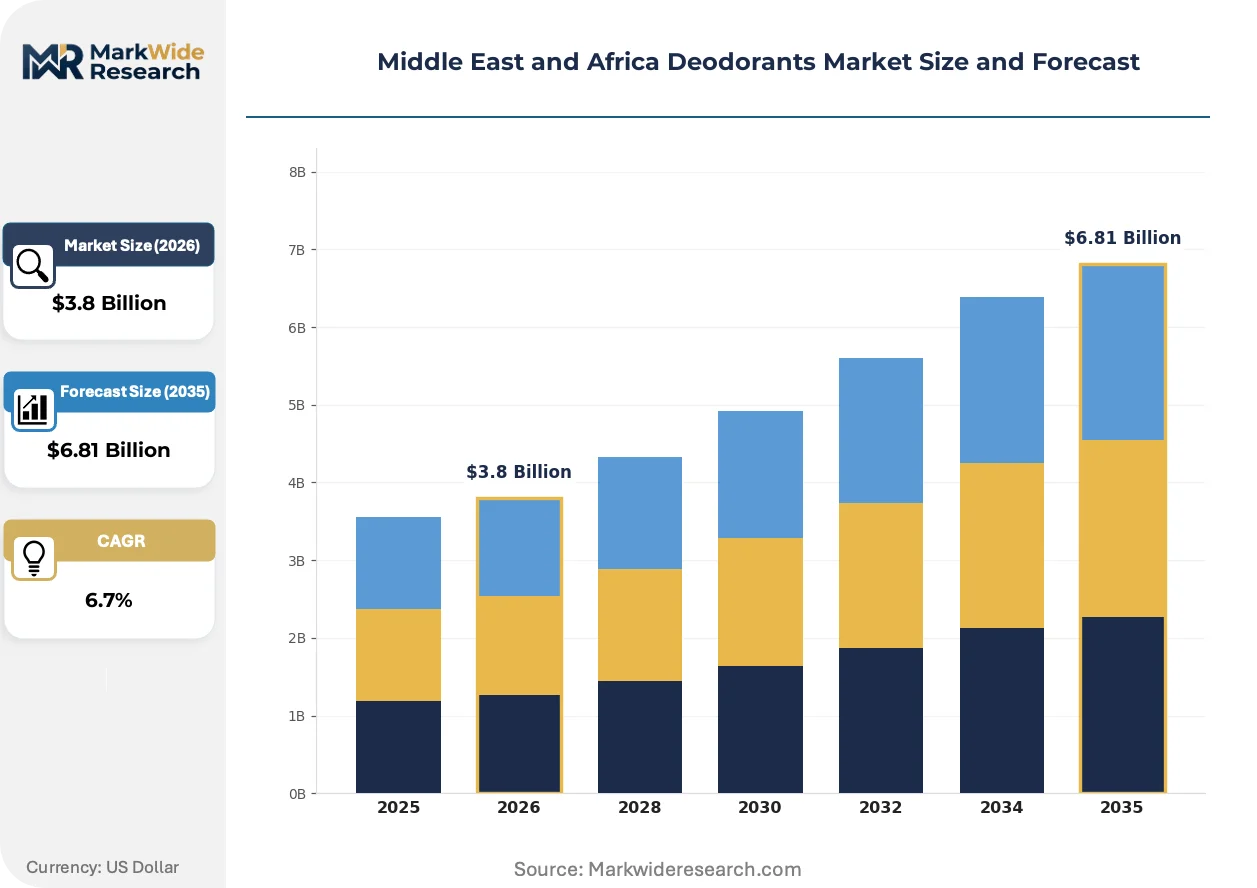
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray, Roll-On, Stick, Gel Target Consumer: Men, Women, Unisex, Teenagers Distribution Channel: Supermarkets, Online, Convenience Stores, Pharmacies Fragrance Type: Citrus, Floral, Woody, Spicy |
| Companies Covered | Unilever PLC, Procter & Gamble Co., L'Oréal S.A., Henkel AG & Co. KGaA, Beiersdorf AG, Colgate-Palmolive, Coty Inc., Church & Dwight Co., Inc., Godrej Consumer Products, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Deodorants Market Shifts & Advancements
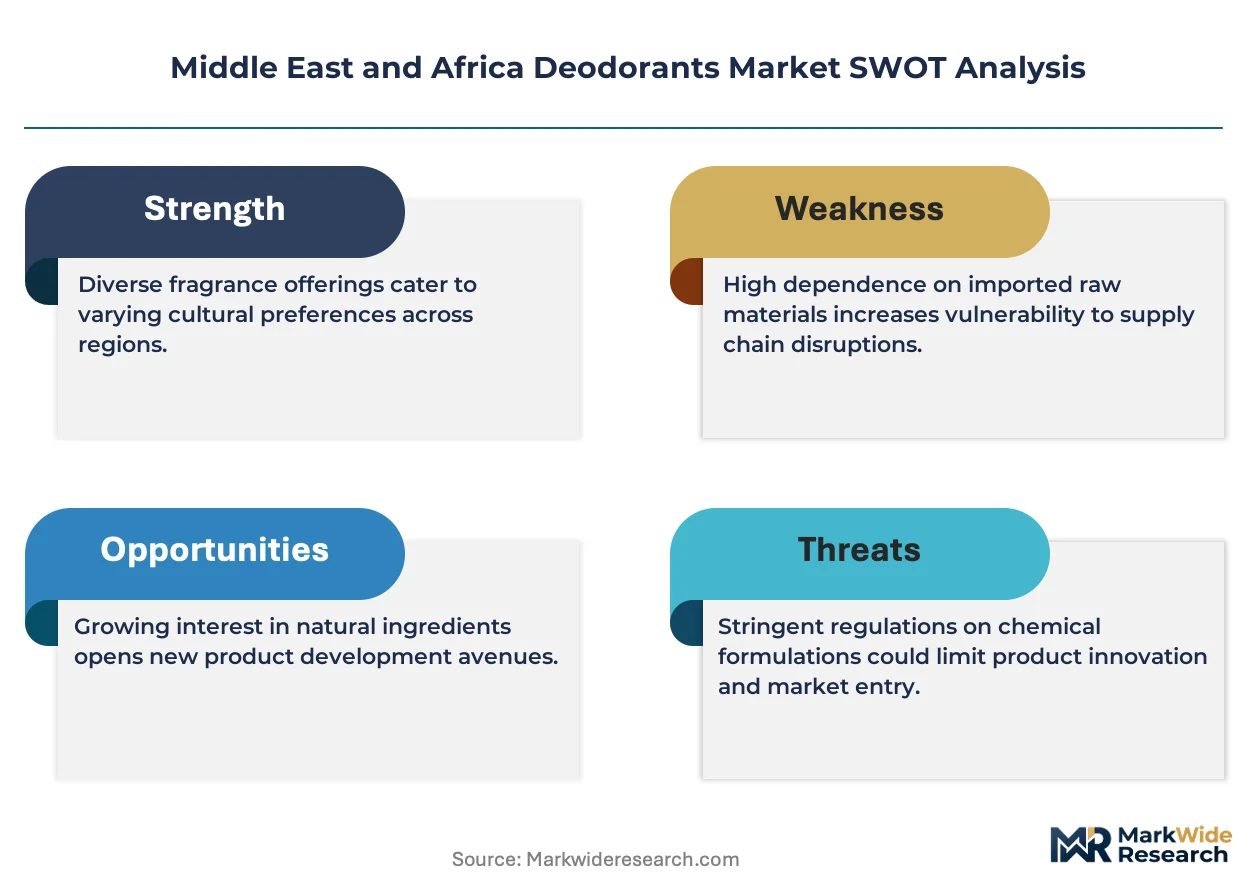
Biotechnology-derived odor control is displacing conventional aluminum salt chemistry across premium positioning tiers, while regulatory disclosure requirements and digital channel expansion simultaneously reshape how formulations reach end consumers.
Enzymatic biotechnology is converging with microbiome-friendly positioning in advanced deodorant formulations. Urban professional consumers in Saudi Arabia and UAE are adopting these products at pace comparable to Western European early markets. This convergence is compressing the traditional segmentation between clinical-strength antiperspirants and cosmetic deodorants, forcing portfolio rationalization among multi-brand manufacturers.
SFDA and ESMA fragrance allergen labeling expansions now require disclosure of twenty-six specific compounds above threshold concentrations. This policy shift forces reformulation of legacy scent profiles or retirement of non-compliant SKUs ahead of enforcement deadlines. Mass-market brands with extensive historical portfolios face disproportionate compliance burdens compared to newer entrants with cleaner formulation starting points.
Gym locker room trial sizes and travel-format impulse placement are displacing traditional pharmacy counter consultation as the primary purchase trigger. Modern trade retailers in South Africa and Nigeria are reallocating shelf space toward grab-and-go formats adjacent to sports nutrition and activewear categories. This behavioral pivot is most visible in Johannesburg and Cape Town, where fitness chain co-location strategies now determine brand visibility more than traditional advertising spend.
Middle East and Africa Deodorants Market Segmentation
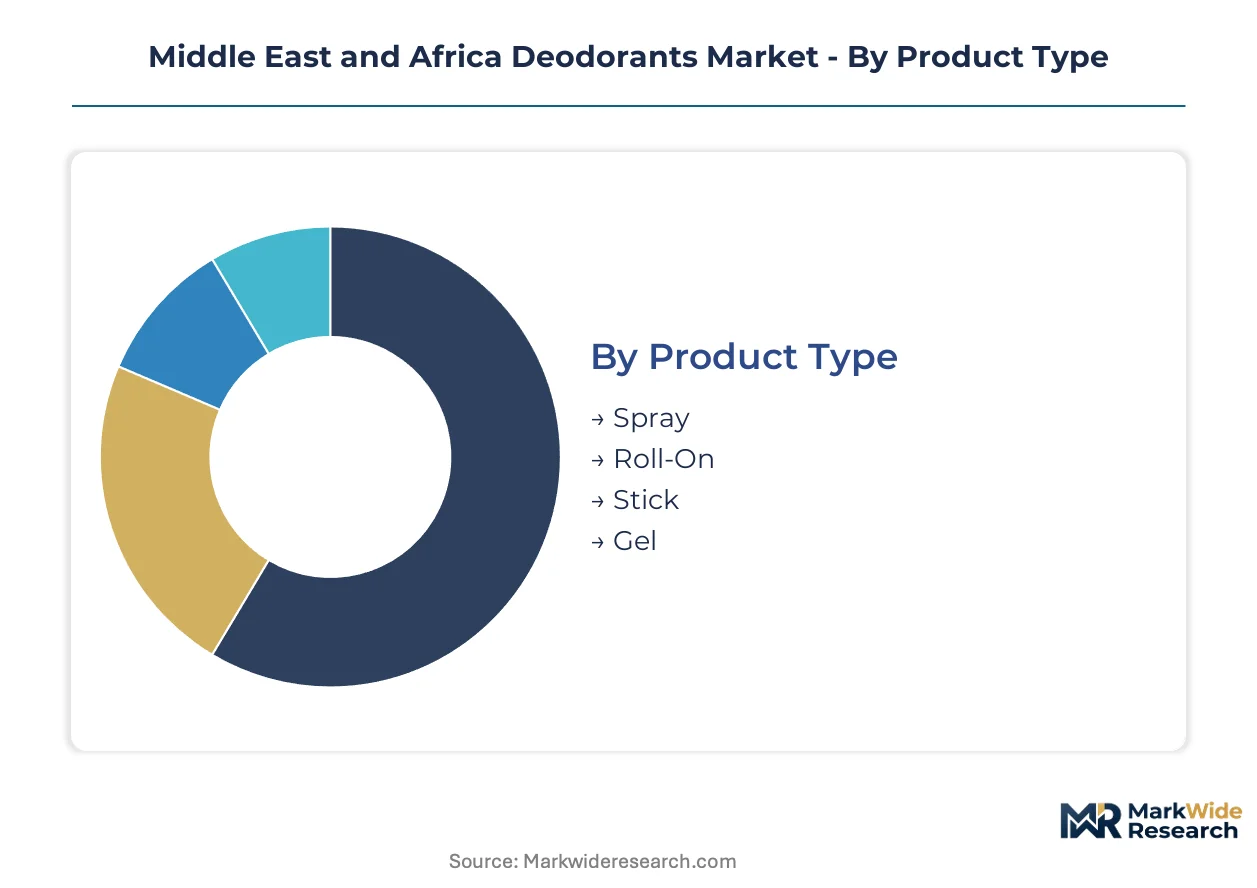
Deodorant manufacturers across the Middle East and Africa calibrate portfolio depth against regional climate demands, halal compliance requirements, and retail infrastructure maturity. Segmentation strategies determine whether brands capture volume in mass-market spray formats or extract premium pricing through specialized roll-on and gel innovations.
Product Type:
Aerosol propellant chemistry versus emulsion or wax-base formulations creates divergent margin profiles and regulatory exposure across this category.
- Spray:Aluminum salt suspensions delivered via liquefied petroleum gas propellants dominate Gulf Cooperation Council shelf space, with SFDA aerosol safety testing filtering import competition. Dubai hypermarkets move spray volumes three-to-one against alternative formats, though propellant cost volatility compresses manufacturer margins.
- Roll-On:Aqueous emulsion formulations with precision ball applicators command pharmacy channel loyalty in Johannesburg and Cape Town, where consumers prioritize controlled dosage over speed of application. Water-scarce production zones in UAE and Saudi Arabia constrain local manufacturing capacity for this format.
- Stick:Solid wax bases incorporating skin-conditioning agents serve travel and gym bag occasions across Nigerian and Kenyan urban centers.
- Gel:Transparent drying formulations with alcohol-free chemistry align with halal certification requirements in Riyadh and Jeddah retail.
Leading the category by volume: Spray. Growing fastest: Roll-On.
Target Consumer:
Purchase frequency and price tolerance diverge sharply across gender-defined versus gender-neutral positioning strategies.
- Men:Woody and spicy fragrance profiles capture the largest margin pool, with gym locker room trial sizes driving replenishment cycles in Lagos and Johannesburg fitness chains. Beiersdorf anchors this segment through climate-adapted Nivea formulations.
- Women:Floral and citrus scent portfolios concentrate in pharmacy and supermarket channels, with aluminum-free alternatives gaining shelf space among Nairobi professional consumers.
- Unisex:Gender-neutral fragrance profiles are expanding shelf space fastest as Saudi and UAE retailers reduce SKU duplication.
- Teenagers:Entry-price positioning with playful branding targets first-time deodorant users in Addis Ababa and Dire Dawa emerging retail zones.
Men-specific lines dominate current revenue. Unisex positioning climbs the fastest.
Distribution Channel:
Modern trade penetration depth versus digital infrastructure maturity shapes channel prioritization across national markets.
- Supermarkets:Hypermarket chains in South Africa and Nigeria provide shelf dominance for Procter & Gamble mass-market infrastructure, with end-cap placement determining brand visibility more than traditional advertising.
- Online:Direct-to-consumer subscription platforms bypass fragmented wholesale networks in East African markets with underdeveloped modern retail infrastructure.
- Convenience Stores:Impulse-format placement captures replenishment occasions in dense urban corridors across Cairo and Casablanca.
- Pharmacies:Clinical-strength antiperspirant consultation remains concentrated in South African pharmacy counters, though gym co-location strategies are displacing this purchase trigger.
Supermarkets lead by volume. Online channels gain share fastest.
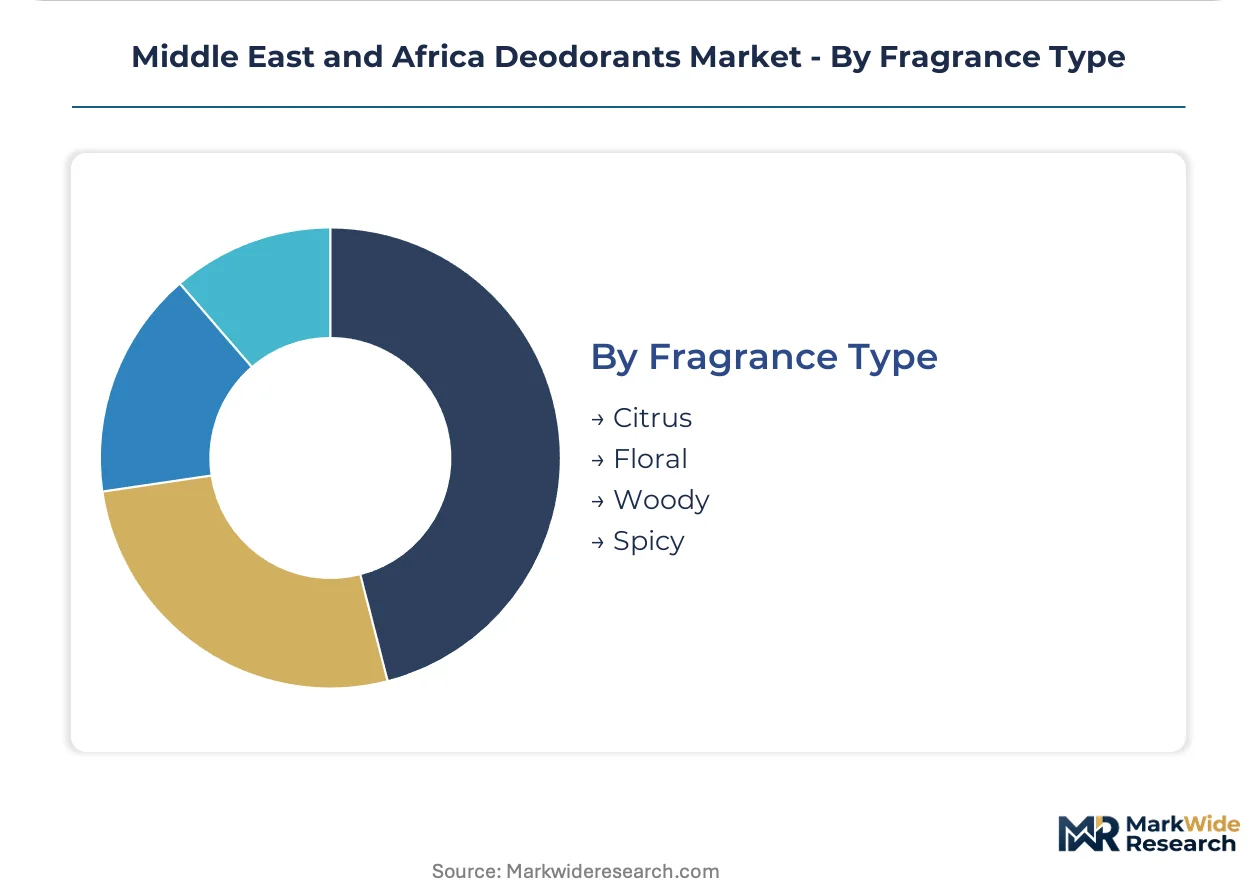
Fragrance Type:
Scent profile selection intersects with ESMA and SFDA allergen disclosure mandates that force reformulation of legacy portfolios.
- Citrus:Fresh top-note formulations dominate unisex positioning and summer seasonal rotations across UAE retail.
- Floral:Traditional women's segment anchor with jasmine and rose bases prevalent in Moroccan and Tunisian local preferences.
- Woody:Sandalwood and cedar bases define men-specific premium tiers in Saudi Arabia and Kuwait.
- Spicy:Oud and amber infusions command highest price positioning in Gulf luxury retail channels.
Woody profiles lead by volume. Citrus formulations expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Jebel Ali and King Abdullah Economic City concentrate deodorant manufacturing capacity through tariff exemptions and streamlined customs processing. Gulf Cooperation Council states leverage these zones to anchor regional supply chains serving high-temperature climate formulations.
Saudi Arabia
Riyadh and Jeddah drive premium-format demand through fitness center proliferation and male grooming routine expansion. SFDA halal certification mandates filter import competition and protect domestic manufacturers with alcohol-free formulation capabilities. The Eastern Province industrial corridor hosts propellant-compatible aerosol production serving Gulf export markets.
United Arab Emirates
Dubai hypermarkets move spray-format volumes at three-to-one ratios against alternatives, with gym locker room trial sizes accelerating replenishment cycles. ESMA blockchain traceability pilots reward early-adopting manufacturers with expedited certification pathways. Jebel Ali free zone concentration enables re-export positioning across East African markets with underdeveloped local production.
South Africa
Johannesburg and Cape Town pharmacy channels sustain roll-on loyalty among consumers prioritizing precision application over speed. NRCS aerosol propellant safety testing creates compliance thresholds that filter smaller importers and concentrate supply among certified domestic manufacturers. Gauteng province retail density supports Procter & Gamble's mass-market infrastructure dominance.
Nigeria
Lagos urban corridors generate entry-price positioning demand for first-time deodorant users in emerging retail zones. Fragrance compound import dependence exposes formulators to euro-denominated cost swings and extended lead times from European specialty chemical houses. Godrej Consumer Products anchors value-tier competition through aggressive pricing in East African adjacent markets.
Kenya
Nairobi professional consumers accelerate aluminum-free alternative adoption, seeking perceived safer chemistry profiles in pharmacy and supermarket channels. Water-scarce production constraints limit local roll-on manufacturing capacity, creating import dependence for emulsion-based formats. E-commerce subscription models bypass fragmented wholesale networks in underdeveloped modern retail infrastructure.
Middle East and Africa Deodorants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational consumer goods conglomerates commanding hypermarket shelf space while regional formulators capture pharmacy and convenience channel loyalty. Market structure tilts toward consolidated mass-market dominance in South Africa and Nigeria, fragmenting into specialty positioning across Gulf Cooperation Council states with divergent halal compliance requirements. Three archetypes define competitive positioning: climate-adapted formulation specialists, value-tier regional challengers, and premium fragrance houses. Dominant competitive moves include portfolio rationalization to meet SFDA and ESMA allergen disclosure deadlines, plus geographic expansion into Ethiopian and Kenyan modern trade before competitive saturation.
Within the multinational conglomerate tier, Unilever PLC and Procter & Gamble Co. exemplify mass-market infrastructure leverage across South African and Nigerian hypermarket channels. Beiersdorf AG occupies a position as the climate-adapted formulation anchor through its Nivea brand equity in high-temperature environments. Among regional challengers, Godrej Consumer Products represents the value-tier archetype competing on aggressive pricing in East African markets with underdeveloped modern retail penetration.
| Leading Market Players |
|---|
| Unilever PLC |
| Procter & Gamble Co. |
| L'Oréal S.A. |
| Henkel AG & Co. KGaA |
| Beiersdorf AG |
| Colgate-Palmolive |
| Coty Inc. |
| Church & Dwight Co., Inc. |
| Godrej Consumer Products |
| Others |
Supply & Pricing Matrix
Liquefied petroleum gas propellant costs cascade through aerosol spray pricing tiers from European specialty chemical houses to Dubai hypermarket shelves, compressing margins at each handoff while concentrating pricing power among Gulf manufacturers with captive propellant supply.
Pricing Analysis
Short lead-time premiums attach to fragrance compound orders from European houses serving Riyadh and Jeddah formulators, while spot inventory discounts emerge in Lagos wholesale channels. Three-tier pricing structure across premium woody-oud positioning, standard citrus-floral blends, and economy-tier unisex formats separates buyers by certification grade and volume scale. Pricing pressure stems from euro-denominated fragrance import costs, with Nairobi professional consumers showing highest price sensitivity and Saudi luxury retail channels least.
Supply Chain Analysis
Direct-to-hypermarket channels handle high-volume spray demand from Dubai retail chains, while fragmented wholesale networks feed Nigerian convenience stores. Manufacturing concentrates in Jebel Ali free zone, Eastern Province industrial corridor, and Gauteng province facilities. Raw material dependencies include aluminum salts, liquefied petroleum gas propellants, and European-sourced fragrance compounds. Single-source vulnerability runs through fragrance compound supply clusters in European specialty houses. Distribution runs through modern trade chains in South Africa and Nigeria, with e-commerce subscriptions bypassing traditional wholesale in East Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa deodorants market sits in a formulation transition phase, with enzymatic biotechnology displacing aluminum salt chemistry across premium tiers and forcing portfolio rationalization among legacy manufacturers.
For Market Incumbents: Deploy halal certification investment as the primary defensive lever against import competition. Accelerate alcohol-free reformulation pipelines to meet SFDA and ESMA allergen disclosure deadlines ahead of enforcement. Secure captive supply of natural mineral-based odor inhibitors through backward integration into specialty chemical partnerships, insulating margin pressure from European fragrance house cost volatility. For New Entrants and Emerging Players: ESMA blockchain traceability pilots in UAE open a window for first-mover advantage among manufacturers with clean formulation starting points. Target Ethiopian modern trade expansion in Addis Ababa and Dire Dawa before competitive saturation, leveraging direct-to-consumer subscription models to bypass fragmented wholesale infrastructure. Lead with gym locker room trial sizes and travel-format placement to capture replenishment occasions in fitness-adjacent retail. For Investors and Strategic Acquirers: SFDA approval timeline compression for aluminum-free SKUs is the leading indicator that biotechnology-derived odor control specialists will command acquisition premiums. Long-term viability favors regional formulators with dual Gulf-African manufacturing footprints and established halal compliance infrastructure. Watch for Ethiopian retail format expansion signals as the inflection point for East African market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Fast-Track | ESMA blockchain traceability pilots reward early adopters with expedited approval pathways. |
| Biotechnology Formulation Pivot | Enzymatic odor control investment compresses segmentation between clinical and cosmetic tiers. |
| East African E-Commerce Launch | Direct-to-consumer subscriptions bypass fragmented wholesale in underdeveloped modern retail zones. |
| Ethiopian Distribution Expansion | Addis Ababa and Dire Dawa modern trade penetration creates first-mover shelf dominance. |
| Gym Channel Co-Location | Fitness locker room trial placement displaces pharmacy consultation as primary purchase trigger. |
Research Methodology
Multi-period observation of SFDA and ESMA regulatory filing patterns anchored the trend analysis, supplemented by interviews with fragrance compound procurement leads, halal certification specialists, modern trade category buyers, and supply chain planners at regional manufacturers. Secondary validation drew from customs trade records, retail audit data, and GCC standards body disclosure archives. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Input-output matrices mapped propellant cost volatility, fragrance import lead times, and halal compliance timelines against projected SKU-level demand across spray, roll-on, stick, and gel formats. Segmentation dimensions included product type, target consumer archetype, distribution channel maturity, and fragrance profile regulatory status. CAGRs derived from weighted average of historical trajectory and technology adoption curve assumptions, with biotechnology penetration rates and gym culture expansion serving as key forecast inputs.
The model assumes a particular technology adoption path for enzymatic biotechnology; alternative pathways for aluminum salt alternatives would alter the outlook. Forecasts reflect base-case assumptions regarding regulatory enforcement timelines and raw material cost stabilization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Arborvitae Oil Market
Flavor and Fragrance Chemicals
Limonene Market
Flavor and Fragrance Chemicals
Global Solid Perfume Market
Flavor and Fragrance Chemicals
Camphor Market
Flavor and Fragrance Chemicals
Global Perfume Ingredients Chemicals Market
Flavor and Fragrance Chemicals
Synthetic Musk Market
Flavor and Fragrance Chemicals
Immortelle Oil Market
Flavor and Fragrance Chemicals
Global Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Deodorant Market
Flavor and Fragrance Chemicals
Perillaldehyde Market
Flavor and Fragrance Chemicals
Fragrance Wax Melts Market
Flavor and Fragrance Chemicals
Linalool Market
Flavor and Fragrance Chemicals
Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Natural Vanillin Market
Flavor and Fragrance Chemicals
Guaiacwood Oil Market
Flavor and Fragrance Chemicals
Sage Essential Oil Market