
 Essential Oil Blends Market | 2026-2036
Essential Oil Blends Market Size, Share, and Industry Trends Forecast 2026-2036
Essential Oil Blends Market Foresight
A shift from single-source botanical supply toward multi-origin sourcing networks is rebalancing raw material risk across the essential oil blends industry. doTERRA leverages its Co-Impact Sourcing program to sustain direct farmer partnerships in over forty countries. Young Living anchors its competitive position through Seed to Seal quality control over corporate-owned farms and partner distilleries. NOW Foods competes on manufacturing scale, operating FDA-registered facilities that supply private-label and branded essential oil blends to mass retail channels.
Essential oil blends are concentrated hydrophobic liquid formulations containing volatile aromatic compounds extracted from plant materials through steam distillation, cold pressing, or CO2 extraction, typically standardized to specific chemotype profiles for therapeutic consistency. These formulations serve commercial purposes spanning aromatherapy diffusion, topical personal care applications, and ambient scenting systems in hospitality environments. Synergy Blends command the widest margin pools by combining multiple single-note oils into functional recipes targeting sleep, immunity, or stress relief. Online Retail channels represent the fastest-growing distribution pathway, though Specialty Stores retain outsized influence in consumer education and premium positioning.
FDA oversight of cosmetic and topical essential oil claims intersects with EPA regulations on pesticide residues in botanical raw materials, creating dual compliance obligations for manufacturers sourcing globally. REACH registration requirements in Europe and USDA organic certification standards in the United States further fragment market access protocols across major demand centers. Stakeholders must monitor evolving fragrance allergen disclosure mandates from ECHA and state-level cosmetic safety legislation in California to anticipate reformulation costs and labeling investments.
Market Dynamics
Multi-origin sourcing networks are rebalancing raw material risk across the essential oil blends industry, forcing manufacturers to diversify botanical supply chains away from single-country dependencies while maintaining chemotype consistency for therapeutic-grade formulations.
Growth Catalysts
- EU Cosmetics Regulation allergen mandates:Stricter disclosure requirements are compelling manufacturers to invest in reformulation capabilities, expanding the addressable market for certified low-allergen blend portfolios.
- Wellness center service expansion:North American spa and integrative health facilities are adding dedicated aromatherapy treatment rooms, creating pull-through demand for professional-grade diffusion systems and bulk therapeutic formulations.
- Steam distillation efficiency gains:Advanced fractional distillation technologies are improving yield recovery from aromatic biomass, lowering per-unit extraction costs for high-value botanicals.
Market Restraints
- Climate-induced harvest volatility:Lavender, tea tree, and eucalyptus crops face yield instability from drought cycles in Australia and Mediterranean growing regions, compressing input cost predictability.
- Dual compliance burdens:FDA cosmetic claims oversight intersects with EPA pesticide residue monitoring for imported botanicals, creating redundant testing requirements for multi-market suppliers.
- Synthetic fragrance substitution:Mass-market personal care brands continue reformulating with petrochemical-derived aroma compounds to bypass agricultural supply constraints and price volatility.
Strategic Opportunities
- Germany pharmacy channel expansion:DM and Rossmann chains are dedicating enlarged shelf sections to certified organic essential oil products, creating a premium retail pathway distinct from mass-market positioning.
- Ambient scenting system integration:Hospitality property management platforms are embedding smart diffusion hardware into building automation systems, enabling subscription-based consumable replenishment models.
- USDA Organic certification tailwind:Federal procurement preferences for organic products are opening institutional channels including university wellness programs and government facility management contracts.
Industry Challenges
- REACH registration timelines:ECHA substance dossier requirements for fragrance allergens are extending product launch cycles by 18-24 months for European market entry.
- Chemotype standardization skill gaps:Gas chromatography-mass spectrometry analysis expertise remains concentrated among specialized analytical laboratories, limiting in-house quality control capabilities for mid-scale blenders.
- CO2 extraction capex intensity:Supercritical extraction equipment for heat-sensitive botanicals requires capital deployment that strains facility expansion budgets for emerging market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Essential Oil Blends Market |
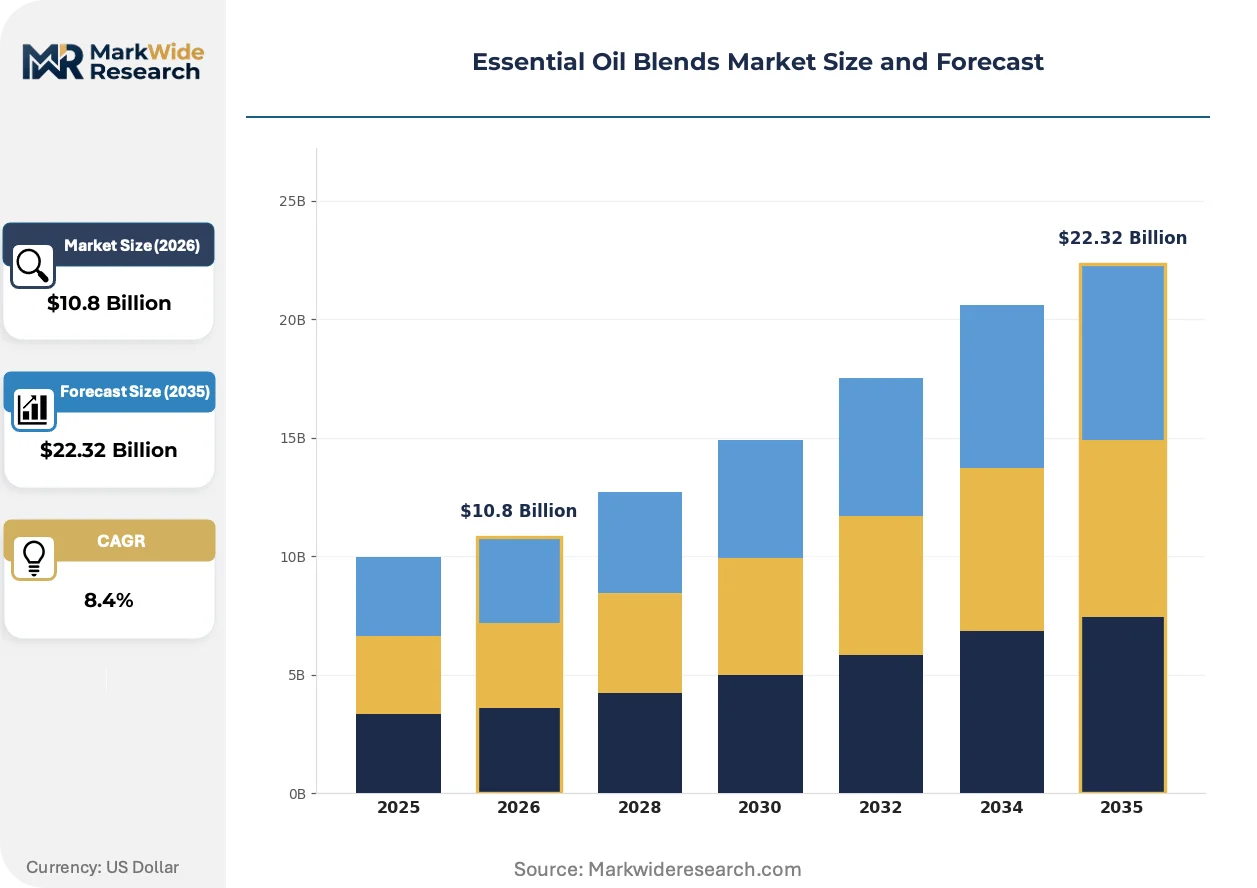
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $22.32 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Notes, Synergy Blends, Diffuser Blends, Therapeutic Blends Application: Aromatherapy, Personal Care, Household, Spa Distribution Channel: Online Retail, Specialty Stores, Health Shops, Direct Sales End User: Consumers, Wellness Centers, Spa Owners, Retailers |
| Companies Covered | Plant Therapy, Aura Cacia, doTERRA, Radha Beauty, Mountain Rose Herbs, Young Living, Rocky Mountain Oils, NOW Foods, Edens Garden, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Essential Oil Blends Market Shifts & Advancements
Smart diffusion hardware and blockchain traceability systems are converging to transform how essential oil blends are dosed, monitored, and authenticated across commercial and residential end-uses.
Supercritical CO2 extraction equipment is integrating into mid-scale production facilities to preserve thermolabile compounds in delicate floral botanicals. Boutique wellness brands and contract manufacturers in California and British Columbia are adopting these systems to differentiate through "cold-process" marketing claims. The technology is integrating quality-sensitive supply chains by enabling on-shore processing of imported raw materials without degradation of volatile aromatic profiles.
REACH registration requirements from ECHA are forcing systematic substance-by-substance documentation of fragrance allergens across European supply chains. Manufacturers must now maintain granular dossiers on limonene, linalool, and citronellol concentrations in finished blends. German and French cosmetic formulators are responding by consolidating supplier bases to reduce traceability audit complexity.
Direct-to-consumer subscription models are displacing traditional retail replenishment cycles for residential diffusion users. Specialty stores that once dominated premium positioning are ceding volume to algorithmic curation platforms that personalize blend selections based on sleep and stress self-reported data. This behavioral shift concentrates most visibly in urban Australian and Canadian markets where wellness app penetration exceeds retail foot traffic for home fragrance categories.
Essential Oil Blends Market Segmentation
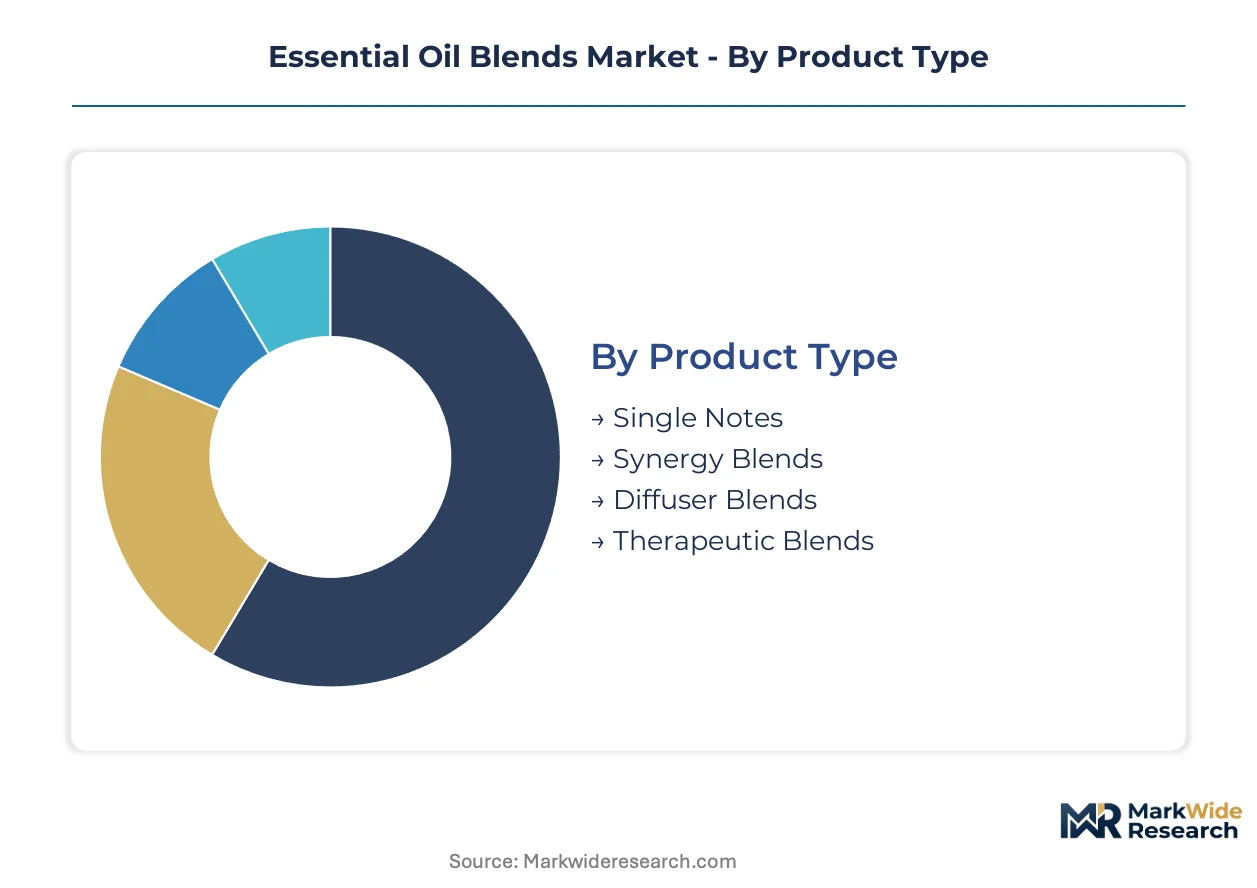
Essential oil blends segment across functional formulation types, use contexts, and procurement pathways that each carry distinct margin structures and regulatory exposure. Manufacturers configure product portfolios differently depending on which segments anchor their revenue.
Product Type:
Standalone single-note oils serve discrete therapeutic protocols, while integrated multi-oil formulations embed into broader wellness systems and ambient scenting infrastructure.
- Synergy Blends:Multi-oil formulations standardized to specific chemotype ratios for functional outcomes like sleep support or immune modulation. Demand concentrates in wellness center procurement contracts across Germany and California, where integrative health protocols require batch-consistent therapeutic profiles. Professional aromatherapists specify these blends for clinical diffusion protocols.
- Therapeutic Blends:Concentrated formulations meeting pharmacopeial standards for topical application and inhalation therapy. German pharmacy chains are dedicating expanded shelf sections to certified organic variants, creating a premium retail pathway distinct from mass-market positioning. These blends carry the most stringent documentation requirements for allergen disclosure under REACH.
- Single Notes:Unblended botanical extracts from individual plant species, typically lavender, tea tree, or eucalyptus.
- Diffuser Blends:Pre-formulated combinations optimized for residential and commercial diffusion hardware, emphasizing aroma longevity over therapeutic potency.
Volume placements concentrate in Synergy Blends; the faster expansion belongs to Therapeutic Blends.
Application:
Cost tier stratification separates professional-grade therapeutic use from mass-market household consumption, with spa applications occupying an intermediate price-performance position.
- Aromatherapy:Clinical and residential diffusion protocols targeting stress reduction, sleep enhancement, and cognitive performance. North American wellness centers are adding dedicated treatment rooms, creating pull-through demand for professional-grade diffusion systems. FDA oversight of therapeutic claims intersects with state-level cosmetic safety legislation in California.
- Personal Care:Topical formulations integrated into skincare, haircare, and bath products. EU Cosmetics Regulation allergen mandates are compelling manufacturers to invest in reformulation capabilities, expanding the addressable market for certified low-allergen blend portfolios. Major personal care brands in France and Germany are consolidating supplier bases to reduce traceability audit complexity.
- Household:Ambient scenting for residential environments, typically through passive diffusion or ultrasonic devices.
- Spa:Treatment-room applications combining inhalation and topical protocols in hospitality and wellness facility settings.
Margin capture peaks in Personal Care; Aromatherapy is climbing the fastest.
Distribution Channel:
Customer type fragmentation splits between self-directed residential purchasers and institutionally governed procurement decisions with divergent compliance requirements.
- Online Retail:Algorithmic curation platforms personalizing blend selections based on sleep and stress self-reported data. Urban Australian and Canadian markets show the most pronounced shift toward subscription-based replenishment models. Direct-to-consumer channels are displacing traditional retail cycles for residential diffusion users.
- Specialty Stores:Brick-and-mortar outlets emphasizing consumer education, olfactory testing, and premium positioning. These retailers retain outsized influence in consumer education despite ceding volume to digital channels. Staff-trained consultation remains critical for therapeutic-grade purchase decisions.
- Health Shops:Nutrition and wellness-focused retail formats emphasizing certified organic and natural product credentials.
- Direct Sales:Network marketing and consultant-driven distribution models with personalized relationship management.
Transaction volume concentrates in Online Retail; Specialty Stores command the steepest expansion trajectory.
End User:
Supply concentration varies sharply between fragmented residential consumers and concentrated institutional procurement with formal vendor qualification requirements.
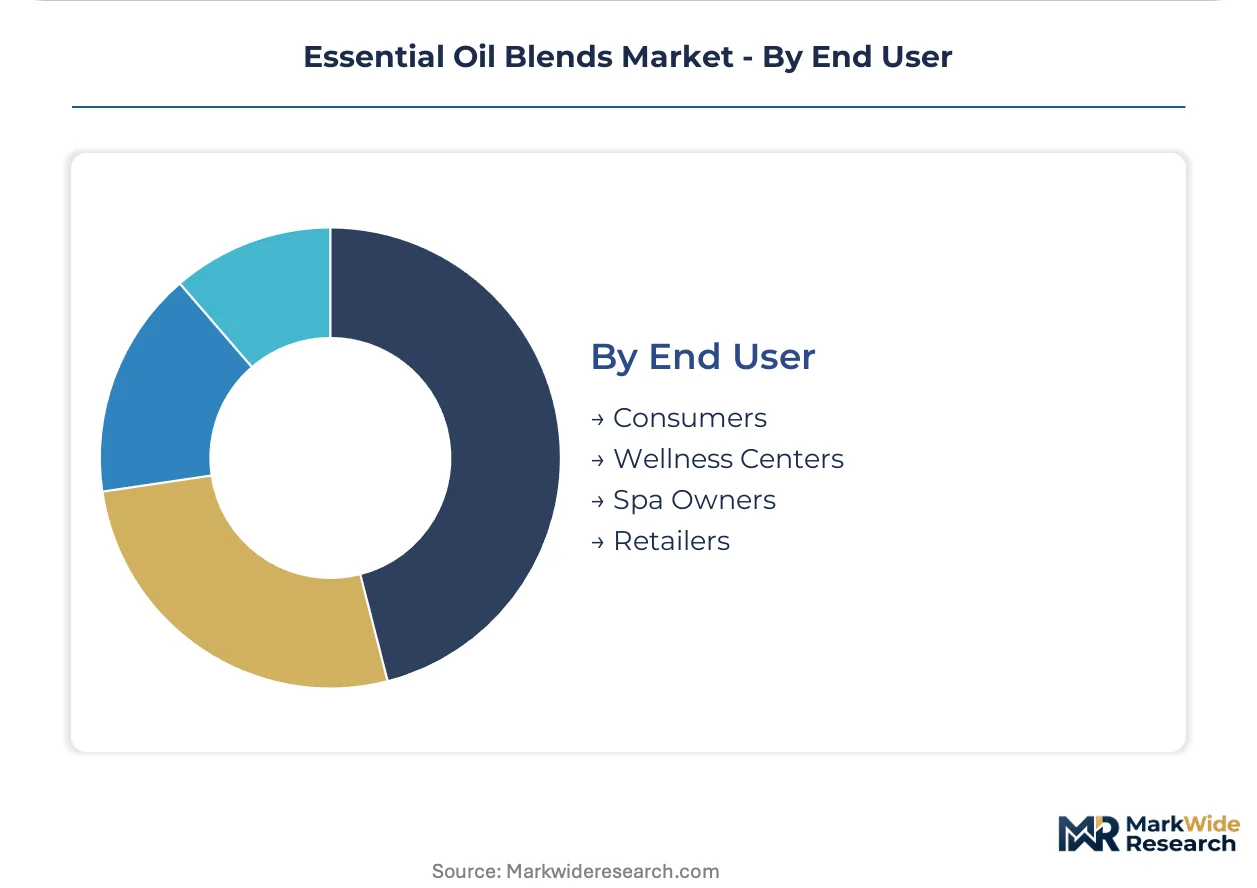
- Wellness Centers:Integrative health facilities and spa operations with professional-grade diffusion infrastructure and bulk therapeutic formulation requirements. North American facilities are expanding service menus to capture consumer spending on stress-management solutions. These buyers specify gas chromatography-mass spectrometry documentation for batch verification.
- Consumers:Individual residential purchasers selecting blends for personal aromatherapy and home fragrance applications. USDA Organic certification tailwinds are opening institutional channels including university wellness programs, indirectly validating consumer-grade quality claims. Self-reported wellness data increasingly drives algorithmic product recommendations.
- Spa Owners:Independent and chain hospitality operators balancing guest experience with operational cost management.
- Retailers:Merchandising intermediaries including pharmacy chains, mass-market outlets, and specialty wellness stores.
Procurement volume concentrates in Wellness Centers; Consumers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates demand through pharmacy chain expansion, while wellness center growth in the United States and Australia pulls professional-grade formulations. Regulatory fragmentation across FDA, REACH, and ECHA mandates creates divergent compliance investments by geography.
Germany
DM and Rossmann pharmacy chains dedicate enlarged shelf sections to certified organic essential oil products, creating a premium retail pathway distinct from mass-market positioning. REACH registration requirements from ECHA force systematic substance-by-substance documentation of fragrance allergens, extending product launch cycles. Bavaria-based formulators consolidate supplier bases to reduce traceability audit complexity for chemotype-standardized blends.
United States
North American wellness centers expand dedicated aromatherapy treatment rooms, generating pull-through demand for professional-grade diffusion systems and bulk therapeutic formulations. FDA oversight of cosmetic claims intersects with EPA pesticide residue monitoring for imported botanicals, creating redundant testing requirements. California's state-level cosmetic safety legislation drives reformulation investments for brands targeting West Coast distribution.
Australia
Urban wellness app penetration exceeds retail foot traffic for home fragrance categories, accelerating direct-to-consumer subscription models. TGA guidelines on therapeutic goods classification affect how aromatherapy claims are positioned in marketing materials. Melbourne and Sydney clusters concentrate boutique wellness brands adopting supercritical CO2 extraction systems for cold-process differentiation.
France
Cosmetic formulators in Paris and Grasse consolidate supplier bases to manage REACH traceability complexity for fragrance allergens. ANSM oversight of cosmetic safety intersects with EU Cosmetics Regulation allergen mandates. Provence-Alpes-Côte d'Azur retains concentration of traditional distillation expertise while integrating advanced fractional technologies for yield recovery.
Canada
Health Canada and PMRA regulations on natural health products shape labeling requirements for therapeutic-grade blends entering the market. British Columbia contract manufacturers adopt supercritical extraction equipment to process imported raw materials without volatile degradation. Toronto and Vancouver wellness center networks expand service menus to capture consumer spending on stress-management solutions.
Essential Oil Blends Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers extend from single-note oils into functional synergy formulations. The vendor base spans multinational wellness conglomerates, specialized botanical extractors, and mass-market private-label suppliers. Three archetypes define positioning: direct-to-consumer subscription platforms, pharmacy-certified organic specialists, and scale-driven mass retail suppliers. Geographic expansion and strategic sourcing partnerships represent the primary competitive vectors.
Within the vertically integrated tier, doTERRA and Young Living anchor contrasting approaches to supply chain control. NOW Foods occupies a position exemplifying scale-driven manufacturing for private-label and branded distribution through mass retail channels. Plant Therapy represents the direct-to-consumer archetype with algorithmic curation capabilities.
| Leading Market Players |
|---|
| Plant Therapy |
| Aura Cacia |
| doTERRA |
| Radha Beauty |
| Mountain Rose Herbs |
| Young Living |
| Rocky Mountain Oils |
| NOW Foods |
| Edens Garden |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between REACH-compliant therapeutic formulations and unregulated commodity blends manifests in divergent margin structures and sourcing configurations. Premium pharmacy-channel products in Germany command substantial markups contingent on ECHA allergen documentation, while mass-market diffuser oils compete on agricultural input arbitrage from Mediterranean and Australian growing regions.
Pricing Analysis
Volume placements concentrate in economy-tier diffuser blends sold through online retail channels, while margin capture peaks in certified organic therapeutic formulations. Price differentiation rests on USDA organic certification and gas chromatography-mass spectrometry batch verification. Pricing pressure stems from synthetic fragrance substitution in mass personal care applications. Wellness centers demonstrate lowest price sensitivity given clinical protocol requirements, whereas residential consumers exhibit highest elasticity.
Supply Chain Analysis
Workforce availability for fractional distillation expertise concentrates in Provence-Alpes-Côte d'Azur, Bulgaria, and Tasmania, constraining capacity expansion for boutique processors. Raw material dependencies include Bulgarian lavender biomass, Australian tea tree leaf, and Indian sandalwood heartwood. Single-source vulnerability runs through Mediterranean climate-dependent harvest cycles. Distribution runs through pharmacy chains in Germany, wellness center procurement networks in California, and algorithmic curation platforms in urban Australian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration requirements function as a cost-of-compliance moat, extending product launch timelines and consolidating supplier relationships around dossier-capable formulators in Germany and France.
For Market Incumbents: Anticipate synthetic fragrance encroachment in mass personal care segments by deepening captive supply of certified organic biomass through direct farmer partnerships. Prioritize gas chromatography-mass spectrometry in-house capabilities to reduce third-party testing dependencies and accelerate batch release cycles. For New Entrants and Emerging Players: Begin with ambient scenting system integration for hospitality property management platforms, where smart diffusion hardware creates recurring consumable revenue streams. Target Canadian and Australian wellness center networks with subscription-based professional-grade formulations, leveraging USDA organic certification for institutional procurement eligibility. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale CO2 extraction specialists given cold-process marketing differentiation and on-shore processing economics. Long-term viability favors facilities capable of thermolabile compound preservation without volatile degradation. Watch for ECHA fragrance allergen mandate expansion as inflection indicator for consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biomass Supply | Direct farmer partnerships in Bulgaria and Tasmania secure chemotype consistency for therapeutic-grade formulations. |
| CO2 Extraction Capacity Addition | Cold-process equipment in California and British Columbia enables heat-sensitive floral botanical processing without degradation. |
| REACH Dossier Consolidation | Systematic allergen documentation reduces audit complexity for German and French pharmacy channel access. |
| Smart Diffusion Hardware Partnership | Building automation integration creates subscription replenishment models for hospitality property management platforms. |
| USDA Organic Certification Program | Federal procurement preferences open university wellness programs and government facility management contracts. |
Research Methodology
Document review covered ECHA substance dossiers, FDA cosmetic claim filings, and USDA organic certification records, complemented by interviews with essential oil blend formulators, pharmacy chain category managers, wellness center procurement directors, and supercritical extraction equipment manufacturers. Secondary validation drew from customs trade data, EU Cosmetics Regulation implementation reports, and hospitality property management platform disclosures. Bottom-up volume estimates triangulated against top-down market sizing across functional formulation categories.
Output projections span volume and value dimensions across the forecast period, with segmentation modeling by product type, application context, distribution pathway, and end-user archetype. CAGRs derive from historical trajectory analysis adjusted for regulatory catalysts and channel shift dynamics. Industry-specific inputs include lavender harvest yield volatility indices, REACH registration timeline benchmarks, and wellness center service expansion rates.
Underlying measurement precision varies by segment; pharmacy-channel therapeutic blends carry tighter precision than fragmented online retail diffuser oils due to consolidated procurement documentation. Forecasts reflect documented assumptions on regulatory implementation schedules and climate-induced harvest patterns. Material deviation in ECHA allergen mandate scope or Mediterranean drought frequency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
India Essential Oils Market
Flavor and Fragrance Chemicals
Smoke Ingredients Market
Flavor and Fragrance Chemicals
Arborvitae Oil Market
Flavor and Fragrance Chemicals
Tannic Acid Market
Flavor and Fragrance Chemicals
Natural Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Carnosic Acid Market
Flavor and Fragrance Chemicals
Asia-Pacific Deodorants Market
Flavor and Fragrance Chemicals
Guaiacwood Essential Oil Market
Flavor and Fragrance Chemicals
Hydroxycitronellal Market
Flavor and Fragrance Chemicals
Dihydrocitronellol Market
Flavor and Fragrance Chemicals
Deodorization Systems Market
Flavor and Fragrance Chemicals
Phenethyl Alcohol Market
Flavor and Fragrance Chemicals
Sulphite Ammonia Caramel Market
Flavor and Fragrance Chemicals
Fragrance Fixatives Market
Flavor and Fragrance Chemicals
Aromatic Compounds Market
Flavor and Fragrance Chemicals
United States Aroma Chemicals Market