
 Tannic Acid Market | 2026-2036
Tannic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Tannic Acid Market Outlook
Gallic acid is realigning cost structures across pharmaceutical and food-grade tannic acid formulations as manufacturers reformulate around plant-derived polyphenol streams. Silvateam leverages backward integration into chestnut and quebracho forestry to sustain raw material security across European tannin production. Tanac S.A. anchors its position through specialized extraction capabilities for high-purity hydrolyzable grades serving wine and beverage applications. Zhushan County Tianxin Medical & Chemical Co., Ltd. dominates gallnut-sourced supply chains with captive sourcing from Hubei province processing clusters.
Tannic acid is a polyphenolic compound extracted primarily from gallnuts, sumac, or chestnut wood, typically containing 50-70% gallotannin content by weight depending on botanical source and extraction method; it functions as a protein precipitant, antioxidant, and metal chelator across industrial and consumer applications. Hydrolyzable tannins command premium positioning in pharmaceutical excipient and food preservative segments where gallic acid purity thresholds determine regulatory acceptance, while condensed tannins from mimosa and quebracho feed mature leather tanning demand with thinner margin pools. Synthetic tannins occupy a narrowing mid-tier as natural-source claims displace petrochemical-derived alternatives in cosmetics and personal care formulations.
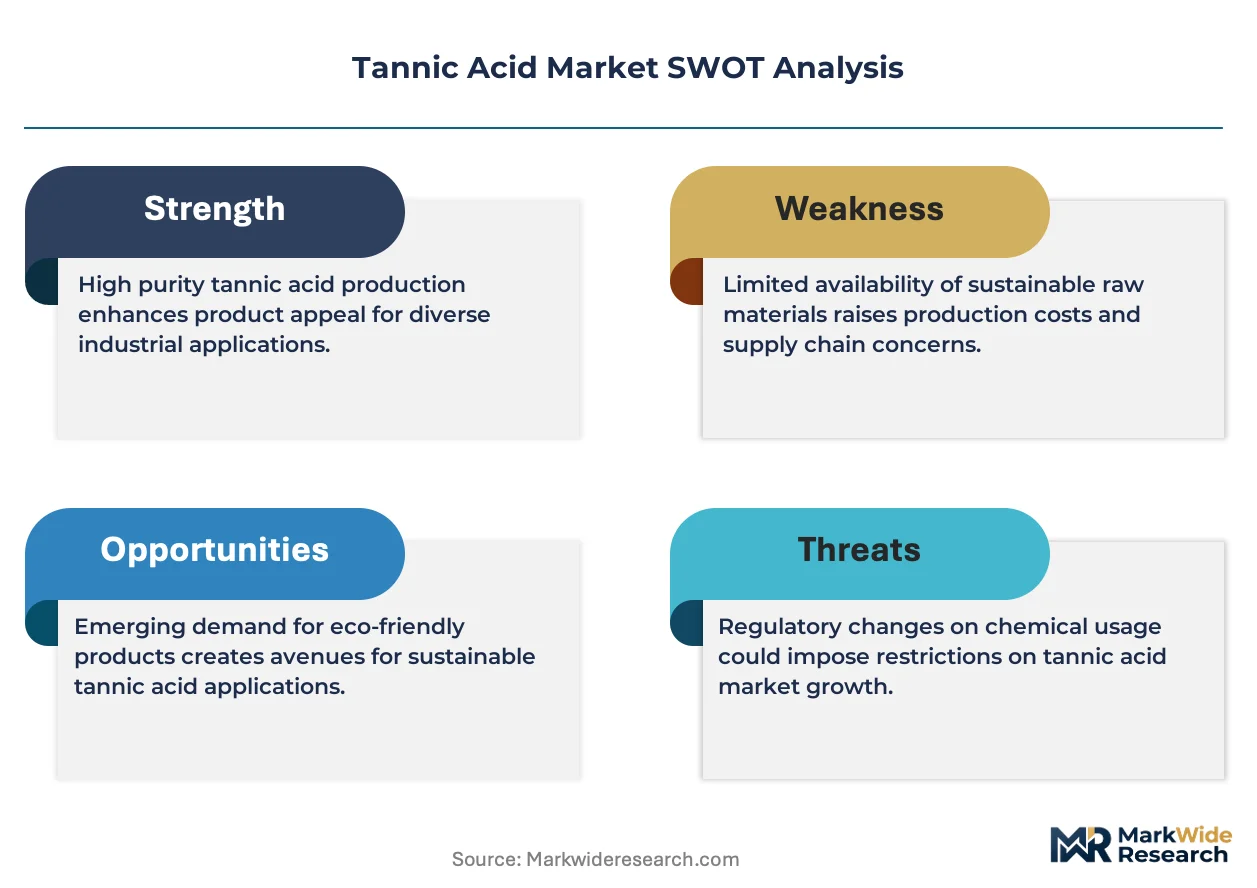
REACH registration requirements govern tannic acid purity and impurity profiling for European cosmetic and food additive placements, while FDA food additive regulations shape GRAS status determinations for gallic acid derivatives in U.S. pharmaceutical coatings. China's GB standards and SAMR oversight enforce heavy metal limits and pesticide residue thresholds for domestic extract exports. Stakeholders must monitor evolving EFSA safety reassessments for hydrolyzable tannin daily intake limits and their downstream impact on formulation maximums across nutrition and oral care products.
Market Dynamics
Pharmaceutical excipient demand is concentrating procurement power among enteric coating formulators, forcing extractors to certify hydrolyzable tannin purity to FDA and EFSA thresholds previously reserved for synthetic alternatives.
Growth Catalysts
- REACH and RoHS compliance tightening:European purity specifications for food-grade and cosmetic-grade extracts are pushing domestic processors to upgrade refining capabilities. This creates certified supply scarcity that rewards early movers with preferred supplier status.
- China's gallnut processing clusters:Domestic hydrolyzable and condensed tannin production in Hubei province feeds regional formulators with shorter lead times than import-dependent competitors.
- Enteric coating applications:Pharmaceutical companies are expanding tannic acid procurement as a natural polymer alternative to synthetic coatings for delayed-release formulations.
Market Restraints
- Raw material concentration risk:Gallnut supply depends on insect-gall formation on specific oak species, creating harvest volatility concentrated in southwestern China and Turkish Anatolia.
- Substitution by synthetic polyphenols:Petrochemical-derived alternatives maintain cost advantages in leather tanning and wood adhesive applications where natural-source claims carry no premium.
- EFSA daily intake reassessments:Pending safety reviews for hydrolyzable tannin consumption limits threaten formulation maximums across nutrition and oral care segments.
Strategic Opportunities
- Underpenetrated U.S. pharmaceutical coating:GRAS status determination pathways for gallic acid derivatives remain incomplete, creating first-mover advantage for extractors who complete FDA food additive petitions.
- Clean-label cosmetic convergence:Natural-source tannin demand in European personal care is accelerating as REACH registration costs filter out mid-tier synthetic competitors.
- Chestnut and quebracho forestry backward integration:Producers securing captive raw material through managed woodland leases insulate margin structures from spot gallnut price swings.
Industry Challenges
- Analytical chemistry skill scarcity:Gallic acid purity verification to pharmacopeial standards requires HPLC-MS capabilities that extractors in traditional tanning regions lack.
- Multi-jurisdiction certification timelines:Parallel FDA, EFSA, and SAMR approval processes for novel excipient grades extend commercialization cycles by 18-36 months.
- Legacy leather tanning equipment retrofit costs:Condensed tannin extractors seeking pharmaceutical-grade output must replace open-vat processing with closed-loop systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tannic Acid Market |
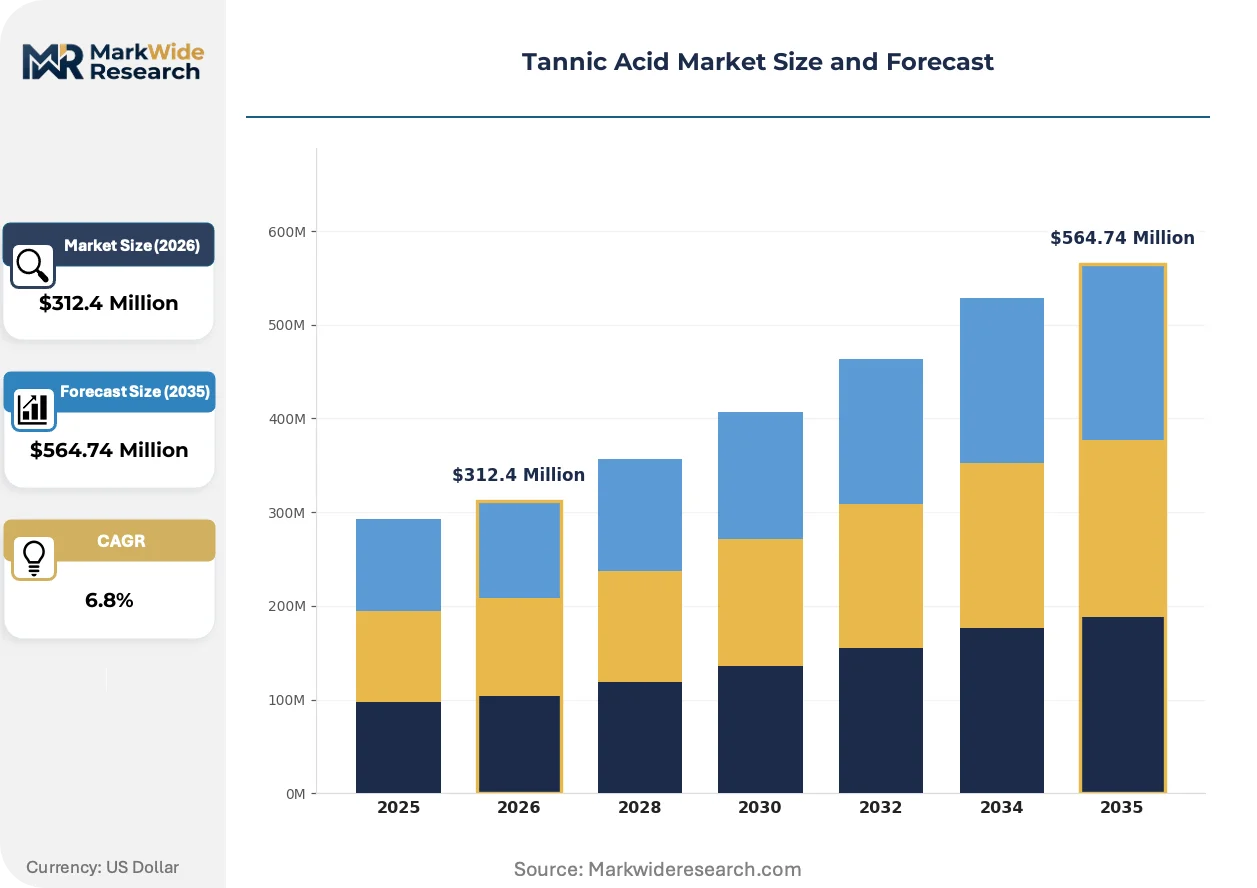
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzable Tannins, Condensed Tannins, Synthetic Tannins, Others Application: Food Preservative, Pharmaceutical Excipients, Leather Tanning, Cosmetics End User: Food Industry, Cosmetics Manufacturers, Pharmaceutical Companies, Leather Industry Distribution Channel: Online Retail, Direct Sales, Specialty Stores, Wholesale Distributors |
| Companies Covered | Ajinomoto Co., Inc., Polson Ltd., Tannin Corporation, Zhushan County Tianxin Medical & Chemical Co., Ltd., Laffort SA, Silvateam, Tanac S.A., Triveni Chemicals, Hubei Tianxin Biotech Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tannic Acid Market Strategic Shifts
Extraction technology convergence with pharmaceutical purification standards is redefining competitive boundaries between traditional tannin suppliers and specialized botanical extract houses.
Membrane filtration coupled with supercritical CO2 extraction is unifying quality tiers previously separated by crude versus refined product categories. Pharmaceutical formulators in Germany and Switzerland are adopting these methods to secure USP-grade material without relying on Chinese gallnut intermediates. This technology shift is compressing the historical premium between food-grade and pharmaceutical-grade pricing bands.
EFSA's pending reassessment of hydrolyzable tannin acceptable daily intake is forcing reformulation across European oral care and dietary supplement portfolios. Manufacturers are preemptively reducing maximum concentrations in anticipation of stricter limits. The wine and beverage segment faces particular exposure given tannic acid's role in astringency modulation and color stabilization.
Buyer consolidation among multinational pharmaceutical excipient distributors is disintermediating regional extractors who previously sold direct to mid-tier formulators. Three specialized chemical distributors now control the majority of European pharmaceutical-grade tannin offtake. This channel compression is most visible in Italy and Spain, where family-owned extractors are surrendering margin to secure volume commitments.
Tannic Acid Market Segmentation
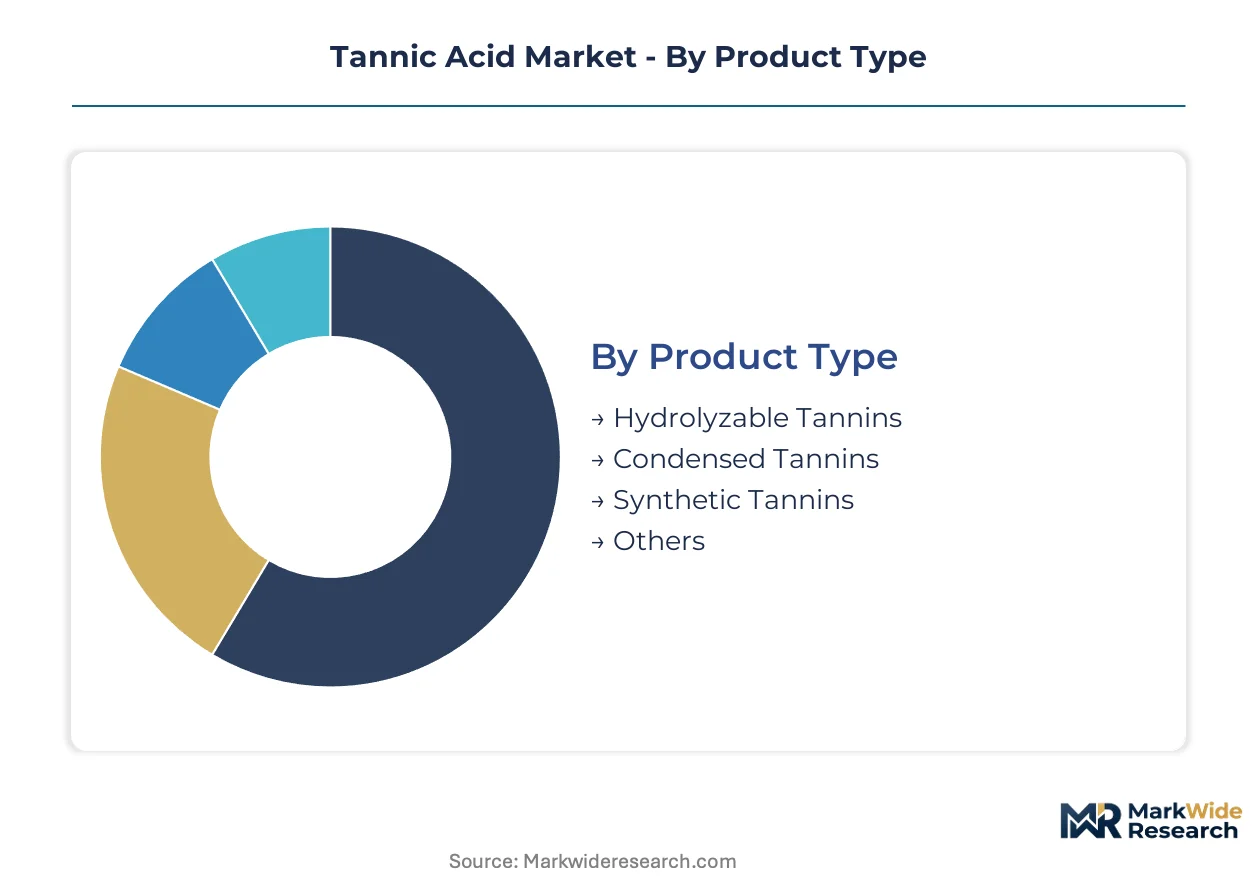
Tannic acid procurement patterns diverge sharply across purity grades and end-use specifications. Pharmaceutical formulators demand pharmacopeial certification that food-grade suppliers cannot fulfill, while leather processors prioritize volume throughput over analytical traceability.
Product Type:
Specification thresholds separate pharmaceutical-grade from industrial-grade supply tiers, with extraction chemistry determining regulatory acceptance.
- Hydrolyzable Tannins:These polyphenols contain ester-linked gallic acid units that hydrolyze under acidic conditions, yielding predictable gallic acid release profiles. Demand concentrates among Swiss and German pharmaceutical coaters seeking USP-grade enteric coating polymers with documented impurity profiles. EFSA's pending daily intake reassessment threatens formulation maximums across oral care applications.
- Condensed Tannins:Flavonoid-based polymers resist hydrolysis and bind proteins through covalent cross-linking rather than precipitation. Italian and Spanish leather tanneries in the Arzignano cluster consume the majority of quebracho and mimosa-derived supply, though margin compression from synthetic alternatives limits price elasticity.
- Synthetic Tannins:Petrochemical-derived phenolic condensates maintain cost advantages in wood adhesive and metal chelation applications where natural-source claims carry no premium.
- Others:Semi-synthetic hybrids and modified natural extracts occupy narrow niches in textile dyeing and ink formulations.
Mature deployment sits with Condensed Tannins. Newer deployment is concentrated in Hydrolyzable Tannins.
Application:
End-use certification requirements create non-overlapping supply pools that extractors cannot serve without dedicated equipment and analytical capabilities.
- Pharmaceutical Excipients:Enteric coating formulators in Basel and Frankfurt specify hydrolyzable tannin batches with HPLC-MS verified gallic acid purity above pharmacopeial thresholds. FDA food additive petition completion timelines of 18-36 months restrict supplier qualification to well-capitalized extractors with parallel regulatory submission capabilities.
- Food Preservative:Antioxidant and antimicrobial applications in wine stabilization and beverage astringency modulation face reformulation pressure from EFSA's anticipated hydrolyzable tannin intake limit reductions.
- Leather Tanning:Vegetable tanning of luxury hides in Tuscany and Veneto relies on condensed tannin formulations with consistent color development and shrinkage resistance.
- Cosmetics:Clean-label personal care brands in France and Germany specify REACH-registered natural tannins as synthetic alternatives face registration cost barriers.
Volume concentration remains in Leather Tanning. Value expansion is climbing the fastest in Pharmaceutical Excipients.
End User:
Buyer scale and technical sophistication determine whether procurement flows through distributors or direct contractual relationships with extractors.
- Pharmaceutical Companies:Multinational excipient distributors in Milan and Barcelona now control the majority of European pharmaceutical-grade offtake, disintermediating regional extractors who previously sold direct.
- Food Industry:Wine and beverage formulators in Bordeaux and Rioja source hydrolyzable tannins for color stabilization and mouthfeel modulation, with shorter lead times from Hubei province processors.
- Cosmetics Manufacturers:Natural-source claims accelerate tannin incorporation into European personal care as REACH registration costs filter synthetic competitors.
- Leather Industry:Italian tannery consortia negotiate volume contracts with South American quebracho processors, insulating against spot gallnut price volatility.
Contractual sophistication is highest with Pharmaceutical Companies. Price sensitivity dominates with Leather Industry.
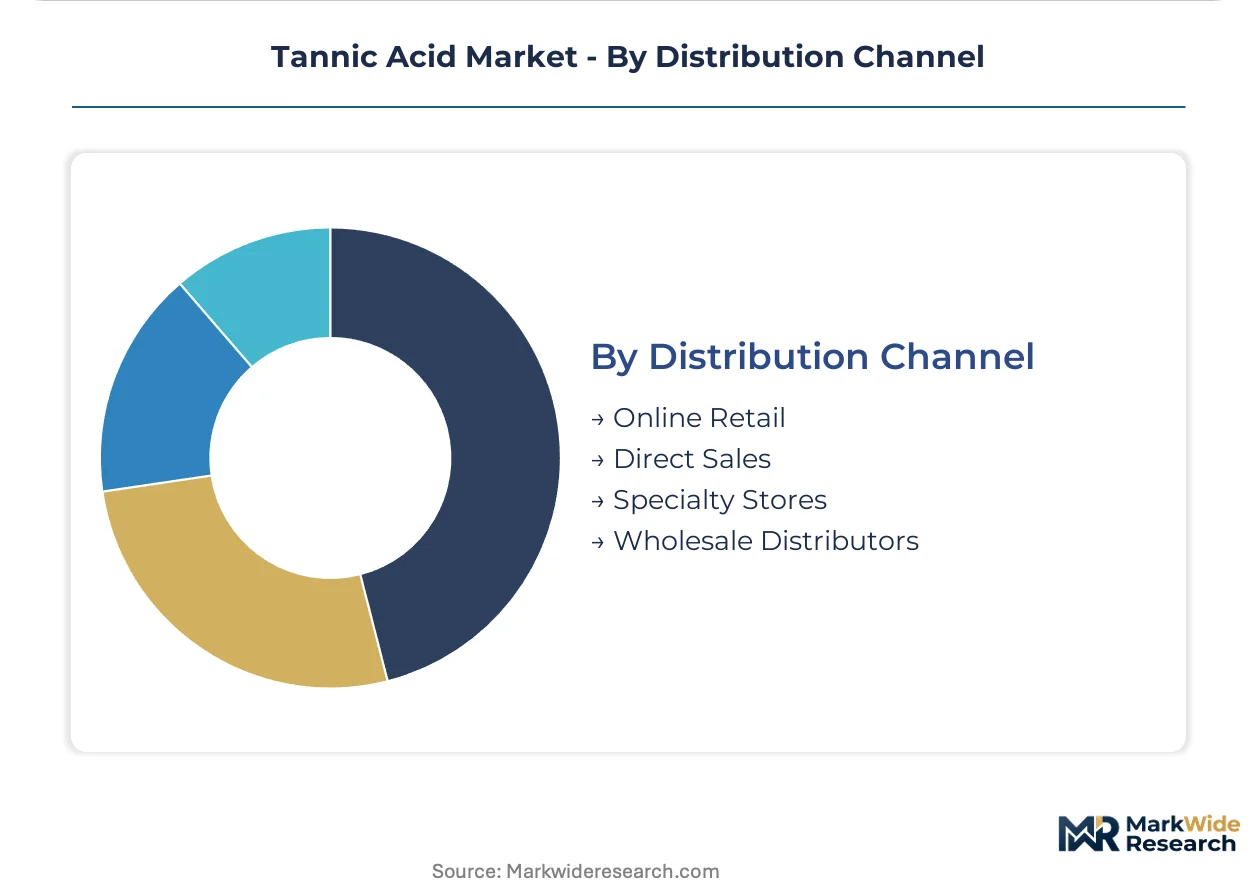
Distribution Channel:
Channel selection reflects lot size requirements and the need for technical support versus commodity pricing.
- Direct Sales:Pharmaceutical and large-scale leather processors negotiate multi-year supply agreements with Silvateam and Tanac S.A. for certified batches with documented chain of custody.
- Wholesale Distributors:Regional chemical distributors stock food-grade and technical-grade materials for mid-tier formulators lacking volume to justify direct extractor relationships.
- Online Retail:Small-scale cosmetics manufacturers and research laboratories procure gram-to-kilogram quantities of analytical-grade reference materials.
- Specialty Stores:Artisanal tanners and boutique winemakers access curated tannin selections with application-specific technical guidance.
Volume flows through Wholesale Distributors. Technical complexity drives preference for Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the heaviest procurement pull for tannic acid, with Hubei province processing clusters supplying both hydrolyzable and condensed tannin variants to pharmaceutical and food formulators across East Asia.
China
Hubei province gallnut harvests feed domestic pharmaceutical coating and wine stabilization demand. SAMR enforces GB standards on heavy metal limits and pesticide residues for extract exports. Zhushan County processors dominate captive sourcing networks, shortening lead times for regional formulators versus import-dependent competitors.
Germany
Basel and Frankfurt pharmaceutical coaters specify USP-grade hydrolyzable tannins for enteric coating applications. ECHA REACH registration requirements govern purity and impurity profiling for cosmetic and food additive placements. Bavarian extraction technology specialists deploy membrane filtration systems to secure pharmaceutical-grade material without Chinese intermediates.
Italy
Tuscan and Veneto leather tanneries consume condensed tannin volumes for luxury hide vegetable tanning. EFSA safety reassessments for hydrolyzable tannin daily intake limits threaten formulation maximums across nutrition products. The Arzignano tanning cluster negotiates volume contracts with South American quebracho processors to insulate against spot price volatility.
United States
Pharmaceutical excipient distributors in the Northeast control majority offtake for enteric coating applications. FDA food additive petition timelines of 18-36 months restrict supplier qualification to well-capitalized extractors. Midwestern formulators await GRAS status determinations for gallic acid derivatives to complete regulatory pathways.
Brazil
Quebracho forestry operations in the Gran Chaco region supply condensed tannin feedstock for European leather tanning. ANVISA oversight shapes import specifications for pharmaceutical-grade extracts. São Paulo-based distributors channel South American supply into Italian and Spanish tanning consortia.
Tannic Acid Market Competitive Environment
Backward integration into forestry assets dominates the current landscape as producers secure captive raw material through managed woodland leases. The vendor base separates into three tiers: integrated forestry operators, specialized extraction houses, and regional chemical distributors. Two archetypes define competitive positioning—those controlling upstream gallnut or quebracho supply, and those commanding pharmacopeial purification capabilities. M&A activity concentrates among mid-tier extractors seeking REACH registration assets, while capacity expansion focuses on closed-loop extraction systems for pharmaceutical-grade output.
Within the integrated forestry tier, Silvateam exemplifies upstream control through chestnut and quebracho woodland management, while Tanac S.A. occupies a position among specialized extraction houses serving wine and beverage applications. Zhushan County Tianxin Medical & Chemical Co., Ltd. anchors the Chinese supply base through Hubei province gallnut processing dominance. These three represent distinct strategic archetypes: European forestry integration, application-specific purification, and Asian raw material concentration.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Polson Ltd. |
| Tannin Corporation |
| Zhushan County Tianxin Medical & Chemical Co., Ltd. |
| Laffort SA |
| Silvateam |
| Tanac S.A. |
| Triveni Chemicals |
| Hubei Tianxin Biotech Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade hydrolyzable tannin certification against food-grade commodity streams creates a bifurcated pricing architecture that segments procurement channels, extraction equipment investments, and buyer-seller contractual terms across the value chain. REACH-registered USP-grade batches command substantial premiums over technical-grade quebracho extracts, while gallnut spot price volatility transmits asymmetrically through these tiers based on backward integration status and regional processing capabilities.
Pricing Analysis
Volume-mass leather tanning applications operate on thin margin pools where synthetic phenolic alternatives exert persistent downward pressure, while pharmaceutical excipient contracts reward pharmacopeial purity with durable pricing power. Price differentiation rests on HPLC-MS certification thresholds and FDA food additive petition completion status. Cost compression in condensed tannin feeds intensifies because South American quebracho processors compete for Italian tannery offtake. Leather processors remain most price-sensitive; Swiss pharmaceutical coaters exhibit least sensitivity given regulatory switching costs.
Supply Chain Analysis
China's SAMR-enforced domestic-content standards for gallnut-derived extracts reshape sourcing patterns as Hubei province processors capture regional pharmaceutical and wine stabilization demand. Raw material supply draws from Chinese gallnut harvests, Turkish oak galls, and Brazilian quebracho forestry. Single-source vulnerability concentrates around insect-gall formation dependency on specific Quercus species. Distribution runs through multinational chemical distributors for pharmaceutical-grade volumes, with direct sales governing large-scale leather contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive forestry assets or specialized extraction capabilities constitutes the defining competitive race, with upstream control over quebracho woodlands or Hubei gallnut processing clusters determining margin sustainability against synthetic substitution threats.
For Market Incumbents: Deploy closed-loop extraction system upgrades to defend pharmaceutical-grade positioning against emerging botanical extract houses with membrane filtration capabilities. Consolidate regional extractor networks in Italy and Spain to secure REACH registration assets before channel compression accelerates. Synthetic polyphenol cost advantages in leather tanning represent the core threat requiring volume contract lock-ins with Arzignano tannery consortia. For New Entrants and Emerging Players: The premium-to-economy price gap in cosmetic-grade natural tannins offers entry traction as REACH registration costs filter mid-tier synthetic competitors from European personal care supply pools. Target U.S. pharmaceutical coating applications awaiting GRAS status determinations for gallic acid derivatives. Pursue technology licensing arrangements with Bavarian membrane filtration specialists to bypass capital-intensive equipment buildouts. For Investors and Strategic Acquirers: Re-rating potential sits with specialized extraction houses possessing parallel FDA-EFSA-SAMR submission capabilities given pending regulatory clarity on hydrolyzable tannin daily intake limits. Long-term viability favors assets with demonstrated pharmacopeial purification competence over commodity condensed tannin operators. Monitor EFSA safety reassessment publication timelines as the critical inflection signal for formulation maximum adjustments across nutrition and oral care portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forestry Assets | Silvateam's chestnut and quebracho woodland leases insulate margin structures from spot gallnut price swings in Anatolia. |
| Pharmaceutical-Grade Purification Capacity Expansion | Closed-loop extraction systems replace open-vat processing to meet USP-grade HPLC-MS verification standards for Basel coaters. |
| Multi-Jurisdiction Regulatory Submission | Parallel FDA food additive petitions and EFSA dossiers compress 18-36 month commercialization cycles for novel excipient grades. |
| Long-term Supply Agreement with Tannery Consortia | Arzignano cluster volume contracts protect quebracho processors against synthetic substitution in luxury hide vegetable tanning. |
| Membrane Filtration Technology Licensing | German and Swiss pharmaceutical formulators adopt supercritical CO2 extraction to bypass Chinese gallnut intermediate dependencies. |
Study Parameters
Independent corroboration across extraction plant managers, pharmaceutical procurement leads at excipient distributors, leather tannery technical directors, and cosmetic formulator R&D heads underwrites the qualitative findings. Secondary validation incorporated customs trade data for gallnut and quebracho extract flows, EFSA safety assessment documentation, FDA food additive petition filings, and SEC disclosures from publicly traded botanical extract houses. Bottom-up volume estimates from regional processing clusters were triangulated against top-down demand projections from end-use industries.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects and grade-tier shifts. Segmentation dimensions modeled include hydrolyzable versus condensed versus synthetic tannin chemistry, pharmaceutical excipient versus food preservative versus leather tanning versus cosmetic application, and direct sales versus wholesale distributor versus online retail channel. CAGRs were derived from normalized historical baselines projected through assumption-based scenario testing. Forecast inputs incorporated EFSA daily intake limit sensitivity analysis and SAMR heavy metal enforcement trajectory.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time gallnut harvest yield data and proprietary extractor cost structures introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding REACH implementation timelines and FDA petition approval velocities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Guaiacwood Oil Market
Flavor and Fragrance Chemicals
Sensory Modifiers Market
Flavor and Fragrance Chemicals
Fragrance Wax Melts Market
Flavor and Fragrance Chemicals
Peel Oil Market
Flavor and Fragrance Chemicals
Middle East and Africa Deodorants Market
Flavor and Fragrance Chemicals
Middle East and Africa Aroma Chemicals Market
Flavor and Fragrance Chemicals
United States Aroma Chemicals Market
Flavor and Fragrance Chemicals
Perfumes and Deodorants Market
Flavor and Fragrance Chemicals
Camphor Market
Flavor and Fragrance Chemicals
Aromatic Compounds Market
Flavor and Fragrance Chemicals
Global Solid Perfume Market
Flavor and Fragrance Chemicals
Global Bio Vanillin Market
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Anisole Market
Flavor and Fragrance Chemicals
Ethyl Vanillin Market
Flavor and Fragrance Chemicals
Aroma Chemicals Market