
 FMCG B2B E-Commerce Market | 2026-2036
FMCG B2B E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
FMCG B2B E-Commerce Market Foresight
Market Context
Recycled and bio-based packaging materials are restructuring unit economics across shelf-stable categories as CPG manufacturers pass through sustainability premiums. Amazon Business leverages its fulfillment density to compress delivery windows for institutional buyers operating thin-inventory models. UNFI anchors its competitive position through proprietary cold-chain logistics that service independent grocers with perishable SKU breadth. Alibaba Group Holding dominates cross-border procurement corridors by integrating trade finance directly into its B2B checkout flow.
Technical Definition and Segment Structure
FMCG B2B E-Commerce denotes digital platforms facilitating bulk transactions of fast-moving consumer goods between manufacturers or distributors and business purchasers, typically operating on minimum order quantities of one pallet or greater with net-30 to net-60 payment terms embedded in enterprise procurement workflows. Packaged Foods commands the largest share of platform gross merchandise value due to replenishment frequency, though Pet Care registers the fastest velocity expansion as veterinary chains and specialty retailers consolidate supplier relationships through subscription ordering methods. Third-Party Marketplaces capture disproportionate margin pools by aggregating fragmented regional distributors, while API Integrations represent the structural growth vector as ERP-native procurement displaces standalone portal logins.
Regulatory Frame and Outlook
The EU Digital Services Act imposes transparency obligations on algorithmic product ranking that reshape how FMCG suppliers achieve visibility across European marketplace platforms. India's ONDC protocol and the country's FSSAI labeling requirements collectively determine which suppliers qualify for digital procurement slots in the world's most populous market. BIS certification standards for packaged goods create non-tariff barriers that platform operators must navigate to onboard Indian domestic manufacturers. Stakeholders must monitor which regulatory jurisdiction—Brussels, New Delhi, or Washington—sets the de facto compliance baseline for cross-border FMCG platform operations.
Market Dynamics
API-native procurement workflows are compressing order cycles and displacing phone-and-fax relationships between distributors and independent retailers across fragmented retail corridors.
Growth Catalysts
- India's ONDC protocol:The interoperability mandate dismantles platform monopolies and redirects procurement flows toward integrated supplier networks, opening access for regional distributors previously locked out of digital marketplaces.
- Subscription ordering methods:Veterinary chains and specialty pet retailers consolidate supplier relationships through automated replenishment systems, locking in recurring revenue streams for platform operators.
- Tier-two city concentration:India's secondary urban centers and Southeast Asian manufacturing corridors generate first-mover advantages for digital wholesalers where fragmented retail infrastructure limits incumbent competition.
Market Restraints
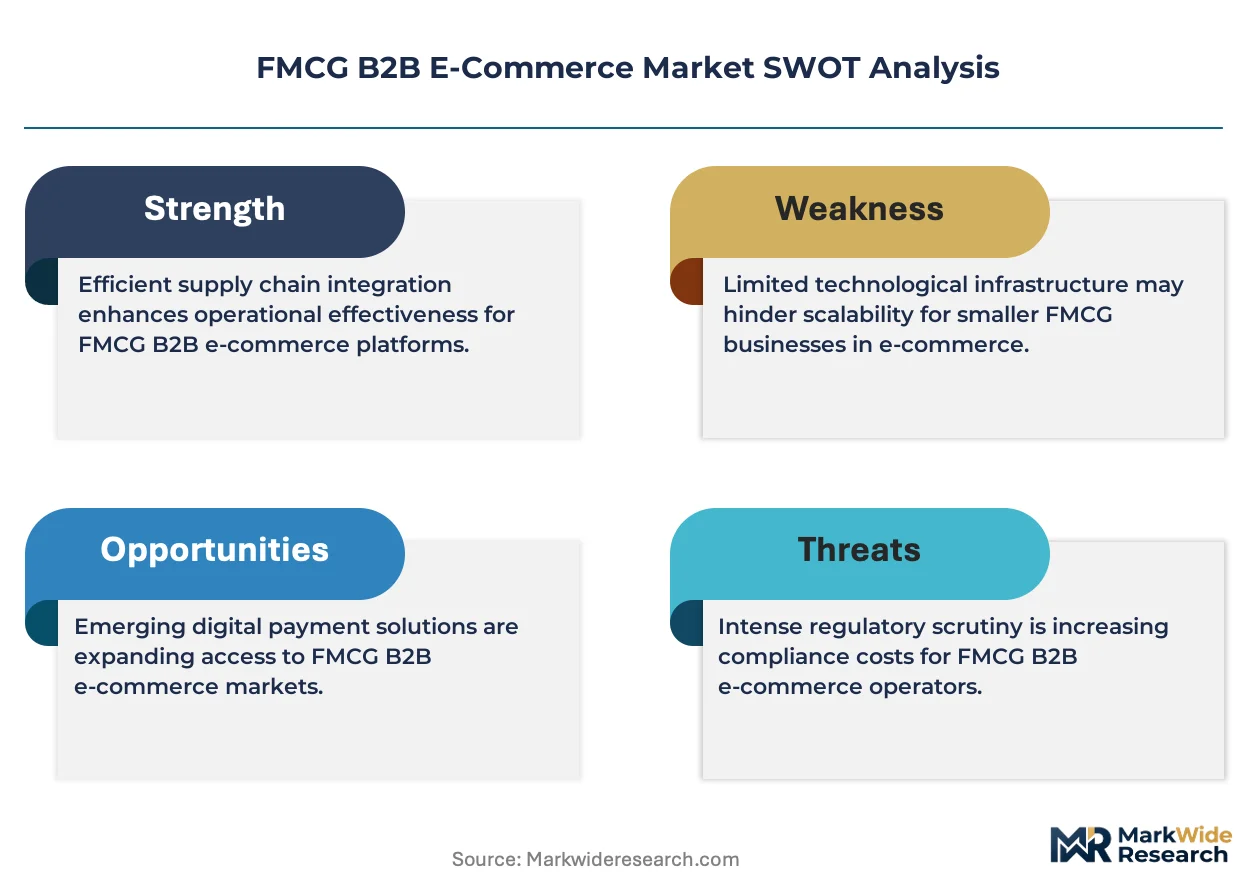
- Cold-chain logistics capex:Perishable SKU breadth demands proprietary refrigerated fulfillment networks that compress margins for entrants lacking UNFI-scale density.
- BIS certification barriers:India's Bureau of Indian Standards creates non-tariff onboarding friction for domestic packaged goods manufacturers seeking platform qualification.
- Thin-inventory buyer models:Institutional purchasers operating minimal stock levels compress delivery window tolerance, forcing fulfillment infrastructure investments that strain working capital.
Strategic Opportunities
- ERP-native procurement displacement:Enterprise resource planning embedded ordering displaces standalone portal logins, creating stickiness for API-integrated platforms serving mid-market distributors.
- FSSAI labeling alignment:India's food safety regulator mandates digital traceability requirements that favor compliant suppliers with pre-integrated certification documentation.
- Trade finance integration:Net-30 to net-60 payment terms embedded in checkout flows unlock working capital for cash-constrained independent grocers in Southeast Asian corridors.
Industry Challenges
- Legacy ERP integration complexity:Distributor back-office systems require custom API development to synchronize inventory, pricing, and order management with marketplace platforms.
- Algorithmic ranking transparency:EU Digital Services Act obligations force operators to disclose product visibility mechanics, complicating supplier relationship management across European marketplaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FMCG B2B E-Commerce Market |
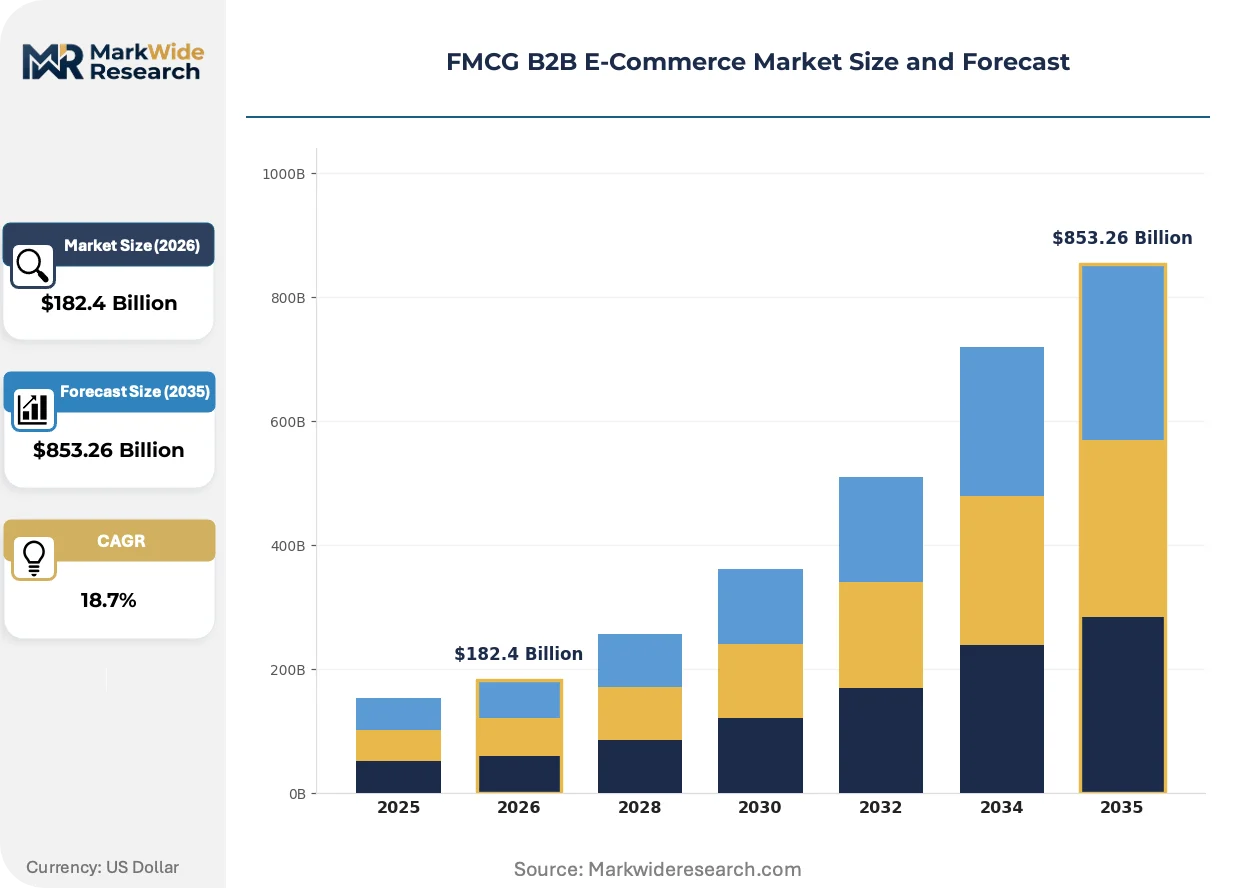
| Market Size in 2026 | $182.4 Billion |
| Market Size in 2035 | $853.26 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Packaged Foods, Personal Care, Household Care, Beverages, Pet Care Customer Type: Wholesalers, Institutional Buyers, Corporate Accounts, Retailers, Distributors Platform Type: Proprietary Websites, Third-Party Marketplaces, Mobile Apps, Enterprise Portals, API Integrations Ordering Method: Bulk Purchase, Subscription Models, Just-In-Time Ordering, Contractual Procurement, Spot Buying |
| Companies Covered | US Foods, C&S Wholesale Grocers, Amazon Business, Reliance Retail, SpartanNash, Walmart Business, UNFI, Alibaba Group Holding, Sysco Shop, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FMCG B2B E-Commerce Market Shifts & Advancements
Digital procurement infrastructure is rewriting how shelf-stable and perishable categories flow from manufacturer to independent retail, with sustainability premiums and embedded finance emerging as competitive differentiators.
Blockchain-enabled provenance tracking is expanding into packaged foods and personal care categories, with Indian and Southeast Asian distributors adopting the technology to satisfy FSSAI and export-market documentation requirements. Independent grocers now demand lot-level traceability as a table-stakes qualification, compressing supplier onboarding timelines for platforms that lack pre-integrated chain-of-custody systems.
The EU Digital Services Act imposes algorithmic ranking transparency obligations that reshape how FMCG suppliers achieve visibility across European marketplace platforms. Operators must now disclose the weighting factors determining product placement, forcing recalibration of vendor relationship strategies and promotional spend allocation. Packaged foods suppliers with established brand equity face margin pressure as algorithmic neutrality erodes historical placement advantages.
Independent convenience store chains now mandate embedded trade finance at checkout, replacing traditional 30-day open-account terms with platform-facilitated working capital. This behavioral shift concentrates procurement relationships with operators offering integrated credit facilities, disadvantaging pure-play logistics providers. India's tier-two cities and Vietnam's provincial manufacturing zones exhibit the fastest adoption velocity as cash-constrained retailers prioritize liquidity over unit price optimization.
FMCG B2B E-Commerce Market Segmentation
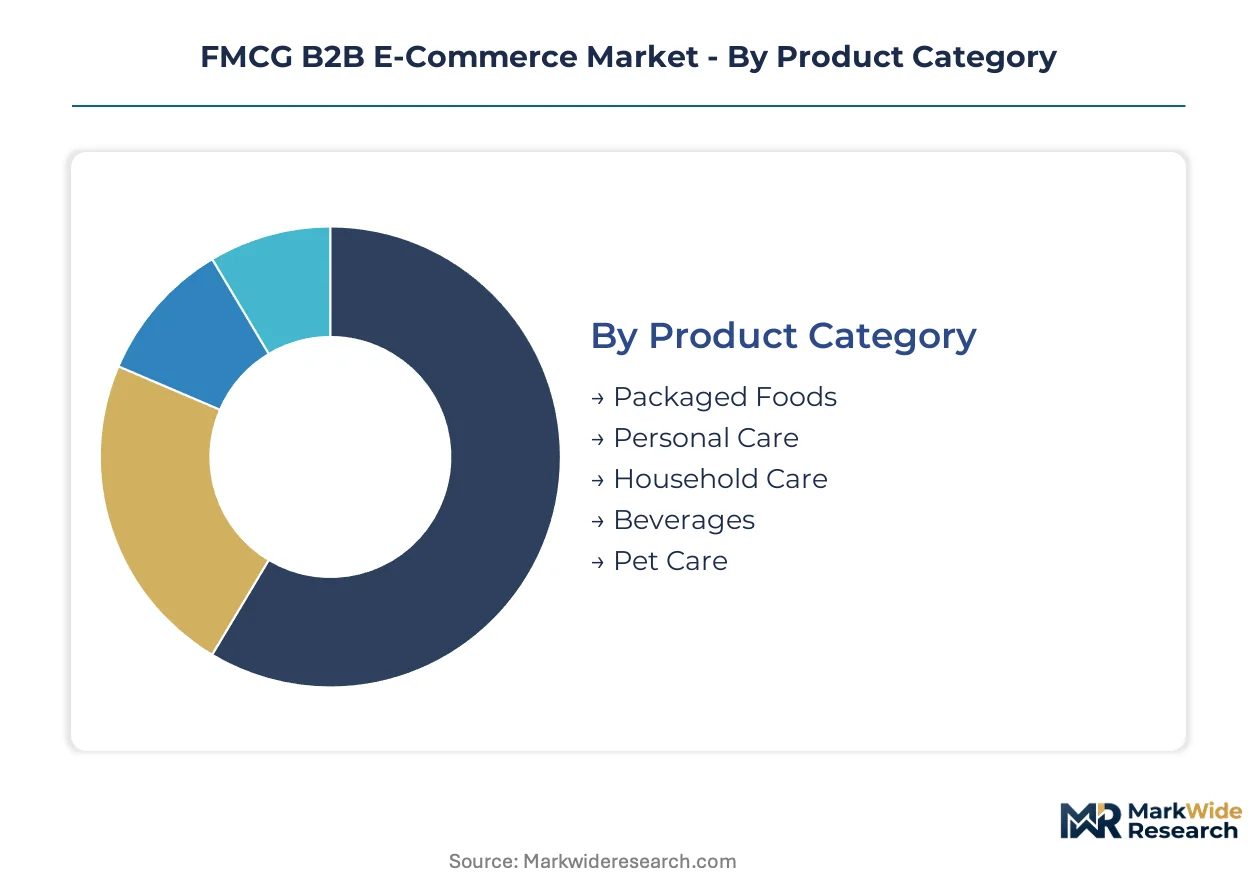
Segmentation in FMCG B2B E-Commerce reveals how procurement workflows, buyer liquidity constraints, and platform integration depth determine competitive positioning. Understanding these divides exposes where margin pools concentrate and which infrastructure investments unlock scalable revenue.
Product Category:
Buyers in this category differentiate by replenishment velocity, perishability tolerance, and sustainability certification requirements that reshape supplier qualification thresholds.
- Packaged Foods:Shelf-stable SKUs with standardized pallet configurations dominate platform gross merchandise value through high-frequency reorder cycles. Demand concentrates among independent grocers in India's tier-two cities where digital procurement replaces phone-and-fax relationships with regional distributors.
- Personal Care:SKU fragmentation across formulations and pack sizes requires configurable minimum order quantities that strain legacy distributor ERP systems. Procurement flows favor platforms with pre-integrated BIS certification documentation that accelerates supplier onboarding.
- Household Care:Concentrated manufacturing bases and predictable demand patterns suit bulk contractual arrangements with extended payment terms.
- Beverages:Weight-to-value ratios and seasonal demand spikes necessitate flexible logistics networks with cross-docking capabilities.
- Pet Care:Veterinary chains and specialty retailers consolidate supplier relationships through automated replenishment systems that lock in recurring platform revenue.
Volume sits with Packaged Foods; growth tilts toward Pet Care.
Customer Type:
Working capital availability and inventory carrying capacity separate buyers in this dimension, determining which platform features—trade finance, delivery windows, or SKU breadth—drive procurement decisions.
- Wholesalers:Regional distributors aggregate fragmented retail demand and require API-native inventory synchronization to prevent stockouts across multiple buyer tiers. Southeast Asian manufacturing corridors generate first-mover advantages for platforms serving cash-constrained intermediaries.
- Institutional Buyers:Thin-inventory operators demand compressed delivery windows that force fulfillment density investments and strain working capital for platform entrants.
- Corporate Accounts:Centralized procurement departments prioritize ERP-embedded ordering workflows over standalone portal experiences.
- Retailers:Independent convenience store chains mandate embedded trade finance at checkout, replacing traditional open-account terms with platform-facilitated liquidity.
- Distributors:Legacy back-office systems require custom API development to synchronize pricing and order management with marketplace infrastructure.
Transaction volume concentrates with Wholesalers; steepest expansion trajectory belongs to Institutional Buyers.
Platform Type:
Integration depth and data ownership rights distinguish buyers here, with procurement sophistication determining willingness to trade platform neutrality for workflow automation.
- Proprietary Websites:Single-brand portals offer direct manufacturer relationships but lack cross-supplier comparison tools that independent grocers increasingly demand.
- Third-Party Marketplaces:Aggregators capture disproportionate margin pools by consolidating fragmented regional distributors under unified checkout experiences with embedded net-30 to net-60 terms.
- Mobile Apps:Interface simplicity suits smaller retailers with limited procurement staff, though order complexity constraints limit adoption for bulk pallet transactions.
- Enterprise Portals:Standalone login requirements face displacement as ERP-native procurement gains traction among mid-market distributors.
- API Integrations:ERP-embedded ordering represents the structural growth vector, creating stickiness for platforms that synchronize inventory, pricing, and fulfillment status directly into buyer back-office systems.
Revenue pools concentrate with Third-Party Marketplaces; API Integrations gain share fastest.
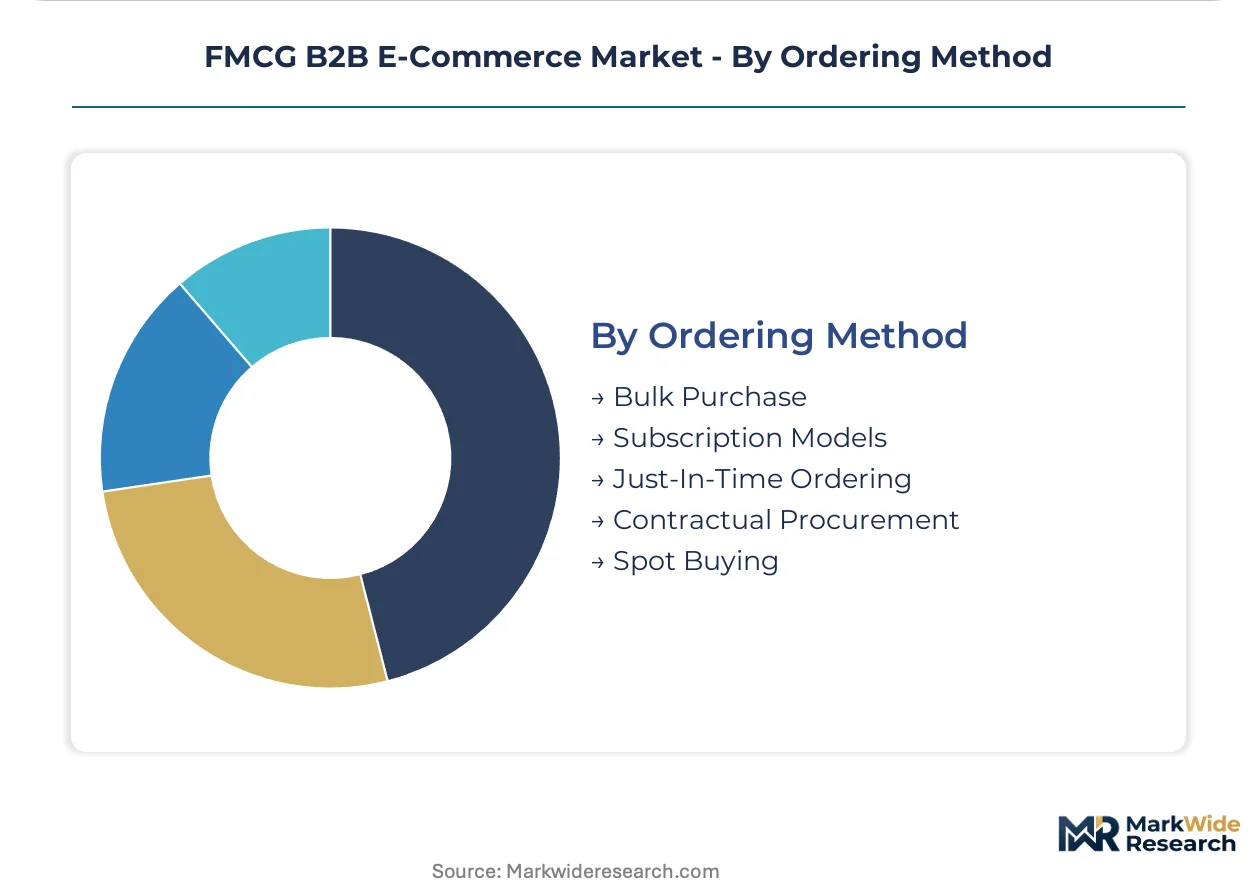
Ordering Method:
Demand predictability and cash flow timing separate buyers in this final dimension, with automation appetite varying by buyer scale and category volatility.
- Bulk Purchase:Pallet-minimum transactions dominate platform economics, with standardized configurations reducing fulfillment complexity for shelf-stable categories.
- Subscription Models:Automated replenishment locks in recurring revenue streams, particularly in Pet Care where veterinary chains prioritize supplier consolidation over price optimization.
- Just-In-Time Ordering:Minimal inventory models compress delivery tolerance to 24-48 hours, requiring proprietary cold-chain networks for perishable SKU breadth.
- Contractual Procurement:Multi-month agreements suit beverage and household care categories with predictable consumption patterns.
- Spot Buying:Opportunistic purchasing responds to promotional pricing or supply disruptions, though fragmented demand complicates fulfillment density.
Platform liquidity concentrates with Bulk Purchase; automation adoption climbs fastest in Subscription Models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates procurement platform expansion as ONDC protocol adoption redirects distributor relationships toward API-integrated networks. Southeast Asian manufacturing corridors generate first-mover advantages for digital wholesalers serving cash-constrained intermediaries. Brazil's independent retail fragmentation creates comparable entry opportunities for embedded-finance platforms.
India
Tier-two cities including Indore, Lucknow, and Coimbatore drive platform volume as independent grocers abandon phone-and-fax ordering. FSSAI labeling mandates and BIS certification standards filter supplier eligibility for digital procurement slots. The Delhi-NCR corridor anchors technical infrastructure development for marketplace operators scaling nationwide.
United States
Institutional buyers operating thin-inventory models compress delivery windows to 24-48 hours, forcing fulfillment density investments. FDA food safety regulations and USDA organic certification requirements shape supplier onboarding protocols. The Chicago metropolitan area concentrates cold-chain logistics infrastructure serving independent convenience store chains.
China
Cross-border procurement corridors integrate trade finance directly into B2B checkout flows, locking in distributor relationships. SAMR antitrust enforcement and GB standards compliance create platform operational constraints. The Yangtze River Delta manufacturing cluster generates supplier density for export-oriented marketplace operators.
Germany
EU Digital Services Act transparency obligations reshape algorithmic product ranking mechanics for FMCG suppliers. REACH chemical regulations and EFSA food safety standards determine packaged goods eligibility for platform listing. The Rhine-Ruhr industrial region anchors fulfillment infrastructure serving central European wholesale corridors.
Brazil
Independent convenience store chains in São Paulo and Rio de Janeiro metropolitan areas mandate embedded trade finance at checkout. ANVISA pharmaceutical and health product regulations extend to personal care categories sold through digital procurement channels. The Southeast region concentrates distributor aggregation platforms targeting fragmented retail infrastructure.
FMCG B2B E-Commerce Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with third-party marketplaces capturing disproportionate margin pools by consolidating fragmented regional distributors. The vendor base organizes around three strategic archetypes: vertically integrated logistics operators with proprietary cold-chain networks, API-native procurement platforms displacing standalone enterprise portals, and cross-border aggregators embedding trade finance into checkout flows. Competitive intensity manifests through M&A activity targeting regional distributor networks and capacity expansion into tier-two city corridors.
Among North American logistics operators, US Foods and UNFI occupy positions within the cold-chain infrastructure archetype, while Alibaba Group Holding exemplifies the cross-border trade finance integration model. These three companies represent distinct strategic vectors: domestic fulfillment density, perishable SKU breadth, and international procurement corridor control.
| Leading Market Players |
|---|
| US Foods |
| C&S Wholesale Grocers |
| Amazon Business |
| Reliance Retail |
| SpartanNash |
| Walmart Business |
| UNFI |
| Alibaba Group Holding |
| Sysco Shop |
| Others |
Supply & Pricing Matrix
Subscription ordering methods from veterinary chains and specialty pet retailers are forcing platforms to embed net-30 to net-60 terms directly into checkout flows, compressing margins for operators lacking trade-finance partnerships and widening spreads between API-integrated suppliers and phone-and-fax holdouts.
Pricing Analysis
Volume concentrates in bulk pallet transactions with standardized configurations, while margin pools accrue to subscription models locking in recurring revenue streams. Price differentiation hinges on FSSAI certification tier and embedded trade-finance availability, with cash-constrained independent grocers in India's tier-two cities exhibiting highest sensitivity. Pricing pressure stems from cold-chain logistics capex demands as UNFI-scale density becomes table stakes for perishable SKU breadth. Least price-sensitive buyers are institutional purchasers prioritizing 24-48 hour delivery windows over unit economics.
Supply Chain Analysis
Workforce availability constraints in Vietnam's provincial manufacturing zones and India's secondary urban centers are redirecting fulfillment infrastructure investments toward automation-heavy regional distribution hubs. Supply concentrates in China, India, and Indonesia, with raw material dependencies spanning recycled packaging substrates, cold-chain refrigerants, and API-enabled inventory synchronization software. Single-source vulnerability runs through proprietary ERP integration specialists serving legacy distributor back-office systems. Distribution runs through third-party marketplaces aggregating fragmented regional wholesalers under unified checkout experiences.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-native procurement workflows are displacing standalone enterprise portals and phone-and-fax relationships, marking a technology-transition phase where ERP-embedded ordering becomes the default procurement interface for mid-market distributors.
For Market Incumbents: Anchor competitive position through proprietary cold-chain density investments in India's tier-two cities and Southeast Asian manufacturing corridors where fragmented retail infrastructure limits challenger scale. Defend against API-native entrants by pre-integrating FSSAI and BIS certification documentation into supplier onboarding workflows, accelerating platform qualification timelines that lock in regional distributor relationships.
For New Entrants and Emerging Players: Embedded trade finance at checkout offers the most penetrable wedge into cash-constrained independent convenience store chains across Brazil's São Paulo metropolitan area and Vietnam's provincial retail zones. Target white-space in subscription ordering methods for Pet Care veterinary chains, where automated replenishment systems consolidate supplier relationships and generate recurring revenue visibility. Pursue go-to-market through ERP-native API integrations displacing standalone portal logins among mid-market distributors.
For Investors and Strategic Acquirers: Re-rating potential sits with API-integrated procurement platforms given ONDC protocol adoption redirecting procurement flows toward interoperable supplier networks. Long-term viability favors operators controlling trade-finance integration and cold-chain fulfillment density rather than pure-play logistics providers. Watch algorithmic ranking transparency enforcement under EU Digital Services Act as signal for margin compression on branded packaged goods suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Procurement Platform Launch | ERP-embedded ordering displaces standalone portals for mid-market distributors. |
| Cold-Chain Logistics Expansion | Proprietary refrigerated networks capture perishable SKU breadth from UNFI. |
| Trade Finance Integration | Net-30 to net-60 checkout terms unlock working capital for cash-constrained retailers. |
| ONDC Protocol Compliance Investment | Interoperability certification opens access to India's tier-two city procurement flows. |
| Subscription Ordering Infrastructure | Automated replenishment locks recurring revenue from veterinary chain consolidation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with platform operations executives, independent grocer procurement managers, cold-chain logistics directors, and ERP integration specialists. Bottom-up triangulation against top-down macroeconomic indicators validated volume and value estimates across the analysis window. Secondary sources encompassed FSSAI certification databases, BIS standards documentation, EU Digital Services Act implementation guidance, and ONDC protocol technical specifications.
Data-stream reconciliation across shipment manifests, marketplace gross merchandise value disclosures, and distributor inventory synchronization logs informed the analytical framework. Segmentation dimensions spanned product category velocity, customer type liquidity constraints, platform integration depth, and ordering method automation appetite. CAGRs derived from logistic growth curves fitted to historical adoption patterns, with sensitivity analysis around ONDC penetration rates and cold-chain capex cycles.
The model holds under sustained ONDC protocol adoption and stable trade-finance regulatory treatment; deviation in EU algorithmic transparency enforcement intensity or India BIS certification timeline compression would shift platform competitive dynamics. Forecasts reflect documented assumptions regarding ERP integration cost curves and independent retailer digital procurement adoption thresholds. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Europe E-Commerce Market
E-Commerce Solutions
Ambient Commerce Market
E-Commerce Solutions
Sweden E-Commerce Market
E-Commerce Solutions
China Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Poland E-Commerce Market
E-Commerce Solutions
North America E-Commerce Watch Market
E-Commerce Solutions
Europe E-Commerce Logistics Market
E-Commerce Solutions
Nigeria E-Commerce Market
E-Commerce Solutions
Japan Cross Border E Commerce Market
E-Commerce Solutions
Global Healthcare E-Commerce Market
E-Commerce Solutions
South Korea E-Commerce Market
E-Commerce Solutions
Cross-Border B2C E-Commerce Market
E-Commerce Solutions
Europe Automotive E-Commerce Market
E-Commerce Solutions
Austria E-Commerce Market
E-Commerce Solutions
Europe Food Platform-To-Consumer Delivery Market
E-Commerce Solutions
United States E-Commerce Market