
 South Africa Fruits and Vegetables Market | 2026-2036
South Africa Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Fruits and Vegetables Market Analytics
Precision irrigation and cold-chain digitization is reconfiguring how South African growers manage harvest quality and extend shelf life from farm to port. ZZ2 leverages its integrated farming network across Limpopo and Mpumalanga to control tomato and avocado supply pipelines. Capespan Group anchors Southern Hemisphere export logistics through its Cape Town port infrastructure and ripening facilities.
South Africa fruits and vegetables encompass fresh and minimally processed plant products cultivated across subtropical, Mediterranean, and temperate climatic zones, with citrus requiring minimum 10.5°Brix soluble solids for export-grade classification and leafy greens demanding hydrocooling within four hours of harvest to suppress respiration. Citrus dominates volume throughput through Durban and Cape Town harbors, while berries capture expanding margin pools through air-freight channels to Middle Eastern retail clients. Root vegetables sustain stable wholesale pricing through SPAR Group and Woolworths Holdings procurement contracts, though mesh bag and clamshell packaging formats face substitution pressure from cardboard-based retail-ready alternatives.
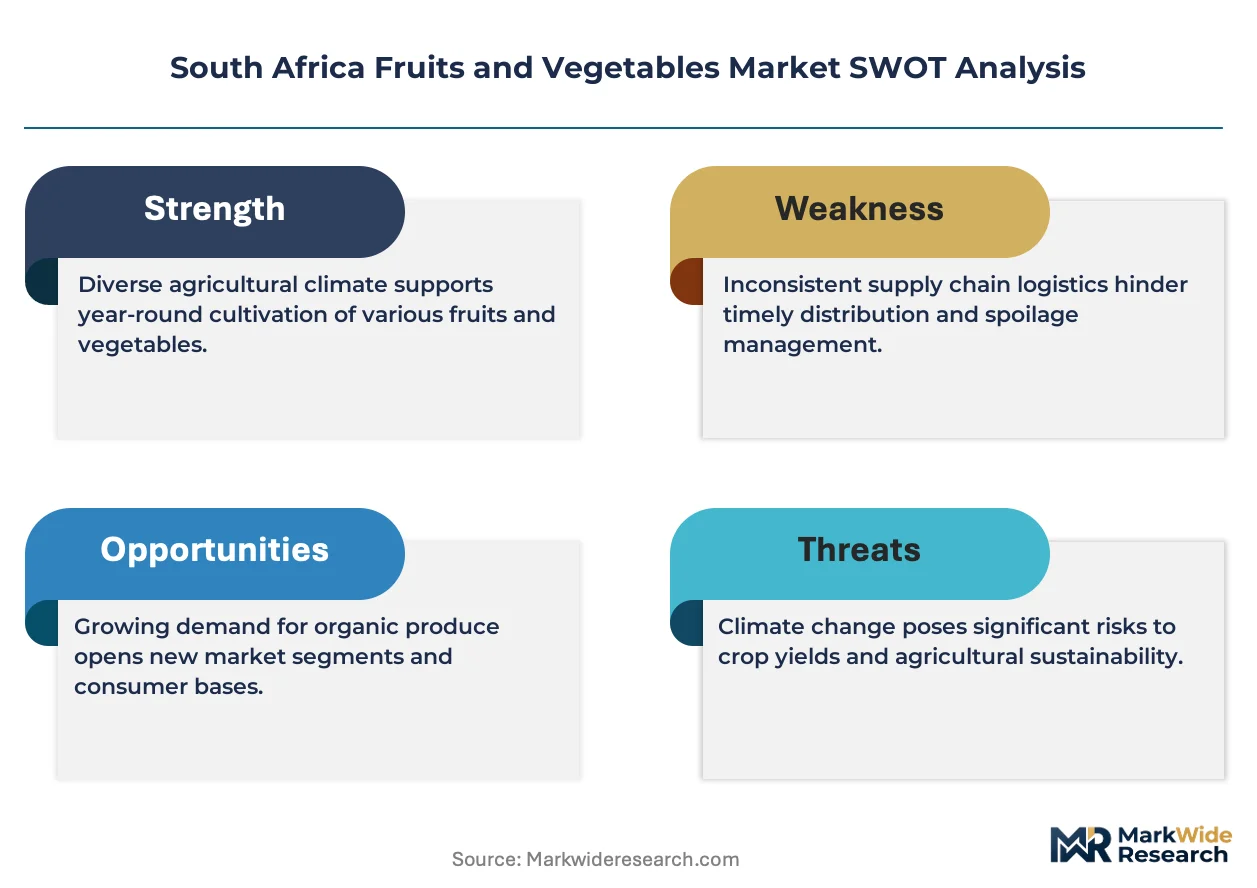
South Africa's Department of Agriculture, Land Reform and Rural Development enforces Plant Improvement Act certification for commercial cultivar propagation, while Perishable Products Export Control Board inspections govern EU and UK market access through adherence to F-Gas-aligned cold-chain standards. The country's national agricultural regulator coordinates with DAFF phytosanitary protocols to manage false codling moth interceptions that trigger border detention risks. Stakeholders must monitor water-use licensing reforms and load-shedding mitigation investments as determinants of irrigated hectare expansion and packhouse operating cost structures.
Market Dynamics
Load-shedding mitigation investments are reconfiguring packhouse operating cost structures across Gauteng and Western Cape, forcing growers to choose between diesel backup systems and solar-battery hybrid arrays for cold-chain continuity.
Growth Catalysts
- Precision irrigation deployment:Drip and subsurface systems in the Limpopo Valley are lifting water-use efficiency above flood-irrigation baselines, expanding viable hectare counts for water-stressed citrus and avocado orchards.
- EU F-Gas Regulation alignment:Cold-chain infrastructure upgrades to meet EU-aligned standards are unlocking detention-risk reduction at Rotterdam and Hamburg entry points for South African stone fruit exporters.
- Food service channel expansion:Gauteng's restaurant and hotel procurement networks are absorbing larger volumes of hydrocooled leafy greens, pulling supply away from traditional wet-market distribution.
Market Restraints
- Electricity cost volatility:Eskom tariff escalations and load-shedding frequency are compressing packhouse margin structures, particularly for smallholder cooperatives lacking capital for solar retrofits.
- Phytosanitary detention concentration:False codling moth interceptions at EU border inspection posts create asymmetric risk for Limpopo and Mpumalanga citrus shipments relative to Western Cape alternatives.
- Cardboard packaging substitution:Retail-ready cardboard clamshells are displacing mesh bag formats for root vegetables, forcing capital retooling at washing and grading facilities.
Strategic Opportunities
- Air-freight berry expansion:Middle Eastern retail clients are absorbing rising volumes of Western Cape blueberries and raspberries through Dubai and Doha hub connections, bypassing slower sea-freight channels.
- Plant Improvement Act certification:Commercial cultivar propagation licensing under DAFF protocols is creating captive germplasm revenue streams for established breeding operations.
- Hydrocooling technology convergence:Integration of forced-air cooling with hydrocooling systems is extending shelf life for leafy greens bound for distant domestic markets and export air freight.
Industry Challenges
- Water-use licensing timelines:Department of Water and Sanitation permit processing delays are stalling irrigated hectare expansion in the Olifants River catchment and other priority zones.
- Cold-chain technician scarcity:Refrigeration and controlled-atmosphere engineering skills are concentrating at Capespan Group and ZZ2, leaving mid-tier packhouses dependent on contract maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Fruits and Vegetables Market |
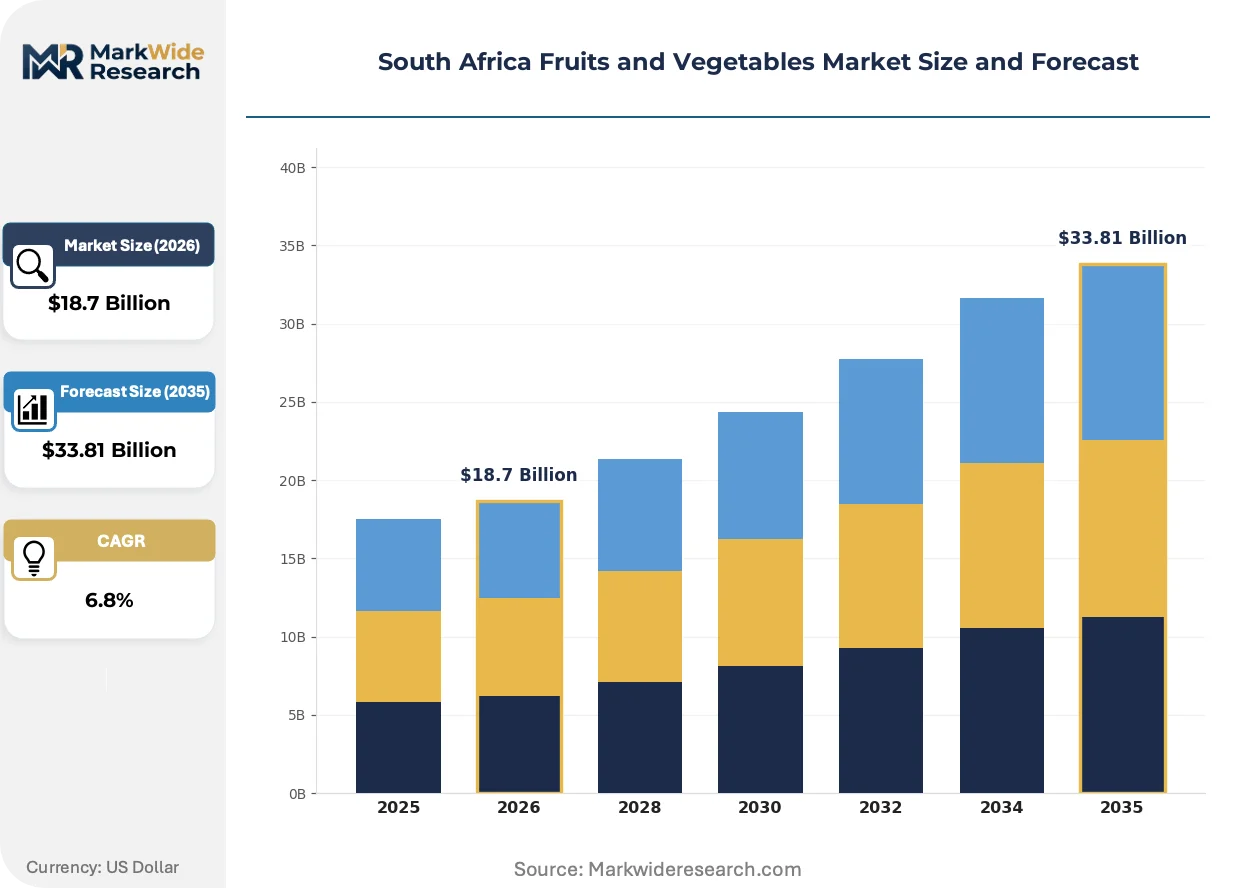
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus, Berries, Leafy Greens, Root Vegetables Distribution Channel: Retail Stores, Wholesalers, Online Markets, Farmers' Markets Packaging Type: Plastic Bags, Cardboard Boxes, Mesh Bags, Clamshell Containers End User: Consumers, Food Service, Retailers, Exporters |
| Companies Covered | ZZ2, Capespan Group, Westfalia Fruit, Dutoit Group, Freshworld International, The Karsten Group, Bertie van Zyl, Woolworths Holdings, SPAR Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Fruits and Vegetables Market Evolving Landscape
Digital infrastructure is penetrating harvest logistics and shelf-life extension protocols, compressing information asymmetries between farm gate and retail shelf while enabling predictive quality management.
Sensor-networked cold-chain monitoring is virtualizing temperature and ethylene exposure tracking from Limpopo packhouses through Cape Town port terminals. Woolworths Holdings and SPAR Group procurement teams are mandating real-time data feeds for premium produce categories. This virtualization is compressing insurance and rejection-cost exposures that previously accrued across multi-day transit gaps.
South Africa's Department of Agriculture, Land Reform and Rural Development is tightening Plant Improvement Act enforcement for commercial cultivar registration and propagation licensing. Breeders must now document distinctness, uniformity, and stability through extended field trials before market release. Citrus and avocado germplasm developers are responding by consolidating breeding programs to amortize compliance costs across larger variety portfolios.
Retail procurement consolidation is compressing supplier counts for standardized produce categories while expanding direct farmgate contracting for differentiated offerings. SPAR Group's centralized distribution centers are displacing traditional fresh produce market intermediaries for root vegetables and basic salad lines. Western Cape berry growers are responding by establishing captive air-freight booking arrangements with Emirates and Qatar Airways cargo divisions.
South Africa Fruits and Vegetables Market Segmentation
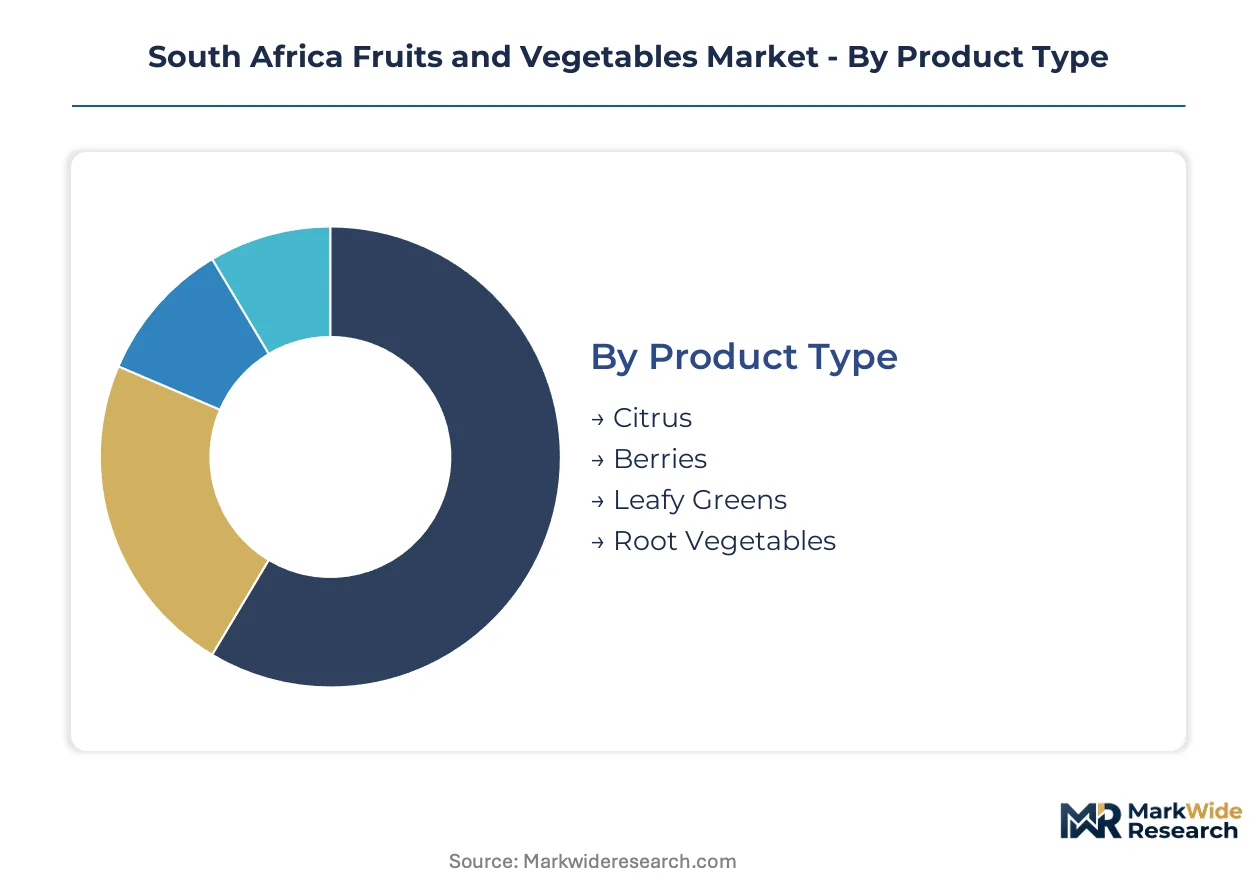
Segmentation reveals how South African growers navigate divergent margin structures across export-grade citrus, air-freight berries, and domestic retail channels. Each product and channel tier demands distinct cold-chain investments and phytosanitary compliance protocols.
Product Type:
Mature citrus operations coexist with emerging berry cultivation as water scarcity reshapes orchard economics across climatic zones.
- Citrus:Oranges, lemons, and grapefruit cultivated across Limpopo and Mpumalanga require minimum 10.5°Brix soluble solids for EU export classification. Durban and Cape Town harbors handle the majority of volume throughput, though false codling moth interceptions at Rotterdam create asymmetric detention risk for Limpopo shipments relative to Western Cape alternatives.
- Berries:Blueberries and raspberries from Western Cape farms capture premium margins through air-freight channels to Dubai and Doha retail clients. Hydrocooling within four hours of harvest suppresses respiration rates for these perishable categories, with Emirates and Qatar Airways cargo divisions absorbing rising booking volumes.
- Leafy Greens:Spinach, lettuce, and kale bound for Gauteng food service networks demand rapid forced-air cooling to extend shelf life through domestic distribution.
- Root Vegetables:Carrots, potatoes, and sweet potatoes sustain stable wholesale pricing through SPAR Group and Woolworths Holdings procurement contracts with longer storage tolerances.
Citrus handles the majority of throughput; berries are climbing the fastest on share as Middle Eastern retail demand accelerates.
Distribution Channel:
Channel selection determines cold-chain capital intensity and phytosanitary documentation burdens for South African growers.
- Retail Stores:SPAR Group and Woolworths Holdings centralized distribution centers mandate real-time temperature data feeds for premium produce categories, displacing traditional fresh produce market intermediaries for standardized lines.
- Wholesalers:Johannesburg and Cape Town fresh produce markets remain dominant for root vegetables and basic salad categories, though margin compression from retail consolidation forces volume aggregation.
- Online Markets:Direct-to-consumer platforms are gaining traction in Gauteng metropolitan areas for hydrocooled leafy greens with same-day delivery promises.
- Farmers' Markets:Urban consumers in Cape Town and Pretoria seek traceability assurances for heirloom cultivars and organic-certified produce outside formal retail channels.
Retail stores command the dominant volume position; online markets are expanding most quickly as logistics platforms mature.
Packaging Type:
Packaging format selection reflects tension between retail-ready presentation and export durability requirements.
- Plastic Bags:Polyethylene formats for leafy greens face substitution pressure from cardboard alternatives as Woolworths Holdings advances sustainability procurement criteria.
- Cardboard Boxes:Retail-ready clamshells and corrugated containers are displacing mesh bags for root vegetables, forcing capital retooling at washing and grading facilities to meet SPAR Group specifications.
- Mesh Bags:Woven polypropylene remains standard for bulk root vegetable wholesale through Johannesburg fresh produce market channels.
- Clamshell Containers:PET and molded fiber formats protect berry integrity through air-freight handling to Middle Eastern retail clients.
Cardboard boxes are capturing the fastest share growth; plastic bags retain the largest installed base despite sustainability headwinds.
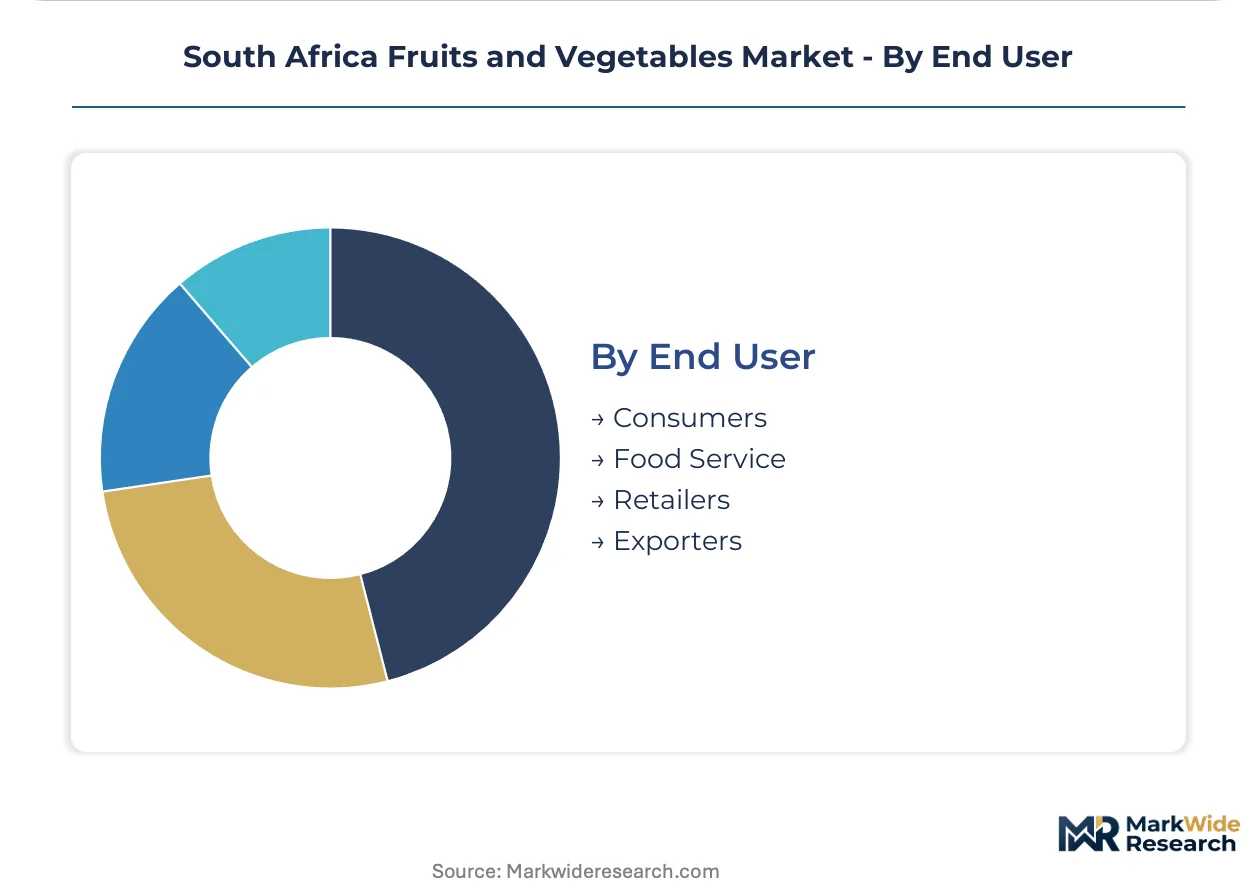
End User:
End-user segmentation separates price-sensitive domestic consumption from premium export and food service channels.
- Consumers:Household purchasers through retail and informal markets drive volume for standardized citrus and root vegetable categories with limited quality differentiation.
- Food Service:Gauteng restaurant and hotel procurement networks absorb expanding volumes of hydrocooled leafy greens, pulling supply away from traditional wet-market distribution toward direct farmgate contracting.
- Retailers:SPAR Group and Woolworths Holdings procurement teams consolidate supplier counts for standardized produce while expanding direct contracting for differentiated berry and heirloom categories.
- Exporters:Capespan Group anchors Southern Hemisphere logistics through Cape Town port infrastructure and ripening facilities, with Perishable Products Export Control Board inspections governing EU and UK market access.
Retailers handle the dominant procurement volume; food service is gaining share fastest as Gauteng hospitality sector expansion continues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's fruit and vegetable trade balance tilts toward export surplus in citrus and stone fruit, while import dependency persists for temperate-zone commodities. Gauteng and Western Cape provinces absorb the dominant share of domestic food service and retail procurement, with Limpopo Valley operations anchoring outbound shipment volumes through Durban and Cape Town harbors.
Western Cape
Berry cultivation clusters around Grabouw and Ceres, where blueberries and raspberries feed air-freight channels to Dubai and Doha. The Department of Agriculture, Land Reform and Rural Development enforces Plant Improvement Act certification for new cultivar releases from Stellenbosch-based breeding operations. Cape Town port infrastructure and Capespan Group ripening facilities anchor Southern Hemisphere export logistics for stone fruit and pome categories.
Gauteng
Restaurant and hotel procurement networks in Johannesburg and Pretoria absorb expanding volumes of hydrocooled leafy greens, pulling supply away from traditional wet-market distribution. National agricultural regulator coordination with DAFF phytosanitary protocols manages false codling moth interception risks. Tshwane fresh produce market intermediaries face displacement as SPAR Group centralized distribution centers consolidate root vegetable procurement.
Limpopo
Precision irrigation deployment in the Limpopo Valley lifts water-use efficiency for citrus and avocado orchards facing Department of Water and Sanctions licensing constraints. Perishable Products Export Control Board inspections govern EU market access for Valencia orange shipments through Durban harbor. Polokwane packhouses invest in solar-battery hybrid arrays to mitigate Eskom load-shedding impacts on cold-chain continuity.
KwaZulu-Natal
Subtropical fruit cultivation concentrates along the north coast, where avocado and macadamia operations serve Middle Eastern retail clients. DAFF phytosanitary compliance shapes detention-risk profiles at Rotterdam and Hamburg entry points. Durban harbor handles the majority of citrus volume throughput, with mesh bag packaging formats facing substitution pressure from cardboard-based retail-ready alternatives.
South Africa Fruits and Vegetables Market Competitive Landscape
On the supply side, the industry is consolidating around integrated farming networks and export-logistics specialists that control supply pipelines from germplasm to port. Three archetypes dominate: vertically integrated producers with captive breeding programs, port-anchored logistics operators with ripening infrastructure, and retail-procurement consolidators with centralized distribution mandates. Competitive moves center on cold-chain capital deployment and direct farmgate contracting to bypass traditional market intermediaries.
Among South Africa-based integrated producers, ZZ2 and Westfalia Fruit occupy positions that exemplify the vertically integrated archetype, controlling cultivation networks across multiple climatic zones. Capespan Group anchors the export-logistics tier through Cape Town infrastructure. These three represent the structural concentration where breeding program scale, harbor-adjacent ripening capacity, and retail procurement consolidation intersect.
| Leading Market Players |
|---|
| ZZ2 |
| Capespan Group |
| Westfalia Fruit |
| Dutoit Group |
| Freshworld International |
| The Karsten Group |
| Bertie van Zyl |
| Woolworths Holdings |
| SPAR Group |
| Others |
Value Network & Pricing Analysis
Durban-to-Rotterdam citrus freight corridors anchor cost dynamics that concentrate supply power among Capespan Group and ZZ2 while forcing three-tier price stratification across export-grade, domestic retail, and food service channels. Eskom tariff volatility and diesel backup costs at Limpopo packhouses feed directly into per-kilogram pricing premiums for cold-chain-guaranteed shipments.
Pricing Analysis
Conventional flood-irrigation citrus operations, precision-irrigated avocado orchards, and sensor-networked berry farms occupy distinct price bands based on water-use efficiency and phytosanitary certification tiers. Price differentiation hinges on EU F-Gas Regulation compliance status and hydrocooling technology deployment, with detention-risk exposure at Rotterdam compressing margins for non-certified Limpopo shipments relative to Western Cape alternatives. Cost compression in domestic wholesale channels is intensifying because SPAR Group and Woolworths Holdings procurement consolidation squeezes intermediary margins. Smallholder cooperatives exhibit highest price sensitivity due to capital constraints for solar retrofit investments, while air-freight berry exporters to Dubai and Doha command lowest sensitivity through premium retail positioning.
Supply Chain Analysis
Phytosanitary detention risk at EU border inspection posts dominates supply vulnerability for South African citrus exporters dependent on Rotterdam and Hamburg entry clearance. Geographic supply concentration centers on Limpopo Valley citrus groves, Western Cape berry clusters around Grabouw and Ceres, and Mpumalanga avocado operations. Raw material dependencies include drip irrigation hardware, hydrocooling equipment, and cold-chain refrigerants aligned with F-Gas standards. Distribution runs through Capespan Group's Cape Town ripening facilities and SPAR Group's centralized Gauteng distribution centers, with air-freight bookings through Emirates and Qatar Airways cargo divisions bypassing slower sea channels for perishable categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's fruits and vegetables market sits in early-cycle expansion as precision irrigation deployment and air-freight berry channels penetrate previously water-stressed or logistically constrained segments. Food service procurement growth in Gauteng hospitality networks accelerates adoption velocity for hydrocooled leafy greens.
For Market Incumbents: Build captive germplasm moats through Plant Improvement Act certification programs that amortize compliance costs across expanded variety portfolios. Consolidate breeding operations to defend against emerging specialized berry propagators while securing water-use licenses ahead of Department of Water and Sanitation processing delays. Channel control through direct farmgate contracting with Woolworths Holdings displaces traditional fresh produce market intermediaries and locks in margin capture. For New Entrants and Emerging Players: Build out hydrocooling technology integration for leafy greens bound for Gauteng restaurant and hotel procurement networks, the most penetrable segment given wet-market displacement trends. Target online direct-to-consumer platforms in metropolitan Pretoria and Johannesburg with same-day delivery capabilities for organic-certified heirloom cultivars outside formal retail channels. Position through sustainability-forward cardboard clamshell packaging formats that meet SPAR Group specifications ahead of mesh bag phase-out. For Investors and Strategic Acquirers: Solar-battery hybrid array installers serving Limpopo and Mpumalanga packhouses represent the priority acquisition archetype, capturing load-shedding mitigation spend that Eskom tariff escalations accelerate. Long-term viability across the analysis window hinges on water-use licensing reform timelines and cold-chain technician training pipeline development. The signal to monitor is Department of Agriculture, Land Reform and Rural Development enforcement intensity for Plant Improvement Act violations that could consolidate breeding program economics toward scaled incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Irrigation Deployment | Drip and subsurface systems in Limpopo Valley expand viable hectare counts for water-stressed citrus orchards. |
| Cold-Chain Digitization | Sensor-networked temperature tracking from packhouse to Cape Town port compresses insurance and rejection-cost exposures. |
| Air-Freight Channel Expansion | Emirates and Qatar Airways cargo bookings for Western Cape berries bypass slower sea-freight to Middle Eastern retail clients. |
| Direct Farmgate Contracting | SPAR Group and Woolworths Holdings procurement teams displace traditional fresh produce market intermediaries for standardized lines. |
| Solar-Battery Hybrid Installation | Packhouse load-shedding mitigation investments reconfigure operating cost structures against Eskom tariff volatility. |
Research Methodology
Operator-level perspectives from citrus orchard managers, packhouse operations directors, cold-chain logistics coordinators, and retail procurement leads anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from Perishable Products Export Control Board inspection records, Department of Water and Sanitation licensing databases, and EU F-Gas Regulation compliance filings. Customs throughput data from Durban and Cape Town harbors, alongside SPAR Group and Woolworths Holdings distribution center capacity disclosures, supplied quantitative foundations. Bottom-up hectare expansion estimates and top-down export value trajectories underwent iterative triangulation.
Scenario-bracketing around water-use licensing reform timelines and load-shedding frequency assumptions structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, packaging format, and end-user category, with provincial regulatory cluster and cold-chain technology tier as industry-specific cross-cuts. CAGRs derived from compound trajectory analysis of precision irrigation adoption curves and air-freight booking growth rates. Forecast inputs incorporated Department of Agriculture, Land Reform and Rural Development enforcement patterns and Eskom tariff escalation scenarios.
The forecast holds incumbent behavior within observed patterns; aggressive germplasm consolidation moves by ZZ2 and Westfalia Fruit would shift outcomes toward breeding program concentration. Continuous validation against operating reality is the recommended discipline, with particular attention to false codling moth interception rates at Rotterdam and hydrocooling technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Mexico Lime Market
Fruits and Vegetables
Plums and Sloes Market
Fruits and Vegetables
Aegle Marmelos Market
Fruits and Vegetables
Fresh Figs Market
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
Edible Flowers Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
Jicama Market
Fruits and Vegetables
US Vegetable Puree Market
Fruits and Vegetables
Frozen Vegetables Market
Fruits and Vegetables
Vaccinium Myrtillus Market
Fruits and Vegetables
Fruit and Vegetable Cleaners Market
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Frozen Fruits Market
Fruits and Vegetables
Asia Pacific Orange Market
Fruits and Vegetables
Camellia Oil Market