
 Admission Management Software Market | 2026-2036
Admission Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Admission Management Software Market Intelligence
Cloud-native architecture is reshaping how admission platforms are built and delivered across higher education technology stacks. Slate by Technolutions leverages deep CRM specialization to dominate elite university segments in North America. Ellucian anchors its position through ERP integration breadth across mid-tier institutions. Salesforce Education Cloud extends its enterprise cloud infrastructure to compete for multi-campus system contracts.
Admission management software orchestrates the complete student enrollment lifecycle, encompassing application intake, document verification, decision workflow automation, and enrollment yield analytics through configurable rule engines and real-time dashboards. Cloud-based deployment leads segment expansion as institutions abandon on-premise maintenance burdens, while API integration capabilities command premium positioning due to interoperability demands with SIS and financial aid systems. Application tracking features represent the most mature functional category, whereas admission analytics emerges as the fastest-growing capability area as enrollment offices prioritize predictive modeling.
FCC guidelines on educational communications and data privacy influence how vendors architect consent management and messaging audit trails for US deployments. GDPR compliance requirements across European higher education institutions shape data residency specifications and cross-border transfer protocols for cloud-hosted platforms. Stakeholders must monitor evolving state-level student data privacy legislation and interoperability standards to anticipate procurement specification shifts.
Market Dynamics
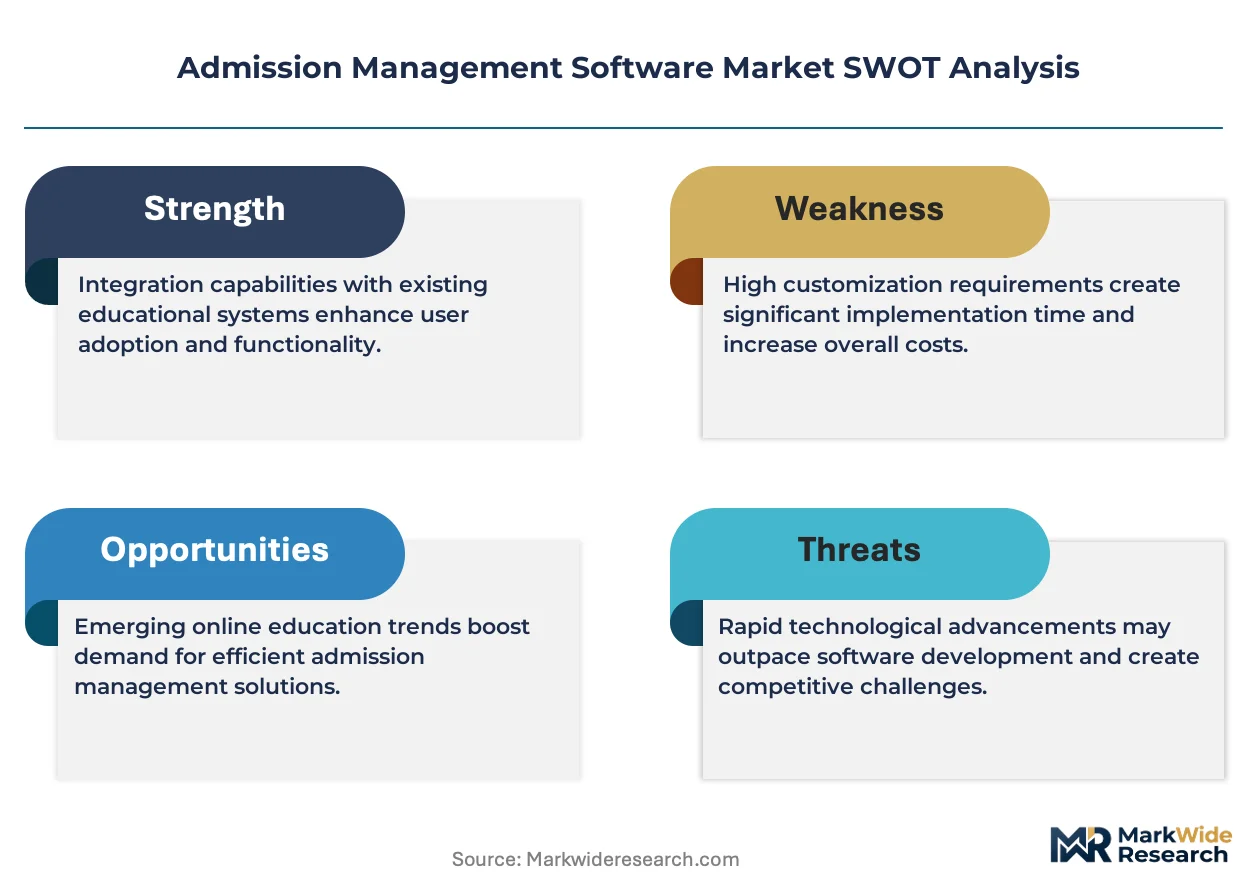
Cloud migration is forcing a fundamental rearchitecture of how universities procure and deploy enrollment technology, compressing vendor evaluation cycles and elevating API interoperability above feature breadth in procurement scoring.
Growth Catalysts
- FCC guidelines on educational communications:US institutions must maintain auditable consent trails for student outreach, creating mandatory upgrade cycles for legacy messaging infrastructure.
- GDPR data residency mandates:European universities face binding requirements on cross-border data flows, accelerating replacement of on-premise systems with EU-sovereign cloud deployments.
- Predictive modeling capabilities:Enrollment offices now require machine learning pipelines for yield forecasting, pulling investment toward platforms with native analytics engines.
Market Restraints
- Legacy ERP integration costs:Custom middleware development for Student Information System connectivity consumes 40-60% of implementation budgets.
- Specialized talent scarcity:Higher education IT departments lack staff versed in both enrollment operations and cloud architecture.
- State-level privacy fragmentation:Divergent student data protection laws across US states multiply compliance engineering overhead.
Strategic Opportunities
- Community college digitization:Two-year institutions in the United States remain underpenetrated by modern enrollment platforms.
- AI-assisted document verification:Machine learning plus robotic process automation convergence promises 70% reduction in manual transcript review hours.
- Subscription pricing models:Annual recurring revenue structures replace perpetual licenses, lowering barrier-to-entry for mid-tier institutions.
Industry Challenges
- Interoperability certification delays:IMS Global Learning Consortium standards compliance requires 8-14 month validation timelines.
- Change management resistance:Admissions staff accustomed to decades-old workflows resist dashboard-centric decision environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Admission Management Software Market |
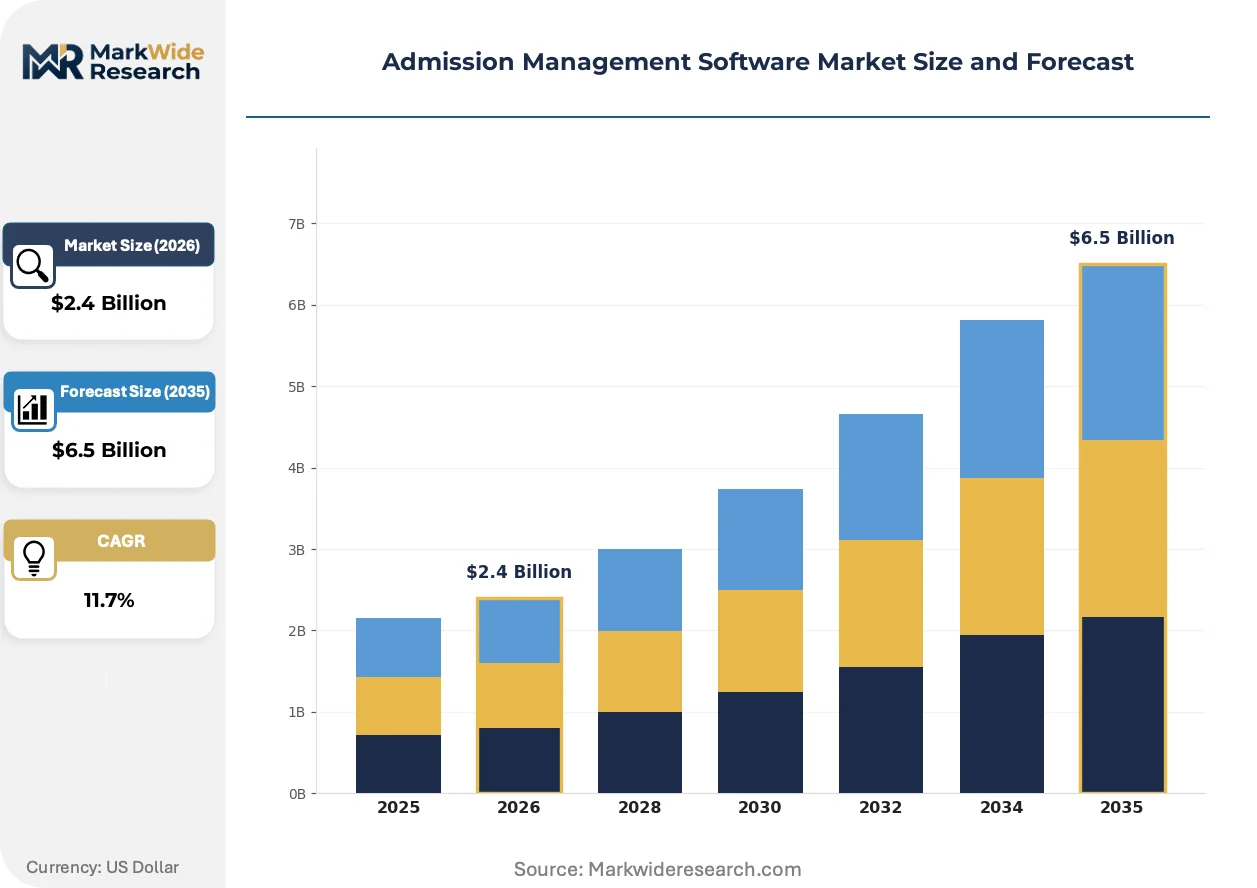
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Universities, Colleges, Vocational Schools, Online Institutions Feature: Application Tracking, Document Management, Admission Analytics, Communication Tools Integration Level: API Integration, Single Sign-On, Data Import, Third-Party Tools |
| Companies Covered | Element451, Slate by Technolutions, Salesforce Education Cloud, Embark, Community Brands, Ellucian, EdVisorly, Wisenet, Blackbaud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Admission Management Software Market Strategic Shifts & Innovations
Artificial intelligence is embedding into every layer of enrollment operations, from document ingestion through yield optimization, compressing decision cycles and redefining staff roles.
Optical character recognition is migrating from standalone transcript parsing tools to integrated, multi-document intake pipelines. Large public university systems now demand automated extraction from international credentials and financial aid forms. This migration from point solutions to unified ingestion architectures is compressing vendor consolidation timelines.
GDPR Article 17 right-to-erasure enforcement is forcing architectural redesign of student record retention policies. Cloud-hosted platforms must now implement automated purging workflows with cryptographic proof of deletion. European institutions are responding by prioritizing EU-based data centers in procurement specifications.
Outcome-based vendor selection is displacing feature-checklist evaluation among US research universities. Procurement offices now weight post-implementation enrollment yield improvement above initial license cost. This behavioral shift is most visible in California and Texas public university systems, where multi-campus contracts tie vendor payments to documented conversion rate gains.
Admission Management Software Market Segmentation
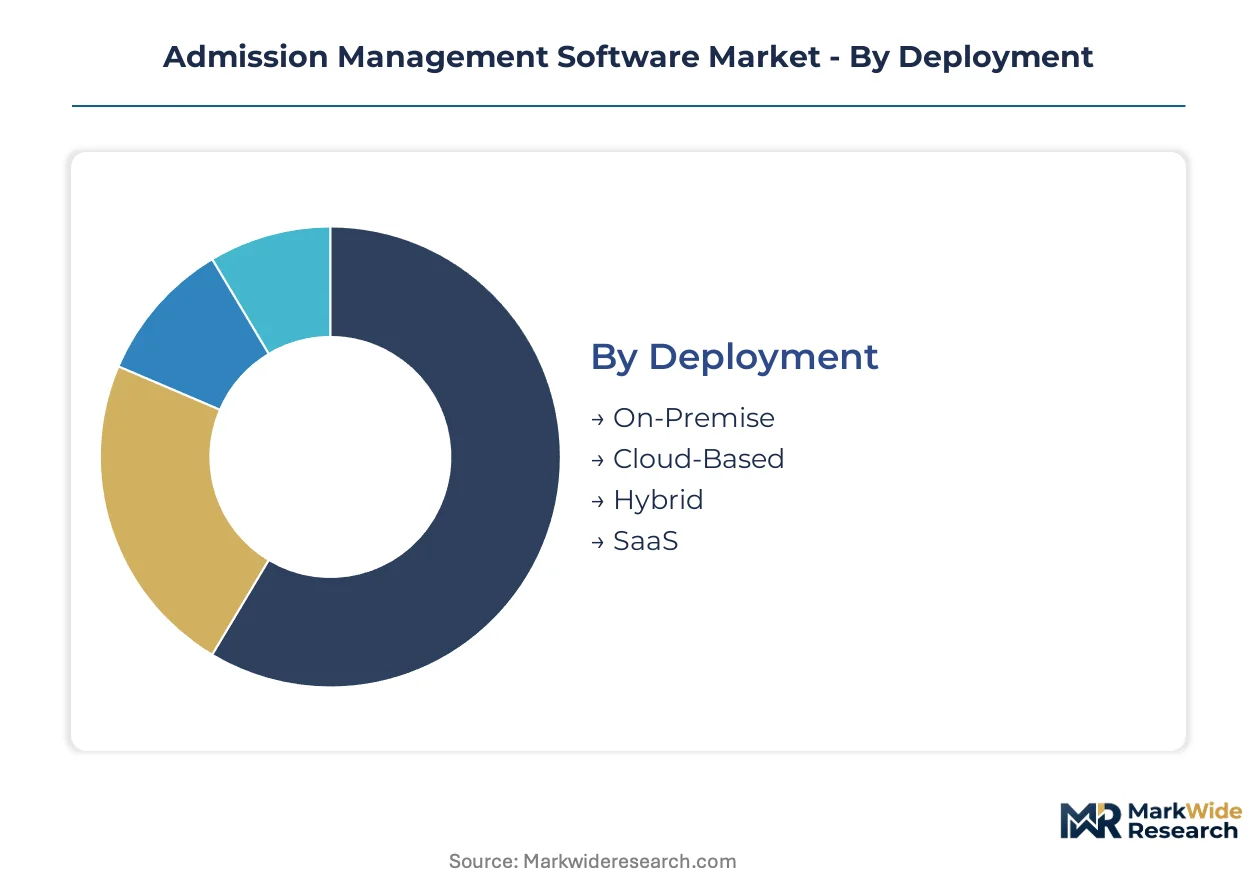
Admission management software procurement patterns diverge sharply across deployment models, institutional types, and integration requirements. Understanding these fault lines reveals where vendor R&D investments concentrate and which customer segments command pricing power.
Deployment:
Cloud-based platforms refresh functionality on quarterly cycles, while on-premise installations stagnate across multi-year maintenance windows. SaaS offerings compress implementation timelines from months to weeks.
- On-Premise:Legacy infrastructure requiring dedicated server hardware and internal IT maintenance. Large public university systems in the United States retain these installations due to bond-financed data center investments and FERPA compliance audit trails, though upgrade cycles stretch to 7-10 years.
- Cloud-Based:Fully managed environments with automatic security patching and elastic compute scaling. European institutions under GDPR Article 44 cross-border transfer restrictions are migrating here fastest, prioritizing EU-sovereign data centers over US-hosted alternatives.
- Hybrid:Split architectures keeping sensitive student PII on local servers while pushing application processing to cloud nodes. Community college districts adopt this model to balance compliance control with cost containment.
- SaaS:Subscription-delivered platforms with zero infrastructure footprint. Mid-tier private colleges gravitate here for predictable annual budgeting and rapid feature access without capital expenditure approval cycles.
Cloud-based systems anchor the volume base while SaaS offerings gain share at the steepest rate.
End User:
Procurement sophistication scales with enrollment complexity—research universities demand predictive analytics while vocational schools prioritize document workflow automation.
- Universities:Multi-college systems managing 50,000+ annual applications. These institutions require machine learning pipelines for yield forecasting and automated international credential evaluation, driving the highest per-seat pricing tiers.
- Colleges:Four-year undergraduate-focused institutions with 5,000-20,000 applications yearly. Liberal arts colleges in the Northeastern United States emphasize CRM integration for personalized recruitment campaigns.
- Vocational Schools:Career-training programs with accelerated intake cycles. These operators prioritize rapid document verification and employer partnership tracking over traditional admissions funnels.
- Online Institutions:Asynchronous learning providers with rolling enrollment. Platform demands center on 24/7 application processing and automated financial aid packaging to support continuous start dates.
Universities dominate current revenue concentration while online institutions expand most quickly.
Feature:
Functional maturity varies—application tracking has commoditized while predictive analytics commands 40-60% implementation budget allocation.
- Application Tracking:Status dashboards and workflow routing for individual applicant files. This capability has achieved near-universal adoption across US higher education, with differentiation shifting to mobile responsiveness and parent portal access.
- Document Management:Transcript ingestion, verification, and storage with audit trails. Optical character recognition accuracy rates now determine vendor selection, particularly for institutions processing high volumes of international credentials.
- Admission Analytics:Predictive modeling for enrollment yield and demographic forecasting. Texas and California public university systems now tie vendor contract renewals to documented conversion rate improvements from these tools.
- Communication Tools:Multi-channel outreach with consent management and engagement scoring. FCC guidelines on educational communications mandate auditable opt-in trails, forcing upgrades from basic email blast functionality.
Application tracking saturates the installed base while admission analytics climbs the fastest.
Integration Level:
Connectivity requirements scale with institutional IT complexity—single sign-on is table stakes while API depth separates premium from standard tiers.
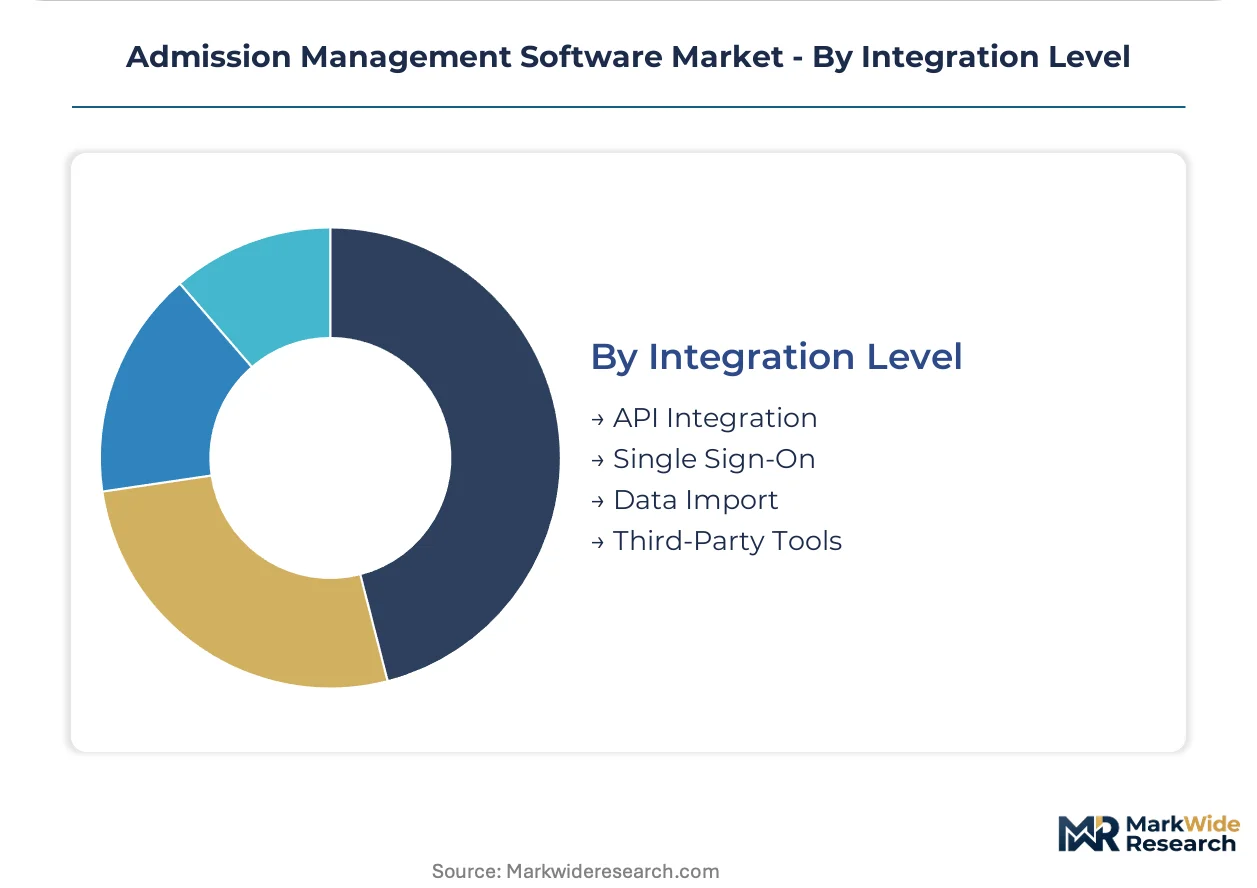
- API Integration:Programmatic data exchange with Student Information Systems and financial aid platforms. Custom middleware development for legacy SIS connectivity consumes the majority of implementation budgets at large public institutions.
- Single Sign-On:Unified authentication across campus identity providers. Shibboleth and SAML protocol support is now non-negotiable for any vendor seeking R1 research university contracts.
- Data Import:Batch file ingestion from legacy databases and external testing services. Community colleges rely heavily on standardized test score imports and prior learning assessment uploads.
- Third-Party Tools:Pre-built connectors for CRM, marketing automation, and video interviewing platforms. Slate by Technolutions dominates here through its extensive partner ecosystem in North American elite admissions.
API integration anchors enterprise procurement decisions while third-party tool connectivity expands most rapidly among mid-tier institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based vendors export admission management platforms to English-speaking university systems across Canada, Australia, and the United Kingdom, establishing a dominant trade corridor in higher education technology.
United States
Large public university systems in California and Texas drive procurement volume for cloud-native enrollment platforms. FCC guidelines mandate auditable consent trails for student outreach, forcing compliance upgrades across legacy messaging infrastructure. Boston and Austin anchor development clusters where vendors refine machine learning pipelines for yield forecasting.
United Kingdom
Russell Group universities prioritize API interoperability with existing campus identity systems. GDPR Article 44 cross-border transfer restrictions shape data residency specifications in procurement contracts. London and Edinburgh concentrate vendor implementation teams serving multi-campus contracts across England and Scotland.
Germany
Technical universities in Bavaria and Baden-Württemberg demand automated international credential evaluation for non-EU applicants. The Federal Data Protection Act (BDSG) reinforces GDPR compliance requirements for student record processing. Berlin hosts emerging SaaS providers targeting Central European institutions with localized deployment options.
Canada
Provincial university systems in Ontario and British Columbia modernize enrollment infrastructure to support international student recruitment targets. Health Canada privacy guidelines intersect with provincial data protection statutes, creating layered compliance obligations. Toronto and Vancouver serve as North American deployment hubs for vendors managing cross-border data flows.
Australia
Group of Eight universities invest in predictive analytics to optimize international enrollment yields from Southeast Asian markets. The Privacy Act and Australian Privacy Principles govern cross-border disclosure of student personal information. Sydney and Melbourne concentrate vendor professional services capacity for Asia-Pacific support.
Admission Management Software Market Key Industry Players
On the supply side, the industry is consolidating around three distinct strategic tiers. Specialized CRM vendors, ERP-integrated platform providers, and enterprise cloud infrastructure companies each occupy differentiated positions in procurement scoring. Competitive dynamics center on API depth, SIS connectivity, and outcome-based contract structures. M&A activity targets document verification automation capabilities, while partnerships with learning management system vendors expand integration breadth.
Within the specialized CRM tier, Slate by Technolutions and Embark exemplify deep functional specialization for elite admissions workflows. Salesforce Education Cloud anchors the enterprise cloud vector, leveraging infrastructure scale for multi-campus system contracts. Ellucian occupies a position bridging ERP integration depth with modular enrollment functionality, serving mid-tier institutions with legacy system migration requirements.
| Leading Market Players |
|---|
| Element451 |
| Slate by Technolutions |
| Salesforce Education Cloud |
| Embark |
| Community Brands |
| Ellucian |
| EdVisorly |
| Wisenet |
| Blackbaud |
| Others |
Cost & Logistics Intelligence
Single-source dependency on hyperscaler cloud infrastructure determines both pricing tier spreads and supply chain shape in admission management software procurement. AWS and Azure concentration forces vendors into cost-pass-through structures that compress margins at the standard tier while enabling premium positioning for EU-sovereign alternatives.
Pricing Analysis
Legacy on-premise installations command 3-4x annual maintenance versus cloud-native subscription tiers, while next-generation AI-embedded platforms extract 40-60% implementation budget premiums for predictive analytics modules. Three-tier pricing structure across premium, standard, and economy levels stratifies by API depth and SIS connectivity complexity. Cost compression in the standard tier intensifies because mid-tier institutions commoditized application tracking functionality. Community college districts exhibit highest price sensitivity due to bond-financing constraints, whereas large public university systems prioritize outcome-based contracts over license cost.
Supply Chain Analysis
AWS, Microsoft Azure, and Google Cloud Platform hold dominant capacity for higher education cloud deployments across the United States, Ireland, and Germany. Software development draws from specialized machine learning engineering pools, OCR document processing libraries, and identity management protocol stacks. Single-source vulnerability concentrates in hyperscaler regions where GDPR Article 44 cross-border transfer restrictions create regulatory chokepoints. Distribution runs through direct enterprise sales teams for large systems and value-added resellers for mid-tier private colleges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The admission management software market rewards vendors who bridge enrollment operations expertise with cloud architecture fluency, a combination scarce in both higher education IT departments and pure-play software firms. Procurement offices now weight post-implementation yield improvement above feature breadth, shifting competitive advantage toward outcome-accountable providers.
For Market Incumbents: Pre-empt API standardization consolidation by embedding native predictive analytics engines before outcome-based contracts become universal procurement requirements. Defend position through backward integration into document verification automation, neutralizing the 70% manual review cost advantage that threatens legacy transcript processing revenue. Prioritize EU-sovereign data center certification to capture GDPR-mandated replacement cycles before regional challengers establish local hosting presence. For New Entrants and Emerging Players: United States community college districts offer the most penetrable segment, with two-year institutions remaining underpenetrated by modern enrollment platforms and exhibiting acute price sensitivity to subscription pricing models. Target vocational schools and online institutions with accelerated intake cycles that prioritize rapid document verification over traditional admissions funnel complexity. Establish go-to-market traction through pre-built connectors to widely deployed Student Information Systems, compressing implementation timelines that stall incumbent sales cycles. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized CRM vendors with deep enrollment workflow expertise over horizontal platform providers. Long-term viability rests on machine learning pipeline differentiation and SIS connectivity breadth rather than feature commoditization. Acquisition target archetype: document verification automation specialists with proven OCR accuracy rates for international credentials. Watch for inflection when California and Texas public university systems publish standardized API interoperability requirements in multi-campus RFPs.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native SIS connectivity reduces implementation budgets consumed by custom middleware development. |
| Acquisition of Specialist Firm | Document verification automation compresses vendor consolidation timelines for international credential processing. |
| Geographic Expansion | EU-sovereign data centers capture GDPR Article 17 right-to-erasure compliance procurement specifications. |
| Strategic Partnership | Learning management system vendor alliances expand integration breadth beyond core enrollment workflows. |
| Product Launch | AI-assisted yield forecasting modules command premium positioning in outcome-based contract structures. |
Research Approach
Operator-level perspectives from enrollment management directors, university CIOs, financial aid systems integrators, and admissions operations managers anchored the qualitative base. Primary interviews combined with secondary validation against EDUCAUSE technology surveys, IMS Global Learning Consortium standards documentation, and vendor SEC filings. Bottom-up triangulation across deployment model adoption rates and top-down cross-checks against higher education IT expenditure patterns ensured segment integrity.
Scenario-bracketing framed analytical approach across the analysis window, modeling cloud migration velocity against legacy system retention scenarios. Segmentation dimensions included deployment architecture, institutional type, functional capability maturity, and integration complexity tier. CAGRs derived from enrollment volume elasticity to platform pricing and documented procurement cycle frequencies. Forecast inputs incorporated FCC consent management audit requirements and GDPR cross-border transfer restriction enforcement timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed platform entrants or EU-regional challengers would shift outcomes. Assumptions reflect steady state-level privacy fragmentation and stable IMS Global certification timelines. Quarterly review of multi-campus system RFP language and documented yield improvement claims is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Retail Management Systems Software Market
Software & Services
Global Trade Promotion Management Software Market
Software & Services
Commercial Drone Software Market
Software & Services
Packaged Software Market
Software & Services
Freight Management Software Market
Software & Services
Fire Software Market
Software & Services
Multi-Cloud SDN Market
Software & Services
India Sports Management Software Market
Software & Services
Geophysical Software Service Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Global Online Community Management Software Market
Software & Services
Job Description Management Software Market
Software & Services
Global Desktop As a Service Market
Software & Services
Jobsite Management Software Market
Software & Services
Advanced Process Control Software Market
Software & Services
Objectives & Key Results (OKR) Software Market