
 Professional Dubbing Services Market | 2026-2036
Professional Dubbing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Professional Dubbing Services Market Insights
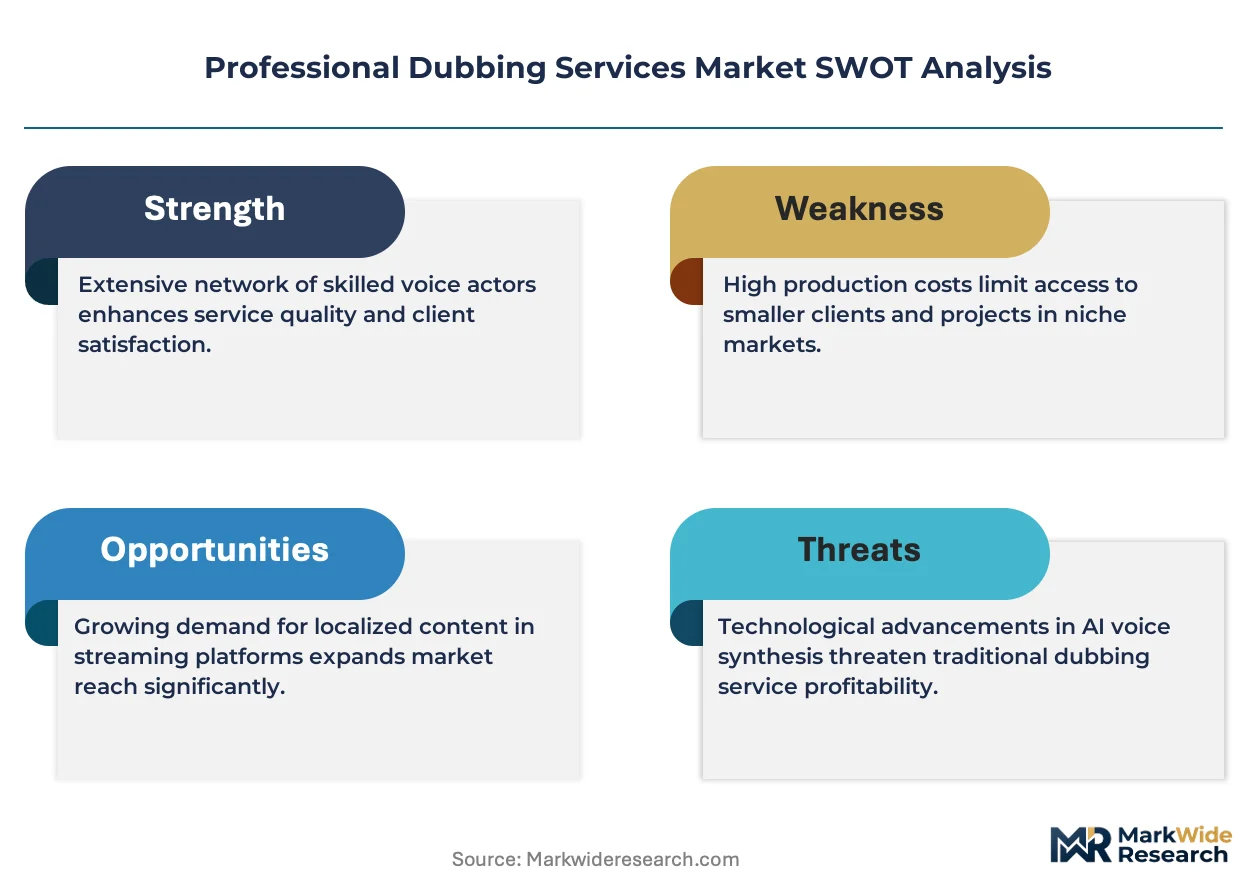
The gap between premium theatrical dubbing and commodity-grade streaming localization is expanding in measurable ways. VSI Group leverages its network of owned studios across London, Paris, and Berlin to sustain premium pricing for feature-film clients. Iyuno Media Group anchors its position through massive capacity in Asian hubs, competing on volume for streaming catalog deals.
Professional dubbing services encompass the complete replacement of original dialogue tracks with synchronized vocal performances in target languages, typically requiring frame-accurate lip-sync matching within 2-3 frames and acoustic treatment in ISO-standard recording booths. These services enable content owners to monetize intellectual property across linguistic territories without subtitling-dependent viewer retention losses. Localization and subtitling segments show divergent margin structures, with localization commanding premium rates for cultural adaptation while subtitling scales efficiently through automation. Surround sound and Dolby Digital formats concentrate value in theatrical and premium streaming releases, whereas mono delivery persists in cost-sensitive broadcast markets.
FCC captioning mandates in the United States, CSA audio-description requirements in France, and CDSCO-adjacent content localization norms for pharmaceutical video training in India collectively shape compliance-driven dubbing procurement. GDPR and the EU AI Act increasingly govern voice data retention and synthetic voice disclosure in European dubbing workflows. Stakeholders must monitor regulatory divergence between human-performance standards and emerging AI-voice disclosure frameworks as procurement criteria evolve.
Market Dynamics
AI voice synthesis is compressing turnaround times from weeks to days while fragmenting pricing power across theatrical, streaming, and broadcast tiers. This technological inflection is redistributing margins between legacy studios and automated localization platforms.
Growth Catalysts
- FCC captioning mandates:Compliance requirements for accessible content in the United States sustain procurement volumes for broadcast and streaming catalog localization.
- Streaming platform expansion:Netflix, Disney+, and regional services commission multilingual dubbing for day-and-date global releases, creating continuous demand spikes.
- ISO-standard recording infrastructure:Certified acoustic treatment and frame-accurate lip-sync capabilities differentiate premium theatrical dubbing from commodity streaming work.
Market Restraints
- Human voice actor cost structures:Union-scale theatrical talent commands premium rates that automated synthesis cannot yet replicate for emotional nuance.
- Supply concentration in Indian hubs:Mumbai and Chennai studio clusters create geographic risk for global streaming clients dependent on single-region capacity.
- GDPR voice data retention limits:European recording sessions face stricter archival and synthetic disclosure requirements than Asian or North American workflows.
Strategic Opportunities
- Pharmaceutical video training localization:CDSCO-adjacent compliance norms in India create specialized demand for medical dubbing with regulatory documentation.
- EU AI Act synthetic voice disclosure:Early compliance with emerging transparency frameworks positions vendors for public-sector procurement in France and Germany.
- Convergence of neural TTS and emotion modeling:ElevenLabs-style platforms paired with prosody control tools open theatrical-adjacent quality tiers.
Industry Challenges
- Frame-accurate lip-sync talent scarcity:Skilled dubbing directors capable of 2-3 frame synchronization are concentrated in legacy European and Indian studios.
- Dolby Atmos certification timelines:Immersive audio mixing credentials require capital-intensive booth upgrades and extended engineer training periods.
- Cross-border IP licensing complexity:Voice performance rights and residual structures vary across SAG-AFTRA, Equity, and international union jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Professional Dubbing Services Market |
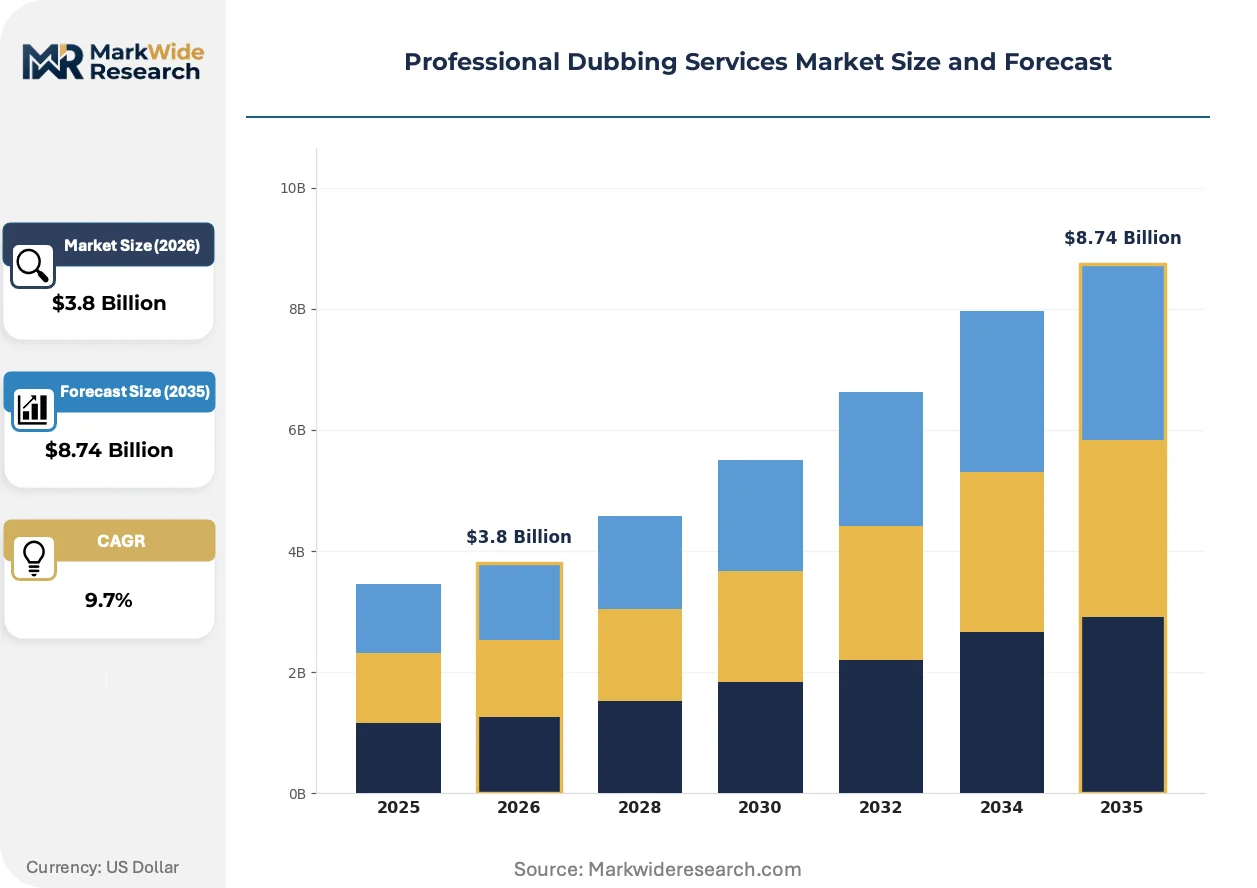
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice Over, Localization, Subtitling, Transcription End User: Film Producers, Television Networks, Streaming Platforms, Advertising Agencies Language Pair: English to Spanish, French to English, Mandarin to German, Japanese to Portuguese Audio Format: Stereo, Surround Sound, Mono, Dolby Digital |
| Companies Covered | VSI Group, FUNimation (Crunchyroll), Iyuno Media Group, Sound & Vision India, Prime Focus Studios, Sukudo Studios, ElevenLabs, BeMultilingual, Keywords Studios, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Professional Dubbing Services Market Trends and Innovations
Neural voice synthesis and immersive audio formats are bifurcating the market into premium theatrical preservation and automated streaming scale. Regulatory frameworks are catching up to synthetic performance disclosure.
Neural text-to-speech platforms with prosody control are expanding into mid-tier streaming catalog work previously reserved for human actors. Regional platforms in Southeast Asia and Latin America adopt these tools for volume localization of back-catalog content. The technology is expanding into voice-cloning workflows where original actors license their vocal signatures for synthetic performance.
The EU AI Act mandates synthetic voice disclosure in commercial media, creating compliance overhead for European dubbing vendors. France's CNIL and Germany's data protection authorities are interpreting voice biometric retention under GDPR precedents. Theatrical distributors in Italy and Spain face the strictest disclosure requirements for AI-augmented performances.
Buyers are unbundling theatrical, streaming, and broadcast localization into separate vendor relationships based on quality tier and speed requirements. Major studios now maintain parallel supplier rosters: premium owned-studio networks for feature films, high-volume Asian hubs for streaming catalogs, and automated platforms for news and reality content. This fragmentation is most advanced in the United States and United Kingdom, where procurement teams specialize by content category.
Professional Dubbing Services Market Segmentation
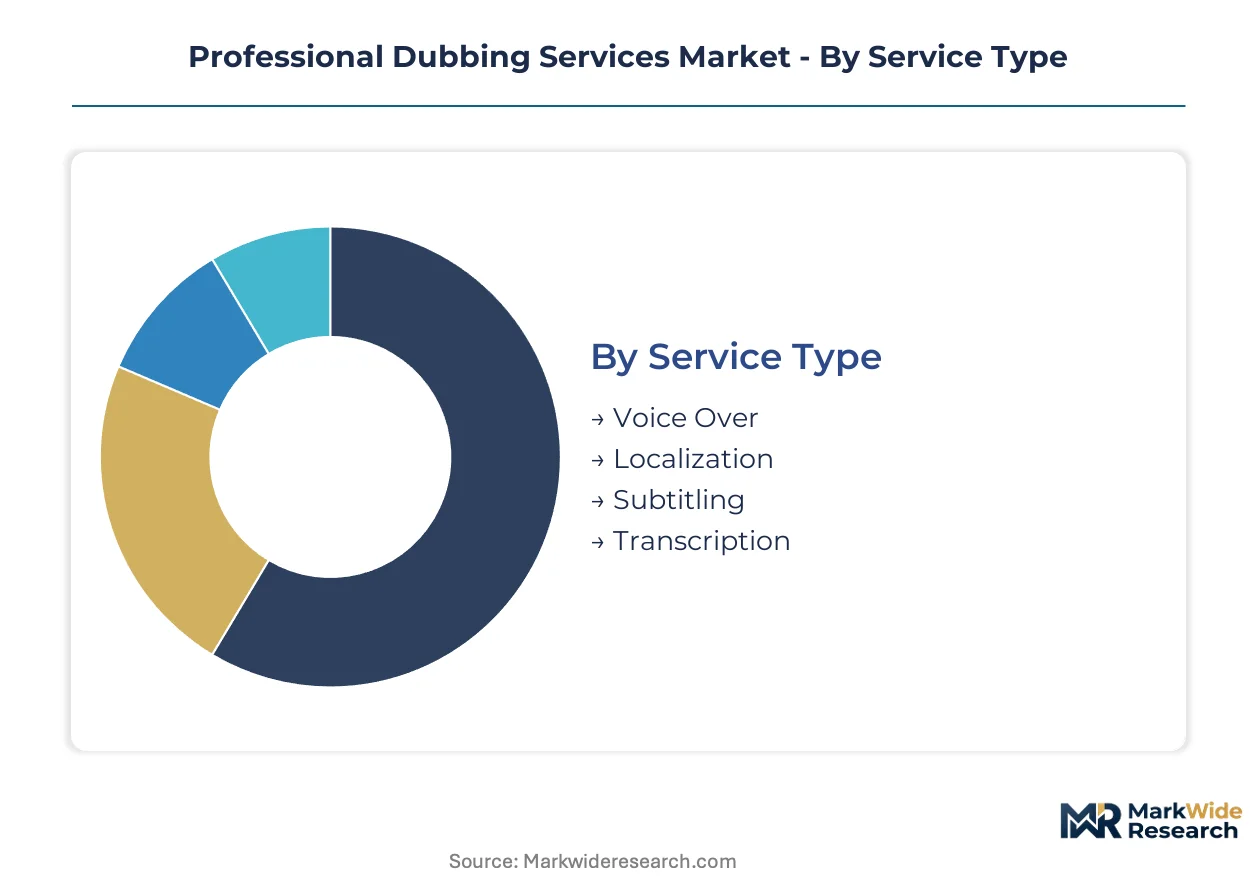
Segmentation in professional dubbing reveals how capital deployment, talent scarcity, and format certification create divergent margin profiles across service tiers. Each dimension exposes distinct procurement patterns and vendor specialization strategies.
Service Type:
Capital intensity varies sharply across this category, with acoustic infrastructure and talent certification driving fixed-cost differentiation between premium and commodity tiers.
- Voice Over:Requires ISO-standard recording booths with acoustic treatment and frame-accurate lip-sync direction. Demand concentrates in theatrical distribution chains where union-scale talent and 2-3 frame synchronization justify premium pricing.
- Localization:Encompasses cultural adaptation beyond literal translation, including idiom replacement and reference adjustment. Streaming platforms in India commission high volumes for day-and-date global releases, compressing turnaround timelines.
- Subtitling:Automation-enabled scaling through AI-assisted timing tools reduces per-minute costs dramatically.
- Transcription:Lowest capital barrier; cloud-based workflows dominate documentary and reality content pipelines.
Localization absorbs the bulk of installed capacity; voice over is expanding most quickly as streaming platforms commission theatrical-grade quality for premium series.
End User:
Procurement sophistication separates this category, with theatrical distributors demanding certified workflows that broadcast and digital advertisers bypass.
- Film Producers:Mandate Dolby Atmos mixing credentials and SAG-AFTRA or Equity union compliance for theatrical releases. European art-house distributors in France and Germany sustain premium pricing for native director supervision.
- Television Networks:Operate under FCC captioning mandates in the United States and CSA audio-description requirements in France, creating compliance-driven procurement cycles.
- Streaming Platforms:Netflix and Disney+ commission multilingual dubbing for simultaneous global drops, favoring high-volume Indian hubs.
- Advertising Agencies:Prioritize speed over certification, accepting automated platforms for regional campaign localization.
Streaming platforms absorb the bulk of installed capacity; film producers command the steepest expansion trajectory as theatrical windows recover post-pandemic.
Language Pair:
Geographic concentration of native talent pools creates supply asymmetries that reshape pricing power across directional flows.
- English to Spanish:Largest volume corridor serving Latin American theatrical and streaming markets. Madrid and Mexico City studio clusters compete on speed for platform catalog deals.
- French to English:Premium tier dominated by Paris-based owned-studio networks serving European art-house distributors requiring cultural nuance preservation.
- Mandarin to German:Specialized workflows for documentary and corporate training content with limited theatrical penetration.
- Japanese to Portuguese:Niche anime localization pipeline concentrated in São Paulo studios with JIS-standard quality emulation.
English to Spanish absorbs the bulk of installed capacity; French to English is gaining share fastest as European co-production volumes climb.
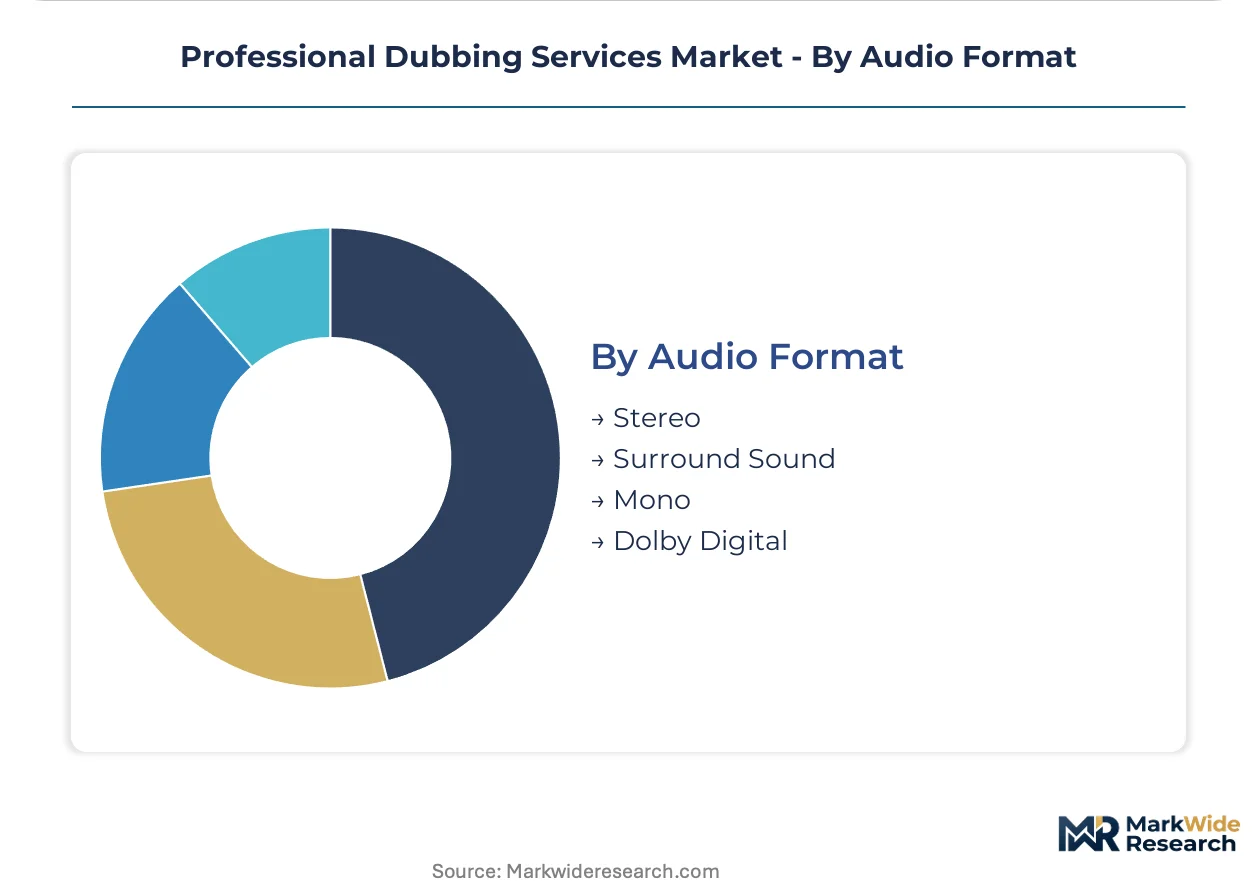
Audio Format:
Certification timelines and booth upgrade costs stratify vendor capabilities, with immersive formats creating moats around premium theatrical work.
- Stereo:Baseline delivery for streaming and broadcast with minimal certification overhead. Mumbai studios process high volumes for platform catalog content.
- Surround Sound:Required for premium streaming releases and theatrical adjacent windows. Demand concentrates in London and Berlin facilities with THX certification.
- Mono:Persists in cost-sensitive broadcast markets and legacy content remastering.
- Dolby Digital:Theatrical distribution mandate with strict quality assurance protocols and extended engineer training periods.
Stereo absorbs the bulk of installed capacity; surround sound is climbing the fastest as streaming platforms upgrade to immersive audio for competitive differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai and Chennai anchor professional dubbing capacity through dense studio clusters serving streaming platforms and theatrical distributors with frame-accurate lip-sync infrastructure.
United States
Netflix and Disney+ commission day-and-date multilingual releases for premium series and feature films. FCC captioning mandates sustain procurement volumes for broadcast and streaming catalog localization. Los Angeles maintains theatrical-grade facilities with SAG-AFTRA union compliance for feature-film dubbing.
India
Streaming platform expansion drives massive volume demand for English-to-Hindi and regional language localization. CDSCO-adjacent compliance norms create specialized procurement for pharmaceutical video training dubbing. Mumbai's Andheri studio corridor and Chennai's Kodambakkam cluster process high-volume catalog work for global clients.
United Kingdom
European co-production volumes climb for art-house theatrical distribution requiring cultural nuance preservation. GDPR voice data retention limits shape archival protocols and synthetic voice disclosure workflows. London's Soho district hosts owned-studio networks serving premium feature-film clients with THX-certified surround mixing.
Germany
EU AI Act synthetic voice disclosure requirements position early-compliance vendors for public-sector procurement. The country's national media regulator interprets transparency frameworks for AI-augmented performances. Berlin facilities compete with Paris and London for theatrical-grade immersive audio projects.
France
CSA audio-description requirements sustain compliance-driven dubbing procurement for broadcast and theatrical releases. CNIL guidance on voice biometric retention under GDPR precedents shapes European recording session protocols. Paris-based owned-studio networks command premium pricing for native director supervision of art-house distribution.
Professional Dubbing Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification grade and turnaround speed dimensions. The vendor base stratifies into theatrical-grade owned-studio networks, high-volume Asian hubs, and automated synthesis platforms. Three archetypes dominate: legacy facilities with union credentials, scale-driven Indian operations, and AI-native voice synthesis providers. Competitive moves concentrate on M&A for geographic coverage and Dolby Atmos certification investments for immersive audio differentiation.
Within the legacy theatrical tier, VSI Group and Iyuno Media Group exemplify divergent scale strategies. VSI Group represents premium-network positioning through owned facilities across European capitals. Iyuno Media Group anchors high-volume Asian capacity for streaming catalog deals. Among AI-native entrants, ElevenLabs occupies a position compressing turnaround timelines through neural voice synthesis with prosody control.
| Leading Market Players |
|---|
| VSI Group |
| FUNimation (Crunchyroll) |
| Iyuno Media Group |
| Sound & Vision India |
| Prime Focus Studios |
| Sukudo Studios |
| ElevenLabs |
| BeMultilingual |
| Keywords Studios |
| Others |
Pricing and Supply Chain Analysis
Streaming platform procurement teams at Netflix and Disney+ concentrate demand for high-volume localization, anchoring a project-based pricing model where turnaround speed commands premium multiples over standard catalog work. This buyer concentration compresses margins for commodity-tier vendors while preserving rate premiums for theatrical-grade facilities with union credentials.
Pricing Analysis
Value-based pricing anchored to frame-accurate lip-sync precision and Dolby Atmos certification separates theatrical distributors from streaming platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by acoustic infrastructure grade and talent union status. Cost compression in automated streaming tiers intensifies as neural TTS platforms displace human actors for back-catalog localization. Advertising agencies exhibit highest price sensitivity, accepting mono delivery and compressed timelines, while film producers absorb premium rates for SAG-AFTRA compliance and native director supervision.
Supply Chain Analysis
Freight costs for physical media masters and encrypted drive shipments to theatrical distributors remain marginal against total project value, though digital pipeline bandwidth shapes real-time collaboration economics. Supply concentrates in India, the United Kingdom, and Germany, with Mumbai's Andheri corridor and Chennai's Kodambakkam cluster processing high-volume streaming work. Raw material dependencies span ISO-standard acoustic foam, broadcast-grade mixing consoles, and voice actor union scale agreements. Single-source vulnerability concentrates in Indian hub capacity for global streaming clients. Distribution runs through owned-studio networks for premium theatrical, Asian hub partnerships for streaming volume, and API-integrated platforms for automated synthesis.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Professional dubbing services represent a consolidation play as AI voice synthesis fragments pricing power and forces sub-scale theatrical operators into distressed exits. Margin compression at the commodity tier accelerates shakeout timelines for undifferentiated regional studios.
For Market Incumbents: Anticipate neural TTS encroachment by securing exclusive voice talent licensing agreements and investing in Dolby Atmos certification moats. Defensive consolidation moves include acquiring distressed European art-house facilities to preserve premium-network positioning and embedding compliance workflows for EU AI Act synthetic disclosure mandates ahead of regulatory enforcement. For New Entrants and Emerging Players: Cloud-native API distribution routes offer lowest-friction entry for automated localization platforms targeting advertising agency procurement teams. White-space targets include pharmaceutical video training dubbing under CDSCO-adjacent compliance norms and Southeast Asian back-catalog localization where human actor costs exceed neural synthesis thresholds. Go-to-market positioning should emphasize day-and-date speed guarantees rather than certification credentials. For Investors and Strategic Acquirers: Distressed-cycle entries favor THX-certified immersive audio facilities in London and Berlin where theatrical window recovery sustains premium rate structures. Long-term viability hinges on owned-studio network scale with union compliance infrastructure. The signal to watch is streaming platform procurement shifting from volume-based RFPs to quality-tier unbundling, indicating sustainable margin bifurcation.| Strategic Initiative | Industry Significance |
|---|---|
| Dolby Atmos Certification Investment | Creates defensive moat around theatrical-grade immersive audio mixing credentials required by major studios. |
| Neural TTS Platform Integration | Compresses turnaround timelines for streaming catalog work while preserving human oversight for emotional nuance. |
| EU AI Act Compliance Workflow | Positions vendors for public-sector procurement in France and Germany under emerging synthetic voice disclosure mandates. |
| Indian Hub Capacity Expansion | Captures volume-driven streaming platform contracts for day-and-date multilingual releases at scale. |
| Exclusive Talent Licensing Agreements | Secures original actor vocal signatures for synthetic performance workflows in voice-cloning revenue streams. |
Research Methodology
Industry association filings, customs records for broadcast equipment imports, and SEC disclosures from listed localization providers formed the secondary backbone. Primary interviews with dubbing studio directors, streaming platform localization procurement managers, voice actor union representatives, and theatrical distribution executives combined with secondary validation. Bottom-up and top-down triangulation cross-referenced facility capacity estimates against platform content spend disclosures.
Bottom-up modeling segmented by service type, end user, language pair, and audio format across the projection horizon. CAGRs derived from volume-weighted capacity expansion rates and platform content localization budgets. Forecast inputs incorporated neural TTS adoption curves and regulatory compliance cost overlays for GDPR and EU AI Act workflows.
The model holds under stable streaming platform content investment levels; deviation in theatrical window collapse or accelerated union deregulation would shift capacity utilization assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Middle East Media and Entertainment Market
Digital Media
Digital Content Creator Market
Digital Media
Global Playout Automation and Channel in a Box Market
Digital Media
Social TV Market
Digital Media
Sound Effects Services Market
Digital Media
Media Gateway Market
Digital Media
Digital Media Switchers Market
Digital Media
Animation Services Market
Digital Media
Digital Content Creation Market
Digital Media
United States Sports Betting Market
Digital Media
Sports Broadcasting Technology Market
Digital Media
China Webtoons Market
Digital Media
APAC Animation, VFX and Post Production Market
Digital Media
Digital Video Advertising Market
Digital Media
Global Music Video Production Market
Digital Media
Saudi Arabia Webtoons Market