
 Vietnam Online Travel Market | 2026-2036
Vietnam Online Travel Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Online Travel Market Analytics
The capital-intensity divergence between domestic platforms and multinational aggregators is collapsing as cloud infrastructure costs plummet and API-based inventory access democratizes. Agoda leverages its parent-network hotel supply to dominate coastal resort inventory. Traveloka sustains hyperlocal payment integration across Vietnam's e-wallet ecosystem. VietTravel anchors its position through exclusive domestic tour operator relationships and offline-to-online conversion.
Vietnam online travel denotes digitally intermediated tourism commerce encompassing real-time inventory aggregation, dynamic pricing algorithms, and multi-currency settlement for transportation, lodging, and experiential services. Platforms process search queries through GDS connections and direct supplier APIs, returning ranked results filtered by price, availability, and user-generated sentiment scores. Accommodation booking captures the largest transaction volume due to fragmented hotel supply and homestay proliferation. Package tours generate superior per-booking economics through bundled margin stacking. Mobile apps outperform browser-based platforms in conversion rates, reflecting Vietnam's smartphone-first internet penetration pattern.
The Ministry of Transport enforces e-ticketing standards for aviation and rail carriers, compelling offline operators onto certified platforms. The State Bank of Vietnam's licensing regime for non-bank payment intermediaries shapes wallet integration requirements and escrow protocols for travel deposits. Vietnam's cybersecurity law mandates data localization, increasing infrastructure costs for foreign platforms while creating compliance barriers to entry. Stakeholders must monitor regulatory divergence between ASEAN digital economy frameworks and Vietnam's sovereign data governance posture.
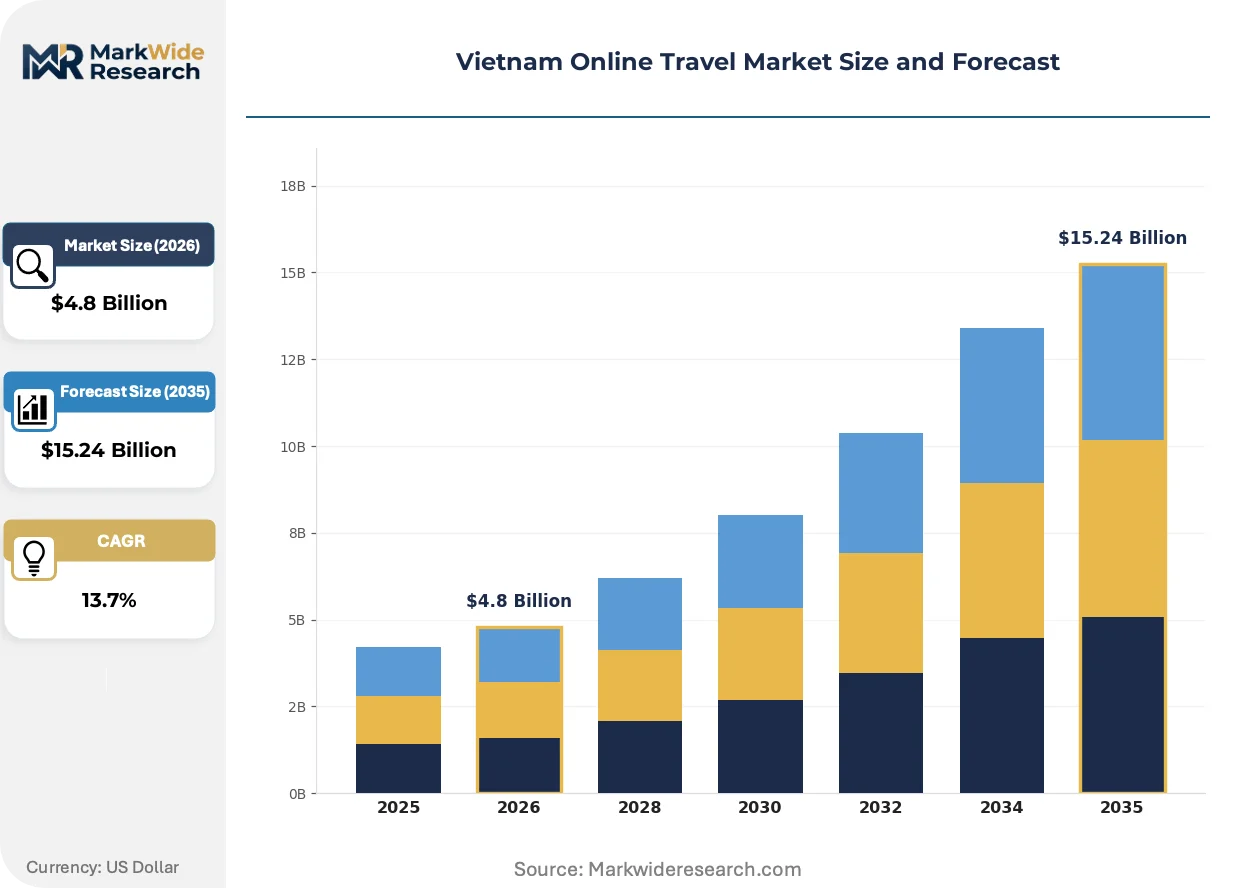
Market Dynamics
Mobile-first booking behavior among Vietnamese leisure travelers is compressing conversion funnels and forcing platform architecture toward instant-confirmation inventory systems. The State Bank of Vietnam's payment licensing framework and the Ministry of Transport's e-ticketing mandates are accelerating offline operator migration to certified digital channels.
Growth Catalysts
- State Bank of Vietnam Payment Licensing:The central bank's framework for non-bank payment intermediaries standardizes escrow protocols and wallet integration, reducing friction for domestic e-wallet adoption across travel platforms.
- Ho Chi Minh City Leisure Demand:Domestic travelers from Vietnam's largest urban center drive mobile booking volume through smartphone-first search and instant-confirmation expectations.
- Cloud Infrastructure Cost Collapse:Plummeting API-based inventory access costs democratize real-time hotel supply aggregation for domestic platforms competing against multinational aggregators.
Market Restraints
- Data Localization Compliance:Vietnam's cybersecurity law mandates domestic server infrastructure, increasing fixed costs for foreign platforms and creating sovereign compliance barriers.
- Fragmented Hotel Supply:The dispersed nature of Vietnam's accommodation inventory—spanning international chains, domestic hotels, and homestays—complicates real-time availability standardization.
- Offline-to-Online Conversion Friction:Traditional tour operators with entrenched agent networks resist full platform migration despite regulatory pressure.
Strategic Opportunities
- Central Highlands Tourism Corridors:Underpenetrated domestic destinations beyond coastal hotspots offer white space for platform inventory expansion and package tour development.
- Dynamic Pricing Algorithm Deployment:Machine learning-driven yield management tools enable real-time rate optimization across Vietnam's seasonal demand fluctuations.
- Ministry of Transport E-Ticketing Mandates:Compulsory digital ticketing for aviation and rail creates regulatory tailwind for certified platform certification and supplier onboarding.
Industry Challenges
- API Integration Complexity:Legacy property management systems at domestic hotels require costly middleware development for real-time inventory synchronization.
- Digital Talent Scarcity:Shortage of engineers skilled in travel-specific payment orchestration and multi-currency settlement limits platform development velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Online Travel Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accommodation Booking, Flight Reservation, Package Tours, Car Rentals Customer Type: Leisure Travelers, Business Travelers, Group Tours, Solo Adventurers Service Type: Online Platforms, Mobile Apps, Travel Agencies, Aggregators Distribution Channel: Direct Sales, Affiliate Marketing, Social Media, Online Marketplaces |
| Companies Covered | Trivago, Expedia, Agoda, VietTravel, Skyscanner, Booking.com, TripAdvisor, Vietnam Airlines, Traveloka, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Online Travel Market Evolving Landscape
Artificial intelligence and sovereign data governance are actively reshaping how Vietnam's online travel platforms architect inventory systems and manage user data. Three distinct shifts are compressing competitive timelines and redefining operational requirements.
Generative AI recommendation engines are fragmenting traditional search-based booking pathways. Domestic platforms deploy large language models to curate personalized itinerary suggestions based on conversational queries rather than static filters. Younger travelers in Hanoi and Da Nang adopt these interfaces at accelerating rates. The technology is fragmenting established ranking algorithms and compressing the window between search intent and transaction completion.
The Ministry of Transport's e-ticketing mandates compel aviation and rail carriers onto certified digital platforms. This regulatory pressure eliminates paper ticket alternatives and forces offline operators to integrate with licensed intermediaries. Coastal tourism corridors see the fastest compliance velocity as international route operators face dual pressure from regulators and foreign partner systems.
Travelers now book accommodation through super-app ecosystems rather than dedicated travel platforms. Grab and ZaloPay users in Ho Chi Minh City initiate hotel searches within financial service interfaces, bypassing traditional aggregators. This behavior shift compresses platform discovery to embedded finance moments. Vietnam's e-wallet penetration rate makes this pattern most visible in urban centers with mature digital payment infrastructure.
Vietnam Online Travel Market Segmentation
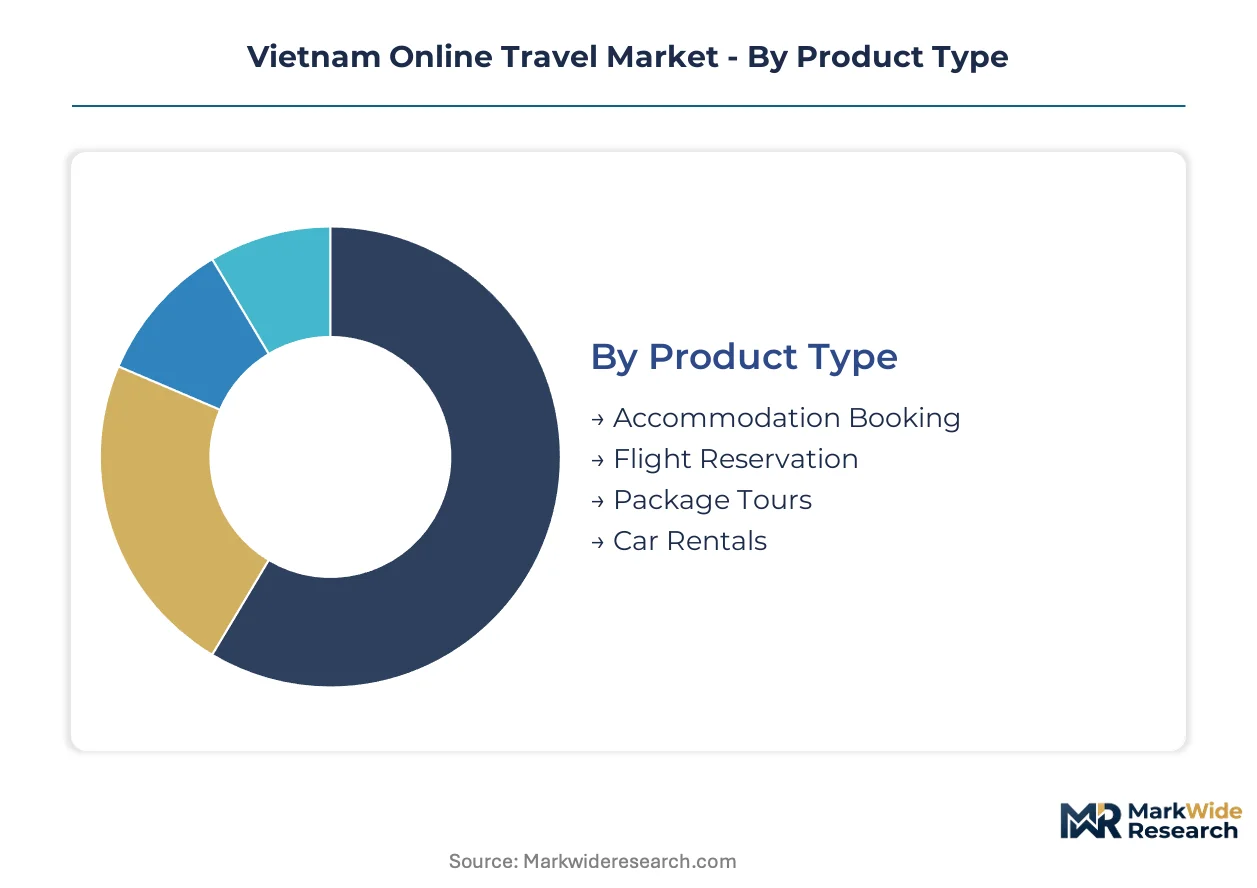
Segmentation in Vietnam's online travel market reveals how booking behavior fragments across product categories and customer profiles. Platform architecture and distribution strategy must align to specific segment expectations around payment integration and confirmation speed.
Product Type:
Domestic leisure demand concentrates in accommodation and package bookings, while flight reservations draw mixed domestic-international traffic. Car rentals remain predominantly domestic with limited cross-border penetration.
- Accommodation Booking:Real-time inventory aggregation spans international chains, domestic hotels, and homestays across Vietnam's coastal corridors. Ho Chi Minh City and Hanoi travelers drive mobile-first search volume with instant-confirmation expectations compressing booking windows.
- Package Tours:Bundled transportation, lodging, and experiential services generate superior per-booking economics through margin stacking. Central Highlands destinations attract expanding domestic interest beyond established coastal hotspots.
- Flight Reservation:Ministry of Transport e-ticketing mandates compel aviation carriers onto certified digital platforms with standardized API protocols.
- Car Rentals:Self-drive and chauffeured services segment by urban pickup density, with Da Nang and Nha Trang showing rising leisure adoption.
Accommodation booking commands the established base. The steepest expansion runs through package tours.
Customer Type:
Leisure travelers dominate transaction volume with smartphone-first behavior, while business travelers prioritize direct platform relationships and flexible cancellation terms.
- Leisure Travelers:Domestic tourists from Vietnam's major urban centers initiate searches through mobile apps with conversational AI interfaces replacing static filters. Younger demographics in Hanoi and Da Nang adopt generative recommendation engines at accelerating rates.
- Business Travelers:Corporate account structures demand centralized billing and policy-compliant inventory with negotiated rate access. This segment concentrates in Ho Chi Minh City and Hanoi where multinational presence drives premium accommodation demand.
- Group Tours:Offline-to-online conversion friction persists as traditional operators with entrenched agent networks resist full platform migration.
- Solo Adventurers:Independent travelers seek fragmented inventory with real-time availability verification and peer-review validation.
Leisure travelers anchor volume concentration. Solo adventurers are expanding most quickly.
Service Type:
Mobile apps outperform browser-based platforms in conversion rates, reflecting Vietnam's smartphone-first internet penetration pattern. Super-app ecosystems increasingly disintermediate dedicated travel interfaces.
- Online Platforms:Browser-based booking sites process search queries through GDS connections and direct supplier APIs, returning ranked results filtered by price and availability.
- Mobile Apps:Native applications achieve superior conversion through streamlined payment flows and push-notification retargeting. Grab and ZaloPay users initiate hotel searches within financial service interfaces, bypassing traditional aggregators.
- Travel Agencies:Traditional intermediaries face regulatory pressure to migrate onto certified digital channels despite legacy commission structures.
- Aggregators:Inventory consolidation platforms compete on supply breadth and dynamic pricing algorithm sophistication.
Mobile apps capture the steepest growth trajectory. Online platforms retain the established revenue base.
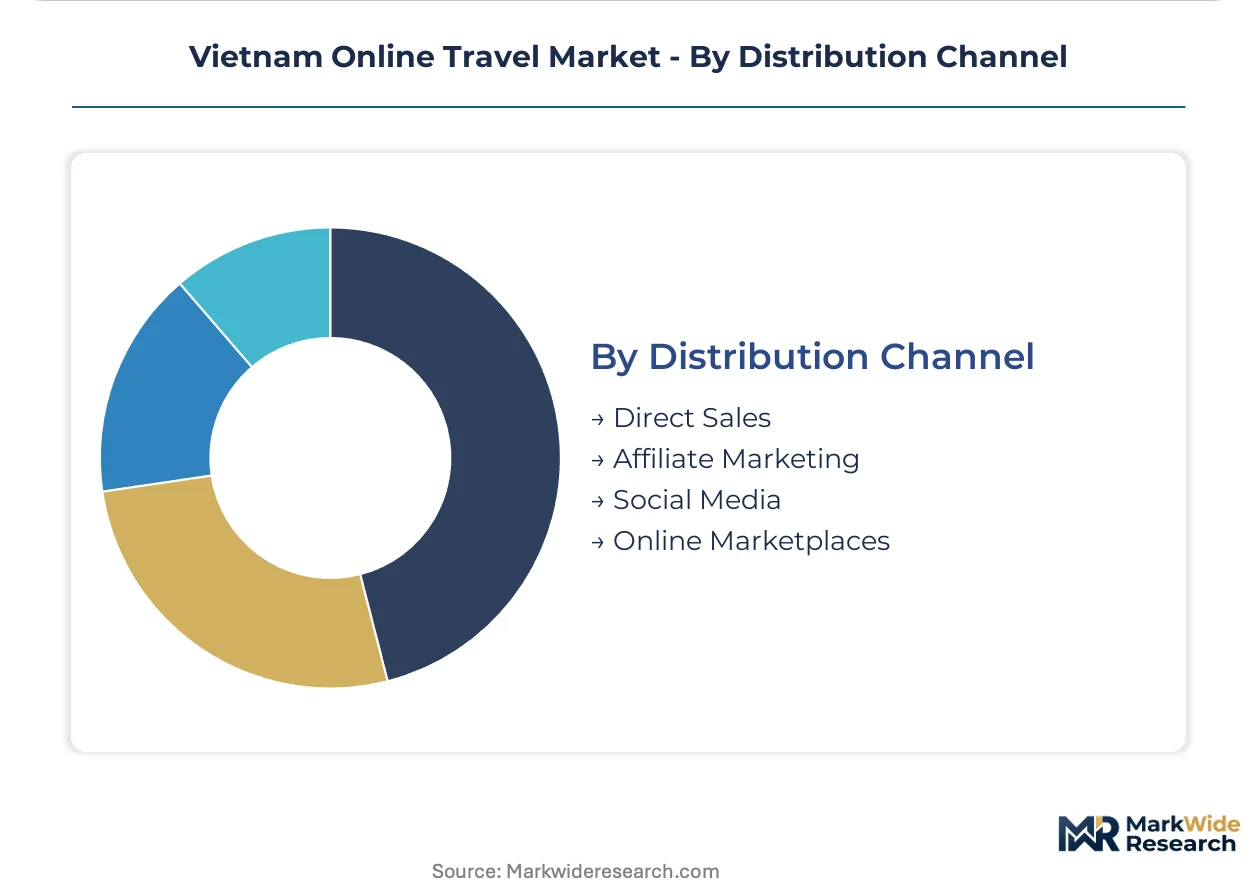
Distribution Channel:
Direct sales and affiliate marketing split customer acquisition costs, while social media and marketplace integrations reshape discovery patterns.
- Direct Sales:Platform-owned traffic reduces customer acquisition costs through organic search optimization and loyalty program retention. State Bank of Vietnam payment licensing enables streamlined escrow protocols for direct bookings.
- Affiliate Marketing:Performance-based partnerships with content publishers and comparison sites extend reach with variable cost structures.
- Social Media:Influencer-driven discovery and user-generated content validation compress consideration phases for younger demographics.
- Online Marketplaces:Embedded travel modules within e-commerce and financial super-apps fragment traditional aggregator dominance.
Direct sales command the established base. Social media distribution is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Vietnamese travel corridors. Ho Chi Minh City leisure buyers exhibit high price sensitivity and mobile-first booking compression. Hanoi corporate travelers show lower elasticity with policy-compliant inventory preferences. Coastal resort zones capture premium willingness-to-pay during peak seasons.
Ho Chi Minh City
Domestic leisure travelers from Vietnam's largest urban center drive mobile booking volume through smartphone-first search behavior. The State Bank of Vietnam's payment licensing framework enables streamlined e-wallet integration across local platforms. District 1 and District 7 hotel clusters see the fastest instant-confirmation inventory adoption.
Hanoi
Business travelers from the capital prioritize direct platform relationships and flexible cancellation terms. Ministry of Transport e-ticketing mandates compel aviation carriers onto certified digital channels. The Ba Dinh and Hoan Kiem accommodation corridors concentrate corporate account demand.
Da Nang
Younger leisure demographics adopt generative AI recommendation engines at accelerating rates for coastal resort bookings. The Ministry of Transport enforces e-ticketing standards for aviation carriers serving the central region. My Khe Beach and Non Nuoc hotel zones attract expanding domestic package tour development.
Nha Trang
Coastal tourism corridors here show fastest regulatory compliance velocity as international route operators face dual pressure. Vietnam's cybersecurity law mandates data localization, increasing infrastructure costs for foreign platforms serving this market. The Tran Phu Beach hotel cluster anchors real-time inventory aggregation efforts.
Central Highlands
Underpenetrated domestic destinations beyond coastal hotspots offer white space for platform inventory expansion. Traditional tour operators with entrenched agent networks resist full platform migration despite regulatory pressure. Dalat and Pleiku emerging as testbeds for bundled experiential package development.
Vietnam Online Travel Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Vietnam's online travel market. Multinational aggregators leverage parent-network hotel supply and global GDS connections. Domestic platforms anchor through hyperlocal payment integration and exclusive tour operator relationships. Competitive moves concentrate on API-based inventory access expansion and super-app ecosystem embedding.
Within the multinational aggregator tier, Agoda and Booking.com exemplify global supply leverage positions. Traveloka occupies a position as the regionally headquartered platform with deep e-wallet integration. VietTravel represents the domestic incumbent archetype with offline-to-online conversion capabilities and exclusive supplier relationships.
| Leading Market Players |
|---|
| Trivago |
| Expedia |
| Agoda |
| VietTravel |
| Skyscanner |
| Booking.com |
| TripAdvisor |
| Vietnam Airlines |
| Traveloka |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure scale economies at Vietnamese domestic platforms compress API access costs and enable price competition against multinational aggregators. This capacity utilization advantage shapes margin structures across accommodation booking tiers while forcing supply chain consolidation around real-time inventory systems.
Pricing Analysis
Post-booking service revenue from itinerary modifications, cancellation insurance, and in-destination experiences drives lifetime value per traveler. Three-tier pricing structure across premium instant-confirmation, standard deferred-confirmation, and economy non-refundable levels segments buyer willingness-to-pay. Price differentiation hinges on confirmation speed and payment flexibility, with Ho Chi Minh City leisure travelers exhibiting highest sensitivity to cancellation policy premiums. Cost compression in standard-tier accommodation booking intensifies as cloud-native entrants replicate API aggregation capabilities without legacy infrastructure overhead.
Supply Chain Analysis
Strategic stockpiling of exclusive hotel inventory through forward-contracted allotments dominates over just-in-time availability models in Vietnam's coastal resort corridors. Platform supply draws from Thailand, Singapore, and domestic Vietnamese property management systems with varying API maturity. Raw material dependencies include cloud compute capacity, payment gateway licenses from the State Bank of Vietnam, and GDS connectivity fees. Single-source vulnerability concentrates in parent-network hotel supply controlled by multinational aggregators. Distribution runs through mobile super-app ecosystems, certified platform direct channels, and remnant affiliate networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded finance integration within Grab and ZaloPay ecosystems threatens dedicated travel platform relevance, forcing incumbents to defend search-intent capture at financial service touchpoints.
For Market Incumbents: Compound defensive data localization investments to satisfy Vietnam's cybersecurity law while accelerating generative AI recommendation engine deployment. Secure exclusive Central Highlands tour operator relationships before regulatory pressure forces full platform migration. Vertical integration into payment escrow infrastructure anchors transaction flow against super-app disintermediation.
For New Entrants and Emerging Players: Lead with white-label inventory aggregation for traditional offline operators resisting full digital migration. Target Dalat and Pleiku package tour development where bundled experiential services generate superior per-booking economics. Deploy conversational AI interfaces to fragment established search-based booking pathways among Hanoi and Da Nang younger demographics.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with sovereign data governance compliance and hyperlocal payment integration depth. Five-to-ten year viability hinges on API-based inventory access expansion beyond coastal corridors into underpenetrated domestic destinations. Monitor State Bank of Vietnam payment licensing velocity as inflection indicator for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Recommendation Engine Deployment | Large language models fragment traditional search-based booking pathways among younger Vietnamese travelers. |
| Central Highlands Inventory Expansion | Dalat and Pleiku package tour development captures white space beyond established coastal tourism corridors. |
| Super-App Ecosystem Embedding | Grab and ZaloPay integration compresses platform discovery to embedded finance moments in Ho Chi Minh City. |
| Exclusive Tour Operator Relationship Securing | Offline-to-online conversion capabilities anchor domestic market share against multinational aggregator supply leverage. |
| Data Localization Infrastructure Investment | Vietnam's cybersecurity law compliance creates sovereign barriers protecting domestic platforms from foreign entrants. |
Research Methodology
Initial hypotheses were tested against primary input from platform product managers, hotel supply partnership directors, payment gateway technical leads, and Ministry of Transport regulatory officials and refined through secondary validation. Primary fieldwork combined structured interviews with online travel platform executives and traditional tour operator digital transformation leads. Secondary sources encompassed State Bank of Vietnam licensing disclosures, Ministry of Transport e-ticketing mandate documentation, and ASEAN digital economy framework comparisons. Bottom-up transaction volume modeling and top-down market sizing triangulation converged on segment-level estimates.
Variance decomposition across product type, customer archetype, service interface, and regional corridor dimensions shaped the analytical framework. CAGRs were derived from fitted growth curves against historical booking volume trajectories and regulatory mandate implementation schedules. Modeled inputs included smartphone penetration elasticity, e-wallet adoption velocity, and generative AI interface adoption rates among Vietnamese leisure travelers. Forecast outputs reflect assumption sets tested across sensitivity scenarios without deterministic year-specific predictions.
The analysis sits within stated boundaries; outcomes outside sustained State Bank of Vietnam payment licensing enforcement or accelerated super-app travel module expansion would require recalibration. Forecasts reflect documented assumptions around regulatory compliance velocity and cloud infrastructure cost trajectories. Revision becomes warranted when embedded finance booking penetration crosses thresholds that fragment dedicated travel platform discovery patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Ecotel Tourism Market
Travel and Tourism
Agritourism Market
Travel and Tourism
Global Enotourism Market
Travel and Tourism
LAMEA Pet Travel Services Market
Travel and Tourism
Mexico Sustainable Tourism Market
Travel and Tourism
Indonesia Sustainable Tourism Market
Travel and Tourism
Japan Outbound Tourism Market
Travel and Tourism
North America Driving Vacation Market
Travel and Tourism
Flower Delivery Services Market
Travel and Tourism
Travel and Tourism Market
Travel and Tourism
Sustainable Traveling Market
Travel and Tourism
New Zealand Sports Tourism Market
Travel and Tourism
Singapore Travel Retail Market
Travel and Tourism
Asia Pacific Wellness Travel Market
Travel and Tourism
South Africa Sports Tourism Market
Travel and Tourism
Digital Travel Market