
 Yacht Charter Service Market | 2026-2036
Yacht Charter Service Market Size, Share, and Industry Trends Forecast 2026-2036
Yacht Charter Service Market Insights
Ultra-high-net-worth private individuals is reorganizing demand patterns across the yacht charter landscape, displacing corporate event planners who once anchored seasonal bookings. Dream Yacht Charter leverages its extensive Caribbean and Mediterranean fleet network to capture extended-family voyage contracts. Fraser Yachts sustains dominance in the superyacht segment through curated crewed experiences exceeding fifty meters. Northrop and Johnson differentiates via its brokerage-to-charter pipeline, converting sales clients into repeat charter patrons.
A yacht charter service constitutes the commercial provision of vessel access—crewed or bareboat—where hull specifications range from thirty-foot sailing monohulls to hundred-meter-plus motor yachts with diesel-electric or conventional propulsion systems, delivered through time-bound contractual arrangements for recreational or hospitality use. Luxury yacht and catamaran categories command premium rate structures due to stabilized platform design and expanded beam-to-length ratios that enhance guest capacity and onboard amenity installation. Motor yacht configurations lead weekly-duration bookings in the Mediterranean, while sailboat demand clusters in hourly and daily windows across Caribbean instructional tourism circuits.
France's ANSM and CNIL frameworks intersect with maritime charter operations through crew certification mandates and guest data handling protocols for online booking platforms. The EU Green Deal and F-Gas Regulation progressively constrain refrigerant choices in onboard climate systems, compelling fleet operators to retrofit or phase older vessels. Stakeholders must monitor emerging port-entry carbon tariffs and decide between accelerated fleet renewal or retrofit compliance pathways before regulatory thresholds harden.
Market Dynamics
Ultra-high-net-worth private individuals are reorganizing demand patterns across the yacht charter landscape, displacing corporate event planners who once anchored seasonal bookings. Mediterranean emissions standards and Croatian marina investments now determine fleet composition and itinerary economics.
Growth Catalysts
- EU Green Deal marine protocols:France and Italy's tightened port-entry standards for protected marine reserves accelerate diesel-electric retrofits, opening premium positioning for compliant operators.
- Croatian Adriatic infrastructure:Marina capacity expansions along Dalmatian coastlines enable extended island-hopping itineraries that capture multi-week bookings from Middle Eastern tourists.
- Catamaran platform engineering:Stabilized hull designs with expanded beam-to-length ratios enhance guest capacity and amenity installation, commanding rate premiums in family voyage contracts.
Market Restraints
- Marine diesel price volatility:Conventional propulsion fleets face margin compression from bunker fuel cost swings, particularly affecting hourly-rate Caribbean instructional operators.
- Superyacht construction concentration:Hull and superstructure fabrication clusters in Italian and Dutch shipyards create supply bottlenecks for fifty-meter-plus crewed vessels.
- F-Gas refrigerant phase-down:The EU F-Gas Regulation constrains onboard climate system choices, forcing accelerated depreciation schedules for vessels with legacy cooling infrastructure.
Strategic Opportunities
- Saudi Red Sea coastline development:Amaala and NEOM projects generate greenfield demand for expedition yacht itineraries with helicopter and submersible capabilities.
- Brokerage-to-charter conversion pipelines:Sales client databases represent untapped repeat charter revenue streams through curated crewed experience offerings.
- Carbon tariff anticipation:Early fleet renewal ahead of hardened port-entry thresholds secures operational permits in French and Italian protected waters.
Industry Challenges
- Certified marine engineer scarcity:STCW-compliant crew recruitment lags vessel delivery schedules, particularly for hybrid-electric propulsion specialists.
- Guest data compliance complexity:France's CNIL frameworks intersect with online booking platform operations, requiring jurisdictional expertise for cross-border reservation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yacht Charter Service Market |
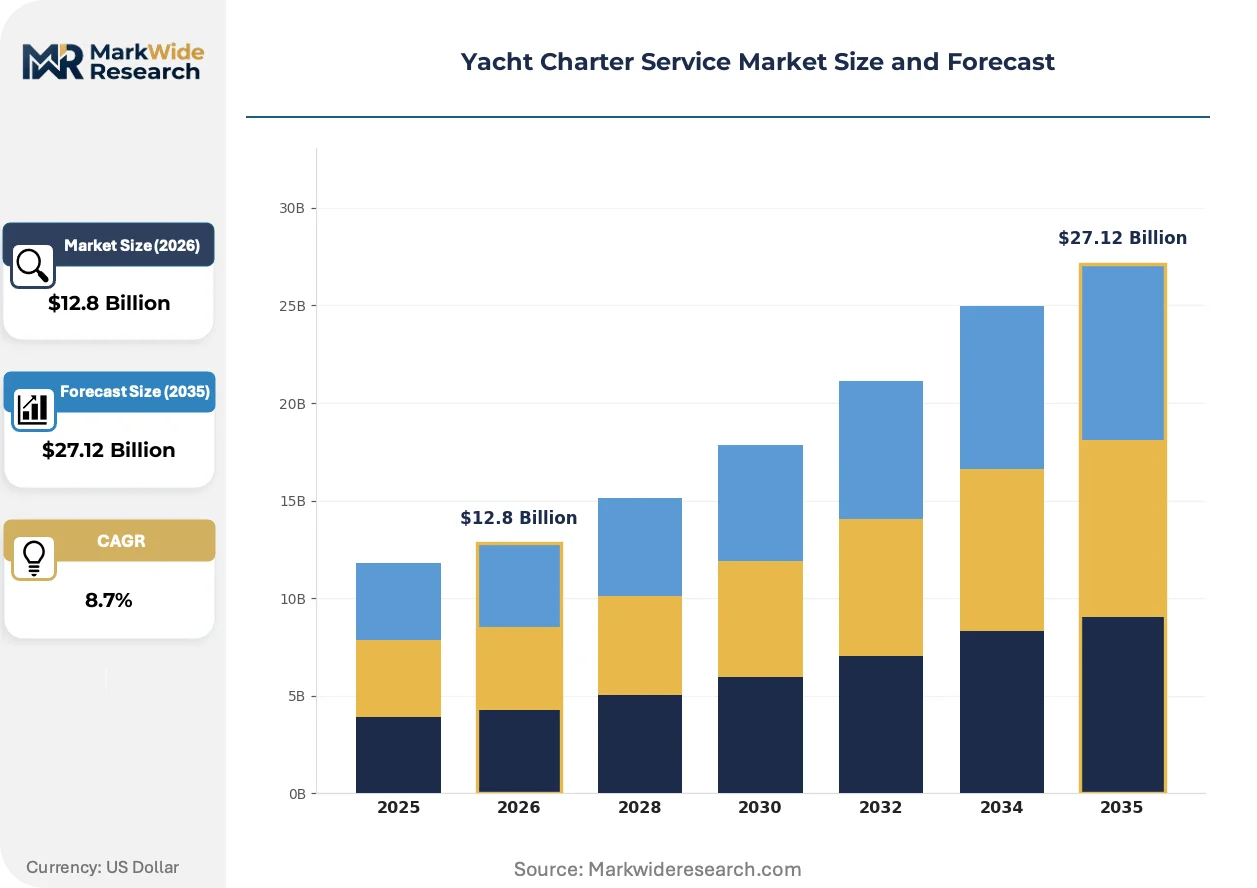
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Luxury Yacht, Sailboat, Motor Yacht, Catamaran Customer Type: Corporate Clients, Private Individuals, Tourists, Event Planners Duration: Hourly, Daily, Weekly, Monthly Booking Channel: Online Platforms, Travel Agencies, Direct Booking, Brokers |
| Companies Covered | Burgess, Dream Yacht Charter, Northrop and Johnson, The Moorings, Fraser Yachts, Ocean Independence, Y.CO, Camper and Nicholsons, IYC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yacht Charter Service Market Trends and Innovations
Diesel-electric hybrid propulsion is actively reshaping fleet investment decisions. Regulatory pressure and buyer preference are converging to redefine operational economics across vessel categories.
Hybrid marine propulsion systems integrate battery storage with conventional diesel generation to enable zero-emission port maneuvering and hotel load operation. Ultra-high-net-worth charter clients now specify electric-quiet anchorage capability as a baseline requirement. This specification is displacing pure diesel configurations from premium weekly-rate Mediterranean bookings.
The EU F-Gas Regulation progressively tightens refrigerant quotas for onboard HVAC and galley cooling systems. Fleet operators face retrofit-or-retire decisions for vessels with high-global-warming-potential cooling circuits. Superyacht segments above fifty meters absorb compliance costs through extended charter rate structures, while smaller bareboat operators accelerate vessel turnover.
Extended-family voyage contracts are compressing traditional corporate event booking windows. Multi-generational itineraries with educational and adventure components displace single-occasion hospitality charters in Caribbean and Mediterranean demand. Croatian Adriatic operators capture this rotation through island-hopping packages designed for seven-to-fourteen-day durations.
Yacht Charter Service Market Segmentation
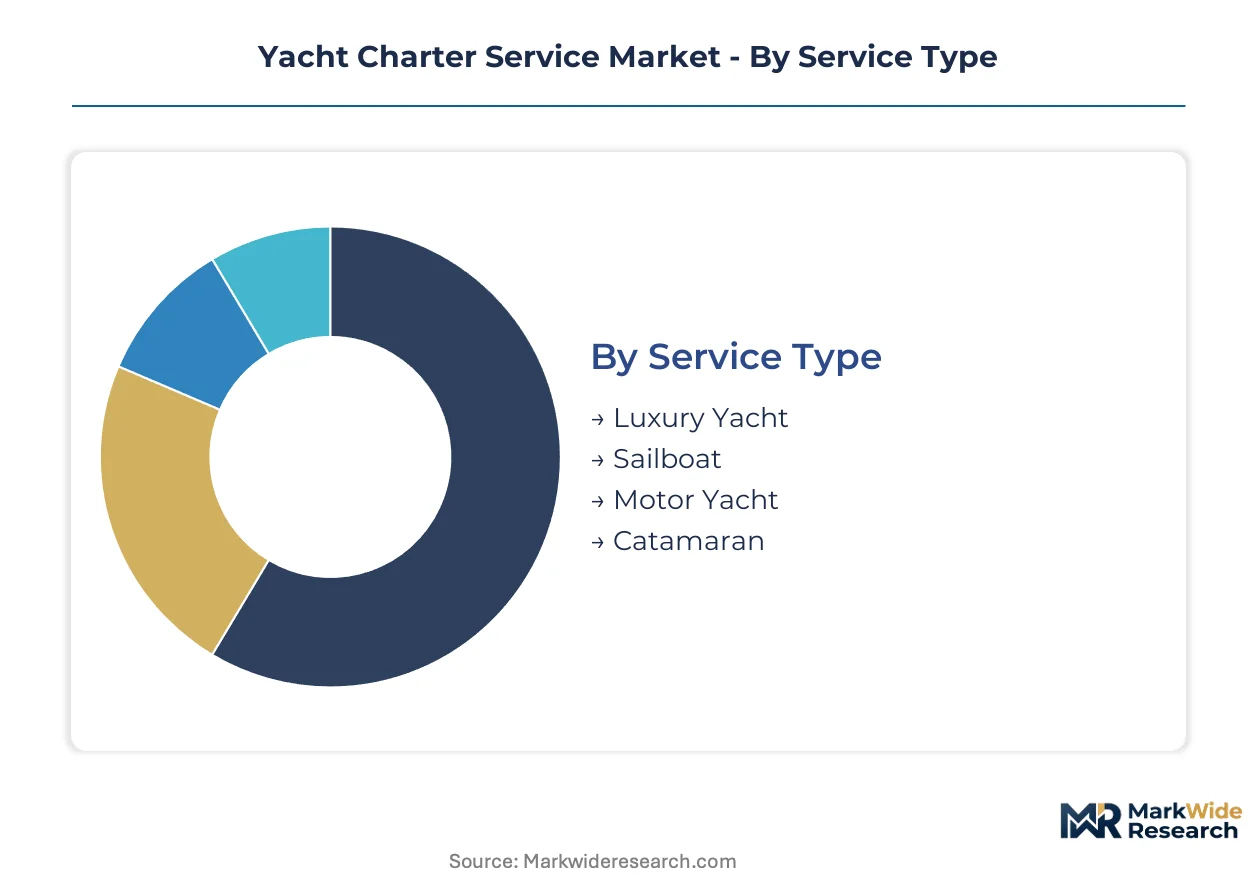
Yacht charter segmentation determines regulatory compliance pathways, crew certification requirements, and rate structures. Different vessel categories face distinct emissions standards under French ANSM and Italian port authority frameworks, while customer type shapes booking duration and seasonal concentration patterns.
Service Type:
French ANSM certification mandates and EU Green Deal marine protocols create divergent compliance burdens across hull configurations, with emissions thresholds varying by propulsion system and vessel length.
- Motor Yacht:Diesel-electric hybrid configurations now dominate weekly Mediterranean bookings as ultra-high-net-worth clients specify electric-quiet anchorage capability. French and Italian protected marine reserves enforce tiered entry standards that exclude conventional diesel-only vessels above certain emission thresholds.
- Catamaran:Stabilized platform designs with expanded beam-to-length ratios enable enhanced guest capacity and onboard amenity installation. Croatian Adriatic operators capture extended-family voyage contracts through island-hopping itineraries that exploit catamaran shallow-draft access to secluded anchorages.
- Luxury Yacht:Vessels exceeding fifty meters command premium rate structures through curated crewed experiences and helicopter or submersible capabilities.
- Sailboat:Hourly and daily instructional tourism circuits in Caribbean markets concentrate demand for smaller bareboat configurations with lower capital requirements.
Established volume favors Motor Yacht; emerging adoption favors Catamaran.
Customer Type:
Cost tier differentiation separates high-touch brokerage relationships from automated platform bookings, with margin structures varying by acquisition channel and repeat purchase rates.
- Private Individuals:Ultra-high-net-worth clients displace traditional corporate event planners as the dominant seasonal booking anchor. Multi-generational itineraries with educational components compress traditional single-occasion hospitality windows in Mediterranean and Caribbean markets.
- Corporate Clients:Event planners now represent a shrinking share of peak-season demand as extended-family contracts capture premium vessel availability. Remaining corporate demand concentrates in product launch and executive retreat formats requiring confidentiality protocols.
- Tourists:European and Middle Eastern visitors drive Croatian Adriatic multi-week bookings through marina infrastructure investments enabling extended island-hopping itineraries.
- Event Planners:Specialized hospitality coordinators now focus on superyacht segments above fifty meters where extended charter rate structures absorb compliance and crew costs.
Private Individuals command premium rate tiers; Tourists drive volume expansion in emerging destinations.
Duration:
Application patterns vary by geography, with Mediterranean itineraries favoring extended windows and Caribbean instructional markets fragmenting into shorter rental periods.
- Weekly:Motor yacht configurations dominate this window in Mediterranean markets where port-hopping itineraries require minimum durations to justify repositioning costs and crew rotations.
- Monthly:Extended contracts capture Middle Eastern tourist demand in Croatian Adriatic markets where marina infrastructure supports sequential island exploration without vessel turnover.
- Daily:Sailboat demand clusters in Caribbean instructional circuits where certification courses and recreational day trips generate high-frequency utilization.
- Hourly:Bareboat operators in coastal tourism zones monetize short windows through streamlined check-in protocols and reduced crew requirements.
Weekly bookings yield highest per-vessel revenue; Daily rentals maximize fleet utilization rates.
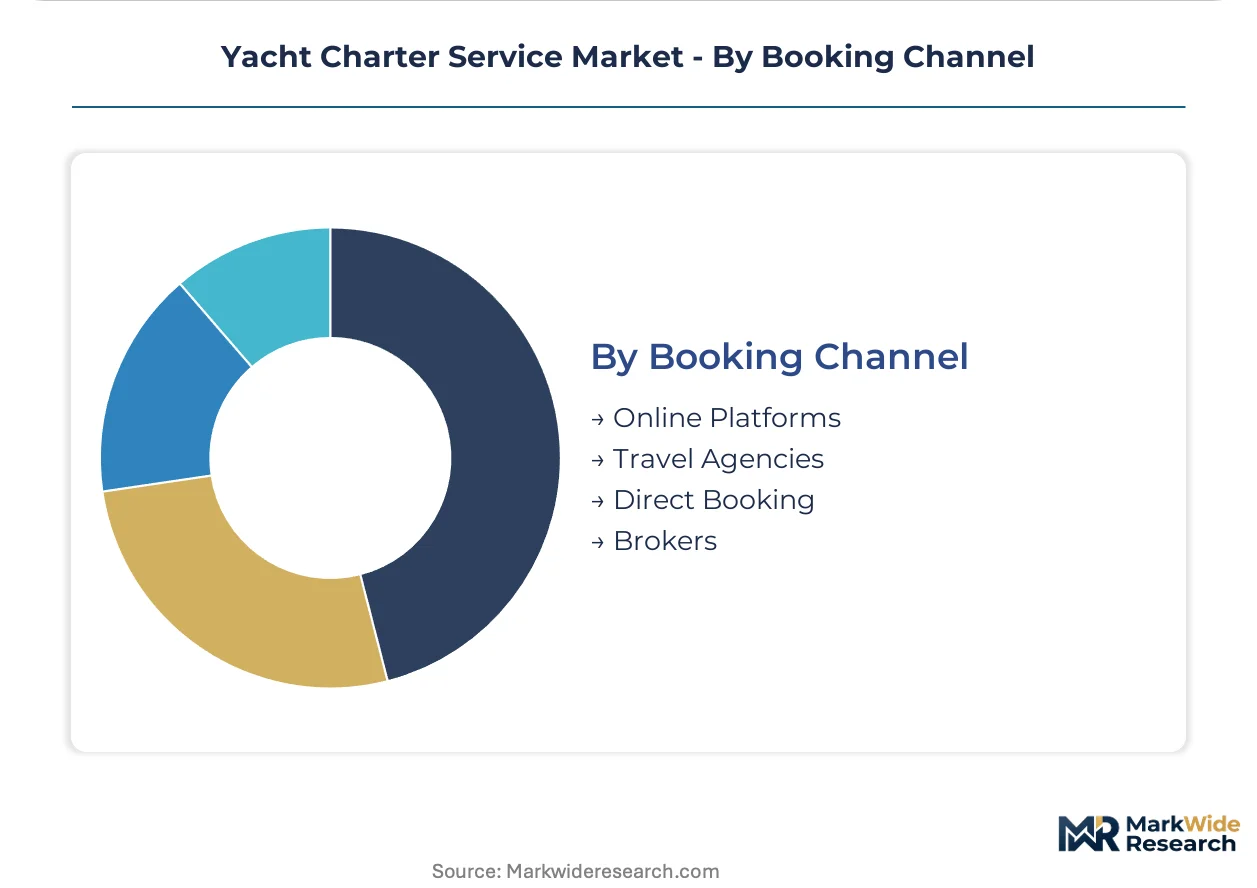
Booking Channel:
Supply concentration among specialized intermediaries creates margin pressure for direct operators, while platform economics favor scaled inventory aggregation.
- Brokers:Sales-to-charter conversion pipelines generate repeat revenue through curated crewed experience offerings and client relationship continuity.
- Online Platforms:France's CNIL data handling protocols impose compliance complexity on cross-border reservation systems, requiring jurisdictional expertise for guest information management.
- Travel Agencies:Traditional intermediaries retain relevance in packaged itinerary markets where flight, transfer, and vessel coordination reduces client planning burden.
- Direct Booking:Owner-operators and fleet managers capture full margin on repeat clients while avoiding platform commission structures.
Brokers dominate superyacht placement; Online Platforms are gaining share fastest in sub-fifty-meter segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Split anchors Croatian Adriatic operations, with marina infrastructure investments enabling extended island-hopping itineraries that capture multi-week bookings from European and Middle Eastern tourists. This facility underwrites the region's emergence as the Mediterranean's fastest-growing yacht charter destination.
France
Ultra-high-net-worth clients drive demand along the Côte d'Azur for diesel-electric hybrid vessels with electric-quiet anchorage capability. ANSM certification mandates and CNIL data handling protocols intersect with crew certification and online booking platform operations. Cannes and Antibes clusters concentrate superyacht brokerage activity above fifty meters.
Italy
Port-entry emissions standards for protected marine reserves reshape fleet composition in Sardinia and Sicily cruising grounds. The EU Green Deal marine protocols accelerate diesel-electric retrofits among operators seeking premium positioning. Italian and Dutch shipyard clusters fabricate hulls and superstructures for fifty-meter-plus crewed vessels.
Croatia
Marina capacity expansions along Dalmatian coastlines enable sequential island exploration without vessel turnover. Middle Eastern tourists generate multi-week bookings through infrastructure investments at Split, Dubrovnik, and Zadar. The shallow-draft accessibility of catamarans opens secluded anchorages inaccessible to deeper-hulled motor yachts.
United States
Caribbean instructional tourism circuits concentrate hourly and daily sailboat demand in Florida Keys and Virgin Islands bases. Bareboat operators monetize short windows through streamlined check-in protocols. Miami and Fort Lauderdale clusters anchor brokerage-to-charter conversion pipelines for repeat client revenue.
United Arab Emirates
Saudi Red Sea coastline development at Amaala and NEOM generates greenfield demand for expedition yacht itineraries. Dubai Marina infrastructure supports superyacht wintering and repositioning logistics. The emirate's aviation connectivity positions it as a gateway for Middle Eastern tourist flows into Mediterranean markets.
Yacht Charter Service Market Competitive Landscape
Listed leaders compete with private specialists across fleet scale and client relationship depth. The market structures around three tiers: global fleet operators with Caribbean-Mediterranean networks, superyacht brokers curating crewed experiences above fifty meters, and regional bareboat specialists serving instructional tourism circuits. Archetypes include inventory aggregators, relationship-driven placement agents, and owner-operator direct providers. Consolidation pressure runs through M&A activity among fleet operators and strategic partnerships between brokers and shipyards.
Within the superyacht placement tier, Burgess and Fraser Yachts occupy positions defined by curated crewed experience offerings and client relationship continuity. Dream Yacht Charter exemplifies the global fleet operator archetype with extensive Caribbean and Mediterranean network coverage. These three anchors represent distinct competitive vectors: brokerage relationship depth, fleet inventory scale, and geographic network density.
| Leading Market Players |
|---|
| Burgess |
| Dream Yacht Charter |
| Northrop and Johnson |
| The Moorings |
| Fraser Yachts |
| Ocean Independence |
| Y.CO |
| Camper and Nicholsons |
| IYC |
| Others |
Pricing and Supply Chain Analysis
French ANSM certification and EU Green Deal marine protocols gate both fleet qualification and rate differentiation simultaneously. Vessel compliance status separates premium weekly-rate Mediterranean bookings from discounted bareboat Caribbean circuits.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the market. Premium tiers attach to diesel-electric hybrid configurations with electric-quiet anchorage capability; standard tiers cover conventional motor yachts in Croatian Adriatic operations; economy tiers capture hourly bareboat sailboat rentals. Price differentiation hinges on emissions compliance grade and crew certification level. Pricing pressure stems from F-Gas refrigerant retrofit costs compressing margins on legacy-cooled vessels. Corporate event planners exhibit highest price sensitivity; ultra-high-net-worth private individuals show lowest sensitivity.
Supply Chain Analysis
Inventory lead times for fifty-meter-plus crewed vessels stretch eighteen to thirty-six months due to hull and superstructure fabrication bottlenecks. Supply concentrates in Italian and Dutch shipyards for superyacht construction, with Croatian and Greek yards handling mid-size refit work. Raw material dependencies include marine-grade aluminum, carbon fiber composites, and hybrid-electric propulsion battery systems. Supply chain risk centers on single-source vulnerability for STCW-compliant marine engineers. Distribution runs through specialized brokers for superyacht placement and online platforms for sub-fifty-meter segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against luxury villa and expedition cruise alternatives that capture extended-family hospitality spending. Incumbents must harden their experiential differentiation to retain charter contract flow.
For Market Incumbents: Shield weekly-rate Mediterranean positioning through accelerated diesel-electric fleet renewal ahead of hardened French and Italian port-entry thresholds. Secure captive crew pipelines via STCW training academy partnerships to offset certified marine engineer scarcity. Vertical integration into Croatian marina infrastructure locks in itinerary control against bareboat competitors.
For New Entrants and Emerging Players: Differentiate on carbon-neutral charter certification to capture ESG-mandated corporate retreat contracts. Target Saudi Red Sea greenfield development at Amaala and NEOM where expedition yacht demand outstrips supply. Pursue direct-to-consumer online platform entry with streamlined booking protocols for hourly sailboat circuits.
For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned Mediterranean fleet operators lacking succession liquidity. Long-term viability favors brokerage-to-charter conversion pipelines with embedded client relationship databases. Watch for inflection when French carbon tariff implementation dates firm, triggering distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Diesel-Electric Fleet Renewal | Secures operational permits in French and Italian protected marine reserves. |
| Marina Infrastructure Partnership | Captures Croatian Adriatic itinerary control through Dalmatian coast capacity. |
| Brokerage-to-Charter Pipeline | Converts yacht sales clients into repeat charter revenue streams. |
| STCW Crew Training Academy | Addresses certified marine engineer scarcity constraining fleet expansion. |
| Carbon-Neutral Certification Program | Positions operators for ESG-mandated corporate retreat contracts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet managers, superyacht brokers, marina operators, and charter clients. Secondary validation drew from EU maritime regulatory filings, port authority emissions databases, customs vessel movement records, and industry association membership data. Bottom-up vessel inventory counts triangulated against top-down market value estimates.
Across the analysis window, the forecasting framework modeled service type, customer type, duration, and booking channel dimensions alongside geographic regulatory cluster variations. CAGRs derived from historical booking volume trajectories adjusted for emissions compliance phase-in schedules and marina infrastructure investment pipelines. Hybrid propulsion adoption curves and Middle Eastern tourist flow patterns served as industry-specific inputs.
Forecasts assume regulatory continuity in French ANSM and EU Green Deal marine protocols; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Japan Sports Tourism Market
Travel and Tourism
Vietnam Online Travel Market
Travel and Tourism
Asia Pacific Wellness Travel Market
Travel and Tourism
South Korea Tourism Market
Travel and Tourism
Incentive Travel Market
Travel and Tourism
India Sports Tourism Market
Travel and Tourism
US Outbound Tourism Market
Travel and Tourism
Tourism Market
Travel and Tourism
Ecotel Tourism Market
Travel and Tourism
France Luxury Travel Market
Travel and Tourism
Hong Kong Outbound Tourism Market
Travel and Tourism
South Korea Travel Retail Market
Travel and Tourism
Customised Holidays Market
Travel and Tourism
USA Sustainable Tourism Market
Travel and Tourism
USA Sports Tourism Market
Travel and Tourism
Global Duty-Free and Travel Retail Market