
 South America E-Commerce Apparel Market | 2026-2036
South America E-Commerce Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
South America E-Commerce Apparel Market Insights
Platform licensing revenue from third-party seller tools is reconfiguring margin pools away from pure merchandise sales toward recurring software income. Mercado Libre leverages its proprietary logistics network to control fulfillment costs across the region. Nike Inc anchors its position through direct-to-consumer app investments that bypass marketplace fee structures. Adidas AG competes via localized production partnerships that compress delivery timelines for Brazilian consumers.
South America E-Commerce Apparel encompasses digitally transacted garments sold through web and mobile interfaces, typically requiring integrated payment gateways, reverse logistics capabilities, and size-fit algorithms to manage high return rates inherent to non-tactile purchasing. The primary commercial purpose is to bridge inventory access between fragmented urban demand and concentrated textile production zones. Activewear commands premium positioning as athleisure penetration deepens among Brazilian and Colombian middle-class segments. Mobile Apps represent the fastest-growing distribution vector, though Online Marketplaces still capture the bulk of transaction volume. The Affordable price tier absorbs the largest order volume, while Luxury segments concentrate margin retention on brand-owned channels.
ANVISA in Brazil and the country's consumer protection agency (Senacon) enforce labeling accuracy and return-right standards that elevate operational compliance costs for cross-border sellers. Argentina's AFIP tax authority and Chile's SII impose value-added collection obligations that reshape pricing architecture on imported apparel. Stakeholders must monitor how data localization mandates and evolving customs de minimis thresholds interact with fulfillment network investments already deployed.
Market Dynamics
Platform licensing revenue from third-party seller tools is reconfiguring margin pools away from pure merchandise sales toward recurring software income, while Brazil's LGPD compliance requirements reshape data collection architectures for personalization engines.
Growth Catalysts
- Mobile-first penetration:Smartphone adoption across Brazilian and Colombian middle-class segments accelerates app-based purchasing frequency. São Paulo's logistics density enables same-day delivery promises that drive repeat transactions.
- LGPD framework maturation:Brazil's data protection law forces platforms to build consent-based personalization infrastructure, creating competitive moats for compliant operators. First-movers capture consumer trust premiums.
- Activewear category expansion:Athleisure demand concentrates among urban professionals in Brazil and Colombia, compressing seasonal sales volatility. Localized production partnerships compress delivery timelines for performance apparel.
Market Restraints
- Cross-border tax complexity:Argentina's AFIP and Chile's SII impose value-added collection obligations that elevate pricing for imported apparel, disadvantaging foreign sellers against domestic platforms.
- Return logistics cost structure:High return rates inherent to non-tactile purchasing strain reverse logistics networks, particularly in markets with limited centralized warehousing outside São Paulo and Bogotá corridors.
- Payment gateway fragmentation:Heterogeneous local payment methods across Brazil, Argentina, and Chile force redundant integration investments, elevating technical overhead for regional expansion.
Strategic Opportunities
- Size-fit algorithm deployment:Machine learning models reducing return rates through predictive sizing capture margin recovery currently lost to logistics. Brazilian platforms lead regional adoption.
- Colombia corridor development:Underpenetrated e-commerce infrastructure in Medellín and Cali offers first-mover advantages for fulfillment network investments ahead of demand maturation.
- Senacon compliance standardization:Brazil's consumer protection agency mandates create operational templates exportable to neighboring markets, reducing multi-jurisdiction adaptation costs for prepared entrants.
Industry Challenges
- Data localization infrastructure:LGPD server requirements force capital-intensive domestic cloud deployments, compressing cash flow for platforms dependent on global hosting economics.
- Customs de minimis volatility:Shifting threshold policies for duty-free imports across Argentina, Chile, and Brazil create inventory planning uncertainty for cross-border sellers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America E-Commerce Apparel Market |
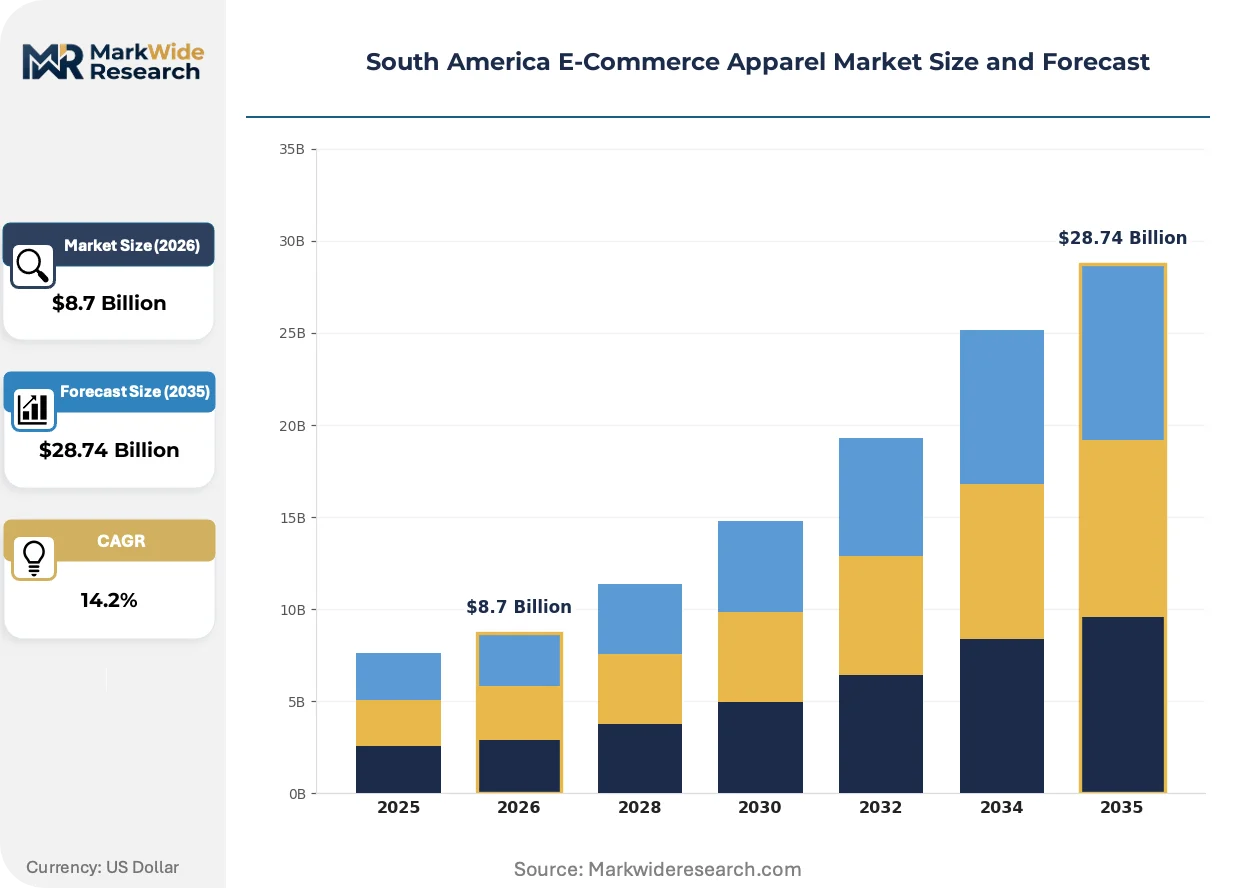
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-shirts, Dresses, Jeans, Jackets, Activewear Customer Type: Men, Women, Kids, Athletes Distribution Channel: Online Marketplaces, Brand Websites, Social Media, Mobile Apps Price Tier: Luxury, Mid-range, Affordable, Discounted |
| Companies Covered | Mercado Libre, Amazon, Nike Inc, Industria de Diseño Textil, S.A. (INDITEX), H & M Hennes & Mauritz AB, Adidas AG, PVH Corp, Falabella, Netshoes, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America E-Commerce Apparel Market Trends and Innovations
Artificial intelligence applications are compressing return rates and logistics costs while regulatory data frameworks force architectural reinvestment across Brazilian operations.
Size-fit algorithms are migrating from basic measurement matching to predictive body modeling using smartphone camera inputs. Mid-market Brazilian retailers adopt these tools at accelerating pace to reduce return processing volumes. The technology is migrating from experimental pilot programs to standard checkout infrastructure, enabling margin recovery previously lost to reverse logistics.
ANVISA labeling requirements for textile imports enforce chemical disclosure standards that elevate supplier documentation burdens. Brazilian platforms must integrate compliance verification into onboarding workflows or face Senacon enforcement actions. Activewear and children's apparel segments absorb the highest compliance adaptation costs due to stricter material safety thresholds.
Direct-to-consumer channel capture is accelerating among brand owners seeking to bypass marketplace fee structures. Nike and Adidas anchor this shift through proprietary app investments that own customer data relationships. São Paulo and Rio de Janeiro metropolitan zones concentrate this behavior, where logistics density supports independent fulfillment economics.
South America E-Commerce Apparel Market Segmentation
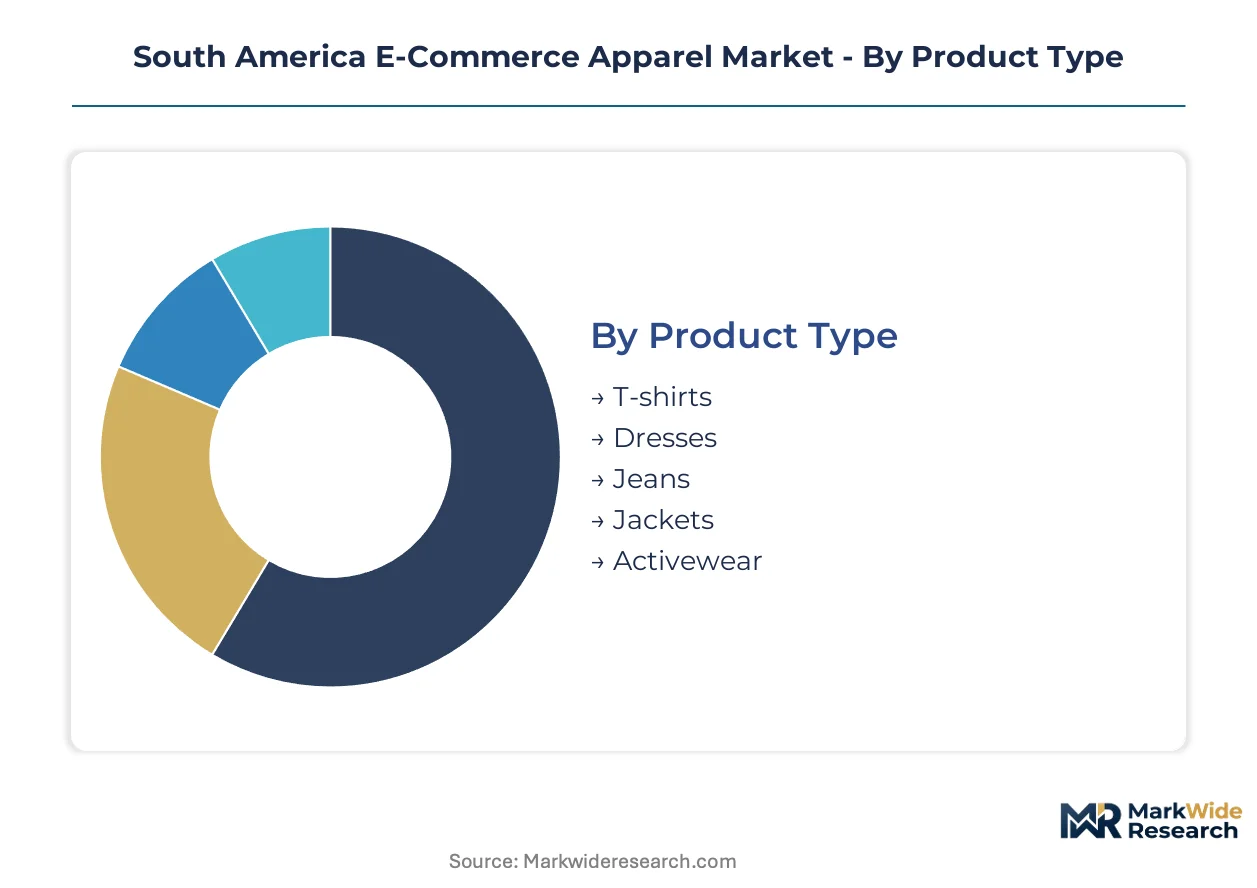
Segmentation in South America E-Commerce Apparel reveals how inventory velocity, margin profiles, and logistics requirements vary sharply across product categories and channel types. Understanding these structural differences enables platforms to allocate fulfillment capacity and marketing spend against actual turnover economics rather than aggregate demand.
Product Type:
Cycle times range from under 30 days for basic tops to 90-plus days for outerwear, with seasonal compression effects most acute in temperate zones like São Paulo and Bogotá.
- T-shirts:Cotton and cotton-blend basics with minimal size variation and standardized grading. Demand concentrates in São Paulo's metropolitan corridor where same-day delivery infrastructure supports impulse replenishment cycles.
- Dresses:Higher SKU complexity with fit-dependent return rates elevated versus separates. Brazilian platforms deploy virtual try-on tools to compress return processing costs in this category.
- Jeans:Denim bottoms with size consistency challenges across regional body-type variation. Colombian consumers drive premium denim demand through Medellín and Cali urban clusters.
- Jackets:Seasonal outerwear with compressed selling windows and elevated warehousing costs. Southern Brazil and Chilean markets extend the viable sales period through temperature variation.
- Activewear:Performance fabrics with technical specifications driving premium positioning. Athleisure adoption among Brazilian and Colombian middle-class professionals anchors regional expansion.
T-shirts dominate installed base. Activewear is where expansion concentrates.
Customer Type:
Spending concentration and frequency patterns diverge significantly, with professional athletes representing a narrow but high-margin niche against mass-market family purchasing.
- Women:Higher average order values with elevated return rates requiring sophisticated size-fit infrastructure. São Paulo and Rio de Janeiro metropolitan zones concentrate purchasing frequency for casualwear.
- Men:Lower return incidence and higher brand loyalty metrics supporting subscription and replenishment models. Brazilian platforms capture recurring revenue through simplified size profiles.
- Kids:Rapid size turnover driving replacement purchasing cycles shorter than adult segments. ANVISA labeling requirements for children's apparel elevate compliance costs for textile imports.
- Athletes:Technical performance requirements with specialized fit needs and premium price tolerance. Localized production partnerships in Brazil compress delivery timelines for this segment.
Women dominate installed base. Athletes is where expansion concentrates.
Distribution Channel:
Channel economics vary from high-fee marketplace structures to owned-infrastructure investments with multi-year payback horizons.
- Online Marketplaces:Aggregated inventory with standardized logistics and payment integration. Mercado Libre's proprietary network controls fulfillment costs across Brazil, Argentina, and Chile.
- Brand Websites:Direct-to-consumer capture enabling data ownership and margin retention. Nike and Adidas anchor this shift through proprietary app investments in São Paulo and Rio de Janeiro zones.
- Social Media:Discovery-driven purchasing with embedded checkout reducing friction for impulse categories. Brazilian and Colombian urban demographics show highest conversion rates through Instagram and TikTok interfaces.
- Mobile Apps:Native interfaces with push-notification engagement driving repeat purchase frequency. São Paulo's logistics density enables same-day delivery promises that reinforce app retention.
Online Marketplaces dominate installed base. Mobile Apps is where expansion concentrates.
Price Tier:
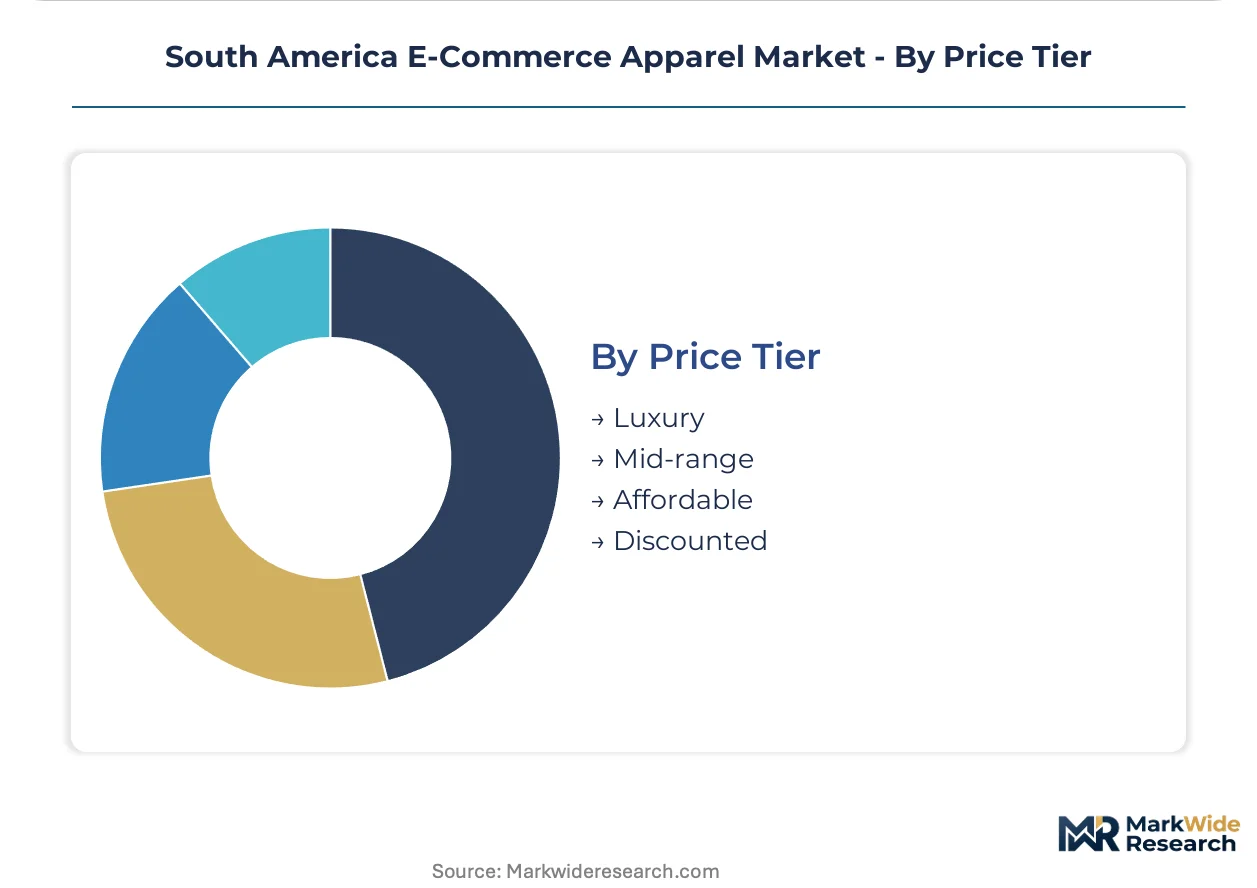
Margin structures and customer acquisition costs invert across tiers, with luxury segments demanding owned-channel infrastructure while affordable tiers absorb marketplace fee structures.
- Luxury:Brand-owned channels with controlled distribution and elevated service expectations. São Paulo concentrates regional luxury demand through dedicated fulfillment infrastructure.
- Mid-range:Balanced margin and volume with platform-dependent logistics economics. Brazilian middle-class segments in São Paulo and Belo Horizonte anchor this tier.
- Affordable:High volume with compressed per-unit margins requiring scale efficiency. Colombia and Brazil absorb largest order volumes through marketplace distribution.
- Discounted:Inventory liquidation and off-season clearance with reverse logistics integration. Seasonal volatility in Southern Brazil and Chile creates planning complexity.
Affordable dominates installed base. Mid-range is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
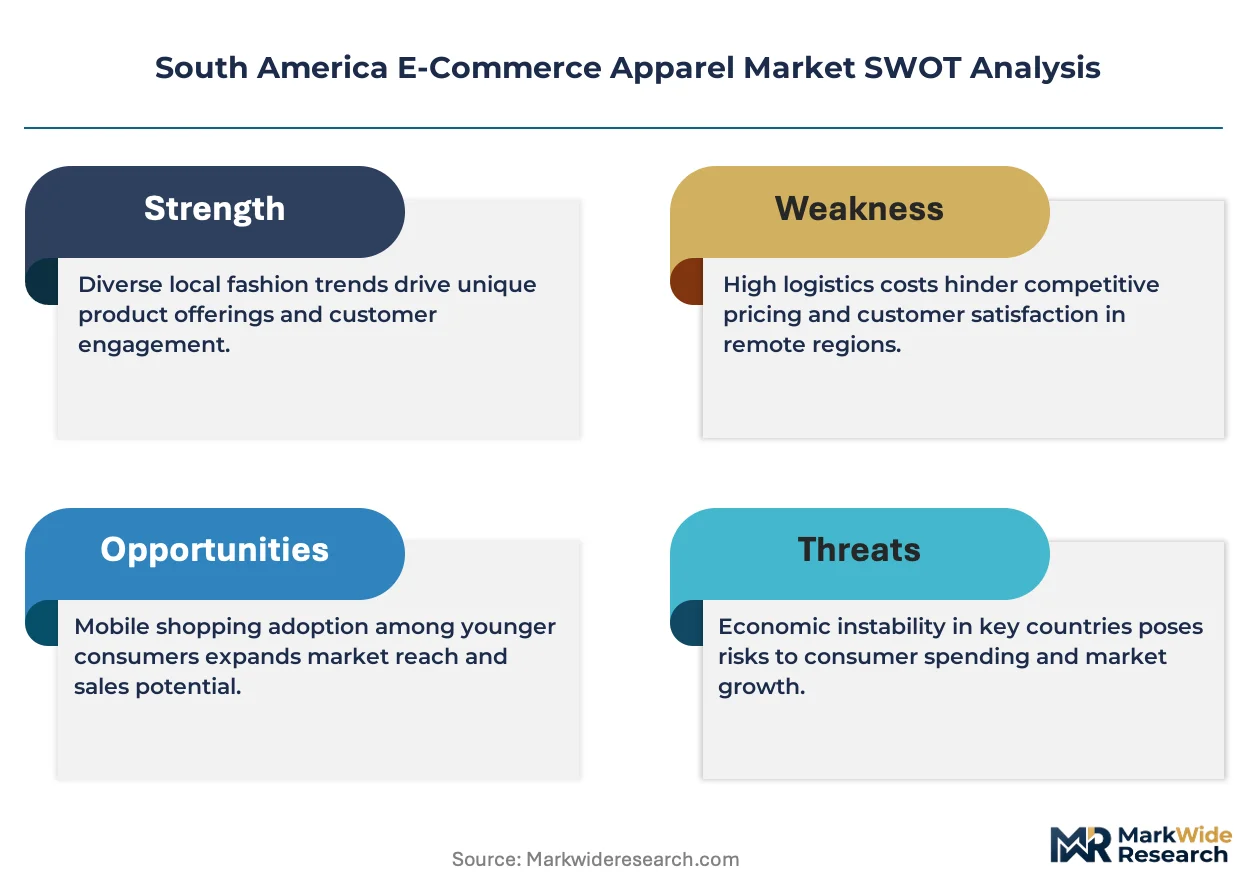
Price elasticity diverges sharply across South American e-commerce apparel markets, with Argentine consumers exhibiting acute sensitivity to import taxation while Brazilian metropolitan buyers absorb premium pricing for same-day fulfillment convenience.
Brazil
LGPD compliance investments by domestic platforms create trust premiums that accelerate app-based purchasing frequency. ANVISA and Senacon enforce labeling accuracy and return-right standards that elevate operational costs for cross-border sellers. São Paulo's logistics density anchors same-day delivery promises, concentrating demand in the metropolitan corridor where fulfillment infrastructure supports repeat transactions.
Argentina
AFIP value-added collection obligations on imported apparel reshape pricing architecture, disadvantaging foreign sellers against domestic platforms. Currency volatility compresses purchasing power among middle-class segments, driving demand toward affordable tiers. Buenos Aires concentrates e-commerce adoption, though logistics fragmentation outside the capital region limits fulfillment speed promises.
Chile
SII tax collection mandates on cross-border transactions elevate landed costs for international apparel sellers. Santiago's concentrated urban population supports efficient last-mile delivery economics. The Valparaíso corridor develops as a secondary fulfillment node, though warehouse density remains below Brazilian standards.
Colombia
Medellín and Cali urban clusters drive athleisure demand among professional segments with compressed seasonal volatility. National consumer protection frameworks mandate return-right standards that platforms must integrate into operational workflows. Bogotá's logistics infrastructure lags São Paulo density, creating first-mover opportunities for fulfillment network investments.
Peru
Lima concentrates national e-commerce apparel demand through limited alternative metropolitan alternatives. Customs processing efficiency for textile imports varies, creating inventory planning uncertainty for cross-border sellers. Local marketplace platforms leverage domestic payment method integration to capture share from international competitors.
South America E-Commerce Apparel Market Competitive Landscape
Capability concentration sits with logistics-integrated platforms that control fulfillment infrastructure; scale advantage sits with global marketplace operators that aggregate third-party inventory. The market structure tiers between proprietary network owners and fee-dependent sellers. Three archetypes dominate: logistics-integrated marketplaces, direct-to-consumer brand owners, and specialized vertical platforms. Competitive moves center on fulfillment network expansion and proprietary app development that captures customer data relationships.
Within the logistics-integrated tier, Mercado Libre exemplifies infrastructure control through proprietary network investments across Brazil, Argentina, and Chile. Nike Inc and Adidas AG anchor the direct-to-consumer vector through brand-owned channel strategies that bypass marketplace economics. These three entities represent divergent approaches to margin retention—software licensing revenue, data ownership, and localized production partnerships respectively.
| Leading Market Players |
|---|
| Mercado Libre |
| Amazon |
| Nike Inc |
| Industria de Diseño Textil, S.A. (INDITEX) |
| H & M Hennes & Mauritz AB |
| Adidas AG |
| PVH Corp |
| Falabella |
| Netshoes |
| Others |
Pricing and Supply Chain Analysis
China's concentrated textile manufacturing base anchors cost structures for South American e-commerce apparel platforms, with Bangladesh and Vietnam absorbing overflow capacity as regional demand for fast-fashion replenishment intensifies. Margin pools downstream concentrate with logistics-integrated operators that control last-mile delivery economics rather than pure merchant intermediaries.
Pricing Analysis
Platform licensing revenue from third-party seller tools now drives lifetime value beyond initial merchandise transactions. Three-tier pricing structure across premium, standard, and economy levels segments buyers by delivery speed expectations and return flexibility. Price differentiation rests on logistics density and data personalization maturity. Cost compression in the affordable tier intensifies as cross-border tax obligations from Argentina's AFIP and Chile's SII elevate landed costs for foreign sellers. Argentine consumers exhibit acute price sensitivity due to currency volatility, while São Paulo metropolitan buyers absorb premium pricing for same-day fulfillment convenience.
Supply Chain Analysis
Extended payment terms from Bangladeshi and Vietnamese garment suppliers compress working capital cycles for platform procurement teams. Raw material dependencies center on cotton futures, synthetic fiber blends, and performance textiles from Chinese petrochemical feedstocks. Single-source vulnerability concentrates in dyeing and finishing capabilities concentrated in Guangdong province. Distribution runs through Mercado Libre's proprietary logistics network across Brazil, Argentina, and Chile, with emerging direct-to-consumer channels bypassing marketplace fee structures entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software licensing revenue from seller tools and size-fit algorithm subscriptions expands faster than pure merchandise margins, reframing this market as a service-attach opportunity with recurring income stability.
For Market Incumbents: Harden data localization infrastructure to meet Brazil's LGPD server requirements before enforcement actions from Senacon accelerate compliance costs. Deepen proprietary logistics network density in Colombia's Medellín and Cali corridors ahead of demand maturation. Control fulfillment infrastructure rather than outsourcing to capture margin recovery from return logistics compression. For New Entrants and Emerging Players: Colombia's underpenetrated e-commerce infrastructure offers first-mover positioning in athleisure segments where localized production partnerships compress delivery timelines. Target professional athletes and urban professionals in Bogotá with technical activewear assortments underserved by current marketplace inventory. Deploy size-fit algorithms as standard checkout infrastructure to differentiate against incumbent return processing costs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across proprietary logistics network deployments as platforms shift from asset-light marketplace models to infrastructure ownership. Long-term viability favors operators with integrated fulfillment economics and consent-based personalization architectures compliant with evolving data protection mandates. Monitor LGPD enforcement patterns and customs de minimis threshold adjustments as inflection indicators for cross-border seller competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Logistics Network Expansion | Mercado Libre's fulfillment infrastructure controls cost structures across Brazil, Argentina, and Chile corridors. |
| Size-Fit Algorithm Deployment | Machine learning models reduce return processing volumes and recover margins lost to reverse logistics. |
| Direct-to-Consumer Channel Launch | Nike and Adidas bypass marketplace fees through proprietary apps that own customer data relationships. |
| LGPD Compliance Infrastructure Investment | Domestic cloud deployments create competitive moats as Senacon enforcement elevates operational barriers. |
| Localized Production Partnerships | Brazilian manufacturing compresses delivery timelines for performance apparel and children's segments under ANVISA scrutiny. |
Research Methodology
Operator-level perspectives from e-commerce platform executives, logistics network managers, apparel brand digital directors, and regulatory compliance officers anchored the qualitative base. Primary interviews combined with secondary validation from ANVISA regulatory filings, Senacon consumer protection directives, AFIP tax authority publications, and customs trade records. Bottom-up demand modeling triangulated against top-down market sizing across product type, customer segment, distribution channel, and price tier dimensions.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation modeling spanning product category velocity, customer purchase frequency, channel economics, and metropolitan logistics density. CAGRs derived from trend extrapolation of mobile app penetration, athleisure adoption patterns, and platform licensing revenue growth. Forecast inputs incorporated LGPD compliance cost trajectories and cross-border tax collection obligation impacts on pricing architecture.
The forecast holds incumbent behavior within observed patterns; aggressive infrastructure investments by direct-to-consumer brand owners or logistics-integrated specialists would shift outcomes. Macroeconomic volatility in Argentina, regulatory enforcement acceleration from Brazil's data protection authority, or customs threshold policy deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
E-Commerce in Nigeria Market
E-Commerce Solutions
UAE Ecommerce Market
E-Commerce Solutions
Sweden E-Commerce Market
E-Commerce Solutions
United States Same-Day Delivery Market
E-Commerce Solutions
South Korea Ecommerce Logistics Market
E-Commerce Solutions
Europe Automotive E-Commerce Market
E-Commerce Solutions
Philippines E-Commerce Market
E-Commerce Solutions
Indonesia E-Services Market
E-Commerce Solutions
Poland E-Commerce Market
E-Commerce Solutions
IT Consumer Electronics E-Commerce Market
E-Commerce Solutions
Saudi Arabia E-Commerce Market
E-Commerce Solutions
North America E-Commerce Watch Market
E-Commerce Solutions
New Zealand E-Commerce Market
E-Commerce Solutions
Asia-Pacific Dropshipping Market
E-Commerce Solutions
China Alcohol E-Commerce Market
E-Commerce Solutions
Slovakia E-Commerce Market