
 US Outbound Tourism Market | 2026-2036
US Outbound Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
US Outbound Tourism Market Analytics
Mexico's hospitality capacity build-out is reshaping competitive dynamics for US outbound tourism operators. Trafalgar leverages its guided tour infrastructure across European itineraries to sustain repeat booking rates among affluent American retirees. Intrepid Travel competes through adventure-focused small-group formats that dominate the under-35 demographic. G Adventures anchors its position with community tourism partnerships that differentiate supply from mass-market cruise and resort packages.
US outbound tourism encompasses American residents traveling internationally for temporary stays, typically involving commercial air transport, lodging arrangements, and destination services booked through digital or agent-mediated channels. The sector functions as a demand-driven services ecosystem where traveler preferences, currency fluctuations, and carrier capacity collectively determine volume distribution. Leisure travel within the Travel Purpose dimension leads absolute spending, while the Solo Travelers demographic profile generates the fastest-growing margin pool as operators design premium-priced unaccompanied itineraries. Online Travel Agencies within the Booking Channel dimension capture disproportionate share among price-sensitive segments, though Direct Booking strengthens in luxury and adventure categories where customization commands premium positioning.
The Department of Transportation enforces consumer protection standards for airline overbooking and refund timelines that directly shape US traveler confidence in international bookings. The Transportation Security Administration coordinates with foreign aviation authorities on security protocol reciprocity, influencing destination accessibility and perceived risk. The Federal Trade Commission monitors deceptive pricing in Online Travel Agencies, tightening transparency requirements. Stakeholders must monitor how biometric border systems and evolving carbon disclosure rules for aviation alter traveler choice architecture and supplier compliance burdens.
Market Dynamics
Biometric border screening infrastructure at US ports of entry is compressing processing times while elevating traveler expectations for seamless international journeys, forcing destination operators to synchronize their arrival experiences with federal standards.
Growth Catalysts
- Real ID enforcement:The Department of Homeland Security's phased implementation of enhanced identification requirements has streamlined domestic-to-international passenger flows at major US airports, reducing friction for outbound departures.
- Experience economy spending:Millennial and Gen Z leisure travelers allocate disproportionate budgets to immersive cultural programming, adventure activities, and local gastronomy rather than traditional resort packages.
- Digital booking platforms:Online Travel Agencies and direct-to-consumer operator websites have collapsed search-to-purchase cycles, enabling dynamic packaging of flights, lodging, and destination services.
Market Restraints
- Jet fuel cost volatility:Carrier fuel hedging strategies face pressure from geopolitical supply disruptions, compressing operating margins and constraining route expansion to secondary destinations.
- Airport slot concentration:Limited takeoff and landing rights at Newark, JFK, and LAX create bottlenecks that favor legacy network carriers over emerging low-cost competitors.
- Visa processing friction:Extended appointment wait times at US consulates for destinations requiring pre-approved entry documents deter spontaneous booking patterns among price-sensitive segments.
Strategic Opportunities
- Secondary city gateways:Austin, Nashville, and Denver international airports are expanding direct long-haul capacity, reducing dependency on coastal hub connections for outbound travelers.
- Sustainable aviation fuel mandates:The Inflation Reduction Act's production tax credits for SAF create pathway for carriers to market lower-carbon itineraries to environmentally conscious travelers.
- Solo traveler premiumization:Unaccompanied leisure travelers represent an underserved margin pool, with demand for single-occupancy accommodations and curated independent experiences outpacing supply.
Industry Challenges
- Biometric system integration:Destination operators must reconcile TSA PreCheck and Global Entry data standards with foreign border control technologies, creating interoperability costs.
- Workforce compression:Pilot and cabin crew shortages at regional carriers limit capacity recovery, constraining feeder traffic to international hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Outbound Tourism Market |
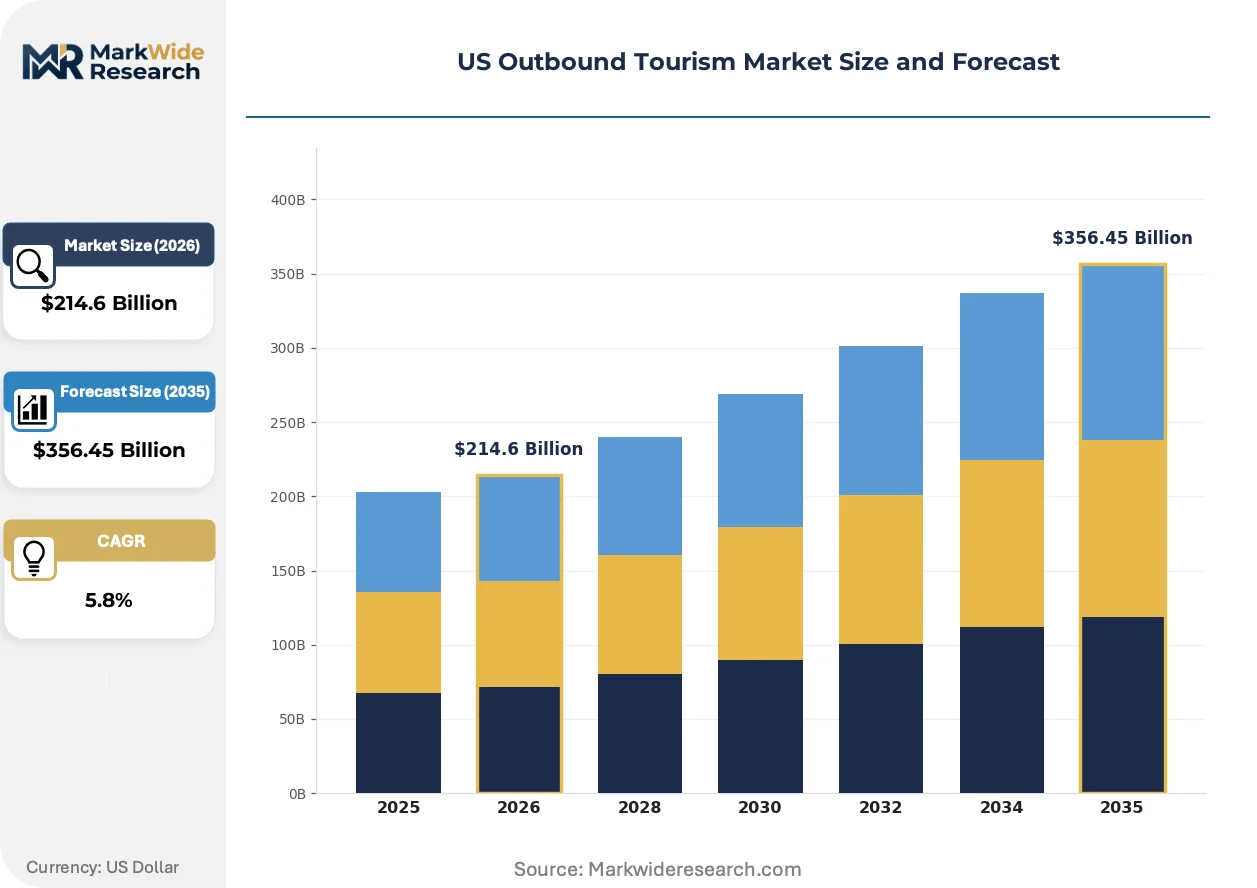
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $356.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Travel Purpose: Leisure, Business, Education, Medical Demographic Profile: Families, Couples, Solo Travelers, Seniors Booking Channel: Online Travel Agencies, Direct Booking, Travel Agents, Mobile Apps Destination Type: International Cities, Beach Resorts, Cultural Sites, Adventure Destinations |
| Companies Covered | Trafalgar, Exodus Adventure Travels, Apple Leisure Group, Insight Vacations, Explore!, Flight Centre Travel Group, Intrepid Travel, Bamba Travel, G Adventures, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Outbound Tourism Market Evolving Landscape
Distributed ledger and artificial intelligence applications are rewiring how travelers discover, book, and experience international itineraries, collapsing traditional agency intermediation while elevating personalization expectations.
Biometric identity verification is migrating from pilot programs at select airports to standardized deployment across the US departure ecosystem. The Transportation Security Administration's Credential Authentication Technology with Camera integration enables touchless document checks at 80-plus airports. This infrastructure compression is forcing foreign destination authorities to reciprocate with compatible entry systems or risk losing US visitor volume to more accessible alternatives.
The Federal Trade Commission's updated advertising disclosure rules for Online Travel Agencies now mandate all-in pricing transparency, eliminating drip-pricing tactics that obscured true trip costs. This regulatory shift compresses margin flexibility for intermediaries while elevating direct booking appeal among comparison-fatigued travelers. Luxury and adventure operators with complex customization needs are responding by strengthening proprietary reservation platforms.
Subscription-based travel memberships are displacing transactional booking patterns among frequent outbound travelers. Generation Z buyers in particular favor annual fee structures that unlock priority access, flexible cancellation, and exclusive inventory over per-trip commissions. This behavioral rotation is most visible in coastal metropolitan markets where digital-native travelers demonstrate higher willingness to pre-commit capital for travel benefits.
US Outbound Tourism Market Segmentation
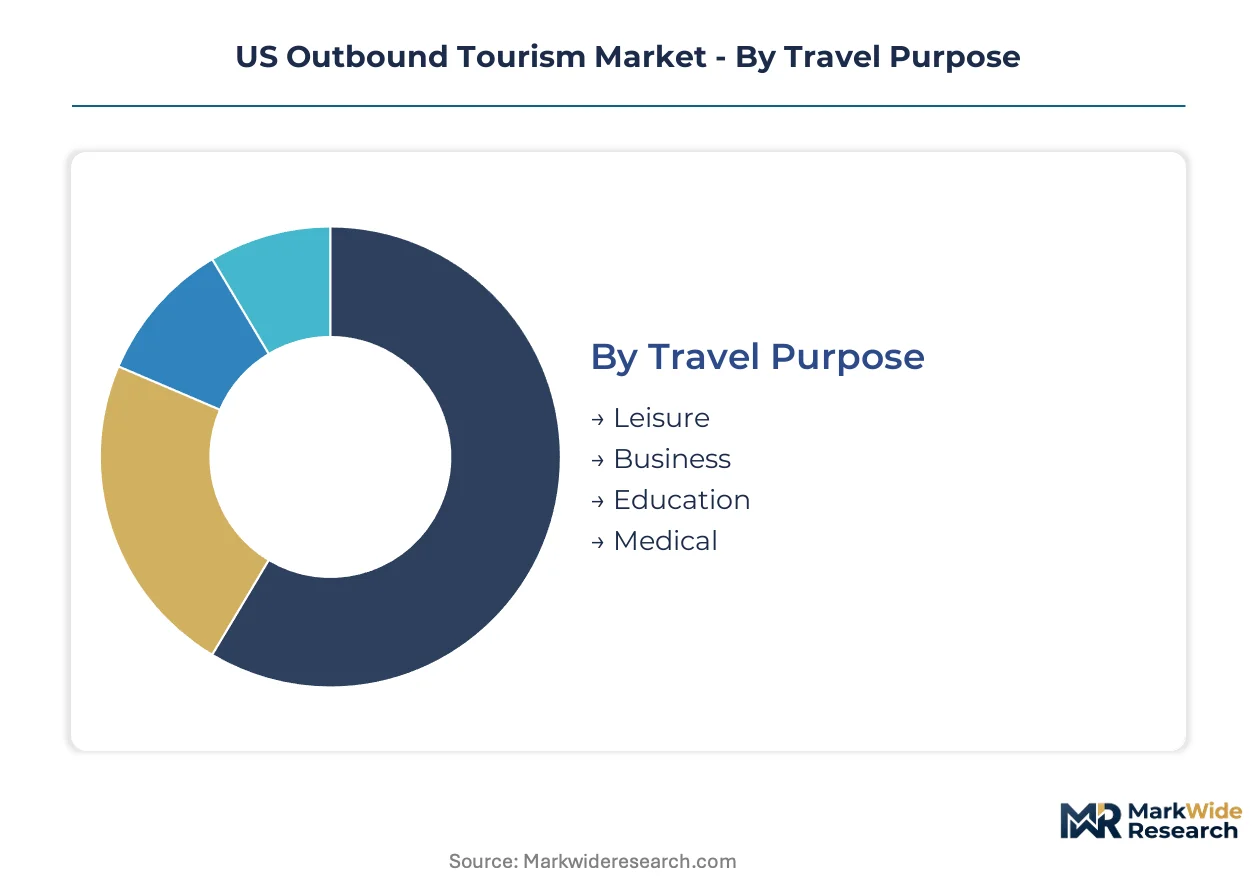
Segmentation in US outbound tourism reveals how traveler identity and purchase context reshape operator economics. Cycle times vary dramatically across categories, with booking channels turning over in minutes while demographic loyalties persist across years.
Travel Purpose:
Booking windows compress from twelve weeks for leisure itineraries to forty-eight hours for medical departures, creating divergent revenue recognition patterns across segments.
- Leisure:Discretionary vacation travel spanning cultural immersion, beach relaxation, and entertainment pursuits. Demand concentrates in Western European capitals and Southeast Asian coastal provinces, driven by millennial preference for experience-intensive itineraries over traditional resort packages. Leisure dominates installed base. Education is where expansion concentrates.
- Business:Corporate-sponsored travel for meetings, conferences, and client engagements. Procurement cycles align with fiscal quarters, with demand clustering in global financial centers and technology corridors where multinational headquarters maintain presence. Business dominates installed base. Education is where expansion concentrates.
- Education:Academic programs, language immersion, and research placements abroad. Enrollment decisions lock twelve to eighteen months ahead of departure, creating predictable cash flow but limiting dynamic pricing leverage.
- Medical:Elective procedures, specialized treatments, and wellness retreats requiring international travel. Appointment scheduling ties to clinical availability rather than seasonal patterns, compressing ancillary service attach rates.
Leisure dominates installed base. Education is where expansion concentrates.
Demographic Profile:
Cost tiers stratify sharply across this dimension, with solo travelers commanding per-capita premiums while families optimize for bundled value.
- Families:Multi-generational or parent-child travel units prioritizing safety infrastructure, connected accommodations, and activity variety. Demand clusters in Orlando gateway departures toward Caribbean all-inclusive properties and European heritage circuits.
- Couples:Pair-based leisure travel emphasizing romantic positioning, dining experiences, and privacy amenities. Honeymoon and anniversary segments sustain above-average commission rates for specialized packaging.
- Solo Travelers:Unaccompanied leisure travelers seeking independence with curated support structures. Demand concentrates in premium-priced single-occupancy lodging and guided small-group formats, with Austin and Denver origins expanding fastest. Solo Travelers dominates installed base. Families is where expansion concentrates.
- Seniors:Retiree travelers with extended duration flexibility and cruise package affinity. Trafalgar's guided European itineraries capture disproportionate repeat booking rates from this cohort through accessibility-assured programming.
Solo Travelers dominates installed base. Families is where expansion concentrates.
Booking Channel:
Volume concentrates in digital intermediaries, though margin accrues to direct relationships where customization complexity justifies service premiums.
- Online Travel Agencies:Digital platforms aggregating flights, lodging, and ancillary services with comparison-driven interfaces. The FTC's all-in pricing disclosure mandates have compressed margin flexibility, elevating transparency expectations. Online Travel Agencies dominates installed base. Direct Booking is where expansion concentrates.
- Direct Booking:Reservations completed through operator-owned websites, call centers, or proprietary mobile applications. Luxury and adventure specialists strengthen these channels where itinerary complexity exceeds OTA configuration limits.
- Travel Agents:Human-mediated booking through independent advisors or agency networks. Corporate accounts and complex multi-destination leisure itineraries sustain this channel against digital displacement.
- Mobile Apps:Smartphone-native booking interfaces with push-notification deal delivery and one-tap purchase flows. Generation Z adoption rates exceed other demographics, with coastal metropolitan markets showing highest penetration.
Online Travel Agencies dominates installed base. Direct Booking is where expansion concentrates.
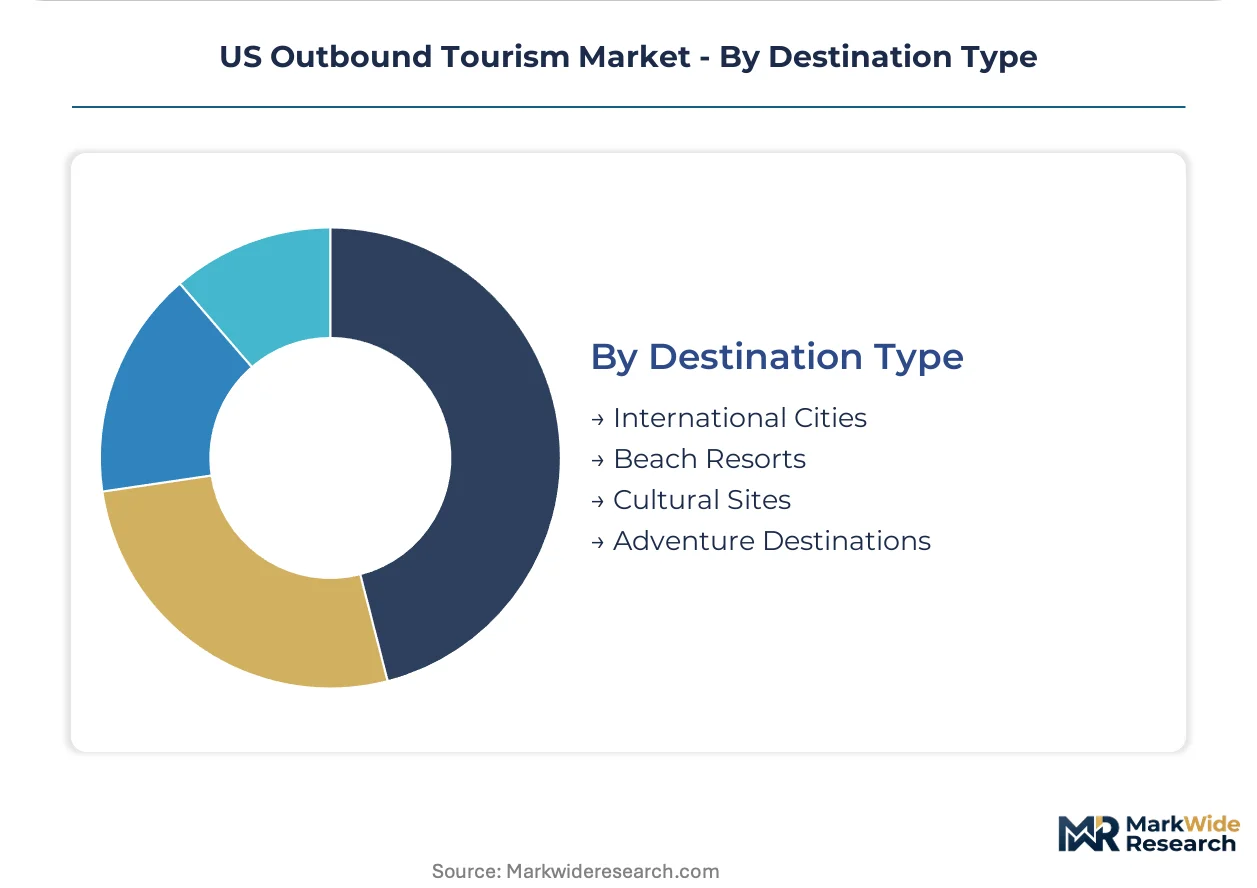
Destination Type:
Supply concentration varies by infrastructure requirements, with international cities demanding established carrier networks while adventure destinations rely on specialized ground operators.
- International Cities:Metropolitan destinations with dense business districts, cultural institutions, and entertainment infrastructure. Newark and JFK slot concentration favors legacy carrier access to London, Paris, and Tokyo. International Cities dominates installed base. Adventure Destinations is where expansion concentrates.
- Beach Resorts:Coastal leisure properties emphasizing sand, water recreation, and relaxation amenities. Mexico's hospitality capacity build-out has reshaped competitive dynamics for US operators in this segment.
- Cultural Sites:Heritage tourism centered on museums, archaeological zones, and historic districts. Extended dwell times and guided programming requirements differentiate this from city-break travel.
- Adventure Destinations:Physically active itineraries spanning trekking, diving, wildlife observation, and extreme sports. Intrepid Travel's small-group formats dominate the under-35 demographic, with community tourism partnerships from G Adventures differentiating supply from mass-market alternatives. Adventure Destinations dominates installed base. Beach Resorts is where expansion concentrates.
International Cities dominates installed base. Adventure Destinations is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US outbound travelers exhibit distinct consumption patterns by destination geography, with Western European itineraries emphasizing cultural density and extended dwell times while Southeast Asian bookings prioritize beach resort concentration and shorter average stays.
United Kingdom
Heritage tourism and theater programming drive repeat visitation from American retirees and cultural enthusiasts. The UK's Electronic Travel Authorization scheme streamlines pre-arrival screening for eligible US passport holders. London Heathrow maintains slot dominance for transatlantic legacy carriers, while Manchester and Edinburgh gateways expand direct service from secondary US cities.
France
Gastronomy-focused itineraries and luxury retail positioning sustain above-average per-capita spending from affluent American couples. The country's national aviation regulator enforces consumer protection standards for flight delays and baggage handling that align with US traveler expectations. Paris Charles de Gaulle concentrates premium cabin demand, with Lyon and Nice capturing regional dispersal from experiential travelers.
Italy
Multi-generational family travel clusters around heritage circuits and agriturismo properties in Tuscany and Umbria. Italy's national tourism board operates targeted visa facilitation programs for US educational group travel. Rome Fiumicino anchors central Mediterranean connectivity, while Florence and Venice benefit from cruise-to-land extensions.
Mexico
Proximity-driven beach resort demand and medical tourism procedures generate the highest volume of US outbound trips by destination country. Mexico's federal consumer protection agency enforces all-inclusive pricing transparency mandates that mirror FTC disclosure requirements. Cancun and Los Cabos concentrate hospitality capacity investment, with Mexico City capturing cultural city-break segments.
Japan
Culinary tourism and seasonal nature observation attract experience-focused Millennial and Gen Z travelers from coastal US metropolitan markets. Japan's National Tourism Organization operates dedicated inbound marketing programs targeting American adventure and solo traveler demographics. Tokyo Narita and Haneda split long-haul capacity, with Osaka Kansai serving as the primary gateway for regional dispersal.
US Outbound Tourism Market Competitive Landscape
Capability concentration sits with specialized tour operators possessing deep destination expertise and curated local partnerships; scale advantage sits with integrated leisure conglomerates controlling vertical distribution from air capacity to ground services. The market structure divides between premium-positioned experiential specialists and volume-driven package holiday platforms. Three archetypes dominate: guided tour operators with repeat-booking retiree bases, adventure-focused small-group format providers, and community tourism partnership specialists. Competitive moves concentrate on direct-to-consumer platform investment and sustainable aviation fuel marketing alliances.
Within the guided tour archetype, Trafalgar and Insight Vacations occupy positions emphasizing European itinerary depth and accessibility-assured programming for older demographics. Intrepid Travel exemplifies the adventure-focused format, competing through small-group structures that dominate under-35 market segments. G Adventures anchors the community tourism partnership model, differentiating supply from mass-market alternatives through local operator integration. These three represent distinct strategic postures rather than overlapping competitive sets.
| Leading Market Players |
|---|
| Trafalgar |
| Exodus Adventure Travels |
| Apple Leisure Group |
| Insight Vacations |
| Explore! |
| Flight Centre Travel Group |
| Intrepid Travel |
| Bamba Travel |
| G Adventures |
| Others |
Value Network & Pricing Analysis
Newark's slot concentration at Liberty International Airport compresses carrier competition and elevates pricing power for legacy network operators serving transatlantic routes, while secondary gateway expansion in Austin and Denver introduces downward pressure on coastal hub premiums.
Pricing Analysis
Long-term offtake contracts between tour operators and hotel chains dominate leisure packaging, with spot-market inventory filling capacity gaps during shoulder seasons. Three-tier pricing structure across premium guided tours, standard package holidays, and economy seat-only bookings reflects differentiation by customization depth and concierge inclusion. Price differentiation hinges on biometric expedited processing add-ons and single-occupancy lodging premiums. Cost compression in economy tiers is intensifying because Online Travel Agencies face FTC-mandated all-in pricing transparency that eliminates drip-pricing flexibility. Corporate accounts demonstrate lowest price sensitivity due to procurement cycle alignment, while solo leisure travelers show highest willingness to pay premium positioning.
Supply Chain Analysis
Extended payment terms from European ground operators to US-based tour wholesalers have become standard, with supply-chain finance facilities bridging working capital gaps during booking-to-departure cycles. Destination service provision concentrates in Mexico, the United Kingdom, and Japan, with hospitality capacity build-out in Cancun and Los Cabos reshaping competitive dynamics. The ecosystem draws from commercial aviation seat inventory, ground transportation networks, and licensed local guide services. Single-source vulnerability persists where regional carriers feed international hubs through limited pilot-staffed routes. Distribution runs through Online Travel Agencies for price-sensitive segments and direct-to-consumer platforms for complex customization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US outbound tourism exhibits cyclical recovery characteristics as millennial and Gen Z leisure travelers restore experience-economy spending patterns following pandemic-era compression, with jet fuel cost volatility representing the dominant cyclical swing factor.
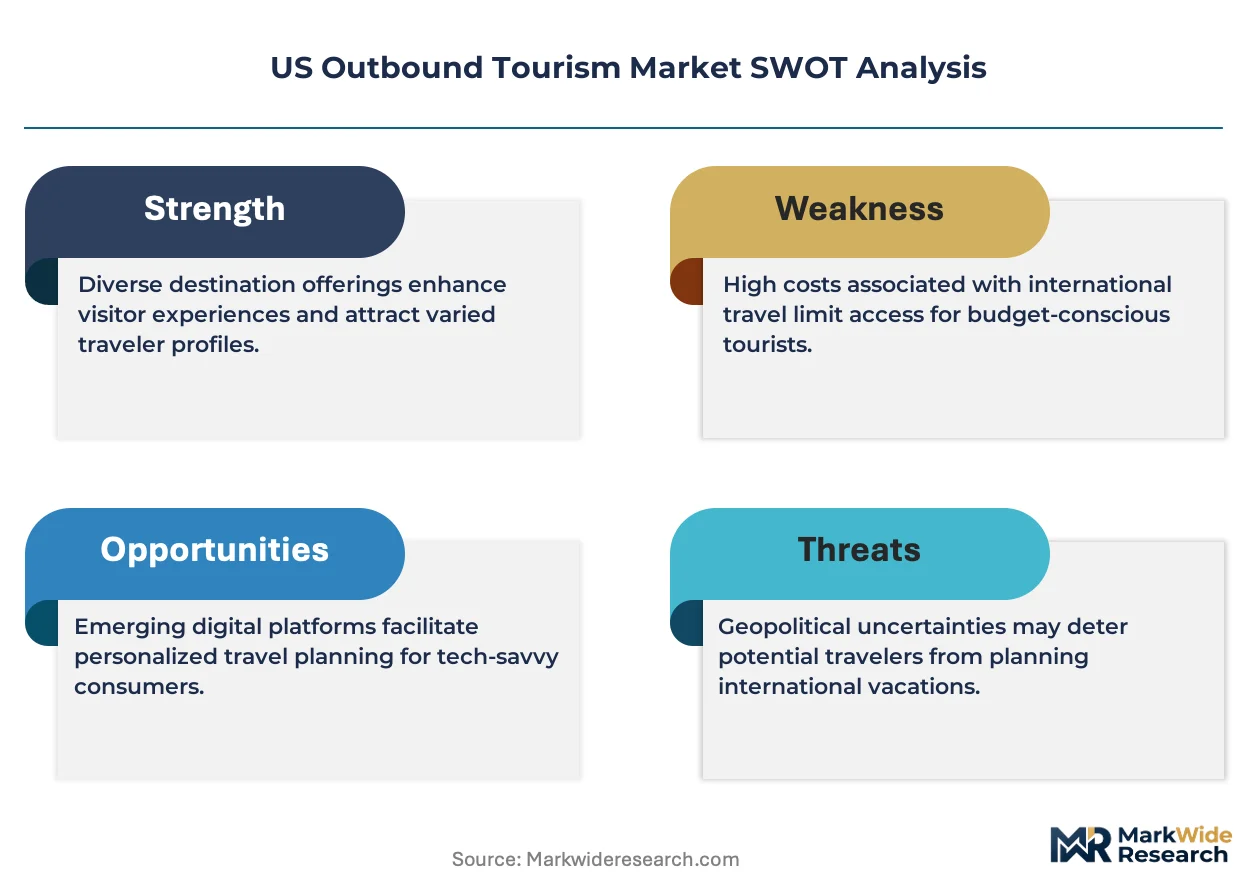
For Market Incumbents: Harden direct booking channel infrastructure against Online Travel Agency margin compression by investing in proprietary mobile applications with biometric-integrated check-in features. Consolidate community tourism partnerships in adventure destinations to defend positioning against Intrepid Travel's small-group format expansion. Vertical integration into single-occupancy lodging supply addresses the fastest-growing solo traveler margin pool.
For New Entrants and Emerging Players: Pursue secondary city gateway origination markets where Austin, Nashville, and Denver international airports expand direct long-haul capacity with less slot-constrained competition. Target the family segment's underserved expansion trajectory with multi-generational heritage circuit programming in Italy and the United Kingdom. A subscription-based annual membership model unlocks pre-committed capital from Generation Z coastal metropolitan buyers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors experiential specialists with curated local partnerships over volume-driven package holiday platforms. Long-term viability over the next decade rests on sustainable aviation fuel marketing alliances and biometric system integration capabilities. The signal to monitor is Inflation Reduction Act SAF production tax credit utilization rates as a carrier differentiation indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Border Integration | TSA Credential Authentication Technology deployment at 80-plus airports forces foreign destination reciprocity. |
| Sustainable Aviation Fuel Marketing | Inflation Reduction Act production tax credits enable lower-carbon itinerary positioning for environmentally conscious travelers. |
| Direct-to-Consumer Platform Investment | Proprietary reservation systems bypass Online Travel Agency margin compression under FTC all-in pricing mandates. |
| Secondary Gateway Capacity Expansion | Austin and Denver long-haul growth reduces dependency on Newark and JFK slot-constrained connections. |
| Solo Traveler Premium Product Development | Single-occupancy accommodations and curated independent experiences capture fastest-growing margin pool. |
Research Methodology
Desk research of carrier capacity filings, destination tourism board statistics, and Online Travel Agency financial disclosures preceded structured interviews with tour operator product directors, airline network planning executives, hospitality revenue managers, and travel agent consortium leaders. Primary fieldwork validated booking channel shift patterns and biometric system deployment timelines. Secondary triangulation incorporated Department of Transportation consumer complaint databases, TSA throughput metrics, and Federal Trade Commission enforcement actions. Bottom-up traveler segmentation analysis and top-down market sizing reconciled through cross-reference checks.
Assumptions regarding Real ID enforcement phasing, sustainable aviation fuel production scaling, and secondary airport infrastructure completion were held fixed across baseline scenarios, with jet fuel price trajectory and visa processing capacity varied in sensitivity testing. The analytical framework modeled traveler spend across leisure, business, education, and medical purposes; demographic profiles spanning families, couples, solo travelers, and seniors; booking channels including Online Travel Agencies, direct booking, travel agents, and mobile apps; and destination types covering international cities, beach resorts, cultural sites, and adventure destinations. CAGRs were derived from segment-level growth rate blending weighted by installed base contribution.
Sensitivities concentrate around geopolitical supply disruptions affecting carrier fuel hedging strategies, extended consular appointment wait times altering spontaneous booking patterns, and biometric system interoperability costs compressing destination operator margins. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
China Online Travel Market
Travel and Tourism
Middle East and Africa Travel Retail Market
Travel and Tourism
Global Duty-Free and Travel Retail Market
Travel and Tourism
Tourism Vehicle Rental Market
Travel and Tourism
Yoga Tourism Market
Travel and Tourism
Global Ecotourism Market
Travel and Tourism
Singapore Travel Retail Market
Travel and Tourism
Travel and Tourism User Generated Content Market
Travel and Tourism
B2B Travel Market
Travel and Tourism
North America Travel Retail Market
Travel and Tourism
LAMEA Pet Travel Services Market
Travel and Tourism
UAE Sustainable Tourism Market
Travel and Tourism
Global Golf Travel Market
Travel and Tourism
Luxury Travel Market
Travel and Tourism
Dark Tourism Market
Travel and Tourism
Latin America Inflight Services Market