
 Skill Gaming Market | 2026-2036
Skill Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Skill Gaming Market Analytics
Cloud-based server infrastructure is broadening access economics for real-time multiplayer skill platforms. Electronic Arts leverages its Frostbite engine pipeline to sustain latency-sensitive competitive environments. NetEase Games anchors live-service operations across Southeast Asian data centers. Riot Games differentiates through proprietary anti-cheat architecture that controls tournament integrity standards.
Skill gaming encompasses digital competitions where player proficiency, rather than chance mechanisms, determines outcomes, typically operating on matchmaking algorithms with sub-50ms latency requirements and server-authoritative validation protocols designed for wagering compliance and ranked progression systems. Fantasy sports and trivia games represent the fastest-expanding game type segments where margin pools concentrate around microtransaction velocity and season-pass renewal rates. Mobile apps dominate platform distribution due to lower customer acquisition costs and higher session frequency compared to console installations.
FCC guidelines on internet service quality and state-level wagering statutes in the US shape permissible prize structures, while India's TRAI data localization mandates and RBI payment processing rules constrain cross-border tournament liquidity flows. GDPR compliance requirements in Europe impose identity verification burdens that raise operational costs for platforms serving minors. Stakeholders must monitor evolving classification disputes between games of skill and games of chance as jurisdictions revise their statutory frameworks.
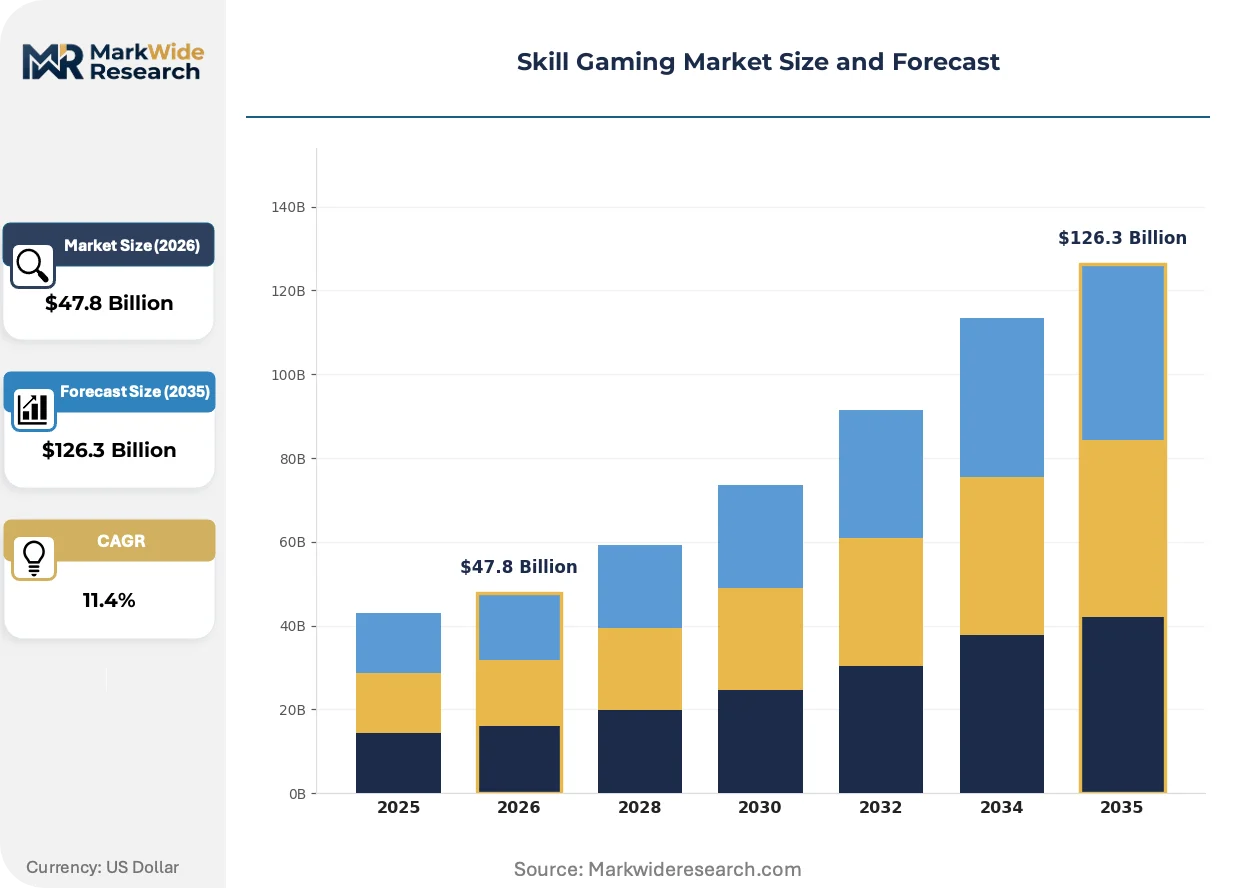
Market Dynamics
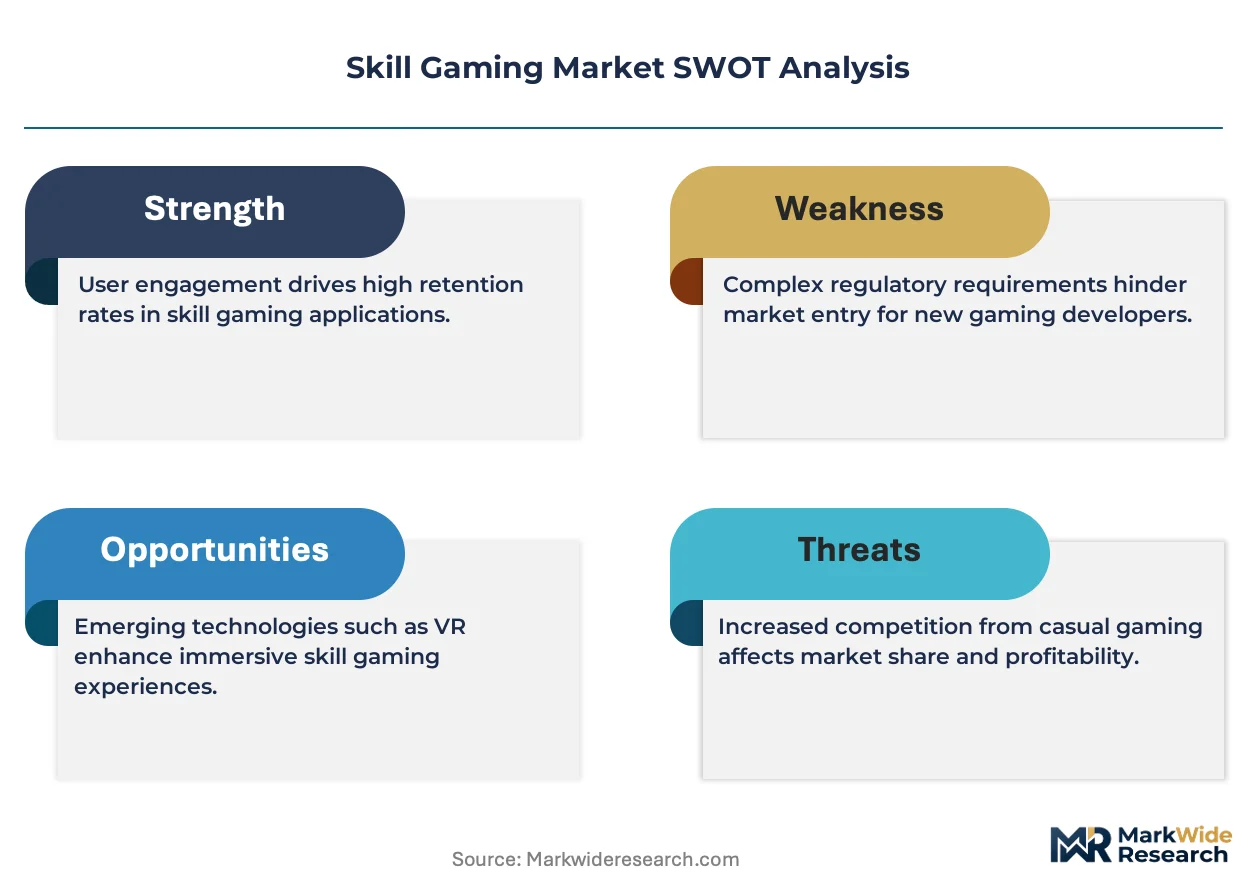
Server-authoritative validation protocols are compressing latency tolerances below 50ms while wagering compliance frameworks multiply across jurisdictions, forcing platforms to rebuild architecture for simultaneous regulatory adherence and competitive integrity.
Growth Catalysts
- India PLI scheme:The production-linked incentive program for digital infrastructure accelerates data center buildouts, reducing operational costs for tournament operators seeking localized server clusters.
- Mobile esports tournaments:Competitive cash-prize formats on smartphones attract player bases with higher session frequency than console equivalents, expanding addressable participant pools.
- Frostbite engine pipelines:Real-time rendering architectures sustain sub-frame latency environments essential for ranked progression systems and wagering-validated outcomes.
Market Restraints
- GDPR identity verification:European compliance mandates impose operational cost burdens on platforms serving minors, constraining cross-border user acquisition strategies.
- RBI payment processing rules:India's central bank regulations limit cross-border tournament liquidity flows, fragmenting prize pool structures for international competitions.
- State-level wagering statutes:US jurisdictional fragmentation creates prize structure uncertainty, requiring platform-by-platform legal architecture rather than unified national deployment.
Strategic Opportunities
- Southeast Asian data centers:NetEase Games anchors live-service operations across regional server clusters, demonstrating scalable infrastructure templates for latency-sensitive competitive environments.
- Fantasy sports microtransaction velocity:Season-pass renewal rate optimization in trivia and fantasy formats creates recurring revenue pools distinct from one-time tournament entry fees.
- Proprietary anti-cheat architecture:Tournament integrity standards controlled through in-house validation systems differentiate platform trustworthiness for wagering participants.
Industry Challenges
- Skill-chance classification disputes:Jurisdictions revising statutory frameworks create legal uncertainty requiring continuous compliance monitoring and platform reclassification.
- TRAI data localization mandates:India's telecom regulator requirements constrain architecture flexibility, mandating domestic server placement that complicates global tournament liquidity management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skill Gaming Market |
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $126.3 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Card Games, Board Games, Trivia Games, Fantasy Sports Platform: Mobile Apps, PC Games, Online Platforms, Consoles Player Type: Casual Players, Competitive Players, Professional Gamers, Social Players Monetization Model: Freemium, Subscription, In-App Purchases, Ad Revenue |
| Companies Covered | Nexon, Take-Two Interactive, Riot Games, 37Games, Roblox Corporation, Electronic Arts, NetEase Games, Garena, Epic Games, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skill Gaming Market Evolving Landscape
Cloud-based server infrastructure is compressing access economics for real-time multiplayer platforms while regulatory fragmentation forces architectural redesign around jurisdiction-specific compliance modules.
Edge computing nodes are consolidating latency-sensitive competitive environments by distributing server authority closer to player populations. Mobile-first tournament operators deploy these architectures most aggressively across Southeast Asian metropolitan clusters. The structural result is consolidating platform economics around geographic server density rather than centralized cloud regions.
FCC guidelines on internet service quality are reshaping permissible prize structures by establishing baseline connectivity standards for wagering-validated competitions. US state regulators reference these federal benchmarks when adjudicating skill-game classifications. Fantasy sports operators respond by segmenting product tiers based on verified connection quality thresholds.
Session frequency patterns among mobile app users are displacing console-centric competitive formats as the dominant engagement model. Lower customer acquisition costs on smartphone distribution channels redirect platform investment toward in-app progression systems. India and Brazil exhibit the most pronounced behavioral shift toward microtransaction-driven seasonal engagement over discrete tournament entry.
Skill Gaming Market Segmentation
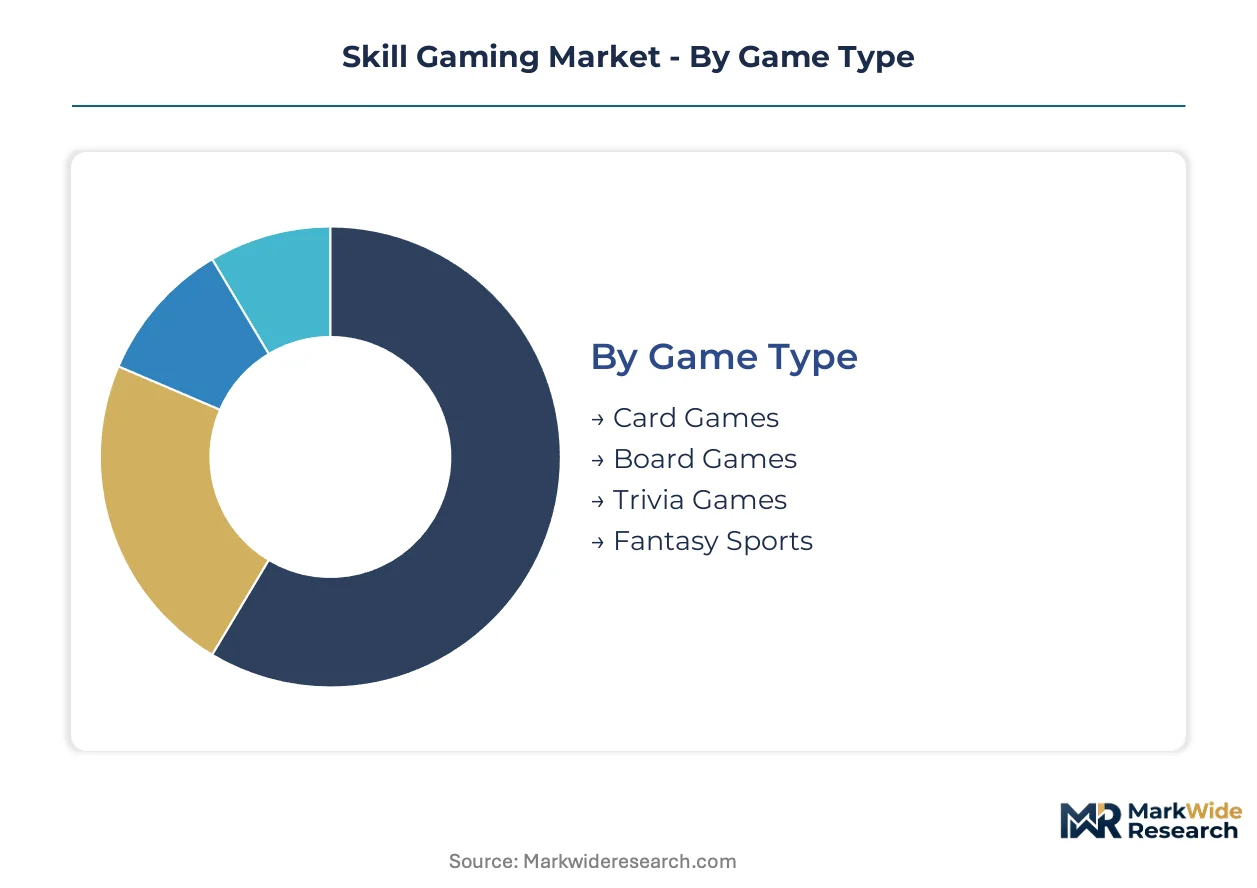
Skill gaming platforms architect their infrastructure, compliance frameworks, and revenue models around distinct segment boundaries. Each axis—game mechanics, access technology, player motivation, and payment structure—imposes specific latency, regulatory, and monetization requirements that shape platform economics.
Game Type:
Technical complexity and wagering validation protocols vary sharply across competitive formats, with server-authoritative architectures calibrated to specific outcome-determination mechanisms.
- Fantasy Sports:Season-long roster management systems require real-time statistical aggregation from multiple live data feeds. Demand concentrates in the United States where state-level wagering statutes permit prize pools tied to athletic performance metrics, though regulatory fragmentation forces platform-by-platform compliance architecture.
- Card Games:Deterministic rule engines with zero-sum scoring depend on cryptographically secure shuffle algorithms and sub-50ms latency validation. Competitive player bases in India and Southeast Asia drive tournament liquidity, constrained by RBI payment processing rules that fragment cross-border prize structures.
- Board Games:Turn-based asynchronous formats tolerate higher latency thresholds than real-time alternatives. Social player segments sustain session frequency through mobile app distribution.
- Trivia Games:Synchronous question-response cycles demand sub-second consensus mechanisms across distributed player pools. Microtransaction velocity around season-pass renewals creates recurring revenue pools distinct from entry fees.
Mature deployment sits with Card Games. Newer deployment is concentrated in Fantasy Sports.
Platform:
Access economics diverge sharply across hardware categories, with customer acquisition costs and session frequency patterns dictating platform investment priorities.
- Mobile Apps:Lower customer acquisition costs and higher session frequency redirect platform investment toward in-app progression systems. India and Brazil exhibit pronounced behavioral shift toward microtransaction-driven seasonal engagement over discrete tournament entry.
- PC Games:Frostbite engine pipelines and comparable rendering architectures sustain sub-frame latency environments essential for ranked progression. Competitive integrity standards require proprietary anti-cheat validation systems.
- Online Platforms:Browser-based access broadens participant pools but introduces connectivity variability that complicates wagering compliance. FCC guidelines on internet service quality reshape permissible prize structures through baseline connectivity benchmarks.
- Consoles:Higher per-user revenue offsets elevated acquisition costs through premium tournament entry tiers. Console installations lag smartphone equivalents in session frequency metrics.
Volume leadership belongs to Mobile Apps. Margin concentration favors PC Games.
Player Type:
Engagement depth and monetization elasticity segment the addressable population across four distinct behavioral profiles with divergent lifetime value trajectories.
- Competitive Players:Cash-prize tournament participation demands verified identity protocols and wagering-compliant infrastructure. GDPR identity verification requirements in Europe impose operational cost burdens on platforms serving minors within this segment.
- Professional Gamers:Full-time competitive activity requires guaranteed prize structures and anti-cheat architecture meeting tournament integrity standards. TRAI data localization mandates in India constrain global tournament liquidity management for this cohort.
- Casual Players:Lower-stakes engagement patterns favor freemium monetization with intermittent in-app purchase conversion. Session frequency exceeds duration per session.
- Social Players:Network-driven participation prioritizes multiplayer matchmaking over individual skill ranking. Viral acquisition mechanics reduce platform marketing expenditure.
Revenue per user peaks with Professional Gamers. User acquisition efficiency concentrates with Social Players.
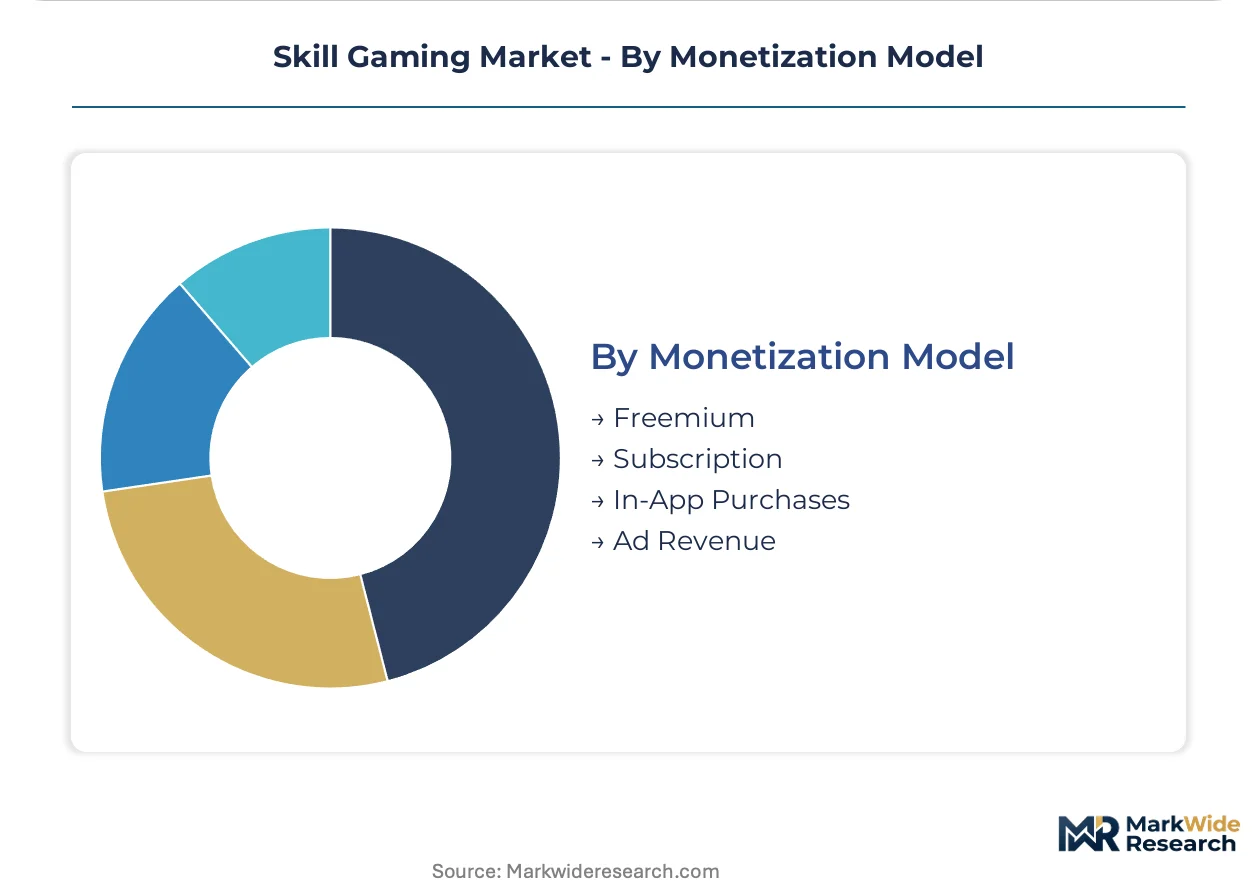
Monetization Model:
Payment structure selection directly determines recurring revenue predictability and regulatory exposure across jurisdictions with divergent wagering classifications.
- In-App Purchases:Microtransaction velocity around cosmetic items, power-ups, and progression accelerators generates highest-margin revenue pools. Season-pass renewal rate optimization in trivia and fantasy formats creates recurring revenue distinct from one-time tournament entry.
- Freemium:Tiered access gates convert free users through demonstrated skill progression rather than upfront payment. Conversion rates vary sharply by game type and geography.
- Subscription:Predictable recurring revenue supports infrastructure investment in server-authoritative validation protocols. State-level wagering statutes in the US create prize structure uncertainty that subscription models partially mitigate.
- Ad Revenue:Lower per-user yield requires mass-scale participation pools sustained through low-friction mobile app distribution. FCC guidelines indirectly affect ad-supported formats through connectivity quality benchmarks.
Margin stability favors Subscription. Expansion velocity clusters with In-App Purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Southeast Asia and India's software technology parks of India (STPI) scheme are concentrating server infrastructure investment and platform development. These zones offer tax holidays and simplified regulatory pathways that reduce operational costs for tournament operators. The geographic distribution of skill gaming demand follows data center density and mobile penetration rates rather than traditional gaming hardware markets.
United States
Fantasy sports platforms generate concentrated revenue pools through season-pass renewal models tied to professional athletic leagues. State-level wagering statutes fragment prize structure permissibility, forcing operators to maintain jurisdiction-specific compliance architectures. Dallas and Austin anchor server clusters for real-time statistical aggregation serving North American tournament pools.
India
Mobile-first card game tournaments attract competitive player bases seeking cash prizes through smartphone distribution channels. The RBI payment processing rules constrain cross-border liquidity flows, fragmenting international prize pool structures. Bangalore and Hyderabad data centers under the PLI scheme for digital infrastructure reduce latency for domestic tournament validation.
China
Live-service operations sustain player engagement through microtransaction velocity around seasonal content cycles. MIIT cybersecurity reviews and content approval processes extend platform launch timelines. Shanghai and Shenzhen anchor regional server clusters for latency-sensitive competitive environments across Southeast Asian markets.
South Korea
PC bang culture sustains high-frequency competitive gaming sessions with verified identity protocols for ranked progression systems. The Game Rating and Administration Committee (GRAC) classification requirements shape permissible wagering structures. Seoul Capital Area concentrates professional gamer training facilities and tournament broadcast infrastructure.
Brazil
Mobile app distribution channels exhibit pronounced behavioral shifts toward microtransaction-driven engagement over discrete tournament entry. ANVISA data protection frameworks impose identity verification burdens on platforms serving minor demographics. São Paulo anchors Portuguese-language server infrastructure for Latin American competitive pools.
Skill Gaming Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with proprietary engine developers commanding premium positioning in latency-sensitive competitive environments. The vendor base organizes around three strategic archetypes: integrated platform operators owning full technology stacks, specialized tournament infrastructure providers, and mobile-first distribution platforms. Consolidation pressures concentrate among mid-scale operators lacking proprietary server-authoritative validation protocols. Dominant competitive moves include geographic expansion through localized data center partnerships and portfolio diversification into adjacent fantasy sports formats.
Within the integrated platform tier, Electronic Arts and NetEase Games exemplify divergent regional strategies. Electronic Arts leverages its Frostbite engine pipeline to sustain sub-frame latency environments essential for wagering-validated outcomes. NetEase Games anchors live-service operations across Southeast Asian data centers, demonstrating scalable infrastructure templates for emerging market penetration. Riot Games occupies a distinct position through proprietary anti-cheat architecture that controls tournament integrity standards, differentiating platform trustworthiness for competitive player segments.
| Leading Market Players |
|---|
| Nexon |
| Take-Two Interactive |
| Riot Games |
| 37Games |
| Roblox Corporation |
| Electronic Arts |
| NetEase Games |
| Garena |
| Epic Games |
| Others |
Value Network & Pricing Analysis
Sovereign-backed data center operators and private-equity-rolled-up cloud infrastructure specialists concentrate server capacity ownership across India and Southeast Asia, translating localized compute scarcity into pricing discipline for tournament operators while forcing platform economics toward geographic server density rather than centralized cloud arbitrage.
Pricing Analysis
Premium pricing attaches to sub-50ms latency guarantees with sub-frame validation, while spot inventory of excess server capacity in tier-two Indian metros trades at meaningful discounts. Three-tier pricing structure across premium, standard, and economy levels separates wagering-compliant tournament tiers from casual matchmaking pools. Cost compression in the standard tier intensifies because RBI payment processing rules fragment prize pool liquidity and force redundant infrastructure builds. Casual player segments exhibit highest price sensitivity, while professional gamer cohorts absorb premium tiers for guaranteed integrity standards.
Supply Chain Analysis
Regional distribution centers in Bangalore, Hyderabad, and Singapore anchor hub-and-spoke patterns for latency-sensitive competitive environments, with edge nodes proliferating across Southeast Asian metropolitan clusters. Server hardware concentrates in Taiwan, South Korea, and China, while specialized anti-cheat software modules source from US and European development centers. Single-source vulnerability sits with NVIDIA GPU allocations for real-time rendering pipelines. Distribution runs through hyperscaler partnerships and direct-to-operator colocation agreements rather than traditional IT channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Server-authoritative validation capacity functions as the binding constraint propping pricing power, with data center buildout timelines under India's PLI scheme running 18-24 months behind tournament operator demand curves.
For Market Incumbents: Anchor proprietary anti-cheat architecture as the defensive moat against emerging mobile-first entrants with borrowed infrastructure. Consolidate through targeted acquisition of regional tournament operators lacking server-authoritative validation protocols. Vertical integration into edge computing node deployment in Brazil and Southeast Asia protects margin structure from hyperscaler pricing volatility. For New Entrants and Emerging Players: Mobile app distribution channels in Brazil and India offer the most penetrable white-space, with ANVISA and RBI compliance frameworks creating incumbent blind spots for agile specialists. Freemium conversion mechanics in trivia and board game formats bypass wagering classification complexity. Go-to-market through social player network effects reduces customer acquisition cost burdens versus competitive cash-prize positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale tournament operators with existing data center leases in India and Southeast Asia but lacking proprietary engine pipelines. Five-to-ten year viability hinges on wagering compliance architecture rather than content IP. The signal to watch is FCC guideline evolution on connectivity quality benchmarks, which would reclassify permissible prize structures and reshape platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Node Expansion | NetEase Games demonstrates scalable templates for latency-sensitive competitive environments across Southeast Asian metropolitan clusters. |
| Proprietary Anti-Cheat Development | Riot Games validates that in-house tournament integrity systems differentiate platform trustworthiness for wagering participants. |
| Fantasy Sports Format Diversification | Season-pass renewal rate optimization in US-focused platforms creates recurring revenue pools distinct from entry-fee volatility. |
| Localized Data Center Partnerships | India's PLI scheme for digital infrastructure reduces operational costs for domestic tournament validation and compliance. |
| Mobile-First Platform Integration | Electronic Arts leverages Frostbite engine pipelines to sustain sub-frame latency environments essential for ranked progression systems. |
Research Methodology
Independent corroboration across platform engineering executives, tournament operations directors, regulatory compliance officers, and cloud infrastructure procurement leads underwrites the qualitative findings. Primary fieldwork combined with secondary validation from TRAI spectrum allocation records, RBI payment system circulars, FCC broadband deployment reports, and hyperscaler data center capex disclosures. Bottom-up segmentation modeling triangulates against top-down market sizing from disclosed tournament prize pools and platform operator filings.
Rate-of-change decomposition separates volume expansion from pricing evolution across the analysis window, with segmentation dimensions spanning game type, platform access technology, player motivation archetype, and monetization model. CAGRs derive from curve-fitting against historical tournament participation growth and server infrastructure deployment trajectories. Fantasy sports regulatory fragmentation and mobile esports session frequency patterns function as primary forecast inputs.
The model holds under stable wagering classification regimes; deviation in skill-chance statutory reinterpretations or data localization mandate expansions would shift addressable market boundaries. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness
Hunting Rangefinder Market
Sports & Fitness
Rowing Boats Market
Sports & Fitness
Yoga and Exercise Mats Market
Sports & Fitness
Carbon Fiber Badminton Racket Market
Sports & Fitness
Volleyball Equipment Market
Sports & Fitness
France Sports Teams and Clubs Market
Sports & Fitness
Football Equipment Market
Sports & Fitness
Player Tracking System Market
Sports & Fitness
Global Smart Wearable Fitness and Sports Devices Market
Sports & Fitness
Arginine Supplement Market
Sports & Fitness
Global Sports Management Software Market
Sports & Fitness
Europe Protein Based Sports Drinks Market
Sports & Fitness
Creatine Market
Sports & Fitness
Wetsuits Market
Sports & Fitness
North America Personal Watercraft Market
Sports & Fitness
Cross Training Shoes Market