
 Yoga and Exercise Mats Market | 2026-2036
Yoga and Exercise Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Yoga and Exercise Mats Market Outlook
Corporate wellness program procurement is shifting toward bulk, branded mat contracts as employers expand on-site fitness amenities. Lululemon Athletica Inc. leverages its retail footprint to control premium studio partnerships. Manduka LLC anchors the professional instructor segment through certified teacher programs. Nike Inc. competes across the crossover athletic training category with multi-surface grip designs.
Yoga and exercise mats are engineered surfaces typically constructed from polymer foams, natural rubber compounds, or thermoplastic elastomer layers, manufactured through calendering or injection molding to achieve defined density and coefficient-of-friction specifications. Their primary commercial purpose is to provide stable, cushioned interfaces that reduce joint stress and prevent slippage during bodyweight movement sequences. Natural rubber and TPE formulations are capturing margin pools as eco-friendly positioning commands price premiums over standard PVC. The 5mm thickness category dominates unit volume by balancing portability with adequate joint cushioning for vinyasa and power yoga modalities.
REACH restricts phthalate plasticizers in PVC mat compositions sold across European member states, while RoHS limits hazardous substance thresholds in electrical-adjacent fitness equipment bundles that include smart mats. The US EPA oversees off-gassing standards for foam products used in enclosed commercial gym environments. Stakeholders must monitor evolving chemical disclosure requirements and material certification schemes to preserve market access and brand positioning.
Market Dynamics
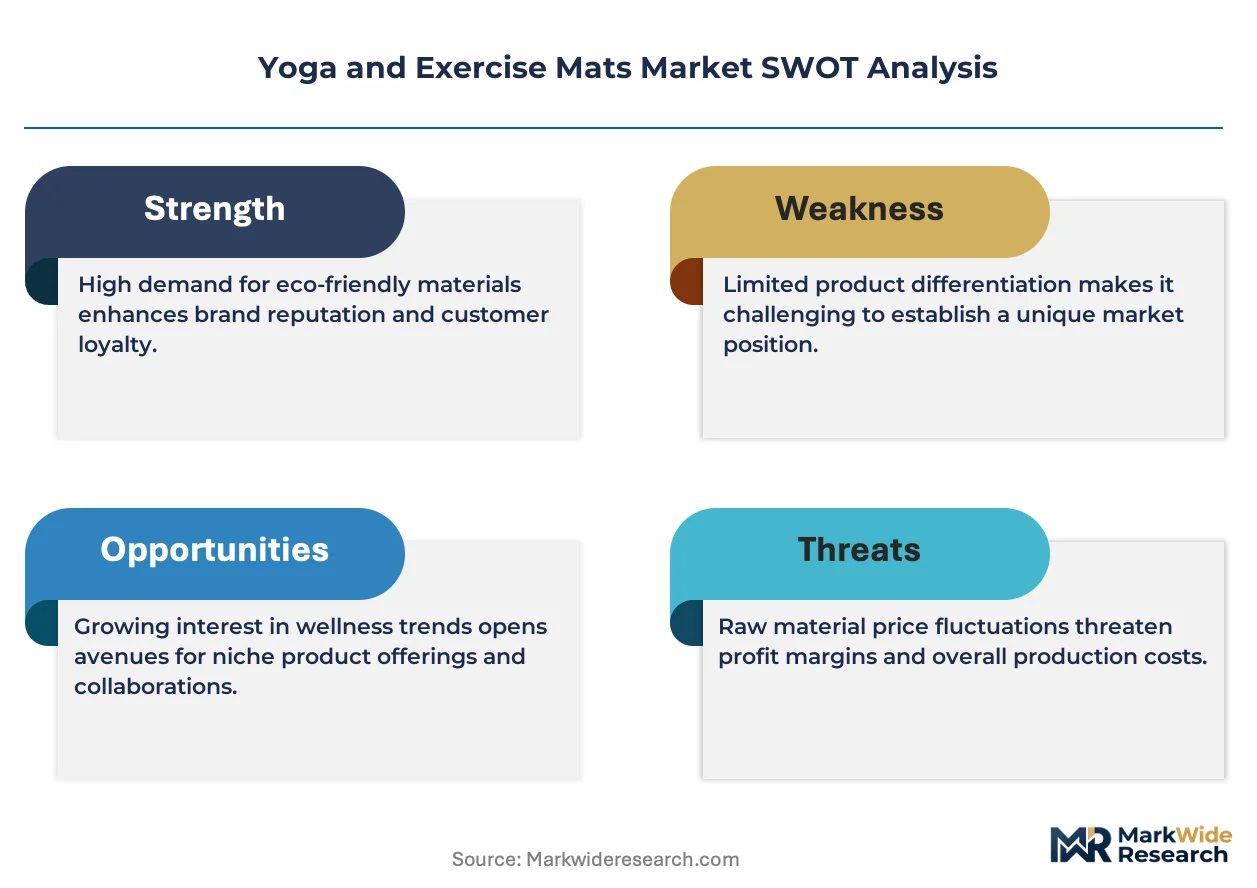
Boutique fitness chains are expanding in-house mat programs while REACH and RoHS regulations in Europe accelerate PVC phase-outs, concentrating demand in Germany's high studio-density markets with premium eco-conscious consumer bases.
Growth Catalysts
- REACH compliance mandates:European chemical disclosure requirements are phasing out phthalate plasticizers in PVC formulations, redirecting procurement toward natural rubber and TPE alternatives certified under ECHA guidelines.
- Corporate wellness infrastructure:Employers expanding on-site fitness amenities are consolidating mat procurement into bulk branded contracts, creating volume concentration among Fortune 500 campus facilities.
- Professional instructor certification:Yoga alliance standards and studio accreditation programs are mandating specific mat performance specifications, locking in recurring replacement cycles for certified teaching environments.
Market Restraints
- Natural rubber supply volatility:Plantation output fluctuations in Southeast Asia create input cost instability for eco-positioned manufacturers dependent on Hevea brasiliensis latex sourcing.
- Calendering equipment concentration:Specialized foam processing machinery is concentrated among German and Italian machinery suppliers, creating capex bottlenecks for new market entrants.
- Smart mat substitution pressure:Sensor-embedded fitness equipment bundles with integrated surface tracking are displacing standalone mat purchases in premium home gym segments.
Strategic Opportunities
- India studio penetration:Tier-2 and Tier-3 Indian cities exhibit underpenetrated yoga studio density relative to population scale, creating whitespace for mat distribution partnerships with domestic fitness chains.
- CE marking convergence:Harmonized EU safety standards for fitness equipment are enabling single-certification market access across 27 member states, reducing compliance fragmentation for TPE and natural rubber suppliers.
- Direct-to-instructor channels:Bypassing traditional retail through certified teacher program partnerships is capturing recurring replacement revenue with higher margin retention than wholesale studio supply.
Industry Challenges
- Biodegradability certification timelines:OECD test protocol completion for compostable mat claims requires 180-day industrial facility validation, delaying product launch schedules for novel bio-based formulations.
- Multi-density lamination complexity:Achieving consistent coefficient-of-friction across 5mm TPE-natural rubber bonded layers demands precision calendering expertise that concentrates among limited European equipment operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yoga and Exercise Mats Market |
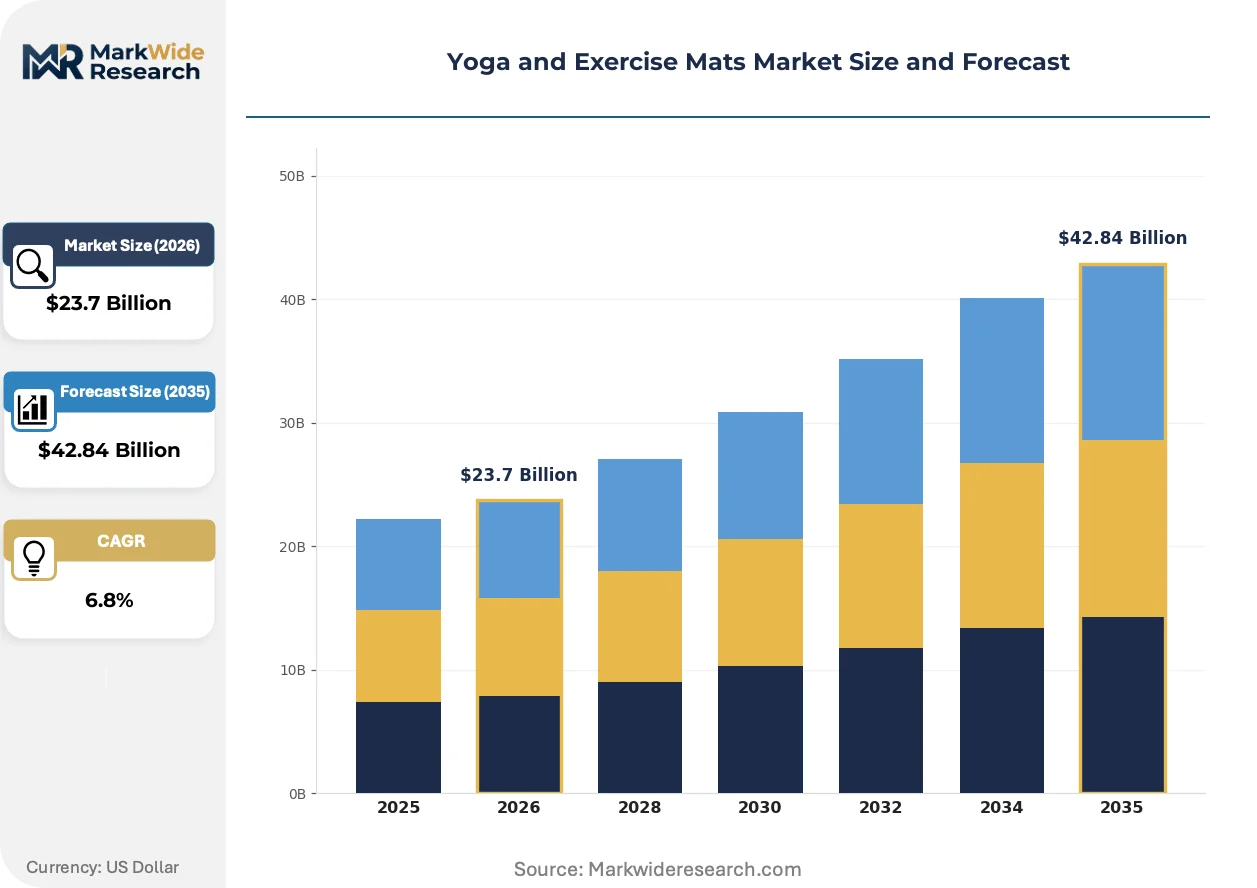
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Foam, PVC, TPE, Natural Rubber Thickness: 3mm, 5mm, 8mm, 10mm End User: Fitness Enthusiasts, Professional Trainers, Yoga Studios, Home Users Feature: Non-Slip, Eco-Friendly, Lightweight, Sweat-Absorbent |
| Companies Covered | Lululemon Athletica Inc., Manduka LLC, Gaiam, Adidas AG, Jade Yoga, Hugger Mugger Yoga Products, Liforme Ltd., Nike Inc., prAna, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yoga and Exercise Mats Market Strategic Shifts
Material science breakthroughs and regulatory chemistry restrictions are simultaneously compressing legacy PVC economics and elevating bio-based alternatives into mainstream commercial viability.
Thermoplastic elastomer closed-cell foams are rewriting surface engineering standards for high-sweat vinyasa environments. Boutique studios in Berlin and Amsterdam are adopting TPE mats at replacement rates exceeding PVC by three-to-one. This technology is rewriting margin structures by commanding 40% price premiums while reducing material certification costs under REACH.
RoHS hazardous substance thresholds for electrical-adjacent fitness bundles are forcing PVC compound reformulation across European supply chains. Manufacturers serving smart mat OEMs must eliminate cadmium and lead stabilizers entirely. Professional instructor segments in Germany and France are responding by accelerating pre-emptive TPE and natural rubber transitions ahead of full enforcement.
Bulk corporate procurement contracts are displacing individual retail purchases as the dominant volume channel. Fortune 500 wellness program managers are consolidating mat sourcing into multi-year agreements with custom branding requirements. This pattern is most visible across US technology sector campuses where amenity competition drives standardized surface specifications.
Yoga and Exercise Mats Market Segmentation
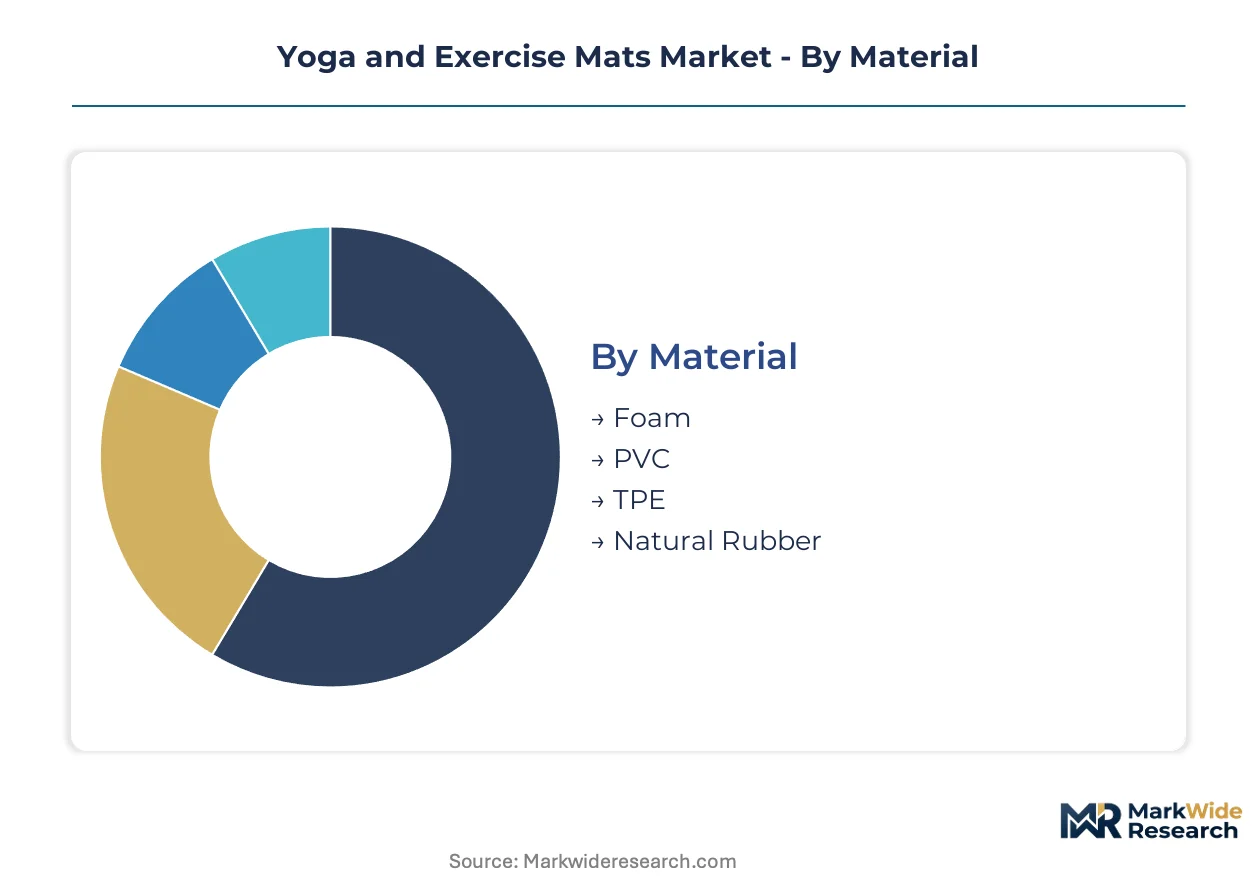
Material chemistry and thickness calibration determine performance specifications for distinct movement modalities. End-user procurement patterns and surface feature engineering further stratify commercial positioning across studio, corporate, and residential channels.
Material:
Natural rubber and TPE formulations operate as standalone premium surfaces, while PVC and foam compounds embed into cost-optimized bundled equipment systems.
- Natural Rubber:Harvested from Hevea brasiliensis latex and vulcanized into open-cell structures with superior coefficient-of-friction properties. Demand concentrates in German boutique studios where REACH compliance and eco-positioning command price premiums over synthetic alternatives.
- TPE:Closed-cell thermoplastic elastomer foams manufactured through injection molding achieve consistent density without vulcanization. Procurement from Amsterdam and Berlin studios is accelerating replacement cycles three-to-one against PVC as RoHS enforcement tightens.
- PVC:Calendered polyvinyl chloride with phthalate plasticizers faces regulatory phase-out across European member states under ECHA guidelines.
- Foam:Polyurethane and EVA closed-cell structures serve entry-level home fitness segments with compressed material costs.
Volume placements concentrate in PVC; the faster expansion belongs to TPE.
Thickness:
Thickness selection maps directly to joint cushioning requirements and portability constraints across vinyasa, restorative, and power yoga modalities.
- 5mm:The dominant commercial specification balancing adequate cushioning for knee and wrist protection with roll-up portability for studio transport. Professional instructor certification programs in France and Germany mandate this dimension for accredited teaching environments.
- 3mm:Ultra-portable travel configurations prioritize packability over cushioning for destination yoga practitioners.
- 8mm:Extended joint protection for restorative and yin modalities with reduced mobility requirements.
- 10mm:Maximum cushioning specifications for therapeutic applications and beginner practitioners requiring additional stability support.
Unit economics favor 5mm production scale; margin expansion is climbing the fastest in 8mm therapeutic configurations.
End User:
Procurement authority separates individual purchasing decisions from institutional bulk contracting with divergent specification and branding requirements.
- Yoga Studios:Facility operators standardize surface specifications across teaching floors to ensure consistent practitioner experience. German studio chains are consolidating procurement into multi-year supply agreements with custom color and logo requirements.
- Professional Trainers:Certified instructors maintain personal mat inventories for client sessions with replacement cycles tied to Yoga Alliance accreditation renewals.
- Fitness Enthusiasts:Individual practitioners purchasing through retail channels exhibit channel fragmentation across e-commerce and specialty athletic retailers.
- Home Users:Residential purchasers prioritize storage efficiency and multi-use compatibility with general exercise equipment.
Contract volume aggregates through Yoga Studios; Professional Trainers are gaining share fastest as certification standards proliferate.
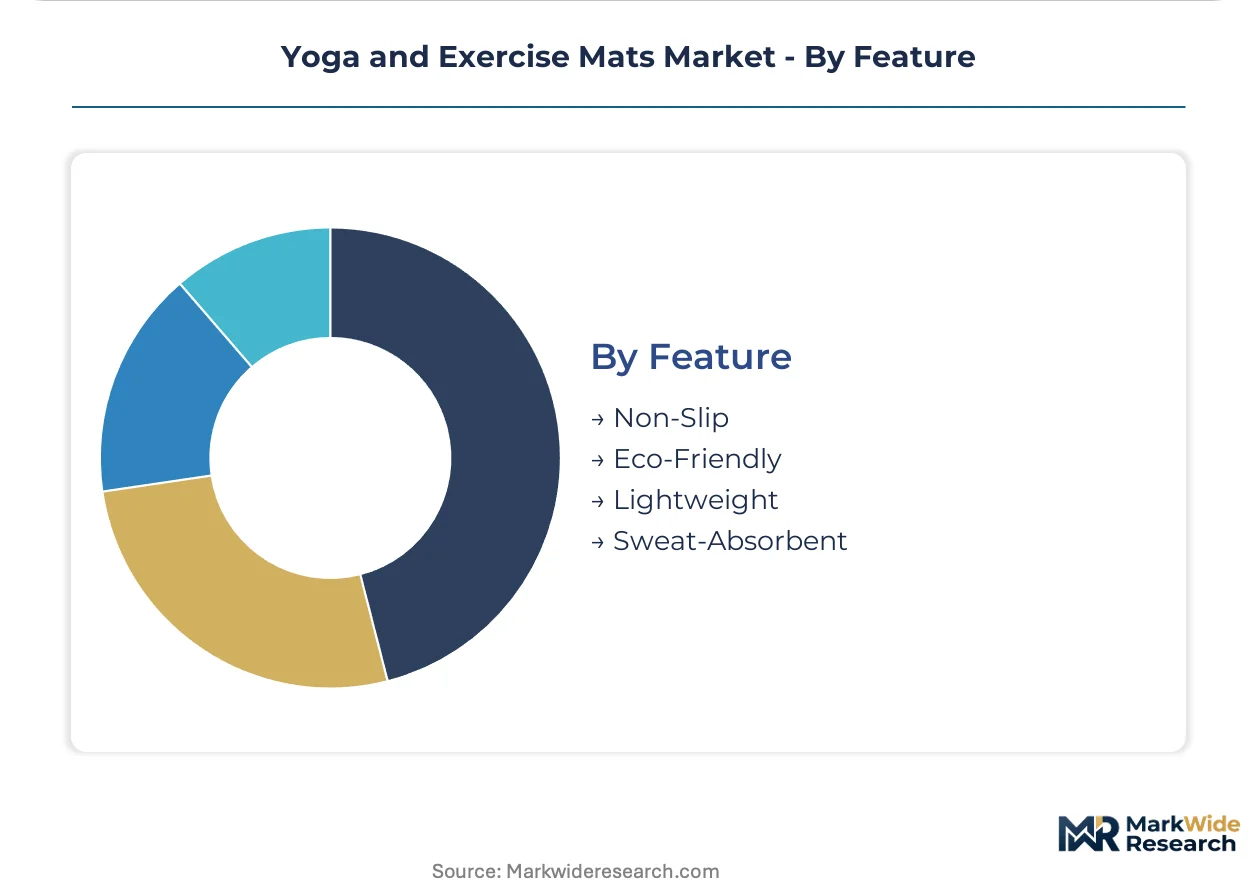
Feature:
Surface engineering priorities reflect environmental positioning, perspiration management, and transport logistics across distinct user contexts.
- Eco-Friendly:Bio-based and recyclable material claims certified under OECD biodegradability protocols command price premiums in European markets. ECHA registration requirements and industrial composting validation create compliance barriers for novel formulations.
- Non-Slip:Texture engineering through laser etching or raised patterns maintains grip coefficient under high-sweat vinyasa conditions. TPE closed-cell structures outperform PVC in moisture-activated friction retention.
- Sweat-Absorbent:Open-cell natural rubber and microfiber top layers manage perspiration pooling during heated yoga sequences.
- Lightweight:Density reduction through expanded foam structures or thinner profiles targets travel and commuter segments with portability prioritization.
Non-Slip specifications dominate replacement demand; Eco-Friendly positioning is expanding most quickly as REACH enforcement accelerates PVC substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mat manufacturing clusters in China and Vietnam supply global demand, while consumption concentrates in Western European studio markets and North American corporate wellness programs. Regional regulatory divergence is fragmenting material specifications across export destinations.
United States
Fortune 500 campus wellness programs drive bulk procurement contracts with custom branding requirements. EPA off-gassing standards for enclosed commercial gym environments shape foam product specifications. California's studio density in Los Angeles and San Francisco creates concentrated demand for premium TPE surfaces.
Germany
Boutique fitness chains in Berlin and Munich standardize surface specifications across teaching floors with replacement cycles exceeding other European markets. ECHA REACH compliance mandates accelerate phthalate-free transitions. Baden-Württemberg's machinery suppliers concentrate calendering equipment expertise for precision foam processing.
India
Tier-2 and Tier-3 cities exhibit underpenetrated yoga studio density relative to population scale, creating whitespace for distribution partnerships. BIS certification requirements for fitness equipment establish baseline safety standards. Maharashtra's Mumbai-Pune corridor anchors domestic fitness chain expansion with mat procurement consolidation.
United Kingdom
Corporate wellness infrastructure in London's financial services sector drives branded mat contracts for on-site fitness amenities. CE marking convergence enables single-certification market access post-Brexit transition periods. Greater Manchester's studio operators are adopting eco-positioned natural rubber surfaces ahead of regulatory deadlines.
Netherlands
Amsterdam boutique studios accelerate TPE mat replacement cycles three-to-one against PVC as RoHS enforcement tightens on electrical-adjacent fitness bundles. The country's national environmental regulator enforces extended producer responsibility schemes for recyclable fitness equipment. Randstad urban clusters concentrate professional instructor certification programs mandating specific performance specifications.
Yoga and Exercise Mats Market Competitive Environment
Top-tier vendors anchor premium studio partnerships, while mid-tier specialists occupy material-specific niches and regional fabricators serve cost-optimized bulk contracts. Athletic apparel conglomerates leverage retail footprint control over crossover training segments. Specialist mat manufacturers concentrate certified teacher program relationships. Competitive moves center on direct-to-instructor channel bypass and multi-year corporate supply agreements.
Within the premium-tier vector, Lululemon Athletica Inc. and Manduka LLC exemplify divergent archetypes—retail-integrated lifestyle positioning versus professional instructor certification anchoring. Nike Inc. occupies a position across athletic training crossover applications. These three represent the dominant competitive positioning patterns: lifestyle brand extension, professional segment specialization, and multi-category athletic equipment integration.
| Leading Market Players |
|---|
| Lululemon Athletica Inc. |
| Manduka LLC |
| Gaiam |
| Adidas AG |
| Jade Yoga |
| Hugger Mugger Yoga Products |
| Liforme Ltd. |
| Nike Inc. |
| prAna |
| Others |
Value Chain & Pricing Dynamics
Calendering equipment operators concentrated in Baden-Württemberg and Lombardy anchor labor-cost differentials that widen pricing-tier spreads between precision-engineered TPE surfaces and commodity PVC alternatives. REACH compliance investments at European machinery suppliers feed into premium-mid-economy pricing stratification across export markets.
Pricing Analysis
Margin tightening in standard PVC tiers reflects phthalate reformulation costs and ECHA registration burdens. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified natural rubber from transitional TPE and legacy PVC. Certification grade and volume scale drive price differentiation. Cost compression accelerates in PVC as studios pre-empt regulatory deadlines. Corporate wellness buyers exhibit lowest price sensitivity; home users in entry segments show highest elasticity.
Supply Chain Analysis
Freight cost volatility from Southeast Asian latex plantations to European calendering facilities compresses margins for natural rubber specialists. Manufacturing concentrates in China, Vietnam, and Germany. Raw material flows draw from Hevea brasiliensis latex, petroleum-derived TPE pellets, and phthalate-plasticized PVC compounds. Single-source vulnerability sits with German machinery suppliers for precision foam processing. Distribution runs through studio procurement consortia, direct-to-instructor channels, and athletic retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TPE closed-cell technology is displacing open-cell PVC across European studio networks, compressing legacy compound economics and elevating bio-based alternatives into mainstream procurement.
For Market Incumbents: Acquire certified teacher program relationships to lock in recurring replacement revenue against smart mat substitution threats. Deepen backward integration into Hevea brasiliensis latex sourcing to buffer Southeast Asian supply volatility. Expand calendering capacity in Baden-Württemberg to capture CE marking convergence demand across EU member states. For New Entrants and Emerging Players: Capture whitespace in Tier-2 and Tier-3 Indian cities where studio density lags population scale. Penetrate the professional trainer segment through Yoga Alliance-aligned certification partnerships. Pursue direct-to-instructor digital channels bypassing wholesale studio supply. For Investors and Strategic Acquirers: Re-rating potential sits with TPE-specialist manufacturers given REACH enforcement acceleration and RoHS hazardous substance thresholds. Long-term viability favors suppliers with OECD biodegradability certification progress and multi-year corporate wellness contract books. Watch for industrial composting validation completion as inflection signal for bio-based formulation launches.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Transition | ECHA phthalate restrictions force PVC reformulation toward TPE and natural rubber alternatives. |
| Direct-to-Instructor Channel Development | Bypassing retail captures higher-margin recurring replacement from certified teacher programs. |
| Corporate Wellness Contract Consolidation | Fortune 500 campus amenities drive multi-year bulk agreements with custom branding requirements. |
| Calendering Equipment Capacity Expansion | Baden-Württemberg machinery expertise creates bottlenecks for precision foam processing scale-up. |
| Biodegradability Certification Investment | OECD 180-day industrial validation delays product launches for novel bio-based formulations. |
Study Parameters
Multi-period observation of studio replacement cycles, REACH compliance transitions, and corporate procurement patterns anchored the trend analysis, supplemented by interviews with yoga studio operators, certified instructor network heads, fitness chain procurement managers, and TPE compound R&D directors. Secondary validation drew from ECHA substance registration databases, EU customs trade flows for fitness equipment, SEC filings of athletic apparel conglomerates, and OECD biodegradability test protocols. Bottom-up volume triangulation across material-thickness-end user segments converged with top-down market sizing.
The input-output matrix framed demand drivers against supply constraints without year-specific anchoring. Segmentation dimensions modeled include material chemistry, thickness calibration, end-user procurement authority, and surface feature engineering across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macro fitness participation trends. Forecast inputs incorporated REACH enforcement timelines and Hevea brasiliensis plantation yield fluctuations.
The model holds under steady regulatory enforcement trajectories; deviation in ECHA substance restriction acceleration or Southeast Asian climate disruption would shift volume trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Belt Trainers Market
Fitness Equipment
Mexico Outdoor Fitness Equipment Market
Fitness Equipment
Weight Training Market
Fitness Equipment
North America Fitness Rings Market
Fitness Equipment
Yoga Mat Market
Fitness Equipment
Europe Fitness Equipment Market
Fitness Equipment
Functional Fitness Equipment Market
Fitness Equipment
Asia-Pacific Fitness Rings Market
Fitness Equipment
Global Commercial Fitness Equipment Market
Fitness Equipment
Yoga Equipment Market
Fitness Equipment
Smart Scales Market
Fitness Equipment
Pilates Equipment and Gears Market
Fitness Equipment
Europe Refurbished Fitness Equipment Market
Fitness Equipment
Lung Exercise Machine Market
Fitness Equipment
Lateral Fitness Equipment Market
Fitness Equipment
Recumbent Stationary Bikes Market