
 Customised Holidays Market | 2026-2036
Customised Holidays Market Size, Share, and Industry Trends Forecast 2026-2036
Customised Holidays Market Outlook
Itinerary curation and destination consulting revenue is reconfiguring profit pools away from standardized package commissions. TUI Group leverages its vertically integrated hotel and airline network to control margin capture across the booking chain. Intrepid Travel specializes in small-group adventure modules that sustain premium pricing through localized guide networks. Black Tomato anchors its positioning around hyper-personalized experiential design, competing on narrative depth rather than volume scale.
Customised holidays denote travel arrangements built around individual preferences, combining modular transport, accommodation, activity, and guide services into a single coherent itinerary with confirmed bookings and 24-hour operational support. The primary commercial purpose is to match heterogeneous traveler psychographics—risk tolerance, mobility constraints, interest depth—with vetted local supply chains that independent booking cannot reliably assemble. Luxury package types command the widest margin pools due to concierge overhead and supplier exclusivity contracts, while adventure segments represent the fastest-growing category as younger demographics prioritize activity density over passive sightseeing. Solo traveler demand within the customer segment dimension is expanding rapidly, forcing operators to redesign rooming configurations and social mechanics that previously assumed paired or group bookings.
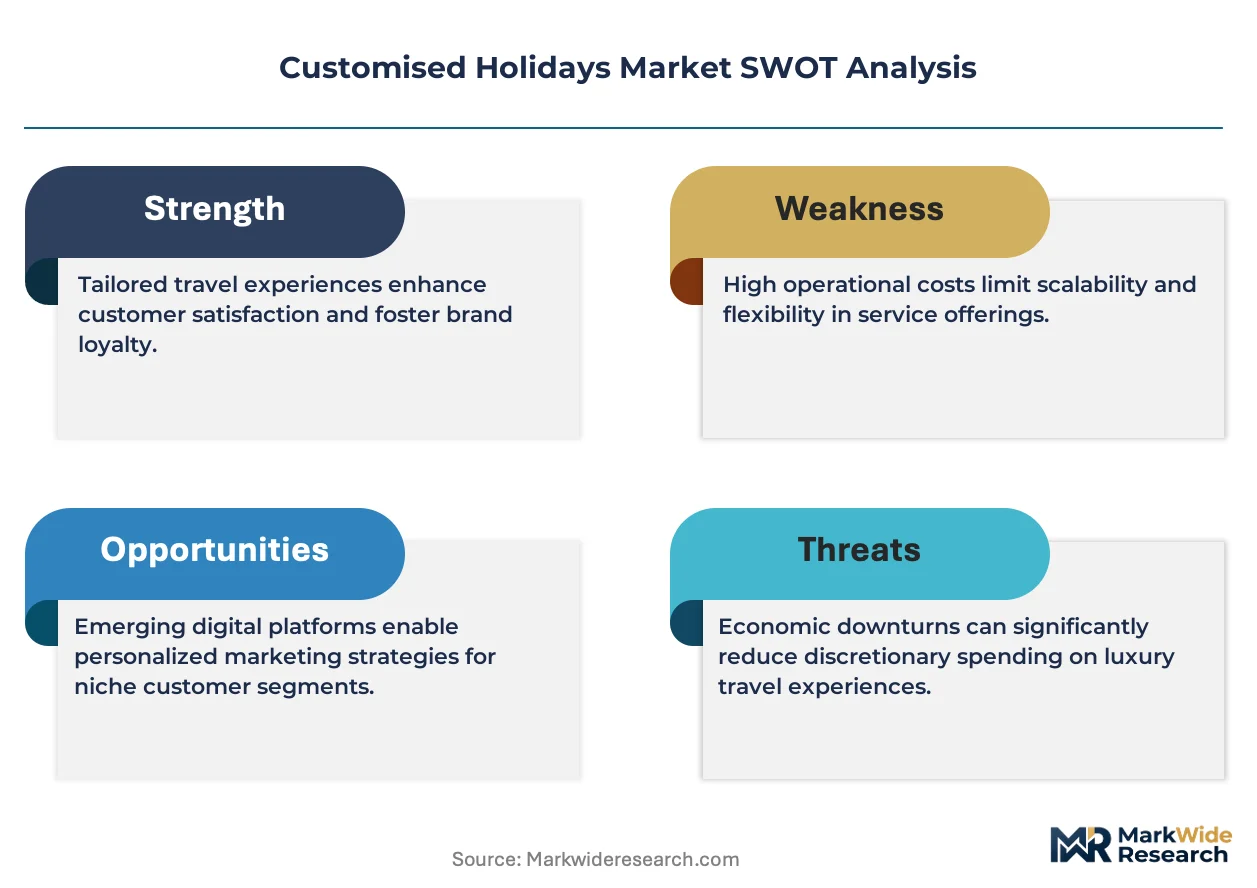
The EU Package Travel Directive and GDPR compliance frameworks shape how European operators bundle and insure multi-supplier itineraries, while Japan's METI tourism quality standards and Australia's TGA-adjacent consumer protection codes govern local operator licensing and refund obligations. These regulatory layers increase entry costs for new platform entrants but simultaneously validate premium positioning for established players with dedicated compliance infrastructure. Stakeholders must monitor how destination-level sustainability certification requirements reshape supplier qualification criteria and itinerary pricing models.
Market Dynamics
The customised holidays sector is reconfiguring around itinerary curation platforms that disintermediate traditional package aggregators, with the EU Package Travel Directive and Japan's METI tourism quality standards accelerating compliance-driven consolidation among mid-tier operators.
Growth Catalysts
- Experiential Travel Prioritization:Younger demographics now prioritize activity density over passive sightseeing, expanding adventure segment bookings. Localized guide networks in Australia and Japan capture premium pricing through exclusive access arrangements.
- GDPR-Compliant Digital Infrastructure:European operators leveraging verified data stewardship build trust with high-net-worth travelers. The EU Package Travel Directive mandates multi-supplier insurance frameworks that validate premium positioning.
- Solo Traveler Accommodation Redesign:Operators are reconfiguring rooming configurations and social mechanics to serve unpaired bookings. France and Australia lead this structural adaptation with dedicated single-occupancy inventory.
Market Restraints
- Concierge Overhead Inflation:Luxury package margins compress under dedicated operational support costs. 24-hour assistance infrastructure requires fixed staffing regardless of seasonal demand fluctuation.
- Supplier Exclusivity Concentration:Premium positioning depends on captive relationships with limited local guide networks. Concentration in French, Japanese, and Australian destination clusters creates availability bottlenecks.
- Refund Obligation Complexity:Australia's TGA-adjacent consumer protection codes and EU refund mandates impose working capital burdens. Multi-supplier itinerary dissolution triggers cascading compensation liabilities.
Strategic Opportunities
- Underpenetrated Nordic Adventure Modules:Norway and Iceland lack vertically integrated operators matching TUI Group's scale. Localized supply chain assembly presents white space for modular expedition design.
- Carbon Accounting Integration:The EU Green Deal's transport emissions disclosure requirements create demand for certified low-impact itineraries. Operators embedding verified offset mechanisms capture sustainability-premium pricing.
- AI-Assisted Itinerary Generation:Machine learning preference matching converges with human curator oversight. Hybrid platforms reduce design cycle time while preserving narrative depth.
Industry Challenges
- Localized Guide Talent Scarcity:Adventure segment expansion outpaces qualified naturalist and cultural interpreter availability. Certification standards vary across France, Japan, and Australia, complicating cross-border deployment.
- Legacy Reservation System Integration:Established operators maintain fragmented booking engines across airline, hotel, and activity suppliers. Real-time inventory synchronization demands substantial middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customised Holidays Market |
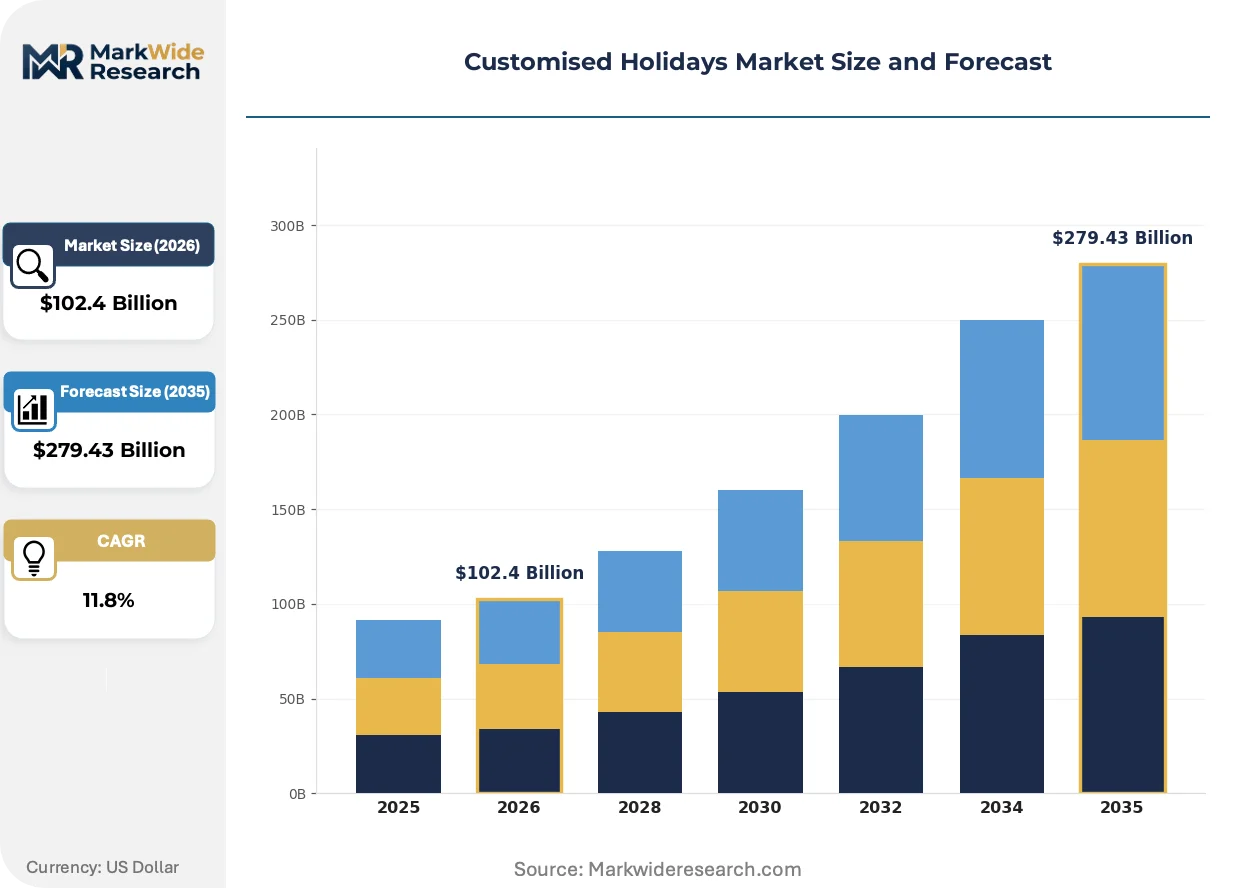
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $279.43 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Package Type: Luxury, Adventure, Family, Honeymoon Destination Type: Beach, Mountain, City, Countryside Customer Segment: Families, Couples, Solo Travelers, Groups Service Level: Premium, Standard, Budget, All-Inclusive |
| Companies Covered | Abercrombie & Kent, Intrepid Travel, Trafalgar, Audley Travel, Expedia Group, TUI Group, MakeMyTrip, G Adventures, Black Tomato, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customised Holidays Market Strategic Shifts
Digital itinerary platforms are compressing the traditional package holiday value chain, with three interconnected developments reshaping how travelers discover, customize, and purchase bespoke travel experiences.
Dynamic packaging engines are migrating from static bundling tools toward real-time inventory aggregation across transport, accommodation, and activity suppliers. High-net-worth travelers and experiential seekers now expect confirmed bookings within single-session platform interactions. This compression is eliminating the multi-day quotation lag that previously characterized bespoke travel procurement.
The EU Package Travel Directive's 2018 recast continues tightening multi-supplier liability frameworks across European operators. Insurers now require documented supplier vetting protocols before extending coverage to customized itineraries. Small-group adventure specialists face the steepest compliance adaptation costs as they scale beyond domestic supplier bases.
Traveler preference formation is shifting from destination-first to activity-first search behavior. Climbing, wildlife tracking, and culinary immersion modules now drive initial itinerary construction, with location selection following experience prioritization. This inversion is most visible among Australian and Japanese outbound segments, where younger demographics treat geography as secondary to skill-building or narrative depth.
Customised Holidays Market Segmentation
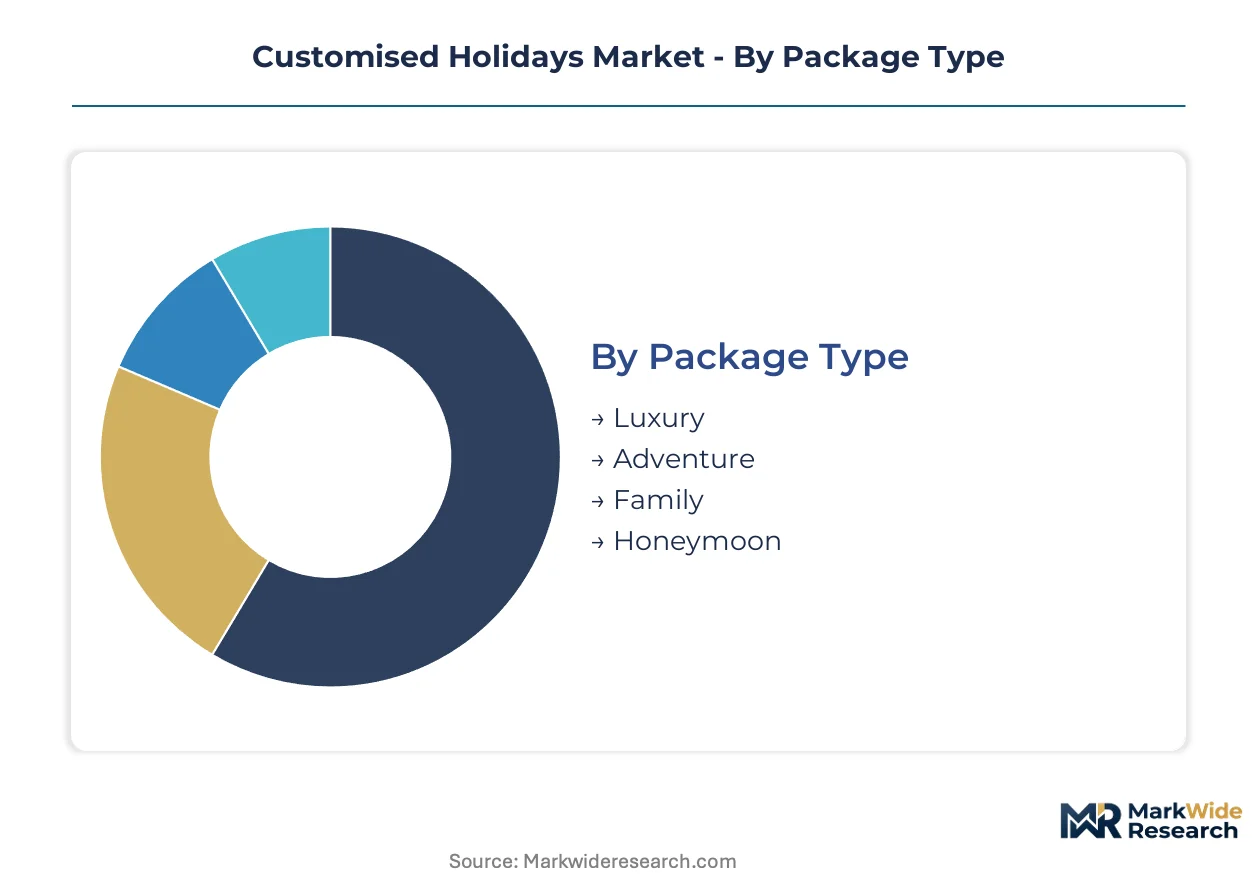
Segmentation in the customised holidays market determines how operators allocate fixed concierge infrastructure across booking profiles with radically different margin profiles and redesign cycles. Adventure and luxury segments compress itinerary development timelines while demanding deeper supplier exclusivity contracts than standardized family packages.
Package Type:
Adventure packages turn over fastest with seasonal route rotations, while honeymoon itineraries maintain the longest design-to-departure cycles and highest revision rates.
- Luxury:White-glove concierge orchestration across private aviation, boutique accommodation, and exclusive guide access commands the widest margin pools. Demand concentrates in France and Japan where high-net-worth travelers seek vetted supplier networks that independent booking cannot reliably assemble.
- Adventure:Modular activity stacking—climbing, wildlife tracking, culinary immersion—drives initial itinerary construction with location selection following experience prioritization. Australian and Japanese outbound segments treat geography as secondary to skill-building density, forcing rapid supplier certification cycles.
- Family:Multi-generational mobility constraints and risk tolerance variations require extended consultation phases but generate predictable repeat booking patterns.
- Honeymoon:Narrative depth expectations and zero-defect service requirements extend curation timelines while limiting supplier flexibility through emotional-occasion positioning.
Luxury anchors the volume base while Adventure gains share at the steepest rate.
Destination Type:
Mountain and countryside segments concentrate supplier relationships in fragmented rural networks, while beach and city destinations leverage more standardized inventory pools.
- Beach:Resort inventory aggregation and water sports module bundling enable rapid quotation turnaround. Coastal concentration in Australia and France supports real-time dynamic packaging with lower concierge overhead.
- Mountain:Specialized guide certification for alpine safety and terrain access creates supplier scarcity. Japanese and Australian mountain clusters face qualified naturalist availability constraints that extend booking windows.
- City:Cultural interpreter density and culinary immersion route density allow faster itinerary assembly through established urban supplier networks.
- Countryside:Dispersed accommodation inventory and limited transport connectivity require extended logistics coordination with localized operators.
Beach maintains the broadest customer reach while Mountain climbs the fastest among experience-prioritized demographics.
Customer Segment:
Solo traveler demand is expanding most quickly, forcing operators to reconfigure rooming economics that previously assumed paired bookings.
- Families:Multi-room inventory blocks and age-appropriate activity sequencing generate predictable seasonal demand patterns. Australian operators lead structural adaptation for extended-family configurations.
- Couples:Premium positioning through exclusive dining and private guide arrangements sustains margin capture across honeymoon and anniversary occasions.
- Solo Travelers:Single-occupancy inventory scarcity and social mechanics redesign are reshaping operator economics. France and Australia have developed dedicated unpaired booking infrastructure fastest.
- Groups:Customized small-group adventure modules sustain pricing power through localized guide networks, though coordination overhead scales non-linearly with group size.
Families anchor revenue stability while Solo Travelers expand most quickly as demographic norms shift.
Service Level:
Premium and all-inclusive tiers concentrate fixed operational support costs, while budget positioning depends on self-service platform efficiency.
- Premium:24-hour assistance infrastructure and documented supplier vetting protocols validate positioning under EU Package Travel Directive and Japan METI quality standards. Fixed staffing requirements compress margins during seasonal troughs.
- Standard:Modular service unbundling allows travelers to select specific concierge touchpoints while self-managing routine logistics.
- Budget:Platform-mediated supplier aggregation with minimal operational support depends on traveler self-sufficiency and digital itinerary tools.
- All-Inclusive:Captive supplier relationships and pre-committed inventory blocks enable predictable cost structures but limit flexibility for experience customization.
Premium captures the highest per-booking value while All-Inclusive demonstrates the steepest expansion trajectory among risk-averse traveler segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supplier networks for customised holidays concentrate in France, Japan, and Australia, where established operators maintain captive relationships with certified guide networks and boutique accommodation providers that independent platforms cannot readily replicate.
France
High-net-worth travelers from Paris and Lyon drive demand for white-glove concierge orchestration across private aviation and exclusive château access. The country's national tourism regulator enforces quality certification standards for guided experience providers. The Provence-Alpes-Côte d'Azur cluster anchors luxury itinerary assembly through vetted wine estate and yacht charter networks.
Japan
Outbound adventure seekers from Tokyo and Osaka prioritize skill-building density over passive sightseeing, expanding bookings for modular climbing and culinary immersion modules. METI tourism quality standards govern local operator licensing and refund obligations. The Kansai region concentrates certified cultural interpreter networks that sustain premium pricing through exclusive temple and artisan access arrangements.
Australia
Solo traveler demand from Sydney and Melbourne is reshaping operator economics, forcing rapid redesign of rooming configurations and social mechanics. The TGA-adjacent consumer protection codes impose working capital burdens through multi-supplier refund mandates. The Queensland coastal cluster supports real-time dynamic packaging through integrated resort inventory and water sports module bundling.
United States
Experiential travel prioritization among younger demographics in California and New York accelerates adoption of activity-first itinerary construction. The FAA regulates private aviation segments that luxury operators bundle into white-glove packages. The Mountain West region faces qualified naturalist availability constraints that extend booking windows for alpine adventure modules.
United Kingdom
GDPR-compliant digital infrastructure investments by London-based operators build trust with privacy-conscious high-net-worth travelers. The EU Package Travel Directive mandates multi-supplier insurance frameworks that validate premium positioning for established players. The Southeast England cluster concentrates dedicated compliance infrastructure that increases entry costs for new platform entrants.
Customised Holidays Market Competitive Environment
Vertically integrated tour operators and specialized experiential designers split the market between scale-driven margin capture and narrative-depth premium positioning. Three archetypes dominate: legacy travel conglomerates with captive airline and hotel networks, small-group adventure specialists leveraging localized guide relationships, and hyper-personalized boutique curators competing on itinerary uniqueness rather than volume. Consolidation pressure intensifies as compliance-driven overhead favors established players with dedicated insurance and refund infrastructure.
Within the experiential design tier, Black Tomato exemplifies narrative-depth positioning through hyper-personalized itinerary architecture, while Intrepid Travel anchors the small-group adventure archetype with modular activity stacking. TUI Group occupies the integrated conglomerate position, leveraging backward integration into airline and hotel supply to control margin capture across the booking chain. These three represent the strategic poles around which mid-tier operators must align or differentiate.
| Leading Market Players |
|---|
| Abercrombie & Kent |
| Intrepid Travel |
| Trafalgar |
| Audley Travel |
| Expedia Group |
| TUI Group |
| MakeMyTrip |
| G Adventures |
| Black Tomato |
| Others |
Value Chain & Pricing Dynamics
The Provence-Alpes-Côte d'Azur cluster anchors luxury itinerary assembly through vetted wine estate and yacht charter networks, with captive supplier relationships translating directly into premium pricing power that independent platforms cannot replicate. This geographic concentration enables white-glove operators to command sustained margin capture across the booking chain while mid-tier competitors face cost compression from fragmented supplier access.
Pricing Analysis
After-sales revenue from concierge extensions and experiential add-ons drives lifetime value across repeat booking cohorts. Three-tier pricing structure across premium, standard, and economy levels stratifies by service depth and supplier exclusivity, with certification under EU Package Travel Directive and Japan METI standards commanding measurable premiums. Pricing pressure stems from fixed 24-hour assistance infrastructure costs that compress margins during seasonal troughs regardless of booking volume. Budget-positioned travelers exhibit highest price sensitivity, while high-net-worth segments prioritize narrative depth and vetted access over rate comparison.
Supply Chain Analysis
Contract-manufacturing concentration for travel experiences rests on localized guide networks in France, Japan, and Australia, with boutique accommodation providers and certified activity operators forming the core production base. Raw material dependencies center on qualified naturalist talent, exclusive venue access rights, and aviation seat inventory blocks. Single-source vulnerability concentrates in Japanese cultural interpreter networks and Australian alpine safety specialists where certification bottlenecks limit rapid scaling. Distribution runs through vertically integrated operator platforms and specialized experiential design boutiques, with direct-to-traveler digital channels gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as experiential travel prioritization among younger demographics rebuilds booking velocity following pandemic-era disruption. Adventure segment expansion and solo traveler accommodation redesign signal durable demand normalization.
For Market Incumbents: Harden supplier exclusivity contracts in French château networks and Japanese temple access arrangements to defend against platform disintermediation. Deepen backward integration into boutique accommodation inventory to capture margin compression points currently leaking to third-party property managers. Invest in AI-assisted itinerary generation tools to reduce design cycle time while preserving narrative depth that validates premium positioning. For New Entrants and Emerging Players: Establish a beachhead in Nordic adventure modules where Norway and Iceland lack vertically integrated operators matching incumbent scale. Target carbon accounting integration services as sustainability-premium pricing creates white space for certified low-impact itinerary specialists. Deploy hybrid machine learning preference matching with human curator oversight to reduce customer acquisition costs against established design boutiques. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because compliance-driven overhead under EU Package Travel Directive and refund obligation complexity favor established players with dedicated infrastructure. Acquisition targets should concentrate on small-group adventure specialists with modular activity stacking capabilities and localized guide network density. Monitor solo traveler inventory redesign velocity as the signal for which operators have adapted structural economics fastest.| Strategic Initiative | Industry Significance |
|---|---|
| Supplier Exclusivity Lock-In | Captive relationships with French wine estates and Japanese artisan networks defend margin capture against platform commoditization. |
| AI-Assisted Itinerary Generation | Machine learning preference matching reduces design cycle time while preserving narrative depth that validates premium pricing tiers. |
| Carbon Accounting Integration | EU Green Deal transport emissions disclosure requirements create demand for certified low-impact itineraries with sustainability-premium pricing. |
| Solo Traveler Infrastructure Redesign | Single-occupancy inventory and social mechanics adaptation captures fastest-expanding demographic segment in France and Australia. |
| Compliance Infrastructure Investment | Documented supplier vetting protocols under EU Package Travel Directive and Japan METI standards validate premium positioning for insurers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with tour operator executives, itinerary design specialists, localized guide network coordinators, and boutique accommodation procurement leads. Secondary validation drew from EU Package Travel Directive regulatory filings, Japan METI tourism quality standard documentation, Australia TGA-adjacent consumer protection code records, and customs data on experiential service imports. Bottom-up booking volume aggregation across package type segments was triangulated against top-down market sizing from operator revenue disclosures.
Calibration anchored historical booking patterns against forward-looking supplier capacity commitments across the projection horizon. Segmentation dimensions modeled include package type, destination cluster, customer segment, and service level tier, with cross-tabulation against regional regulatory framework variations. CAGRs were derived from trend extrapolation of experiential travel prioritization indices and solo traveler demographic shift rates, incorporating aviation seat capacity forecasts and boutique accommodation development pipelines as industry-specific demand drivers.
Sensitivities concentrate around localized guide talent scarcity, refund obligation regulatory changes, and aviation capacity allocation shifts that could compress booking windows. Forecasts reflect assumptions on sustained high-net-worth traveler demand and continued adventure segment expansion among younger demographics. Quarterly review of supplier certification pipeline velocity and solo traveler inventory adaptation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
GCC Outbound Tourism Market
Travel and Tourism
Asia-Pacific Tourism Market
Travel and Tourism
India Travel Retail Market
Travel and Tourism
Educational Tourism Market
Travel and Tourism
New Zealand Sports Tourism Market
Travel and Tourism
Wedding Tourism Market
Travel and Tourism
Japan Sports Tourism Market
Travel and Tourism
Japan Outbound Tourism Market
Travel and Tourism
Camping and Caravanning Market
Travel and Tourism
Yacht Charter Service Market
Travel and Tourism
Group Travel Market
Travel and Tourism
India Sustainable Tourism Market
Travel and Tourism
Hong Kong Tourism Market
Travel and Tourism
Indonesia Sustainable Tourism Market
Travel and Tourism
Greece Tourism Market
Travel and Tourism
Russia Outbound Tourism Market