
 Asia-Pacific Hair Removal Wax Market | 2026-2036
Asia-Pacific Hair Removal Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hair Removal Wax Market Analytics
Market Dynamics
Professional beauty salon expansion is realigning product demand toward bulk hard wax and pre-wax treatment kits. Church & Dwight Co., Inc. leverages its established consumer goods infrastructure to supply both retail and professional channels across Australia and New Zealand. Rica Group anchors its position through specialized wax formulations targeting Mediterranean and olive skin tones prevalent in parts of the region. Marzena Bodycare Australasia dominates the Australian domestic market with localized product ranges and direct salon distribution networks.
Product Landscape
Asia-Pacific hair removal wax comprises thermoplastic resins, natural beeswax or plant-derived alternatives, and skin-conditioning additives formulated for depilation through adhesion and mechanical stripping. Hard wax, applied directly and removed without strips, commands premium positioning in professional settings due to reduced skin trauma on coarse hair. Sugar wax, rooted in traditional halawa methods, captures growing share among natural-formulation consumers in Indonesia and Malaysia. Film wax variants, with polymer-enhanced elasticity, lead innovation cycles as salons seek lower-temperature application protocols for sensitive areas.
Regulatory Environment
South Korea's MFDS enforces cosmetic safety standards that restrict certain synthetic fragrances and mandate ingredient transparency on professional-grade wax labels. Australia's TGA and state-level EPA frameworks govern chemical handling in salon environments, particularly for solvent-based wax removers. China's NMPA and GB standards for cosmetics impose registration requirements on imported wax products containing active skin-soothing compounds. Stakeholders must monitor evolving formulation compliance costs as regulatory divergence between Northeast and Southeast Asian markets intensifies sourcing complexity.
Market Dynamics
Professional salon chains across Southeast Asia are consolidating procurement power, forcing wax manufacturers to restructure pricing and service models around bulk hard-wax supply and on-site technician training programs.
Growth Catalysts
- Hard Wax Premiumization:Salons in metropolitan India and Thailand are upgrading to low-temperature polymer-enhanced formulations that reduce client discomfort and enable faster service turnover.
- TGA Disclosure Mandates:Australia's Therapeutic Goods Administration now requires full ingredient transparency on professional-grade wax labels, accelerating brand consolidation toward compliant manufacturers.
- Threading-to-Wax Migration:Urban middle-class consumers in Delhi, Mumbai, and Bangalore are abandoning traditional threading for salon-grade strip and hard wax services, expanding addressable demand.
Market Restraints
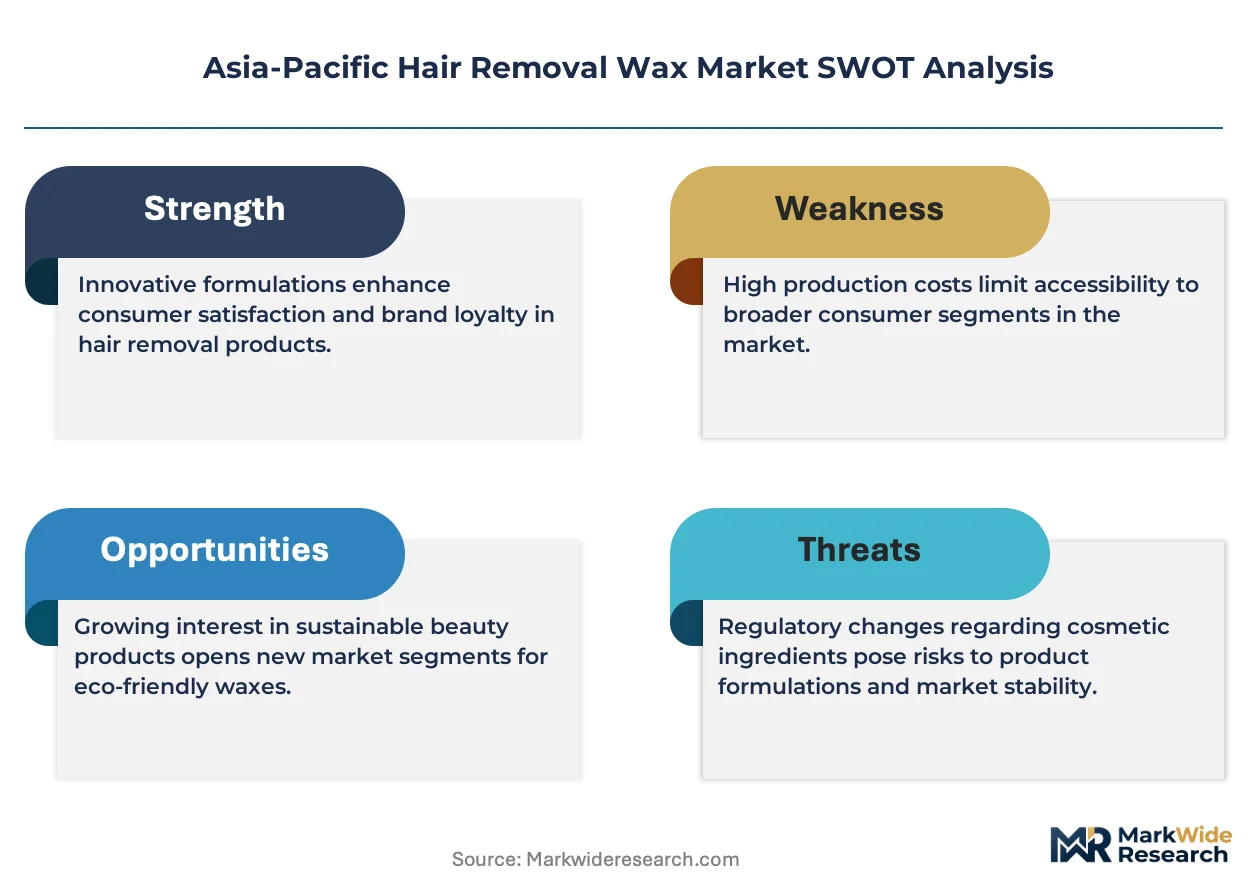
- Beeswax Price Volatility:Climate-induced honey production fluctuations in Australia and New Zealand are destabilizing natural wax input costs for premium formulation lines.
- Import Registration Burden:China's NMPA and GB standards impose multi-month approval timelines on wax products containing active skin-soothing compounds, delaying market entry for foreign suppliers.
- DIY Depilation Devices:Home-use IPL and laser hair removal systems are capturing maintenance-waxing occasions among cost-sensitive consumers in South Korea and Japan.
Strategic Opportunities
- Indonesian Halal Certification:Sugar wax formulations rooted in traditional halawa methods can capture unmet demand among Muslim consumers seeking Sharia-compliant beauty services.
- MFDS Clean-Label Incentives:South Korea's cosmetic safety framework rewards brands eliminating synthetic fragrances, creating first-mover advantage for plant-derived scent alternatives.
- Direct-to-Salon E-Commerce:Professional-grade wax and pre-treatment kits are bypassing traditional distributor networks through B2B platforms serving independent salon operators in Vietnam and the Philippines.
Industry Challenges
- Certified Wax Technician Shortage:Rapid salon expansion in tier-two Indian cities has outpaced vocational training programs, elevating labor costs and service inconsistency.
- Multi-Jurisdiction Labeling Complexity:Divergent disclosure requirements between Australia's TGA, South Korea's MFDS, and China's NMPA force manufacturers to maintain parallel packaging SKUs, elevating operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hair Removal Wax Market |
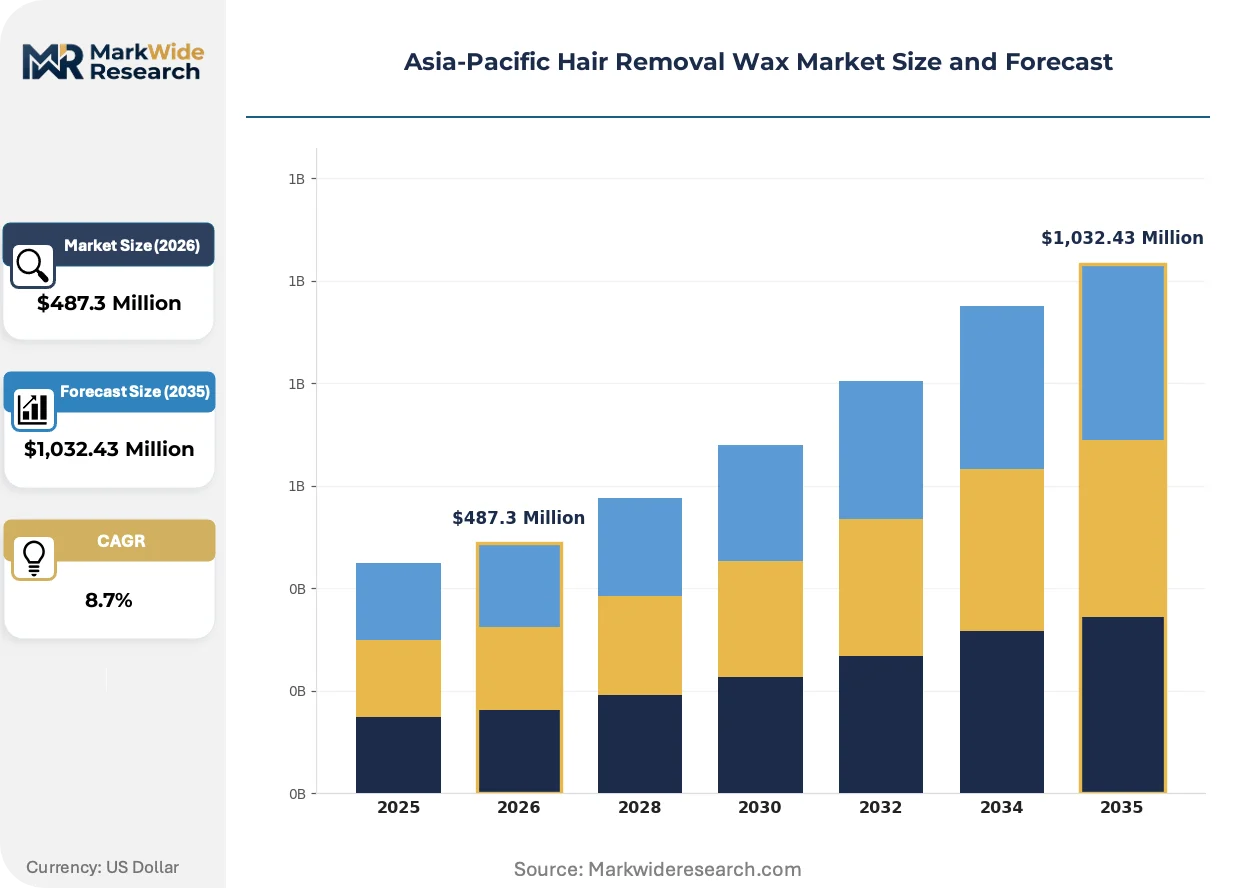
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Wax, Soft Wax, Sugar Wax, Film Wax Application: Facial Hair Removal, Body Hair Removal, Bikini Area, Eyebrow Shaping Formulation: Natural, Organic, Fragrance-Free, Sensitive Skin Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Beauty Salons |
| Companies Covered | American International Industries, Le Club Perron Rigot, Church & Dwight Co., Inc., Coty, Inc., SI&D (Aust) Pty Ltd, The Darent Wax Company Ltd., Starpil Wax Co., Rica Group, Marzena Bodycare Australasia, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hair Removal Wax Market Evolving Landscape
Formulation chemistry and application protocols are converging around client comfort and service efficiency, with polymer science and temperature control engineering driving product differentiation.
Film wax enhanced with synthetic polymer elasticity is absorbing market share from conventional hard wax in premium Southeast Asian salons. Bangkok and Singapore spa chains are adopting these formulations for Brazilian and facial waxing protocols. The technology is absorbing technician training investments by reducing application skill requirements and standardizing removal outcomes.
South Korea's MFDS cosmetic safety standards are tightening restrictions on synthetic fragrance compounds and mandating granular ingredient disclosure. Professional-grade wax importers must now reformulate or relabel existing product lines. Australian salon suppliers are responding fastest, leveraging pre-existing TGA compliance infrastructure to accelerate MFDS-aligned product registrations.
Salon procurement patterns are fragmenting as independent operators in Jakarta and Manila bypass traditional beauty distributors through specialized B2B e-commerce platforms. These channels offer smaller minimum order quantities and direct manufacturer technical support. The shift is most visible in hard wax bead and pre-wax oil categories, where brand loyalty remains low and price transparency pressures legacy distributor margins.
Asia-Pacific Hair Removal Wax Market Segmentation
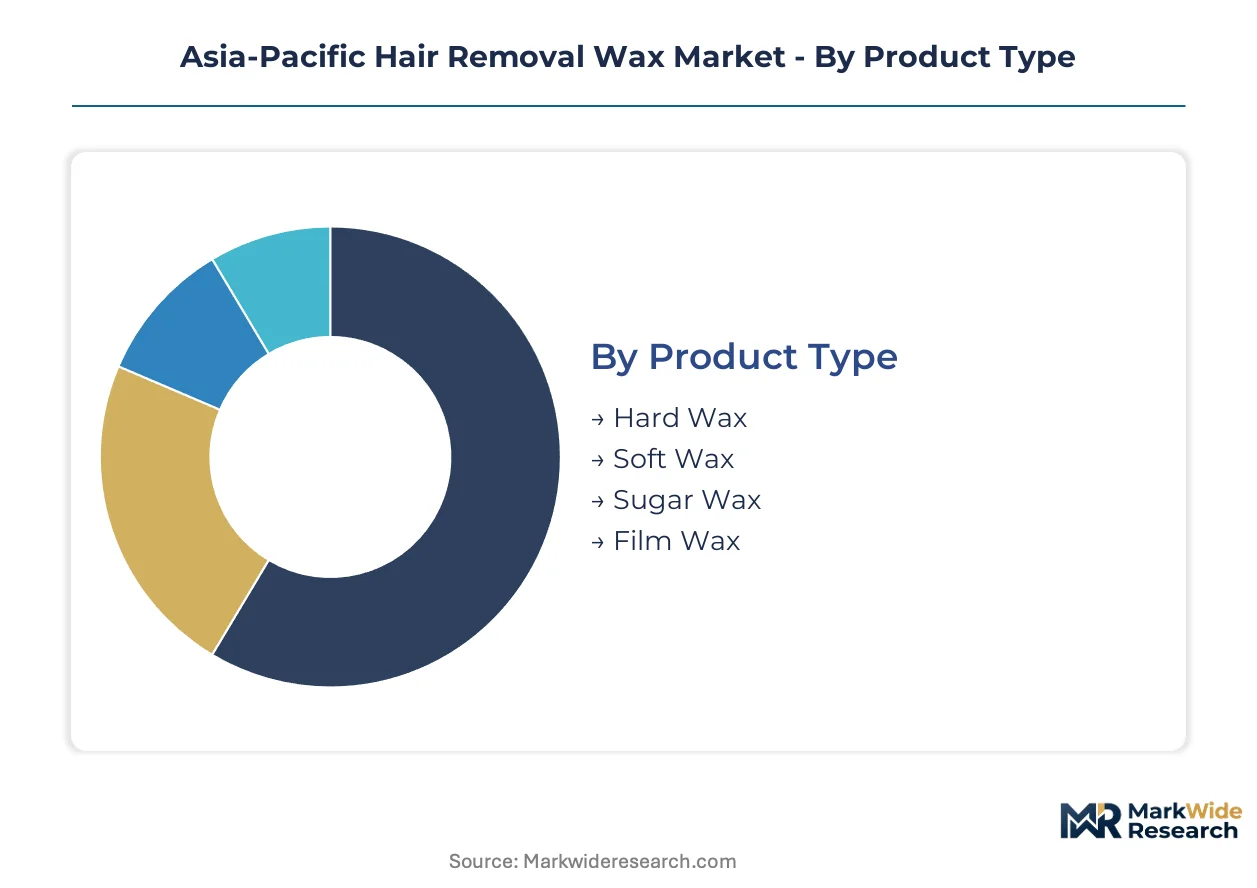
Wax chemistry and application protocols diverge sharply across professional and retail channels in the Asia-Pacific region. Segmentation reveals how formulation choices align with service intensity, regulatory constraints, and consumer willingness to pay for comfort.
Product Type:
Polymer engineering and temperature control specifications define competitive positioning across wax technologies.
- Hard Wax:Thermoplastic resin formulations applied directly without strips, polymer-enhanced variants enable low-temperature application for coarse hair. Demand concentrates in Bangkok and Singapore spa chains seeking reduced client discomfort and faster Brazilian waxing protocols.
- Film Wax:Synthetic polymer-elasticity formulations with superior adhesion and clean removal properties. Metropolitan Indian salons in Delhi and Mumbai are adopting these for sensitive-area services where technician skill variability creates service inconsistency.
- Soft Wax:Traditional strip-dependent formulations using resin and beeswax blends remain standard for high-volume leg and arm services.
- Sugar Wax:Water-soluble halawa-method formulations rooted in traditional practices, capturing natural-formulation demand in Indonesia and Malaysia.
Mature deployment sits with soft wax in established salon chains. Newer deployment is concentrated in film wax variants across premium Southeast Asian operators.
Application:
Service intensity and pain tolerance thresholds segment demand across anatomical zones.
- Body Hair Removal:High-volume leg, arm, and back services drive bulk procurement in Australian and New Zealand salon networks. Hard wax beads dominate this segment where service speed and cost efficiency override premium positioning.
- Bikini Area:Specialized Brazilian and intimate waxing protocols command premium pricing and require low-temperature formulations. Bangkok spa chains and Sydney premium salons are standardizing on film wax and polymer-enhanced hard wax for reduced skin trauma.
- Facial Hair Removal:Precision application for upper lip and chin areas, threading-to-wax migration in Indian cities is expanding addressable demand for gentle formulations.
- Eyebrow Shaping:High-precision services requiring minimal skin contact time, pre-wax oil protocols are standardizing across professional channels.
Volume leadership belongs to body hair removal in Australian salon chains. Steepest expansion trajectory is occurring in bikini-area services across Southeast Asian metropolitan markets.
Formulation:
Regulatory disclosure mandates and consumer ingredient awareness are restructuring formulation priorities.
- Natural:Beeswax and plant-derived resin bases without synthetic additives. Australian TGA disclosure requirements and South Korean MFDS clean-label incentives are accelerating brand consolidation toward transparent natural lines.
- Sensitive Skin:Hypoallergenic formulations with reduced rosin content and added skin-conditioning agents. Demand is climbing fastest in Japan and South Korea where atopic skin concerns drive professional consultation requirements.
- Organic:Certified organic wax bases with full supply chain traceability, commanding price premiums in Australian retail channels.
- Fragrance-Free:Unscented formulations eliminating synthetic and natural fragrance compounds, MFDS restrictions on fragrance allergens are expanding mandatory adoption in South Korean professional channels.
Established penetration rests with natural formulations in Australian domestic markets. Regulatory pressure is concentrating new product development in fragrance-free and sensitive-skin variants.
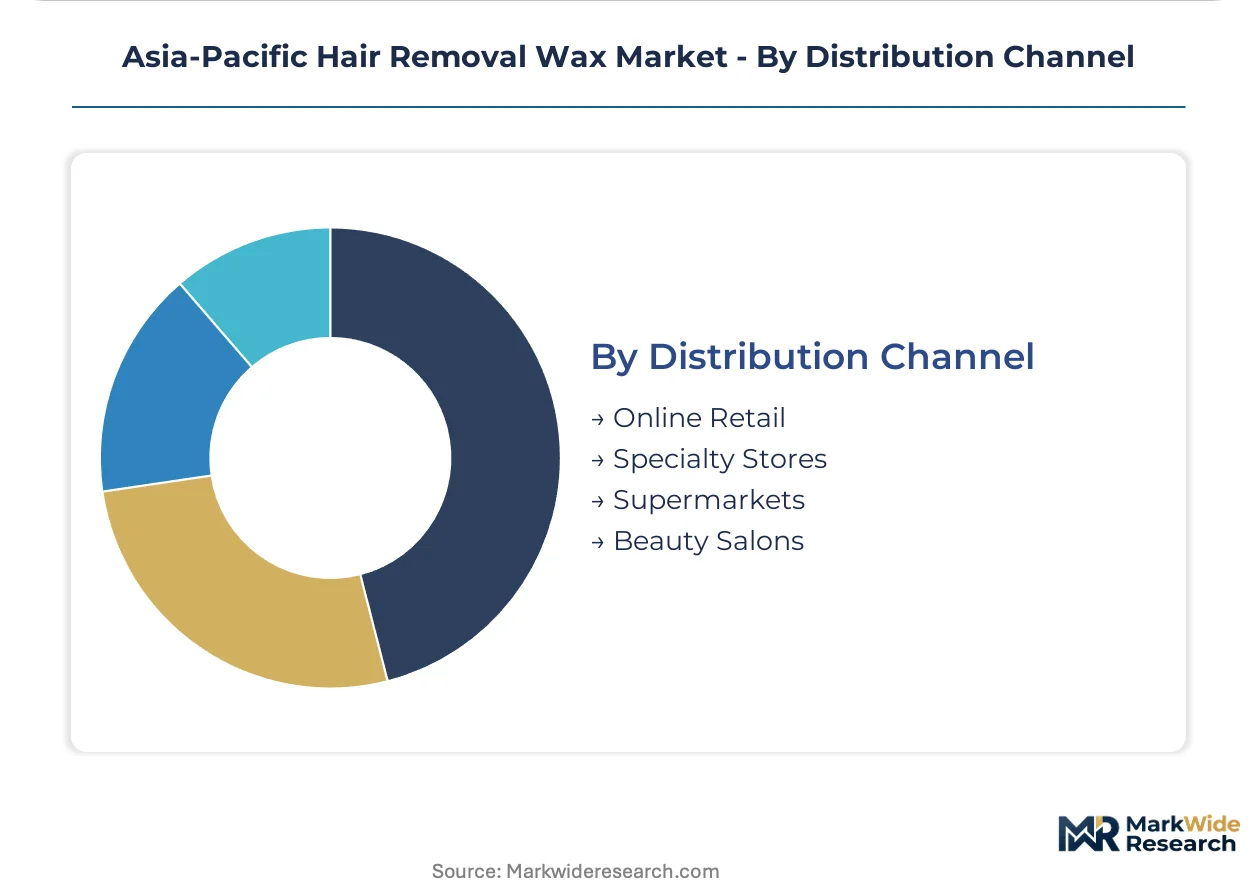
Distribution Channel:
Channel economics and customer acquisition costs determine margin structures and brand investment priorities.
- Beauty Salons:Professional-grade bulk supply with on-site technician training and technical support. Southeast Asian salon chain consolidation is forcing manufacturers to restructure pricing around volume commitments and service bundling.
- Online Retail:Direct-to-consumer and B2B platform sales, independent Jakarta and Manila operators are bypassing traditional distributors through specialized e-commerce channels with smaller minimum order quantities.
- Specialty Stores:Curated beauty retailers with educated staff, dominant in Australian and New Zealand consumer markets for at-home waxing kits.
- Supermarkets:Mass-market strip wax and microwaveable home kits, price-competitive positioning with limited formulation differentiation.
Dominant volume flows through beauty salons across the region. Channel growth is accelerating fastest in online retail serving independent Vietnamese and Philippine operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of beeswax and plant-derived resins clusters in Australia and New Zealand, while consumption concentrates in metropolitan India and Southeast Asian salon chains. Import-dependent markets in China and South Korea face extended registration timelines that reshape competitive entry patterns.
Australia
TGA disclosure mandates for professional-grade wax labels are accelerating consolidation toward compliant domestic manufacturers. Church & Dwight Co., Inc. leverages established consumer goods infrastructure to supply both retail and professional channels across Australia and New Zealand. Sydney and Melbourne salon networks drive premium demand for polymer-enhanced hard wax and pre-wax treatment protocols.
India
Urban middle-class consumers in Delhi, Mumbai, and Bangalore are abandoning traditional threading for salon-grade strip and hard wax services. BIS cosmetic standards and state-level manufacturing incentives support domestic formulation capacity expansion. Tier-two city salon expansion has outpaced certified wax technician training programs, elevating labor costs and service inconsistency in emerging markets like Pune and Hyderabad.
South Korea
MFDS restrictions on synthetic fragrance compounds and mandatory ingredient granularity are forcing reformulation of imported professional wax lines. Atopic skin concerns drive fastest-climbing demand for hypoallergenic and fragrance-free variants. Seoul Capital Area spa chains standardize on low-temperature application protocols for sensitive-area services.
China
NMPA and GB standards impose multi-month approval timelines on wax products containing active skin-soothing compounds, delaying market entry for foreign suppliers. Yangtze River Delta and Pearl River Delta metropolitan clusters concentrate professional salon expansion and bulk procurement power. Domestic manufacturers gain share through streamlined registration pathways for natural-formulation lines.
Indonesia
Sugar wax formulations rooted in traditional halawa methods capture unmet demand among Muslim consumers seeking Sharia-compliant beauty services. Jakarta and Surabaya independent operators bypass traditional distributors through specialized B2B e-commerce platforms with smaller minimum order quantities. Halal certification requirements create first-mover advantage for transparent supply chain documentation.
Asia-Pacific Hair Removal Wax Market Competitive Landscape
Top-tier vendors anchor professional salon supply chains across Australia and New Zealand, while mid-tier specialists concentrate on Southeast Asian distributor networks. The vendor base stratifies around formulation chemistry expertise, regulatory compliance infrastructure, and direct-to-salon service capabilities. Three archetypes dominate: multinational consumer goods conglomerates with dual-channel reach, regional specialists in skin-tone-specific formulations, and domestic distributors with localized technical support. Competitive moves center on regulatory pre-certification investments and B2B platform partnerships that bypass legacy distributor margins.
Within the premium professional tier, Church & Dwight Co., Inc. and Rica Group occupy positions anchored by established compliance infrastructure and specialized formulation expertise. Marzena Bodycare Australasia exemplifies domestic market concentration through localized product ranges. These three entities represent distinct strategic postures: multinational scale with consumer goods synergies, Mediterranean skin-tone specialization, and Australian domestic distribution density.
| Leading Market Players |
|---|
| American International Industries |
| Le Club Perron Rigot |
| Church & Dwight Co., Inc. |
| Coty, Inc. |
| SI&D (Aust) Pty Ltd |
| The Darent Wax Company Ltd. |
| Starpil Wax Co. |
| Rica Group |
| Marzena Bodycare Australasia |
| Others |
Value Network & Pricing Analysis
Family-owned Australian wax manufacturers with multi-decade salon relationships anchor premium pricing power through direct technical service bundling, while Southeast Asian distributor consolidation forces cost-down pressure on imported formulations. Beeswax price volatility from climate-stressed Australian apiaries and polymer resin supply disruptions from Northeast Asian petrochemical hubs create divergent margin pressures across natural versus synthetic formulation lines.
Pricing Analysis
Margin tightening in economy-grade soft wax traces to Indonesian and Vietnamese salon chain procurement centralization demanding volume rebates and extended payment terms. Three-tier pricing structure across premium, standard, and economy levels separates polymer-enhanced film wax from conventional hard wax and basic strip formulations. Certification grade under TGA and MFDS disclosure mandates commands price premiums. Cost-down pressure on standard-tier products accelerates because independent Jakarta and Manila operators bypass legacy distributors for direct B2B platform sourcing. DIY IPL device penetration in South Korea and Japan makes retail maintenance-waxing segments most price-sensitive, while Australian premium spa chains show least sensitivity due to service bundling economics.
Supply Chain Analysis
Regional distribution centers in Sydney, Singapore, and Mumbai orchestrate hub-and-spoke patterns serving salon networks across Australasia and Southeast Asia. Geographic supply concentration clusters in Australia and New Zealand for beeswax and plant-derived resins, China for synthetic polymer inputs, and India for rosin derivatives. Raw material dependencies center on honey production cycles, petrochemical polymer feedstocks, and pine resin extraction. Supply chain risk from single-source vulnerability in Australian beeswax exposes premium natural formulation lines to climate-induced input cost spikes. Distribution runs through professional beauty distributors with on-site technical support, though B2B e-commerce platforms are fragmenting downstream access for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where South Korea's MFDS fragrance disclosure mandates and Australia's TGA labeling requirements erect barrier-to-entry moats favoring manufacturers with pre-existing regulatory infrastructure.
For Market Incumbents: Deploy certification investment as the primary lever to widen compliance gaps against emerging competitors. Accelerate MFDS-aligned product registrations leveraging existing TGA disclosure infrastructure to capture reformulation-driven consolidation. Deepen backward integration into Australian beeswax sourcing to hedge climate volatility threatening premium natural lines. Channel control through direct-to-salon technical service contracts defends against B2B platform disintermediation in Southeast Asia. For New Entrants and Emerging Players: Capture Indonesian halal-certified sugar wax demand among Muslim consumers seeking Sharia-compliant beauty services, where transparent supply chain documentation creates first-mover positioning. Target tier-two Indian cities where certified wax technician shortages elevate labor costs and service inconsistency, opening white-space for training-bundled supply contracts. Penetrate through specialized B2B e-commerce platforms serving independent Vietnamese and Philippine operators with smaller minimum order quantities and direct manufacturer support. For Investors and Strategic Acquirers: Distressed-cycle entries favor Australian domestic distributors with localized product ranges and dense salon network relationships in an environment of import registration delays. Long-term viability hinges on regulatory pre-certification assets that compound over successive disclosure mandate cycles. Acquisition targets should demonstrate compliance infrastructure spanning TGA, MFDS, and NMPA frameworks. Watch for NMPA registration timeline compression as signal of competitive entry acceleration in China.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Program | Unlocks Indonesian Muslim consumer segment through Sharia-compliant supply chain documentation. |
| MFDS Pre-Certification Investment | Captures reformulation-driven consolidation as fragrance disclosure mandates tighten. |
| Direct-to-Salon E-Commerce Platform | Bypasses legacy distributor margins by serving independent Jakarta and Manila operators. |
| Backward Integration into Beeswax | Hedges climate-induced input cost volatility threatening Australian premium formulation lines. |
| Certified Technician Training Program | Addresses labor scarcity in tier-two Indian cities while locking in supply contract loyalty. |
Research Methodology
Document review covered customs and trade databases, TGA and MFDS regulatory filings, and salon industry procurement records, complemented by interviews with wax formulation chemists, professional salon chain procurement directors, B2B platform operators, and beauty distributor technical service managers. Secondary validation drew from Australian Bureau of Agricultural and Resource Economics honey production data, China NMPA cosmetic registration disclosures, and Indian BIS cosmetic standard notifications. Bottom-up demand modeling from salon service volume estimates triangulated against top-down market sizing from raw material consumption patterns.
Cross-referencing historical pricing elasticity against panel input from procurement directors anchored volume and value projections across the analysis window. Segmentation dimensions modeled include wax chemistry type, application protocol intensity, formulation certification grade, and distribution channel structure. CAGRs derived from compounding annual growth assumptions tied to salon chain expansion rates and threading-to-wax migration velocity in Indian metropolitan markets. Industry-specific forecast inputs incorporated beeswax harvest yield volatility and polymer resin price index trajectories from Northeast Asian petrochemical complexes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA registration timeline shifts and climate impacts on Australian apiary productivity. Outputs reflect documented assumptions around salon technician training pipeline expansion and B2B platform penetration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
GCC Hair Styling Products Market
Beauty & Personal Care
Switzerland Cosmetics Market
Beauty & Personal Care
US Color Cosmetics Market
Beauty & Personal Care
Eyelash Serum Market
Beauty & Personal Care
Face Makeup Market
Beauty & Personal Care
Body Firming Creams Market
Beauty & Personal Care
Europe Cosmeceuticals Market
Beauty & Personal Care
Colombia Beauty and Personal Care Products Market
Beauty & Personal Care
UK Vegan Cosmetics Market
Beauty & Personal Care
United States Beauty and Personal Care Products Market
Beauty & Personal Care
Portable Atomizer Market
Beauty & Personal Care
Depilatories Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
Saudi Arabia Body Care and Personal Hygiene Market
Beauty & Personal Care
GCC Male Grooming Products Market
Beauty & Personal Care
Hair Serums Ingredient Market