
 Smart Bottle Warmers Market | 2026-2036
Smart Bottle Warmers Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Bottle Warmers Market Insights
Fragmentation across first-time millennial parents and dual-income households is recalibrating how brands allocate marketing spend and product development resources. Baby Brezza leverages its direct-to-consumer channel strength to sustain premium positioning in North America. Philips Avent anchors European retail shelves through pharmacy and baby-specialty distribution networks.
Smart bottle warmers are temperature-controlled appliances designed to heat infant formula or breast milk to body-safe levels, typically using thermoelectric Peltier elements or infrared sensors with precision within one degree Celsius for nutritional preservation. Electric warmers dominate unit economics due to higher average selling prices and recurring consumable attachment, while portable warmers represent the fastest-expanding margin pool as travel-friendly designs capture on-the-go feeding occasions. Smart connectivity integration across Wi-Fi and Bluetooth protocols is shifting competitive focus toward app-enabled scheduling and remote monitoring capabilities.
FDA oversees material safety and electrical standards for infant feeding devices in the United States, while the EU's CE marking and Ecodesign Directive govern energy consumption and electromagnetic compatibility across member states. REACH compliance restricts certain phthalates and flame retardants in plastics that contact food or infant products, directly influencing supplier qualification and material substitution timelines. Stakeholders must monitor evolving interoperability standards between smart home ecosystems and pediatric health platforms as the category's value proposition shifts from standalone warming to integrated nursery data systems.
Market Dynamics
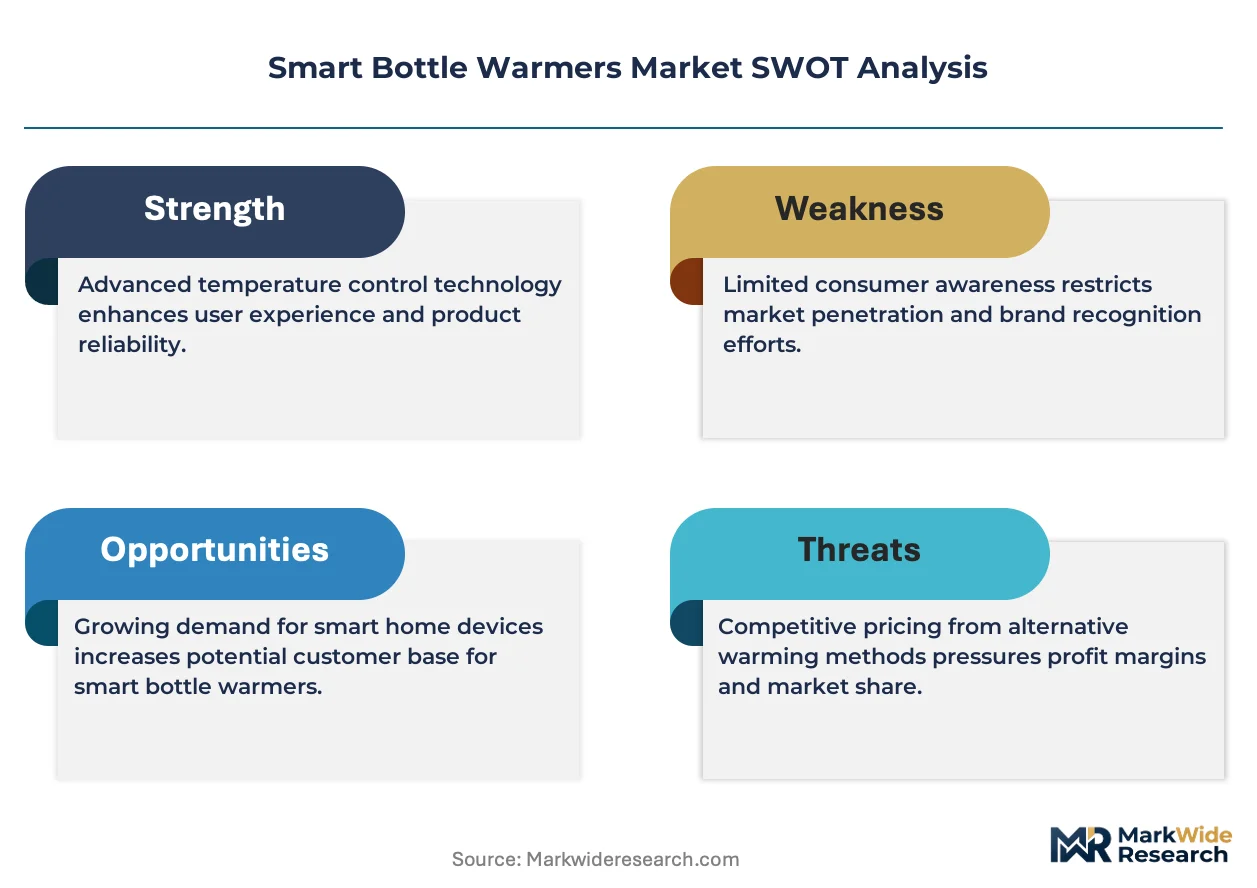
Smart bottle warmers are pivoting from standalone appliances to data-capture nodes within connected nursery ecosystems, driven by millennial parental demand for remote monitoring and pediatric health integration.
Growth Catalysts
- EU Ecodesign Directive:Energy-efficiency mandates for small appliances are accelerating R&D investment in thermoelectric Peltier systems that reduce standby power consumption below one watt.
- Dual-income household penetration:Time-constrained parents in Germany and the United States are prioritizing app-enabled scheduling features that automate feeding preparation during work hours.
- Infrared sensor precision:One-degree Celsius temperature accuracy is preserving heat-sensitive breast milk nutrients, expanding clinical endorsement from lactation consultants and pediatric networks.
Market Restraints
- REACH compliance costs:Phthalate and flame retardant restrictions in food-contact plastics are extending supplier qualification timelines by eight to fourteen months for Asian contract manufacturers.
- Wi-Fi module supply concentration:Semiconductor fabrication for IoT chipsets clusters in Taiwan and South Korea, exposing brands to geopolitical disruption and allocation constraints.
- Thermoelectric efficiency limits:Peltier element coefficient of performance caps warming speed, preventing sub-three-minute heat cycles that would match microwave convenience.
Strategic Opportunities
- F-Gas Regulation phase-down:The EU's refrigerant restrictions are creating first-mover advantage for solid-state warming technologies that eliminate compressor-based cooling circuits entirely.
- Pharmacy channel expansion:Baby-specialty retailers in France and Switzerland are allocating premium shelf space to CE-marked devices with pediatrician co-branding.
- Bluetooth-LE and Thread convergence:Interoperability with Matter-enabled smart home hubs is opening integration with Nest, Ecobee, and Apple HomeKit nursery automation workflows.
Industry Challenges
- FDA 510(k) pathway complexity:Electrical safety and material biocompatibility documentation for infant feeding devices requires specialized regulatory affairs expertise that smaller brands struggle to staff.
- Legacy interoperability gaps:Proprietary app ecosystems from incumbent manufacturers resist open API standards, fragmenting data portability for parents switching between device brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bottle Warmers Market |
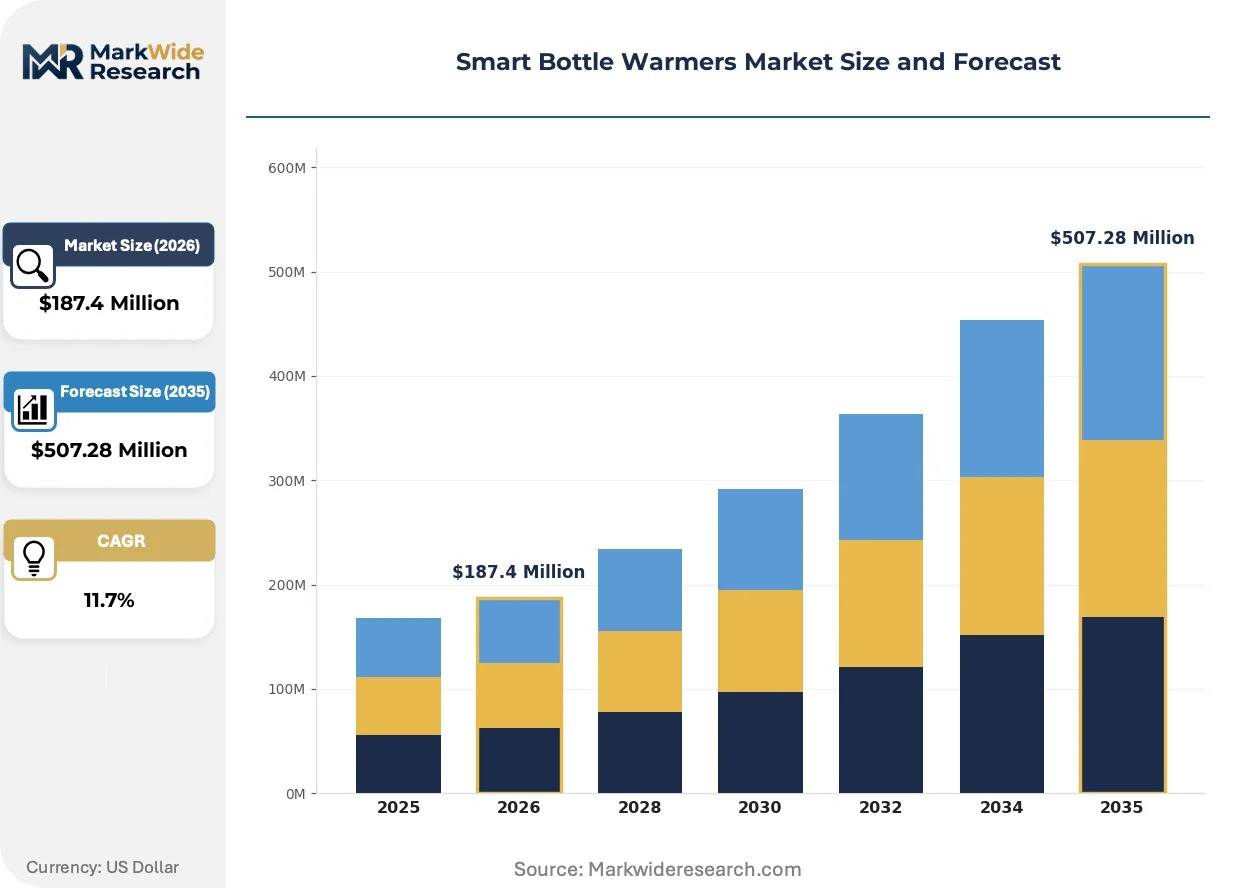
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Warmers, Microwave Warmers, Portable Warmers, Non-Electric Warmers End User: Parents, Caregivers, Hospitals, Daycares Technology: Smart Connectivity, Thermoelectric, Infrared, Induction Distribution Channel: Online Retail, Hypermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Baby Brezza, Momcozy, Tommee Tippee, Chicco, Philips Avent, Dr. Brown's, Grownsy, Baby's Brew, Kiinde, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bottle Warmers Market Trends and Innovations
Product development is converging on predictive warming algorithms and voice-control integration, shifting competitive differentiation from hardware specifications to software-enabled parenting workflows.
Thermoelectric solid-state heating is expanding into portable and travel-oriented form factors that eliminate water baths and steam chambers. Parents commuting between childcare facilities and workplaces are adopting battery-powered units with USB-C charging. This architecture is expanding into airline carry-on compatibility and vehicle 12V adapter ecosystems, compressing the addressable market for traditional countertop models.
The EU's F-Gas Regulation and Ecodesign Directive are jointly mandating elimination of hydrofluorocarbon refrigerants and standby power limits below 0.5 watts by 2029. Manufacturers are redesigning thermal management subsystems around phase-change materials and vacuum insulation panels. Premium product lines targeting German and Nordic markets are responding with modular, repairable designs that extend service life beyond seven years.
Millennial parents are unbundling after-sales service from hardware purchase, subscribing to app-based feeding analytics and remote pediatric consultations. Direct-to-consumer brands are capturing this shift through recurring revenue models that monetize data insights rather than device margins. This behavioral pivot is most visible in the United States, where telehealth integration with pediatric networks is becoming a standard bundle feature.
Smart Bottle Warmers Market Segmentation
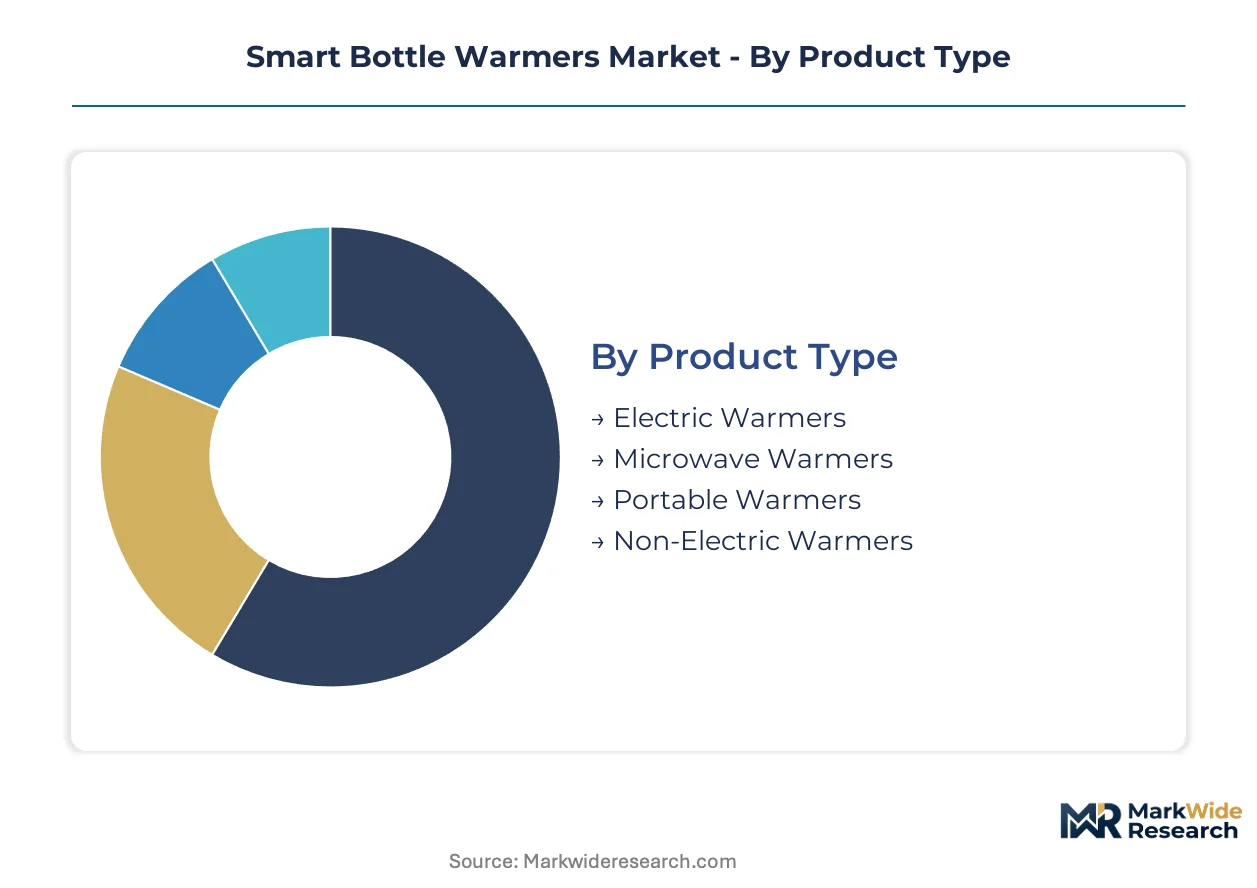
Segmentation in the Smart Bottle Warmers Market reveals divergent capital requirements and margin profiles across heating architectures, customer workflows, and channel economics. Manufacturers optimize R&D allocation by mapping thermoelectric efficiency gains against the addressable base of dual-income households versus institutional procurement cycles.
Product Type:
Capital intensity varies sharply across heating architectures, with thermoelectric solid-state systems demanding the highest upfront tooling investment for precision semiconductor integration.
- Electric Warmers:Countertop units employing resistive heating elements or thermoelectric Peltier modules with integrated temperature sensors. German households absorb the bulk of premium electric unit shipments, driven by Ecodesign Directive compliance requirements that disqualify inefficient legacy designs. These systems carry the highest bill-of-materials complexity due to Wi-Fi module integration and phase-change thermal management subsystems.
- Portable Warmers:Battery-powered units with USB-C charging and 12V vehicle adapter compatibility, eliminating water bath dependencies. United States commuter parents between childcare facilities and workplaces are expanding this segment fastest as on-the-go feeding occasions multiply. Solid-state thermoelectric architectures here compress warming cycles into airline carry-on compliant form factors.
- Microwave Warmers:Insulated containers designed for standardized microwave exposure with thermal mass stabilization. These units require minimal electronic content and dominate pharmacy channel entry-level pricing in France.
- Non-Electric Warmers:Vacuum-flask or gel-pack systems relying on passive thermal retention without electrical input. Swiss alpine regions and Nordic outdoor-oriented households sustain demand for these emergency backup solutions.
Electric warmers absorb the bulk of installed capacity; portable warmers are expanding most quickly.
End User:
Customer workflows dictate feature prioritization, with institutional buyers demanding batch-processing capacity while individual purchasers optimize for single-serve convenience and app integration.
- Parents:Millennial first-time buyers in dual-income United States households, prioritizing app-enabled scheduling and remote monitoring through Bluetooth-LE and Thread protocols. This segment concentrates spending on premium SKUs with pediatrician co-branding and telehealth bundle integration.
- Hospitals:Neonatal intensive care units and maternity wards requiring FDA 510(k) cleared devices with material biocompatibility documentation and electromagnetic interference shielding. Procurement runs through group purchasing organizations with multi-year service contracts.
- Caregivers:Extended family members and professional nannies operating across multiple households, favoring simplified interfaces without smartphone dependency.
- Daycares:Licensed childcare facilities in Germany and Switzerland subject to CE-marked equipment mandates and local hygiene inspectorate protocols.
Parents command the highest per-unit expenditure; hospitals are climbing the fastest as clinical endorsement networks expand.
Technology:
Intellectual property concentration clusters around sensor fusion algorithms and wireless protocol stacks, with connectivity integration now table stakes rather than differentiator.
- Smart Connectivity:Wi-Fi and Bluetooth-enabled units with cloud-based feeding analytics, remote temperature adjustment, and integration with Nest, Ecobee, and Apple HomeKit ecosystems. United States direct-to-consumer brands monetize recurring subscription revenue for pediatric telehealth consultations layered atop hardware margins.
- Thermoelectric:Peltier element systems achieving one-degree Celsius precision without compressor-based refrigerant circuits, qualifying for EU F-Gas Regulation phase-down compliance. German engineering subsidiaries dominate patent holdings in this architecture.
- Infrared:Non-contact temperature sensing for nutrient-preserving breast milk warming, endorsed by lactation consultants in France and Switzerland.
- Induction:Electromagnetic field heating for rapid thermal transfer, currently limited to premium countertop units due to coil cost and EMI certification complexity.
Thermoelectric systems anchor production volume; smart connectivity integration is gaining share fastest as Matter protocol adoption accelerates.
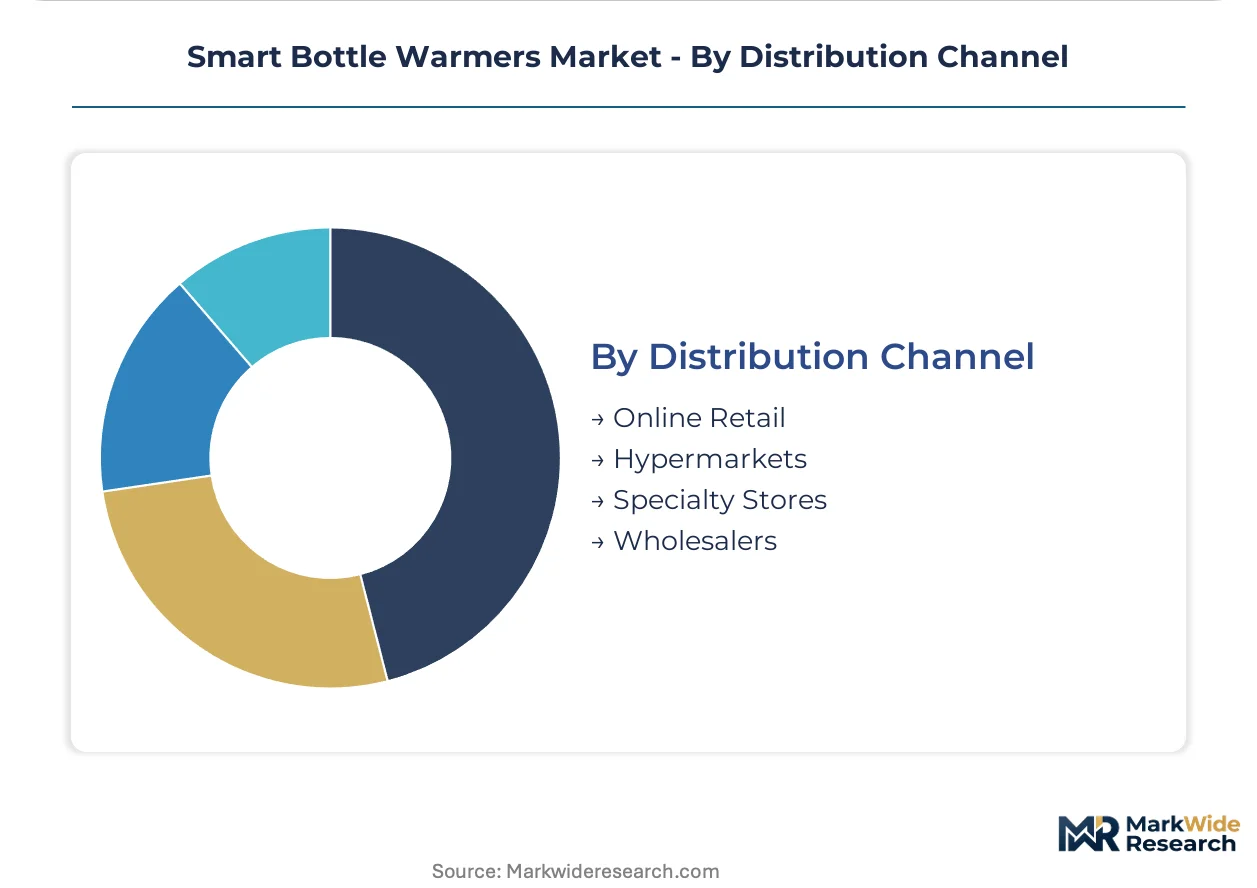
Distribution Channel:
Channel mix determines margin capture, with direct-to-consumer platforms retaining highest contribution margins while pharmacy and specialty retail confer credibility premiums in European markets.
- Online Retail:Brand-owned storefronts and marketplace platforms capturing subscription attach rates and first-party data for predictive warming algorithm refinement. United States millennial parents initiate purchase journeys here exclusively.
- Specialty Stores:Baby-product retailers and pharmacy chains in France, Switzerland, and Germany allocating premium shelf space to CE-marked devices with pediatrician co-branding.
- Hypermarkets:Mass merchandisers moving volume-tier SKUs with reduced connectivity features and standardized warranty terms.
- Wholesalers:Institutional distributors serving hospital group purchasing organizations and daycare procurement consortia with bulk pricing and extended payment terms.
Online retail concentrates revenue contribution; specialty stores are expanding most quickly as pharmacy channel premiumization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermoelectric Peltier module fabrication clusters in German industrial zones anchor European supply chains for precision temperature control subsystems.
United States
Dual-income millennial households in California and New York Metro drive premium SKU absorption for app-enabled scheduling features. FDA 510(k) clearance requirements for infant feeding devices create regulatory moats that favor established electrical safety documentation. Boston-area pediatric telehealth networks are integrating feeding analytics into remote consultation workflows.
Germany
Bavarian engineering subsidiaries dominate patent holdings in solid-state thermoelectric architectures. The Ecodesign Directive's standby power limits below 0.5 watts by 2029 are accelerating modular, repairable product redesigns. Berlin-Brandenburg households command the highest penetration of CE-marked premium childcare technology in Europe.
France
Pharmacy channel premiumization concentrates demand in Paris and Lyon for infrared sensor-equipped units with lactation consultant endorsements. ANSM oversight of material biocompatibility extends supplier qualification timelines for food-contact plastics. Auvergne-Rhône-Alpes manufacturing clusters are pivoting toward REACH-compliant polymer substitution.
Switzerland
Swissmedic certification requirements for pediatric devices sustain price premiums in Zurich and Geneva retail networks. Alpine outdoor-oriented households in Bernese Oberland sustain niche demand for vacuum-flask non-electric backup systems. Basel-area chemical suppliers are reformulating phase-change materials for extended thermal retention.
China
MIIT standards for electromagnetic compatibility govern Wi-Fi module integration in Shenzhen and Dongguan assembly operations. GB standards for small appliance energy efficiency are converging toward EU Ecodesign benchmarks for export-oriented production. Yangtze River Delta contract manufacturers are extending semiconductor fabrication partnerships for IoT chipset allocation security.
Smart Bottle Warmers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription models and telehealth bundle integration. The vendor base stratifies across three tiers: legacy baby-care conglomerates with pharmacy distribution depth, direct-to-consumer specialists monetizing recurring data revenue, and Asian contract manufacturers supplying white-label thermoelectric hardware. Dominant competitive moves include strategic partnerships with pediatric health platforms and geographic expansion through CE-marked product lines into German pharmacy channels.
Among North American direct-to-consumer specialists, Baby Brezza exemplifies the subscription-revenue archetype through app-based feeding analytics. Philips Avant anchors the European retail tier through pharmacy and baby-specialty distribution networks. Momcozy represents the emerging Asian brand archetype, occupying a position in portable and travel-oriented form factors with USB-C charging ecosystems.
| Leading Market Players |
|---|
| Baby Brezza |
| Momcozy |
| Tommee Tippee |
| Chicco |
| Philips Avent |
| Dr. Brown's |
| Grownsy |
| Baby's Brew |
| Kiinde |
| Others |
Pricing and Supply Chain Analysis
Dual-income millennial parents in the United States and Germany command premium positioning for app-enabled thermoelectric units, anchoring a subscription-anchored pricing model that monetizes recurring telehealth bundles rather than transactional hardware margins.
Pricing Analysis
Volume concentrates in countertop electric warmers while margin pools concentrate in portable thermoelectric units with USB-C charging ecosystems. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k) cleared devices with pediatrician co-branding from entry-level pharmacy SKUs. Pricing pressure stems from REACH compliance costs extending supplier qualification timelines for Asian contract manufacturers. Institutional buyers in hospital group purchasing organizations exhibit lowest price sensitivity; commuter parents seeking travel-compatible form factors show highest elasticity.
Supply Chain Analysis
The EU's Ecodesign Directive and F-Gas Regulation are reshaping sourcing toward solid-state thermoelectric components that eliminate compressor-based refrigerant circuits. Wi-Fi module fabrication clusters in Taiwan and South Korea; precision Peltier element production concentrates in German industrial zones; final assembly operations draw from Shenzhen and Dongguan facilities. Semiconductor allocation constraints for IoT chipsets present single-source vulnerability. Distribution runs through direct-to-consumer platforms for subscription revenue capture alongside pharmacy and baby-specialty retail networks in France and Switzerland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Bottle Warmers Market functions as a cost-of-compliance story where the EU's F-Gas Regulation erects barrier-to-entry moats favoring incumbents with solid-state thermoelectric R&D capabilities and CE-marking infrastructure already deployed.
For Market Incumbents: Lock in supplier exclusivity agreements for REACH-compliant polymer formulations before Asian contract manufacturers complete qualification cycles. Expand modular, repairable product architectures targeting German Ecodesign Directive standby power mandates. Vertical integration into Peltier element semiconductor fabrication defends margin position against Wi-Fi module supply concentration in Taiwan. For New Entrants and Emerging Players: The F-Gas Regulation in Europe opens a window for solid-state warming technologies that bypass compressor-based cooling circuits entirely. Target portable and travel-oriented form factors with USB-C charging ecosystems where incumbent pharmacy channel presence remains thin. Pursue direct-to-consumer launch with subscription-anchored pediatric telehealth bundles rather than competing on hardware margins. For Investors and Strategic Acquirers: The window for entry favors direct-to-consumer specialists with recurring revenue infrastructure and first-party feeding analytics capabilities. Acquisition targets should demonstrate Matter protocol integration readiness for Nest, Ecobee, and Apple HomeKit nursery automation workflows. Monitor Bluetooth-LE and Thread convergence adoption rates as inflection indicator for smart home ecosystem integration viability.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Telehealth Bundle Integration | Direct-to-consumer brands monetize recurring subscriptions layered atop hardware margins in United States markets. |
| CE Marking Pathway Acceleration | Pharmacy channel premiumization in France and Switzerland requires ANSM-compliant material biocompatibility documentation. |
| Solid-State Thermoelectric R&D Scale-Up | Elimination of hydrofluorocarbon refrigerants qualifies products for EU F-Gas Regulation phase-down compliance. |
| Matter Protocol Certification | Interoperability with Apple HomeKit and Nest ecosystems opens integration into connected nursery automation workflows. |
| REACH-Compliant Polymer Substitution | Phthalate and flame retardant restrictions in food-contact plastics extend supplier qualification timelines for Asian manufacturers. |
Research Methodology
Independent corroboration across regulatory filings, customs trade data, and connected nursery ecosystem platform disclosures underwrites the qualitative findings in this study. Primary interviews with product development executives at thermoelectric component suppliers, regulatory affairs leads navigating FDA 510(k) pathways, pharmacy category buyers in France and Germany, and pediatric telehealth platform engineers combined with secondary validation from ECHA REACH substance databases, EU Ecodesign implementing measures, and SEC filings from disclosed market participants. Bottom-up segmentation modeling and top-down market sizing triangulate volume and value estimates.
Comparable-period anchoring to historical adoption curves for smart home appliances and infant care technology diffusion patterns structured the projection horizon. The analytical framework models segmentation across heating architecture, customer workflow, connectivity integration level, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to Ecodesign Directive implementation timelines and millennial household formation patterns. Forecast inputs include Wi-Fi module supply allocation constraints and Matter protocol adoption trajectories.
The model assumes a particular technology adoption path; alternative pathways for solid-state thermoelectric efficiency gains or abrupt semiconductor supply disruption would alter the outlook. Forecasts reflect documented assumptions regarding regulatory implementation schedules and parental willingness to subscribe for data-enabled services. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Global Baby Car Seats Market
Baby Products
Global Baby Mattresses Market
Baby Products
Stroller Rental Market
Baby Products
Baby Changing Station Market
Baby Products
Baby Tableware Market
Baby Products
Global Baby Product Market
Baby Products
Global Pregnancy Pillow Market
Baby Products
Baby Feeding Accessories Market
Baby Products
Baby Care and Mother Care Market
Baby Products
Global Baby Pajamas and Sleepwears Market
Baby Products
Indonesia Baby Care Products Market
Baby Products
Kids Training Pant Market
Baby Products
Diaper Pails Market
Baby Products
Baby Playpens Market
Baby Products
China Maternity Goods Market
Baby Products
Global Baby Play Mats Market