
 Global Grid Computing Market | 2026-2036
Global Grid Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Grid Computing Market Foresight
Specialized HPC engineering talent is bifurcating the competitive landscape, as enterprises struggle to source professionals fluent in MPI protocols and distributed resource management. IBM Corporation leverages its long-standing presence in academic supercomputing partnerships to sustain pipeline visibility. Dell Technologies Inc. anchors commercial grid infrastructure sales through direct enterprise relationships and modular server architectures.
Grid computing denotes a distributed computing architecture that aggregates processing power, storage, and data resources across geographically dispersed nodes through standardized middleware protocols such as OGSA or Globus Toolkit, enabling coordinated problem-solving for workloads too large for single systems. Its primary purpose centers on orchestrating heterogeneous resources to execute parallel computations, data-intensive analytics, and collaborative scientific workflows across institutional boundaries. Hybrid Grid deployments now capture disproportionate strategic attention as organizations balance on-premises control with burst capacity into public clouds, while Computational Grid technology dominates transaction volume due to sustained demand from physics simulation and quantitative finance sectors. Knowledge Grid remains nascent but attracts R&D investment from semantic web and AI training consortia seeking inference-at-scale architectures.
FDA guidelines on computational validation for pharmaceutical modeling, EPA emissions frameworks affecting data center buildouts, and EMA data integrity requirements for clinical trial simulations collectively elevate compliance costs while standardizing grid audit trails across regulated industries. China's MIIT cloud service classification rules and dual carbon goals further constrain where cross-border grid nodes may physically reside. Stakeholders must weigh sovereign compute mandates against latency requirements when architecting multi-node deployments spanning jurisdictions with divergent data localization regimes.
Market Dynamics
Hybrid Grid architectures are forcing infrastructure vendors to recalibrate middleware roadmaps as enterprises demand seamless burst capacity into public clouds without surrendering on-premises control over sensitive molecular simulation workloads.
Growth Catalysts
- EU AI Act compliance:Cross-border compute governance frameworks in Europe are mandating auditable distributed processing trails, accelerating certified grid deployments in pharmaceutical and automotive R&D clusters.
- Materials science simulation:Fraunhofer institutes and German industrial consortia are anchoring high-performance grid infrastructure for multiphysics modeling of next-generation composites and battery chemistries.
- Container orchestration:Kubernetes-native grid middleware is collapsing deployment friction for life sciences organizations running large-scale genomic alignment and protein folding pipelines.
Market Restraints
- NVIDIA GPU supply concentration:Foundry capacity constraints for AI accelerators are extending lead times for grid nodes requiring H100 or successor architectures, compressing deployment schedules for quantitative finance clients.
- Dual carbon compliance:China's MIIT cloud service classification rules and provincial emissions targets are restricting where cross-border grid nodes may physically reside, fragmenting pan-Asian compute fabrics.
- Interconnect latency floors:Optical fiber propagation limits between continental grid sites impose hard bounds on tightly coupled MPI workloads, relegating certain molecular dynamics simulations to single-region deployments.
Strategic Opportunities
- Saudi sovereign compute:NEOM and King Abdullah University of Science and Technology are constructing carbon-neutral grid facilities to attract pharmaceutical and climate modeling consortia seeking jurisdictional diversification.
- Federated learning grids:Convergence of differential privacy frameworks with edge-distributed training architectures is opening compliant collaborative AI development across institutional boundaries without raw data migration.
- Green hydrogen co-location:Nordic data center operators are siting grid nodes adjacent to electrolyzer facilities to secure long-term renewable power purchase agreements and attract ESG-constrained European research budgets.
Industry Challenges
- MPI protocol specialization:Academic training pipelines are producing insufficient systems programmers fluent in Open MPI tuning and InfiniBand topology optimization, forcing enterprises to compete for a shrinking pool of HPC engineering talent.
- EMA audit trail standardization:Pharmaceutical grid operators must reconstruct decade-old computational provenance records to satisfy evolving data integrity requirements for clinical trial simulations, imposing retrospective compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Grid Computing Market |
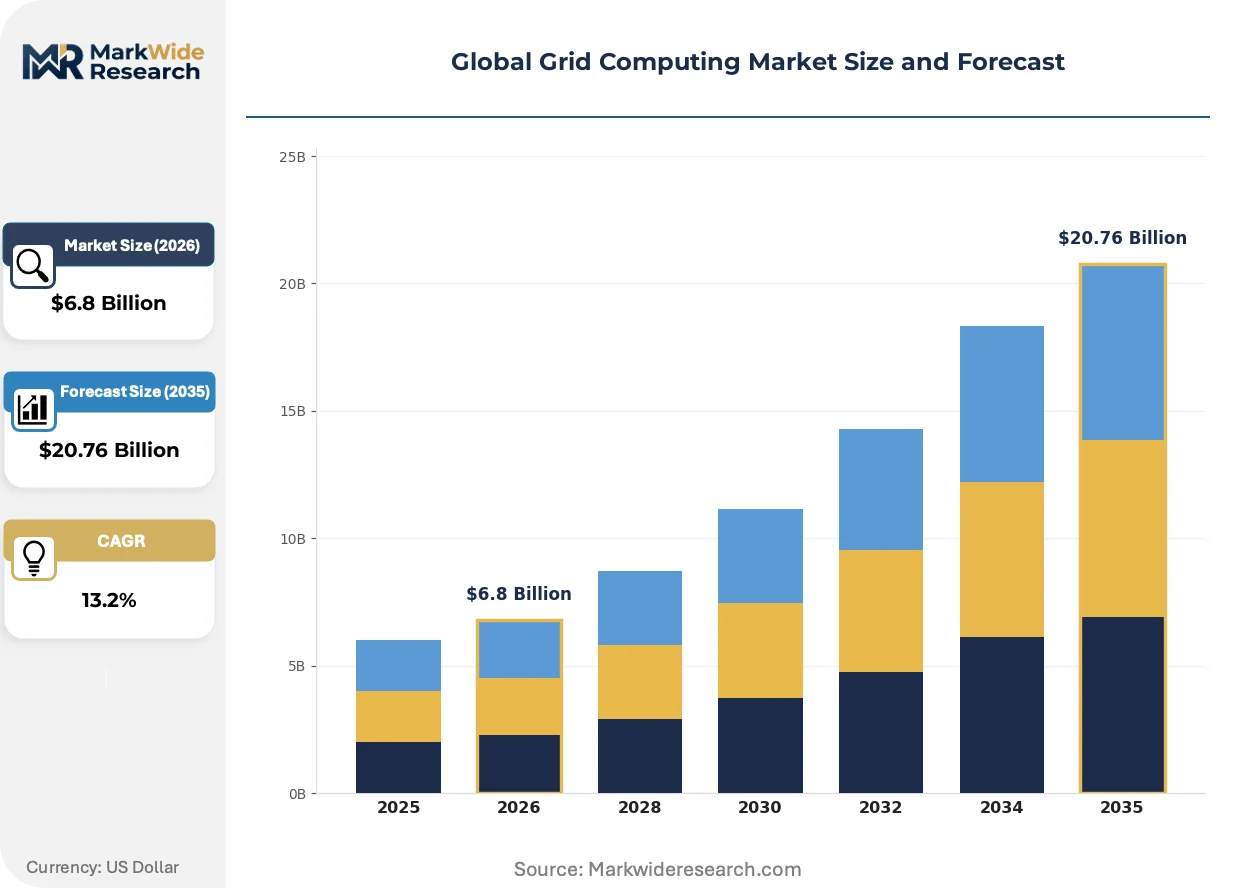
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Grid, Private Grid, Hybrid Grid, Community Grid Technology: Data Grid, Computational Grid, Service Grid, Knowledge Grid, Sensor Grid Application: Scientific Research, Financial Modeling, Media Rendering, Weather Forecasting, Academic Computing End User: Research Institutes, Government Agencies, Cloud Service Providers, IT Enterprises, Educational Organizations |
| Companies Covered | IBM Corporation, Dell Technologies Inc., Amazon Inc., Intel Corporation, Hewlett Packard Enterprise Company, Google LLC, Oracle Corporation, GridGain Systems Inc., Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Grid Computing Market Shifts & Advancements
Workload portability demands are dissolving the boundary between institutional clusters and hyperscale clouds, while regulatory pressure on computational provenance is elevating middleware with built-in audit capabilities.
Edge-native grid nodes are miniaturizing. These containerized compute pods embed storage-class memory and programmable NICs to execute inference workloads within manufacturing plants and clinical trial sites. Automotive suppliers in Stuttgart and Wolfsburg are deploying these units for real-time generative design loops. The technology is miniaturizing the acceptable latency envelope for grid participation, enabling shop-floor integration previously impossible with centralized architectures.
REACH substance registration requirements are expanding computational toxicology mandates. ECHA's 2024 updates now accept QSAR predictions only from validated grid-based workflows with documented hardware configurations and software versioning. Contract research organizations operating across Basel, Rotterdam, and Antwerp are retrofitting legacy clusters with blockchain-anchored provenance logs. The regulation is compressing competitive differentiation to audit infrastructure rather than raw simulation throughput.
Consortium-based procurement is consolidating buyer power. Mid-sized biotech firms in Cambridge, Massachusetts and Research Triangle Park are pooling grid capacity reservations through shared middleware layers, displacing individual enterprise licenses. These collectives negotiate directly with infrastructure vendors for dedicated node slices rather than competing for spot market capacity. The pattern is most visible in immuno-oncology therapeutic areas where simulation workloads spike unpredictably around IND filing deadlines.
Global Grid Computing Market Segmentation
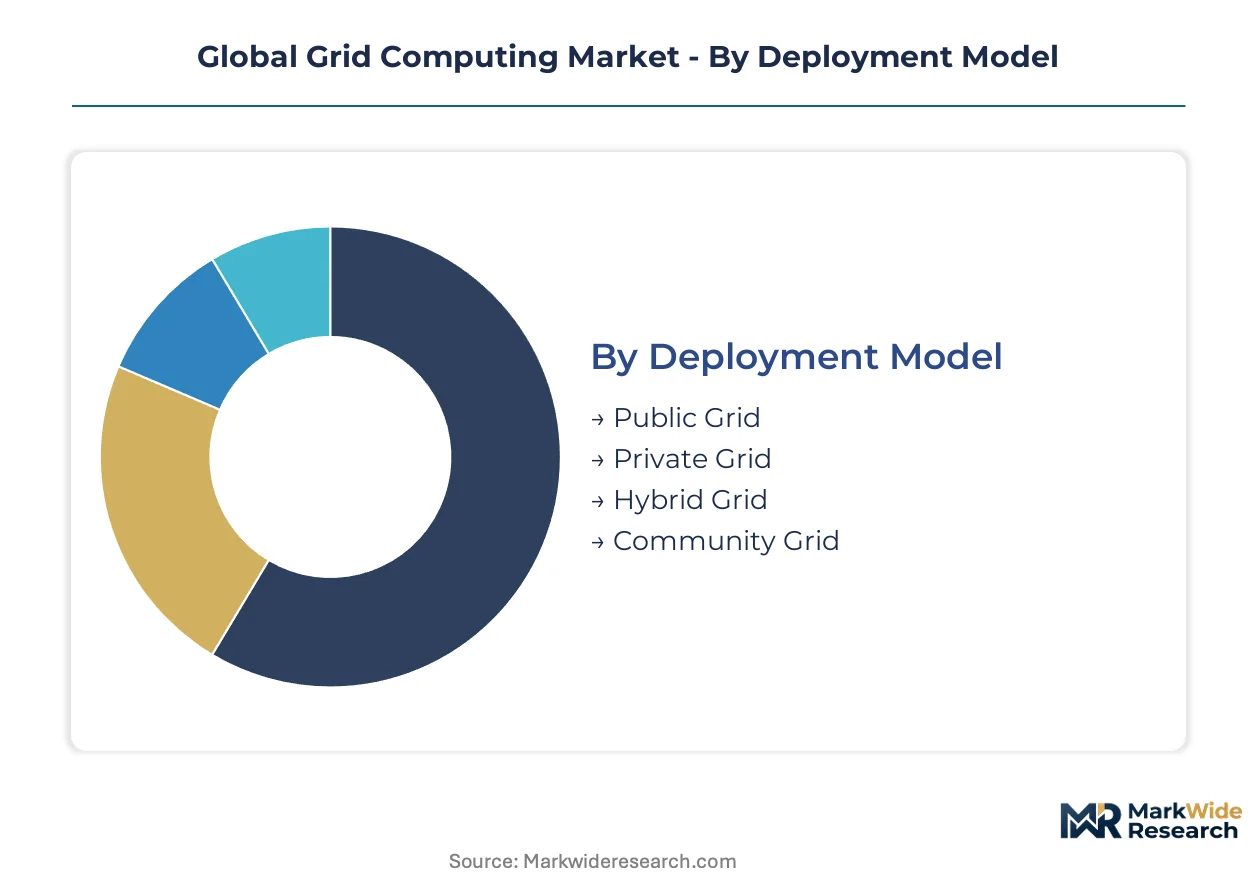
Grid computing markets fragment across deployment architectures, technology layers, and institutional use cases that dictate middleware requirements and compliance postures. Procurement patterns diverge sharply between burst-capacity financial clients and sovereignty-constrained pharmaceutical operators.
Deployment Model:
Channel mix varies by data sensitivity: public grids flow through hyperscale marketplaces, private grids through direct vendor relationships, hybrid through systems integrators, and community grids through academic consortia.
- Hybrid Grid:Architectures orchestrate on-premises clusters with burst capacity into public clouds via containerized middleware. Pharmaceutical firms in Basel and Boston dominate demand as they balance molecular simulation control with elastic scaling for IND filing spikes.
- Private Grid:Dedicated infrastructure serves defense contractors and central banks requiring air-gapped computational environments. German automotive R&D consortia anchor European demand for sovereign battery chemistry simulations under EU AI Act audit mandates.
- Public Grid:Shared utility models attract mid-sized quantitative hedge funds seeking spot-market GPU cycles without capital commitment.
- Community Grid:Academic and nonprofit resource pools aggregate idle institutional capacity for climate modeling and genomic epidemiology.
By volume, Private Grid leads. By growth pace, Hybrid Grid is expanding most quickly.
Technology:
Cost tiers stratify by infrastructure intensity: computational grids command premium hardware spend, data grids mid-tier storage investment, knowledge grids experimental R&D budgets.
- Computational Grid:MPI-optimized clusters execute tightly coupled physics simulations across InfiniBand fabrics. Quantitative finance desks in London and Singapore drive transaction volume for derivatives pricing and risk aggregation workloads.
- Knowledge Grid:Semantic inference architectures integrate distributed ontologies for AI training pipelines. EU-funded research consortia exploring GDPR-compliant federated learning represent the primary demand concentration.
- Data Grid:Federated storage systems enable cross-border genomic dataset sharing with cryptographic provenance logging.
- Service Grid:Utility-computing middleware exposes grid resources through standardized web service interfaces.
- Sensor Grid:Edge-aggregated IoT streams feed real-time manufacturing quality control in Stuttgart automotive plants.
Computational Grid captures dominant revenue share. Knowledge Grid shows steepest expansion trajectory.
Application:
Customer type determines procurement modality: academic computing flows through grant-funded consortia, financial modeling through direct enterprise licensing, scientific research through hybrid cloud contracts.
- Scientific Research:Multi-institutional collaborations in particle physics and materials discovery consume the largest aggregate core-hours. CERN and DESY coordinate cross-border grid scheduling for detector simulation pipelines.
- Financial Modeling:Monte Carlo derivatives pricing and regulatory stress testing demand low-latency interconnects. Basel III compliance deadlines compress deployment timelines for European systemic banks.
- Weather Forecasting:National meteorological services run ensemble prediction systems across federated supercomputing centers.
- Media Rendering:Visual effects studios burst animation workloads into cloud grids during production crunches.
- Academic Computing:University shared-utility clusters serve departmental research with queue-based allocation.
Scientific Research leads by installed base. Financial Modeling gains share fastest.
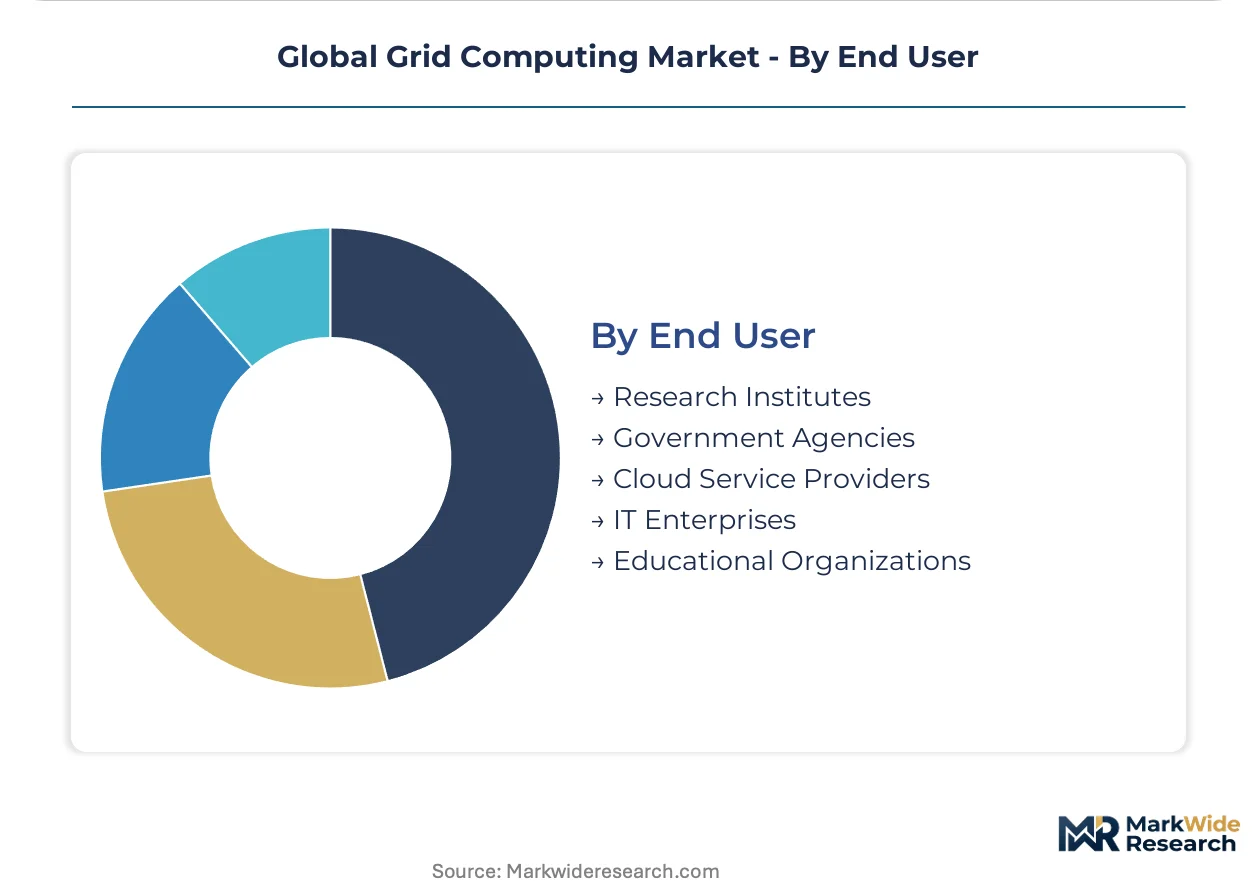
End User:
Margin profiles diverge by sophistication: cloud service providers extract platform fees, research institutes negotiate subsidized academic rates, government agencies mandate sovereign compliance.
- Research Institutes:Fraunhofer Society and Max Planck facilities anchor German grid infrastructure for automotive and battery materials simulation. Grant-funded procurement cycles align with EU research framework program timelines.
- Cloud Service Providers:Hyperscale operators resell managed grid middleware to enterprises avoiding capital expenditure. AWS and Azure compete for pharmaceutical burst-workload contracts with compliance-certified environments.
- Government Agencies:Defense and intelligence grids require domestic node residency under classified processing mandates.
- IT Enterprises:Fortune 500 technology firms internalize grid capacity for product development and supply chain optimization.
- Educational Organizations:K-12 and undergraduate institutions access discounted community grid resources for curriculum integration.
Research Institutes dominate by node count. Cloud Service Providers climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for grid infrastructure concentrates in German industrial consortia, while cost-sensitive pharmaceutical operators in India compress margins through consortium-based procurement.
United States
Quantitative hedge funds in New York and Chicago drive spot-market GPU cycle demand for Monte Carlo derivatives pricing. FDA computational validation guidelines for pharmaceutical modeling mandate auditable grid audit trails, elevating compliance-certified middleware. Greater Boston biotech clusters pool grid capacity through shared reservation layers for immuno-oncology simulation spikes around IND deadlines.
Germany
Fraunhofer institutes and automotive R&D consortia anchor high-performance grid deployments for multiphysics battery chemistry modeling. EU AI Act cross-border compute governance requires documented distributed processing trails, accelerating certified infrastructure investments. Stuttgart and Wolfsburg automotive suppliers deploy edge-native grid nodes for real-time generative design loops within manufacturing plants.
China
MIIT cloud service classification rules and dual carbon goals constrain cross-border grid node residency, fragmenting pan-Asian compute fabrics. Provincial emissions targets restrict data center buildout locations for molecular simulation workloads. Yangtze River Delta research institutes navigate sovereign compute mandates against latency requirements for tightly coupled MPI workloads.
Saudi Arabia
NEOM and King Abdullah University of Science and Technology construct carbon-neutral grid facilities to attract pharmaceutical and climate modeling consortia seeking jurisdictional diversification. The national pharmaceutical regulator aligns computational infrastructure standards with emerging Gulf data sovereignty frameworks. Riyadh-based operators secure long-term renewable power purchase agreements through green hydrogen co-location strategies.
United Kingdom
London financial modeling desks demand low-latency interconnects for regulatory stress testing under compressed Basel III compliance timelines. EMA data integrity requirements for clinical trial simulations impose retrospective computational provenance reconstruction costs on pharmaceutical grid operators. Cambridge biotech firms participate in consortium-based procurement pools displacing individual enterprise licenses.
Global Grid Computing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with specialized HPC engineering capabilities bifurcating competitive positioning. The vendor base stratifies across three tiers: hyperscale cloud operators reselling managed middleware, legacy systems integrators with academic supercomputing partnerships, and container-native specialists collapsing deployment friction. Dominant competitive moves include strategic partnerships between infrastructure vendors and pharmaceutical R&D clusters, plus geographic expansion into sovereign compute jurisdictions with carbon-neutral mandates.
Within the legacy enterprise tier, IBM Corporation leverages long-standing academic supercomputing partnerships to sustain pipeline visibility for molecular simulation workloads. Dell Technologies Inc. anchors commercial grid infrastructure sales through direct enterprise relationships and modular server architectures. Among hyperscale operators, Amazon Inc. competes for pharmaceutical burst-workload contracts with compliance-certified cloud environments.
| Leading Market Players |
|---|
| IBM Corporation |
| Dell Technologies Inc. |
| Amazon Inc. |
| Intel Corporation |
| Hewlett Packard Enterprise Company |
| Google LLC |
| Oracle Corporation |
| GridGain Systems Inc. |
| Microsoft Corporation |
| Others |
Supply & Pricing Matrix
Forty-week lead times for NVIDIA H100 GPU allocations concentrate pricing power with Taiwanese foundry operators and compress margins for European pharmaceutical grid operators facing EMA audit mandates. This inventory tightness amplifies the customization premium for MPI-optimized InfiniBand clusters while forcing mid-sized biotech firms toward consortium-based procurement pools.
Pricing Analysis
The customization-premium spread widens to three-to-one between configured-to-order private grid deployments and standard public grid spot pricing. Three-tier pricing structure across premium certification-grade, standard enterprise, and economy academic tiers separates pharmaceutical operators with FDA validation requirements from hedge funds seeking raw compute cycles. Pricing pressure stems from NVIDIA GPU supply concentration extending procurement timelines for quantitative finance clients. Mid-sized biotech firms in Cambridge and Research Triangle Park exhibit highest price sensitivity, while defense contractors with air-gapped mandates show lowest elasticity.
Supply Chain Analysis
Inventory tightness for AI accelerators anchors supply concentration in Taiwan, South Korea, and the United States, with foundry capacity constraints propagating through German automotive R&D consortia. Critical component dependencies include high-bandwidth memory modules from SK Hynix and Micron, plus InfiniBand switches from NVIDIA's Mellanox division. Single-source vulnerability in advanced packaging feeds from TSMC's CoWoS capacity limitations. Distribution runs through direct vendor relationships for private grids, hyperscale marketplaces for public capacity, and academic consortia for community resource pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of systems programmers fluent in Open MPI tuning and InfiniBand topology optimization constrains deployment velocity for molecular simulation workloads across Basel and Boston pharmaceutical clusters. This capability gap widens competitive moats for incumbents with established academic partnerships while elevating acquisition premiums for specialized HPC engineering teams.
For Market Incumbents: Secure exclusive capacity reservations with Taiwanese foundry operators to buffer against GPU supply volatility threatening quantitative finance deployment schedules. Deepen backward integration into container-native middleware development to collapse deployment friction for life sciences genomic alignment pipelines. Fortify academic supercomputing partnerships at Fraunhofer institutes and CERN to sustain talent pipeline visibility against emerging cloud-native competitors. For New Entrants and Emerging Players: Lead with Kubernetes-native grid orchestration targeting mid-sized biotech consortiums in Cambridge and Research Triangle Park where individual enterprise license displacement creates white-space opportunity. Penetrate the Saudi sovereign compute market through carbon-neutral facility partnerships with NEOM and King Abdullah University of Science and Technology. Differentiate via differential privacy frameworks enabling GDPR-compliant federated learning grids for EU research consortia. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy systems integrators with stranded academic supercomputing assets and underutilized MPI engineering benches. Long-term viability hinges on middleware vendors capturing pharmaceutical compliance certification workflows as EMA audit trail mandates harden. Watch for inflection signals in container-native grid deployment velocity at European automotive R&D clusters as indicator of architectural transition momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership with Academic Supercomputing Centers | IBM's Fraunhofer alliances sustain pipeline visibility for molecular simulation workloads against cloud-native entrants. |
| Green Hydrogen Co-location Agreement | Nordic operators secure renewable PPAs adjacent to electrolyzer facilities attracting ESG-constrained European research budgets. |
| Container-Native Middleware Acquisition | Dell collapses deployment friction for Kubernetes-native genomic alignment pipelines at Boston pharmaceutical clusters. |
| Sovereign Compute Facility Buildout | NEOM carbon-neutral grid construction attracts pharmaceutical consortia seeking jurisdictional diversification beyond EU AI Act jurisdiction. |
| Compliance-Certified Cloud Environment Launch | Amazon captures pharmaceutical burst-workload contracts requiring FDA-validated computational provenance logging. |
Research Methodology
The analysis maps computational grid, knowledge grid, data grid, and sensor grid sub-sectors, each validated through HPC engineering directors, pharmaceutical IT procurement officers, cloud infrastructure architects, and academic research computing leads. Primary interviews with grid middleware vendors and hyperscale operator strategy teams combined with secondary validation from SEC hyperscaler capex disclosures, EU research framework program funding databases, and FDA computational validation guidance documents. Bottom-up node deployment tallies triangulated against top-down infrastructure spending estimates across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across deployment model, technology layer, application vertical, and regional regulatory cluster dimensions. CAGRs derived from regression analysis of historical infrastructure procurement cycles and projected demand elasticity for molecular simulation workloads. Industry-specific forecast inputs included MPI workload growth rates at CERN and DESY, plus GPU allocation lead-time observations from Taiwanese foundry operators.
The analysis sits within stated boundaries; outcomes outside sustained NVIDIA supply constraints or EU AI Act enforcement intensity would require recalibration. Forecasts reflect assumptions regarding pharmaceutical R&D budget trajectories and sovereign compute mandate proliferation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Global Server Virtualization Market
Cloud Computing
ASEAN Cloud Computing Market
Cloud Computing
Cloudifier Market
Cloud Computing
Cloud-Based Repository Services Market
Cloud Computing
Saudi Arabia Cloud Computing Market
Cloud Computing
Philippines ICT Market
Cloud Computing
Cloud Computing Stack Layers Market
Cloud Computing
Indonesia Cloud Market
Cloud Computing
High-Performance Computing (HPC) As a Service Market
Cloud Computing
Cloud Based Information Governance Market
Cloud Computing
UK Cloud Computing Market
Cloud Computing
Multi-Cloud Networking Market
Cloud Computing
Cloud ECS Market
Cloud Computing
Cloud Data Quality Monitoring Market
Cloud Computing
North America Healthcare Cloud Computing Market
Cloud Computing
Dbaas and Cloud Database Market