
 Fig Glycolic Extract Market | 2026-2036
Fig Glycolic Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Fig Glycolic Extract Market Analytics
Prestige skincare formulators is reorganizing purchasing priorities toward botanical acid sources as mass-market brands lag in ingredient transparency. Greentech leverages its French biotechnology heritage to dominate fermentation-derived extraction pathways. Croda International anchors global supply through its lipid and active ingredient distribution networks. Advanced Biotech specializes in small-batch phytochemical refinement for North American clean beauty labels.
Fig glycolic extract comprises alpha-hydroxy acids isolated from Ficus carica fruit through aqueous or enzymatic extraction, typically standardized to specific titratable acidity for cosmetic compatibility. The extract functions primarily as a gentle exfoliant and cell-renewal agent in topical formulations, replacing petroleum-derived glycolic acid in prestige and natural-positioned product lines. Organic and natural product type segments command premium positioning as certification schemes tighten allowable synthetic residuals. Skincare and cosmetics applications absorb the majority of volume, with hair care emerging as a faster-growing adjacency as scalp health formulations proliferate. E-commerce and beauty salons represent contrasting end-user channels where the former scales reach while the latter validates professional efficacy claims.
EMA cosmetic ingredient safety assessments and REACH Annex XVII restrictions on synthetic acid concentrations shape formulation migration toward botanical alternatives in Europe. FDA cosmetic labeling requirements and impending MoCRA enforcement in the United States pressure brands to substantiate natural origin claims with traceable supply documentation. Stakeholders must monitor regulatory divergence between jurisdictions where botanical acid thresholds and permissible marketing claims are tightening asynchronously.
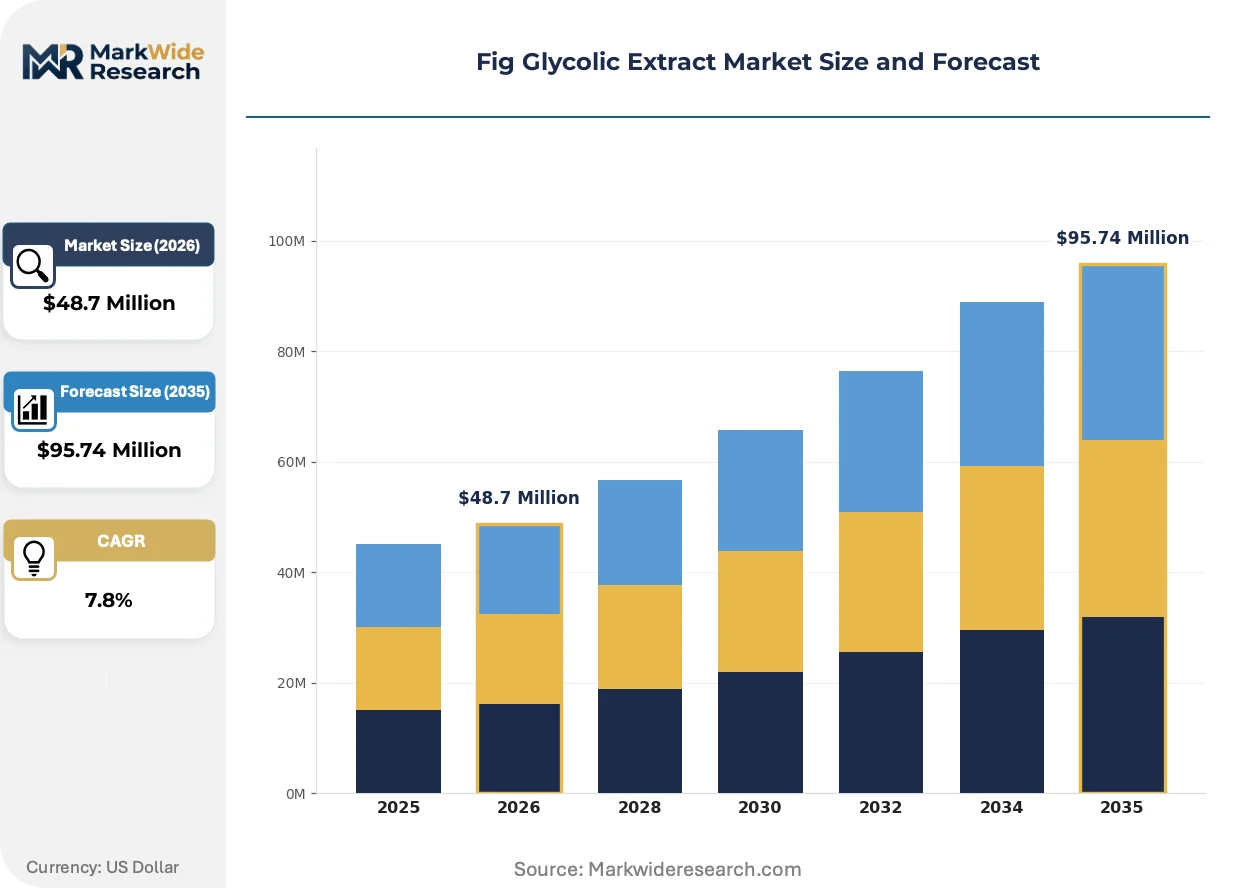
Market Dynamics
REACH Annex XVII restrictions on synthetic acid concentrations are forcing prestige cosmetic formulators to requalify supply chains around fermentation-derived botanical alternatives, concentrating procurement authority with biotechnology clusters in France and contract manufacturers serving clean beauty labels.
Growth Catalysts
- REACH synthetic acid thresholds:European formulators face tightening permissible concentrations for petroleum-derived glycolic acid in leave-on cosmetic products, accelerating technical validation of fig-derived titratable acidity as a compliant replacement pathway.
- Scalp health formulations:Hair care applications for fig glycolic extract are expanding beyond facial skincare as brands develop pre-shampoo treatments and scalp renewal serums targeting microbiome balance.
- Fermentation biotechnology:Enzymatic extraction methods are reducing batch-to-batch acidity variation compared to aqueous processes, improving cosmetic-grade standardization for multinational formulators.
Market Restraints
- Input cost volatility:Organic Ficus carica fruit supply fluctuates with Mediterranean harvest cycles, compressing margin predictability for extraction facilities dependent on certified organic feedstock.
- Extraction capacity concentration:Commercial-scale fermentation infrastructure for cosmetic-grade glycolic acid remains clustered around Grasse and Toulouse, creating geographic single-source vulnerability for North American brands.
- Petrochemical substitute pricing:Synthetic glycolic acid from ethylene glycol oxidation maintains cost advantages at industrial scale, limiting botanical penetration in mass-market exfoliant formulations.
Strategic Opportunities
- MoCRA traceability mandates:FDA cosmetic facility registration and product listing requirements create competitive opening for suppliers with documented batch-level botanical origin verification.
- Professional salon channel:Medical aesthetic clinics and licensed estheticians represent underpenetrated distribution for professional-strength fig glycolic peels with controlled titration protocols.
- Biotech-convergence formulations:Pairing fig-derived acids with postbiotic ferments enables next-generation scalp microbiome products targeting seborrheic conditions and follicular health.
Industry Challenges
- Cosmetic chemist specialization:Formulation science expertise at the intersection of botanical extraction titration and skin penetration kinetics remains scarce, extending product development timelines for brands without in-house phytochemistry capabilities.
- Organic certification latency:ECOCERT and COSMOS approval cycles for new extraction facilities average 18-24 months, delaying market entry for capitalized entrants targeting premium positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fig Glycolic Extract Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $95.74 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Natural, Synthetic, Blended Application: Cosmetics, Skincare, Nutraceuticals, Hair Care End User: Beauty Salons, E-commerce, Retail Outlets, Manufacturers Packaging Type: Glass Bottles, Plastic Containers, Sachets, Jars |
| Companies Covered | Greentech, Advanced Biotech, Croda International, Marc Jacobs, Stonewall Kitchen, Rosebud Preserves, Newmans Own, Hiya India, The Chemours Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fig Glycolic Extract Market Evolving Landscape
Biotechnology-enabled extraction standardization is reshaping competitive access to cosmetic-grade botanical acids, while regulatory documentation requirements and channel fragmentation are redefining how suppliers demonstrate efficacy and provenance.
Enzymatic fermentation of Ficus carica pulp is supplanting traditional aqueous maceration as the dominant extraction pathway for cosmetic applications. Prestige skincare laboratories in France and California are adopting this method to achieve tighter titratable acidity specifications required for professional peel formulations. The technology is compressing minimum viable batch sizes and enabling small-batch phytochemical refinement previously uneconomical at commercial scale.
EMA cosmetic ingredient safety assessments and REACH Annex XVII amendments are tightening concentration thresholds for synthetic alpha-hydroxy acids in rinse-off and leave-on products. European formulators are responding by requalifying supply chains around botanical acid sources with documented dermatological safety profiles. This regulatory pressure concentrates procurement decisions with biotechnology suppliers possessing established cosmetic dossier libraries.
Clean beauty certification is becoming a non-negotiable filter in professional channel purchasing. Licensed estheticians and medical aesthetic clinics in France and the United States are requiring ECOCERT or COSMOS documentation before stocking professional-strength exfoliant treatments. This behavioral shift privileges suppliers with vertically controlled organic feedstock and extraction certification, marginalizing traders without captive agricultural relationships.
Fig Glycolic Extract Market Segmentation
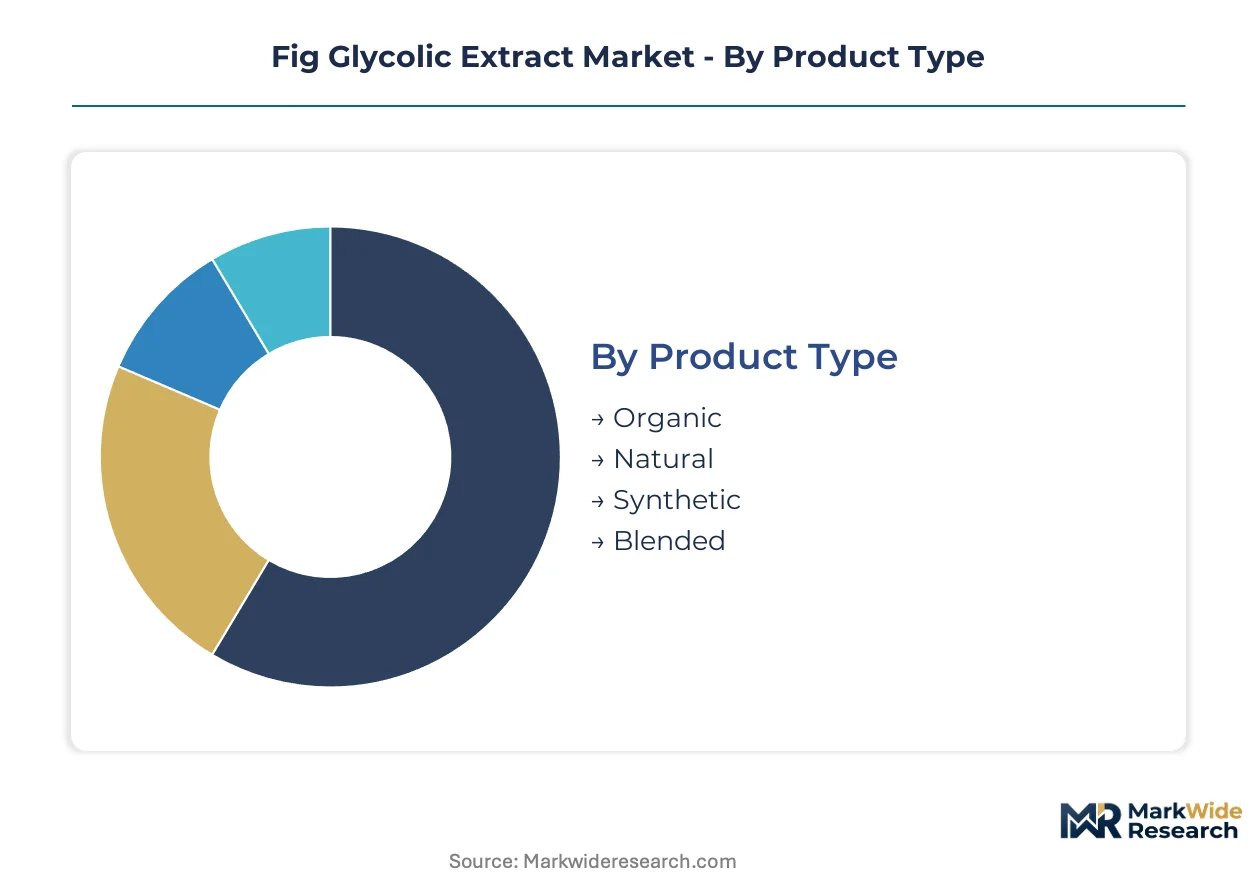
Segmentation in fig glycolic extract procurement reveals how certification tiers, application channels, and packaging formats fragment purchasing authority across distinct stakeholder groups with divergent technical requirements.
Product Type:
Organic and natural grades dominate export flows toward European and North American premium formulators, while synthetic and blended variants serve cost-sensitive domestic manufacturers in Asia-Pacific markets.
- Organic:Certified organic Ficus carica fruit undergoes ECOCERT or COSMOS-validated extraction with zero synthetic residual tolerance. French biotechnology clusters around Grasse supply the majority of this grade to prestige skincare laboratories seeking documented botanical provenance for MoCRA compliance.
- Natural:Non-certified natural extraction permits trace synthetic processing aids, achieving lower unit costs while retaining clean beauty positioning. Demand concentrates in mid-tier cosmetics manufacturers across Germany and California balancing certification overhead with marketing claims.
- Synthetic:Petrochemical-derived glycolic acid blended with fig extracts for flavoring claims serves mass-market exfoliant producers in China and India where cost minimization overrides botanical purity requirements.
- Blended:Hybrid formulations combine fig-derived acids with other botanical AHAs to achieve specific titratable acidity targets at reduced input cost. Hair care brands developing scalp microbiome products favor this grade for formulation flexibility.
Organic commands the established base. The steepest expansion runs through Natural as mid-tier brands accelerate certification adoption without absorbing full organic premium.
Application:
Volume distribution across applications reflects divergent regulatory exposure, with leave-on facial products facing stricter REACH Annex XVII thresholds than rinse-off hair formulations.
- Cosmetics:Color cosmetics and makeup primers incorporate fig glycolic extract at low concentrations for surface smoothing without visible peeling effects. Prestige brands in France and the United States lead procurement as they reformulate away from synthetic acid bases ahead of tightening FDA labeling enforcement.
- Skincare:Facial serums, moisturizers, and professional peels represent the dominant volume sink, with titratable acidity specifications ranging from consumer-grade daily use to clinic-strength controlled exfoliation. California clean beauty labels and Parisian dermatological laboratories anchor demand concentration.
- Nutraceuticals:Oral supplements and functional beverages leverage fig extract for antioxidant positioning rather than exfoliant function. Regulatory divergence between FDA dietary supplement rules and EFSA novel food assessments fragments market access pathways.
- Hair Care:Pre-shampoo scalp treatments and follicular health serums are expanding most quickly as microbiome positioning penetrates professional salon channels. Korean and Australian brands pioneer this adjacency with fermentation-derived extract variants.
Skincare retains volume leadership. Hair Care is climbing the fastest as scalp health formulations migrate from niche professional use toward mainstream retail positioning.
End User:
Channel concentration patterns reveal how documentation requirements and batch-size economics split procurement authority between high-touch professional validation and scaled direct-to-consumer reach.
- Beauty Salons:Licensed estheticians and medical aesthetic clinics demand professional-strength formulations with controlled titration protocols and batch-level traceability documentation. This channel validates efficacy claims that subsequently support premium pricing in retail.
- E-commerce:Direct-to-consumer platforms enable clean beauty brands to scale reach without retail margin stacking, though they require consumer-education investments to communicate botanical acid differentiation against cheaper petrochemical alternatives.
- Retail Outlets:Sephora, Ulta, and comparable prestige retailers filter assortment through clean beauty certification requirements, concentrating shelf access with suppliers possessing vertically controlled organic feedstock.
- Manufacturers:Contract manufacturers serving private-label brands aggregate fragmented demand into larger batch orders, though they typically specify blended or synthetic grades to maintain cost competitiveness for mass-market positioning.
Manufacturers command the established base. Beauty Salons represent the steepest expansion trajectory as professional channel validation becomes prerequisite for premium retail placement.
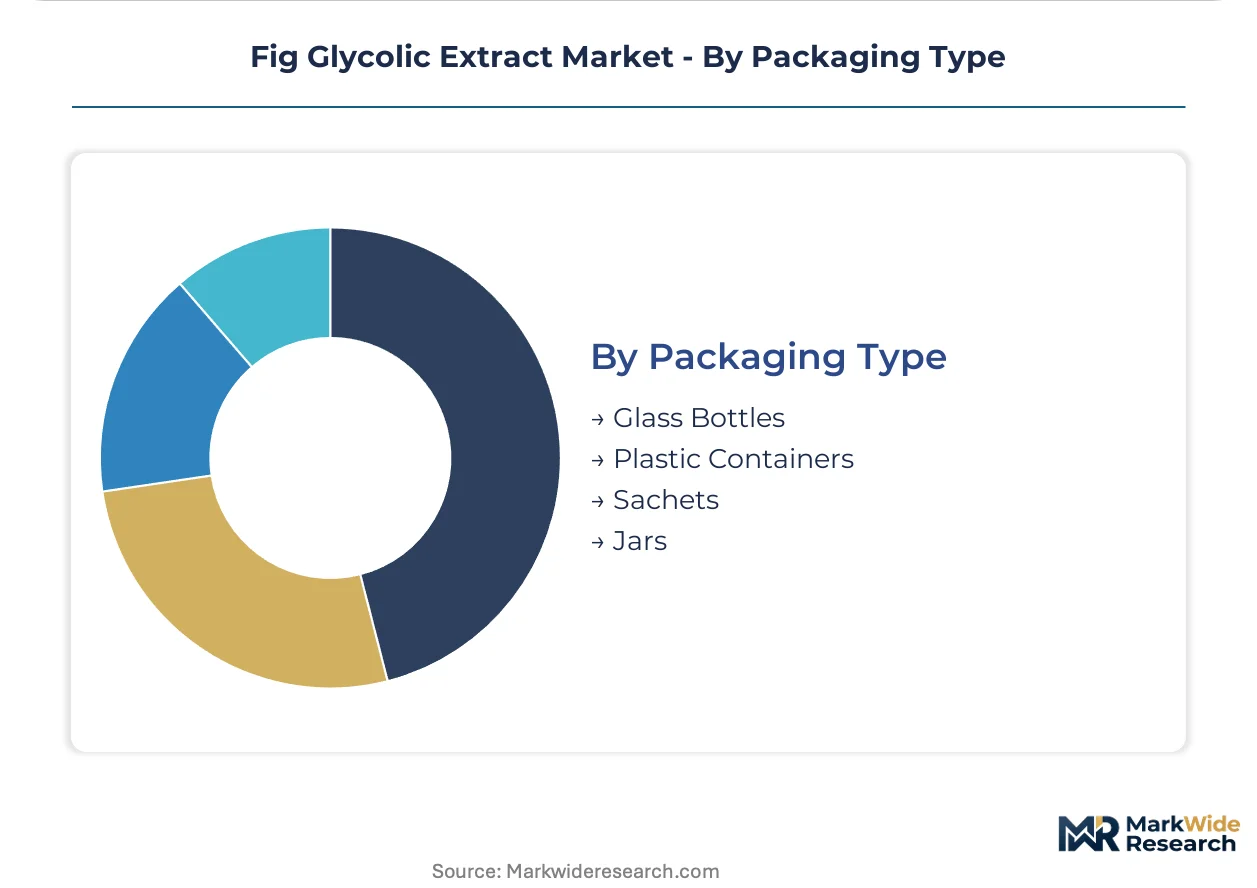
Packaging Type:
Packaging selection tracks application viscosity, oxidation sensitivity, and channel-specific presentation requirements from clinical minimalism to unboxing experience.
- Glass Bottles:Amber and cobalt glass dominates professional serum and oil formulations, providing UV protection and premium tactile signaling for salon and prestige retail placement.
- Plastic Containers:Airless pump systems in opaque polymers balance cost reduction with oxidation protection for mid-tier daily skincare distributed through e-commerce and mass retail.
- Sachets:Single-use foil sachets enable sampling programs and travel-size positioning, with Korean beauty brands pioneering this format for exfoliant sheet masks and scalp treatment ampoules.
- Jars:Wide-mouth jars accommodate thicker cream and mask consistencies, though they require robust preservative systems given repeated air exposure during use.
Plastic Containers command the established base. Glass Bottles show the steepest expansion as premiumization and sustainability positioning drive material upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Marseille-Fos anchors Mediterranean feedstock flows for French extraction clusters, while Rotterdam's chemical handling infrastructure distributes botanical acids across Northwestern European formulators. Rail links from Grasse to Paris and Lyon channel cosmetic-grade outputs toward prestige laboratories.
France
Grasse biotechnology corridors supply fermentation-derived fig glycolic extract to Parisian dermatological laboratories reformulating professional peel lines. REACH Annex XVII synthetic acid thresholds accelerate technical validation of botanical titratable acidity. Toulouse extraction facilities expand enzymatic capacity to serve California clean beauty labels seeking ECOCERT documentation.
United States
FDA cosmetic facility registration under MoCRA pressures brands toward traceable botanical supply chains with batch-level origin verification. California clean beauty formulators in Los Angeles and San Francisco anchor procurement for prestige skincare repositioning away from petrochemical exfoliants. New York-based medical aesthetic clinics demand professional-strength formulations with controlled titration protocols.
Germany
Mid-tier cosmetics manufacturers in Hamburg and Munich balance ECOCERT overhead against clean beauty marketing claims, driving natural-grade procurement. ECHA enforcement of REACH concentration limits forces requalification of synthetic acid inventories. Düsseldorf-based contract manufacturers aggregate fragmented demand into larger batch orders for blended-grade specifications.
China
Mass-market exfoliant producers in Shanghai and Guangzhou favor cost-minimized synthetic and blended grades where petrochemical substitutes maintain industrial-scale pricing advantages. NMPA cosmetic ingredient filing requirements lag European thresholds, slowing botanical acid migration. Domestic Ficus carica cultivation in Sichuan and Yunnan provinces expands organic feedstock potential for export-oriented extraction facilities.
South Korea
Seoul-based hair care brands pioneer scalp microbiome formulations using fermentation-derived fig glycolic variants in pre-shampoo treatments and ampoule formats. MFDS cosmetic safety assessments align with EMA dermatological standards, easing European export pathways. Busan port infrastructure handles inbound Mediterranean botanical acid shipments for formulation re-export across Asia-Pacific markets.
Fig Glycolic Extract Market Competitive Landscape
Concentration sits with biotechnology specialists possessing vertically controlled organic feedstock and established cosmetic dossier libraries. French extraction clusters around Grasse dominate fermentation-derived pathways, while North American contract manufacturers serve clean beauty labels through small-batch phytochemical relationships. Three archetypes define competitive positioning: biotechnology heritage suppliers with captive agricultural networks, global ingredient distributors anchoring multinational supply chains, and regional refinement specialists targeting certification-intensive premium segments. Dominant competitive moves include backward integration into organic Ficus carica cultivation and technology licensing agreements for enzymatic extraction standardization.
Within the biotechnology heritage tier, Greentech exemplifies French fermentation expertise leveraging Grasse proximity to cosmetic laboratories. Advanced Biotech occupies a position among North American specialists serving clean beauty labels with documented batch-level traceability. Croda International represents the global distribution archetype, anchoring supply chain access through lipid and active ingredient networks spanning European and North American formulators.
| Leading Market Players |
|---|
| Greentech |
| Advanced Biotech |
| Croda International |
| Marc Jacobs |
| Stonewall Kitchen |
| Rosebud Preserves |
| Newmans Own |
| Hiya India |
| The Chemours Company |
| Others |
Value Network & Pricing Analysis
Botanical acid substitution for petroleum-derived glycolic acid simultaneously redistributes procurement gravity toward French biotechnology clusters and compresses margin tolerance for extraction facilities facing organic feedstock cost volatility. REACH Annex XVII synthetic acid thresholds concentrate buyer power with fermentation-capable suppliers while Mediterranean harvest cycles inject seasonality into raw material pricing.
Pricing Analysis
Volume-discount tiering structures separate organic ECOCERT-certified grades from natural and blended specifications, with certification overhead driving 40-60% price elevation at the premium tier. Price differentiation rests on titratable acidity standardization and batch-level traceability documentation demanded by MoCRA-compliant brands. Cost compression in mid-tier natural grades is intensifying as German and California manufacturers accelerate certification adoption without absorbing full organic premiums. Mass-market formulators in Asia-Pacific markets exhibit highest price sensitivity, while Parisian dermatological laboratories and New York medical aesthetic clinics prioritize documented provenance over unit cost.
Supply Chain Analysis
Inbound logistics costs from Mediterranean ports to North American formulation facilities have tightened container availability on Marseille-Los Angeles lanes, elevating landed cost premiums for ECOCERT-certified extracts. Geographic supply concentration centers on France, with secondary fermentation capacity emerging in South Korea and domestic cultivation expansion in China's Sichuan province. Raw material dependencies include organic Ficus carica fruit, enzymatic processing agents, and pharmaceutical-grade stabilization compounds. Single-source vulnerability characterizes commercial-scale extraction infrastructure clustered around Grasse and Toulouse. Distribution runs through Rotterdam's chemical handling facilities for European formulators and direct biotech-supplier relationships for California clean beauty labels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-entrenchment defensive moat, where REACH and MoCRA documentation requirements create switching costs that cement incumbent positioning against unqualified challengers.
For Market Incumbents: Shield market position by deepening backward integration into certified organic Ficus carica cultivation in Provence and Languedoc, eliminating feedstock vulnerability to Mediterranean climate volatility. Prioritize ECOCERT and COSMOS certification renewal acceleration to exploit 18-24 month approval latency barriers facing capitalized entrants. Capacity expansion in Toulouse enzymatic facilities addresses North American demand concentration while reinforcing geographic supply control against Korean fermentation competitors. For New Entrants and Emerging Players: COSMOS fast-track partnerships with established French agricultural cooperatives bypass the 18-24 month organic certification latency that blocks de novo extraction facilities. White-space concentration exists in professional salon channel distribution for controlled-titration scalp microbiome formulations, where Korean brands currently lead but European documentation standards create entry friction. California clean beauty labels seeking MoCRA-compliant botanical acid alternatives represent the most penetrable buyer segment, accessible through small-batch phytochemical refinement capabilities and batch-level traceability systems. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed French biotechnology specialists possessing Grasse-proximate fermentation infrastructure and established cosmetic dossier libraries but limited North American channel penetration. Five-to-ten year viability hinges on regulatory divergence persistence between REACH/MoCRA thresholds and lagging NMPA adoption in China, which sustains premium pricing for documented botanical provenance. Acquisition targets should demonstrate captive organic feedstock relationships rather than trader-dependent supply. The signal to watch is MFDS alignment with EMA dermatological standards, which would accelerate Korean formulation re-export competition and compress margin premiums for European suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captive Ficus carica supply in Provence eliminates Mediterranean harvest volatility exposure. |
| Enzymatic Extraction Capacity Expansion | Toulouse facility scale-up serves California clean beauty labels demanding ECOCERT documentation. |
| Professional Salon Channel Development | Medical aesthetic clinic partnerships validate efficacy claims supporting premium retail pricing. |
| MoCRA Traceability System Implementation | Batch-level origin verification meets FDA facility registration requirements for US market access. |
| Scalp Microbiome Formulation Partnerships | Postbiotic-ferment pairing with fig-derived acids targets seborrheic conditions in Korean hair care. |
Research Methodology
A standing panel of cosmetic formulation chemists, biotechnology extraction engineers, ECOCERT certification auditors, and professional esthetician purchasing managers provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA REACH Annex XVII amendment filings, FDA MoCRA facility registration databases, ECOCERT/COSMOS certification registries, and Mediterranean agricultural cooperative harvest reports. Bottom-up triangulation across extraction facility capacity audits and top-down reconciliation with prestige skincare brand procurement disclosures anchored volume estimates.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. The analytical framework modeled segmentation dimensions including certification grade tier, application channel, end-user channel type, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves incorporating REACH enforcement timelines and MoCRA implementation phases. Industry-specific forecast inputs included enzymatic extraction yield improvements and organic Ficus carica cultivation expansion rates in Sichuan province.
Decision-makers should treat outputs as directional under sustained regulatory divergence between European synthetic acid thresholds and lagging NMPA adoption in China; material deviation would warrant model refresh. Specific risk factors include MFDS-EMA alignment acceleration, Mediterranean climate disruption affecting organic harvests, and petrochemical glycolic acid cost breakthroughs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Irish Moss Extract Market
Extracts
Helichrysum Oil Market
Extracts
Orange Oil Market
Extracts
Peppermint Oil Market
Extracts
Global Pine-Derived Chemicals Market
Extracts
Marine Algae Polysaccharides Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
Global Herbal Extract Market
Extracts
Jalapeno Extract Market
Extracts
Potassium Hydrogen Tartrate Market
Extracts
Anise Extract Market
Extracts
Citronella Oil Market
Extracts
Sandalwood Oil Market
Extracts
China Cedar Wood Oil Market
Extracts
Hydroglycolic Extracts Market
Extracts
Organic Herbal Extracts Market