
 Peppermint Oil Market | 2026-2036
Peppermint Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Peppermint Oil Market Outlook
Multi-source agricultural procurement is consolidating around vertically integrated processors with direct farm relationships. Young Living Essential Oils leverages its Utah-based distillation infrastructure to control quality from seed to bottle. doTERRA anchors its sourcing through the Co-Impact Sourcing initiative across multiple growing regions. Lebermuth, Inc. competes as a bulk supplier to industrial flavor and fragrance houses, sustaining volume leadership through Midwestern processing capacity.
Peppermint oil is a steam-distilled volatile oil derived from Mentha piperita leaves, typically containing 35-55% menthol by weight alongside menthone and menthyl acetate, and serves as an active ingredient in pharmaceutical, food, and cosmetic formulations. Essential oil grades command premium positioning in therapeutic and aromatherapy channels where purity certification drives margin pools. Food grade supply concentrates within flavor houses serving confectionery and oral care manufacturers, while cosmetic grade volumes expand through clean-label personal care formulations. Aroma oil variants, often blended or diluted, occupy mass-market household and spa segments with thinner margins but higher throughput.
FDA's GRAS designation for peppermint oil in food applications shapes formulation standards for US-bound exports, while REACH registration requirements in Europe mandate full toxicological dossiers for high-volume natural substances. India's BIS certification for mentha oils creates a quality gate for domestic trading and export eligibility. Stakeholders must monitor evolving pesticide residue limits across import jurisdictions and invest in traceability infrastructure before compliance gaps disrupt market access.
Market Dynamics
Pharmaceutical formulators in Germany are expanding peppermint oil uptake for enteric-coated drug delivery systems, creating a demand pull that is restructuring procurement relationships across the value chain.
Growth Catalysts
- REACH Annex Updates:The EU's tightened purity documentation requirements for botanical extracts are forcing quality upgrades that favor certified suppliers with laboratory infrastructure.
- Enteric Coating Expansion:German pharmaceutical manufacturers are incorporating peppermint oil into delayed-release tablet formulations for irritable bowel syndrome therapeutics.
- Contract Farming Consolidation:India's mentha-growing belt around Uttar Pradesh and Bihar has organized into vertically coordinated supply networks serving international flavor houses.
Market Restraints
- Climate Volatility:Monsoon-dependent cultivation in Bihar and Uttar Pradesh creates yield instability that ripples through raw material pricing.
- Substitution Pressure:Synthetic menthol produced via Japanese-developed catalytic hydrogenation processes competes on cost for industrial flavor applications.
- Regulatory Documentation Burden:REACH registration mandates full toxicological dossiers that small-scale distillers cannot assemble without external laboratory partnerships.
Strategic Opportunities
- Clean-Label Personal Care:Cosmetic grade volumes are expanding through preservative-free formulations where peppermint oil serves dual function as fragrance and mild antimicrobial.
- Direct Farm Sourcing:Flavor houses are bypassing traditional auction markets to establish captive supply relationships with Indian mentha cultivator cooperatives.
- GRAS Alignment:FDA's food-grade designation for peppermint oil creates formulation standardization pathways for US-bound export consignments.
Industry Challenges
- Analytical Chemist Scarcity:Gas chromatography-mass spectrometry expertise for terpene profiling is concentrated among a handful of contract laboratories in Mumbai and Hyderabad.
- Residue Testing Backlogs:Pesticide screening protocols for export certification are creating shipment delays at Indian testing facilities during peak harvest windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peppermint Oil Market |
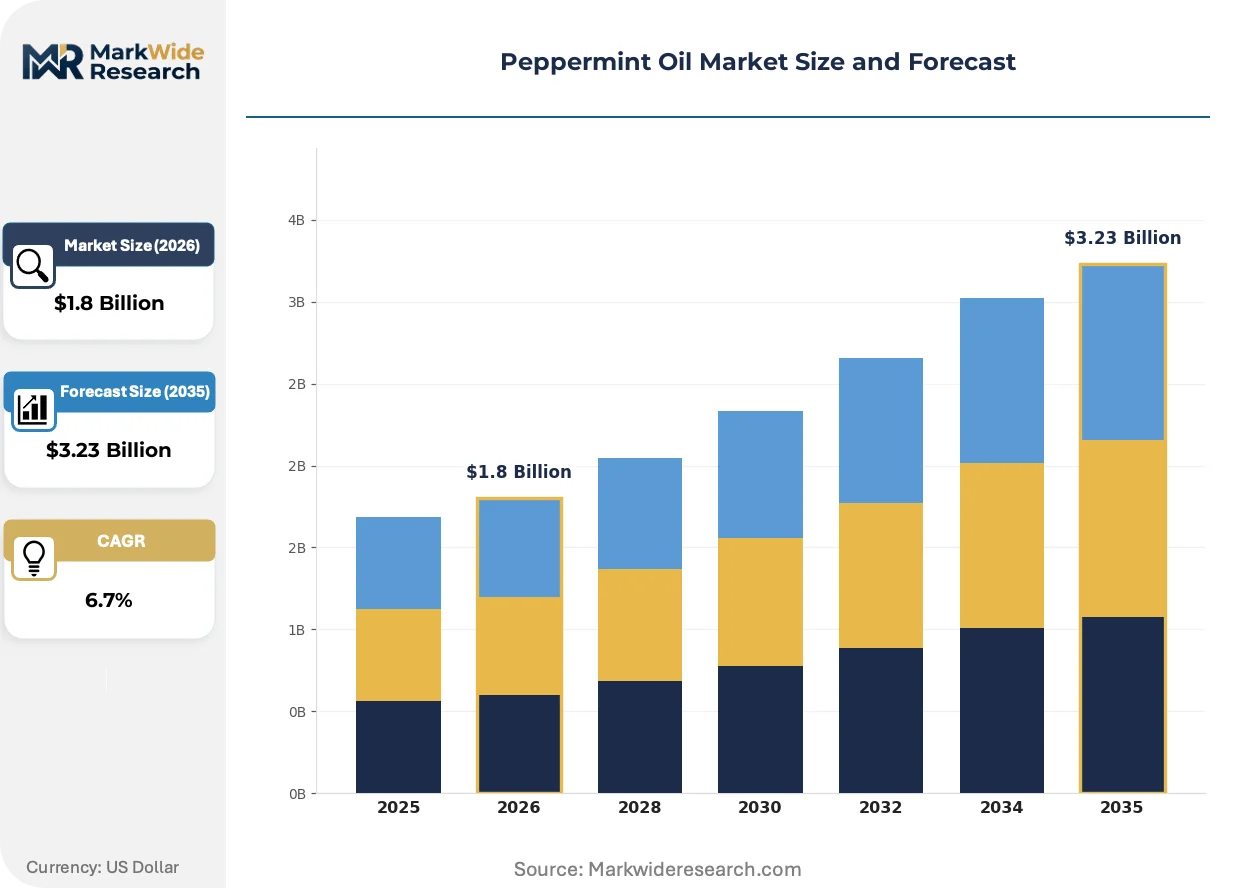
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oil, Aroma Oil, Food Grade, Cosmetic Grade End Use: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers Form: Liquid, Crystals, Capsules, Blends |
| Companies Covered | Young Living Essential Oils, doTERRA, Aromaaz International, Lebermuth, Inc., Aksu Vital Natural Products and Cosmetics, Mountain Rose Herbs, NOWER Foods, Plant Therapy Essential Oils, Greenleaf Extractions Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peppermint Oil Market Strategic Shifts
Steam distillation automation and traceability infrastructure are compressing batch-to-batch variability while regulatory data requirements are expanding documentation obligations across the supply base.
Supercritical CO2 extraction technology is automating the separation of peppermint oil's oxygenated fractions from hydrocarbon terpenes with precision that steam distillation cannot match. Pharmaceutical ingredient buyers in Germany and Switzerland are specifying CO2-derived grades for drug master file submissions. This automation is compressing the premium that therapeutic-grade oils command over conventional steam-distilled material.
REACH registration requirements for high-volume natural substances now mandate full substance identity profiles and extended safety data sets for botanical extracts imported above one tonne annually. European flavor houses are consolidating supplier panels to those with in-house regulatory affairs capacity. The food-grade segment is most affected, with manufacturers reformulating around documented supply chains rather than spot-market purchases.
Flavor house procurement teams are requiring blockchain-traceable batch records from Indian mentha processors as a condition of contract renewal. Direct farm relationships are displacing auction-based spot purchasing in the bulk supply tier. This behavioral shift is most visible in Uttar Pradesh, where processor-owned distillation units now coordinate harvesting schedules with cultivator cooperatives.
Peppermint Oil Market Segmentation
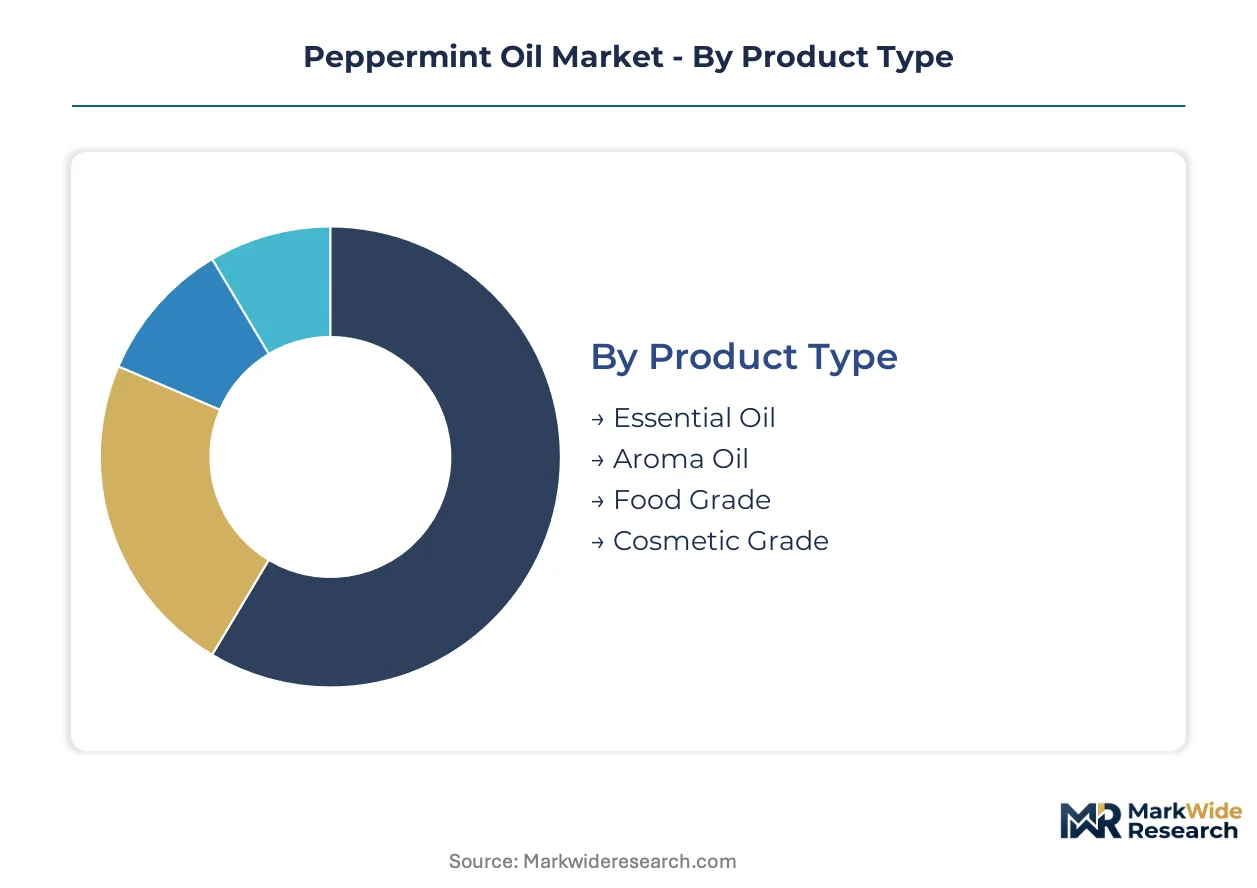
Peppermint oil segmentation reflects divergent capital requirements across extraction technologies and certification tiers. Processor investment decisions hinge on whether output targets pharmaceutical dossier standards or commodity flavor volumes.
Product Type:
Capital intensity peaks in segments demanding laboratory infrastructure for regulatory compliance and purity verification.
- Essential Oil:Steam-distilled volatile oil containing 35-55% menthol alongside menthone and menthyl acetate. German pharmaceutical formulators specify this grade for enteric-coated drug delivery systems where REACH-mandated toxicological dossiers filter out uncertified suppliers.
- Food Grade:Formulation-standardized supply meeting FDA GRAS designation for confectionery and oral care manufacturers. India's BIS-certified processors dominate export consignments to US-bound flavor houses seeking documentation alignment.
- Aroma Oil:Blended or diluted variants for mass-market household and spa applications. Thinner margins drive volume throughput rather than certification investment.
- Cosmetic Grade:Clean-label personal care formulations leveraging dual-function fragrance and mild antimicrobial properties.
Food Grade absorbs the bulk of installed capacity; Cosmetic Grade is expanding most quickly.
End Use:
Application maturity determines whether segments reward specification precision or cost minimization.
- Pharmaceuticals:Enteric coating applications for irritable bowel syndrome therapeutics. Swiss and German drug master file submissions specify supercritical CO2-extracted grades with automated terpene fractionation.
- Personal Care:Preservative-free formulations where peppermint oil replaces synthetic antimicrobials. Blockchain-traceable batch records are becoming mandatory for contract renewal.
- Food & Beverage:Confectionery and oral care manufacturing through established flavor house relationships. REACH registration requirements are consolidating supplier panels to those with in-house regulatory affairs capacity.
- Household Products:Mass-market diffusion and cleaning applications with lower specification barriers.
Food & Beverage commands the deepest supplier relationships; Pharmaceuticals is climbing the fastest.
Distribution Channel:
Channel selection reflects buyer scale and documentation requirements rather than consumer preference alone.
- Wholesalers:Bulk procurement by industrial flavor and fragrance houses with direct farm relationships in Uttar Pradesh and Bihar.
- Specialty Stores:Therapeutic-grade oils for aromatherapy practitioners demanding purity certification.
- Online Retail:Direct-to-consumer therapeutic and wellness positioning with traceability marketing.
- Supermarkets:Mass-market aroma oil placement with limited differentiation.
Wholesalers channel the highest volumes; Online Retail is gaining share fastest.
Form:
Physical form factors align with end-use handling requirements and dosing precision needs.
- Liquid:Standard steam-distilled output for formulation flexibility across pharmaceutical and flavor applications.
- Crystals:Menthol-rich solid fractions for controlled-release pharmaceutical and oral care specifications.
- Capsules:Unit-dose delivery for irritable bowel syndrome therapeutics with enteric coating compatibility.
- Blends:Pre-formulated combinations for spa and household diffusion markets.
Liquid form dominates processing infrastructure; Capsules show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical formulators in Germany are restructuring procurement relationships as enteric-coated drug delivery systems expand peppermint oil uptake. India's contract farming networks in Uttar Pradesh and Bihar now supply bulk raw material to international flavor houses. Switzerland and the United States complete the demand concentration map with distinct regulatory pathways shaping supply access.
Germany
Enteric coating applications for irritable bowel syndrome therapeutics drive pharmaceutical-grade demand. ECHA's REACH annex updates mandate full toxicological dossiers for botanical extracts above one tonne annually. The Baden-Württemberg cluster hosts flavor houses consolidating supplier panels to certified processors with in-house regulatory affairs capacity.
India
Contract farming networks in Uttar Pradesh and Bihar organize vertically coordinated supply to international buyers. BIS certification for mentha oils creates a quality gate for domestic trading and export eligibility. Processor-owned distillation units in Lucknow and Patna now coordinate harvesting schedules directly with cultivator cooperatives.
Switzerland
Drug master file submissions specify supercritical CO2-extracted grades for precision terpene fractionation. Swissmedic maintains stringent documentation requirements for natural substance pharmaceutical ingredients. Basel-area formulators source through captive relationships with Indian processors capable of blockchain-traceable batch records.
United States
Confectionery and oral care manufacturers anchor food-grade consumption through established flavor house relationships. FDA's GRAS designation for peppermint oil shapes formulation standards for import-bound consignments. Utah-based distillation infrastructure controls quality from seed to bottle for therapeutic-channel positioning.
Japan
Cosmetic grade volumes expand through preservative-free personal care formulations. METI guidelines on natural cosmetic ingredients emphasize purity verification for clean-label claims. Osaka-based fragrance houses source menthol-rich fractions for dual-function antimicrobial applications in skincare.
Peppermint Oil Market Competitive Environment
Backward integration into farm-level supply dominates the current landscape as processors establish captive raw material relationships. The vendor base stratifies across three tiers: vertically integrated specialists with seed-to-bottle control, bulk suppliers to industrial flavor houses, and direct-to-consumer wellness brands. Strategic archetypes include quality-certification leaders, volume-scale processors, and traceability-marketing specialists. M&A activity and direct farm sourcing partnerships represent the dominant competitive moves reshaping procurement relationships.
Within the vertically integrated tier, Young Living Essential Oils and doTERRA occupy positions emphasizing quality control from cultivation through distillation. Lebermuth, Inc. exemplifies the bulk supply archetype serving industrial flavor and fragrance houses. These three anchors illustrate how geographic concentration in processing infrastructure—Utah for therapeutic-grade distillation, Midwestern US for volume capacity—maps to distinct market positioning strategies.
| Leading Market Players |
|---|
| Young Living Essential Oils |
| doTERRA |
| Aromaaz International |
| Lebermuth, Inc. |
| Aksu Vital Natural Products and Cosmetics |
| Mountain Rose Herbs |
| NOWER Foods |
| Plant Therapy Essential Oils |
| Greenleaf Extractions Pvt. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between pharmaceutical dossier standards and commodity flavor volumes manifests in divergent margin pools and procurement relationship structures across the peppermint oil value chain. REACH-mandated toxicological documentation and FDA GRAS alignment create pricing power for certified processors, while spot-market auction purchasing compresses returns for undifferentiated bulk supply.
Pricing Analysis
Volume throughput in aroma oil and household product tiers runs at thinner margins than certification-heavy pharmaceutical and therapeutic grades. Three-tier pricing structure across premium, standard, and economy levels separates supercritical CO2-extracted pharmaceutical grades from steam-distilled food-grade volumes and blended aroma variants. Cost compression in the commodity tier is intensifying because synthetic menthol from Japanese-developed catalytic hydrogenation processes undercuts natural extraction on unit economics. Industrial flavor houses show highest price sensitivity; Swiss and German drug master file submitters demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Container freight volatility from Indian mentha-growing belt processors to European flavor houses and North American distributors has compressed working capital cycles for mid-tier traders. Geographic supply concentration centers on India, specifically Uttar Pradesh and Bihar contract farming networks, with secondary processing capacity in the United States and Germany. Raw material dependencies draw from Mentha piperita cultivar seeds, agricultural labor pools, and steam distillation or supercritical CO2 extraction equipment. Single-source vulnerability around monsoon-dependent cultivation in Bihar and Uttar Pradesh creates yield instability that ripples through raw material pricing. Distribution runs through processor-direct relationships with flavor houses, displacing traditional auction-market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints around analytical chemist scarcity for terpene profiling and pesticide residue testing backlogs prop pricing power for certified processors with in-house laboratory infrastructure.
For Market Incumbents: Acquire gas chromatography-mass spectrometry laboratory capacity in Mumbai or Hyderabad to internalize quality verification and reduce dependency on contract testing backlogs. Secure captive distillation relationships with Uttar Pradesh and Bihar cultivator cooperatives before flavor houses complete direct farm sourcing consolidation. Synthetic menthol substitution pressure and REACH documentation burdens threaten undifferentiated bulk suppliers; certification investment and backward integration into farm-level supply represent the primary defensive levers. For New Entrants and Emerging Players: Swiss and German pharmaceutical formulators seeking supercritical CO2-extracted grades with blockchain-traceable batch records represent an underserved buyer archetype with limited certified supplier panels. Clean-label personal care manufacturers in Japan and North America offer penetrable white-space for cosmetic-grade volumes with preservative-free antimicrobial positioning. Direct-to-online therapeutic channel positioning with seed-to-bottle traceability marketing provides a viable go-to-market angle against established wholesale relationships. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated processors given REACH registration consolidation forcing flavor houses to narrow supplier panels to certified operators. Long-term viability across the analysis window favors assets with direct farm relationships, in-house regulatory affairs capacity, and supercritical extraction infrastructure. The signal to watch as inflection indicator is blockchain-traceable batch record adoption becoming mandatory for contract renewal at major flavor houses.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm-Level Supply | Captive raw material relationships in Uttar Pradesh and Bihar insulate against monsoon yield volatility and auction-market price swings. |
| Supercritical CO2 Extraction Capacity Addition | Automated terpene fractionation meets Swissmedic and ECHA specifications for pharmaceutical drug master file submissions. |
| In-House Regulatory Affairs Investment | REACH dossier assembly capability filters out small-scale distillers and consolidates supplier panel access. |
| Blockchain Traceability Infrastructure | Immutable batch records satisfy flavor house procurement requirements for contract renewal eligibility. |
| Direct-to-Consumer Therapeutic Channel Launch | Seed-to-bottle quality control supports premium positioning in aromatherapy and wellness segments. |
Study Parameters
Document review covered customs and trade data from Indian DGFT, FDA GRAS designation filings, ECHA REACH registration databases, and FAO agricultural statistics, complemented by interviews with essential oil distillation plant managers, flavor house procurement leads, pharmaceutical formulators in Germany and Switzerland, and regulatory affairs specialists at BIS-certified processors. Primary fieldwork with Uttar Pradesh cultivator cooperatives and Mumbai contract testing laboratories validated secondary data on supply chain consolidation trends. Bottom-up volume modeling across extraction technology tiers triangulated against top-down value estimates from flavor and fragrance industry associations.
Segment-level outputs across the projection horizon reflect disaggregated modeling by product type, end-use application, and distribution channel, with cross-validation against regional production cluster capacity. CAGRs were derived from historical trade flow analysis and forward-looking capacity expansion announcements from major processors. Industry-specific forecast inputs incorporated monsoon pattern variability indices and REACH annex update implementation timelines.
Revisions become necessary when pesticide residue limit changes disrupt Indian export eligibility, supercritical CO2 extraction technology cost curves shift competitive economics, or synthetic menthol capacity expansions accelerate substitution pressure. Forecasts reflect documented assumptions about regulatory compliance burden trajectories and contract farming network consolidation rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Apple Powder Market
Extracts
Essential Oil Isolates Market
Extracts
Palmarosa Oil Market
Extracts
Herb and Spice Extracts Market
Extracts
Cassia Extract Market
Extracts
CO2 Extract Market
Extracts
Flower Extract Market
Extracts
Gelatin Hydrolysates Market
Extracts
Tagetes Oil Market
Extracts
Copaiba Essential Oil Market
Extracts
Bidens Pilosa Extract Market
Extracts
Floral Extract Market
Extracts
Lavender Oil Market
Extracts
Passion Flower Extracts Market
Extracts
Turpentine Market
Extracts
Global Rose Oils Market