
 Cornflower Extract Market | 2026-2036
Cornflower Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Cornflower Extract Market Analytics
Buyer concentration in European cosmetics manufacturing is restructuring procurement relationships for botanical extracts. Herb Pharm leverages certified organic cultivation to secure premium supply contracts with formulators. Gaia Herbs anchors North American distribution through practitioner-exclusive channels that limit price transparency. Givaudan competes on flavor and fragrance integration, extending cornflower extract into premium beverage applications.
Cornflower extract derives from Centaurea cyanus petals through aqueous or hydroalcoholic extraction, yielding flavonoids and anthocyanins with documented anti-inflammatory and antioxidant activity for topical and ingestible products. Liquid extracts currently dominate pharmaceutical compounding due to dosing flexibility, while powder formats are gaining fastest in capsule dietary supplements where stability and shelf life command margin premiums. The dietary supplements segment sustains higher per-unit pricing than food and beverage applications, where cornflower serves primarily as a natural colorant with limited functional differentiation.
EMA botanical drug guidance, FDA New Dietary Ingredient notification requirements, and ECHA REACH Annex III substance evaluation collectively determine market access timelines and testing burdens for cornflower extract suppliers. EMA's evolving quality standards for herbal medicinal products push smaller suppliers toward third-party certification investments they cannot self-fund. Stakeholders must monitor regulatory divergence between EU and US botanical frameworks when allocating R&D and registration budgets across geographies.
Market Dynamics
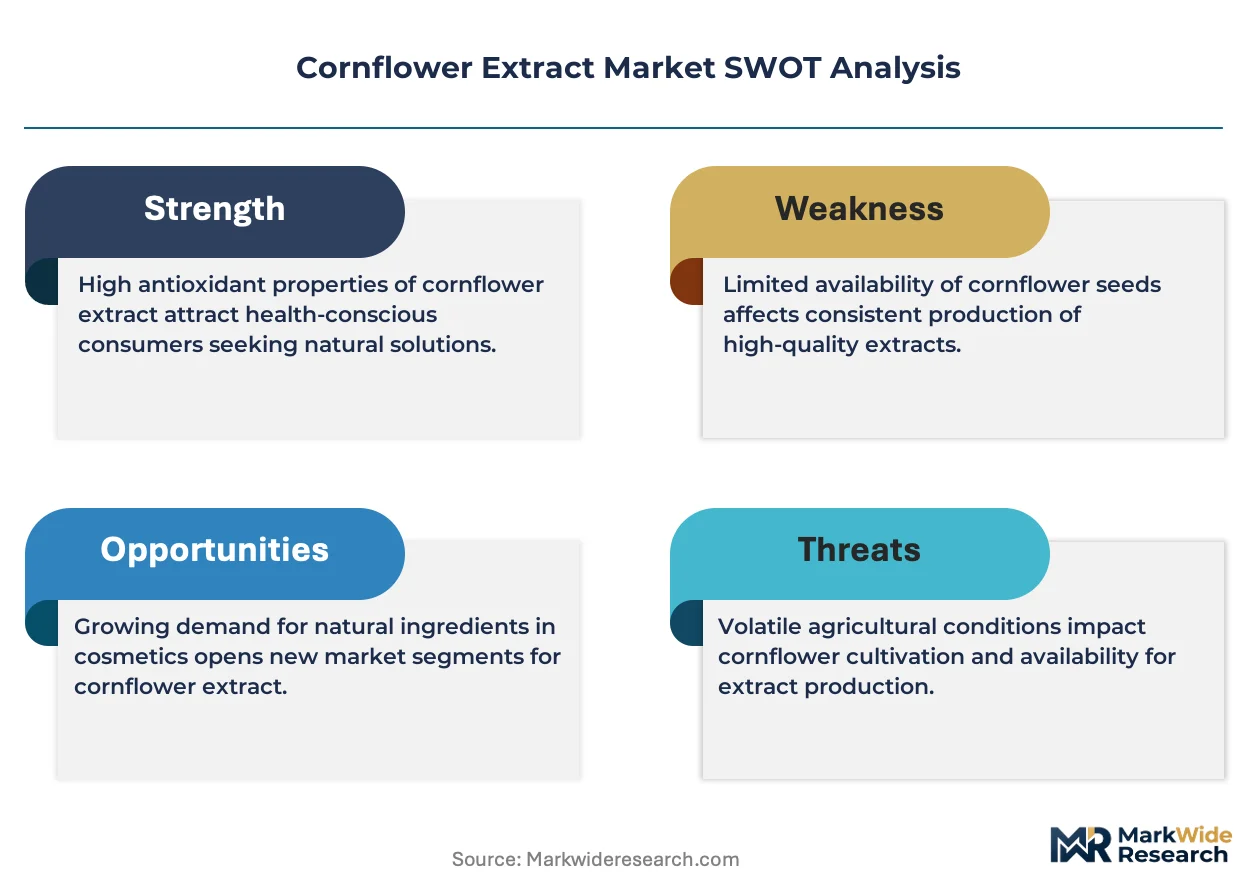
REACH Annex III substance evaluation is forcing cornflower extract suppliers to consolidate testing documentation or exit EU pharmaceutical supply chains entirely, compressing the qualified supplier base ahead of the 2035 compliance horizon.
Growth Catalysts
- K-beauty manufacturing expansion:Seoul-based cosmetics formulators are scaling anthocyanin-rich cornflower extract procurement for sensitive-skin product lines targeting Southeast Asian export markets.
- EMA botanical drug guidance evolution:The European Medicines Agency's tightening quality standards for herbal medicinal products is filtering out uncertified suppliers and concentrating volume with GMP-compliant producers.
- Supercritical CO2 extraction adoption:Advanced solvent-free processing is yielding higher flavonoid retention rates, enabling premium positioning in dietary supplement capsules where stability commands margin premiums.
Market Restraints
- Raw material geographic concentration:Certified organic Centaurea cyanus cultivation clusters in France's Provence and Germany's Bavaria, exposing buyers to regional weather volatility and single-source risk.
- Substitution by synthetic anthocyanins:Food and beverage manufacturers facing cost pressure are reformulating with petroleum-derived colorants that replicate cornflower's blue hue without botanical price premiums.
- FDA New Dietary Ingredient notification burden:The pre-market safety documentation requirement adds 18-24 month lead times for novel cornflower extract formulations, freezing smaller suppliers out of US dietary supplement channels.
Strategic Opportunities
- Underpenetrated Brazilian market:ANVISA's evolving herbal product regulations are creating first-mover openings for EU-certified suppliers to establish practitioner-channel distribution before local cultivation scales.
- Clean-label beverage convergence:Premium sparkling water and functional tea brands are integrating cornflower extract as both natural colorant and antioxidant marker, displacing artificial alternatives.
- South Korean MFDS fast-track pathway:The Ministry of Food and Drug Safety's expedited review for traditional herbal ingredients is compressing registration timelines for European suppliers with established safety dossiers.
Industry Challenges
- Phytochemical standardization expertise gap:Formulators lack in-house capability to validate batch-to-batch flavonoid consistency, forcing reliance on third-party analytical services that extend quality control cycles.
- Dual certification timeline compression:Simultaneous pursuit of EU organic certification and USP dietary ingredient verification is straining smaller suppliers' documentation bandwidth and capital reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cornflower Extract Market |
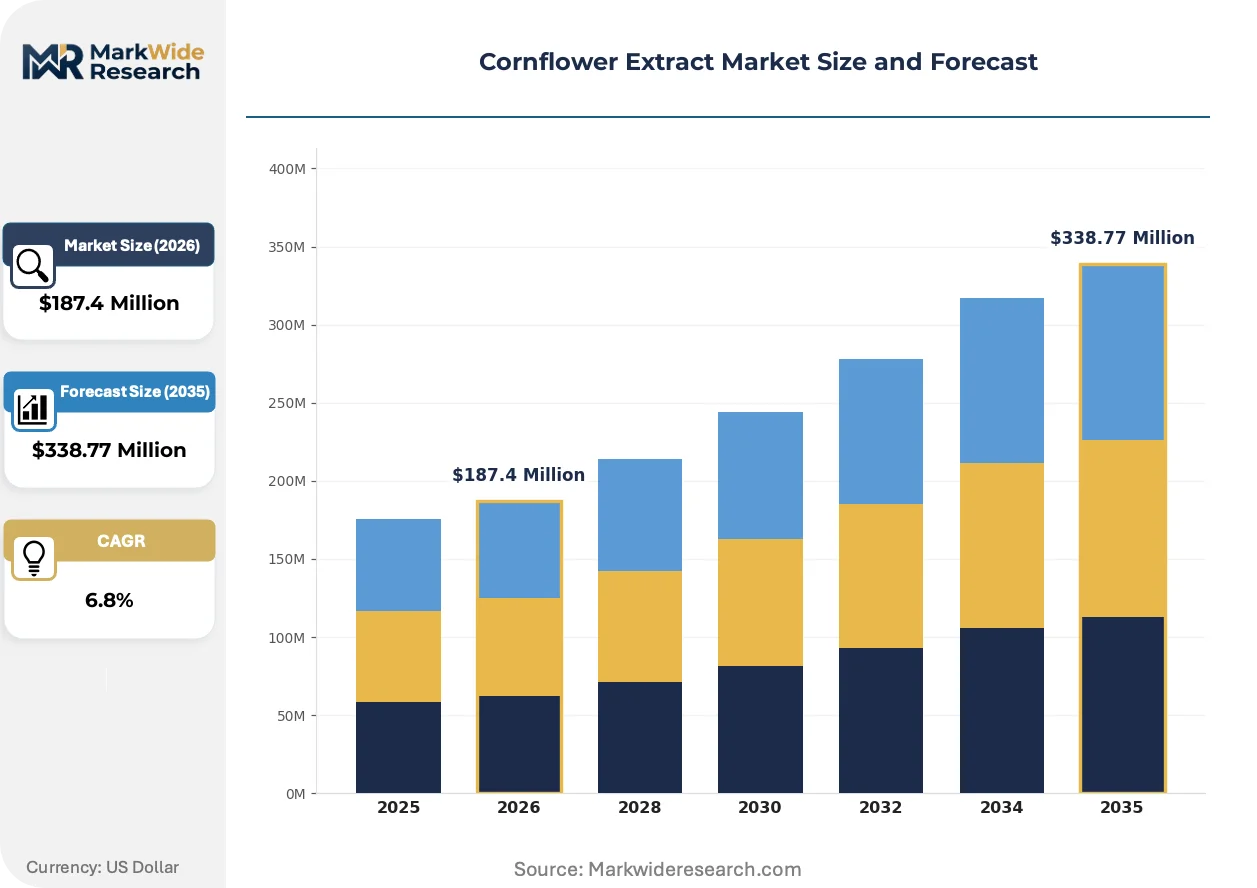
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Capsules, Tablets Application: Cosmetics, Pharmaceuticals, Food and Beverages, Dietary Supplements End User: Manufacturers, Retailers, Distributors, Consumers Distribution Channel: Online, Specialty Stores, Supermarkets, Health Shops |
| Companies Covered | Herb Pharm, Gaia Herbs, Solgar, Swanson Health Products, Source Naturals, BlueBonnet Nutrition, Bioforce, Givaudan, Naturalin Bio-Resources, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cornflower Extract Market Evolving Landscape
Supercritical fluid extraction and precision fermentation are converging to redefine how cornflower-derived actives reach formulators, compressing traditional aqueous extraction's dominance while opening entirely new supply chain configurations.
Supercritical CO2 extraction technology is rewriting the economics of high-purity anthocyanin production. Pharmaceutical compounders in Germany are adopting this solvent-free approach at pilot scale, enabling API-grade material qualification that aqueous methods cannot achieve. The technology is compressing yield variability and unlocking contract manufacturing margins previously reserved for synthetic actives.
EMA's 2023 revised guideline on quality of herbal medicinal products is mandating expanded heavy metal and pesticide residue testing for all botanical drug submissions. This regulatory tightening is disqualifying uncertified cultivators and consolidating procurement relationships with vertically integrated suppliers who control cultivation through finished extract. French and Italian pharmaceutical formulators are responding by dual-sourcing from REACH-registered suppliers with captive organic farming operations.
Direct-to-brand supply contracts are displacing traditional distributor intermediaries in the cosmetics segment. K-beauty manufacturers around Seoul are negotiating annual volume commitments directly with Provence-based extractors, bypassing Rotterdam and Hamburg trading houses that historically captured 15-20 point margins. This channel compression is most visible in premium sensitive-skin lines where traceability documentation has become a non-negotiable procurement criterion.
Cornflower Extract Market Segmentation
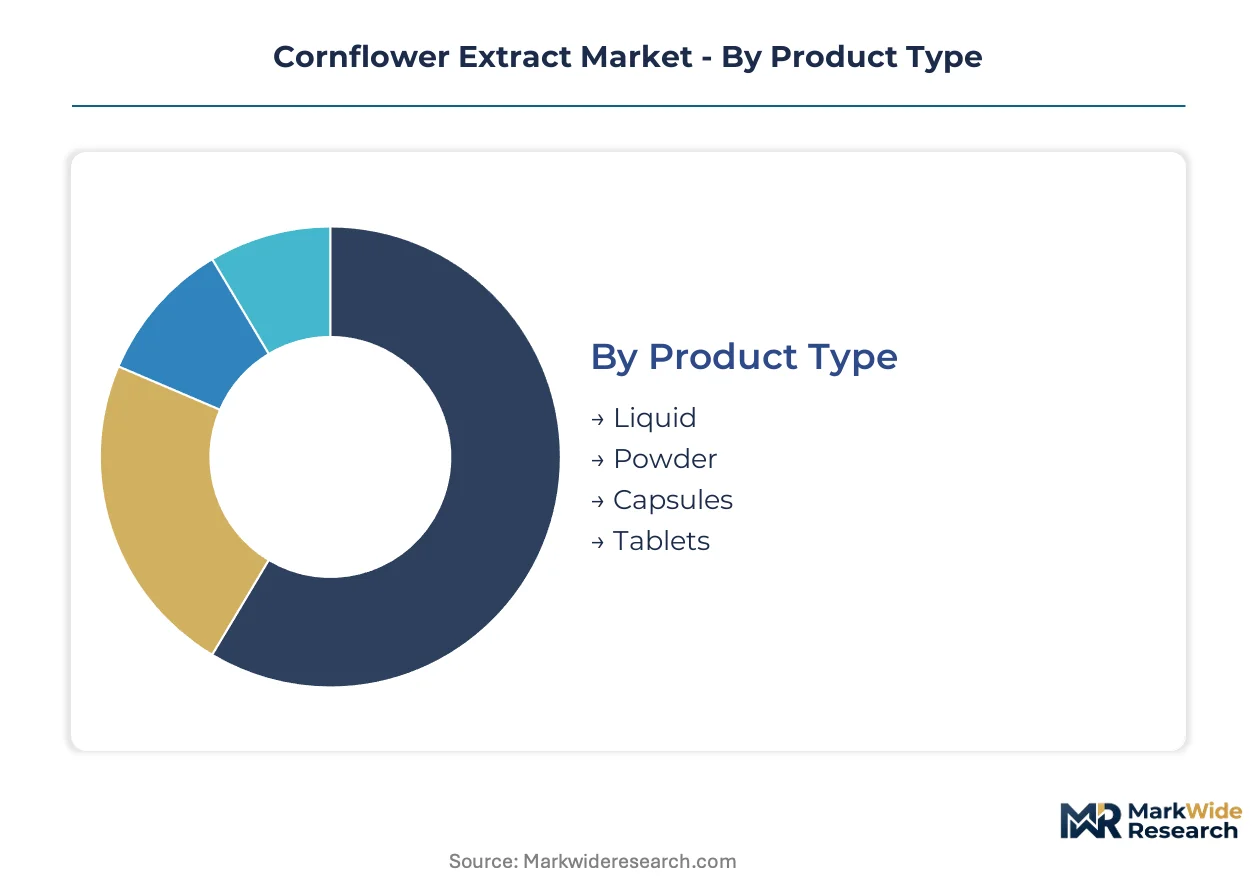
Cornflower extract procurement splits across formulation requirements, regulatory pathways, and channel economics. Buyers select product formats and supply routes based on end-use certification demands and margin structures.
Product Type:
Formulators prioritize stability profiles and dosing precision when selecting extract formats for their production lines.
- Liquid:Aqueous or hydroalcoholic solutions containing dissolved flavonoids and anthocyanins enable flexible dosing in pharmaceutical compounding and cosmetic formulation. German pharmaceutical compounders favor liquid extracts for bespoke tincture production where batch customization drives procurement decisions.
- Powder:Spray-dried or freeze-dried particulates offer extended shelf stability and standardized potency for encapsulation. Seoul-based K-beauty manufacturers are scaling powder procurement for pressed powder cosmetics and dry mask formulations targeting Southeast Asian humidity conditions.
- Capsules:Pre-measured gelatin or vegetable-based shells containing standardized extract doses for dietary supplement brands.
- Tablets:Compressed solid doses with binding agents for mass-market supplement distribution through retail pharmacy chains.
Liquid extracts lead on scale; powder formats lead on momentum.
Application:
Regulatory classification determines testing burdens, margin premiums, and speed-to-market for cornflower-derived formulations.
- Cosmetics:Topical formulations leverage anthocyanin colorants and anti-inflammatory claims for sensitive-skin positioning. French formulators in Grasse and Paris are expanding procurement for EU-compliant natural cosmetic lines subject to REACH Annex III allergen labeling mandates.
- Pharmaceuticals:Botanical drug submissions under EMA quality guidelines require heavy metal and pesticide documentation that filters supplier eligibility. Bavarian extractors with captive organic cultivation are consolidating supply relationships as uncertified competitors exit.
- Food and Beverages:Natural blue colorant applications in premium beverages face substitution pressure from synthetic anthocyanins.
- Dietary Supplements:Capsule and tablet formats command higher per-unit pricing than food applications where functional differentiation remains limited.
Cosmetics applications lead on scale; pharmaceuticals lead on momentum.
End User:
Procurement authority and volume scale vary sharply across the value chain, reshaping supplier engagement strategies.
- Manufacturers:Cosmetics, pharmaceutical, and food production facilities with direct formulation capability and technical specification requirements.
- Retailers:Pharmacy chains, natural product stores, and department store beauty counters with private-label sourcing authority.
- Distributors:Traditional trading houses in Rotterdam and Hamburg facing margin compression as K-beauty brands negotiate direct contracts with Provence extractors.
- Consumers:Direct purchasers through practitioner channels and e-commerce platforms seeking single-ingredient supplements.
Manufacturers lead on scale; retailers lead on momentum.
Distribution Channel:
Channel selection governs traceability documentation requirements and margin capture for extract suppliers.
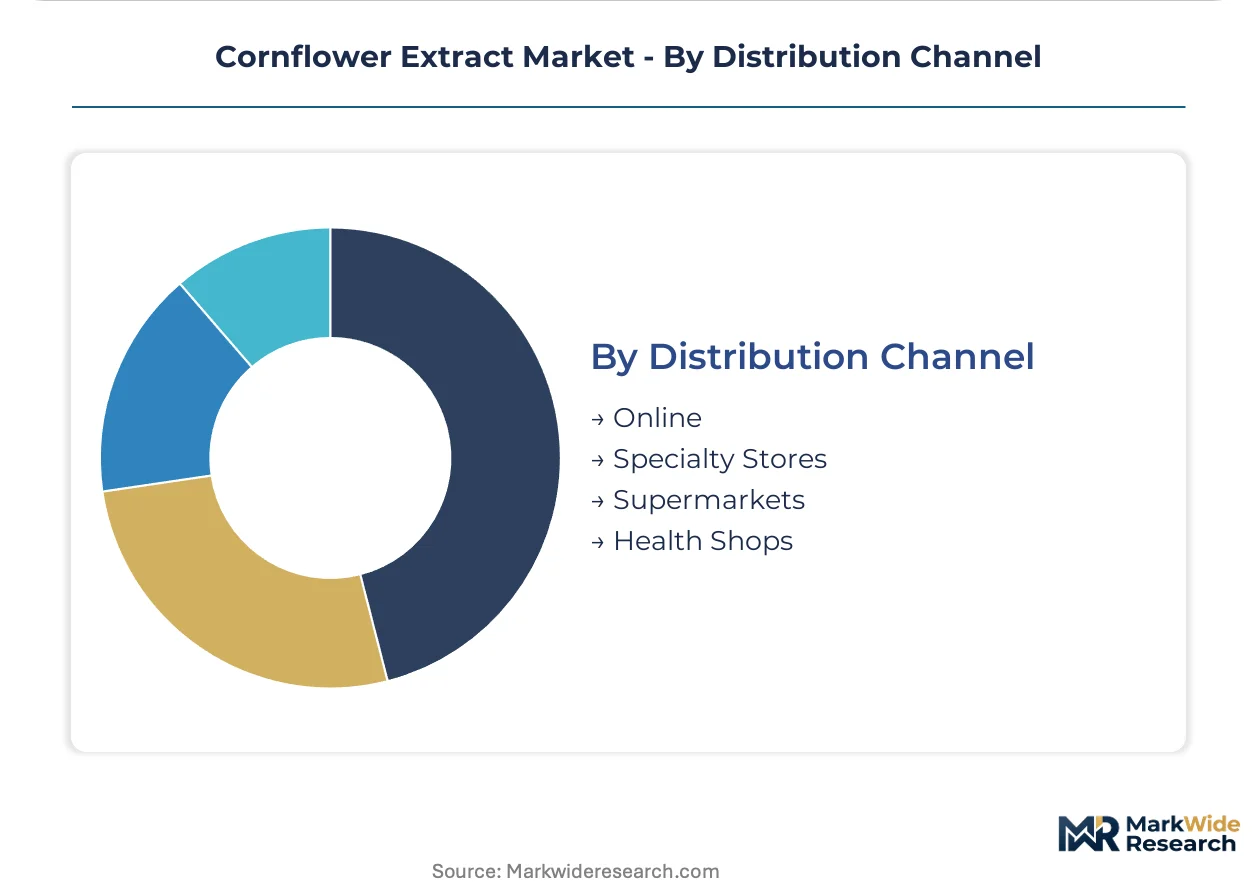
- Online:Direct-to-consumer and direct-to-brand e-commerce platforms enabling bypass of traditional distributor intermediaries.
- Specialty Stores:Natural product retailers and apothecaries with trained staff capable of explaining botanical sourcing credentials.
- Supermarkets:Mass-market grocery chains with volume requirements and price positioning constraints for food-grade colorant applications.
- Health Shops:Practitioner-exclusive channels limiting price transparency and anchoring premium positioning for certified organic grades.
Specialty stores lead on scale; online channels lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized extraction chemists and organic cultivation specialists cluster in France's Provence region and Germany's Bavaria, anchoring European supply capacity. Seoul's K-beauty manufacturing corridor draws technical talent from cosmetic chemistry programs at Seoul National University and Sungkyunkwan University.
France
Grasse-based fragrance houses and Parisian cosmetic laboratories drive anthocyanin procurement for sensitive-skin formulations. ANSM enforces expanded allergen labeling under EU cosmetics regulation, disqualifying uncertified cultivators. Provence extractors with captive organic farming operations are consolidating supply relationships as trading house margins compress.
Germany
Bavarian pharmaceutical compounders favor liquid extracts for bespoke tincture production where batch customization governs procurement. EMA's tightened quality standards for herbal medicinal products filter supplier eligibility through heavy metal and pesticide documentation requirements. Munich and Nuremberg extraction facilities are adopting supercritical CO2 processing at pilot scale for API-grade material qualification.
South Korea
Seoul-based cosmetics formulators scale powder procurement for pressed powder cosmetics and dry mask formulations targeting Southeast Asian humidity conditions. MFDS operates an expedited review pathway for traditional herbal ingredients, compressing registration timelines for European suppliers with established safety dossiers. The Seoul Capital Area manufacturing corridor is displacing Rotterdam and Hamburg trading houses through direct annual volume commitments with Provence extractors.
United States
Practitioner-exclusive channels in the Northeast and California anchor premium positioning for certified organic grades through limited price transparency. FDA New Dietary Ingredient notification requirements add 18-24 month lead times for novel formulations, freezing smaller suppliers out of dietary supplement channels. Gaia Herbs exemplifies North American distribution strategies that limit price transparency and reinforce premium tier positioning.
Brazil
ANVISA's evolving herbal product regulations create first-mover openings for EU-certified suppliers to establish practitioner-channel distribution before local cultivation scales. São Paulo and Rio de Janeiro formulators lack in-house phytochemical standardization capability, forcing reliance on third-party analytical services that extend quality control cycles. European suppliers with REACH-registered status and captive organic operations are prioritizing Brazilian market entry ahead of domestic competitor maturation.
Cornflower Extract Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across multiple value chain positions. The supplier base concentrates around vertically integrated cultivator-extractors and technology-licensed contract manufacturers. Three archetypes dominate: captive organic farmers with extraction capability, flavor-and-fragrance integrators extending into botanical actives, and practitioner-channel specialists limiting price transparency. Competitive moves center on dual certification pursuit and direct-to-brand contract negotiation.
Within the practitioner-channel specialist tier, Gaia Herbs and Herb Pharm exemplify strategies that limit price transparency and anchor premium positioning. Givaudan occupies a position among diversified flavor-and-fragrance integrators extending cornflower extract into premium beverage applications. These three companies represent distinct competitive archetypes: the certified organic cultivator-extractor, the practitioner-exclusive distributor, and the cross-category ingredient platform.
| Leading Market Players |
|---|
| Herb Pharm |
| Gaia Herbs |
| Solgar |
| Swanson Health Products |
| Source Naturals |
| BlueBonnet Nutrition |
| Bioforce |
| Givaudan |
| Naturalin Bio-Resources |
| Others |
Value Network & Pricing Analysis
K-beauty manufacturers in Seoul negotiate direct annual volume commitments with Provence extractors, compressing distributor margins and anchoring contract-based pricing that rewards traceability documentation over spot-market flexibility. This buyer concentration shifts pricing power toward vertically integrated suppliers with captive organic cultivation.
Pricing Analysis
Service bundling separates certified organic grades with full documentation from unbundled commodity extracts lacking allergen testing. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with EMA-compliant pharmaceutical grades commanding the widest premiums. Cost compression in food-grade colorant tiers is intensifying because synthetic anthocyanin substitution erodes botanical price premiums. Cosmetics formulators show least price sensitivity due to sensitive-skin positioning requirements.
Supply Chain Analysis
REACH registration and organic certification gating filters supplier eligibility, consolidating procurement with vertically integrated cultivator-extractors. Supply concentrates in France's Provence and Germany's Bavaria for certified organic Centaurea cyanus, with South Korea's Seoul corridor driving powder format demand. Raw material sourcing draws from captive farming operations, aqueous extraction facilities, and supercritical CO2 processing pilots. Single-source vulnerability runs through weather-dependent Provence harvests. Distribution runs through direct-to-brand contracts displacing Rotterdam and Hamburg trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cornflower extract functions as a stable compounder anchored by regulatory tightening that filters out uncertified suppliers and concentrates volume with compliant producers.
For Market Incumbents: Hedge against synthetic anthocyanin substitution in food-grade tiers by deepening backward integration into supercritical CO2 extraction capacity for API-grade qualification. Defend pharmaceutical margins through dual certification pursuit of EU organic and USP dietary ingredient verification. Channel control in practitioner-exclusive networks limits price transparency and reinforces premium tier positioning. For New Entrants and Emerging Players: Capture first-mover advantage in Brazil's practitioner-channel distribution before ANVISA regulatory maturation enables domestic cultivation scaling. Target underpenetrated Brazilian formulators lacking phytochemical standardization expertise by offering bundled analytical validation services alongside extract supply. For Investors and Strategic Acquirers: Flavor-and-fragrance integrators represent the most active acquirer category in this space, seeking botanical active platforms for beverage extension. Long-term viability rests on regulatory moat sustainability rather than commodity extraction economics. Watch for MFDS fast-track pathway expansion as inflection signal for Asian market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | EMA and USP verification filters supplier eligibility and consolidates procurement relationships. |
| Direct-to-Brand Contracting | Seoul-based K-beauty manufacturers bypass Rotterdam trading houses for traceability documentation. |
| Supercritical CO2 Adoption | German pharmaceutical compounders pilot solvent-free processing for API-grade material qualification. |
| Brazilian Market Entry | ANVISA regulatory evolution creates practitioner-channel openings before domestic cultivation scales. |
| Precision Fermentation R&D | Advanced bioprocessing threatens traditional aqueous extraction economics for high-purity anthocyanins. |
Research Methodology
Direct dialogue with cosmetics formulators, pharmaceutical compounders, certified organic cultivators, and regulatory affairs specialists combined with secondary validation from EMA guidance documents, REACH registration databases, MFDS submission records, and customs trade data. Bottom-up volume estimates triangulated against top-down market sizing across extraction technology tiers.
Segment-level value outputs incorporate product format, application regulatory pathway, and end-user procurement authority dimensions across the projection horizon. CAGRs derive from annual growth rate progression modeling calibrated to K-beauty manufacturing expansion rates and EMA compliance timeline compression. Forecast inputs include supercritical CO2 adoption curves and synthetic anthocyanin substitution elasticity in food-grade applications.
Underlying measurement precision varies by segment; pharmaceutical and cosmetics applications carry tighter precision than food-grade colorant tiers due to documentation requirements. Forecasts reflect assumptions about regulatory enforcement consistency and cultivation yield stability. A model refresh is warranted upon material change in REACH Annex III substance evaluation timelines or MFDS fast-track pathway expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Herb and Spice Extracts Market
Extracts
Irish Moss Market
Extracts
Wild Yam Powder Market
Extracts
Citronella Oil Market
Extracts
Botanical CO2 Extracts Market
Extracts
Global Aphrodisiac Powder Market
Extracts
Histidine Market
Extracts
Copaiba Essential Oil Market
Extracts
Helichrysum Oil Market
Extracts
Frankincense Oil Market
Extracts
Phytochemicals Market
Extracts
Cajeput Oil Market
Extracts
Sandalwood Oil Market
Extracts
Lemon Balm Extract Market
Extracts
Organic Herbal Extracts Market
Extracts
Jalapeno Extract Market