
 Pectinase Market | 2026-2036
Pectinase Market Size, Share, and Industry Trends Forecast 2026-2036
Pectinase Market Analysis
Juice and wine processing is hardening as the dominant demand vertical for pectinase enzymes, displacing traditional textile degumming applications. Novozymes leverages its fungal strain library to dominate Northern European supply contracts. Kerry Group anchors its position through backward integration into fermentation infrastructure. DuPont de Nemours Inc. competes on thermostable pectinase variants for high-temperature fruit processing lines.
Pectinase denotes a class of enzymes that hydrolyze pectin polysaccharides through depolymerization of galacturonic acid chains, typically operating optimally at pH 3.5–5.5 and temperatures between 45°C and 55°C. These enzymes serve primarily to reduce viscosity in fruit mashes, enhance juice yield, and clarify beverages by degrading pectin haze. Liquid formulations command the largest volume share due to ease of dosing in continuous processing lines, while powder grades attract pharmaceutical compounders seeking extended shelf stability. Fungal-sourced pectinase, derived predominantly from Aspergillus niger, leads production economics through established submerged fermentation protocols.
REACH registration requirements in Europe, FDA food contact substance notifications in the United States, and FSSAI enzyme safety specifications in India collectively shape product purity thresholds and market access conditions. The EU Green Deal pushes manufacturers toward reduced solvent use in downstream enzyme recovery. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs.
Market Dynamics
Juice and wine processors are consolidating pectinase procurement around high-activity fungal enzyme concentrates, compressing demand for lower-specific-activity formulations as yield-per-dose becomes the dominant purchasing criterion.
Growth Catalysts
- EU Green Deal solvent reduction mandates:Enzyme recovery protocols in Germany and Denmark now prioritize aqueous extraction methods, creating pull for pectinase strains with higher thermal stability that survive gentler downstream processing.
- Aspergillus niger strain optimization:CRISPR-edited fungal lines achieve 40% higher galacturonase titers in submerged fermentation, cutting unit production costs for industrial-scale juice clarifiers.
- Cold-pressed juice segment expansion:Premium beverage brands in California and Victoria specify pectinase treatments that operate at reduced temperatures to preserve volatile aromatic compounds.
Market Restraints
- Submerged fermentation capex concentration:Commercial-scale bioreactor infrastructure clusters in Bavaria and Jutland, leaving processors in peripheral markets exposed to logistics premiums and currency-hedged supply contracts.
- REACH registration cost escalation:ECHA data requirements for enzyme protein characterization now exceed €200,000 per novel formulation, freezing SME participation in EU supply chains.
- Cellulase-pectinase blend substitution:Multi-enzyme cocktails for textile bioscouring offer comparable degumming performance at lower per-kilogram enzyme cost, eroding pectinase's historical position in non-food applications.
Strategic Opportunities
- FSSAI enzyme safety specification alignment:Indian food processors face mandatory pectinase purity certifications from 2026, creating first-mover advantage for suppliers with pre-validated analytical packages.
- Precision fermentation enzyme production:Yeast-based expression systems eliminate fungal mycotoxin risks entirely, opening pharmaceutical-grade pectinase supply for pectin-derived oligosaccharide therapeutics.
- Direct-to-processor digital platforms:Enzyme-as-a-service subscription models bypass traditional distributor markups for mid-size Brazilian and South African citrus processors.
Industry Challenges
- ISO 17025 analytical method harmonization:Inconsistent pectinase activity assays across contract laboratories force redundant validation spending for multi-jurisdictional suppliers.
- Legacy batch reactor integration:Continuous enzyme dosing systems require stainless steel line modifications that conflict with seasonal fruit processing plant shutdown windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pectinase Market |
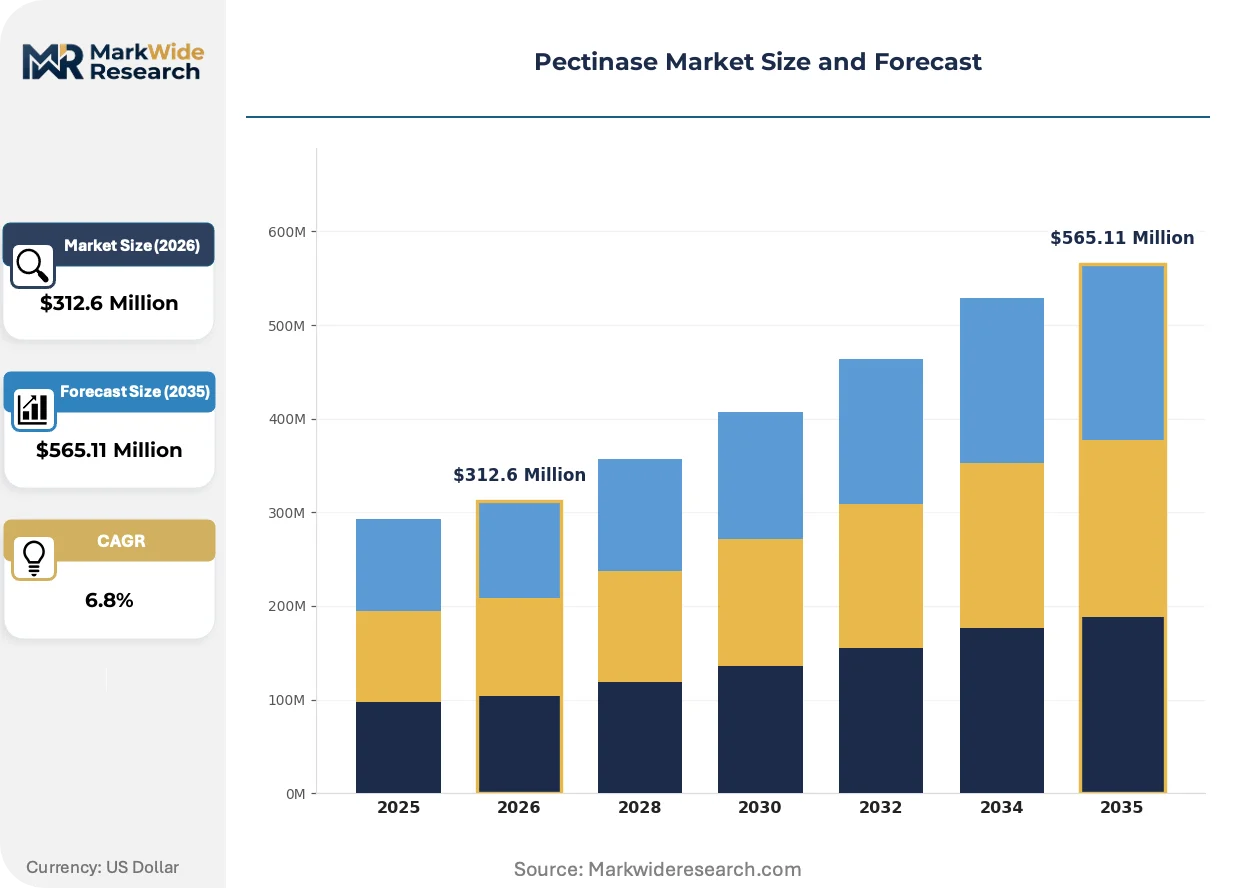
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granule, Concentrate Application: Food & Beverage, Textiles, Paper & Pulp, Cosmetics End User: Food Processors, Beverage Manufacturers, Pharmaceutical Companies, Personal Care Firms Source: Fungal, Bacterial, Plant, Animal |
| Companies Covered | Novozymes, Kerry Group, Cargill Incorporated, AB Enzymes GmbH, International Flavors & Fragrances Inc., BASF SE, Koninklijke DSM N.V., Merck Co. & KGaA, DuPont de Nemours Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pectinase Market Emerging Trajectories
Enzyme engineering platforms are compressing development cycles for pectinase variants, while regulatory chemistry is tightening purity thresholds and procurement patterns are fragmenting across direct and channel routes.
Immobilized pectinase on magnetic nanoparticles is consolidating enzyme recovery economics in wine must clarification. Champagne houses in Reims and Epernay now deploy magnetically separable enzyme systems that cut protein carryover into finished bottles. This technology is consolidating the supplier base around fermentation technology firms with materials science capabilities, marginalizing pure-play enzyme merchants.
REACH Annex XIV authorization timelines are extending lead times for novel pectinase introductions into EU food contact applications. ECHA's 2024 guidance on protein allergenicity assessment now requires extended dermal sensitization studies for powdered enzyme grades. Wine cooperatives in Bordeaux and Piedmont are accelerating liquid formulation conversions to preempt registration bottlenecks.
Long-term supply agreements with fixed annual volume commitments are displacing spot enzyme purchases among multinational beverage conglomerates. Procurement teams at integrated fruit processors now negotiate three-year pectinase contracts with price collars indexed to agricultural commodity futures. This pattern is most pronounced in California's Central Valley, where permanent crop investments justify enzyme inventory pre-positioning.
Pectinase Market Segmentation
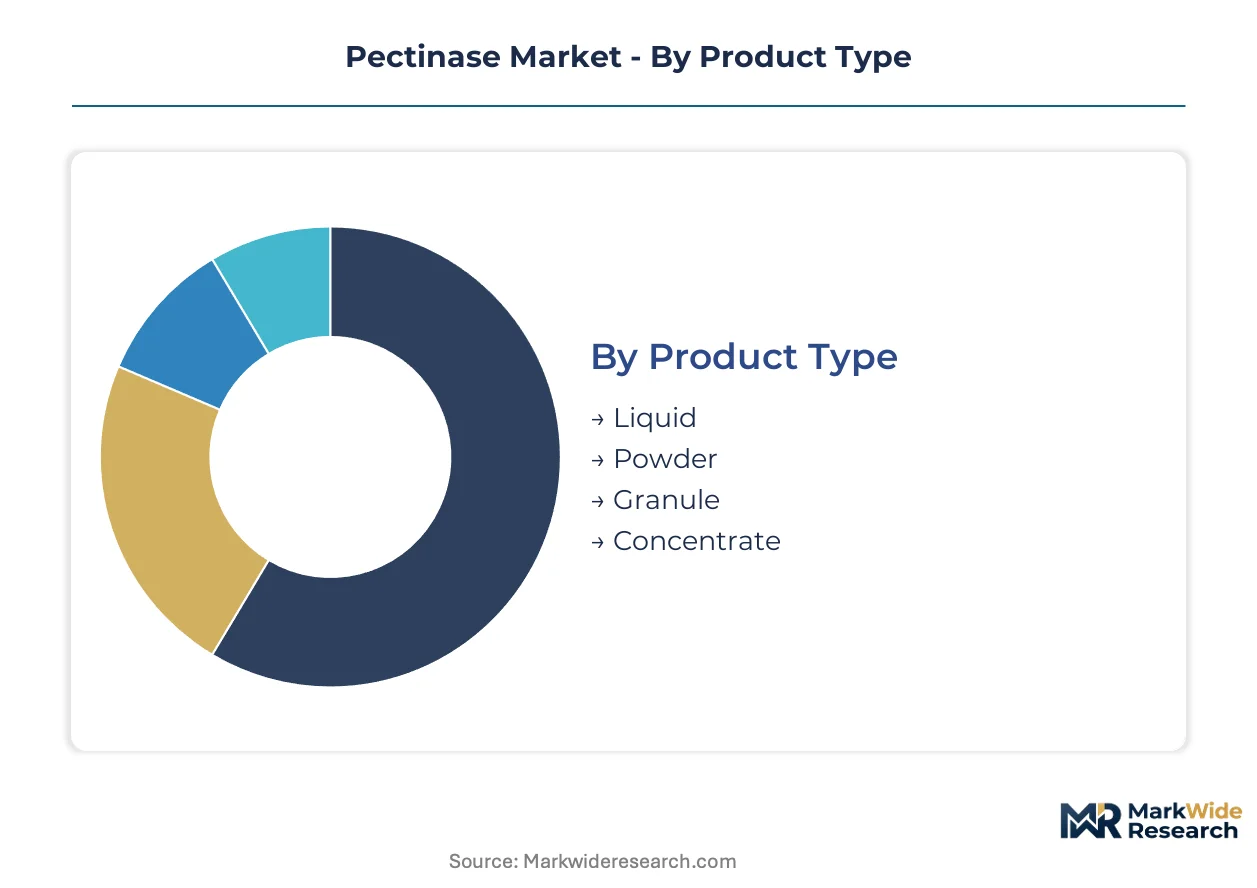
Pectinase procurement patterns diverge sharply across formulation physics, downstream application chemistry, and biological origin. Each segmentation axis carries distinct regulatory, logistics, and performance imperatives that reshape supplier positioning.
Product Type:
Formulation state determines dosing precision, stability windows, and integration capital requirements in continuous processing environments.
- Liquid:Aqueous enzyme solutions enable metered injection into high-throughput juice clarification lines. California citrus processors and Champagne cooperatives specify liquid grades to eliminate rehydration steps and reduce batch-to-batch activity variance.
- Powder:Spray-dried preparations with maltodextrin carriers extend shelf stability beyond 24 months under ambient storage. Pharmaceutical compounders in Basel and Hyderabad source powder grades for pectin-derived oligosaccharide synthesis where moisture sensitivity governs raw material selection.
- Granule:Agglomerated formulations with controlled dissolution kinetics serve seasonal fruit processors lacking liquid handling infrastructure. Brazilian orange juice cooperatives deploy granules during harvest peaks when cold chain capacity saturates.
- Concentrate:High-activity fungal filtrates reduce freight costs per million activity units. Northern European enzyme distributors blend concentrates locally to match regional formulation preferences.
Liquid leads on scale; concentrate leads on momentum.
Application:
End-use chemistry dictates pH tolerance requirements, thermal stability thresholds, and co-enzyme compatibility specifications.
- Food & Beverage:Juice clarification and wine must processing consume the majority of industrial pectinase volume. German fruit processors specify fungal-derived polygalacturonase with pH optima at 3.8–4.2 for white grape pressing sequences.
- Textiles:Bioscouring of cotton and linen employs pectinase-cellulase blends to replace caustic soda degumming. Italian textile finishers in Prato are shifting toward multi-enzyme cocktails that erode pure pectinase demand.
- Paper & Pulp:Pectin hydrolysis in wood chip pretreatment reduces refining energy consumption. Nordic pulp mills trial pectinase as a partial replacement for thermomechanical refining in specialty paper grades.
- Cosmetics:Pectinase-assisted extraction of plant polysaccharides yields rheology modifiers for skincare emulsions. Korean cosmetic manufacturers source low-endotoxin grades for hyaluronic acid co-formulations.
Food & Beverage dominates volume; cosmetics climbs fastest on purity premium capture.
End User:
Customer scale and technical sophistication fragment procurement patterns across spot purchasing, annual contracts, and long-term supply agreements.
- Food Processors:Integrated fruit and vegetable processors negotiate three-year pectinase contracts with price collars indexed to agricultural commodity futures. California's Central Valley operators pre-position enzyme inventory to match permanent crop harvest calendars.
- Beverage Manufacturers:Wine cooperatives in Bordeaux and Piedmont are accelerating liquid formulation conversions to preempt REACH Annex XIV registration bottlenecks for powdered grades.
- Pharmaceutical Companies:Precision fermentation-derived pectinase eliminates fungal mycotoxin risks for pectin oligosaccharide therapeutics. Swiss and Danish biotech firms validate yeast-based expression systems for injectable-grade supply.
- Personal Care Firms:Natural cosmetics brands specify plant-sourced pectinase to support clean-label positioning. French and German formulators audit supply chains for genetically modified organism exclusion.
Food processors lead on contract value; pharmaceutical companies lead on specification intensity.
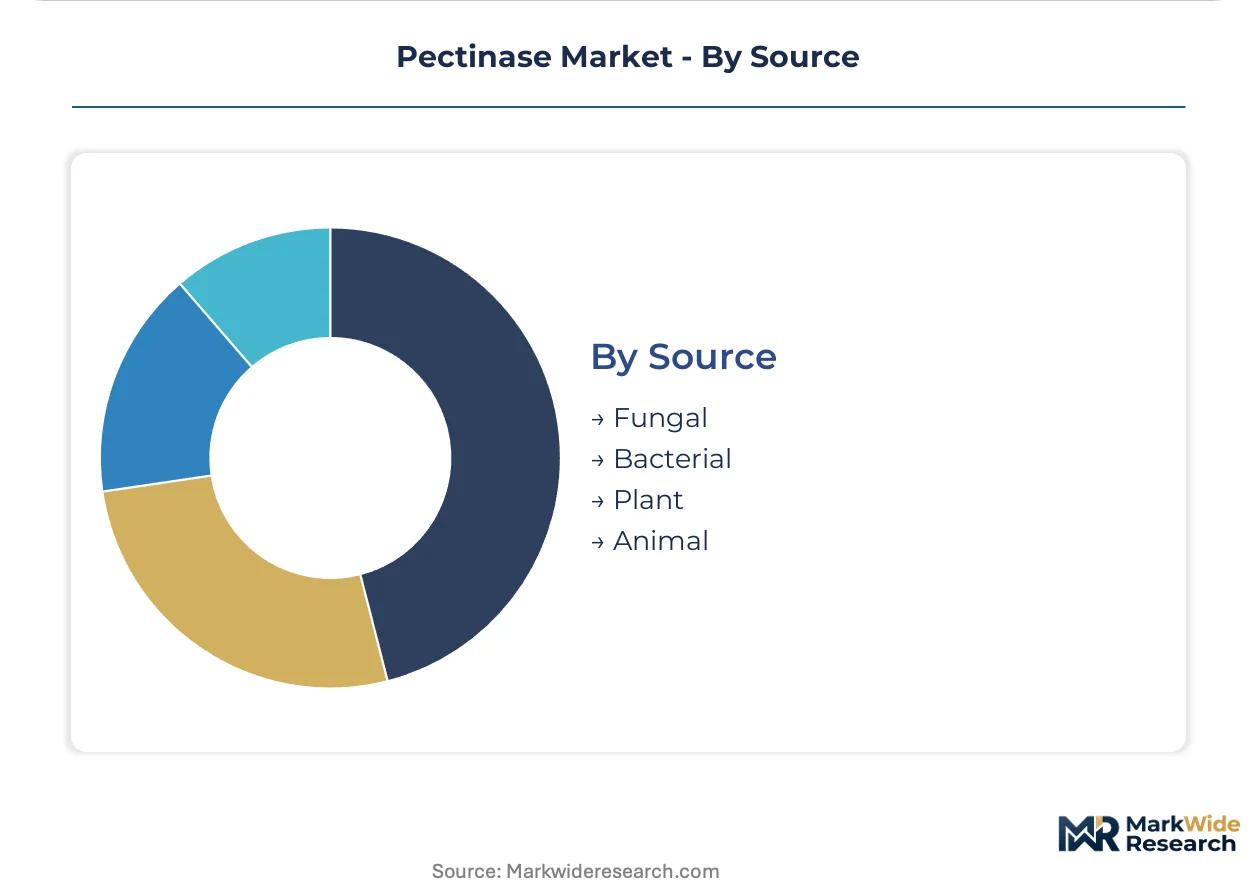
Source:
Biological origin governs production economics, regulatory pathway complexity, and contaminant risk profiles.
- Fungal:Submerged fermentation of Aspergillus niger dominates industrial supply through established galacturonase titer protocols. CRISPR-edited strains achieve elevated expression levels that compress unit costs for juice clarifiers.
- Bacterial:Bacillus-derived alkaline pectinase serves textile bioscouring applications requiring pH 8–9 operating windows. Indian and Bangladeshi denim processors specify bacterial grades for combined desizing and bioscouring sequences.
- Plant:Papaya and tomato-derived pectinase extracts attract clean-label cosmetic applications. Supply constraints limit commercial scale.
- Animal:Snail and insect sources remain research-grade curiosities with negligible industrial penetration.
Fungal leads on manufacturing scale; bacterial leads on application expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting pectinase production toward jurisdictions with streamlined enzyme approval pathways, as REACH compliance costs in Europe exceed alternative certification regimes by substantial margins.
Germany
Bavarian biotech clusters anchor continental European enzyme supply, with Jülich and Munich fermentation facilities serving juice processors across the Rhine corridor. ECHA registration requirements for novel protein formulations now exceed €200,000 per submission, compressing SME participation. The Baden-Württemberg precision fermentation corridor is consolidating strain development capabilities for thermostable variants.
United States
California Central Valley citrus processors negotiate three-year pectinase contracts with agricultural commodity price collars. FDA food contact substance notifications govern enzyme safety validation for beverage applications. The Sacramento-San Joaquin processing belt pre-positions enzyme inventory to align with permanent crop harvest calendars.
India
Maharashtra and Gujarat fruit processors face mandatory FSSAI enzyme purity certifications from 2026, creating compliance-driven procurement shifts. CDSCO alignment with international pharmacopoeial standards is opening pharmaceutical-grade pectinase pathways for oligosaccharide therapeutics. The Pune biotech corridor is validating fungal expression systems for export-oriented supply.
France
Champagne cooperatives in Reims and Epernay deploy magnetically separable immobilized pectinase systems to reduce protein carryover. ANSM oversight of enzyme allergenicity is accelerating liquid formulation conversions ahead of REACH Annex XIV bottlenecks. The Bordeaux wine region is consolidating procurement around high-activity fungal concentrates.
Denmark
Jutland fermentation infrastructure clusters serve Nordic and Baltic juice processors with aqueous extraction protocols aligned to EU Green Deal solvent reduction mandates. The Danish Medicines Agency's enzyme protein characterization standards influence ECHA guidance development. Copenhagen-area biotech firms are optimizing CRISPR-edited Aspergillus lines for elevated galacturonase expression.
Pectinase Market Vendor Landscape
Strategic partnerships dominate the current landscape, with technology licensing agreements and fermentation capacity sharing arrangements reshaping supply relationships. The vendor base organizes around three tiers: integrated biotech conglomerates with captive strain libraries, mid-scale enzyme specialists with regional formulation capabilities, and precision fermentation startups targeting pharmaceutical-grade purity thresholds. M&A activity concentrates on acquiring submerged fermentation infrastructure, while backward integration into upstream strain development is compressing reliance on external research collaborations.
Within the integrated biotech tier, Novozymes and DuPont de Nemours Inc. occupy positions defined by fungal strain portfolio breadth and thermostable variant development capabilities. Kerry Group exemplifies the mid-scale specialist archetype through its fermentation infrastructure investments. These three entities represent distinct competitive vectors: strain optimization depth, formulation flexibility, and supply chain control intensity respectively.
| Leading Market Players |
|---|
| Novozymes |
| Kerry Group |
| Cargill Incorporated |
| AB Enzymes GmbH |
| International Flavors & Fragrances Inc. |
| BASF SE |
| Koninklijke DSM N.V. |
| Merck Co. & KGaA |
| DuPont de Nemours Inc. |
| Others |
Supply Flow & Price Mechanics
Agricultural commodity futures indices governing fruit and grain feedstocks cascade through pectinase manufacturing economics, compressing margins for processors locked into fixed-price enzyme contracts while rewarding suppliers with backward integration into fermentation substrate supply.
Pricing Analysis
Distributor markups of 15-25 percent on liquid formulations are compressing as direct-to-processor digital platforms disintermediate traditional enzyme merchants in Brazil and South Africa. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade certification levels separates FSSAI-validated Indian supply from REACH-registered European product and unregistered economy-tier alternatives. Pricing pressure stems from CRISPR-edited strain proliferation elevating galacturonase titers and unit volume availability. Spot purchasers in seasonal citrus processing exhibit acute price sensitivity; pharmaceutical compounders in Basel and Hyderabad absorb premiums for endotoxin-controlled powder grades.
Supply Chain Analysis
ISO 17025 certification gating forces redundant analytical validation spending for multi-jurisdictional suppliers seeking cross-border enzyme shipments. Submerged fermentation capacity concentrates in Germany, Denmark, and India, drawing from molasses and corn steep liquor feedstocks. Supply chain risk centers on single-source vulnerability in Bavarian bioreactor clusters serving continental European juice processors. Distribution runs through regional formulation specialists who blend concentrates locally to match liquid, powder, or granule preferences.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play: REACH registration costs exceeding €200,000 per novel formulation in Europe against streamlined FSSAI pathways in India create divergent entry economics for precision fermentation startups.
For Market Incumbents: Lock in three-year supply agreements with California Central Valley citrus processors before precision fermentation entrants achieve commercial scale. Defend position by acquiring submerged fermentation infrastructure in Jutland to anchor Nordic supply. Prioritize thermostable variant R&D to capture EU Green Deal solvent-reduction mandates.
For New Entrants and Emerging Players: FSSAI enzyme safety specifications in India open a window for pre-validated analytical packages ahead of 2026 mandatory certifications. Target Maharashtra and Gujarat fruit processors with direct-to-processor digital platforms bypassing distributor markups. Penetrate pharmaceutical-grade supply through yeast-based expression systems eliminating fungal mycotoxin risks.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision fermentation startups targeting injectable-grade pectinase for oligosaccharide therapeutics. Five-to-ten-year viability hinges on regulatory approval velocity rather than manufacturing scale. Watch for CDSCO alignment with international pharmacopoeial standards as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Substrates | Captive molasses supply insulates Novozymes and Kerry Group from agricultural commodity volatility. |
| Precision Fermentation Scale-Up | Yeast-based expression systems unlock pharmaceutical-grade pectinase supply for Swiss oligosaccharide therapeutics. |
| Direct-to-Processor Digital Platform Launch | Subscription models bypass traditional distributor markups for mid-size Brazilian citrus processors. |
| REACH Annex XIV Pre-Registration | Liquid formulation conversions by Champagne houses preempt protein allergenicity assessment bottlenecks. |
| CRISPR Strain Development Partnership | Copenhagen-area biotech firms optimize Aspergillus lines for elevated galacturonase expression in Jutland facilities. |
Methodological Framework
Multiple input streams — technical discussions with fermentation plant managers, regulatory affairs leads at enzyme manufacturers, procurement directors at integrated fruit processors, and distribution channel partners — were reconciled against customs data, ECHA registration databases, FSSAI certification records, and SEC filings from publicly traded biotech conglomerates. Bottom-up volume estimates from individual bioreactor capacity and top-down demand aggregation from juice and wine processing volumes were triangulated to constrain forecast variance.
Data-stream reconciliation across formulation physics, application chemistry, biological origin, and geographic regulatory clusters shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume and value build-ups indexed to agricultural commodity futures and enzyme activity pricing trends. Forecast inputs included CRISPR strain development timelines, REACH Annex XIV authorization progressions, and FSSAI compliance rollout schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory divergence between ECHA and FDA allergenicity standards. A model refresh is warranted upon material change in EU Green Deal solvent mandate enforcement or precision fermentation yield breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Kelp Extracts Market
Extracts
Cassia Seed Extract Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
Aloe Vera Derivatives Market
Extracts
Belladonna Market
Extracts
Asia-Pacific Botanical Extract Market
Extracts
Palmarosa Oil Market
Extracts
Ovalbumin Powder Market
Extracts
Pearl Extract Market
Extracts
Nigella Sativa Extract Market
Extracts
Turpentine Market
Extracts
CO2 Extract Market
Extracts
Marine Algae Polysaccharides Market
Extracts
Herba Houttuyniae Extract Market
Extracts
Chamomile Oil Market
Extracts
Yucca Extract Material Market