
 Corn Steep Powder Market | 2026-2036
Corn Steep Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Steep Powder Market Outlook
Buyer concentration among large-scale animal nutrition compounders is hardening across North America and Western Europe. Cargill leverages its captive wet milling network to secure upstream supply of corn steep liquor solids. Tate & Lyle anchors its position through deep integration into fermentation-derived product streams. Archer Daniels Midland competes on geographic reach, with processing assets clustered near Midwest corn belts.
Corn steep powder comprises dried corn steep liquor solids containing crude protein, lactic acid, and B-vitamins recovered from corn wet milling steepwater evaporation. The material functions primarily as a nutrient-rich feed ingredient and fermentation substrate, with protein content typically ranging between 40% and 50% on a dry basis. Non-organic powder dominates volume owing to lower input costs and established supply chains, while organic variants command premium positioning in specialty feed and food additive channels. Fermentation applications represent the fastest-expanding end-use segment as microbial culture media demand intensifies across biotechnology.
The FDA enforces mycotoxin limits under the Food Safety Modernization Act, while the USDA monitors feed ingredient quality through its Agricultural Marketing Service. In Europe, EFSA evaluates corn steep powder for novel food and feed applications under evolving Novel Food Regulation frameworks. Stakeholders must monitor regulatory divergence between jurisdictions as biotech-grade specifications tighten and sustainability disclosure requirements expand.
Market Dynamics
Buyer concentration among North American compound feed manufacturers is consolidating procurement leverage, forcing corn steep powder suppliers toward certified mycotoxin-compliant production systems and long-term offtake contracts.
Growth Catalysts
- Fermentation Media Demand:Biotechnology firms are expanding microbial culture production, driving corn steep powder consumption as a nitrogen-rich substrate. Lactic acid content enhances bacterial growth rates in precision fermentation.
- USDA Feed Safety Mandates:The Agricultural Marketing Service enforces mycotoxin thresholds that favor certified suppliers, pushing compounders toward documented supply chains with batch-level testing protocols.
- Midwest Wet Milling Infrastructure:Concentrated corn processing capacity in Iowa, Illinois, and Nebraska creates localized supply advantages, reducing logistics costs for regional feed manufacturers.
Market Restraints
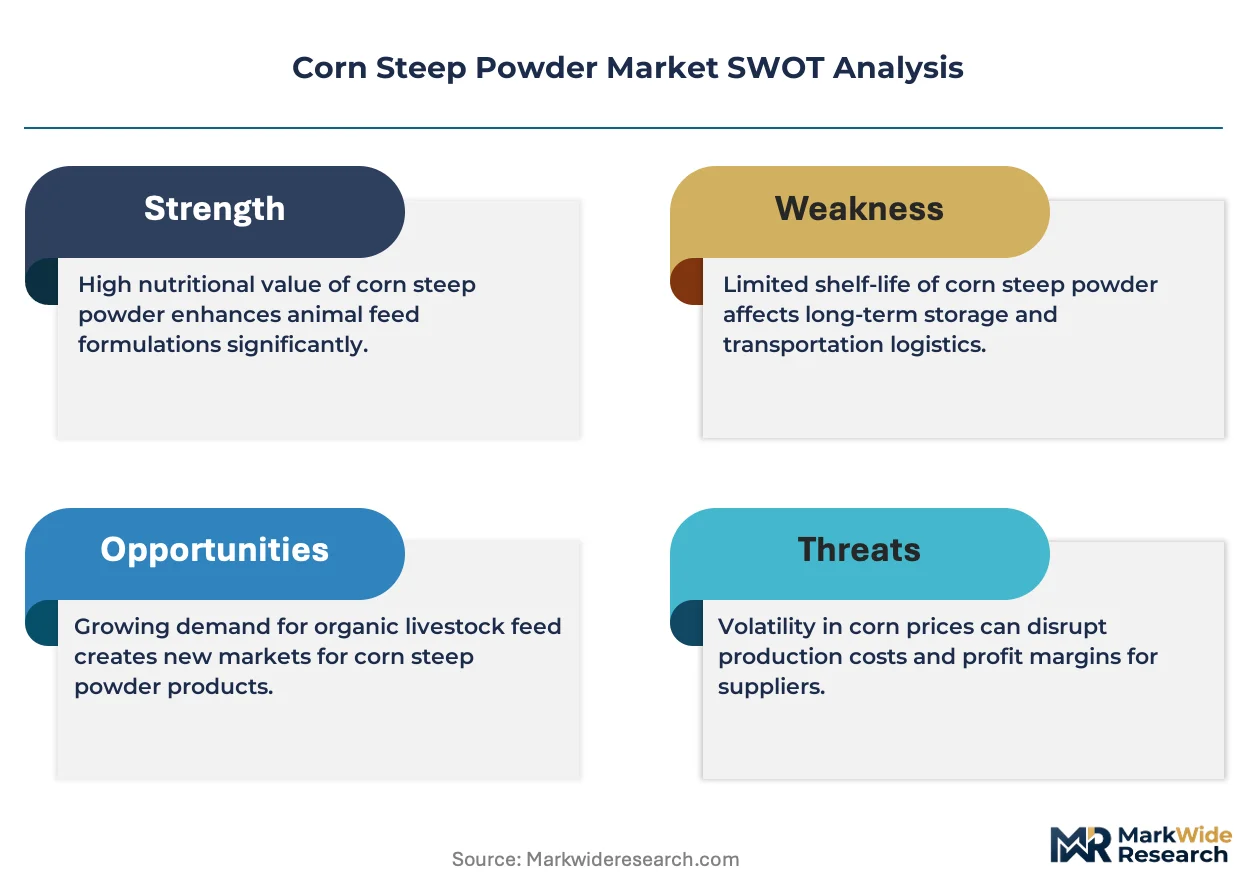
- Input Cost Volatility:Corn price fluctuations directly compress corn steep powder margins, as steep liquor solids remain tethered to grain commodity cycles without effective hedging mechanisms for by-product streams.
- Supply Concentration Risk:Wet milling capacity clusters among a handful of integrated processors, creating vulnerability to localized production disruptions or coordinated pricing behavior in concentrated geographies.
- Soybean Meal Substitution:Oilseed crush expansion in South America generates competitive protein meal supply, pressuring corn steep powder pricing in international feed formulations where amino acid profiles allow interchangeability.
Strategic Opportunities
- Organic Certification Premiums:Specialty livestock and aquaculture channels in Western Europe reward organic corn steep powder with price multiples, creating margin expansion for processors achieving EU organic regulation compliance.
- Precision Fermentation Scale-Up:Contract manufacturing organizations building microbial production facilities require standardized culture media, opening bulk supply contracts with biotechnology end-users.
- Carbon Accounting Integration:The EU Green Deal sustainability disclosure requirements favor corn steep powder as a low-carbon protein source against energy-intensive soybean processing, positioning the material in ESG-aligned procurement frameworks.
Industry Challenges
- Mycotoxin Testing Bottlenecks:FDA enforcement under the Food Safety Modernization Act requires batch-level aflatoxin and fumonisin screening, straining analytical laboratory capacity and extending release timelines.
- Drying Energy Intensity:Evaporating steep liquor to powder form consumes substantial thermal energy, exposing processors to natural gas price volatility and complicating decarbonization commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Steep Powder Market |
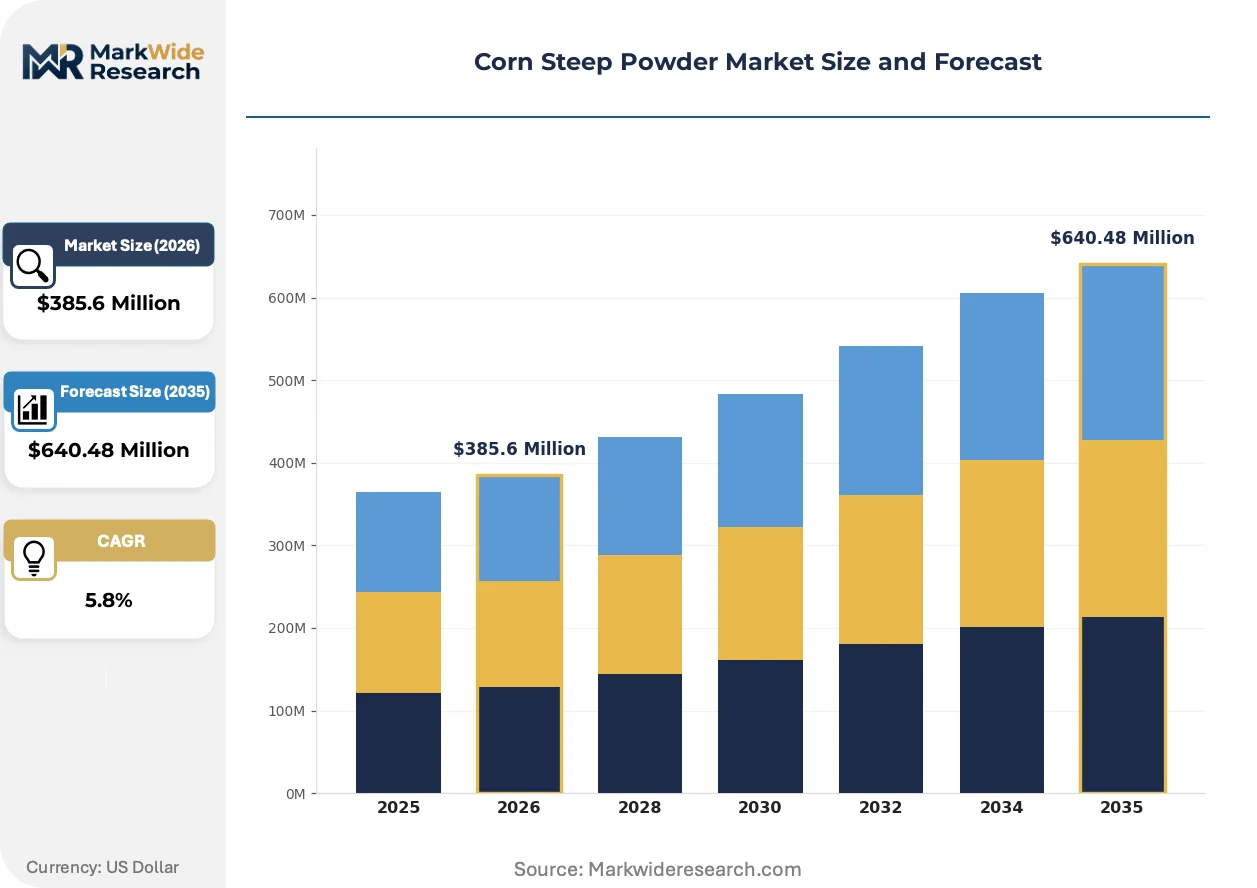
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Non-Organic, Liquid, Powder End User: Fertilizers, Animal Feed, Food Additives, Biotechnology Application: Agriculture, Aquaculture, Fermentation, Animal Nutrition Distribution Channel: Online, Offline, Wholesale, Retail |
| Companies Covered | Tate & Lyle, Cargill, Archer Daniels Midland, Roquette, Ingredion Incorporated, Grain Processing Corporation, Gulshan Polyols, Tereos, Global Bio-chem Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Steep Powder Market Strategic Shifts
Process intensification in corn wet milling is reshaping corn steep powder quality profiles, while regulatory disclosure mandates and biotechnology procurement standardization are redefining commercial requirements.
Spray drying technology with integrated lactic acid recovery is converging with membrane filtration systems to produce higher-purity corn steep liquor solids. Precision fermentation operators are adopting these refined grades for pharmaceutical-grade microbial culture media. This convergence is compressing the addressable market for commodity-grade powder while expanding premium-tier supply contracts.
The EU Green Deal Corporate Sustainability Reporting Directive now mandates Scope 3 emissions disclosure for large feed compounders, compelling documentation of agricultural input carbon intensity. Corn steep powder processors are responding with lifecycle assessments and mass-balance certifications. European compound feed manufacturers are most affected, prioritizing suppliers with verified low-carbon production methods.
Compound feed manufacturers are consolidating vendor lists and demanding multi-year supply agreements with fixed mycotoxin specifications. This behavior is displacing spot-market transactions and favoring integrated wet millers with captive laboratory testing infrastructure. The shift is most visible in the United States, where Tyson Foods and Smithfield subsidiary feed operations are standardizing approved supplier lists.
Corn Steep Powder Market Segmentation
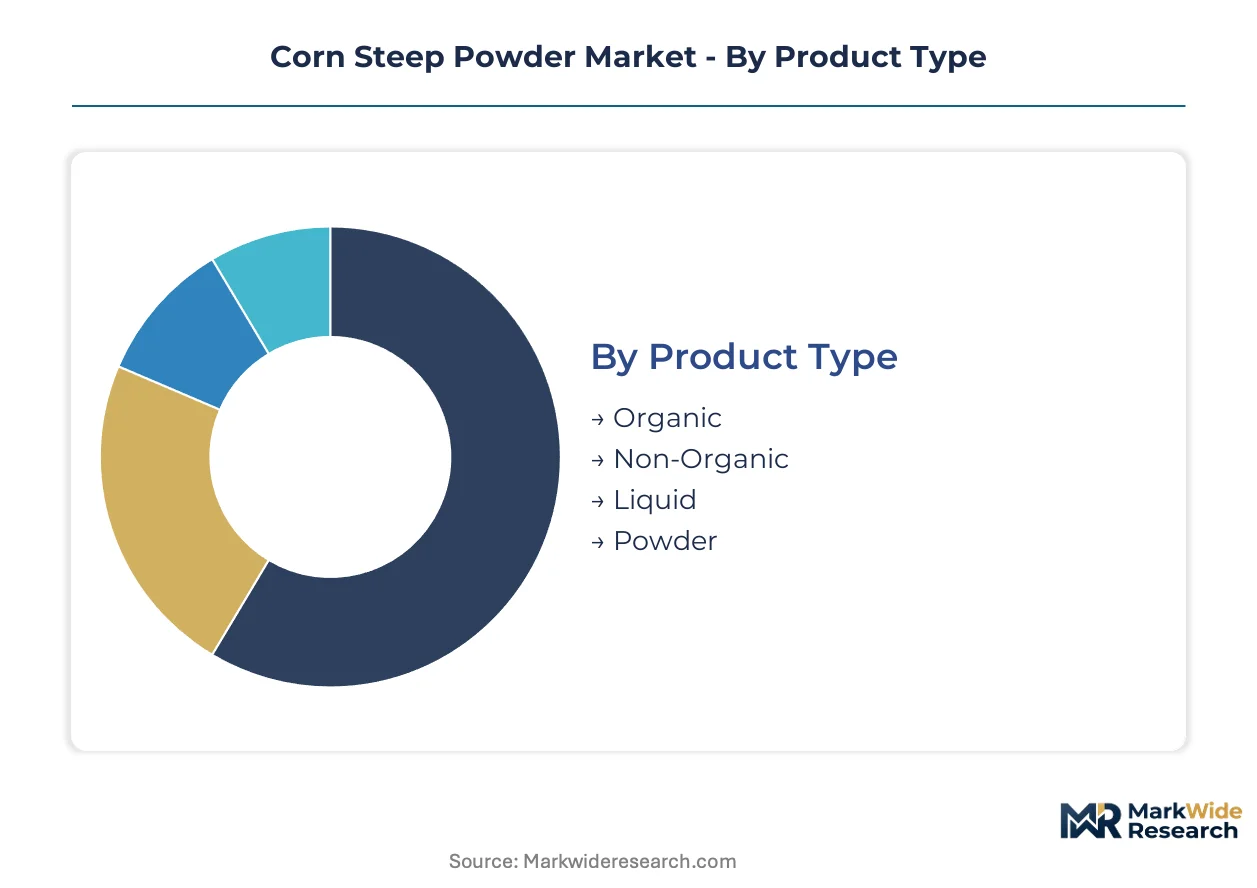
Corn steep powder procurement decisions pivot on certification status, end-use purity requirements, and volume scale. Buyers in animal feed and biotechnology evaluate protein content, mycotoxin documentation, and supply chain traceability differently across segment boundaries.
Product Type:
Cost tier determines access to premium pricing pools and regulatory compliance pathways.
- Non-Organic:Dried steep liquor solids produced through conventional wet milling without synthetic input restrictions. Protein content ranges 40-50% dry basis. Demand concentrates among Midwest compound feed manufacturers seeking least-cost protein supplementation, though USDA mycotoxin mandates now require batch-level documentation even for conventional grades.
- Organic:Certified production under USDA National Organic Program or EU organic regulation, with restricted pesticide and synthetic fertilizer use in upstream corn cultivation. Western European aquaculture and specialty livestock channels absorb supply at substantial premiums, driven by ESG-aligned procurement frameworks and retailer sustainability commitments.
- Liquid:Concentrated steep liquor before spray drying, shipped in bulk tanker configurations to regional compounders with on-site blending capacity.
- Powder:Spray-dried or drum-dried solids with extended shelf stability, favored by biotechnology fermentation facilities and export-oriented distributors.
Volume sits with Non-Organic; growth tilts toward Organic.
End User:
Application purity requirements separate commodity feed buyers from specification-sensitive biotechnology procurement.
- Animal Feed:Compound feed manufacturers integrate corn steep powder as a cost-effective protein source alongside amino acid balancing. Iowa, Illinois, and Nebraska livestock operations drive concentrated demand near wet milling infrastructure.
- Biotechnology:Precision fermentation operators require nitrogen-rich substrates with documented low endotoxin levels and consistent lactic acid content. Microbial culture media production is expanding most quickly in contract manufacturing facilities serving pharmaceutical and alternative protein sectors.
- Fertilizers:Agricultural input blenders incorporate steep liquor solids for micronutrient content and soil conditioning properties.
- Food Additives:Limited specialty applications in fermentation-derived flavor and coloring agents, constrained by FDA food-grade specification requirements.
Procurement scale favors Animal Feed; margin expansion concentrates in Biotechnology.
Application:
End-use performance specifications dictate processing intensity and certification investment.
- Animal Nutrition:Ruminant and monogastric feed formulations utilize crude protein and B-vitamin content for growth promotion and feed conversion efficiency.
- Fermentation:Industrial biotechnology applications require refined grades with controlled mineral profiles for consistent microbial growth rates.
- Agriculture:Direct soil amendment and organic fertilizer blending leverage phosphorus and micronutrient availability.
- Aquaculture:Shrimp and fish feed compounders in Western Europe specify organic-certified powder to meet retailer sustainability audit requirements.
Established volume flows through Animal Nutrition; Fermentation commands steepest expansion trajectory.
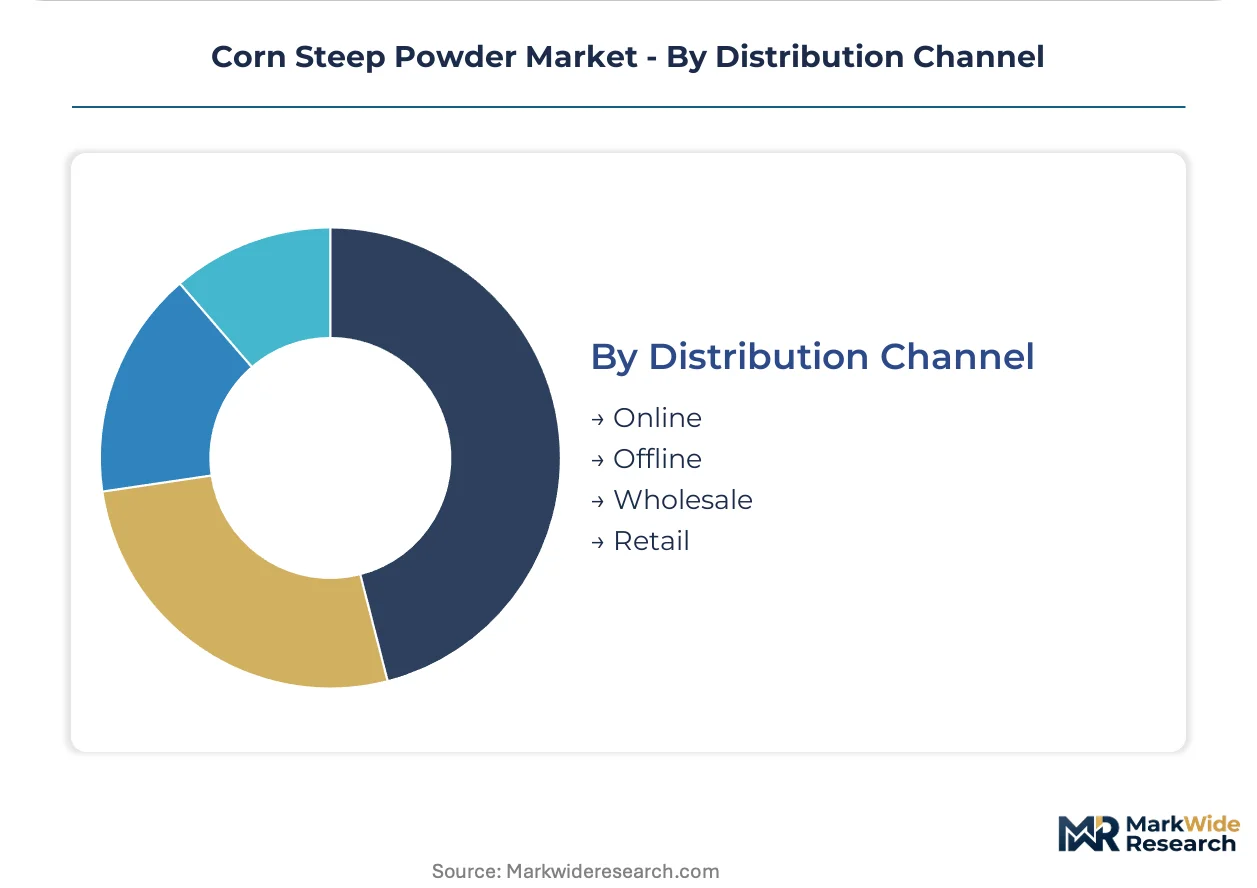
Distribution Channel:
Customer scale and geographic concentration determine channel economics and relationship structure.
- Wholesale:Integrated wet millers ship bulk powder and liquid directly to compound feed manufacturers under multi-year offtake agreements with fixed mycotoxin specifications.
- Offline:Regional distributors maintain inventory for smaller compounders and specialty agriculture buyers requiring technical support and flexible order quantities.
- Online:Emerging platform procurement for research-grade and small-volume biotechnology applications, with limited penetration in bulk feed ingredient trade.
- Retail:Garden and hobby agriculture packaging represents minimal volume, primarily organic-certified products for consumer direct sales.
Contracted volume anchors Wholesale; channel diversification favors Offline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for corn steep powder concentrates in agricultural and biotechnology hubs where wet milling infrastructure intersects with dense livestock operations and fermentation capacity.
United States
Iowa, Illinois, and Nebraska compound feed manufacturers purchase the majority of North American corn steep powder volume. The USDA Agricultural Marketing Service enforces mycotoxin thresholds that favor certified suppliers with batch-level documentation. Archer Daniels Midland operates processing assets clustered throughout the Midwest corn belt, securing captive supply for regional distribution.
Germany
Western European aquaculture and specialty livestock channels absorb organic-certified powder at substantial premiums. The EU Green Deal Corporate Sustainability Reporting Directive mandates Scope 3 emissions disclosure, compelling feed compounders to document agricultural input carbon intensity. Bavaria and North Rhine-Westphalia host biotechnology fermentation facilities requiring nitrogen-rich microbial culture substrates.
China
Domestic corn wet milling expansion supports both animal feed and industrial fermentation applications. The Ministry of Ecology and Environment monitors processing emissions under dual carbon goals, pressuring energy-intensive drying operations toward efficiency upgrades. Shandong Province and the Yangtze River Delta concentrate starch processing capacity with integrated steep liquor recovery systems.
Brazil
Soybean meal dominance in regional feed formulations creates competitive pressure on corn steep powder pricing, though proximity to expanding poultry and swine operations sustains niche demand. ANVISA maintains feed ingredient safety standards that align with export market requirements. São Paulo and Paraná state processors balance domestic supply against Mercosur trade flows.
India
Growing compound feed manufacturing in Gujarat and Maharashtra generates procurement pull for cost-effective protein supplementation. The Food Safety and Standards Authority of India monitors mycotoxin limits in feed-grade ingredients, pushing suppliers toward testing infrastructure investment. Gulshan Polyols represents domestic processing capacity serving regional agriculture and fermentation end-users.
Corn Steep Powder Market Competitive Environment
United States producers anchor one tier; European specialists hold certification-driven positioning in premium channels. The vendor base clusters around integrated wet millers with captive laboratory infrastructure and regional distributors serving smaller compounders. Three archetypes dominate: multinational agribusiness conglomerates with backward integration into corn processing, mid-scale regional processors competing on logistics proximity, and biotechnology-focused refiners supplying pharmaceutical-grade culture media. Capacity consolidation and multi-year offtake contracting constitute the primary competitive moves.
Within the integrated agribusiness tier, Cargill, Tate & Lyle, and Archer Daniels Midland exemplify divergent strategic positioning. Cargill leverages its captive wet milling network to secure upstream supply of steep liquor solids. Tate & Lyle anchors its competitive position through deep integration into fermentation-derived product streams. Archer Daniels Midland competes on geographic reach, with processing assets concentrated near Midwest corn belts to minimize logistics costs for regional feed manufacturers.
| Leading Market Players |
|---|
| Tate & Lyle |
| Cargill |
| Archer Daniels Midland |
| Roquette |
| Ingredion Incorporated |
| Grain Processing Corporation |
| Gulshan Polyols |
| Tereos |
| Global Bio-chem Technology Group |
| Others |
Value Chain & Pricing Dynamics
Family-owned wet milling operations in the US Midwest anchor supply discipline through long-term corn supply contracts and captive steep liquor recovery, translating input cost stability into pricing power over regional compound feed manufacturers facing USDA mycotoxin compliance mandates.
Pricing Analysis
Volume concentrates in non-organic commodity grades while margin expansion concentrates in organic-certified and biotechnology-refined tiers. Price differentiation separates USDA-certified batch-documented powder from conventional grades, with organic variants commanding substantial premiums in Western European aquaculture channels. Pricing pressure stems from South American soybean meal expansion pressuring protein substitution economics in international formulations. Midwest compound feed manufacturers exhibit highest price sensitivity due to least-cost ration formulation requirements, while precision fermentation operators demonstrate lowest sensitivity given substrate quality criticality for microbial culture yields.
Supply Chain Analysis
Freight economics favor supply concentration within 300-mile radiuses of wet milling infrastructure, with Iowa, Illinois, and Nebraska forming the dominant production cluster. Corn cultivation draws from Midwest grain belts, while natural gas feeds thermal drying operations and lactic acid recovery systems. Single-source vulnerability concentrates among integrated processors with captive laboratory infrastructure, creating procurement risk during localized production disruptions. Distribution runs through multi-year offtake contracts with fixed mycotoxin specifications, displacing spot-market transactions among large-scale compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FDA Food Safety Modernization Act enforcement creates a barrier-to-entry moat favoring processors with batch-level testing infrastructure and documented supply chains.
For Market Incumbents: Cement laboratory certification advantages through expanded mycotoxin testing capacity and long-term offtake contracting with Tyson Foods and Smithfield subsidiary feed operations. Threat substitution from South American soybean meal expansion demands backward integration into corn processing assets near Midwest livestock density clusters to defend logistics-cost positioning.
For New Entrants and Emerging Players: Begin with organic certification pathways targeting Western European aquaculture channels where retailer sustainability audits create specification premiums unavailable to conventional processors. The penetrable segment sits with biotechnology fermentation facilities requiring pharmaceutical-grade culture media, approached through membrane filtration technology partnerships with precision fermentation contract manufacturers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale regional processors with laboratory infrastructure in Iowa and Illinois during corn price volatility compressing margins for undifferentiated commodity producers. Long-term viability centers on fermentation-grade refinement capability and carbon accounting documentation for EU Green Deal procurement compliance. The inflection signal to monitor is biotechnology facility construction permitting activity in Bavaria and North Rhine-Westphalia.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Processing | Cargill and Archer Daniels Midland secure captive steep liquor supply through Midwest wet milling assets. |
| Organic Certification Investment | EU Green Deal disclosure requirements reward USDA National Organic Program compliance with premium channel access. |
| Precision Fermentation Partnership | Tate & Lyle leverages fermentation-derived product integration for pharmaceutical-grade culture media contracts. |
| Mycotoxin Testing Infrastructure Expansion | FDA enforcement under FSMA mandates batch-level aflatoxin screening favoring laboratory-capable processors. |
| Carbon Accounting Documentation | Scope 3 emissions disclosure requirements position corn steep powder against energy-intensive soybean processing. |
Study Parameters
Independent corroboration across wet miller procurement directors, compound feed manufacturing executives, and biotechnology fermentation specialists underwrites the qualitative findings. Primary fieldwork encompassed plant managers at corn processing facilities, procurement leads at Midwest livestock operations, regulatory affairs directors navigating FDA and USDA compliance pathways, and technical R&D heads at precision fermentation contract manufacturers. Secondary validation drew from USDA Agricultural Marketing Service reports, FDA Food Safety Modernization Act guidance documents, SEC 10-K filings of integrated agribusiness conglomerates, and EU Green Deal Corporate Sustainability Reporting Directive technical standards. Bottom-up volume modeling from facility-level capacity assessments triangulates against top-down demand aggregation from end-use consumption patterns.
Comparable-period anchoring to historical corn wet milling output and steep liquor recovery rates established the forecast baseline across the projection horizon. Segmentation modeling incorporated product type tiers, end-use application purity requirements, geographic production clusters, and certification status dimensions. CAGRs were derived through regression analysis of input-output relationships between corn processing volumes and steep powder yields, calibrated against biotechnology fermentation capacity expansion trajectories and livestock feed formulation substitution elasticities.
Underlying measurement precision varies by segment; organic-certified and biotechnology-grade powder carry tighter precision than commodity feed-grade volumes due to concentrated supplier bases and documented transaction flows. Forecasts reflect assumptions regarding corn price cycles, regulatory enforcement intensity, and fermentation facility construction timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Algae Extracts Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
Valerian Root Powder Market
Extracts
Saffron Extract Market
Extracts
Patchouli Oil Market
Extracts
CO2 Extract Market
Extracts
Natural Rosemarine Extract Market
Extracts
Functional Extract Market
Extracts
Marigold Essential Oil Market
Extracts
Wild Yam Powder Market
Extracts
Hibiscus Flower Powder Market
Extracts
Cornflower Extract Market
Extracts
Sandalwood Oil Market
Extracts
Basil Extracts Market
Extracts
Botanicals Market
Extracts
Passion Flower Extracts Market