
 Algae Extracts Market | 2026-2036
Algae Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Algae Extracts Market Analysis
EU Novel Food Regulation is pivoting the cost-of-entry calculus for algae-derived ingredients entering European food and nutraceutical channels. DSM-Firmenich leverages captive spirulina cultivation in Israel to secure supply continuity for carotenoid production. BASF anchors its marine biotechnology portfolio through specialized extraction partnerships in Scandinavia. Cargill competes in the feed additive segment with algal omega-3 alternatives to fish oil.
Algae extracts comprise bioactive compounds—phycocyanins, fucoxanthins, astaxanthins, and sulfated polysaccharides—harvested from microalgae and macroalgae biomass through solvent extraction, supercritical CO2 processing, or aqueous separation, serving primarily as functional ingredients across nutrition, personal care, and animal health formulations. Spirulina and chlorella dominate the product type landscape due to established cultivation infrastructure and broad regulatory acceptance, while kelp extracts command premium positioning in cosmetic applications where fucoidan content drives formulator interest. The nutraceuticals application segment captures concentrated margin pools as clinical validation for algal bioactives expands, though food additives sustain higher absolute volumes through bakery and beverage fortification.
FDA GRAS determinations and EFSA novel food opinions shape market access timelines for new algal species entrants, while China's NMPA and SAMR govern functional food registration requirements for domestic distribution. USDA organic certification and EU organic regulation create parallel premium tiers that influence procurement decisions among North American and European finished goods manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions where biomass sourcing claims and extraction method disclosures face escalating scrutiny.
Market Dynamics
Cosmetic formulators in South Korea are accelerating fucoxanthin-rich kelp extraction capacity to meet clean-label positioning requirements, while EU Novel Food Regulation approvals compress time-to-market for chlorella and spirulina entrants. This dual regulatory-technology pressure is restructuring competitive access across nutraceutical and personal care channels.
Growth Catalysts
- EU Novel Food Regulation streamlining:EFSA novel food opinions now create predictable approval timelines for chlorella and spirulina ingredients, reducing regulatory uncertainty for European market entry.
- Fucoxanthin demand from cosmetic formulators:South Korean skincare manufacturers are expanding kelp derivative procurement to capitalize on antioxidant positioning in anti-aging formulations.
- Coastal processing cluster integration:China's biomass cultivation facilities in Shandong and Fujian provinces are linking directly to downstream extraction infrastructure, shortening supply cycles.
Market Restraints
- Biomass input cost volatility:Open-pond spirulina cultivation faces climate-driven yield fluctuations in subtropical zones, compressing margin predictability for commodity-grade producers.
- Extraction technology concentration:Supercritical CO2 processing capacity clusters in Germany and Japan, creating equipment access bottlenecks for mid-scale entrants.
- Fish oil substitution ceiling:Algal omega-3 alternatives face entrenched cost positioning from Peruvian anchovy fisheries in bulk feed applications.
Strategic Opportunities
- USDA organic certification tier:Premium-tier algae extracts command procurement preference among North American finished goods manufacturers seeking label differentiation.
- Sulfated polysaccharide expansion:Fucoidan applications in functional beverages remain underdeveloped relative to established cosmetic channels.
- Israeli captive cultivation models:Controlled-environment spirulina production in arid climates offers supply continuity advantages for carotenoid extraction.
Industry Challenges
- Phycocyanin stability expertise gap:Formulation chemists with algal pigment stabilization experience remain scarce relative to synthetic colorant specialists.
- Dual jurisdiction compliance timelines:Simultaneous FDA GRAS determinations and EFSA novel food opinions create parallel resource drains for species entrants.
- Aqueous extraction capex requirements:Cold-water processing infrastructure for bioactive preservation demands front-loaded capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algae Extracts Market |
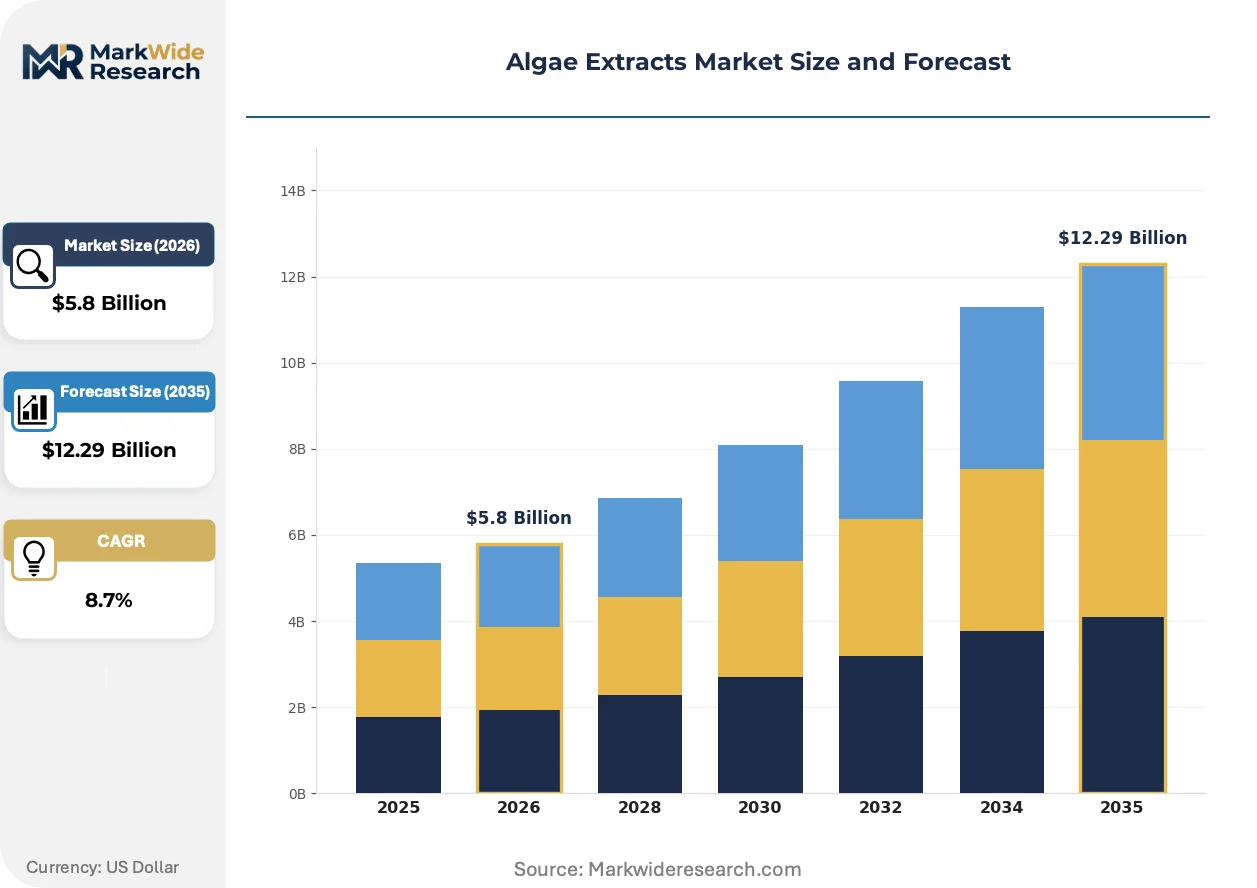
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirulina, Chlorella, Wakame, Kelp Application: Food Additive, Nutraceuticals, Cosmetics, Feed Additive Form: Powder, Liquid, Gel, Capsule End User: Food Industry, Pharmaceutical Industry, Cosmetic Industry, Animal Nutrition |
| Companies Covered | DSM-Firmenich, BASF, Cargill, Corbion, Cyanotech Corporation, CP Kelco, DuPont, Gelymar, Algatechnologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algae Extracts Market Emerging Trajectories
Supercritical CO2 extraction is overtaking solvent-based methods as the dominant processing technology for high-value carotenoid recovery, compressing residual solvent concerns and enabling clean-label positioning. This shift is restructuring equipment vendor relationships and regional processing capacity distribution.
Supercritical CO2 extraction systems recover fucoxanthin and astaxanthin without hexane or ethanol residues, satisfying EU organic regulation constraints. Scandinavian extraction partnerships are expanding capacity fastest, driven by EFSA novel food opinion precedents for kelp-derived bioactives. This technology is overtaking conventional solvent methods in premium cosmetic and nutraceutical applications where residual solvent thresholds approach zero.
EFSA novel food opinions are creating harmonized safety validation pathways for chlorella and spirulina ingredients across EU member states. The regulation compresses national-level approval fragmentation that previously required redundant toxicology submissions. Nutraceutical contract manufacturers in Germany and the Netherlands are consolidating formulation pipelines around EFSA-cleared species to streamline multi-market distribution.
Clean-label procurement mandates from finished goods manufacturers are compressing synthetic additive substitution timelines. Brand owners in personal care and functional food segments are requiring third-party verification of extraction method and biomass origin. This verification-driven sourcing is most visible in North American and Western European markets where USDA organic certification and EU organic regulation create parallel premium tiers.
Algae Extracts Market Segmentation
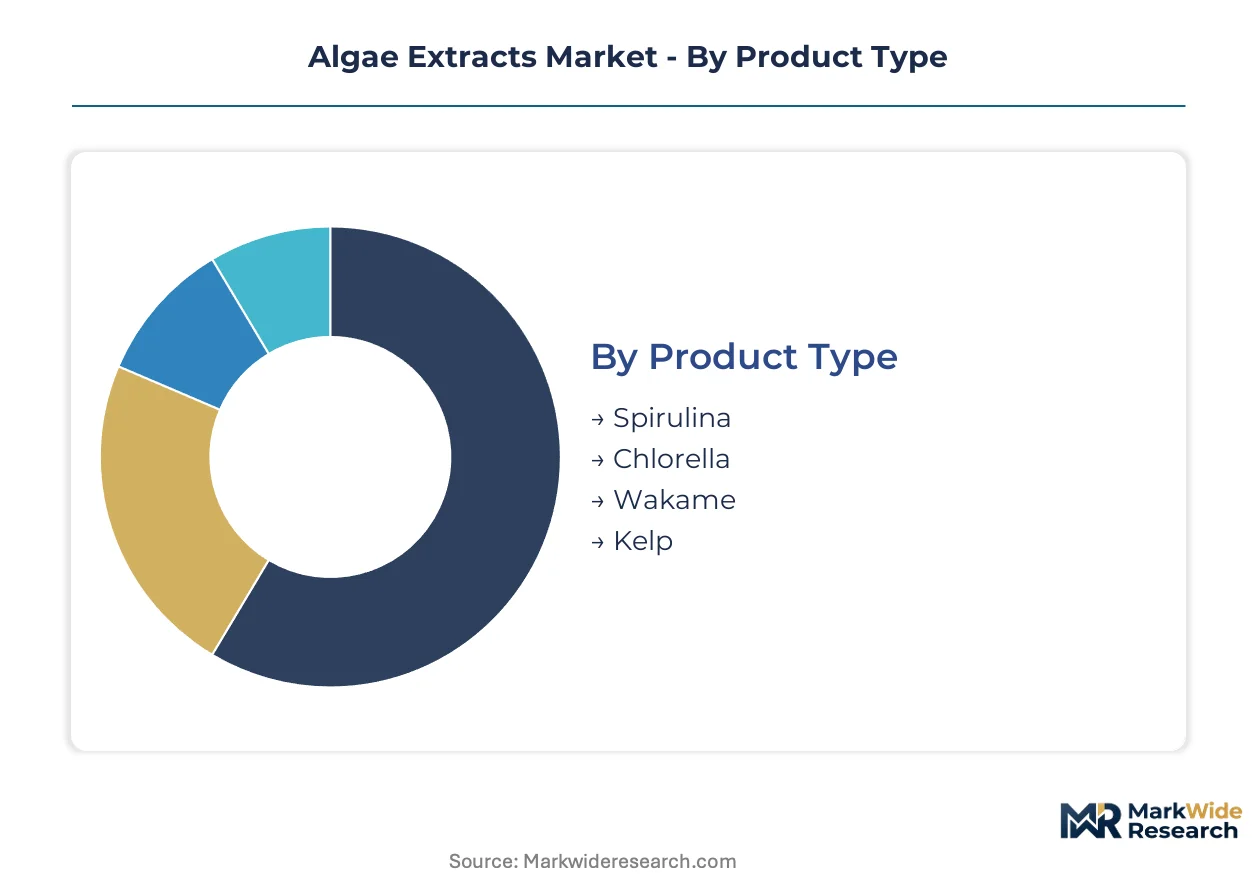
Algae extracts fragment across biomass source, processing intensity, and regulatory clearance requirements. Each segmentation axis carries distinct margin profiles and certification burdens that reshape procurement decisions for finished goods manufacturers.
Product Type:
Standardization dominates commodity-grade biomass while premium tiers demand species-specific phytochemical profiles and traceable cultivation conditions.
- Spirulina:Cyanobacterial biomass rich in phycocyanin and protein concentrates. Demand concentrates in German nutraceutical contract manufacturing where EFSA novel food opinions enable streamlined multi-market distribution. Regulatory clearance density makes this the default entry point for new European market entrants.
- Chlorella:Single-celled green algae with established cell-wall disruption protocols for bioavailability. South Korean cosmetic formulators drive premium procurement for detoxification-positioned skincare lines. Broken-cell processing requirements create technology moats between commodity and pharmaceutical-grade suppliers.
- Wakame:Brown macroalgae harvested for fucoxanthin and dietary fiber content. Japanese functional food manufacturers anchor procurement volumes.
- Kelp:Laminaria species extracted for fucoidan and iodine compounds. Norwegian and Icelandic coastal processors dominate supply.
Leading the category by volume: Spirulina. Expanding most quickly: Kelp.
Application:
Cost tiers separate commodity fortification from clinical-grade bioactive delivery, with certification requirements widening the gap.
- Nutraceuticals:Clinical-grade extracts for dietary supplements and functional medicine protocols. US finished goods manufacturers prioritize FDA GRAS determinations for new species entrants, compressing development timelines for cleared biomass. Margin concentration here exceeds other application tiers due to dosage standardization requirements.
- Cosmetics:Bioactive positioning for anti-aging and photoprotection claims. South Korean formulators drive fucoxanthin-rich kelp derivative procurement to meet clean-label positioning mandates. Stability expertise for algal pigments remains scarce relative to synthetic colorant chemistry pools.
- Food Additive:Natural colorants and texture modifiers for bakery and beverage fortification. Higher absolute volumes sustain processing infrastructure.
- Feed Additive:Algal omega-3 alternatives to fish oil for aquaculture and livestock. Peruvian anchovy cost positioning limits penetration in bulk applications.
Dominating by revenue capture: Nutraceuticals. Gaining share fastest: Cosmetics.
Form:
Supply concentration clusters around powder processing, with liquid and gel formats demanding specialized stabilization expertise.
- Powder:Spray-dried or freeze-dried biomass with standardized moisture content. China's Shandong and Fujian coastal clusters integrate cultivation directly with downstream drying infrastructure, shortening supply cycles for commodity-grade procurement.
- Liquid:Aqueous extracts requiring cold-chain integrity and preservative systems. German extraction partnerships anchor supercritical CO2-derived carotenoid suspensions for premium cosmetic applications.
- Gel:Hydrogel matrices for topical delivery and controlled-release formulations. Israeli controlled-environment cultivation supports supply continuity for high-viscosity extracts.
- Capsule:Encapsulated powders and oils for precise dosing in supplement applications. North American manufacturers prioritize USDA organic certification tiers for label differentiation.
Anchor by volume: Powder. Steepest expansion trajectory: Capsule.
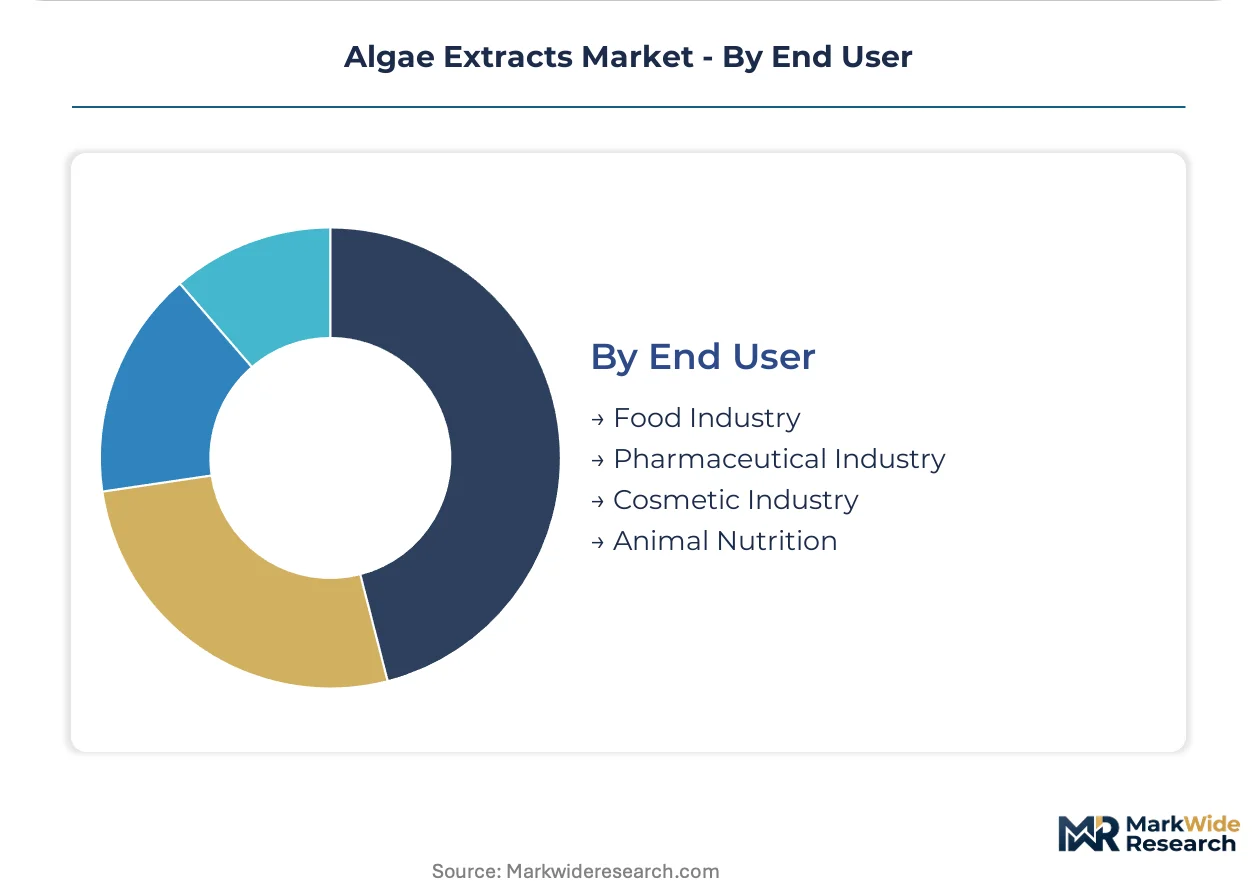
End User:
Customer type determines specification stringency, with pharmaceutical and cosmetic channels demanding full traceability while food industry procurement tolerates broader biomass sourcing.
- Cosmetic Industry:Formulators require third-party verification of extraction method and biomass origin for clean-label positioning. EU organic regulation compliance creates parallel premium tiers that influence procurement decisions among Western European finished goods manufacturers.
- Pharmaceutical Industry:Active pharmaceutical ingredient precursors and excipients with batch-level documentation. Dual jurisdiction compliance timelines for FDA GRAS and EFSA novel food opinions create parallel resource drains for species entrants targeting both markets.
- Food Industry:Natural colorants, emulsifiers, and fortification agents for processed foods. China's NMPA and SAMR govern functional food registration requirements for domestic distribution.
- Animal Nutrition:Feed-grade algae for aquaculture, poultry, and livestock omega-3 enrichment. Cost positioning against Peruvian anchovy fisheries constrains volume expansion.
Leading by absolute procurement volume: Food Industry. Climbing the fastest: Cosmetic Industry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province's marine biotechnology industrial parks attract algae processors through tax abatements and subsidized cold-chain infrastructure. Coastal special economic zones in China, Norway, and South Korea concentrate extraction capacity near biomass cultivation sites.
China
Shandong and Fujian coastal clusters integrate kelp and spirulina cultivation with downstream spray-drying infrastructure. NMPA and SAMR govern functional food registration requirements for domestic distribution. Qingdao's marine science park anchors supercritical CO2 equipment deployment for carotenoid extraction.
South Korea
Cosmetic formulators in Seoul and Busan drive fucoxanthin-rich kelp derivative procurement for anti-aging skincare lines. MFDS regulates novel ingredient safety assessments for functional cosmetics. Jeju Island's controlled-environment cultivation facilities supply premium biomass to domestic extractors.
Germany
Nutraceutical contract manufacturers in Hamburg and Frankfurt consolidate formulation pipelines around EFSA-cleared chlorella and spirulina species. EFSA novel food opinions streamline multi-market distribution across EU member states. Bavaria's extraction technology vendors dominate supercritical CO2 equipment supply to Scandinavian processors.
Norway
Kelp harvesting cooperatives in Nordland and Troms supply Laminaria biomass for fucoidan extraction to pharmaceutical and cosmetic channels. REACH compliance governs chemical safety documentation for exported bioactives. Bergen's marine biotechnology cluster hosts specialized extraction partnerships serving EU organic regulation premium tiers.
Israel
Arid-climate controlled-environment spirulina farms near Eilat secure supply continuity for carotenoid production. The national food regulator oversees novel food safety validations for export-bound ingredients. Negev Desert cultivation facilities leverage solar thermal energy for closed-pond temperature management.
Algae Extracts Market Vendor Landscape
Scandinavian and Israeli producers anchor the premium extraction tier; Chinese coastal processors hold commodity-grade volume leadership. The vendor base separates into three strategic archetypes: multinational ingredient conglomerates with captive cultivation, specialized marine biotechnology firms with regional extraction partnerships, and integrated coastal processors controlling biomass-to-extract supply chains. Competitive moves concentrate on supercritical CO2 capacity expansion and EFSA novel food opinion precedents for species clearance.
Within the multinational ingredient tier, DSM-Firmenich and BASF occupy positions defined by captive supply arrangements and specialized extraction partnerships respectively. Cargill represents the scale-driven feed additive archetype competing against fish oil incumbents. These three entities exemplify divergent strategic postures: biotechnology-forward cultivation control, regional extraction alliance networks, and commodity-scale algal omega-3 positioning.
| Leading Market Players |
|---|
| DSM-Firmenich |
| BASF |
| Cargill |
| Corbion |
| Cyanotech Corporation |
| CP Kelco |
| DuPont |
| Gelymar |
| Algatechnologies |
| Others |
Supply Flow & Price Mechanics
Supercritical CO2 extraction specialists concentrated in Germany and Japan command wage premiums that widen spreads between premium solvent-free extracts and commodity-grade solvent-processed alternatives. Labor-cost differentials between these high-skill processing hubs and China's coastal drying clusters translate directly into three-tier pricing stratification across cosmetic and nutraceutical channels.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with cosmetic formulators in South Korea paying premiums for sub-30-day kelp derivative delivery while spot inventory of spirulina powder trades at discounts in Shandong. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-cleared organic extracts from conventional grades and uncertified commodity biomass. Pricing pressure stems from Peruvian anchovy cost positioning in feed-grade omega-3 applications, compressing algal alternatives. Feed additive buyers exhibit highest price sensitivity; cosmetic manufacturers demonstrate lowest sensitivity due to clean-label positioning mandates.
Supply Chain Analysis
Dual-sourcing requirements from German nutraceutical contract manufacturers mandate multi-supplier qualification across Israeli spirulina farms and Chinese coastal processors. Geographic supply concentrates in China, Norway, and Israel, with each anchoring distinct biomass-to-extract pathways. Raw material dependencies span open-pond spirulina cultivation, Laminaria kelp harvesting, and supercritical CO2 equipment feedstock. Single-source vulnerability clusters around Japanese and German extraction technology vendors. Distribution runs through specialized marine biotechnology distributors serving cosmetic and pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 processing capacity constraints in Germany and Japan prop pricing premiums for solvent-free extracts, creating supply-constrained conditions that favor incumbent positioning.
For Market Incumbents: Deploy captive cultivation partnerships to secure biomass continuity against climate-driven yield volatility in subtropical spirulina zones. BASF's Scandinavian extraction alliance model offers template for regional technology access without full equipment ownership. EFSA novel food opinion precedents for chlorella and spirulina create regulatory moats against unvalidated species entrants. Capacity addition in Israeli arid-climate facilities addresses supply continuity risks from open-pond concentration. For New Entrants and Emerging Players: EU Novel Food Regulation streamlining in Europe opens a window for species entrants targeting multi-market distribution through German contract manufacturing consolidation. White-space targets include sulfated polysaccharide applications in functional beverages, currently underdeveloped relative to cosmetic fucoidan channels. Fucoxanthin-rich kelp derivatives for South Korean skincare manufacturers represent most penetrable premium segment. Go-to-market angle: aqueous extraction expertise for cold-chain liquid formats where stabilization chemistry gaps limit competition. For Investors and Strategic Acquirers: Re-rating potential sits with specialized marine biotechnology firms possessing EFSA-cleared species portfolios and supercritical CO2 capacity access, given cosmetic formulator procurement consolidation around verified extraction methods. Long-term viability favors processors with backward integration into controlled-environment cultivation. Acquisition target archetype: mid-scale Norwegian or Icelandic kelp extractors with EU organic certification and pharmaceutical channel relationships. Signal to watch: EFSA novel food opinion expansion beyond chlorella and spirulina to additional macroalgae species.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Positions extractors to meet EU organic regulation residual solvent thresholds for cosmetic applications. |
| Captive Cultivation Partnership | Secures biomass supply continuity against climate volatility in open-pond spirulina zones. |
| EFSA Novel Food Opinion Pursuit | Enables streamlined multi-market distribution across EU member states for cleared species. |
| USDA Organic Certification Investment | Unlocks premium-tier procurement preference among North American finished goods manufacturers. |
| Functional Beverage Application Development | Captures underpenetrated demand for sulfated polysaccharides beyond established cosmetic channels. |
Methodological Framework
Document review covered EFSA novel food opinion databases, FDA GRAS determination filings, and EU organic regulation compliance records, complemented by interviews with extraction technology vendors, cosmetic formulator procurement leads, and nutraceutical contract manufacturing executives. Secondary validation drew from customs trade data, marine biotechnology patent filings, and coastal processing cluster infrastructure disclosures. Bottom-up biomass cultivation estimates and top-down extract demand projections were triangulated against regional regulatory clearance timelines.
Segmentation outputs reflect modeling across biomass source, processing intensity, application channel, and regulatory certification tier throughout the forecast period. CAGRs were derived from growth rate reconciliation between supply-side capacity expansion and demand-side formulation adoption curves. Industry-specific inputs included EFSA opinion pipeline status, supercritical CO2 equipment deployment schedules, and clean-label procurement mandate diffusion rates among finished goods manufacturers.
The model assumes a particular technology adoption path; alternative pathways for aqueous cold-water extraction would alter the outlook if phycocyanin stabilization chemistry advances reduce cold-chain dependency. Forecasts reflect assumptions regarding EFSA novel food opinion timeline continuity and climate stability in subtropical cultivation zones. Deviation in EU organic regulation enforcement stringency or open-pond yield volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Botanical CO2 Extracts Market
Extracts
Yucca Extract Material Market
Extracts
Bee Venom Extract Market
Extracts
Apple Powder Market
Extracts
CO2 Extract Market
Extracts
China Cedar Wood Oil Market
Extracts
Labdanum Market
Extracts
Cochineal Extract Market
Extracts
Pectin Powder Market
Extracts
Kelp Extracts Market
Extracts
Citronella Oil Market
Extracts
Botanicals Market
Extracts
Turpentine Market
Extracts
Corn Steep Powder Market
Extracts
Gum Turpentine Oil Market
Extracts
Floral Extract Market