
 Medicinal Plant Extracts Market | 2026-2036
Medicinal Plant Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Medicinal Plant Extracts Market Outlook
Direct procurement between extract manufacturers and finished goods producers is tilting away from traditional trading house intermediaries. Indena S.p.A. leverages vertical integration from cultivation to purification to control supply security for high-value compounds. Sabinsa Corporation anchors its position through patented bioavailability technologies and India-based raw material sourcing. Naturex competes by extending its botanical ingredient platform across European and North American customer bases.
Medicinal plant extracts are concentrated preparations obtained from herbs, flowers, roots, or barks through solvent extraction, distillation, or cold pressing, standardized to defined marker compound levels for therapeutic consistency. Essential oils and dry extracts command the deepest margin pools due to concentration efficiency and shelf stability advantages in pharmaceutical applications. Powders sustain volume leadership in dietary supplements where cost-sensitive formulation dominates, while tinctures occupy niche positions in practitioner-directed channels requiring dose flexibility.
FDA New Dietary Ingredient notifications, EMA herbal monographs, and ISO 17025 laboratory accreditation frameworks collectively raise the compliance threshold for market entry and batch certification. These standards force smaller suppliers toward contract manufacturing partnerships or exit, concentrating supply among validated producers. Stakeholders must monitor evolving pharmacovigilance requirements for botanical-drug interaction databases as polypharmacy risks attract regulatory scrutiny.
Market Dynamics
Pharmaceutical manufacturers are consolidating procurement around validated extract suppliers capable of batch-level pharmacovigilance documentation, compressing the vendor base and forcing capital investment in ISO 17025-compliant analytical infrastructure.
Growth Catalysts
- FDA New Dietary Ingredient notifications:The notification pathway is accelerating demand for pre-validated botanical extracts among supplement manufacturers seeking faster time-to-market.
- Germany's phytotherapy reimbursement framework:Statutory health insurance coverage for herbal medicines sustains predictable demand for standardized dry extracts in prescription channels.
- Supercritical CO2 extraction:This solvent-free technology is expanding addressable markets for heat-sensitive alkaloids and terpenoid fractions in pharmaceutical applications.
Market Restraints
- Wild-harvested raw material volatility:Climate-induced yield fluctuations in Indian turmeric and Chinese ginseng root concentrate supply risk in sourcing geographies with weak agricultural forecasting.
- EMA herbal monograph compliance costs:The documentation burden for traditional use registrations consumes 18-24 month timelines and six-figure analytical investments, excluding smaller regional suppliers.
- Synthetic phytochemical substitution:Fermentation-derived resveratrol and taxanes are capturing pharmaceutical contract volumes previously reserved for plant-sourced equivalents.
Strategic Opportunities
- Practitioner-directed tincture channels:Naturopathic and functional medicine clinics in Australia represent underdeveloped demand for alcohol-based extracts with dose-flexibility advantages over standardized tablets.
- EU Green Deal bioeconomy incentives:Circular processing grants for agricultural waste valorization are opening funding streams for olive leaf and grape seed extract producers in Mediterranean member states.
- Blockchain-IoT traceability convergence:Immutable chain-of-custody records from field to finished extract are creating premium pricing tiers for adulteration-sensitive botanicals like saffron and vanilla.
Industry Challenges
- Phytochemistry analytical talent scarcity:Qualified specialists capable of HPLC marker compound quantification and heavy metal screening command salary premiums that strain mid-tier laboratory operations.
- Multi-jurisdictional dossier harmonization:Divergent FDA, EMA, and TGA evidentiary requirements for botanical safety force redundant toxicology studies and delay geographic expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medicinal Plant Extracts Market |
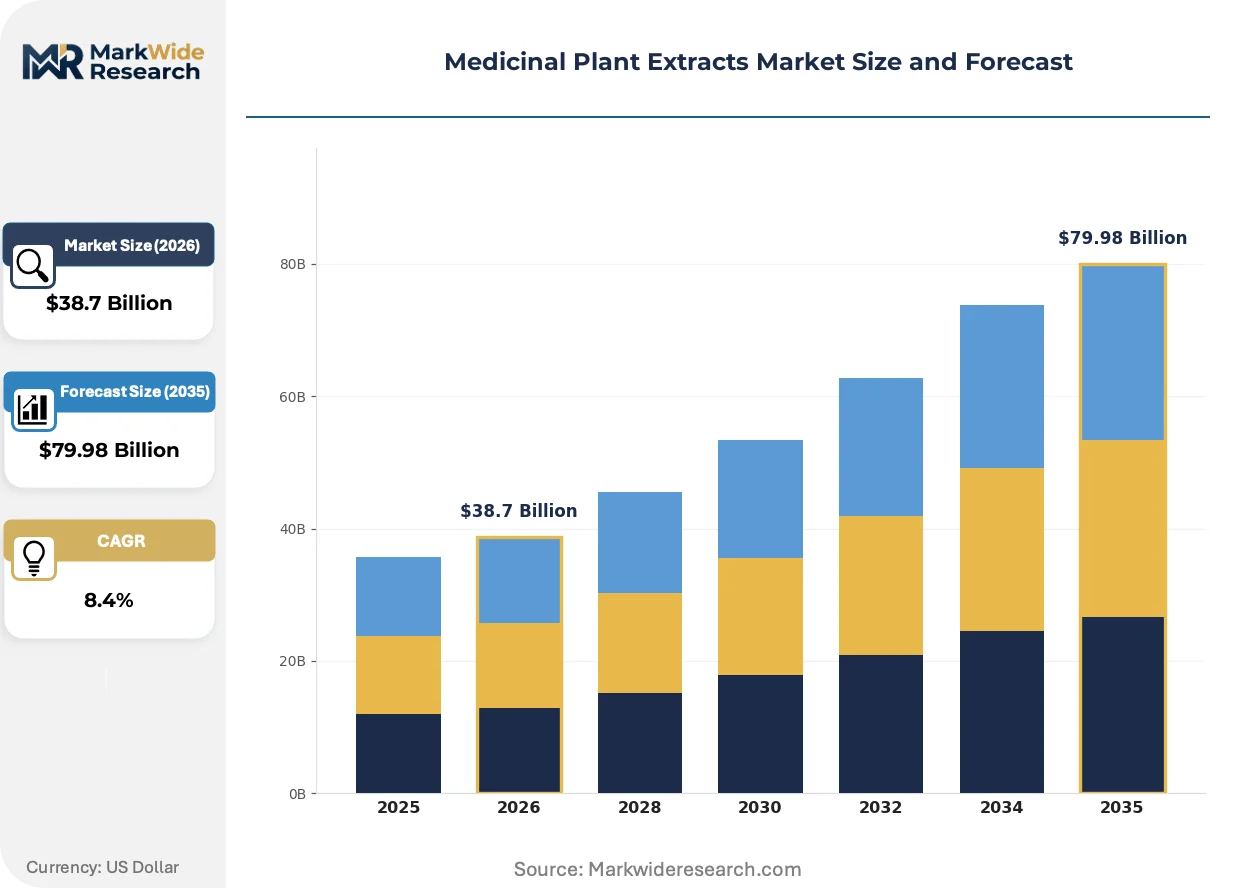
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Tinctures, Powders, Dry Extracts Application: Pharmaceuticals, Dietary Supplements, Cosmetic Products, Animal Nutrition Source: Herbs, Flowers, Roots, Barks Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | Indena S.p.A., Naturex, Sabinsa Corporation, Ginkgo BioWorks, Herbalife Nutrition Ltd., Alchem International, Kancor Ingredients Limited, Botanic Healthcare, Silverline Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medicinal Plant Extracts Market Strategic Shifts
Digital twin platforms are compressing extraction process development cycles while regulatory data integrity mandates reshape laboratory information management investments across the supplier base.
Supercritical fluid chromatography paired with AI-driven compound identification is virtualizing traditional phytochemical screening workflows. Pharmaceutical quality control departments are adopting these platforms to replace manual TLC and gravimetric methods. The technology is virtualizing months of analytical method development into days of automated spectral matching against reference libraries.
EMA's revised herbal monograph system now mandates enhanced heavy metal and pesticide residue thresholds aligned with REACH environmental standards. Extract manufacturers serving European prescription markets must retest legacy raw material inventories or source from certified organic supply chains. Dry extract processors in Germany and Switzerland are absorbing the compliance costs to maintain pharmacy distribution access.
Direct contracting between finished goods manufacturers and cultivation cooperatives is disintermediating traditional trading houses in high-value botanicals. Cosmetic and nutraceutical formulators in France and Italy now specify origin-verified supply for marketing claims. This channel restructuring concentrates procurement leverage with buyers possessing technical audit capabilities and long-term offtake commitments.
Medicinal Plant Extracts Market Segmentation
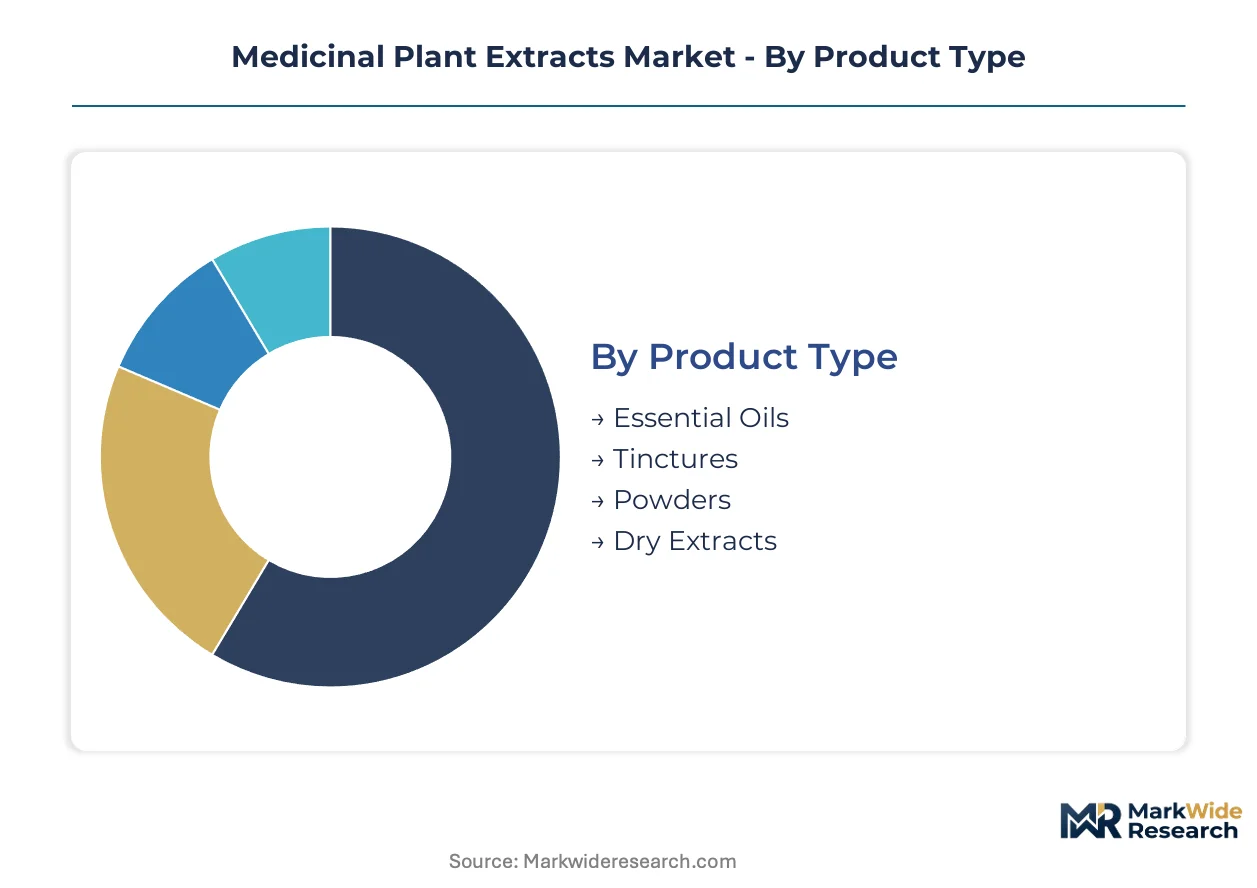
Product form dictates margin structure and regulatory pathway in medicinal plant extracts. Concentration efficiency, shelf stability, and formulation flexibility create divergent commercial profiles across segment boundaries.
Product Type:
Cost tier stratification separates premium solvent-free extracts from commodity-grade preparations. Volume concentration and processing intensity determine margin capture and customer access.
- Essential Oils:Concentrated volatile compounds obtained through steam distillation or cold pressing, standardized to specific terpenoid profiles. Pharmaceutical manufacturers in Germany and France prioritize these for parenteral and topical formulations where solvent residues trigger EMA rejection.
- Dry Extracts:Spray-dried or vacuum-concentrated preparations with defined marker compound ratios, favored in tablet and capsule production. Statutory reimbursement for phytotherapy in Germany sustains predictable prescription demand for standardized dry forms.
- Tinctures:Alcohol-based liquid extracts preserving full-spectrum phytochemical complexity. Practitioner-directed channels in Australia and North America specify these for dose-flexibility in functional medicine protocols.
- Powders:Milled raw botanical material with minimal processing, dominant in cost-sensitive dietary supplement formulations. Bulk procurement by contract manufacturers in India and China anchors volume leadership.
Dry extracts command the established base. The steepest expansion runs through essential oils.
Application:
End-use maturity varies sharply across regulatory intensity and technical specification requirements. Customer type and purchasing authority reshape competitive dynamics.
- Pharmaceuticals:GMP-certified extracts for prescription drug formulations requiring batch-level pharmacovigilance documentation. FDA New Dietary Ingredient notifications and EMA herbal monographs compress the qualified supplier base to ISO 17025-validated producers.
- Dietary Supplements:Standardized extracts for capsule, tablet, and functional food applications. US supplement manufacturers accelerate procurement of pre-validated botanicals to compress time-to-market under notification requirements.
- Cosmetic Products:Origin-verified extracts for marketing claims in French and Italian formulator channels. Direct contracting with cultivation cooperatives is disintermediating traditional trading houses.
- Animal Nutrition:Feed-grade botanical preparations for livestock gut health and growth promotion. Regulatory divergence between EU feed additive frameworks and US FDA veterinary guidelines fragments formulation standards.
Pharmaceuticals anchor revenue concentration. Dietary supplements are climbing the fastest.
Source:
Supply geography and cultivation method determine raw material security and adulteration risk. Wild-harvested versus cultivated sourcing creates divergent compliance burdens.
- Herbs:Aerial plant parts including leaves and stems, processed for polyphenol and flavonoid concentrates. Mediterranean olive leaf and green tea sourcing benefits from EU Green Deal circular processing grants.
- Roots:Underground storage organs requiring multi-year cultivation cycles. Climate-induced yield volatility in Chinese ginseng and Indian turmeric concentrates supply risk.
- Flowers:Reproductive structures harvested for volatile oil and pigment extraction. Saffron and vanilla face acute adulteration sensitivity, driving blockchain-IoT traceability investment.
- Barks:Protective outer tissues from woody perennials, typically wild-harvested. Cinchona and yohimbe sourcing faces sustainability scrutiny under CITES and national forestry regulations.
Herbs maintain volume leadership. Roots face the steepest supply constraints.
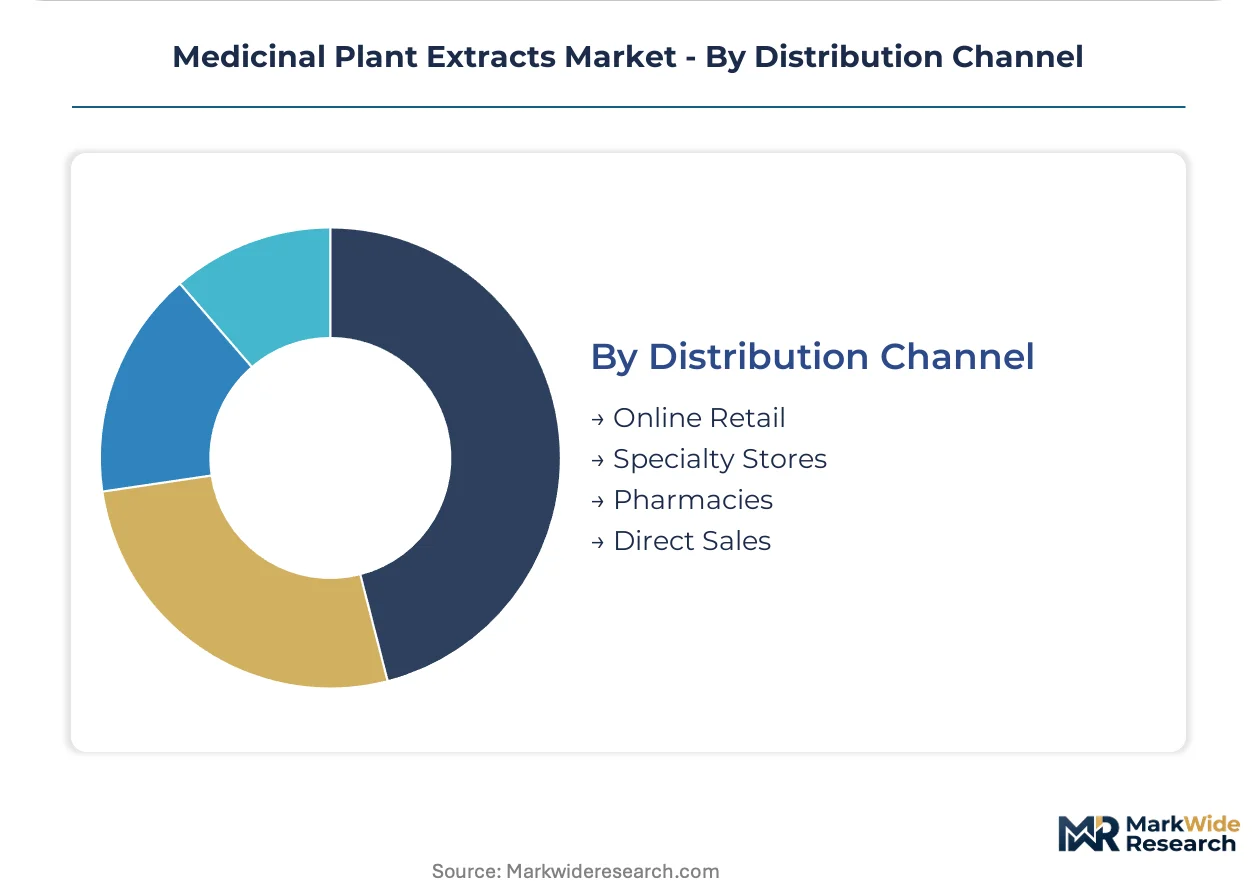
Distribution Channel:
Customer relationship depth and technical support requirements segment channel economics. Procurement leverage and specification authority vary across buyer types.
- Direct Sales:Contract manufacturing relationships between extract producers and finished goods manufacturers. Vertical integration from cultivation to purification secures supply security for high-value compounds.
- Pharmacies:Prescription and OTC distribution in German and Swiss markets with statutory phytotherapy reimbursement. EMA herbal monograph compliance is mandatory for pharmacy access.
- Specialty Stores:Health food and practitioner supply channels emphasizing organic certification and origin claims. Naturopathic clinics in Australia represent underdeveloped demand.
- Online Retail:E-commerce platforms for consumer-direct botanical supplements. Adulteration scandals have intensified third-party testing requirements and damaged trust in unverified sellers.
Direct sales capture margin concentration. Online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA's herbal monograph system anchors European regulatory leadership in medicinal plant extracts. Germany's statutory phytotherapy reimbursement creates predictable prescription demand. The FDA's New Dietary Ingredient notification pathway shapes North American market access requirements.
Germany
Statutory health insurance coverage for herbal medicines sustains pharmacy-channel demand for standardized dry extracts. EMA herbal monograph compliance is mandatory for prescription market access. Bavaria and Baden-Württemberg host concentrated extraction facility clusters serving pharmaceutical formulators.
United States
FDA New Dietary Ingredient notifications accelerate procurement of pre-validated botanicals among supplement manufacturers. ISO 17025 laboratory accreditation requirements compress the qualified supplier base. New Jersey and California anchor GMP-certified extraction capacity for pharmaceutical applications.
India
CDSCO's tightening quality benchmarks for botanical drug substances drive investment in analytical infrastructure. FSSAI regulations for nutraceutical-grade extracts reshape export compliance burdens. Gujarat and Karnataka concentrate solvent-free extraction facilities serving European and North American contract manufacturers.
China
NMPA's traditional medicine registration reforms standardize marker compound specifications for domestic and export markets. Dual carbon goals incentivize supercritical CO2 extraction adoption over solvent-based methods. Shandong and Sichuan provinces dominate cultivated raw material supply for ginseng and berberine extraction.
Australia
TGA's complementary medicine regulatory framework creates distinct pathways for listed versus registered botanical products. Practitioner-directed tincture demand concentrates in naturopathic clinic networks. Victoria and New South Wales host specialty extraction operations serving domestic and Asia-Pacific export channels.
Medicinal Plant Extracts Market Competitive Environment
Vertically integrated specialists and technology-focused ingredient platforms split the market into distinct competitive tiers. The supplier base concentrates among ISO 17025-validated producers capable of batch-level pharmacovigilance documentation. Three archetypes dominate: cultivation-to-purification integrators, patented delivery-technology developers, and botanical ingredient platform extenders. Capacity expansion in supercritical extraction infrastructure and strategic partnerships for traceability technology deployment represent the dominant competitive moves.
Within the integration-focused tier, Indena S.p.A. and Sabinsa Corporation exemplify divergent geographic anchoring strategies. Indena S.p.A. occupies a position representing European vertical control from raw material sourcing through purification. Sabinsa Corporation anchors the technology-patenting archetype with India-based material sourcing. Naturex sits within the platform-extension category, spanning multiple customer geographies through botanical ingredient breadth.
| Leading Market Players |
|---|
| Indena S.p.A. |
| Naturex |
| Sabinsa Corporation |
| Ginkgo BioWorks |
| Herbalife Nutrition Ltd. |
| Alchem International |
| Kancor Ingredients Limited |
| Botanic Healthcare |
| Silverline Chemicals |
| Others |
Value Chain & Pricing Dynamics
Shandong and Sichuan provinces concentrate cultivated ginseng and berberine extraction capacity, concentrating upstream bargaining power among processors with captive raw material supply. This geographic clustering feeds downstream pricing leverage for ISO 17025-certified producers serving pharmaceutical formulators in Germany and the United States.
Pricing Analysis
Price spreads between German pharmacy-grade dry extracts and Indian bulk powder commodities exceed threefold, reflecting EMA herbal monograph compliance costs and batch-level pharmacovigilance documentation. Pricing stratifies across premium solvent-free tiers, standard certified extracts, and economy-grade unstandardized powders. Cost compression in commodity powders intensifies as Chinese contract manufacturers expand supercritical CO2 capacity. Dietary supplement formulators exhibit acute price sensitivity, while prescription pharmaceutical channels absorb premium tiers for regulatory security.
Supply Chain Analysis
Contract manufacturing partnerships concentrate among CDSCO-validated Indian processors and NMPA-registered Chinese facilities with GMP-certified infrastructure. Raw material security draws from cultivated turmeric in Karnataka, wild-harvested ginseng in Jilin, and greenhouse saffron in Kashmir. Single-source vulnerability concentrates in climate-exposed root crops with multi-year cultivation cycles. Distribution runs through direct sales contracts between extract manufacturers and finished goods producers, displacing traditional trading house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmacovigilance documentation services and batch certification subscriptions expand faster than base extract volumes, creating recurring revenue layers for validated producers. This service-attach dynamic rewards suppliers with ISO 17025-compliant analytical infrastructure.
For Market Incumbents: Pre-empt synthetic phytochemical substitution by securing long-term offtake agreements with fermentation-derived resveratrol and taxane producers. Deepen backward integration into certified organic cultivation cooperatives in Mediterranean member states to lock EU Green Deal circular processing grants. Channel control through direct practitioner relationships in Australian naturopathic networks defends margin position against commodity traders. For New Entrants and Emerging Players: Establish a beachhead in Australian practitioner-directed tincture channels where dose-flexibility demand outpaces validated supply. Blockchain-IoT traceability technology partnerships offer a go-to-market angle for adulteration-sensitive botanicals like saffron and vanilla. Functional medicine clinics represent the most penetrable segment for alcohol-based extracts with full-spectrum phytochemical positioning. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because EMA herbal monograph compliance timelines and six-figure analytical investments exclude smaller regional suppliers. Acquisition targets should concentrate on ISO 17025-validated mid-tier laboratories with existing pharmacovigilance databases. Watch for FDA New Dietary Ingredient notification backlogs as an inflection signal for pre-validated extract demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Solvent-free extraction captures heat-sensitive alkaloid demand from EMA-regulated pharmaceutical formulators. |
| Blockchain-IoT Traceability Deployment | Immutable chain-of-custody records command premium pricing for adulteration-sensitive saffron and vanilla extracts. |
| ISO 17025 Laboratory Accreditation | Batch-level pharmacovigilance documentation qualifies suppliers for FDA New Dietary Ingredient notification pathways. |
| Direct Cultivation Cooperative Contracts | Origin-verified supply secures marketing claims for French and Italian cosmetic formulators disintermediating trading houses. |
| Pharmacovigilance Database Development | Botanical-drug interaction monitoring addresses polypharmacy risks attracting regulatory scrutiny from EMA and FDA. |
Study Parameters
A spread of perspectives from extraction facility operations managers, regulatory affairs directors at pharmaceutical formulators, procurement leads at dietary supplement manufacturers, and naturopathic clinic practitioners converged on the working assumptions. Primary interview insights combined with secondary validation from EMA herbal monograph databases, FDA New Dietary Ingredient notification filings, CDSCO botanical drug substance registrations, and FSSAI nutraceutical compliance records. Bottom-up capacity assessments across Shandong, Gujarat, and Bavaria extraction clusters triangulated against top-down demand modeling from prescription phytotherapy reimbursement data.
Demand-supply balance dynamics anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product form concentration tier, application regulatory intensity, source cultivation method, and distribution channel relationship depth. CAGRs derived from historical volume trajectories adjusted for EMA herbal monograph compliance cost absorption and supercritical CO2 technology adoption curves. Forecast inputs incorporated climate-induced yield volatility projections for Indian turmeric and Chinese ginseng root.
Sensitivities concentrate around wild-harvested raw material availability, synthetic phytochemical substitution rates, and pharmacovigilance requirement evolution. Forecasts reflect documented assumptions on regulatory timeline stability and certification cost trajectories. Quarterly review of EMA herbal monograph revision schedules, FDA notification backlog durations, and CDSCO quality benchmark enforcement intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Gelatin Hydrolysates Market
Extracts
Marigold Essential Oil Market
Extracts
Marine Algae Polysaccharides Market
Extracts
Nicotinic Acid Market
Extracts
Eucommia Extract Market
Extracts
Orange Oil Market
Extracts
Chamomile Oil Market
Extracts
Patchouli Oil Market
Extracts
Pullulan Market
Extracts
Global Rose Oils Market
Extracts
Tagetes Oil Market
Extracts
China Cedar Wood Oil Market
Extracts
White Willow Bark Extract Market
Extracts
Citronella Oil Market
Extracts
Cassia Extract Market
Extracts
Industrial Extractor Market