
 Herb and Spice Extracts Market | 2026-2036
Herb and Spice Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Herb and Spice Extracts Market Outlook
Steam-distilled essential oils is repositioning solvent-based oleoresins in mid-tier flavor applications as energy costs and carbon accounting alter production economics. Givaudan SA leverages captive botanical sourcing to secure margin stability across volatile raw material cycles. Kerry Group plc anchors its extract portfolio on clean-label credentials that resonate with North American and European food manufacturers. McCormick & Company, Inc. dominates retail-facing spice extract blends through direct retail channel control and brand recognition.
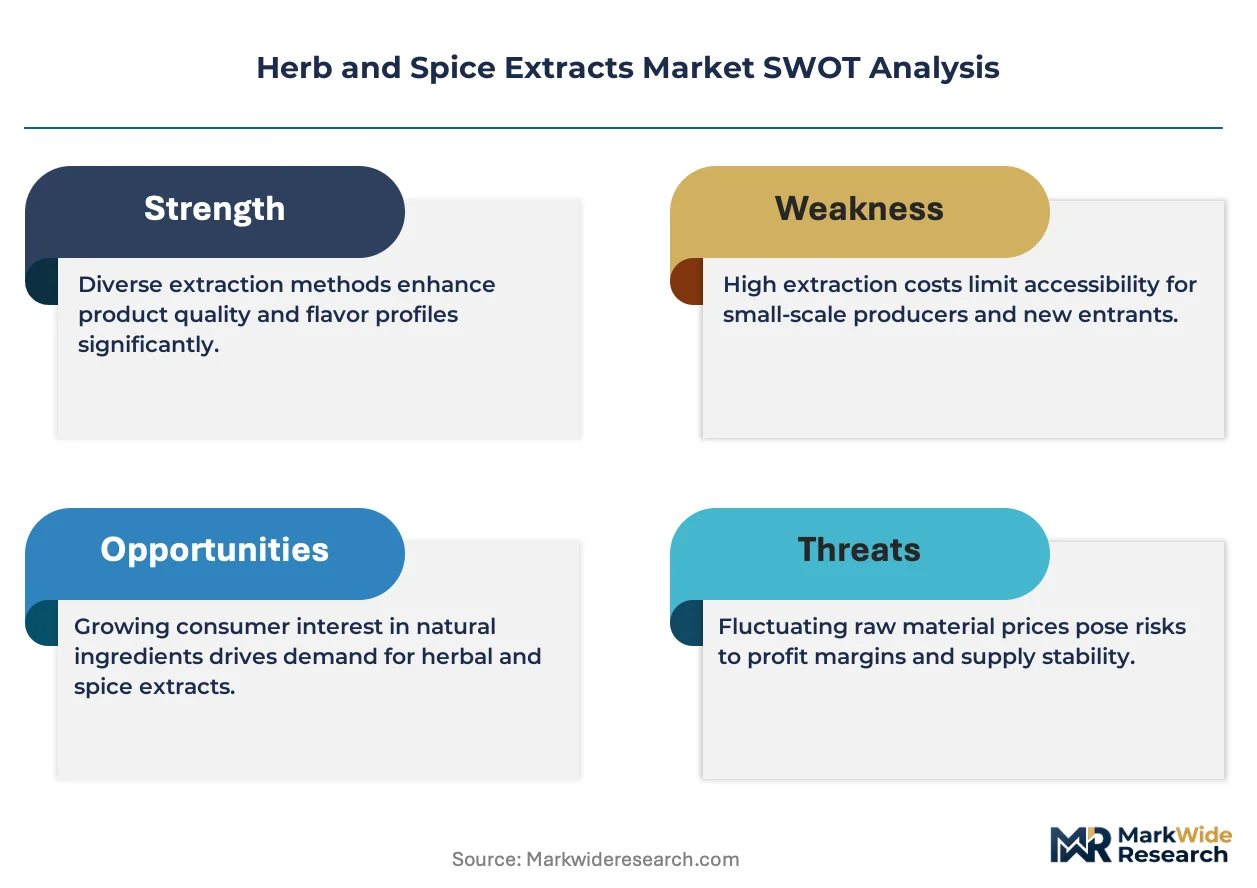
Herb and spice extracts are concentrated preparations derived from botanical raw materials through mechanical, thermal, or solvent-based processes, typically standardized for active compounds such as piperine, capsaicin, or eugenol at specified potency levels. These extracts serve primarily as flavoring agents, natural preservatives, bioactive ingredients, and colorants across formulated consumer products. Essential oils and oleoresins together occupy the dominant value share, with supercritical CO2 extraction gaining traction as a premium method that eliminates residual solvent concerns and preserves thermally labile volatiles. The food and beverages application leads volume consumption, while nutraceuticals represents the fastest-expanding margin pool as consumers prioritize functional ingredients with substantiated health claims.
The FDA governs extract safety and labeling under food additive and GRAS frameworks in the United States, while the EMA and EFSA jointly influence pharmaceutical and food-grade extract standards across Europe through monograph requirements and novel food assessments. REACH compliance constrains solvent selection and waste protocols for European extract manufacturers, redirecting capital toward greener processing infrastructure. Stakeholders must monitor evolving pharmacovigilance data on high-dose botanical extracts, as regulatory bodies on both continents tighten safety dossier requirements for novel concentrated forms.
Market Dynamics
Clean-label mandates from North American and European food manufacturers are compressing demand for solvent-heavy oleoresins while elevating steam-distilled and CO2-extracted alternatives, fundamentally reordering capital allocation across extraction infrastructure worldwide.
Growth Catalysts
- EU Green Deal solvent standards:REACH compliance deadlines are forcing European processors to retire hexane-based extraction lines ahead of schedule, creating replacement demand for supercritical CO2 systems.
- Functional beverage formulation:Sports and wellness drink manufacturers in the United States are standardizing on piperine and capsaicin extracts for bioavailability enhancement and metabolic positioning claims.
- India oleoresin cluster concentration:Kerala and Karnataka processing hubs anchored by Synthite Industries and domestic competitors supply cost-competitive black pepper and turmeric extracts to global flavor houses.
Market Restraints
- Energy cost volatility:Steam distillation and supercritical CO2 extraction are electricity-intensive; European natural gas price swings directly compress processor margins.
- Raw material geographic concentration:Madagascar vanilla, Indian cardamom, and Indonesian clove supply is concentrated in climate-vulnerable coastal regions with limited alternative sourcing.
- Thermal degradation limits:Heat-sensitive volatile compounds in basil, cilantro, and delicate herb extracts cannot survive conventional steam processes, constraining standardization options.
Strategic Opportunities
- Brazil nutraceutical underpenetration:ANVISA's evolving botanical extract registration pathway is opening previously restricted channels for standardized curcumin and gingerol supplements.
- Precision fermentation convergence:Yeast-derived terpene and phenolic compound production is intersecting with traditional extraction, enabling novel bioactive combinations.
- Direct-to-manufacturer digital channels:B2B platforms connecting Indian oleoresin processors with mid-sized North American natural product brands are compressing traditional distributor markups.
Industry Challenges
- Phytochemical analytical talent scarcity:Chromatography and mass spectrometry expertise for batch-to-batch standardization is concentrated in legacy flavor houses and contract labs.
- Novel food dossier timelines:EFSA's concentrated extract safety assessments for new delivery formats extend commercialization cycles by 18-36 months.
- Legacy ERP integration friction:Small-scale Indian and Indonesian processors struggle to connect batch traceability systems with multinational customer compliance portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herb and Spice Extracts Market |
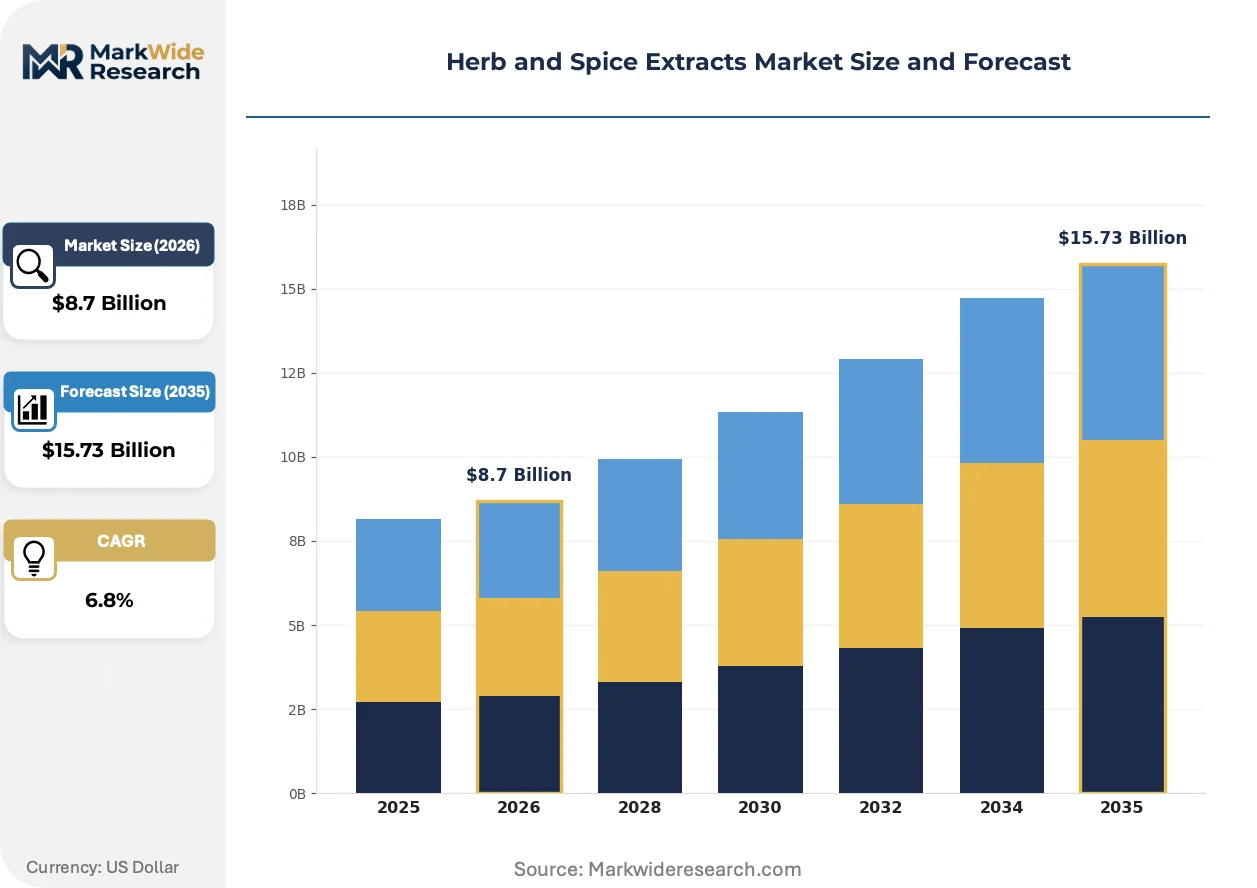
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Oleoresins, Powder Extracts, Fluid Extracts Application: Food & Beverages, Pharmaceuticals, Cosmetics, Nutraceuticals End User: Food Manufacturers, Beverage Companies, Personal Care Brands, Dietary Supplement Providers Extraction Method: Steam Distillation, Solvent Extraction, Cold Pressing, Supercritical CO2 Extraction |
| Companies Covered | Givaudan SA, Kerry Group plc, McCormick & Company, Inc., Symrise AG, International Flavors & Fragrances (IFF), Döhler GmbH, Olam International, Kalsec Inc., Synthite Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herb and Spice Extracts Market Strategic Shifts
Extraction technology evolution and regulatory chemistry requirements are simultaneously elevating process sophistication and compressing acceptable residual solvent thresholds across pharmaceutical, food, and cosmetic grade supply tiers.
Supercritical CO2 extraction is expanding into mid-volume flavor applications previously dominated by hexane oleoresins, as equipment manufacturers scale systems below 500-liter capacity thresholds. Regional sauce and seasoning compounders in Italy and Spain are piloting these units for rosemary and oregano extracts. The technology is compressing the premium-mass market gap by delivering solvent-free certifications at unit economics approaching traditional methods.
REACH Annex XVII solvent restrictions are eliminating dichloromethane and n-hexane options for European cosmetic-grade extracts by 2027, redirecting capital toward ethanol and CO2 infrastructure. German and Dutch processors face the steepest compliance cliffs given their legacy petrochemical extraction bases. Fragrance and personal care extract segments are responding fastest, with reformulation timelines already underway to secure continuity certifications.
Ingredient buyers are consolidating supplier bases around vertically integrated processors with captive botanical sourcing and in-house analytical capabilities. North American clean-label brands are reducing approved vendor lists from 15-20 to 3-5 strategic partners. This concentration is most visible in turmeric and ginger extract procurement, where traceability demands and organic certification requirements favor integrated Indian and Sri Lankan suppliers with direct farming contracts.
Herb and Spice Extracts Market Segmentation
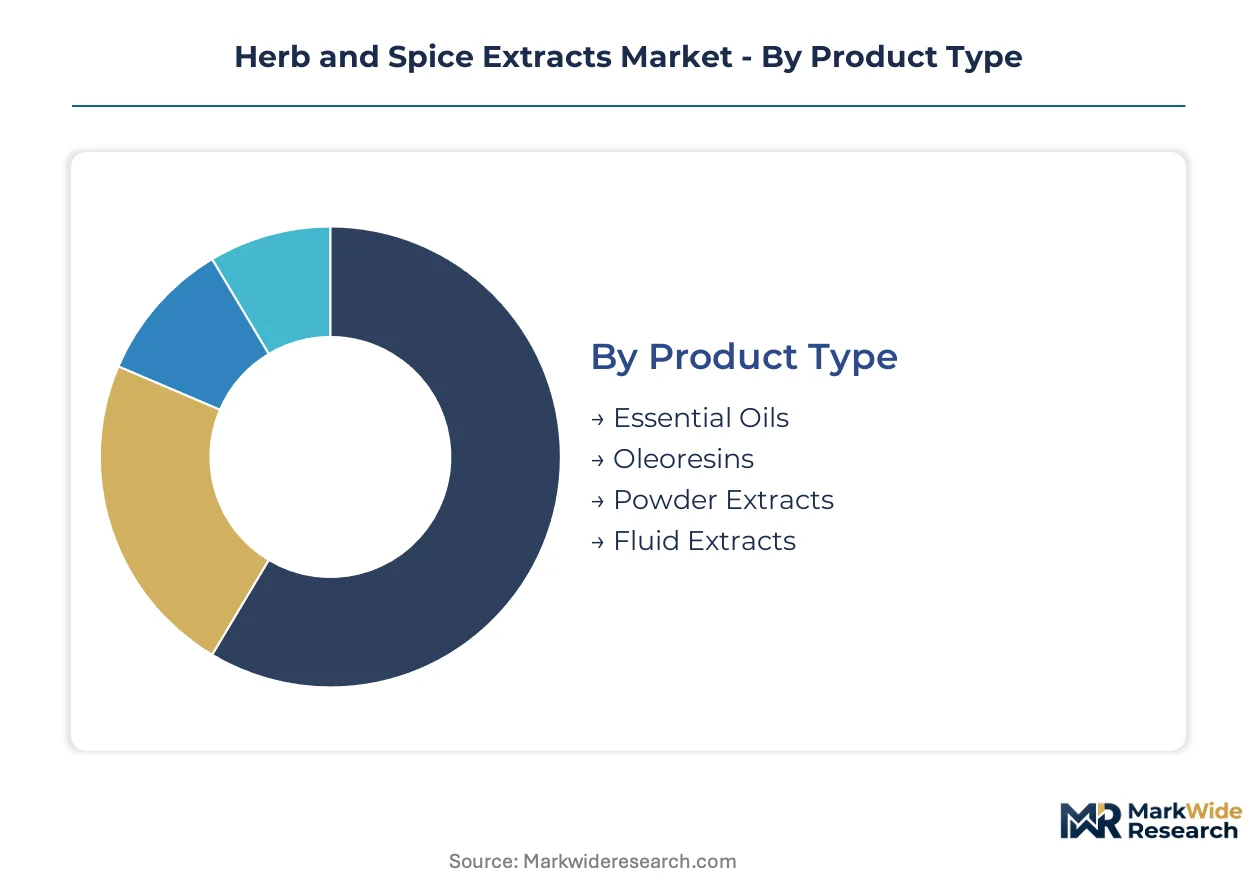
Segmentation in herb and spice extracts reveals how extraction technology and application requirements split demand across fundamentally different value chains. Product type determines margin structure, while extraction method governs capital intensity and regulatory compliance burden.
Product Type:
Standalone extracts command premium positioning in finished formulations, while embedded extract systems integrate into compound flavor bases for mid-tier applications.
- Essential Oils:Volatile aromatic concentrates standardized for specific terpene profiles, typically steam-distilled or cold-pressed. European fragrance houses and North American natural cleaning product manufacturers anchor demand for certified organic citrus and lavender oils.
- Oleoresins:Solvent-derived or CO2-extracted resinous concentrates containing both volatile and non-volatile actives. Indian processors in Kerala supply cost-competitive black pepper and turmeric oleoresins to global sauce and seasoning compounders seeking standardized heat and color metrics.
- Powder Extracts:Spray-dried or carrier-bound preparations for dry mix applications. Bakery and snack manufacturers favor these for shelf-stable incorporation into seasoning blends.
- Fluid Extracts:Hydroalcoholic or glycerin-based liquid preparations with defined soluble solids content. Beverage manufacturers and tincture producers specify these for direct dosing into liquid matrices.
Oleoresins lead volumes today; supercritical CO2-extracted variants are gaining share fastest.
Application:
Cost tier stratification separates pharmaceutical-grade extracts with full monograph compliance from food-grade alternatives with simpler specification requirements.
- Food & Beverages:Flavoring, coloring, and preservation applications across processed foods, sauces, and beverages. Clean-label mandates from US and European manufacturers are compressing demand for solvent-heavy oleoresins while elevating steam-distilled and CO2-extracted alternatives.
- Pharmaceuticals:Standardized extracts for herbal medicinal products requiring full EMA or FDA compliance dossiers. German and Swiss phytopharmaceutical specialists specify these for finished dosage forms with substantiated efficacy claims.
- Cosmetics:Fragrance and bioactive ingredients for skincare and personal care. REACH Annex XVII restrictions on residual solvents are eliminating dichloromethane and n-hexane options for European cosmetic-grade extracts by 2027.
- Nutraceuticals:Dietary supplement ingredients with standardized marker compound levels. Sports and wellness drink manufacturers in the United States are standardizing on piperine and capsaicin extracts for bioavailability enhancement and metabolic positioning claims.
Food and beverages anchors volume consumption; nutraceuticals climbs the fastest as functional ingredient premiums expand.
End User:
Customer type determines procurement sophistication, with multinational food manufacturers imposing traceability systems that smaller personal care brands cannot replicate.
- Food Manufacturers:Processed food and seasoning compounders requiring batch-to-batch consistency for reformulation stability. These buyers are consolidating supplier bases around vertically integrated processors with captive botanical sourcing and in-house analytical capabilities.
- Beverage Companies:Functional drink and flavored beverage producers seeking bioactive positioning. Sports drink specialists specify curcumin and gingerol extracts for anti-inflammatory and digestive health claims.
- Personal Care Brands:Cosmetic and fragrance houses demanding solvent-free certifications. European natural cosmetics manufacturers favor CO2-extracted botanicals for preservative-free formulation credentials.
- Dietary Supplement Providers:Capsule, tablet, and softgel manufacturers with USP or EP monograph requirements. These buyers prioritize standardized marker compounds and heavy metal testing documentation.
Food manufacturers dominate procurement volumes today; dietary supplement providers are expanding their share most steeply.
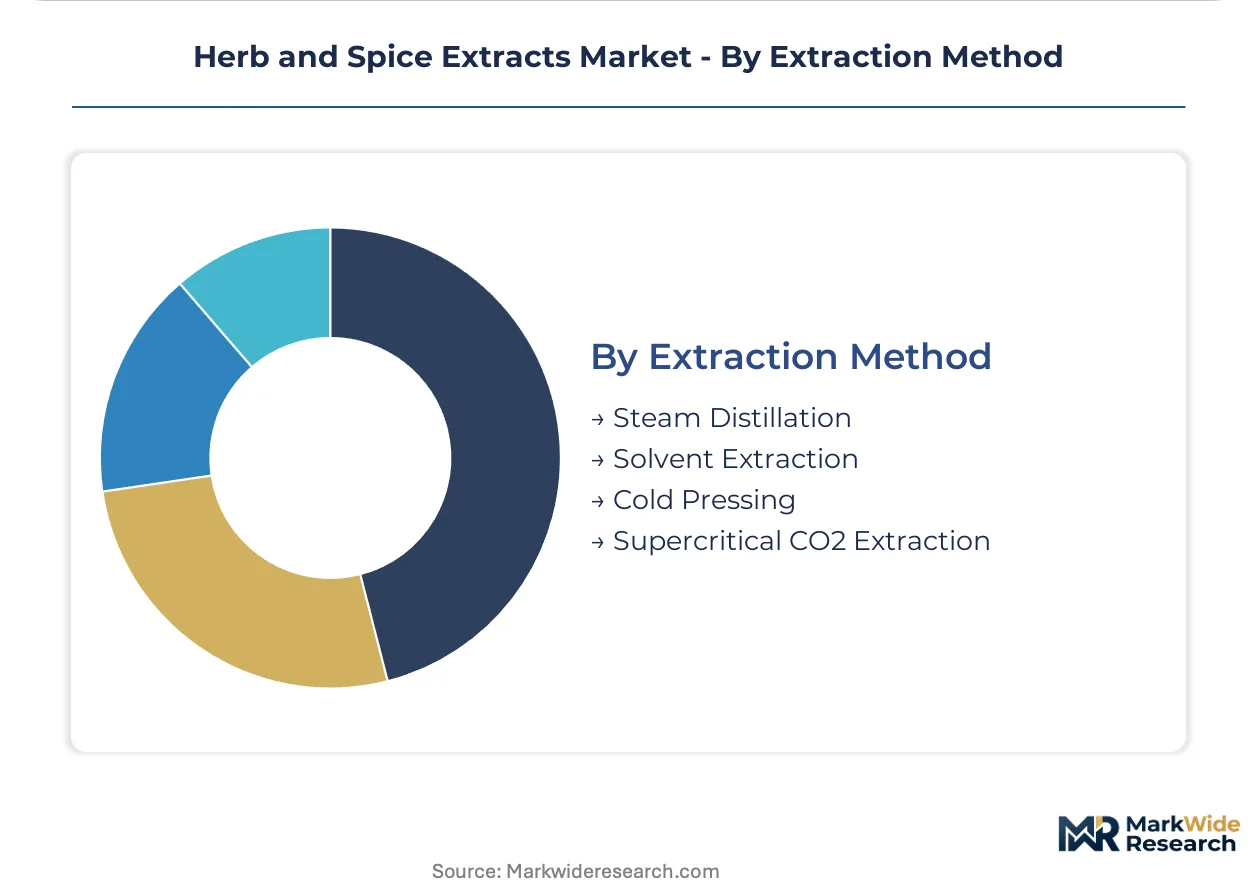
Extraction Method:
Technology maturity separates legacy solvent infrastructure from emerging green chemistry platforms with divergent capital recovery timelines.
- Steam Distillation:Thermal separation of volatile compounds using saturated steam. European natural gas price volatility directly compresses processor margins for this electricity-intensive method.
- Solvent Extraction:Hexane or ethanol-based dissolution of lipophilic actives. REACH compliance deadlines are forcing European processors to retire hexane-based extraction lines ahead of schedule.
- Cold Pressing:Mechanical expression without thermal degradation. Citrus oil producers in Italy and Spain favor this for premium terpene preservation in fragrance applications.
- Supercritical CO2 Extraction:Carbon dioxide in supercritical state for solvent-free selective extraction. Equipment manufacturers are scaling systems below 500-liter capacity thresholds for mid-volume flavor applications previously dominated by hexane oleoresins.
Solvent extraction retains the largest installed base; supercritical CO2 systems are expanding most quickly as green chemistry mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kerala's oleoresin processing corridor anchors global supply chains for black pepper and turmeric extracts, with Synthite Industries and domestic competitors feeding international flavor houses. Regional demand patterns diverge sharply between mature Western markets prioritizing clean-label certification and emerging economies expanding functional ingredient portfolios.
United States
Functional beverage manufacturers in California and Texas drive demand for piperine and capsaicin extracts targeting metabolic health positioning. FDA GRAS self-affirmation pathways accelerate novel extract commercialization compared to European dossier requirements. Chicago and New Jersey processing facilities handle bulk compounding for North American sauce and seasoning manufacturers.
Germany
REACH Annex XVII solvent restrictions are forcing processors in North Rhine-Westphalia and Bavaria to retire hexane-based extraction lines ahead of 2027 deadlines. EMA monograph requirements govern pharmaceutical-grade extract specifications for herbal medicinal products. Frankfurt and Hamburg serve as distribution hubs connecting Indian oleoresin imports to European compounders.
India
FSSAI food safety standards and DGFT export incentive schemes support Kerala and Karnataka processing clusters supplying cost-competitive turmeric and ginger extracts. The PLI scheme for food processing infrastructure is attracting capital toward CO2 extraction upgrades. Kochi and Bangalore anchor domestic R&D capabilities for standardized marker compound development.
Brazil
ANVISA's evolving botanical extract registration pathway is opening previously restricted channels for curcumin and gingerol supplements targeting sports nutrition. São Paulo and Rio de Janeiro concentrate demand from functional beverage startups seeking bioactive positioning. Domestic processors in Minas Gerais are expanding capacity to serve Latin American nutraceutical brands.
Switzerland
Swissmedic pharmaceutical standards and proximity to German flavor houses position Basel and Zurich as high-margin extract trading and quality control centers. Precision fermentation startups in the Lake Geneva region are intersecting with traditional extraction for novel terpene production. The country's private-label supplement manufacturers source premium CO2-extracted botanicals for European distribution.
Herb and Spice Extracts Market Competitive Environment
Global majors compete with regional champions across extraction technology tiers and clean-label certification capabilities. The vendor base splits between integrated flavor houses with captive botanical sourcing and specialized Indian oleoresin processors serving as supply chain flex capacity. Three archetypes dominate: vertically integrated multinationals controlling retail channels, technology-focused processors with supercritical CO2 infrastructure, and cost-driven regional suppliers anchored in Kerala and Karnataka. Competitive moves center on supplier base consolidation by North American clean-label brands and accelerated CO2 equipment deployment by European processors facing REACH compliance cliffs.
Among Swiss and Irish flavor houses, Givaudan SA and Kerry Group plc exemplify the integrated multinational archetype with direct retail channel relationships and brand recognition leverage. Synthite Industries occupies a position within the India-based oleoresin specialist tier, representing cost-competitive supply for global sauce and seasoning compounders. McCormick & Company, Inc. anchors the retail-facing blend segment through direct consumer channel control.
| Leading Market Players |
|---|
| Givaudan SA |
| Kerry Group plc |
| McCormick & Company, Inc. |
| Symrise AG |
| International Flavors & Fragrances (IFF) |
| Döhler GmbH |
| Olam International |
| Kalsec Inc. |
| Synthite Industries |
| Others |
Value Chain & Pricing Dynamics
Captive botanical sourcing in Kerala and Karnataka anchors supply positions for Indian oleoresin processors while insulating them from raw material price swings that compress margins for European competitors dependent on spot markets. This backward integration into farming contracts enables Synthite Industries and domestic rivals to offer standardized turmeric and black pepper extracts at unit economics that hexane-dependent German processors cannot match under REACH compliance deadlines.
Pricing Analysis
Input-cost pass-through from volatile European natural gas prices directly compresses margins for steam-distilled essential oil producers, while supercritical CO2 equipment depreciation creates fixed-cost pressure for mid-tier flavor compounders. Three-tier pricing structure across premium, standard, and economy levels separates solvent-free certified extracts from conventional oleoresins and commodity spice powders. Price differentiation hinges on organic certification tier and volume scale, with North American clean-label brands absorbing premium CO2-extracted positioning costs. Cost compression in standard-grade oleoresins is intensifying because REACH-mandated solvent line retirements accelerate before replacement infrastructure reaches scale. Mid-sized sauce manufacturers exhibit highest price sensitivity, while Swiss pharmaceutical compounders demonstrate lowest sensitivity due to monograph compliance requirements.
Supply Chain Analysis
Workforce availability in Kerala's processing corridor and Karnataka's R&D clusters enables Indian oleoresin specialists to maintain cost-competitive extraction operations that European rivals cannot replicate. Supply concentrates in India, Indonesia, and Madagascar, with raw material dependencies on climate-vulnerable coastal regions for vanilla, cardamom, and clove. Single-source vulnerability from Madagascar's vanilla belt creates concentration risk that multinational flavor houses mitigate through multi-year farming contracts. Distribution runs through Rotterdam and Hamburg port hubs for European compounders, while direct B2B digital channels are compressing traditional distributor markups for North American natural product brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in herb and spice extracts rests on CO2 extraction scale-down economics enabling premium-tier positioning at mid-market price points, while REACH compliance cliffs eliminate lower-cost solvent-based competition.
For Market Incumbents: Lock in captive botanical sourcing through direct farming contracts in Kerala and Karnataka before land lease costs escalate under India's PLI scheme for food processing infrastructure. Invest in sub-500-liter supercritical CO2 systems to defend against precision fermentation substitutes entering terpene production. Certification investment in EU organic and REACH Annex XVII compliance creates switching costs that anchor multinational customer relationships. For New Entrants and Emerging Players: Enter via ANVISA's evolving botanical extract registration pathway in Brazil, where sports nutrition demand for curcumin and gingerol supplements outpaces domestic processing capacity. Target mid-sized North American natural product brands through direct-to-manufacturer digital channels that bypass traditional distributor markups. Go-to-market angle: batch-traceability systems integrated with multinational customer compliance portals. For Investors and Strategic Acquirers: Roll-up economics work for Indian oleoresin specialists with in-house analytical capabilities because North American clean-label brands are consolidating approved vendor lists from 15-20 to 3-5 strategic partners. Long-term viability over the projection horizon favors processors with backward integration into farming and CO2 extraction infrastructure. Signal to watch: EFSA novel food dossier approval timelines for concentrated extract delivery formats.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | REACH Annex XVII deadlines force solvent line retirements, redirecting capital toward green extraction infrastructure. |
| Captive Botanical Sourcing | Direct farming contracts in Kerala and Karnataka secure margin stability across volatile raw material cycles. |
| Precision Fermentation Convergence | Yeast-derived terpene production intersects with traditional extraction for novel bioactive combinations. |
| Digital B2B Channel Development | Direct platforms connecting Indian processors with North American brands compress distributor markups. |
| Novel Food Dossier Investment | EFSA safety assessments for concentrated extracts extend commercialization cycles but secure premium positioning. |
Study Parameters
Bottom-up food and beverage application modeling reconciled against top-down extraction capacity tracking forms the analytical core of this study. Primary interviews with extraction plant managers, procurement leads at flavor houses, distribution channel partners, and technical R&D directors at Indian oleoresin processors combined with secondary validation from FSSAI filings, DGFT export data, ECHA REACH registrations, and SEC 10-K disclosures of listed flavor houses. Top-down triangulation against installed supercritical CO2 equipment capacity and solvent extraction line retirements cross-checks volume assumptions.
Input-output matrices map extraction method capacity by product type against end-use demand across food, pharmaceutical, cosmetic, and nutraceutical applications. Segmentation dimensions modeled include extraction technology tier, application grade, certification level, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized growth curves fitted to historical capacity additions and demand elasticity estimates. Industry-specific forecast inputs incorporate EFSA novel food approval pipeline data and ANVISA registration pathway evolution.
The model holds under stable EU Green Deal implementation timelines and continued FSSAI enforcement consistency; deviation in REACH enforcement severity or Indian agricultural input cost spikes would shift volume trajectories. Forecasts reflect documented assumptions about technology adoption curves and regulatory compliance deadlines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Floral Extract Market
Extracts
Hibiscus Flower Powder Market
Extracts
Rosa Roxburghii Powder Market
Extracts
Plum Extract Market
Extracts
Polygonum Cuspidatum Extract Market
Extracts
Irish Moss Market
Extracts
Pennyroyal Oil Market
Extracts
White Willow Bark Extract Market
Extracts
Bee Venom Extract Market
Extracts
China Cedar Wood Oil Market
Extracts
Cajeput Oil Market
Extracts
Wild Yam Powder Market
Extracts
Botanicals Market
Extracts
Citrus Powder Market
Extracts
Corn Steep Powder Market
Extracts
Sage Extract Market