
 Agmatine Market | 2026-2036
Agmatine Market Size, Share, and Industry Trends Forecast 2026-2036
Agmatine Market Outlook
Buyer concentration in sports nutrition is recalibrating as specialty e-commerce platforms and boutique fitness brands fragment what was once distributor-controlled procurement. NutraBio Labs leverages direct-to-consumer transparency to sustain premium positioning, while Jiangsu NHU Co., Ltd. anchors bulk active pharmaceutical ingredient supply through fermentation scale. NOW Foods competes across mass retail channels with broad SKU coverage, and GNC Holdings, Inc. navigates store footprint compression by extending its private-label agmatine portfolio into online subscription models.
Agmatine is a biogenic amine derived from L-arginine decarboxylation, typically supplied as agmatine sulfate with purity grades ranging from 98% to 99.5% for pharmaceutical and nutraceutical applications; it functions primarily as a neurotransmitter modulator and vasodilation agent in dietary formulations. Powder formats dominate commercial volume due to lower production costs and flexible dosing protocols, while pharmaceutical-grade capsules command concentrated margin pools where AlzChem Group AG specializes in high-purity synthesis. The sports nutrition application segment leads absolute consumption as bodybuilders and competitive athletes drive repeat purchase velocity, though nutraceuticals targeting vascular health represent the fastest-growing demand corridor.
FDA Current Good Manufacturing Practice enforcement for dietary supplements shapes quality thresholds and batch testing requirements for domestic manufacturers, while EFSA novel food assessments govern European market entry for agmatine-containing formulations. The EU Green Deal chemical sustainability frameworks are beginning to influence fermentation feedstock sourcing decisions among European producers. Stakeholders must monitor how evolving pharmacovigilance databases and adverse event reporting systems reshape consumer trust and regulatory risk profiles for agmatine products.
Market Dynamics
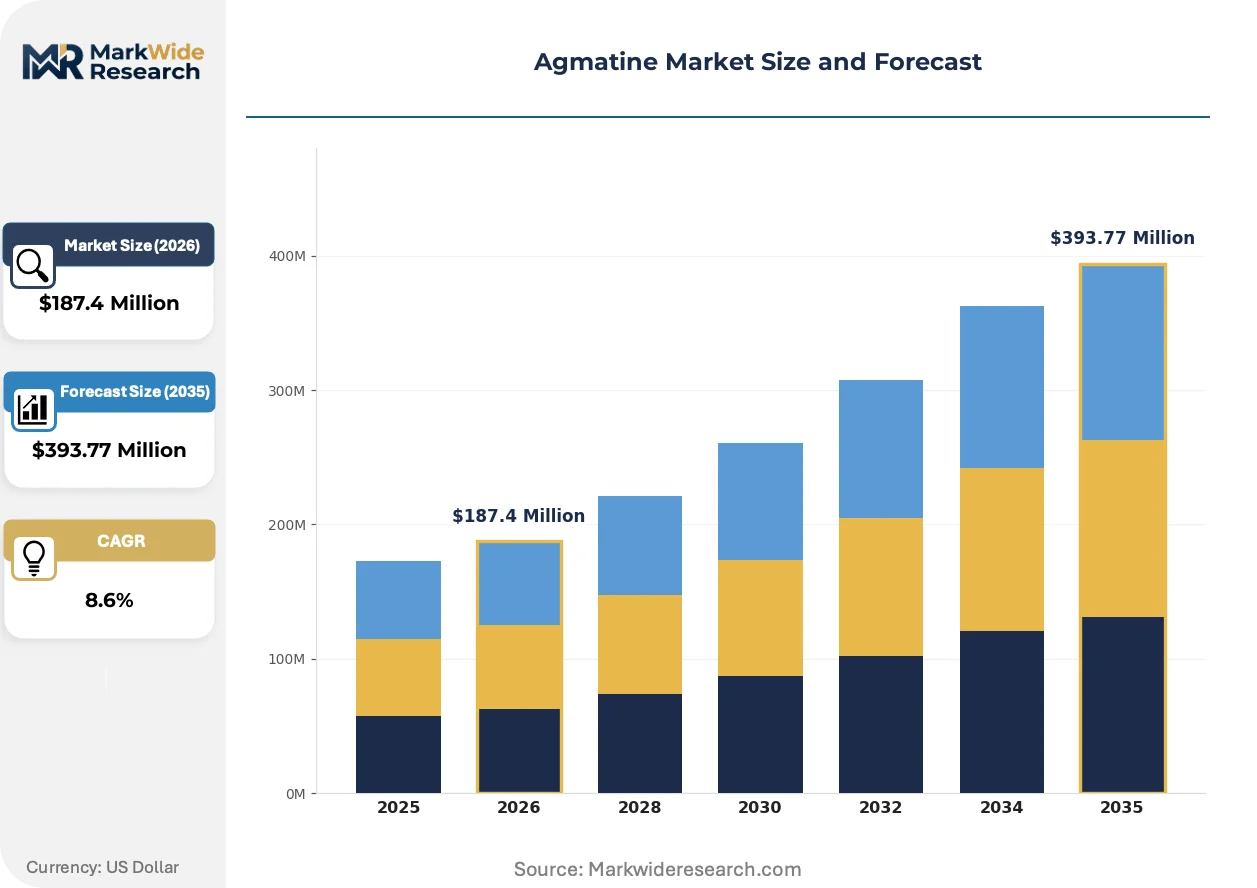
Agmatine sulfate procurement is consolidating around fermentation-derived supply chains as pharmaceutical-grade purity specifications harden under FDA Current Good Manufacturing Practice enforcement and EFSA novel food assessments.
Growth Catalysts
- Regulatory validation:EFSA health claim assessments for vascular function are creating formal pathways for agmatine-containing nutraceuticals to carry qualified health claims in European markets.
- Clinical infrastructure:United States research institutions are expanding agmatine neuroprotection trials, generating peer-reviewed data that sports nutrition brands leverage for consumer education.
- Biomanufacturing scale:Fermentation-based L-arginine decarboxylation is displacing chemical synthesis for pharmaceutical-grade material, lowering batch-to-batch impurity variance.
Market Restraints
- Input cost volatility:Corn-derived glucose feedstock prices swing with drought cycles in Iowa and Illinois, compressing fermentation margins for bulk agmatine sulfate producers.
- Regulatory friction:FDA dietary supplement enforcement actions against unapproved health claims create compliance drag for direct-to-consumer brands without in-house regulatory affairs capacity.
- Substitution threat:Citrulline malate and beetroot-derived nitrates compete for nitric oxide modulation positioning in pre-workout formulations at lower price points.
Strategic Opportunities
- Underpenetrated therapeutic vertical:Japan's PMDA pathway for neuroprotective indications remains underexploited by Western API suppliers despite aging demographics and stroke incidence.
- Channel innovation:Telehealth platforms prescribing vascular health protocols are creating direct-patient subscription channels bypassing traditional retail pharmacy distribution.
- Technology convergence:Continuous flow chemistry paired with real-time mass spectrometry is enabling pharmaceutical manufacturers to reduce solvent waste and accelerate batch release timelines.
Industry Challenges
- Specialized talent scarcity:Fermentation scale-up engineers with cGMP biologics experience command premium compensation in Boston and San Diego clusters, constraining mid-tier manufacturer expansion.
- Certification timeline compression:NSF International Certified for Sport and Informed Sport testing protocols require 12-16 week lead times that conflict with seasonal sports nutrition launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agmatine Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Liquid, Tablet Application: Dietary Supplements, Pharmaceuticals, Sports Nutrition, Nutraceuticals Distribution Channel: Online Retail, Health Stores, Pharmacies, Specialty Stores End User: Athletes, Bodybuilders, General Consumers, Health Enthusiasts |
| Companies Covered | NutraBio Labs, Jiangsu NHU Co., Ltd., NOW Foods, GNC Holdings, Inc., PrimaForce, BulkSupplements, AlzChem Group AG, MyProtein, Swanson Health Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agmatine Market Strategic Shifts
Process analytical technology and direct-to-consumer transparency platforms are compressing quality assurance cycles and fragmenting traditional distributor-controlled supply relationships.
Continuous manufacturing systems integrating in-line Raman spectroscopy are automating real-time purity verification during agmatine sulfate crystallization. Pharmaceutical API contractors in Basel and Singapore are retrofitting batch plants with these modules to reduce offline testing bottlenecks. The technology is automating release-to-stock decisions that previously required 48-72 hour laboratory holds.
EFSA novel food assessment harmonization with EU Green Deal chemical sustainability frameworks is tightening fermentation feedstock traceability requirements. European manufacturers must now document agricultural origin for corn-derived glucose through mass balance certification. German and Dutch producers are responding by securing long-term contracts with certified sustainable agriculture cooperatives.
Subscription-based replenishment models are displacing single-transaction e-commerce for repeat-purchase sports nutrition consumers. Boutique fitness brands in Texas and Florida are bundling agmatine-containing pre-workout formulations with training program memberships. This pattern concentrates most visibly in metropolitan markets where boutique gym density exceeds national averages.
Agmatine Market Segmentation
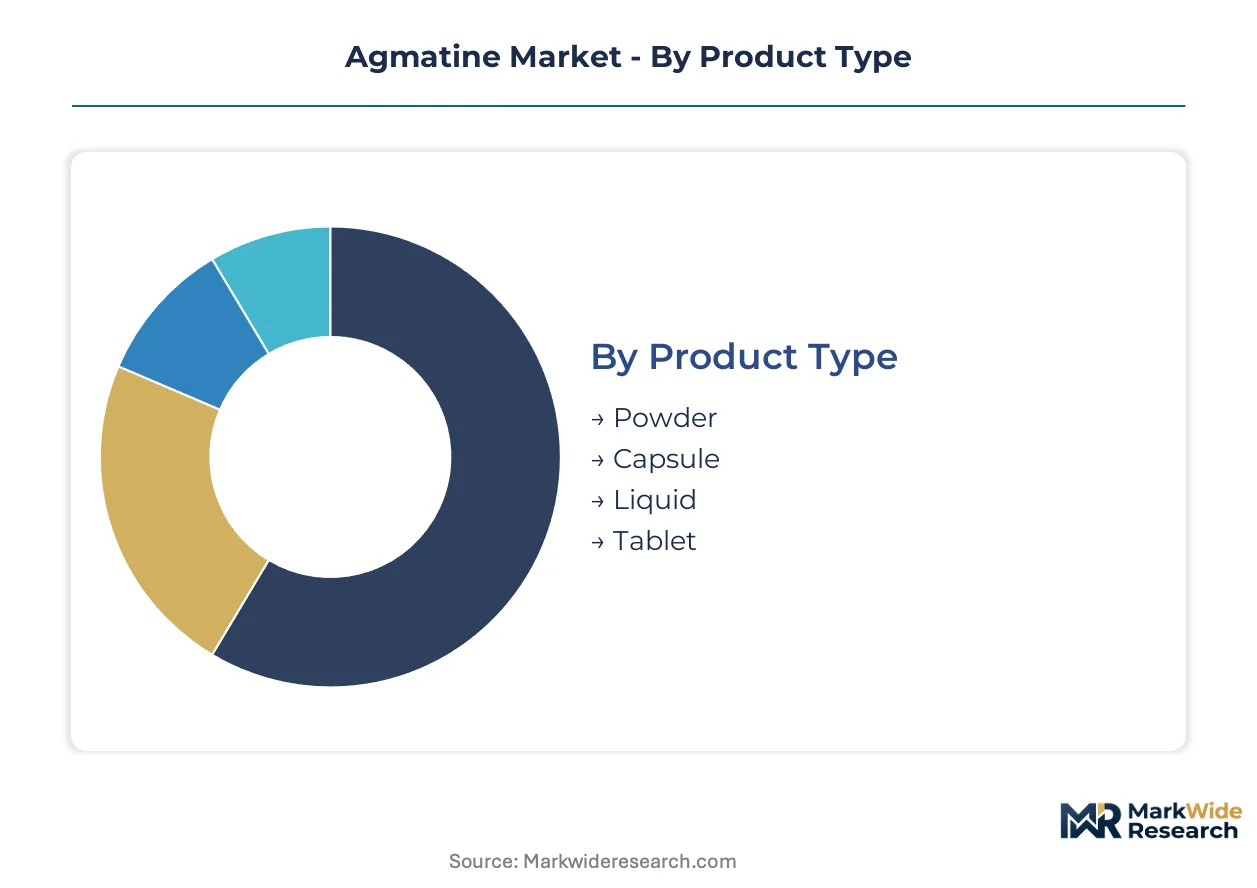
Agmatine product positioning hinges on purity grade and dosing flexibility, with pharmaceutical buyers demanding batch-certified material while sports nutrition consumers prioritize cost-per-serving economics. Segmentation strategy must align formulation format with channel economics and end-user compliance preferences.
Product Type:
Powder formats command volume leadership through lower unit economics and flexible dosing protocols, while pharmaceutical-grade capsules extract concentrated margin pools where purity documentation commands price premiums.
- Powder:Bulk agmatine sulfate in 98-99.5% purity grades dominates fermentation output, serving sports nutrition brands in Texas and Florida with scalable pre-workout formulation inputs. Cost compression from chemical synthesis displacement favors high-volume procurement contracts.
- Capsule:Pharmaceutical-grade encapsulation requires cGMP-certified facilities with batch release documentation, concentrating demand among API contractors in Basel and Singapore. AlzChem Group AG specializes in high-purity synthesis for this specification tier.
- Liquid:Ready-to-dose convenience formats target telehealth subscription channels with vascular health protocols, bypassing retail pharmacy distribution.
- Tablet:Compressed formats serve mass retail channels with standardized dosing compliance for general consumer segments.
Mature deployment sits with Powder. Newer deployment is concentrated in Capsule.
Application:
End-use differentiation tracks regulatory pathway complexity, with dietary supplements navigating FDA enforcement while pharmaceutical applications require IND-enabling toxicology packages.
- Dietary Supplements:Direct-to-consumer brands leverage peer-reviewed neuroprotection data from United States research institutions for consumer education campaigns. FDA Current Good Manufacturing Practice enforcement shapes quality thresholds and batch testing requirements.
- Sports Nutrition:Competitive athletes and bodybuilders drive repeat purchase velocity through specialty e-commerce platforms and boutique fitness brand bundling with training memberships.
- Pharmaceuticals:API supply chains for investigational neuroprotective indications require PMDA pathway navigation in Japan, where aging demographics and stroke incidence create therapeutic opportunity.
- Nutraceuticals:Vascular health positioning gains EFSA health claim assessment traction for qualified claims in European markets, representing the steepest expansion trajectory among application segments.
Volume concentration centers on Sports Nutrition. Margin expansion concentrates in Pharmaceuticals.
Distribution Channel:
Channel selection determines regulatory exposure and customer acquisition cost structure, with online platforms fragmenting traditional distributor-controlled procurement relationships.
- Online Retail:Subscription-based replenishment models displace single-transaction e-commerce for repeat-purchase consumers, concentrating in metropolitan markets with boutique gym density above national averages.
- Health Stores:NOW Foods competes across mass retail channels with broad SKU coverage and shelf presence for general consumer segments.
- Pharmacies:Clinical credibility positioning requires NSF International Certified for Sport or Informed Sport protocols with 12-16 week testing lead times.
- Specialty Stores:Boutique fitness brand partnerships in Texas and Florida bundle agmatine-containing formulations with training program memberships.
Scale economies favor Online Retail. Clinical validation concentrates in Pharmacies.
End User:
User segmentation aligns dosing sophistication with purchase frequency, with performance-oriented segments accepting powder complexity while casual users prefer convenience formats.
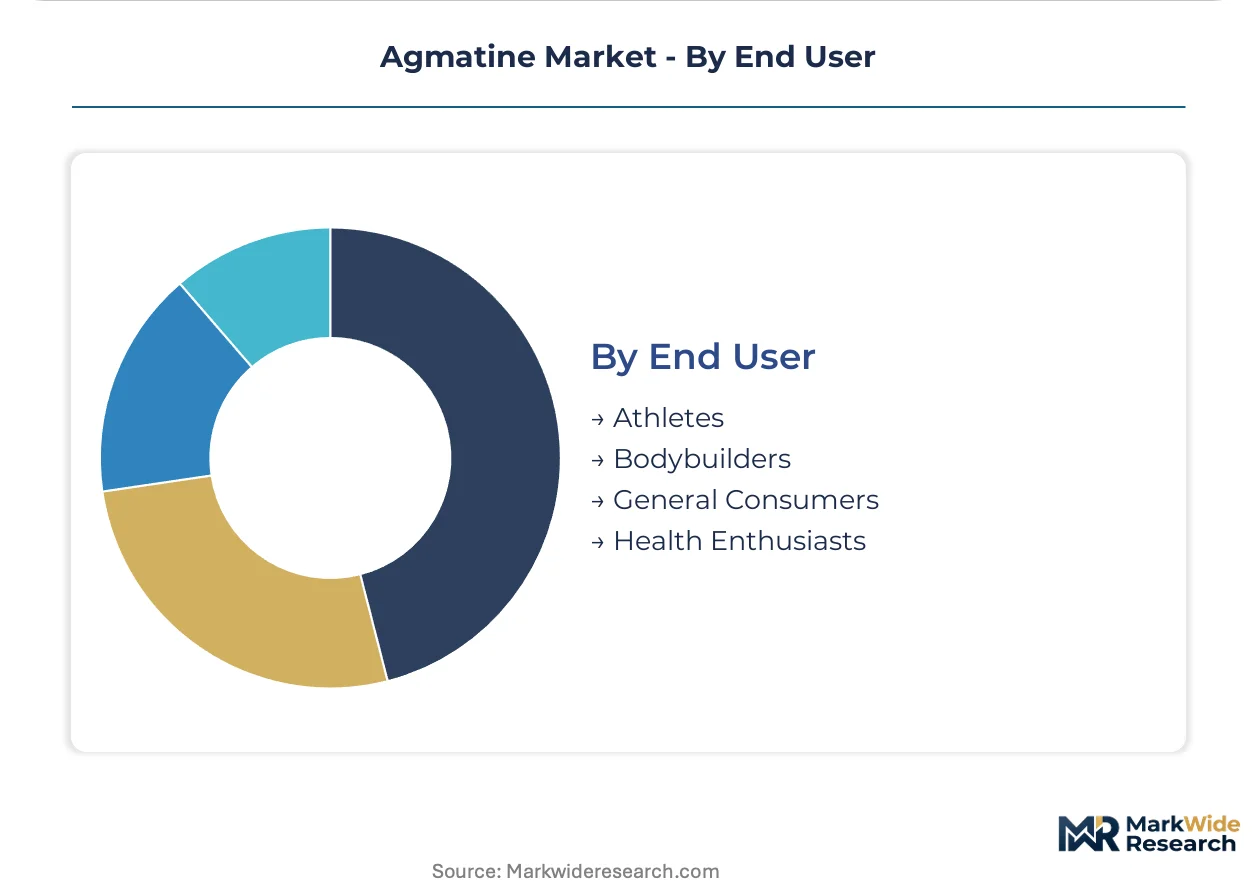
- Athletes:Competitive and recreational athletes drive pre-workout formulation demand through repeat purchase velocity and seasonal training cycle alignment.
- Bodybuilders:Nitric oxide modulation knowledge creates premium positioning tolerance for high-purity agmatine sulfate with transparent sourcing documentation.
- General Consumers:Mass market penetration depends on standardized dosing formats and retail pharmacy accessibility with lower price points.
- Health Enthusiasts:Vascular health and neuroprotection interest segments respond to peer-reviewed data and telehealth platform prescription protocols.
Purchase frequency peaks with Bodybuilders. Expansion opportunity concentrates in Health Enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn-derived glucose feedstock availability in Iowa and Illinois anchors North American fermentation capacity for agmatine sulfate production. Regional demand patterns diverge sharply between sports nutrition consumption clusters and pharmaceutical-grade API procurement centers.
United States
Direct-to-consumer supplement channels and clinical research infrastructure converge to drive procurement volume. FDA Current Good Manufacturing Practice enforcement shapes quality thresholds and batch testing requirements for domestic manufacturers. Boston and San Diego biotech clusters host fermentation scale-up engineers with cGMP biologics experience.
Germany
EFSA novel food assessments and EU Green Deal chemical sustainability frameworks tighten fermentation feedstock traceability requirements. Mass balance certification for corn-derived glucose is now mandatory for market access. AlzChem Group AG in Bavaria specializes in high-purity synthesis for pharmaceutical-grade specifications.
Japan
Aging demographics and stroke incidence create therapeutic opportunity for neuroprotective indications. PMDA pathway navigation remains underexploited by Western API suppliers despite favorable regulatory conditions. Tokyo and Osaka pharmaceutical corridors concentrate investigational drug development infrastructure.
China
Fermentation-based L-arginine decarboxylation capacity scales through Jiangsu NHU Co., Ltd. and comparable bulk active pharmaceutical ingredient suppliers. NMPA oversight of dietary supplement ingredients is tightening purity documentation requirements. Zhejiang and Jiangsu provinces dominate biomanufacturing output.
Switzerland
Pharmaceutical API contractors in Basel retrofit batch plants with continuous manufacturing systems integrating in-line Raman spectroscopy. Swissmedic regulations align with EMA standards for investigational neuroprotective applications. Geneva and Basel clusters automate release-to-stock decisions that previously required 48-72 hour laboratory holds.
Agmatine Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue telehealth subscription channels and boutique fitness brand partnerships. The vendor base spans fermentation-scale bulk suppliers, direct-to-consumer transparency platforms, and pharmaceutical-grade synthesis specialists. Three archetypes dominate: cGMP-certified API contractors, mass-retail SKU coverage operators, and premium-positioned transparency brands. Capacity expansion and backward integration into fermentation feedstock sourcing represent the dominant competitive moves.
Among North American direct-to-consumer operators, NutraBio Labs exemplifies premium-positioned transparency archetypes, while NOW Foods anchors mass-retail SKU coverage. Jiangsu NHU Co., Ltd. represents the fermentation-scale bulk supply tier from Chinese manufacturing bases. These three occupy positions across distinct pricing and certification strata without overlapping core competencies.
| Leading Market Players |
|---|
| NutraBio Labs |
| Jiangsu NHU Co., Ltd. |
| NOW Foods |
| GNC Holdings, Inc. |
| PrimaForce |
| BulkSupplements |
| AlzChem Group AG |
| MyProtein |
| Swanson Health Products |
| Others |
Value Chain & Pricing Dynamics
Captive fermentation capacity in Iowa and Illinois anchors both supply security and pricing power for North American agmatine sulfate producers. Pharmaceutical-grade batch certification from cGMP facilities commands substantial premiums over commodity powder grades, while direct-to-consumer brands absorb margin compression through subscription bundling rather than spot-market exposure.
Pricing Analysis
Warranty-backed purity documentation separates pharmaceutical-grade capsules from unbundled powder formats in commercial negotiations. Three-tier pricing structure across pharmaceutical, sports nutrition, and bulk industrial grades reflects certification intensity and batch testing overhead. Cost compression in commodity powder tiers intensifies because fermentation scale-up in China floods spot markets with 98% purity material. Sports nutrition brands exhibit highest price sensitivity, while API contractors for neuroprotective indications demonstrate inelastic demand for documented 99.5% purity grades.
Supply Chain Analysis
Single-source vulnerability sits with corn-derived glucose feedstock concentration in drought-exposed Midwestern counties. Manufacturing gravity centers on China, the United States, and Germany, with Jiangsu province hosting dominant fermentation capacity. The supply chain rests on L-arginine decarboxylation enzymes, pharmaceutical-grade solvents, and cGMP-certified encapsulation equipment. Tariff exposure on Chinese fermentation imports threatens margin structures for Western formulators lacking captive synthesis. Distribution runs through direct-to-consumer platforms, specialty fitness retail, and API contractor networks in Basel and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-based biomanufacturing is displacing legacy chemical synthesis for pharmaceutical-grade agmatine, compressing timelines for purity verification and batch release. This technology transition rewards producers with integrated process analytical technology and real-time quality systems.
For Market Incumbents: Anticipate citrulline malate and beetroot-derived nitrate substitution in pre-workout formulations by securing exclusive supply contracts with boutique fitness brands. Deepen backward integration into certified sustainable agriculture cooperatives for corn-derived glucose feedstock. Invest in continuous flow chemistry retrofitting to defend margin position against batch-plant competitors in Basel and Singapore.
For New Entrants and Emerging Players: Telehealth platforms prescribing vascular health protocols represent an underserved buyer archetype with subscription-based replenishment economics. Target Japan's PMDA neuroprotective pathway where Western API suppliers remain absent despite aging demographics. Pursue white-label manufacturing partnerships with Texas and Florida boutique fitness brands bundling training memberships with pre-workout formulations.
For Investors and Strategic Acquirers: Exit pathways concentrate in pharmaceutical-grade synthesis specialists with cGMP certification and documented PMDA navigation experience. Long-term viability over the next decade hinges on fermentation scale-up engineering talent scarcity in Boston and San Diego clusters. Monitor EFSA health claim assessment harmonization with EU Green Deal frameworks as the inflection signal for European market access premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Retrofit | Basel and Singapore API contractors automate 48-72 hour laboratory holds through in-line Raman spectroscopy integration. |
| Backward Integration into Feedstock | German and Dutch producers secure mass balance certification for corn-derived glucose under EU Green Deal traceability mandates. |
| Telehealth Channel Partnership | Direct-patient subscription models bypass retail pharmacy distribution for vascular health protocol positioning. |
| PMDA Pathway Navigation | Western API suppliers exploit underpenetrated neuroprotective indications in Tokyo and Osaka pharmaceutical corridors. |
| Certification Investment | NSF International Certified for Sport and Informed Sport protocols enable clinical credibility positioning despite 12-16 week lead times. |
Study Parameters
SEC 10-K filings, FDA warning letter databases, and EFSA novel food assessment registers formed the secondary backbone for supply chain and regulatory mapping. Primary interviews with fermentation scale-up engineers, sports nutrition brand procurement leads, pharmaceutical API contract manufacturers, and regulatory affairs specialists at cGMP facilities validated purity grade demand patterns. Bottom-up and top-down triangulation reconciled volume estimates from corn-derived glucose feedstock consumption with end-use segment consumption rates across powder, capsule, and liquid formats.
Bottom-up modeling anchored volume projections in fermentation capacity expansion announcements and cGMP certification timelines, while top-down analysis cross-checked against dietary supplement industry growth patterns. Segmentation dimensions included product type, application pathway, distribution channel, and end-user sophistication tier. CAGRs were derived from weighted average of historical fermentation output growth and projected EFSA health claim assessment adoption curves. Industry-specific inputs incorporated PMDA neuroprotection trial enrollment rates and boutique fitness brand partnership velocity in Texas and Florida metropolitan markets.
Revisions become necessary when FDA dietary supplement enforcement actions intensify, EFSA novel food assessments delay market entry, or drought cycles in Iowa and Illinois disrupt corn-derived glucose feedstock availability. Forecasts reflect assumptions about regulatory pathway harmonization and substitution threat mitigation by incumbent brands. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Myrrh Powder Market
Extracts
Peppermint Oil Market
Extracts
Rosa Roxburghii Powder Market
Extracts
Yucca Extract Material Market
Extracts
CO2 Extract Market
Extracts
Chlorophyll Extract Market
Extracts
Cochineal Extract Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
Pullulan Market
Extracts
Citronella Oil Market
Extracts
Solid Phase Extraction Market
Extracts
Cajeput Oil Market
Extracts
Industrial Extractor Market
Extracts
Peppermint Leaf Powder Market
Extracts
Natural Rosemarine Extract Market
Extracts
Irish Moss Extract Market