
 Asia-Pacific Spirulina Extract Market | 2026-2036
Asia-Pacific Spirulina Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Spirulina Extract Market Outlook
A shift from single-source to multi-source procurement is restructuring supply security across the Asia-Pacific spirulina extract landscape. E.I.D. Parry (India) Limited anchors its position through backward integration into Tamil Nadu cultivation ponds. DIC Corporation leverages Japanese process technology to sustain premium phycocyanin yields. Far East Microalgae Industries Co., Ltd. competes on Taiwanese organic certification credentials.
Spirulina extract comprises dried biomass of Arthrospira platensis and Arthrospira maxima, typically standardized to protein content exceeding 60% and phycocyanin concentrations between 5% and 25% depending on extraction method, serving primarily as a functional ingredient for protein fortification and natural colorant applications. Powder formulations dominate volume throughput due to lower processing overhead and broader formulation flexibility across food and nutraceutical applications, while liquid extracts command margin concentration in cosmetics and high-end wellness products. The nutraceutical application segment leads value generation as clinical validation of spirulina's lipid-lowering and antioxidant properties deepens practitioner recommendations.
India's FSSAI, China's SAMR, and Japan's MHLW collectively enforce escalating purity thresholds for microalgae-derived ingredients, with China's updated GB standards for edible algae imposing heavy metal limits that disqualify uncertified pond operators. India's PLI scheme for nutraceutical manufacturing is channeling investment into GMP-compliant extraction facilities. Stakeholders must monitor regulatory divergence between ASEAN harmonization efforts and national certification requirements to anticipate market access friction.
Market Dynamics
China's GB standards for edible algae and India's FSSAI nutraceutical purity mandates are compressing supplier margins while redirecting procurement toward certified pond operators with documented heavy metal compliance.
Growth Catalysts
- Phycocyanin standardization:Rising clinical validation of spirulina's lipid-lowering properties is electrifying practitioner recommendations across functional medicine clinics in Japan and South Korea.
- FSSAI PLI scheme:India's production-linked incentive program for nutraceutical manufacturing is channeling capital into GMP-compliant extraction facilities in Tamil Nadu and Telangana.
- Coastal manufacturing clusters:China's eastern seaboard dietary supplement producers are consolidating spirulina powder procurement to secure volume discounts and batch consistency.
Market Restraints
- Arthrospira biomass input volatility:Seasonal temperature fluctuations in open pond cultivation create yield unpredictability that propagates through contract pricing.
- Heavy metal compliance costs:China's updated GB standards impose testing burdens that disqualify small-scale Tamil Nadu pond operators from export eligibility.
- Plant protein substitution:Pea and rice protein isolates compete for formulation slots in mass-market protein fortification applications.
Strategic Opportunities
- Vietnamese pond development:Underpenetrated Mekong Delta cultivation zones offer land and labor cost advantages for organic-certified biomass production.
- Cosmetics-grade phycocyanin:Premium natural colorant demand from K-beauty formulators creates margin concentration in liquid extract formats.
- ASEAN harmonization:Pending regional regulatory alignment could streamline cross-border ingredient certification for Malaysian and Indonesian processors.
Industry Challenges
- Phycocyanin extraction technician scarcity:Specialized downstream processing expertise concentrates in Japanese and Taiwanese facilities, constraining capacity expansion elsewhere.
- Dual certification timelines:Simultaneous organic and GMP compliance documentation extends facility commissioning by 14-18 months in Indian greenfield projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Spirulina Extract Market |
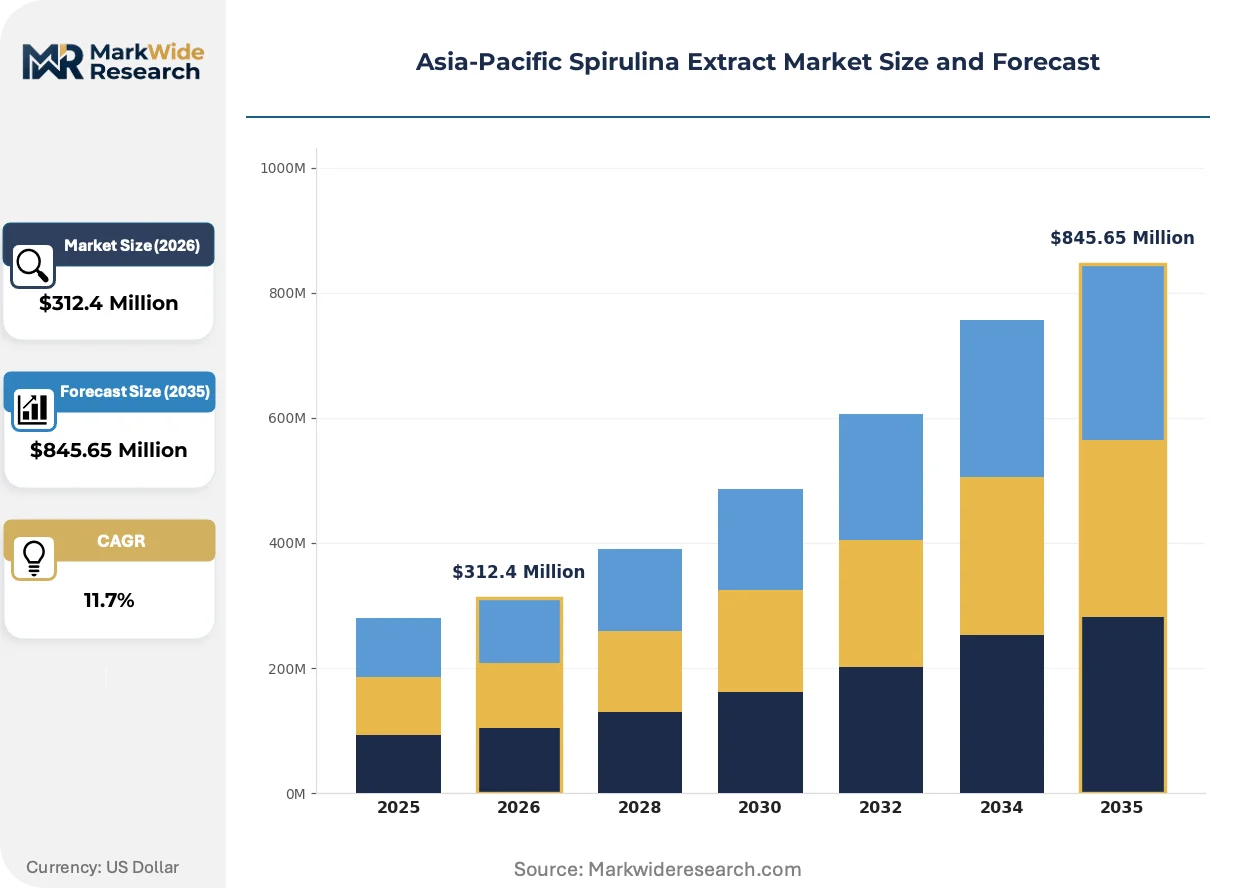
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Tablet, Capsule, Liquid Application: Food Supplement, Nutraceutical, Cosmetics, Animal Feed End User: Healthcare Providers, Retail Consumers, Food Manufacturers, Fitness Industry Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | E.I.D. Parry (India) Limited, Far East Microalgae Industries Co., Ltd., Fuqing King Dnarmsa Spirulina Co., Ltd., Taiwan Chlorella Manufacturing Company, Bluetec Naturals Co., Ltd., DIC Corporation, Aurospirul, Vedan Biotechnology Corporation, Zhejiang Binmei Biotechnology Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Spirulina Extract Market Strategic Shifts
Process intensification and regulatory technology adoption are compressing extraction yields while traceability systems reshape procurement qualification protocols across the Asia-Pacific spirulina value chain.
Closed photobioreactor systems with automated pH and dissolved oxygen monitoring are electrifying biomass productivity per square meter. Japanese nutraceutical contract manufacturers are adopting these systems fastest, with three facilities retrofitting open ponds annually. The technology is electrifying premium phycocyanin supply security by decoupling yields from monsoon seasonality.
China's SAMR implementation of blockchain-enabled ingredient traceability mandates is forcing upstream documentation investments. Pond operators must now attach geolocation and heavy metal test data to every biomass lot. Small-scale Tamil Nadu suppliers without digital infrastructure face exclusion from export channels to Chinese formulators.
Direct contracting between spirulina cultivators and finished goods brands is displacing multi-layer distributor networks. Australian and New Zealand wellness brands now source biomass through verified supplier portals rather than regional trading houses. This pattern concentrates most visibly in phycocyanin orders for sports nutrition applications.
Asia-Pacific Spirulina Extract Market Segmentation
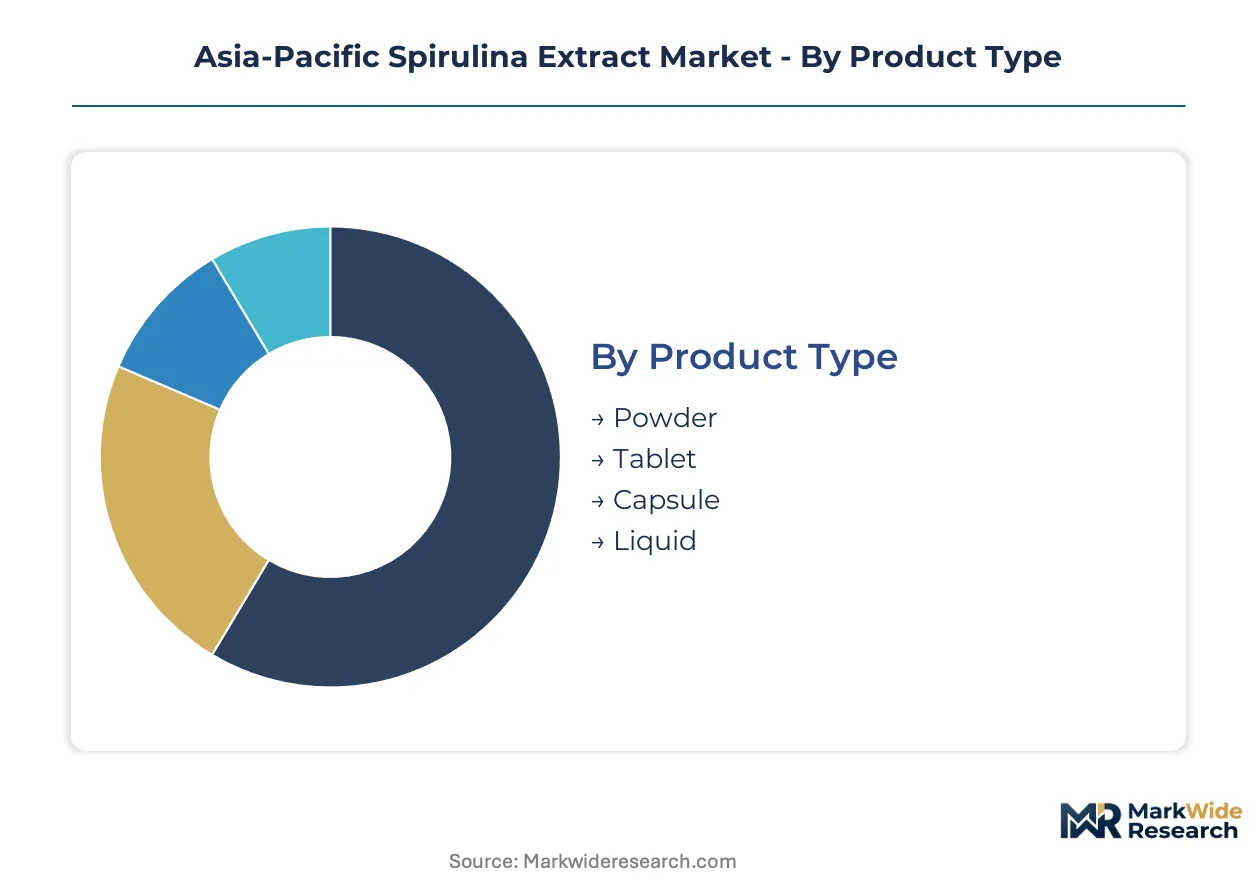
Segmentation in the Asia-Pacific spirulina extract market reveals how procurement patterns diverge across formulation formats and end-use requirements. Powder and liquid extracts serve fundamentally different supply chains, while nutraceutical and cosmetic applications impose distinct purity and documentation standards on cultivators.
Product Type:
Supply concentration varies sharply across extraction formats, with powder dominating biomass throughput and liquid commanding specialized processing infrastructure.
- Powder:Dried biomass standardized to protein content exceeding 60% and phycocyanin concentrations between 5% and 25%, processed through spray-drying or freeze-drying methods. China's eastern coastal manufacturing clusters absorb the majority of volume for dietary supplement formulations, driven by lower processing overhead and broader formulation flexibility across nutraceutical applications.
- Liquid:Aqueous extracts retaining higher phycocyanin bioavailability, typically sold as concentrates for cosmetics and wellness beverages. K-beauty formulators in South Korea are consolidating procurement of liquid formats for premium natural colorant applications, where margin concentration offsets higher cold-chain logistics costs.
- Tablet:Compressed powder formulations with binding agents for direct-to-consumer nutraceutical retail. India's FSSAI-compliant manufacturers in Tamil Nadu process tablets for domestic pharmacy distribution.
- Capsule:Gelatin or vegetable-based encapsulation targeting practitioner-recommended supplement protocols. Japanese functional medicine clinics prefer capsules for standardized dosing regimens.
Powder absorbs the bulk of installed capacity; liquid is expanding most quickly.
Application:
Cost tier differentiation separates mass-market fortification from premium therapeutic positioning across end-use segments.
- Nutraceutical:Clinical-grade extracts validated for lipid-lowering and antioxidant properties, distributed through practitioner channels and pharmacy retail. Japan's functional medicine clinics and South Korean wellness centers are deepening recommendations as human trial data accumulates, concentrating demand in premium phycocyanin-standardized products.
- Cosmetics:Phycocyanin-rich extracts serving as natural colorants and antioxidant actives in skincare formulations. K-beauty brands are contracting directly with Taiwanese organic-certified cultivators for traceable biomass meeting clean beauty standards.
- Food Supplement:Protein fortification ingredients for sports nutrition and meal replacement products. Australian and New Zealand wellness brands source through verified supplier portals rather than regional trading houses.
- Animal Feed:Lower-grade biomass for aquaculture and poultry pigmentation. Vietnamese Mekong Delta pond operators target this segment for volume offtake with reduced purity requirements.
Nutraceutical commands the steepest expansion trajectory; food supplement anchors baseline volume.
End User:
Customer type determines documentation burden and contract structure, from institutional procurement to fragmented retail demand.
- Healthcare Providers:Clinics and hospitals prescribing spirulina for metabolic management. Japan's functional medicine networks require batch-specific heavy metal certificates and phycocyanin assay reports.
- Retail Consumers:Direct purchasers through e-commerce and pharmacy channels. China's SAMR blockchain traceability mandates are reshaping how brands communicate cultivation origin to this segment.
- Food Manufacturers:Industrial buyers incorporating spirulina into packaged foods and beverages. India's PLI scheme beneficiaries in Telangana are securing long-term supply contracts with GMP-compliant extractors.
- Fitness Industry:Sports nutrition brands and gym-affiliated supplement retailers. Australian direct-to-consumer wellness brands dominate procurement for this channel.
Food manufacturers absorb the bulk of installed capacity; healthcare providers are expanding most quickly.
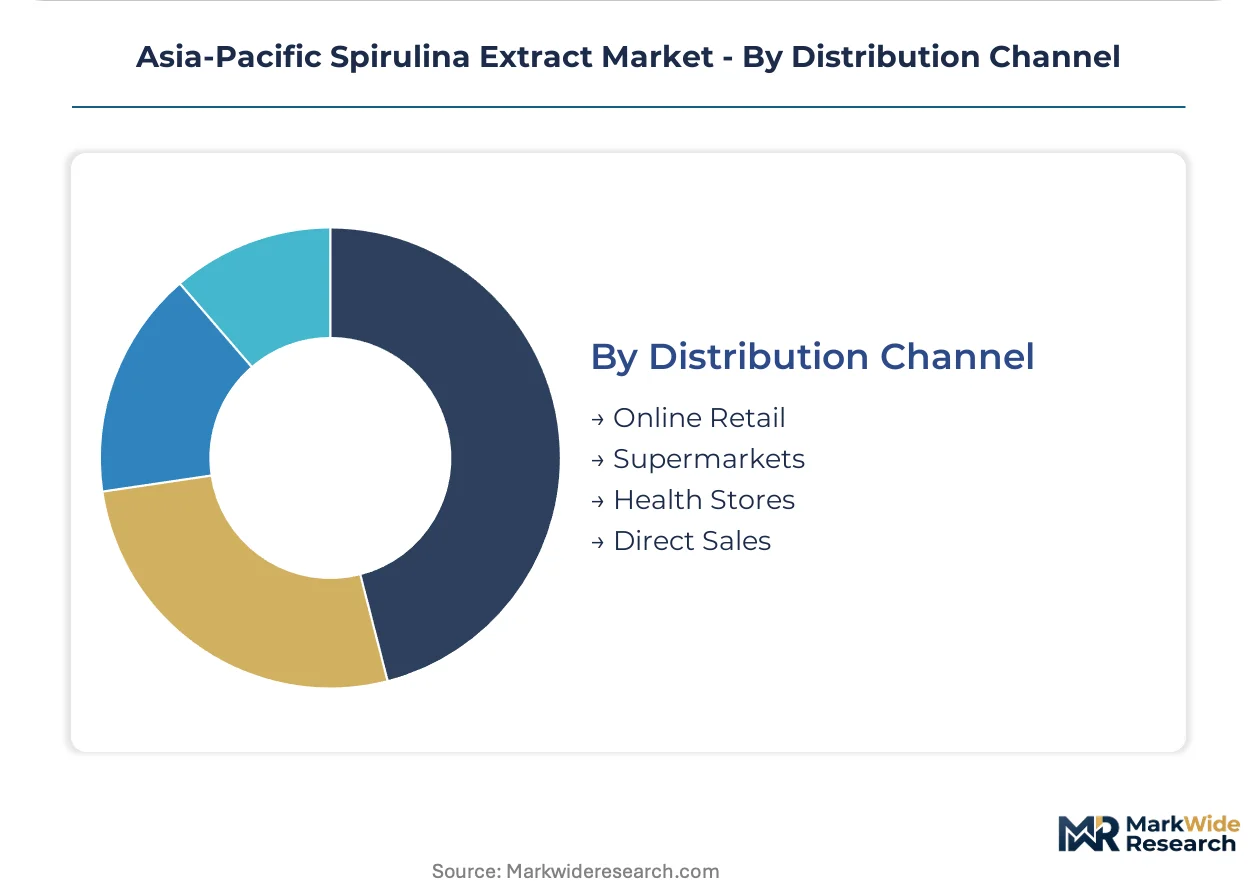
Distribution Channel:
Margin structure and geographic reach diverge across channel types, with digital platforms eroding traditional wholesale networks.
- Online Retail:E-commerce platforms and brand-direct portals with traceability documentation. Australian and New Zealand wellness brands have shifted biomass procurement to verified supplier portals, displacing multi-layer distributor networks.
- Supermarkets:Mass-market retail requiring volume consistency and shelf-stable packaging. China's eastern seaboard dietary supplement producers consolidate procurement to secure batch consistency for this channel.
- Health Stores:Specialty retailers emphasizing organic certification and practitioner endorsement. India's Tamil Nadu processing hubs supply this channel with FSSAI-compliant packaged goods.
- Direct Sales:Network marketing and practitioner-to-patient distribution. Japanese nutraceutical contract manufacturers maintain dedicated salesforces for this segment.
Supermarkets absorb the bulk of installed capacity; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern coastal manufacturing clusters absorb the majority of spirulina powder volume for dietary supplement formulations, while India's Tamil Nadu processing hubs anchor South Asian supply chains for FSSAI-compliant nutraceutical distribution.
China
Dietary supplement manufacturers in Shanghai and Zhejiang provinces are consolidating spirulina procurement to secure volume discounts and batch consistency for domestic retail channels. SAMR's blockchain-enabled ingredient traceability mandates now require geolocation and heavy metal test data attachment to every biomass lot. Small-scale pond operators without digital infrastructure face exclusion from export channels to Chinese formulators.
India
Nutraceutical manufacturers across Tamil Nadu and Telangana are expanding GMP-compliant extraction facilities under the FSSAI production-linked incentive scheme. India's tightening nutraceutical purity benchmarks redirect sourcing toward certified producers with documented heavy metal compliance. Tamil Nadu processing hubs supply FSSAI-compliant packaged goods to domestic pharmacy distribution and health store channels.
Japan
Functional medicine clinics in Tokyo and Osaka are deepening practitioner recommendations as human trial data on spirulina's lipid-lowering properties accumulates. MHLW enforces escalating purity thresholds for microalgae-derived ingredients through pharmaceutical-grade documentation requirements. Japanese nutraceutical contract manufacturers are retrofitting open ponds with closed photobioreactor systems fastest, with three facilities converting annually.
South Korea
K-beauty formulators in Seoul are consolidating procurement of liquid spirulina extracts for premium natural colorant applications in skincare formulations. MFDS cosmetic ingredient regulations impose distinct purity and documentation standards on cultivators supplying this channel. Premium phycocyanin demand from South Korean wellness centers concentrates margin in liquid extract formats with higher cold-chain logistics tolerance.
Vietnam
Mekong Delta pond operators are targeting animal feed segment volume offtake with reduced purity requirements, leveraging land and labor cost advantages for organic-certified biomass production. The country's national food safety regulator is developing frameworks for microalgae cultivation licensing. Underpenetrated cultivation zones offer expansion opportunities for biomass producers seeking alternatives to Tamil Nadu and Chinese sourcing.
Asia-Pacific Spirulina Extract Market Competitive Environment
Backward integration dominates the current landscape as cultivators secure pond-to-extraction control. The vendor base spans vertically integrated biomass producers, Japanese process technology specialists, and Taiwanese organic certification holders. Three strategic archetypes define positioning: pond-owning extractors with captive supply, technology licensors with premium phycocyanin yields, and certification-focused specialists serving clean beauty channels. Capacity expansion and direct contracting with finished goods brands represent the dominant competitive moves displacing multi-layer distributor networks.
Among India-based cultivators, E.I.D. Parry (India) Limited exemplifies the backward-integrated archetype through Tamil Nadu pond ownership. Japanese specialists DIC Corporation occupy positions sustained by process technology advantages in premium phycocyanin recovery. Taiwanese organic certification holders Far East Microalgae Industries Co., Ltd. represent the clean beauty supply tier serving K-beauty direct contracting requirements.
| Leading Market Players |
|---|
| E.I.D. Parry (India) Limited |
| Far East Microalgae Industries Co., Ltd. |
| Fuqing King Dnarmsa Spirulina Co., Ltd. |
| Taiwan Chlorella Manufacturing Company |
| Bluetec Naturals Co., Ltd. |
| DIC Corporation |
| Aurospirul |
| Vedan Biotechnology Corporation |
| Zhejiang Binmei Biotechnology Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
China's GB standards for edible algae and India's FSSAI nutraceutical purity mandates are gating both qualified supply and premium-tier pricing access, compressing margins for uncertified pond operators while rewarding documented heavy metal compliance with pricing power in practitioner-recommended channels.
Pricing Analysis
The volume-versus-margin split separates powder formulations absorbing bulk procurement from liquid extracts commanding premium positioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by phycocyanin concentration and organic certification status. Price differentiation hinges on GB/FSSAI compliance documentation and volume scale in coastal manufacturing clusters. Cost compression in economy-tier animal feed biomass is intensifying because Vietnamese Mekong Delta entrants are undercutting Tamil Nadu pond operators. Food manufacturers exhibit highest price sensitivity; K-beauty formulators show least.
Supply Chain Analysis
Workforce availability for specialized phycocyanin extraction technicians concentrates in Japanese and Taiwanese facilities, constraining capacity expansion in Tamil Nadu and Telangana greenfield projects. Geographic supply concentration centers on China, India, and Vietnam for biomass cultivation, with Japan and Taiwan anchoring downstream processing. Raw material dependencies draw from Arthrospira platensis and Arthrospira maxima strains, phosphate nutrients, and pond infrastructure. Single-source vulnerability runs through Japanese photobioreactor technology licensors. Distribution runs through direct contracting portals displacing multi-layer distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as regulatory compliance costs force sub-scale pond operators toward exit or acquisition by certified competitors.
For Market Incumbents: Anticipate margin compression from Vietnamese organic-certified entrants by securing backward integration into Tamil Nadu cultivation ponds and investing in SAMR-compliant blockchain traceability infrastructure. Prioritize phycocyanin standardization R&D to defend practitioner channel positioning against pea and rice protein substitutes. For New Entrants and Emerging Players: The price-point gap between premium liquid phycocyanin and economy-grade animal feed biomass offers white-space entry. Target Vietnamese Mekong Delta organic certification for K-beauty direct contracting. Pursue GMP-compliant extraction facility partnerships in Telangana to bypass 14-18 month dual certification timelines. For Investors and Strategic Acquirers: FSSAI PLI scheme disbursement acceleration is the leading indicator that Indian nutraceutical manufacturing capacity will consolidate around GMP-compliant processors. Frame five-to-ten year viability around certified pond-to-extraction control. Target acquisition archetype: Tamil Nadu operators with documented heavy metal compliance and existing FSSAI relationships. Watch Japanese photobioreactor retrofit rates as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | E.I.D. Parry's Tamil Nadu pond ownership secures captive biomass supply against input volatility. |
| Photobioreactor Technology Licensing | DIC Corporation's Japanese process expertise sustains premium phycocyanin yield advantages. |
| Organic Certification Investment | Far East Microalgae Industries' Taiwanese credentials unlock K-beauty direct contracting channels. |
| Blockchain Traceability Implementation | SAMR mandates force geolocation and heavy metal data attachment for Chinese market access. |
| Direct-to-Brand Supplier Portals | Australian wellness brands now bypass trading houses for verified biomass procurement. |
Study Parameters
Document review covered FSSAI regulatory filings, SAMR GB standard updates, and MHLW pharmaceutical-grade documentation, complemented by interviews with pond operators, extraction facility managers, nutraceutical procurement leads, and K-beauty formulators. Secondary validation drew from customs trade data, SEC 10-K disclosures of listed microalgae processors, and ASEAN harmonization framework drafts. Bottom-up biomass volume estimates triangulated against top-down nutraceutical ingredient demand projections.
Output modeling generated volume and value trajectories across the analysis window by segmenting powder, liquid, tablet, and capsule formats; nutraceutical, cosmetic, food supplement, and animal feed applications; and healthcare provider, retail consumer, food manufacturer, and fitness industry end users. CAGRs were derived from regression against phycocyanin clinical trial publication rates and PLI scheme capital deployment tracking.
Inputs from FSSAI and SAMR regulatory databases were available through the study window; gaps in real-time Vietnamese cultivation licensing data introduce uncertainty bands around Mekong Delta expansion assumptions. Forecasts reflect biomass yield assumptions tied to monsoon seasonality patterns and photobioreactor adoption curves. Material deviation in GB heavy metal limit enforcement or PLI scheme disbursement velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Herba Houttuyniae Extract Market
Extracts
Pullulan Market
Extracts
Jalapeno Extract Market
Extracts
Glycerol Extracts Market
Extracts
Hydroglycolic Extracts Market
Extracts
Valerian Root Powder Market
Extracts
Global Herbal Extract Market
Extracts
Aloe Vera Derivatives Market
Extracts
Irish Moss Extract Market
Extracts
Kelp Extracts Market
Extracts
Pearl Extract Market
Extracts
Cassia Extract Market
Extracts
Sandalwood Oil Market
Extracts
Labdanum Market
Extracts
Pectin Powder Market
Extracts
Global Azadirachtin Market