
 Flower Extract Market | 2026-2036
Flower Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Flower Extract Market Analysis
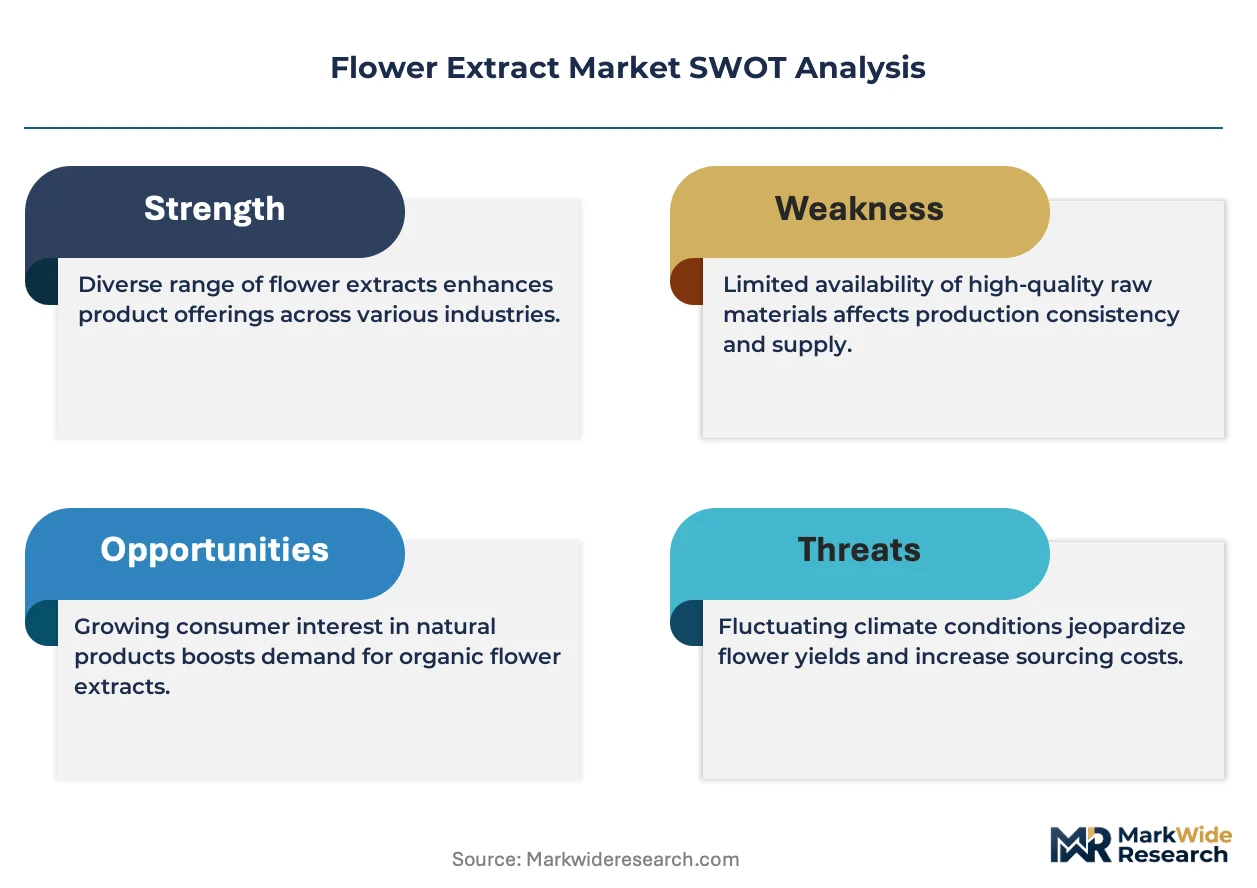
Cosmetics is restructuring demand flows across the flower extract value chain as formulators replace synthetic fragrance compounds with botanical alternatives. Givaudan leverages its captive raw material networks across Grasse and Madagascar to secure jasmine and rose supply chains. Symrise AG anchors European pharmaceutical-grade extraction through certified GMP facilities in Germany. International Flavors & Fragrances, Inc. competes on scale, operating multi-ton solvent extraction plants that supply both flavor and fragrance divisions.
Flower extract comprises volatile and semi-volatile compounds recovered from botanical material through steam distillation, solvent extraction, or cold pressing, yielding essential oils, absolute oils, floral waters, and enfleurage extracts with typical concentrations of 0.02-0.5% by fresh weight depending on species. These materials serve as functional ingredients in perfumery, therapeutic formulations, and food flavoring systems where synthetic substitutes face consumer rejection. Essential oils and absolute oils command the dominant share of value generation due to high concentration thresholds and labor-intensive harvesting requirements for roses, jasmine, and tuberose. Floral waters represent the fastest-expanding category as byproduct utilization improves and toner applications in skincare multiply.
REACH registration mandates in Europe and FDA GRAS determinations in the United States impose compositional disclosure burdens that favor suppliers with standardized analytical dossiers and traceable cultivation partnerships. EFSA novel food evaluations further gate entry for non-traditional floral species seeking food and beverage positioning. Stakeholders must monitor regulatory divergence between jurisdictions as clean-label claims attract intensified scrutiny from the FTC and national advertising standards bodies.
Market Dynamics
Cosmetics formulators are accelerating substitution of synthetic fragrance compounds with botanical absolutes and enfleurage extracts, compressing procurement timelines and rewiring supplier qualification criteria across the value chain.
Growth Catalysts
- Clean-label mandates:REACH and EU Green Deal compliance requirements redirect European investment toward solvent-free extraction technologies, expanding addressable supply for premium cosmetic brands.
- India:The country's PLI scheme for aromatic crop cultivation scales domestic distillation capacity, reducing import dependency for jasmine and tuberose feedstock.
- Supercritical CO2 extraction:This technology eliminates residual solvent concerns while preserving heat-sensitive volatile compounds, qualifying extracts for pharmaceutical-grade applications previously closed to conventional methods.
Market Restraints
- Input cost volatility:Rose and jasmine harvests concentrate in narrow climatic windows across Grasse and Madagascar, exposing processors to weather-driven supply shocks and labor cost inflation.
- Regulatory friction:EFSA novel food evaluations impose multi-year timelines for non-traditional floral species seeking food and beverage positioning, gating revenue diversification.
- Substitution threat:Biotechnology-derived aroma molecules from engineered yeast achieve cost parity with natural extracts in mid-tier fragrance applications.
Strategic Opportunities
- China:NMPA cosmetic registration reforms accelerate approval timelines for botanical ingredients, opening formulation partnerships with domestic skincare brands.
- Floral waters:Toner and facial mist applications multiply as byproduct utilization improves, capturing value previously discarded from essential oil distillation.
- Carbon accounting integration:EU Green Deal supply chain disclosure requirements create first-mover advantage for processors with certified cultivation partnerships and blockchain traceability.
Industry Challenges
- Analytical chemistry talent scarcity:Standardized dossiers for REACH and FDA GRAS determinations require specialized chromatography and spectroscopy capabilities that outpace current training pipelines.
- Multi-jurisdiction compliance synchronization:Divergent disclosure burdens between EFSA, FDA, and China's SAMR fragment quality management systems and extend certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flower Extract Market |
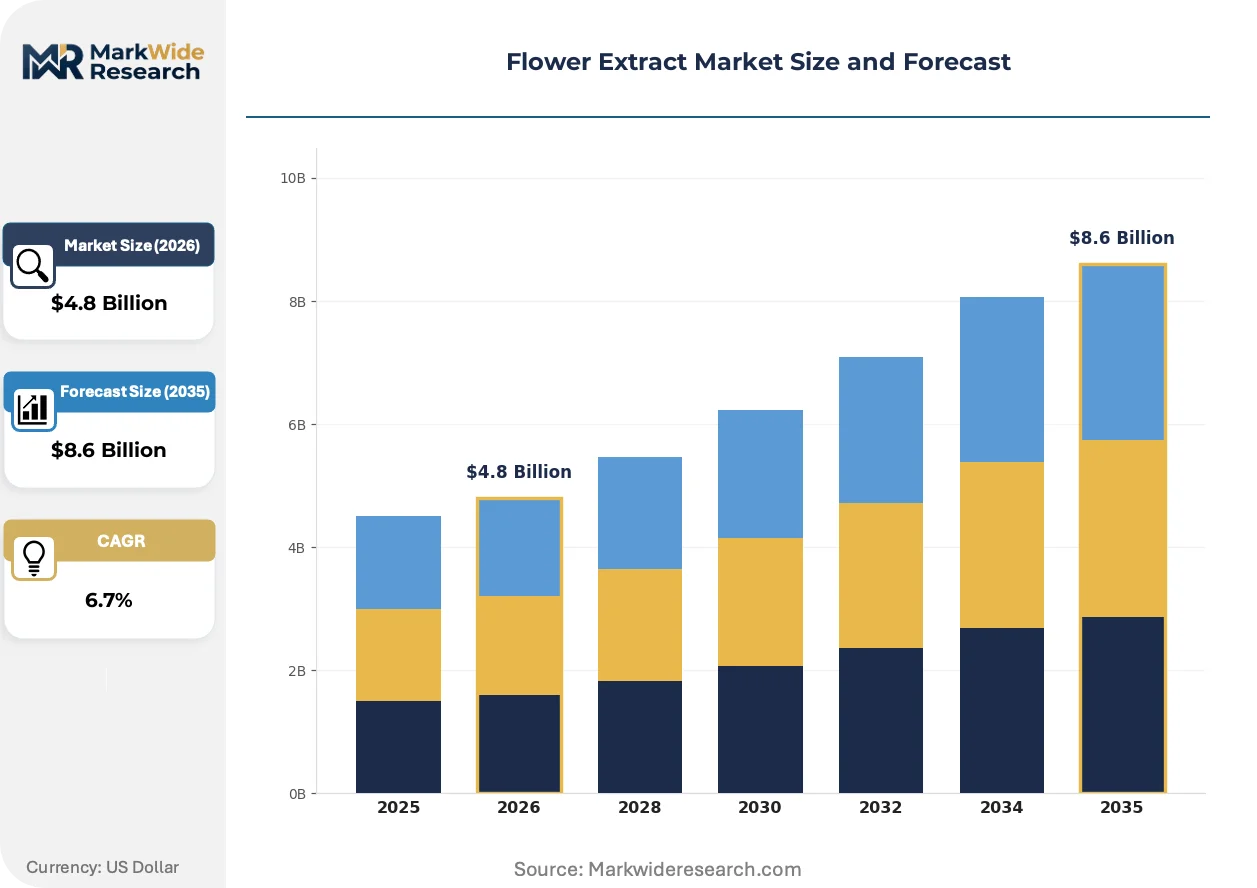
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Absolute Oils, Floral Waters, Enfleurage Extracts Application: Cosmetics, Food & Beverages, Aromatherapy, Pharmaceuticals End User: Cosmetic Manufacturers, Food Producers, Wellness Centers, Pharmaceutical Companies Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | International Flavors & Fragrances, Inc., Arjuna Natural, Givaudan, Döhler Group, Native Extracts Pty. Ltd., Sensient Technologies Corporation, Synthite Industries Ltd., Alchem International Pvt. Ltd., Symrise AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flower Extract Market Emerging Trajectories
Extraction technology convergence with digital traceability platforms is collapsing traditional quality assurance timelines while regulatory disclosure mandates restructure competitive differentiation around verifiable cultivation partnerships.
Supercritical CO2 extraction systems paired with in-line analytics are decentralizing quality control from centralized laboratories to production facilities. Mid-sized processors in France and India adopt these integrated units to bypass third-party testing bottlenecks. This capability compression enables smaller suppliers to meet pharmaceutical-grade specifications previously reserved for GMP-certified multinationals.
REACH registration mandates now require full compositional disclosure for imported botanical materials. European fragrance houses respond by consolidating procurement through vertically integrated Grasse-based operations with captive cultivation networks. Absolute oil supply chains face the steepest compliance burden due to complex multi-step extraction processes and solvent residue documentation requirements.
Direct contracting between cosmetic brands and distillation cooperatives is displacing traditional merchant intermediaries in raw material sourcing. French and Indian skincare labels now negotiate seasonal offtake agreements directly with jasmine and rose growers in Tamil Nadu and Uttar Pradesh. This channel compression accelerates in premium segments where provenance claims command formulation premiums.
Flower Extract Market Segmentation
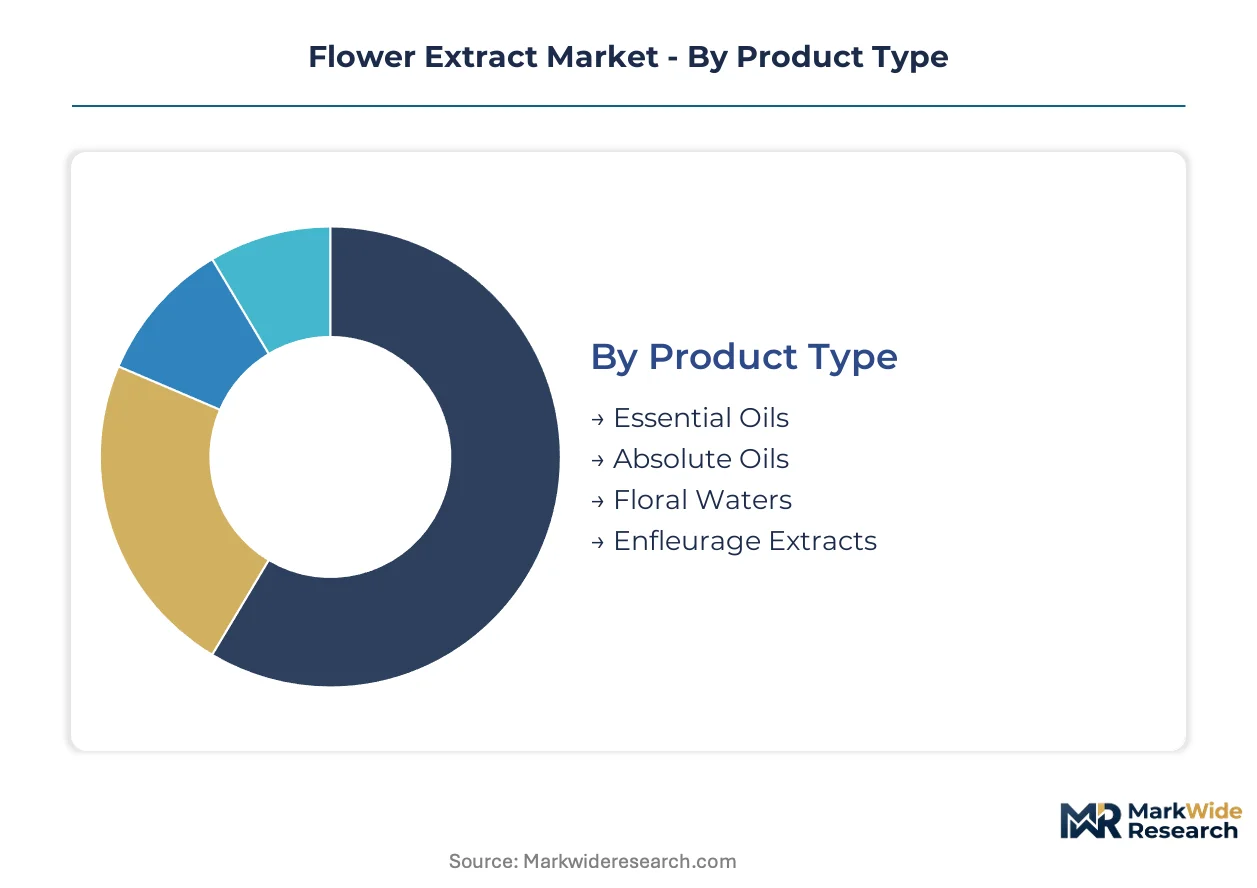
Product type distinctions in flower extracts determine extraction method selection, regulatory pathway, and margin structure across downstream applications. Formulators upgrade from essential oils to absolute oils when fragrance intensity requirements exceed steam distillation yields. Distribution channel choices increasingly reflect traceability demands rather than cost optimization alone.
Product Type:
Upgrade cycles between extraction grades accelerate as REACH disclosure mandates force cosmetic manufacturers to document solvent residues and volatile compound profiles.
- Essential Oils:Steam-distilled volatile compounds typically comprising terpenes, esters, and alcohols at concentrations of 0.02-0.5% fresh weight. Rose and lavender essential oils from Grasse and Bulgaria supply premium perfumery houses seeking standardized chromatographic dossiers for EU compliance.
- Absolute Oils:Solvent-extracted semi-volatile fractions capturing heat-sensitive floral notes unavailable through distillation. Jasmine absolute from Tamil Nadu commands formulation premiums in luxury skincare where enfleurage authenticity supports provenance marketing claims.
- Floral Waters:Hydrosol byproducts from steam distillation containing trace volatiles and water-soluble plant compounds. Toner and facial mist applications in French and Indian cosmetic brands expand utilization of previously discarded fractions.
- Enfleurage Extracts:Traditional cold-fat absorption methods preserving delicate aromatic profiles for niche fragrance applications. Madagascar tuberose enfleurage serves artisanal perfumers targeting connoisseur segments with heritage process narratives.
Essential oils sit at the top of the volume ranking, with floral waters climbing the fastest as byproduct valorization improves across distillation cooperatives.
Application:
Cost tier differentiation separates pharmaceutical-grade specifications from cosmetic and food applications, with analytical chemistry investments determining segment access.
- Cosmetics:Fragrance compounds, active botanicals, and functional ingredients in skincare, haircare, and color cosmetics. French formulators replace synthetic musks with rose and jasmine absolutes to satisfy clean-label procurement mandates from premium brands.
- Food & Beverages:Flavoring agents and natural preservatives in beverages, confectionery, and dairy applications. EFSA novel food evaluations constrain non-traditional floral species seeking positioning in European functional drinks.
- Aromatherapy:Therapeutic-grade essential oils for inhalation, topical, and diffusion applications. Wellness centers in India source certified organic lavender and chamomile through direct contracts with Uttar Pradesh distillation units.
- Pharmaceuticals:API precursors, excipients, and active compounds meeting pharmacopeial monograph standards. Supercritical CO2 extraction enables German GMP facilities to supply jasmine-derived compounds for clinical trial formulations.
Cosmetics commands the dominant revenue share, with food and beverages gaining share fastest as natural flavoring substitutions accelerate in beverage applications.
End User:
Customer type determines procurement scale, specification stringency, and supplier qualification timelines across the value chain.
- Cosmetic Manufacturers:Large-scale formulators and contract manufacturers requiring consistent batch-to-batch aromatic profiles. Givaudan and Symrise AG consolidate absolute oil procurement through captive Grasse cultivation networks to secure jasmine supply chains.
- Food Producers:Beverage and confectionery companies seeking GRAS-affirmed floral extracts for natural flavoring claims. FDA determination timelines favor suppliers with pre-existing analytical dossiers for rose and orange blossom compounds.
- Wellness Centers:Spas, clinics, and alternative therapy practitioners purchasing therapeutic-grade oils in smaller volumes. Direct-to-practitioner distribution in France bypasses traditional merchant intermediaries for chamomile and ylang-ylang supplies.
- Pharmaceutical Companies:Drug developers requiring pharmacopeial-grade extracts with documented purity and stability data. CDSCO registration requirements in India drive domestic distillation investment for standardized active botanical ingredients.
Cosmetic manufacturers anchor procurement volume, with pharmaceutical companies expanding fastest as supercritical extraction qualifies new compounds for clinical applications.
Distribution Channel:
Supply concentration in cultivation clusters shapes channel selection, with traceability requirements displacing cost-based routing decisions.
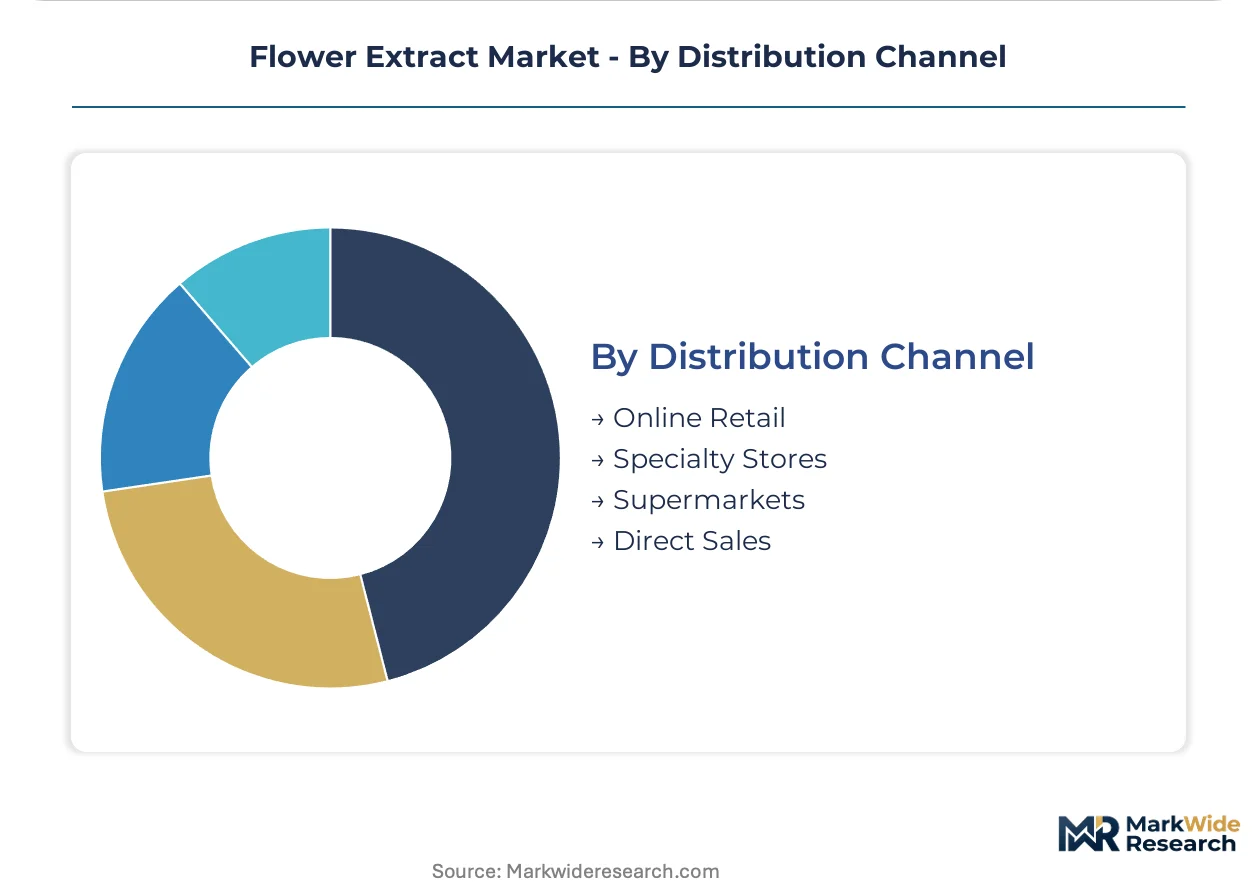
- Online Retail:E-commerce platforms serving artisanal producers, small formulators, and direct-to-consumer wellness brands. Indian jasmine and rose distillers in Tamil Nadu utilize B2B marketplaces to reach European cosmetic startups without intermediary markups.
- Specialty Stores:Dedicated aromatherapy and natural ingredient retailers offering curated selections with provenance documentation. Grasse-based distributors provide batch-specific chromatographic reports for absolute oil purchases by French perfumery ateliers.
- Supermarkets:Mass-market retail chains for standardized essential oils in personal care and home fragrance applications. Floral water SKUs expand shelf presence in French and Chinese grocery channels as toner applications mainstream.
- Direct Sales:Seasonal offtake agreements between cultivation cooperatives and end-user manufacturers. Rose growers in Uttar Pradesh negotiate annual contracts directly with Indian skincare brands, compressing traditional three-tier distribution structures.
Direct sales holds the largest volume position, with online retail expanding most quickly as blockchain traceability platforms enable remote supplier verification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting flower extract production toward jurisdictions with lower compliance costs and established aromatic crop infrastructure. Processors migrate capacity to exploit gaps between REACH registration burdens in Europe and streamlined cosmetic ingredient pathways in Asia.
France
Grasse-based distillation cooperatives supply jasmine and rose absolutes to luxury perfumery houses seeking provenance documentation for EU compliance. ANSM cosmetic safety evaluations enforce batch-level chromatographic disclosure, favoring vertically integrated operators with captive cultivation networks. The Provence-Alpes-Côte d'Azur cluster concentrates enfleurage expertise and solvent-free extraction R&D investment.
India
Tamil Nadu and Uttar Pradesh jasmine growers scale distillation capacity under the PLI scheme for aromatic crops, reducing feedstock import dependency for domestic cosmetic brands. CDSCO registration requirements for pharmaceutical-grade extracts drive GMP facility investment in Karnataka. The Kannauj cluster maintains traditional steam distillation heritage while adopting supercritical CO2 systems for export qualification.
China
Yunnan and Xinjiang rose cultivation expansions target domestic cosmetic ingredient demand as NMPA registration reforms accelerate botanical approval timelines. SAMR cosmetic safety assessments now recognize foreign GMP equivalency, opening formulation partnerships with European skincare brands. The Guangdong processing corridor integrates blockchain traceability platforms for EU Green Deal supply chain disclosure.
Germany
Symrise AG anchors European pharmaceutical-grade extraction through certified GMP facilities serving clinical trial compound suppliers. ECHA REACH enforcement mandates full compositional disclosure for imported absolutes, compressing merchant intermediary margins. The Bavarian chemical corridor concentrates supercritical CO2 equipment manufacturing and in-line analytics integration.
United States
FDA GRAS determinations for rose and orange blossom compounds favor suppliers with pre-existing analytical dossiers, gating entry for new market participants. FTC clean-label claim scrutiny intensifies documentation requirements for natural fragrance positioning in personal care. The New Jersey flavor and fragrance corridor hosts multi-ton solvent extraction plants supplying both cosmetic and food applications.
Flower Extract Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with absolute oil supply chains favoring integrated Grasse-based houses while floral water volumes concentrate in Indian distillation cooperatives. The vendor base organizes around three archetypes: captive cultivation operators, technology-integrated mid-processors, and merchant traders. Consolidation pressures mount as REACH disclosure mandates raise fixed compliance costs. Competitive moves center on backward integration into aromatic crop partnerships and supercritical extraction capacity licensing.
Within the integrated fragrance house tier, Givaudan and International Flavors & Fragrances, Inc. occupy positions defined by captive raw material networks and multi-ton extraction scale. Symrise AG exemplifies the pharmaceutical-grade specialist archetype through its German GMP-certified operations. These three companies anchor the competitive structure, with their geographic footprints and regulatory dossier capabilities determining segment access.
| Leading Market Players |
|---|
| International Flavors & Fragrances, Inc. |
| Arjuna Natural |
| Givaudan |
| Döhler Group |
| Native Extracts Pty. Ltd. |
| Sensient Technologies Corporation |
| Synthite Industries Ltd. |
| Alchem International Pvt. Ltd. |
| Symrise AG |
| Others |
Supply Flow & Price Mechanics
Jasmine and rose absolute spot prices in Grasse fluctuate with harvest yields, cascading through three-tier pricing structures that separate pharmaceutical-grade GMP-certified extracts from cosmetic absolutes and commodity floral waters.
Pricing Analysis
Distributor markups of 35-50% separate specialty stores from direct-to-manufacturer contracts, with pricing stratifying across premium, standard, and economy tiers based on certification grade and batch-level chromatographic documentation. Cost compression in mid-tier absolutes intensifies as Indian distillation cooperatives scale capacity under PLI scheme incentives. Cosmetic manufacturers exhibit highest price sensitivity for floral waters, while pharmaceutical buyers absorb premiums for REACH-registered jasmine compounds.
Supply Chain Analysis
Refurbishment of solvent extraction equipment extends asset life cycles in Indian processing clusters, with supply concentrating in France, India, and China for jasmine, rose, and tuberose feedstocks. The chain draws from seasonal harvest windows in Tamil Nadu, Uttar Pradesh, and Grasse, exposing processors to weather-driven supply shocks. Single-source vulnerability concentrates in Madagascar tuberose enfleurage. Distribution runs through direct seasonal offtake agreements and B2B platforms with blockchain traceability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flower extract markets compound steadily as clean-label substitution in cosmetics creates durable demand pull for botanical absolutes and enfleurage extracts.
For Market Incumbents: Hedge biotechnology substitution threats by deepening captive cultivation partnerships in Tamil Nadu and Grasse while licensing supercritical CO2 extraction technology to mid-tier processors. Prioritize REACH registration dossiers for absolute oil portfolios to defend merchant intermediary margins against vertical integration by fragrance houses. For New Entrants and Emerging Players: NMPA cosmetic registration reforms in China open a window for formulation partnerships with domestic skincare brands seeking European-compliant botanical ingredients. Target floral water toners for mass-market retail penetration, leveraging B2B marketplace distribution to bypass traditional three-tier structures. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-integrated mid-processors possessing in-line analytics capabilities and certified organic cultivation networks. Five-to-ten year viability hinges on carbon accounting integration for EU Green Deal compliance. Monitor EFSA novel food approval timelines as inflection indicators for food and beverage diversification potential.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aromatic Crop Partnerships | Captive jasmine and rose supply in Tamil Nadu secures REACH-compliant feedstock for absolute oil production. |
| Supercritical CO2 Extraction Licensing | German equipment manufacturers expand pharmaceutical-grade qualification to Indian and French mid-processors. |
| Blockchain Traceability Platform Deployment | Guangdong processors integrate EU Green Deal supply chain disclosure for cosmetic brand partnerships. |
| Direct-to-Manufacturer Distribution Expansion | Uttar Pradesh rose growers compress intermediary margins through annual offtake agreements with skincare brands. |
| Carbon Accounting Certification Program | Grasse-based operators capture first-mover advantage in EU Green Deal compliance for provenance marketing claims. |
Methodological Framework
Coverage spans France, India, China, Germany, and the United States, with primary inputs from each market through structured interviews with distillation cooperative managers, cosmetic formulation directors, fragrance house procurement leads, and regulatory affairs specialists at GMP-certified facilities. Secondary validation draws from ECHA REACH registration databases, FDA GRAS determination filings, CDSCO pharmaceutical ingredient approvals, and customs trade data for absolute oil and essential oil shipments. Bottom-up volume estimates from cultivation acreage and distillation capacity triangulate against top-down expenditure flows from cosmetic manufacturer procurement disclosures.
Granularity extends to product type, application, end user, and distribution channel dimensions, with extraction method and certification grade as industry-specific modeling layers. CAGRs derive from regression analysis of historical price-volume relationships and forward projection of regulatory compliance cost burdens across the analysis window. Forecast inputs incorporate PLI scheme implementation timelines for Indian aromatic crops and NMPA reform acceleration for Chinese cosmetic ingredient approvals.
Revisions become necessary when biotechnology-derived aroma molecules achieve cost parity ahead of projected timelines or when EFSA novel food evaluations accelerate for non-traditional floral species. Forecasts reflect assumptions about sustained clean-label procurement mandates and stable climatic conditions in Grasse and Madagascar growing regions. Practitioners should monitor supercritical CO2 equipment adoption rates and blockchain traceability platform deployment for early signals of supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Cajeput Oil Market
Extracts
Cassia Extract Market
Extracts
Thymoquinone Market
Extracts
Kelp Extracts Market
Extracts
Bee Venom Extract Market
Extracts
Patchouli Oil Market
Extracts
Irish Moss Extract Market
Extracts
Eucommia Extract Market
Extracts
Asia-Pacific Botanical Extract Market
Extracts
Histidine Market
Extracts
Tagetes Oil Market
Extracts
Organic Extracts Market
Extracts
Citrus Powder Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
Saffron Extract Market
Extracts
Marigold Essential Oil Market