
 Gum Turpentine Oil Market | 2026-2036
Gum Turpentine Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Gum Turpentine Oil Market Foresight
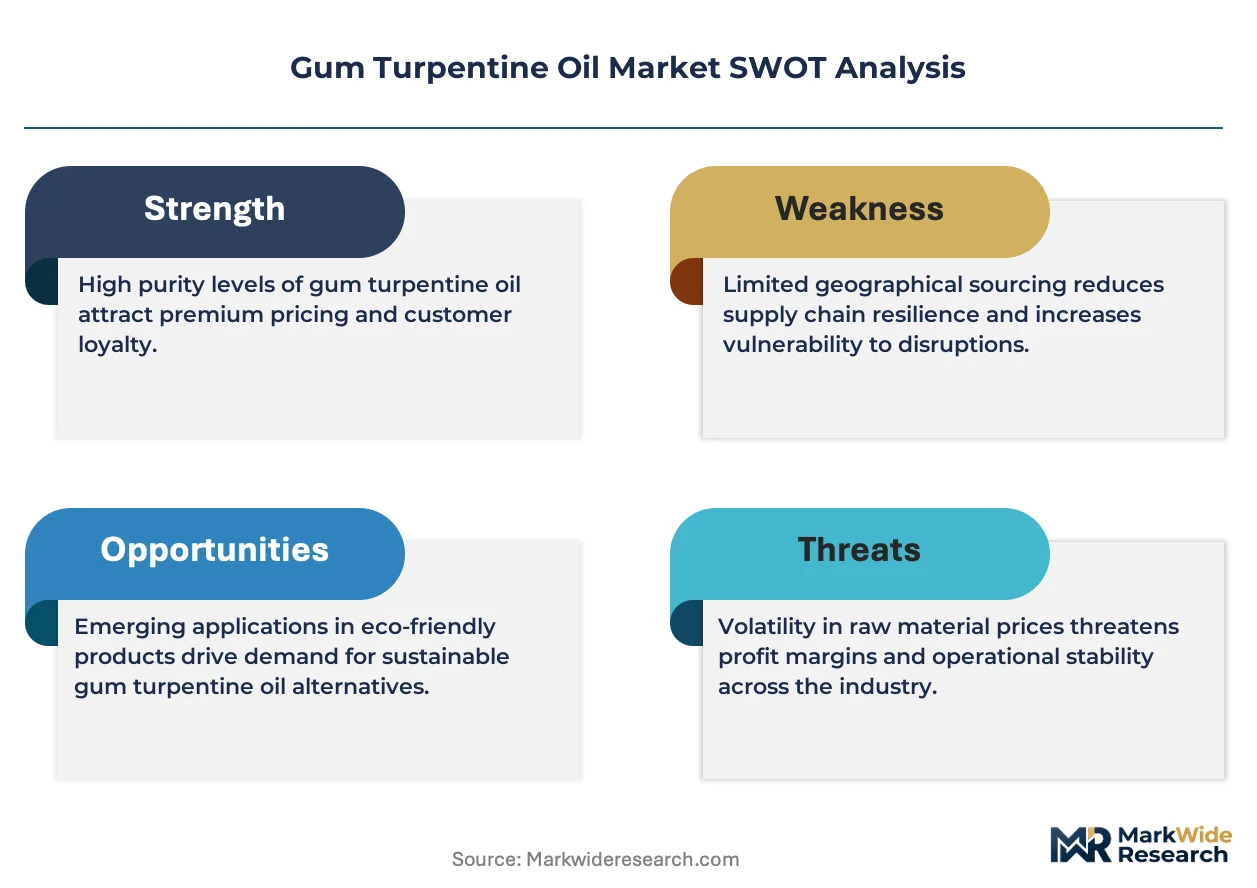
Capital-intensity divergence between integrated distillers and merchant resin processors is reorganizing competitive tiers in gum turpentine oil. DRT leverages captive pine forests in southwestern France to sustain backward integration from tapping to refined terpenes. Georgia-Pacific Chemicals anchors North American supply through controlled access to southeastern US pine stands. Kraton Corporation differentiates via specialized hydrogenated terpene resins for adhesives and sealants.
Gum turpentine oil is a volatile essential oil distilled from oleoresin exuded by living pine trees, typically containing alpha-pinene, beta-pinene, and camphene in varying ratios depending on Pinus species and geographic origin. Its primary commercial purpose centers on solvent applications in coatings and as a chemical feedstock for synthetic camphor, terpineol, and fragrance intermediates. Distilled turpentine commands the largest value share due to consistent purity specifications demanded by fragrance houses and pharmaceutical manufacturers. The cosmetics end-user segment exhibits the fastest structural expansion as formulators replace petroleum-derived solvents with botanically sourced terpenes. Paints and coatings applications remain mature volume anchors though waterborne technology shifts erode traditional solvent demand.
EPA oversight of volatile organic compound emissions shapes US formulation standards, while REACH registration requirements in Europe constrain unrefined crude turpentine imports. China's GB standards for industrial terpene solvents enforce quality thresholds that filter smaller resin processors from qualified supplier lists. Stakeholders must monitor bio-based solvent certification schemes and regional VOC tightening cycles to align product portfolios with evolving compliance thresholds.
Market Dynamics
Waterborne coating technology is systematically displacing solvent-borne formulations across architectural and industrial segments, eroding traditional gum turpentine offtake while simultaneously concentrating demand in high-purity fragrance and pharmaceutical grades that resist substitution.
Growth Catalysts
- REACH Registration Mandates:European ECHA compliance requirements for chemical safety data are filtering out unrefined crude turpentine imports, elevating demand for certified distilled grades among EU fragrance houses.
- Cosmetics Formulation Pivot:Personal care manufacturers are substituting petroleum-derived solvents with botanically sourced terpenes to meet clean beauty certification standards from ECOCERT and COSMOS.
- China's Pine Resin Infrastructure:Concentrated tapping operations across Guangxi and Yunnan provinces supply cost-competitive feedstock that feeds integrated distillation capacity serving Asian coating producers.
Market Restraints
- Crude Sulfate Turpentine Substitution:Kraft pulping byproduct CST supplies 60-70% of global turpentine volume at lower cost, compressing margins for gum-derived material in commodity solvent applications.
- Input Cost Volatility:Labor-intensive manual tapping of Pinus massoniana and Pinus elliottii stands faces wage inflation across southern China and southeastern United States harvesting regions.
- VOC Emission Caps:EPA NESHAP standards for hazardous air pollutants and state-level CARB limits constrain formulation flexibility in US architectural coatings, the largest historical consumption sink.
Strategic Opportunities
- Hydrogenated Terpene Resins:Specialized adhesive and sealant grades command price premiums over standard gum turpentine fractions, opening margin expansion for producers with hydrogenation capability.
- India Personal Care Penetration:Ayurvedic and natural cosmetics manufacturers in Maharashtra and Gujarat represent underdeveloped offtake channels for certified organic terpene solvents.
- EU Green Deal Bio-Based Mandates:Renewable material content targets for public procurement and corporate sustainability reporting under CSRD are creating preferential demand channels for certified bio-based terpenes.
Industry Challenges
- Distillation Skill Shortage:Fractional separation expertise for achieving pharmaceutical-grade alpha-pinene specifications is concentrated among aging technician cohorts in traditional producing regions.
- Multi-Jurisdiction Certification Timelines:Simultaneous pursuit of REACH, EPA TSCA, and China's MEE registration for new terpene derivatives extends commercialization cycles by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gum Turpentine Oil Market |
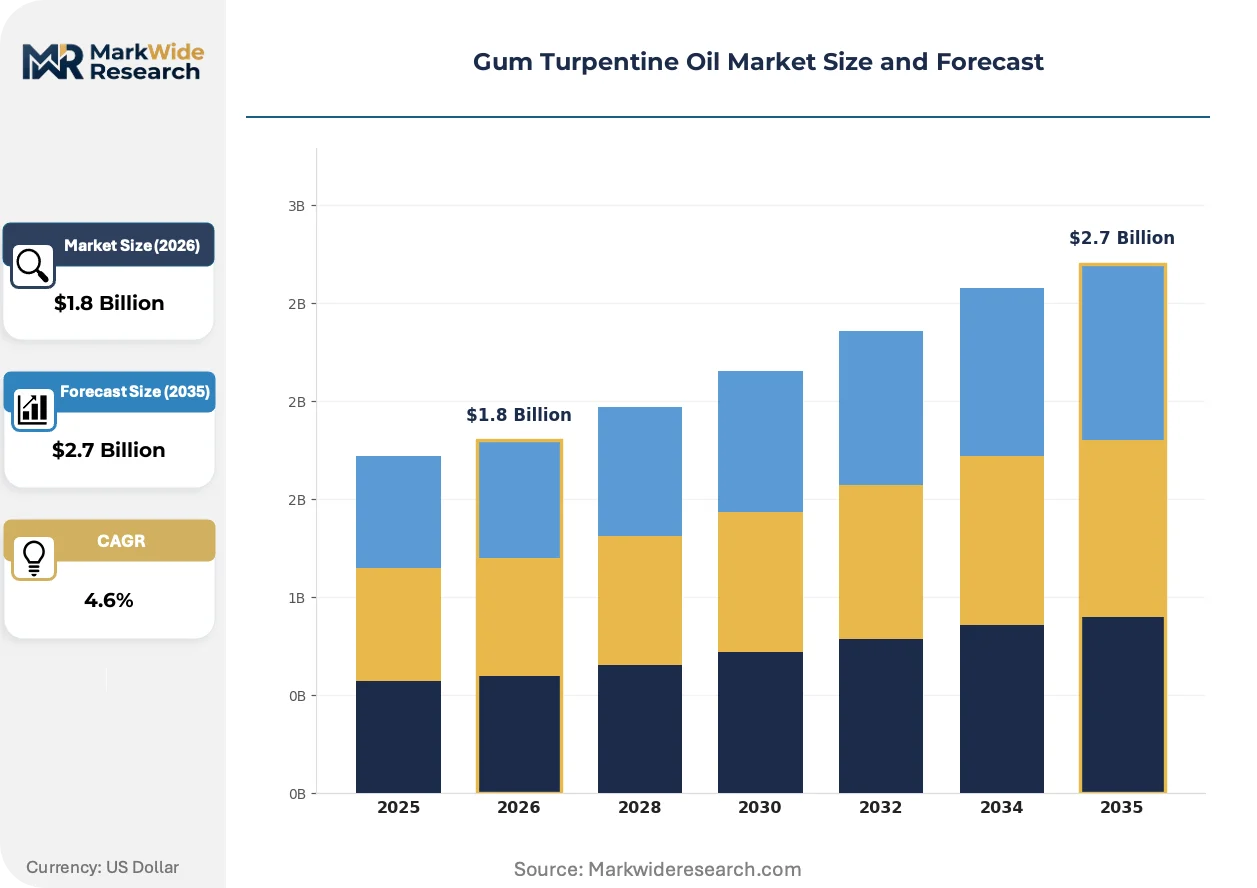
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turpentine Resin, Gum Turpentine, Distilled Turpentine, Crude Turpentine Application: Paints, Coatings, Adhesives, Cleaning Agents End User: Manufacturing, Automotive, Construction, Cosmetics Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Wuzhou Sun Shine Forestry & Chemicals, International Flavors & Fragrances Inc., Kraton Corporation, Lawter Inc., Arakawa Chemical Industries, Ltd., DRT (Les Dérivés Résiniques et Terpéniques), Georgia-Pacific Chemicals, Mentha & Allied Products Pvt. Ltd., Pine Chemical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gum Turpentine Oil Market Shifts & Advancements
Continuous extraction and molecular distillation technologies are reshaping quality thresholds across the value chain, while regulatory differentiation between bio-based and petroleum-derived solvents is creating new certification hierarchies that reward traceability investments.
Supercritical CO2 extraction of pine oleoresin is fragmenting traditional steam distillation economics by enabling cold-processing that preserves heat-sensitive terpene profiles. Fragrance houses in Grasse and Geneva are adopting these systems to secure differentiated raw materials for luxury perfume formulations. The technology is fragmenting supplier tiers by separating capital-intensive continuous processors from batch-operating traditional distillers.
REACH SVHC candidate list expansion is forcing reformulation across European industrial coatings and cleaning product sectors. ECHA's 2023-2024 updates targeting respiratory sensitizers are accelerating substitution of certain terpene fractions in workplace-exposed applications. German and Dutch formulators are responding with pre-registered alternative terpene blends that maintain solvency while reducing classification burden.
Direct contracting between cosmetics brands and certified forest operations is displacing merchant resin trading in premium segments. L'Oréal and Estée Lauder procurement teams now require chain-of-custody documentation from specific Pinus radiata plantations in New Zealand and Chile. This behavior concentrates most visibly in North American and Western European markets where ESG disclosure requirements from SEC and CSRD amplify traceability demands.
Gum Turpentine Oil Market Segmentation
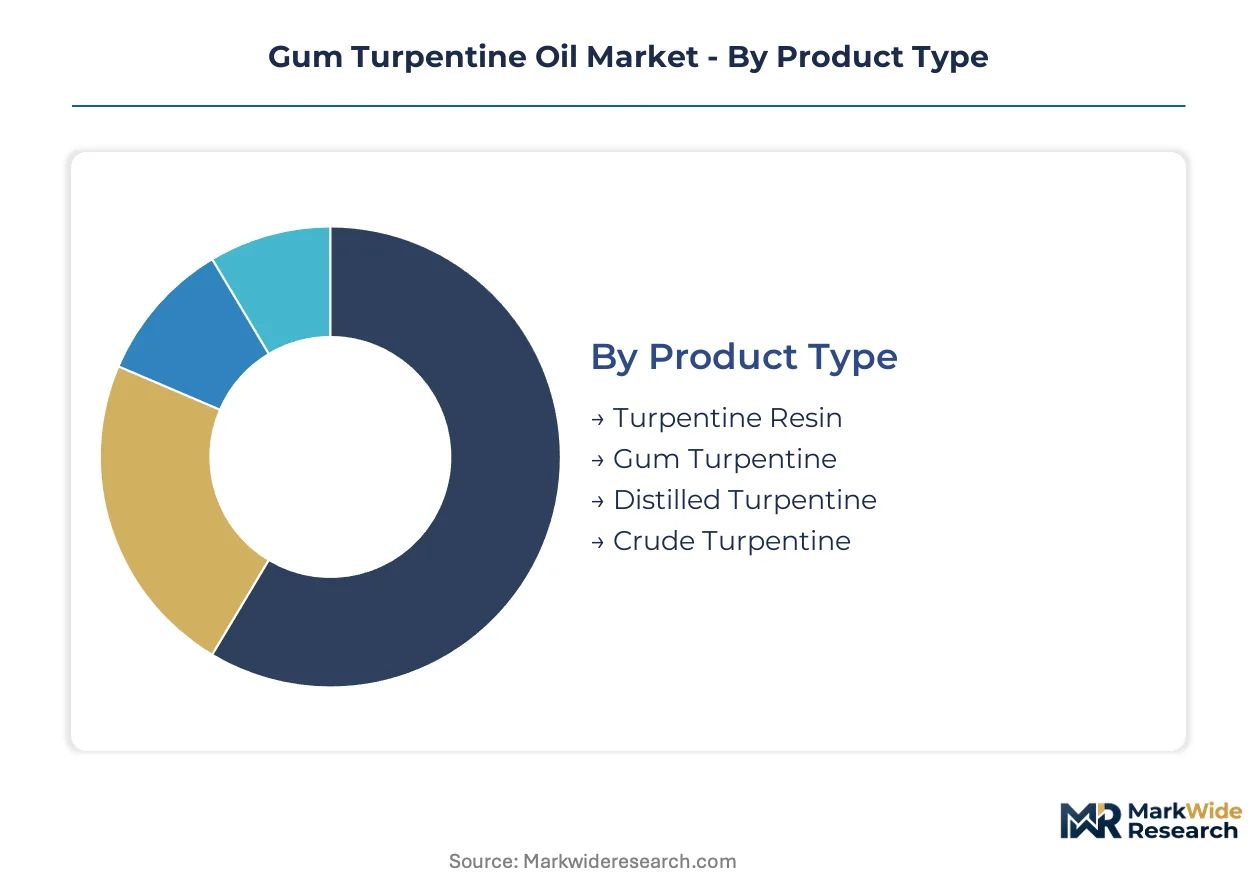
Segmentation in gum turpentine oil reveals how substitution pressures and regulatory thresholds fragment demand across purity grades and end-use specifications. Understanding these divisions exposes where margin compression from crude sulfate turpentine hits hardest versus where certified grades command defensible premiums.
Product Type:
Substitution pressure from crude sulfate turpentine concentrates most acutely in unrefined fractions, while distilled and hydrogenated variants resist displacement through purity specifications demanded by fragrance and pharmaceutical buyers.
- Distilled Turpentine:Refined through fractional separation to achieve consistent alpha-pinene and beta-pinene ratios meeting pharmaceutical and fragrance house specifications. EU fragrance manufacturers in Grasse and Geneva concentrate procurement here to satisfy REACH registration requirements and ECOCERT clean beauty standards.
- Gum Turpentine:Directly extracted from living pine oleoresin through manual tapping, retaining broader terpene profiles than Kraft byproduct alternatives. Chinese processors in Guangxi and Yunnan provinces dominate cost-competitive supply for Asian coating producers seeking bio-based solvent credentials.
- Turpentine Resin:Solid residue post-distillation serving adhesive and ink binder applications.
- Crude Turpentine:Unrefined oleoresin facing steepest margin compression from CST substitution in commodity solvent markets.
Distilled turpentine anchors the volume base while gum turpentine gains share at the steepest rate as cosmetics brands prioritize traceable botanical sourcing over petroleum-derived alternatives.
Application:
Waterborne technology diffusion has hollowed out architectural coating demand, redirecting volume toward specialty adhesive and precision cleaning segments where terpene solvency proves irreplaceable.
- Adhesives:Hydrogenated terpene resins deliver specific tack and peel properties for pressure-sensitive tapes and sealants. Kraton Corporation and specialized Japanese producers concentrate capacity here, commanding price premiums through hydrogenation capability that commodity distillers cannot replicate.
- Cosmetics:Personal care formulators in Maharashtra and Gujarat substitute petroleum-derived solvents with certified organic terpenes to meet Ayurvedic and natural cosmetics positioning. Direct contracting between brands and certified forest operations is displacing merchant resin trading in this channel.
- Paints:Mature volume anchor eroding as waterborne formulations displace solvent-borne systems in architectural and industrial segments.
- Coatings:Industrial maintenance applications retain some solvent demand where corrosion resistance specifications resist aqueous substitution.
- Cleaning Agents:Degreasing and precision electronics cleaning applications leveraging terpene biodegradability and low residue characteristics.
Paints retain the largest installed demand base while cosmetics applications expand most quickly as clean beauty certification schemes proliferate across North American and Western European markets.
End User:
Customer sophistication tiers separate bulk solvent buyers seeking cost minimization from premium segment purchasers requiring chain-of-custody documentation and pharmaceutical-grade specifications.
- Cosmetics:L'Oréal and Estée Lauder procurement teams now mandate specific Pinus radiata plantation sourcing from New Zealand and Chile with full traceability documentation. SEC climate disclosure rules and EU CSRD amplify these requirements, concentrating premium terpene demand among certified suppliers.
- Automotive:Refinishing and assembly plant cleaning applications where VOC emission caps under EPA NESHAP and state-level CARB limits constrain formulation flexibility and favor lower-emitting terpene blends.
- Manufacturing:Broad industrial solvent consumption facing systematic displacement by aqueous and bio-based alternatives in metal cleaning and degreasing operations.
- Construction:Architectural coatings and wood treatment applications where waterborne technology shifts erode traditional solvent offtake most severely.
Manufacturing represents the deepest established demand pool while cosmetics end-use climbs the fastest as ESG disclosure requirements harden procurement specifications across premium consumer markets.
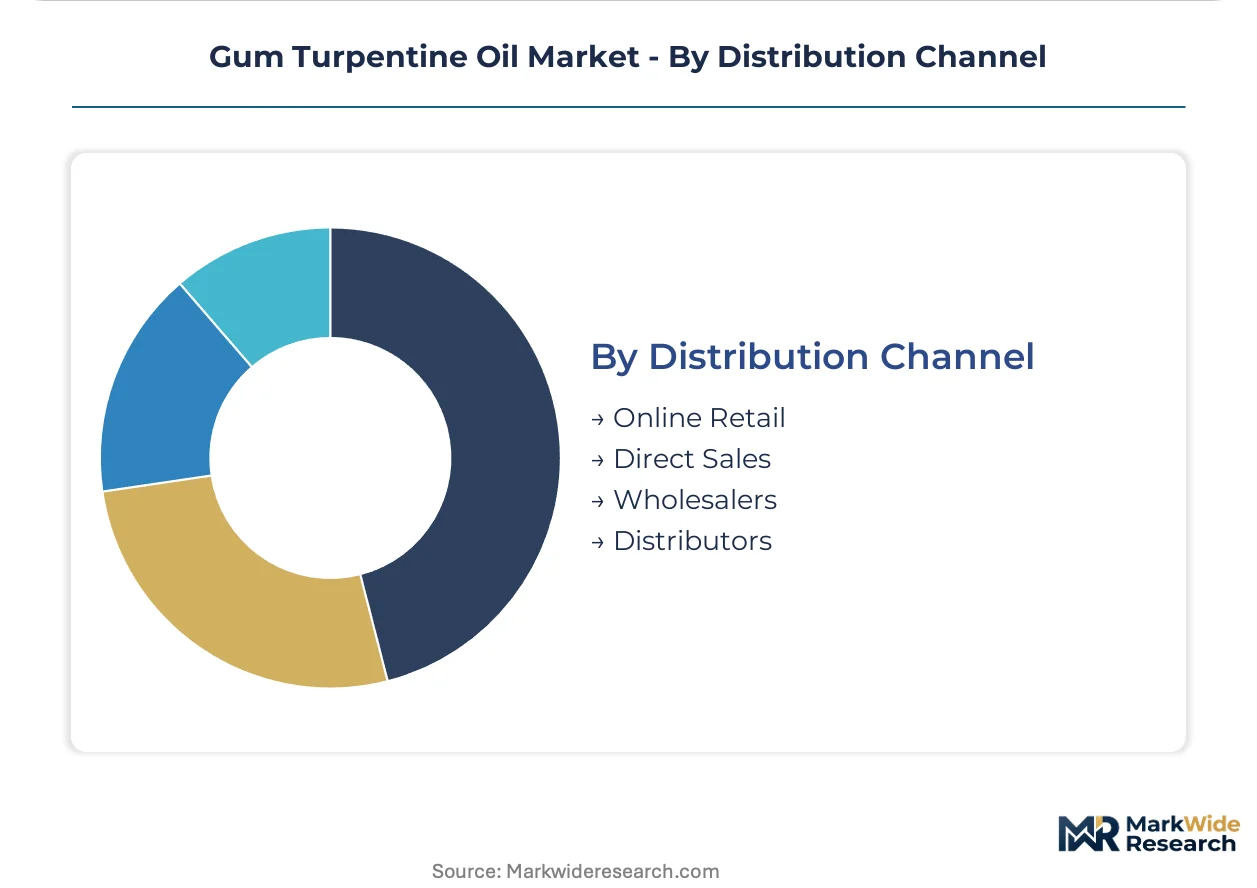
Distribution Channel:
Channel structure reflects the divergence between commodity volume moving through consolidated wholesale tiers and premium grades requiring direct technical service relationships.
- Direct Sales:Fragrance houses and pharmaceutical manufacturers contract directly with integrated distillers like DRT for pharmaceutical-grade alpha-pinene with batch-specific certificates of analysis. These relationships bypass merchant resin traders entirely and lock in multi-year supply agreements.
- Distributors:Regional chemical distributors serve mid-tier coating and adhesive formulators requiring technical support and blended formulations. German and Dutch distributors are pre-registering alternative terpene blends to address ECHA SVHC candidate list expansions targeting respiratory sensitizers.
- Wholesalers:Bulk commodity turpentine for industrial solvent applications where price sensitivity dominates procurement decisions.
- Online Retail:Small-volume specialty terpenes for artisanal cosmetics and craft applications.
Direct sales channels capture the steepest margin expansion while distributor relationships retain the broadest geographic coverage across fragmented industrial customer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for gum turpentine oil fragments sharply across geographies. Chinese buyers prioritize cost-competitive feedstock for industrial coatings, while European and North American purchasers absorb substantial premiums for certified grades meeting fragrance and pharmaceutical specifications.
China
Guangxi and Yunnan provinces concentrate pine resin tapping operations that supply cost-competitive feedstock for Asian coating producers. GB standards for industrial terpene solvents enforce quality thresholds that filter smaller processors from qualified supplier lists. Integrated distillation clusters in the Pearl River Delta serve domestic paint manufacturers seeking bio-based solvent credentials.
United States
Southeastern pine stands anchor North American supply through controlled access arrangements with integrated chemical producers. EPA NESHAP standards for hazardous air pollutants and state-level CARB limits constrain formulation flexibility in architectural coatings. Georgia-Pacific Chemicals leverages captive southeastern US pine resources to maintain backward integration from forest to refined terpenes.
France
Grasse and Geneva fragrance houses concentrate procurement of pharmaceutical-grade alpha-pinene to satisfy REACH registration requirements. ECHA compliance mandates for chemical safety data filter out unrefined crude turpentine imports, elevating demand for certified distilled grades. DRT operates integrated operations from captive pine forests in southwestern France through refined terpene production.
India
Maharashtra and Gujarat Ayurvedic and natural cosmetics manufacturers represent underdeveloped offtake channels for certified organic terpene solvents. BIS quality standards and DGFT import regulations shape access to refined terpene grades. Mumbai-based formulators are substituting petroleum-derived solvents with botanically sourced terpenes to meet clean beauty positioning.
Germany
Industrial coatings and cleaning product sectors face accelerated reformulation pressure from ECHA SVHC candidate list expansions targeting respiratory sensitizers. German formulators are pre-registering alternative terpene blends that maintain solvency while reducing classification burden. The KBA chemical regulatory framework intersects with EU Green Deal bio-based mandates to create preferential demand channels for certified renewable terpenes.
Gum Turpentine Oil Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in gum turpentine oil supply. Captive forest access and fractional distillation capability separate the upper tier from merchant resin processors facing margin compression from crude sulfate turpentine substitution. Three archetypes dominate: integrated forest-to-refinery operators, hydrogenation specialists serving adhesive markets, and fragrance-grade purity suppliers. Consolidation through backward integration into pine stands and forward integration into specialized terpene derivatives represents the primary competitive trajectory.
Among integrated operators with captive forest resources, DRT and Georgia-Pacific Chemicals exemplify the backward-integrated archetype controlling supply from tapping through refined outputs. Kraton Corporation occupies a position within the hydrogenation-specialist tier, differentiated via specialized terpene resin capabilities that commodity distillers cannot replicate. These three anchors illustrate how capital-intensity divergence between integrated and merchant processing tiers is reorganizing competitive positioning.
| Leading Market Players |
|---|
| Wuzhou Sun Shine Forestry & Chemicals |
| International Flavors & Fragrances Inc. |
| Kraton Corporation |
| Lawter Inc. |
| Arakawa Chemical Industries, Ltd. |
| DRT (Les Dérivés Résiniques et Terpéniques) |
| Georgia-Pacific Chemicals |
| Mentha & Allied Products Pvt. Ltd. |
| Pine Chemical Group |
| Others |
Supply & Pricing Matrix
Capacity utilization at integrated distilleries in southwestern France and the southeastern United States shapes margin floors across the value chain, concentrating pricing power among operators with captive pine stands while compressing returns for merchant resin processors exposed to crude sulfate turpentine substitution.
Pricing Analysis
After-sales service contracts for technical support and formulation guidance drive lifetime value in pharmaceutical-grade alpha-pinene supply. Three-tier pricing structure across pharmaceutical, fragrance, and industrial grades reflects purity certification and REACH registration status. Price differentiation hinges on ECOCERT organic credentials and batch-specific chain-of-custody documentation. Cost compression in unrefined crude turpentine is intensifying because Kraft pulping byproduct CST floods commodity solvent markets. Bulk coating formulators exhibit highest price sensitivity while L'Oréal and Estée Lauder procurement teams absorb substantial premiums for traceable Pinus radiata sourcing.
Supply Chain Analysis
Inbound logistics costs from Guangxi and Yunnan provinces to Pearl River Delta distillation clusters fluctuate with port congestion at Shenzhen and container availability on intra-Asia trade lanes. Supply concentrates in China, France, and the United States, with Chinese processors dominating cost-competitive feedstock and French operators anchoring fragrance-grade purity. Raw material dependencies include Pinus massoniana oleoresin, Pinus elliottii stands, and hydrogenation catalysts for adhesive-grade terpene resins. Single-source vulnerability concentrates in manual tapping labor pools across southern China. Distribution runs through direct sales to fragrance houses, regional chemical distributors for mid-tier formulators, and bulk wholesalers for industrial solvent buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated cosmetics procurement teams at L'Oréal and Estée Lauder, fragmenting pricing leverage among smaller resin processors unable to meet chain-of-custody documentation requirements.
For Market Incumbents: Fortify backward integration into captive pine forests in southwestern France and the southeastern United States to secure feedstock against wage inflation in manual tapping operations. Invest in hydrogenation capability for adhesive-grade terpene resins to escape margin compression from crude sulfate turpentine substitution in commodity solvent markets. DRT and Georgia-Pacific Chemicals exemplify this defensive posture through forest-to-refinery control. For New Entrants and Emerging Players: Differentiate on supercritical CO2 extraction technology to serve Grasse and Geneva fragrance houses seeking cold-processed terpene profiles for luxury perfume formulations. Target Maharashtra and Gujarat Ayurvedic cosmetics manufacturers as underdeveloped offtake channels where certified organic terpene demand outpaces qualified supply. Pursue direct contracting relationships with certified Pinus radiata plantations in New Zealand and Chile to bypass merchant resin trading tiers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hydrogenation specialists with adhesive and sealant capabilities over commodity distillers facing structural displacement. Long-term viability rests on producers with pharmaceutical-grade fractional distillation expertise and ESG-traceable feedstock arrangements. Acquisition target archetype: integrated operators with captive forest assets and REACH-registered derivative portfolios. Signal to watch: ECHA SVHC candidate list expansion accelerating terpene fraction substitution in workplace-exposed applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Pine Forests | Secures feedstock supply against labor cost inflation in Guangxi and Yunnan tapping operations. |
| Hydrogenation Capability Investment | Unlocks price premiums in pressure-sensitive adhesive and sealant segments where Kraton Corporation currently dominates. |
| Supercritical CO2 Extraction Adoption | Enables cold-processing that preserves heat-sensitive terpene profiles for Grasse fragrance house procurement. |
| REACH Registration Completion | Maintains EU market access as ECHA compliance filters unrefined crude turpentine imports from qualified supplier lists. |
| Direct Brand-Plantation Contracting | Satisfies SEC climate disclosure and EU CSRD traceability requirements for L'Oréal and Estée Lauder supply chains. |
Research Methodology
Initial hypotheses were tested against primary input from pine resin procurement managers, fractional distillation technicians, fragrance house formulators, and cosmetics brand supply chain directors and refined through secondary validation against customs trade data, ECHA registration databases, SEC climate disclosure filings, and Chinese GB standards documentation. Bottom-up capacity estimates from Guangxi and Yunnan tapping operations were triangulated with top-down demand modeling across coating, adhesive, and personal care end-uses.
Variance decomposition across product type, application, purity grade, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level demand elasticity and substitution trajectory modeling. Forecast inputs included waterborne coating technology diffusion rates, CST supply growth from Kraft pulping capacity expansion, and ECHA SVHC candidate list revision schedules.
Material uncertainties — crude sulfate turpentine supply expansion, REACH SVHC reclassification timing, and manual tapping labor availability in southern China — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and cosmetics brand ESG commitment durability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Lotus Extract Market
Extracts
Cajeput Oil Market
Extracts
Apple Powder Market
Extracts
Palmarosa Oil Market
Extracts
Extracts and Distillates Market
Extracts
Lavender Oil Market
Extracts
Pectinase Market
Extracts
Orange Oil Market
Extracts
Irish Moss Extract Market
Extracts
Peppermint Oil Market
Extracts
Cochineal Extract Market
Extracts
Solid Phase Extraction Market
Extracts
Pennyroyal Oil Market
Extracts
Labdanum Market
Extracts
Gelatin Hydrolysates Market
Extracts
Copaiba Essential Oil Market