
 Kelp Extracts Market | 2026-2036
Kelp Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Kelp Extracts Market Intelligence
Plant-based hydrocolloids is recalibrating conventional gelatin economics across food and pharmaceutical binding applications. Cargill Incorporated leverages its agricultural supply chain infrastructure to secure raw kelp volumes at scale. Acadian Seaplants Limited anchors North Atlantic harvesting operations with proprietary cold-water extraction protocols. CP Kelco dominates refined alginate and carrageenan capacity for industrial texturizing demands.
Kelp extracts comprise concentrated bioactive compounds—principally alginates, fucoidans, and laminarins—derived from brown seaweed through aqueous or solvent extraction, typically standardized to polysaccharide content between fifteen and twenty-five percent for commercial grading. These extracts function as gelling agents, emulsion stabilizers, and bioactive carriers across formulated products. Powder extracts command the widest manufacturing adoption due to extended shelf stability and freight efficiency, while liquid extracts retain faster hydration kinetics for beverage and cosmetic serum applications. Pharmaceutical-grade standardized extracts capture premium margin pools where compendial purity certification gates market access.
The European Chemicals Agency enforces REACH substance registration for imported kelp derivatives, directly conditioning Asian exporter market entry. The FDA maintains GRAS notification pathways for alginates in food matrices, shaping formulation choices for nutraceutical developers. The FAO/WHO Codex Alimentarius provides international food additive specifications that harmonize cross-border trade standards. Stakeholders must monitor evolving solvent residue limits and organic certification reciprocity agreements between major harvesting and consuming jurisdictions to preserve supply continuity.
Market Dynamics
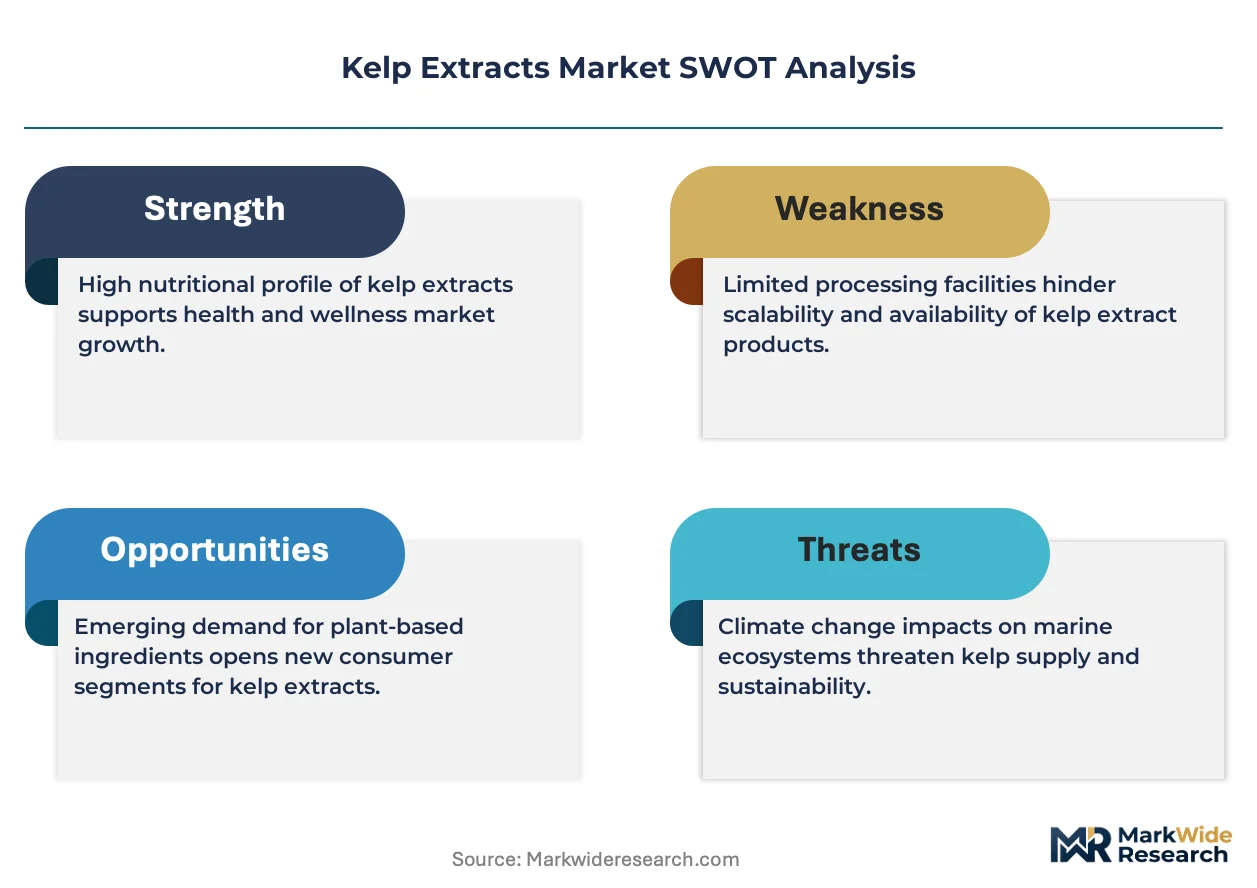
Marine biotechnology maturation is compressing extraction yields while EU solvent standards tighten, forcing processors to retool aqueous systems or exit compendial-grade supply tiers entirely.
Growth Catalysts
- Clean-label hydrocolloid substitution:Food formulators replace synthetic stabilizers with alginate gelling agents to meet retailer clean-label mandates across Western European retail channels.
- REACH registration reciprocity:Harmonized substance dossiers between ECHA and South Korea's MFDS accelerate Korean alginate supplier entry into EU cosmetic ingredient supply chains.
- Cold-water extraction protocols:Proprietary enzymatic pre-treatment methods developed in Canadian Atlantic facilities improve fucoidan bioactivity retention versus conventional heat processing.
Market Restraints
- Wild-harvest biomass volatility:North Atlantic kelp beds face seasonal density fluctuations that concentrate raw material sourcing within a six-week harvest window.
- Pharmaceutical-grade solvent residue limits:EMA and FDA divergent maximum residue levels for methanol and acetone force dual-track purification investments.
- Plant-based gelatin alternatives:Pectin and modified starch texturizers capture mid-tier food applications at 40-60% lower input cost per functional unit.
Strategic Opportunities
- Microbiome-targeted cosmetic actives:Laminarin prebiotic fractions command premium positioning in South Korean fermented skincare formulations.
- Carbon-negative packaging feedstock:Alginate biopolymer films align with EU Green Deal single-use plastic reduction targets for food service applications.
- Direct-to-supplement-brand distribution:Bypassing traditional ingredient distributors allows extractors to capture margin from US nutraceutical startups seeking provenance certification.
Industry Challenges
- Phycologist workforce scarcity:Specialized brown seaweed taxonomy and cultivation expertise concentrates within three Nordic university programs, constraining R&D expansion.
- Organic certification timeline compression:EU organic aquaculture standard revisions delay harvest area recertification, freezing premium-grade inventory access for 18-24 month cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kelp Extracts Market |
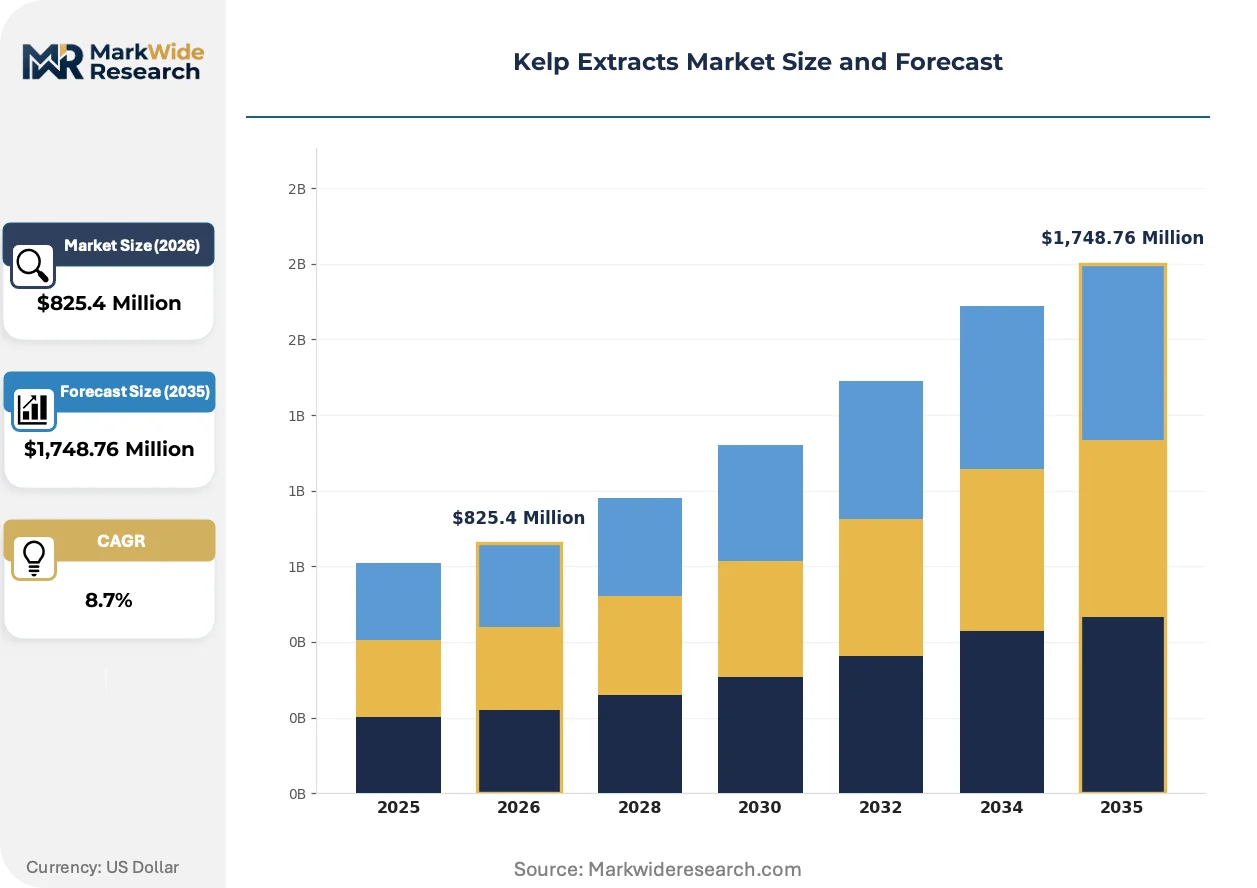
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,748.76 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extracts, Powder Extracts, Granules, Tablets Application: Food & Beverage, Cosmetics, Pharmaceuticals, Agriculture End User: Food Manufacturers, Cosmetic Companies, Nutraceuticals, Farmers Form: Organic Form, Non-Organic Form, Standardized Extracts, Blends |
| Companies Covered | Cargill Incorporated, Acadian Seaplants Limited, CP Kelco, DuPont, Groupe Roullier, Algaia, Gelymar, Kelpak, Seasol International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kelp Extracts Market Strategic Shifts & Innovations
Enzymatic specificity and regulatory data transparency are displacing conventional extraction and certification paradigms across marine ingredient supply chains.
Subcritical water extraction is rewriting fucoidan recovery economics by eliminating organic solvent dependency entirely. Pharmaceutical ingredient buyers in Germany and Switzerland now specify SWE-processed material for injectable-grade applications. This technology compresses capital intensity for new market entrants while raising purity benchmarks incumbent solvent facilities cannot match without full retooling.
EU F-Gas Regulation phase-down schedules are accelerating refrigeration-dependent extraction facility conversions to closed-loop geothermal systems. Baltic Sea processors in Denmark and Sweden face 2027 compliance deadlines that favor greenfield investments over legacy plant retrofit. Cosmetic-grade alginate supply from these facilities now carries carbon footprint disclosure requirements demanded by French and German formulators.
Beauty conglomerates now mandate batch-level blockchain traceability from harvest coordinates through final extraction. South Korean MFDS-registered suppliers lead implementation, with domestic brands requiring QR-linked provenance for shelf placement. This behavioral shift fragments supplier bases: integrated harvest-to-extract operators capture volume while traders without vessel or drying asset control face exclusion from premium tier procurement lists.
Kelp Extracts Market Segmentation
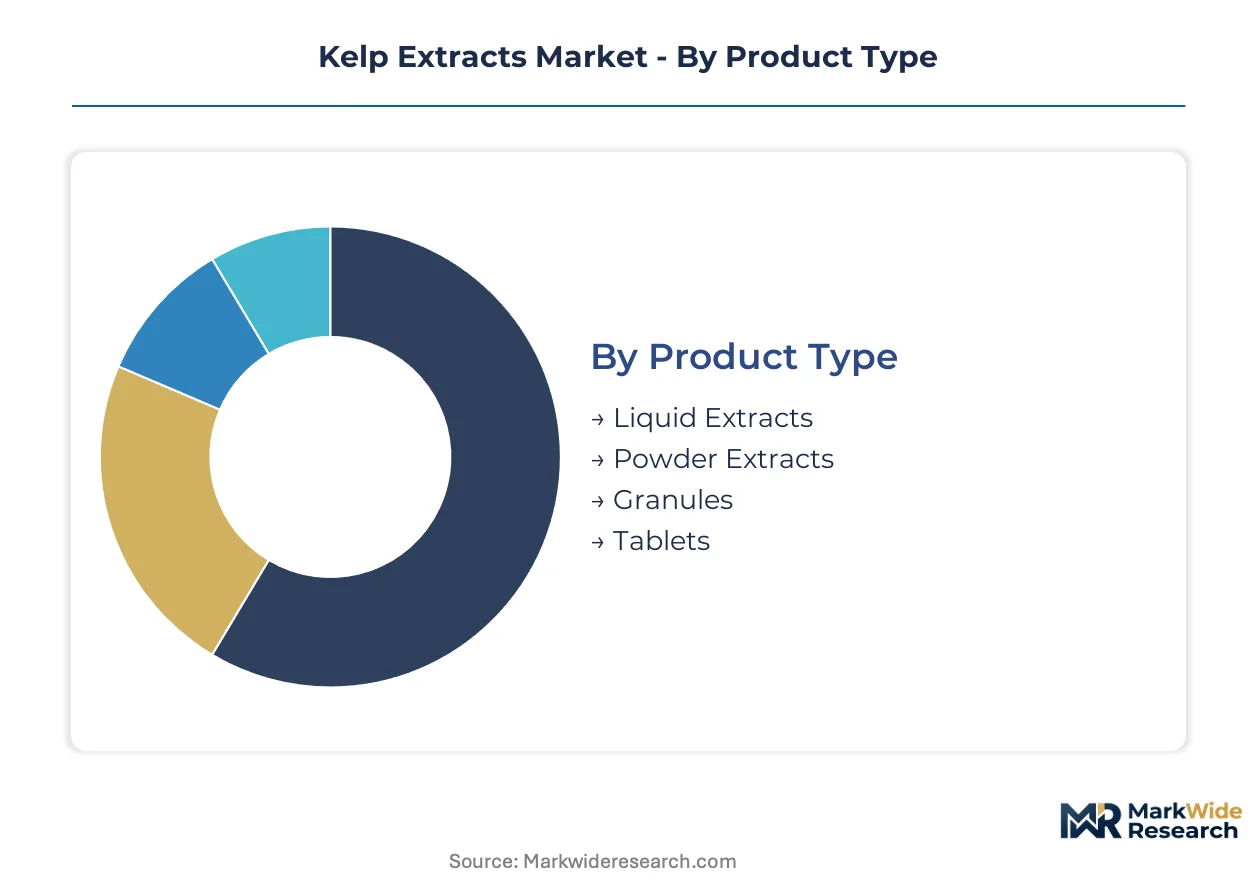
Kelp extract value chains fracture across four dimensions that determine pricing power and regulatory burden. Product form dictates extraction capital requirements while end-user specifications gate market access through certification protocols.
Product Type:
Capital intensity peaks with pharmaceutical-grade powder facilities requiring closed-loop solvent recovery systems, while liquid extraction demands less upfront investment but sacrifices shelf stability premiums.
- Liquid Extracts:Aqueous suspensions with faster hydration kinetics serve beverage formulators and cosmetic serum manufacturers. South Korean beauty conglomerates source MFDS-certified liquid alginate for fermented skincare lines where rapid dispersion properties command formulation preference.
- Powder Extracts:Spray-dried concentrates standardized to 15-25% polysaccharide content dominate commercial grading. Extended shelf stability and freight efficiency position powder extracts as the default specification for industrial texturizing demands across European food manufacturing.
- Granules:Intermediate moisture formats occupy niche agricultural inoculant applications.
- Tablets:Compressed dosage forms serve direct-to-consumer nutraceutical channels with provenance certification requirements.
Most installed capacity flows through Powder Extracts. Expansion is steepest in Liquid Extracts.
Application:
Margin tiering separates pharmaceutical compendial grades from commodity food additives, with cosmetic actives capturing intermediate value pools through bioactive fraction specificity.
- Food & Beverage:Clean-label alginate gelling agents replace synthetic stabilizers in Western European retail channels. Cargill Incorporated leverages agricultural supply chain infrastructure to secure raw kelp volumes at scale for this segment.
- Cosmetics:Marine-based skincare lines source laminarin prebiotic fractions for microbiome-targeted positioning. South Korean fermented skincare formulations command premium pricing through MFDS-registered supplier networks.
- Pharmaceuticals:Injectable-grade fucoidan applications specify subcritical water extraction to eliminate organic solvent dependency entirely.
- Agriculture:Biostimulant applications for crop stress tolerance remain price-sensitive versus hydrocolloid end-uses.
Pharmaceutical-grade installations command highest capital deployment per output ton. Cosmetics applications are gaining share fastest through bioactive premium positioning.
End User:
Procurement sophistication varies dramatically: multinational food manufacturers enforce batch-level blockchain traceability while fragmented agricultural buyers prioritize unit economics over provenance documentation.
- Food Manufacturers:Retailer clean-label mandates drive alginate substitution for synthetic stabilizers. EU F-Gas Regulation compliance now conditions supplier qualification for frozen dessert applications.
- Cosmetic Companies:French and German formulators mandate carbon footprint disclosure from Baltic Sea processors facing 2027 geothermal conversion deadlines.
- Nutraceuticals:US supplement startups seek direct-to-brand distribution bypassing traditional ingredient distributors.
- Farmers:Price-sensitive biostimulant procurement concentrates in Asian cultivation markets with less stringent organic certification requirements.
Food Manufacturers anchor current volume offtake. Nutraceuticals represent the steepest expansion trajectory through provenance-premium capture.
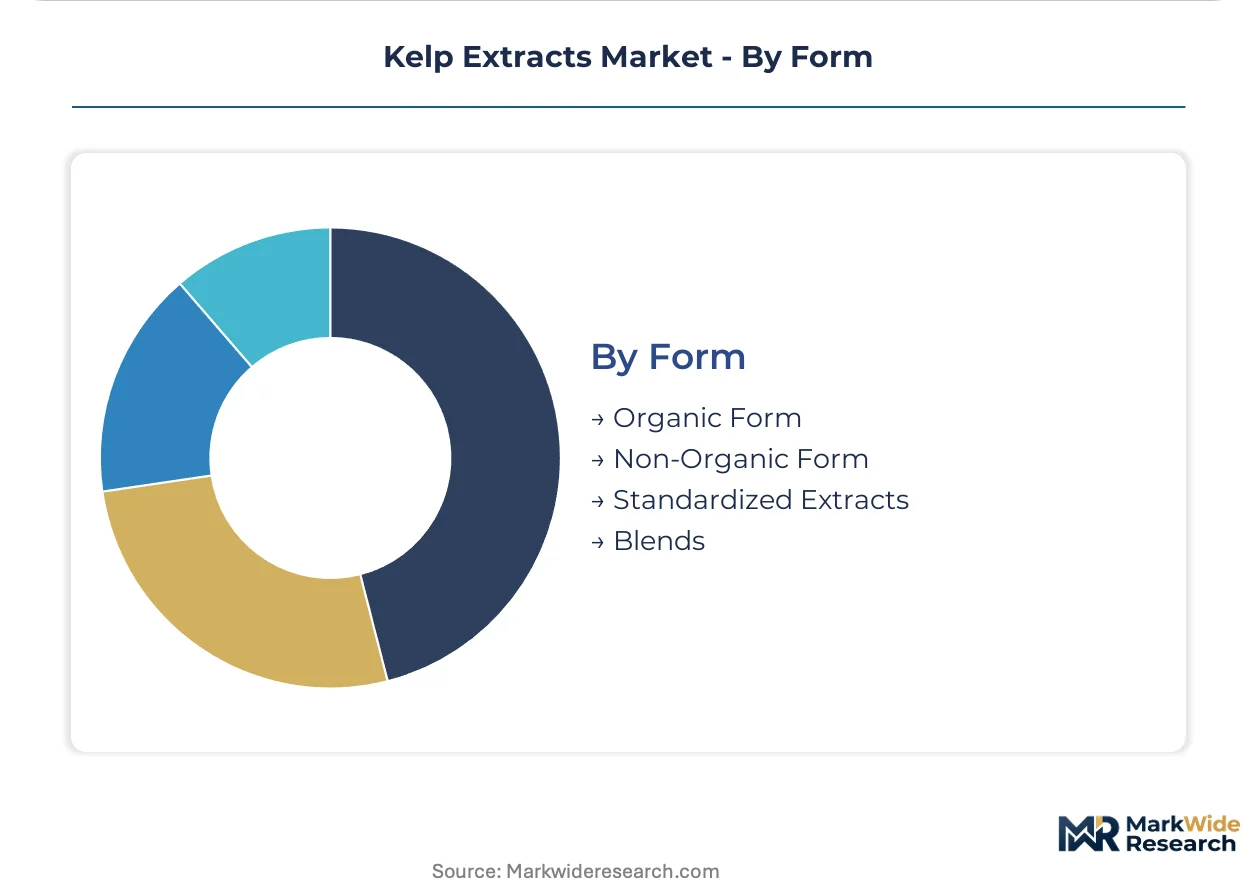
Form:
Certification tiering creates three distinct margin bands: organic aquaculture standard compliance, conventional extraction, and pharmaceutical-grade standardization with divergent solvent residue protocols.
- Organic Form:EU organic aquaculture standard revisions delay harvest area recertification, freezing premium-grade inventory access for 18-24 month cycles. Acadian Seaplants Limited anchors North Atlantic organic harvesting with proprietary cold-water extraction protocols.
- Non-Organic Form:Conventional extraction serves cost-optimized industrial texturizing where EMA and FDA divergent maximum residue levels for methanol and acetone force dual-track purification investments.
- Standardized Extracts:Compendial purity certification gates pharmaceutical market access through USP-NF or EP monograph compliance.
- Blends:Custom polysaccharide ratios address specific rheological requirements in formulated products.
Non-Organic Form carries most installed extraction capacity. Organic Form faces steepest expansion constraints from certification timeline compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Busan-Ulsan anchors kelp extract processing capacity through MFDS-registered alginate suppliers serving domestic beauty conglomerates with fermented skincare formulations.
South Korea
Seoul Capital Area beauty conglomerates drive laminarin prebiotic fraction procurement for microbiome-targeted cosmetic lines. MFDS certification reciprocity with ECHA accelerates EU cosmetic ingredient supply chain entry. Busan-Ulsan processing clusters concentrate cold-water extraction capacity for premium-grade alginate output.
Germany
Pharmaceutical ingredient buyers in Frankfurt-Rhine-Main specify subcritical water extraction for injectable-grade fucoidan applications. EMA solvent residue limits for methanol and acetone gate compendial market access. Baltic Sea processors face 2027 EU F-Gas Regulation compliance deadlines favoring geothermal conversion investments.
United States
Nutraceutical startups in Greater Boston and San Francisco Bay Area seek direct-to-brand distribution bypassing traditional ingredient distributors. FDA GRAS notification pathways for alginates shape food matrix formulation choices. Pacific Northwest harvesting operations supply raw kelp volumes for clean-label hydrocolloid substitution trends.
Canada
Atlantic provinces anchor North American organic kelp harvesting through proprietary cold-water extraction protocols. Health Canada regulatory alignment with US FDA reduces dual-track purification burdens for cross-border pharmaceutical supply. Nova Scotia and New Brunswick facilities improve fucoidan bioactivity retention versus conventional heat processing methods.
France
Paris-based cosmetic formulators mandate carbon footprint disclosure from alginate suppliers under EU Green Deal single-use plastic reduction targets. ANSM compliance protocols condition cosmetic ingredient market entry. Brittany coastal clusters concentrate wild-harvest biomass operations within concentrated six-week seasonal windows.
Kelp Extracts Market Key Industry Players
Capacity expansion dominates the current landscape as processors retool aqueous extraction systems to meet tightening EU solvent standards. The vendor base stratifies across three tiers: integrated harvest-to-extract operators with vessel and drying asset control, mid-scale regional processors serving domestic food manufacturers, and specialty biotech firms targeting pharmaceutical-grade standardization. Strategic archetypes include agricultural supply chain conglomerates leveraging raw material sourcing infrastructure, Atlantic harvesting specialists with proprietary cold-water protocols, and refined hydrocolloid manufacturers dominating industrial texturizing capacity. Competitive moves concentrate on backward integration into captive kelp bed leasing and technology licensing for subcritical water extraction systems.
Among North American harvesting specialists, Acadian Seaplants Limited occupies a position exemplifying Atlantic province organic certification concentration, while CP Kelco represents the scale-driven industrial hydrocolloid tier with refined alginate and carrageenan capacity. Cargill Incorporated anchors the agricultural conglomerate archetype, leveraging supply chain infrastructure to secure raw kelp volumes at scale for food and beverage applications.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Acadian Seaplants Limited |
| CP Kelco |
| DuPont |
| Groupe Roullier |
| Algaia |
| Gelymar |
| Kelpak |
| Seasol International |
| Others |
Cost & Logistics Intelligence
Cosmetic formulators in Seoul Capital Area concentrate procurement power through MFDS-registered supplier mandates, driving a contract-based long-term offtake pricing model with embedded volume commitments and batch-level certification premiums.
Pricing Analysis
Raw kelp biomass pass-through from North Atlantic six-week harvest windows anchors input-cost volatility across powder and liquid extract tiers. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and industrial-grade levels separates compendial purity certification from conventional extraction. Cost compression in industrial-grade alginate is intensifying because pectin and modified starch substitutes capture mid-tier food applications at lower functional-unit economics. Agricultural biostimulant buyers exhibit highest price sensitivity, while injectable-grade pharmaceutical purchasers prioritize solvent-residue compliance over unit cost.
Supply Chain Analysis
Brown seaweed biomass rests on wild-harvest operations in Canada, France, and South Korea, with seasonal density fluctuations compressing raw material sourcing into concentrated harvest windows. Aqueous extraction solvents, enzymatic pre-treatment reagents, and closed-loop solvent recovery systems constitute critical input dependencies. Single-source vulnerability concentrates in Nordic phycologist workforce scarcity, constraining R&D expansion and quality control capacity. Distribution runs through integrated harvest-to-extract operators with vessel and drying asset control, bypassing trader intermediaries excluded from premium-tier procurement lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kelp extracts market reads as a late-cycle quality story, with South Korean beauty conglomerate demand shifting toward laminarin prebiotic fractions that command provenance-premium positioning over commodity hydrocolloids.
For Market Incumbents: Acquire captive kelp bed leasing rights in Atlantic provinces to secure organic-certified raw material access against wild-harvest biomass volatility. Invest in subcritical water extraction technology licensing to eliminate organic solvent dependency and meet EMA injectable-grade residue specifications. Defend margin position by backward integration into proprietary cold-water enzymatic pre-treatment protocols that improve fucoidan bioactivity retention. For New Entrants and Emerging Players: Begin with direct-to-supplement-brand distribution channels serving US nutraceutical startups seeking provenance certification, bypassing traditional ingredient distributor margin capture. Target carbon-negative packaging feedstock applications under EU Green Deal single-use plastic reduction targets, where alginate biopolymer films face limited incumbent specialization. White-space exists in microbiome-targeted cosmetic actives for fermented skincare formulations. For Investors and Strategic Acquirers: Agricultural supply chain conglomerates are the most active acquirer in this space, seeking kelp extract capabilities to complement existing hydrocolloid portfolios. The five-to-ten year viability window favors integrated harvest-to-extract operators with MFDS-ECHA certification reciprocity and blockchain traceability infrastructure. Watch EMA-FDA solvent residue convergence as an inflection indicator for pharmaceutical-grade capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Subcritical Water Extraction Licensing | Eliminates organic solvent dependency for EMA injectable-grade fucoidan specifications. |
| Captive Kelp Bed Leasing | Secures organic-certified biomass access against North Atlantic seasonal harvest compression. |
| Blockchain Traceability Implementation | Meets South Korean MFDS batch-level provenance mandates for beauty conglomerate shelf placement. |
| Geothermal Facility Conversion | Addresses EU F-Gas Regulation 2027 compliance deadlines for Baltic Sea processors. |
| Direct-to-Brand Distribution Buildout | Captures margin from US nutraceutical startups seeking bypass of traditional ingredient distributors. |
Research Approach
Direct dialogue with extraction plant managers, cosmetic formulation chemists, regulatory affairs leads at MFDS-registered suppliers, and procurement directors at South Korean beauty conglomerates grounded qualitative assessment. Secondary validation drew from ECHA REACH substance registrations, FDA GRAS notification filings, FAO/WHO Codex Alimentarius specifications, and EU organic aquaculture standard revision documents. Bottom-up and top-down triangulation reconciled facility-level capacity estimates with trade flow data across the analysis window.
Bottom-up modeling segmented volume and value outputs across product type, application, end user, and certification tier dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic demand drivers. Industry-specific forecast inputs included wild-harvest biomass yield assumptions, solvent residue limit convergence scenarios between EMA and FDA, and MFDS-ECHA registration reciprocity timeline projections.
Caveats apply where EU organic aquaculture standard revision delays, phycologist workforce scarcity constraints, or EMA-FDA solvent residue divergence could materially shift the outlook. Forecasts reflect assumptions about harvest window stability, certification timeline compression, and clean-label hydrocolloid substitution velocity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Belladonna Market
Extracts
Natural Rosemarine Extract Market
Extracts
Flower Extract Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
Global Marigold Flower Extract Market
Extracts
Asia-Pacific Spirulina Extract Market
Extracts
Sage Extract Market
Extracts
Peppermint Oil Market
Extracts
Marigold Essential Oil Market
Extracts
Sandalwood Oil Market
Extracts
Turpentine Market
Extracts
Pectinase Market
Extracts
Chlorophyll Extract Market
Extracts
Asia-Pacific Mineral Turpentine Market
Extracts
Marine Algae Polysaccharides Market
Extracts
Eucommia Extract Market