
 Podcast Market | 2026-2036
Podcast Market Size, Share, and Industry Trends Forecast 2026-2036
Podcast Market Insights
Platform bundling of podcasts with music streaming and audiobook subscriptions is broadening listener acquisition channels beyond standalone podcast apps. Spotify AB leverages its exclusive content deals to anchor listener retention across audio formats. Apple Inc. sustains ecosystem lock-in through native podcast distribution pre-installed on iOS devices. Amazon.com, Inc. competes by integrating podcast access into Prime membership infrastructure, blurring boundaries between retail loyalty and audio consumption.
A podcast is an episodic digital audio program distributed through RSS feeds or proprietary platforms, typically encoded in MP3 or AAC formats with bit rates ranging from 64 to 128 kbps for spoken content, designed for on-demand consumption during commuting, exercise, or passive leisure. The monetization model segment reveals that advertising sponsorships still dominate revenue flows, though subscription tiers are capturing margin pools as listeners accept paywalled premium content. Distribution through streaming platforms concentrates audience reach, while direct download channels retain importance for independent creators seeking platform independence.
The Federal Communications Commission exercises indirect influence through broadcast ownership rules that push traditional radio talent toward unregulated podcast channels, while the Federal Trade Commission scrutinizes native advertising disclosures in sponsored episodes. The EU's Digital Services Act and GDPR compliance requirements are reshaping how platforms collect listener data for targeted ad insertion across European markets. Stakeholders must monitor regulatory fragmentation between privacy-first jurisdictions and markets permitting granular ad targeting, as this divergence will determine where monetization technology investments yield returns.
Market Dynamics
AI-driven transcription and recommendation engines are compressing content discovery cycles while fragmenting listener attention across proprietary platforms. Entertainment conglomerates now treat podcast libraries as strategic IP assets, reshaping how audio content is produced, distributed, and monetized.
Growth Catalysts
- Platform Bundling:Music streaming services now integrate podcast access into subscription tiers, lowering acquisition costs for new listeners. This cross-format anchoring expands addressable audiences beyond standalone podcast applications.
- FCC Broadcast Rules:The Federal Communications Commission's ownership restrictions push traditional radio talent toward unregulated podcast channels, flooding the medium with professional production expertise and established audiences.
- AI Transcription:Automated speech-to-text tools enable searchable episode archives, accessibility compliance, and programmatic ad insertion at scale.
Market Restraints
- Platform Dependency:Independent creators face algorithmic visibility constraints on Spotify and Apple Podcasts, concentrating audience reach within walled-garden ecosystems.
- GDPR Compliance:The EU's General Data Protection Regulation restricts granular listener data collection for targeted advertising across European markets.
- Audio-Only Limitations:Spoken-word content lacks the visual engagement layers that video platforms deploy for retention, capping session durations relative to competing media formats.
Strategic Opportunities
- Subscription Tiers:Paywalled premium content captures margin pools as listener willingness to pay for exclusive episodes matures in the United States.
- Prime Integration:Amazon's bundling of podcast access with retail loyalty infrastructure creates hybrid monetization models linking audio consumption to e-commerce behavior.
- EU Digital Services Act:Transparency requirements for recommendation algorithms create openings for compliant independent platforms to differentiate on editorial independence.
Industry Challenges
- Native Advertising Disclosure:The Federal Trade Commission scrutinizes sponsored episode labeling, forcing production teams to navigate disclosure timing without disrupting narrative flow.
- RSS Feed Fragmentation:Proprietary distribution systems erode the open syndication standard, complicating multi-platform publishing workflows for mid-sized studios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Podcast Market |
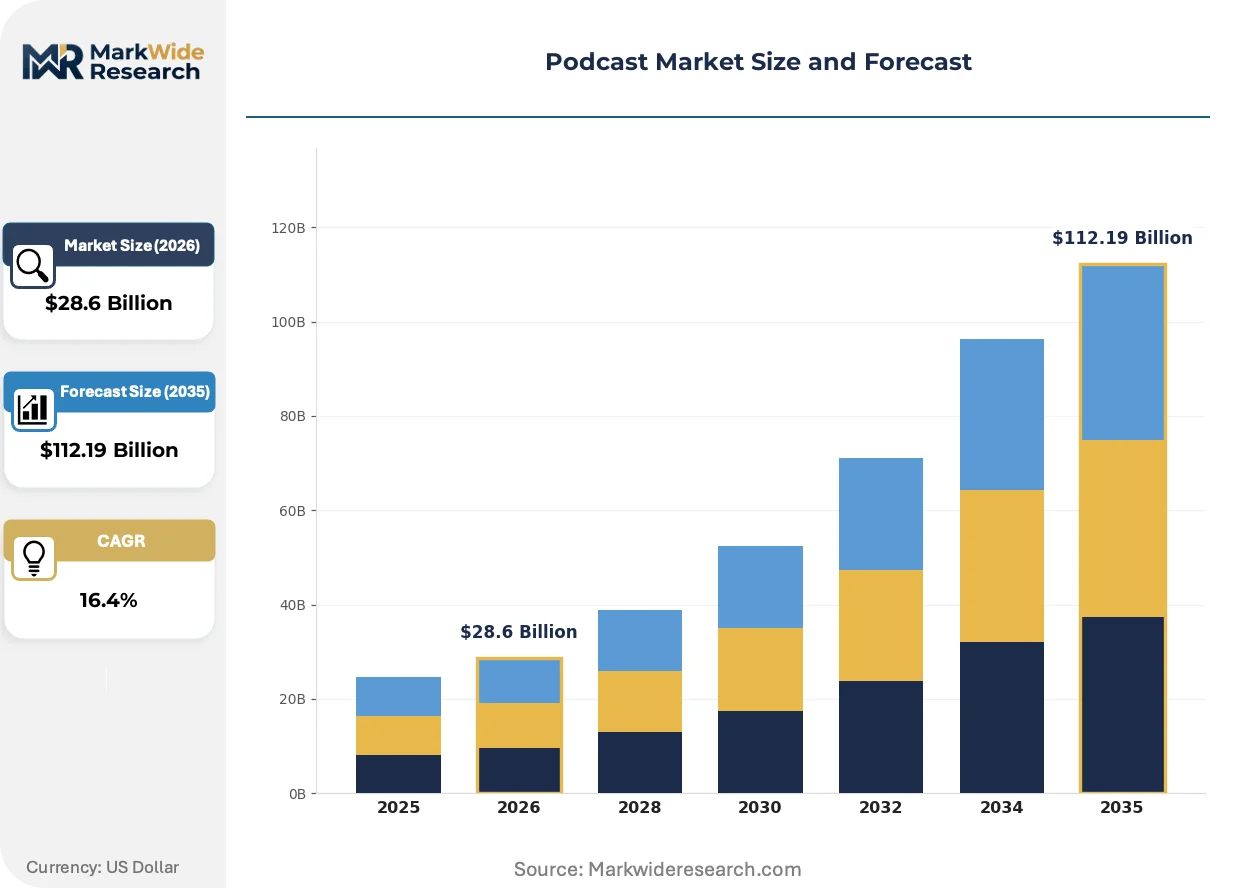
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Genre: Technology, Comedy, Health, True Crime Monetization Model: Subscription, Sponsorship, Ads, Crowdfunding Distribution Channel: Streaming Platforms, Social Media, Direct Download, Aggregator Sites Target Audience: Millennials, Professionals, Students, Parents |
| Companies Covered | Spotify AB, Apple Inc., iHeartMedia Inc., Amazon.com, Inc., Libsyn, Acast, NPR, SoundCloud Limited, TuneIn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Podcast Market Trends and Innovations
Content production workflows and monetization mechanics are diverging sharply between privacy-first jurisdictions and markets permitting granular ad targeting. This regulatory fragmentation is forcing platform architecture decisions that will lock in competitive positions for the forecast window.
Generative AI tools for automated editing, synthetic voice cloning, and dynamic ad insertion are rewriting production economics for independent creators. Mid-tier studios now deploy these tools to compress post-production timelines from days to hours. The structural consequence is a supply surge of lower-cost content that pressures CPM rates for undifferentiated programming.
The EU's Digital Services Act imposes algorithmic transparency obligations on platforms with significant reach, compelling Spotify and Apple to disclose ranking factors for podcast recommendations. European regulators now audit these systems for discriminatory amplification patterns. Smaller platforms in Germany and France are responding by marketing human-curated discovery as a compliance-light alternative.
Listener attention is fragmenting toward short-form audio clips distributed through TikTok and YouTube Shorts, displacing full-episode consumption among audiences under 35. Podcast studios now produce excerpt-native content rather than repurposing long-form episodes. This behavioral shift is most visible in the United States, where creator economy infrastructure supports rapid format experimentation.
Podcast Market Segmentation
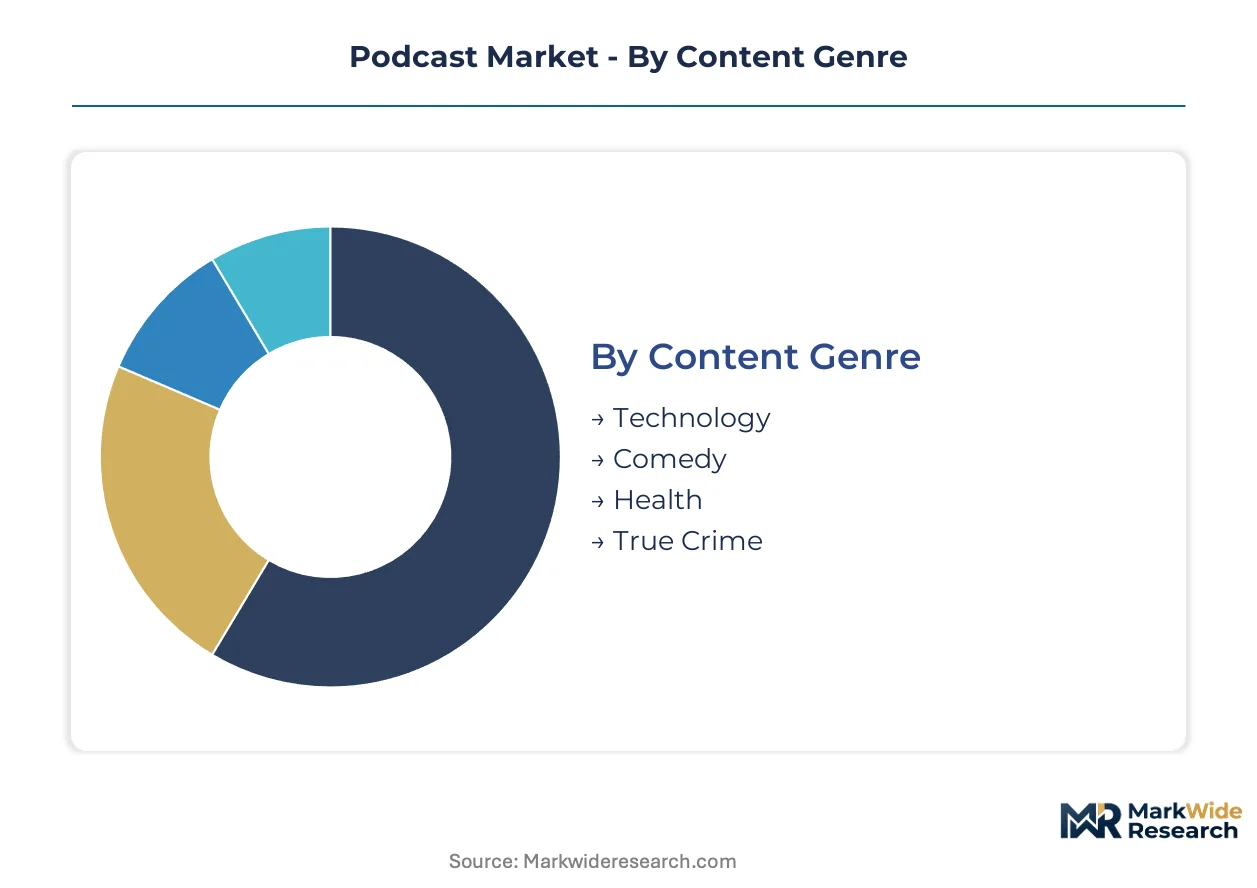
Podcast segmentation reveals how listener preferences and revenue mechanics split across content types and access methods. Genre selection drives platform investment priorities. Monetization paths determine which creators capture sustainable economics versus dependence on algorithmic distribution.
Content Genre:
Listener acquisition costs vary sharply by genre, with retention economics favoring serialized formats over episodic programming.
- Technology:Deep-dive interviews and product analysis episodes attract affluent, advertiser-desirable demographics. Demand concentrates among software engineers and venture capital professionals in the United States, where B2B sponsorship rates exceed consumer categories by substantial margins.
- True Crime:Narrative investigative series generate the highest episode completion rates and seasonal binge consumption. Production investment is climbing fastest here as studios compete for exclusive access to law enforcement sources and victim families.
- Comedy:Conversational formats with established entertainers anchor platform exclusivity deals. Listener loyalty attaches to host personality rather than production value.
- Health:Wellness and medical advice content faces elevated liability exposure and platform content moderation scrutiny. Credibility signaling through clinician credentials shapes audience trust.
True Crime leads on scale; Technology leads on momentum.
Monetization Model:
Revenue stability depends on diversification across recurring and transactional income streams.
- Sponsorship:Host-read advertisements command premium CPMs based on audience trust transfer and demographic targeting precision. Mid-roll insertion technology now enables dynamic ad replacement based on listener location and device type.
- Subscription:Paywalled premium feeds and early access windows capture margin pools from committed audiences. The model works best for creators with established parasocial relationships built through years of free distribution.
- Ads:Programmatic insertion through demand-side platforms scales revenue for high-volume publishers but commoditizes inventory and depresses rates. Auction dynamics favor platforms with proprietary listener data over independent RSS distribution.
- Crowdfunding:Patreon-style membership and one-time donations sustain niche programming outside commercial viability thresholds. This path attracts creators with ideological or artistic motivations that resist advertiser influence.
Sponsorship leads on scale; Subscription leads on momentum.
Distribution Channel:
Reach concentration versus creator independence defines platform selection tradeoffs.
- Streaming Platforms:Spotify and Apple Podcasts concentrate audience discovery through algorithmic recommendation and pre-installed app penetration. Exclusive licensing deals lock premium content behind proprietary walls, fragmenting the open RSS ecosystem.
- Social Media:TikTok and YouTube Shorts distribute excerpt clips that drive full-episode conversion among under-35 audiences. Clip-native production now precedes long-form recording in many studio workflows.
- Direct Download:RSS feed subscriptions and website-hosted files preserve creator control over listener relationships and data. This channel retains importance for independent publishers and subscription-first business models.
- Aggregator Sites:Third-party directories and newsletter-curated recommendations surface content outside platform algorithms. Editorial curation builds trust with audiences fatigued by automated suggestions.
Streaming Platforms lead on scale; Social Media leads on momentum.
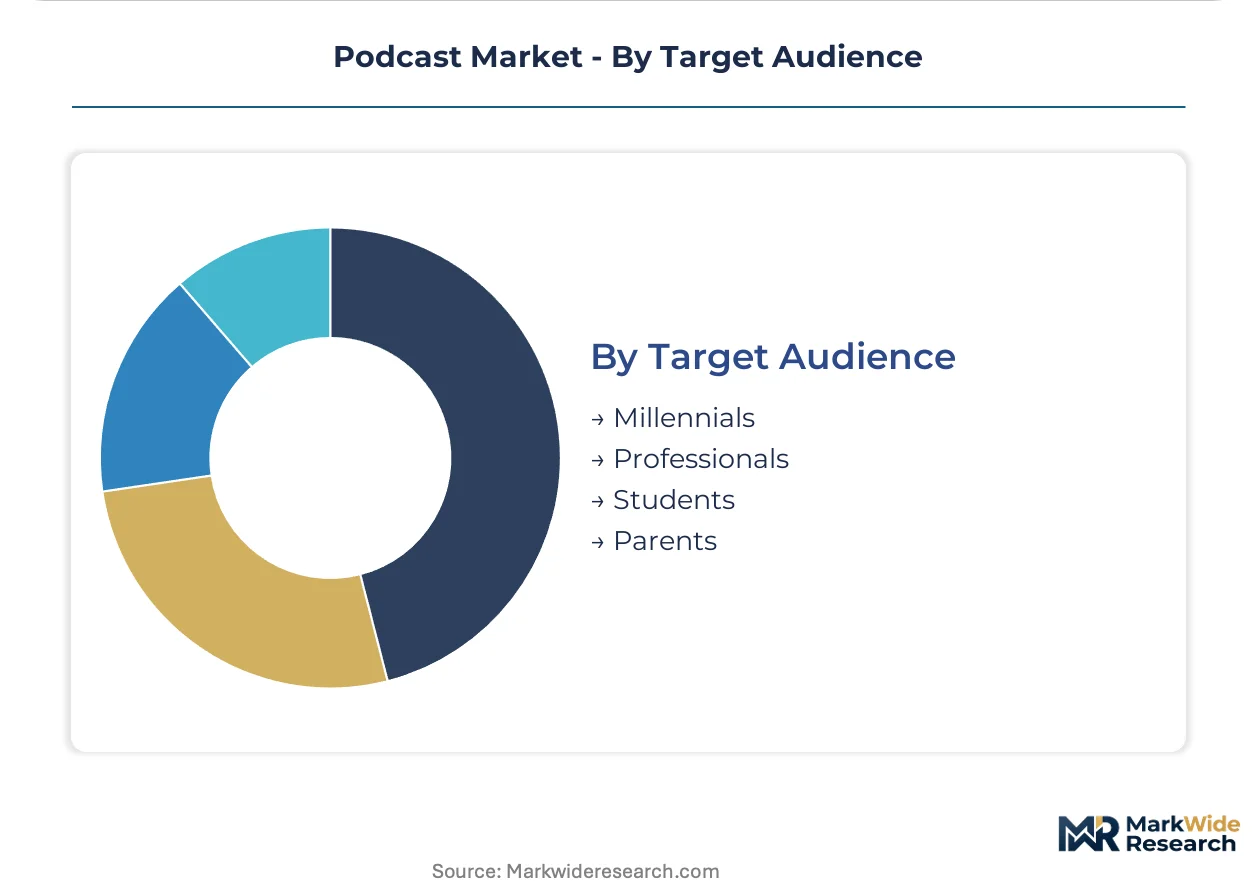
Target Audience:
Demographic concentration determines advertising verticals and content format investments.
- Millennials:This cohort maintains the highest podcast consumption hours per week and strongest willingness to pay for premium subscriptions. Content preferences span interview formats, investigative journalism, and personality-driven comedy.
- Professionals:Commute and exercise listening patterns favor business, technology, and self-improvement genres. B2B advertising verticals target this segment with enterprise software and professional services messaging.
- Students:Educational and career preparation content attracts this price-sensitive segment. Free ad-supported tiers dominate; subscription conversion requires substantial value demonstration.
- Parents:Childcare and family management podcasts capture dedicated but time-constrained listening windows. Episode length compression and topic segmentation address interrupted consumption patterns.
Millennials lead on scale; Professionals lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Podcast distribution infrastructure first achieved commercial scale in the United States during the mid-2000s, when RSS syndication protocols enabled independent creators to bypass traditional broadcast gatekeepers. The medium's monetization architecture matured through successive waves of advertising technology investment concentrated in North American and European metropolitan markets.
United States
Creator economy infrastructure and advertising technology investment anchor podcast monetization at scale. The Federal Communications Commission's broadcast ownership restrictions push traditional radio talent toward unregulated podcast channels, flooding the medium with professional production expertise. Los Angeles and New York City host the densest concentrations of podcast studios and talent representation agencies.
Germany
Public media investment and audio journalism tradition sustain high production-value content creation. The EU's Digital Services Act imposes algorithmic transparency obligations on platforms with significant reach, compelling disclosure of recommendation ranking factors. Berlin anchors the country's independent podcast production cluster, with studios concentrated in the Kreuzberg and Neukölln districts.
United Kingdom
London's media ecosystem bridges American production formats with European regulatory compliance requirements. Ofcom exercises indirect influence through broadcast licensing frameworks that shape talent migration patterns toward podcast channels. The city's Soho and Shoreditch neighborhoods concentrate boutique production houses serving both domestic and export markets.
Sweden
Streaming platform headquarters location and early podcast platform investment created specialized technical talent pools. The Swedish Authority for Privacy Protection enforces GDPR compliance standards that restrict granular listener data collection for targeted advertising. Stockholm's Södermalm district hosts engineering teams developing transcription and recommendation algorithms.
Australia
English-language content export orientation and timezone advantages for Asian market scheduling support international distribution strategies. The Australian Communications and Media Authority monitors native advertising disclosure standards in sponsored content. Sydney and Melbourne sustain the domestic production base, with creators leveraging Commonwealth cultural ties for UK and North American market access.
Podcast Market Competitive Landscape
Premium-margin players sit above commodity-margin players across content exclusivity and proprietary data dimensions. The market structures around three tiers: streaming platforms with exclusive licensing deals, open-distribution infrastructure providers, and public media organizations with established audience trust. Platform consolidation and algorithmic recommendation system investment constitute the dominant competitive moves reshaping audience capture dynamics.
Among streaming-platform operators, Spotify AB and Apple Inc. exemplify the exclusive-content archetype, while Amazon.com, Inc. occupies a position integrating audio consumption with broader membership infrastructure. These three entities anchor competitive positioning through divergent ecosystem strategies rather than direct feature parity.
| Leading Market Players |
|---|
| Spotify AB |
| Apple Inc. |
| iHeartMedia Inc. |
| Amazon.com, Inc. |
| Libsyn |
| Acast |
| NPR |
| SoundCloud Limited |
| TuneIn |
| Others |
Pricing and Supply Chain Analysis
Exclusive content licensing bifurcation between premium studio productions and independent creator catalogs manifests in divergent monetization architectures and distribution infrastructure investments. This split concentrates production expenditure in Los Angeles and New York City while fragmenting hosting and analytics services across specialized vendors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates podcast monetization. Host-read sponsorships command premium CPMs based on audience trust transfer and demographic precision, while programmatic insertion commoditizes inventory. Cost compression in ad-supported tiers intensifies because generative AI tools flood supply with lower-cost content. Independent creators show highest price sensitivity; platform-exclusive studios with established parasocial relationships demonstrate lowest.
Supply Chain Analysis
Direct-to-creator platforms handle independent publisher demand through RSS infrastructure and subscription management tools. Content production concentrates in the United States, the United Kingdom, and Sweden, with technical development anchored in Stockholm engineering clusters. Raw material dependencies span audio engineering talent, cloud hosting services, and transcription API access. Single-source vulnerability runs through proprietary recommendation algorithms controlled by dominant streaming platforms. Distribution runs through streaming applications, social media excerpt channels, and direct download feeds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Digital Services Act functions as a regulatory compounder, mandating algorithmic transparency that creates compliance costs for incumbents while opening differentiation paths for challengers.
For Market Incumbents: Lock in exclusive talent relationships through multi-year licensing deals before GDPR enforcement tightens data-dependent targeting. Vertical integration into transcription and synthetic voice technology preserves margin pools against AI-driven production cost deflation. Platform dependency among independent creators threatens supply-side leverage; preemptive revenue-sharing improvements deflect regulatory scrutiny.
For New Entrants and Emerging Players: Social media clip distribution offers the most penetrable route for audience acquisition among under-35 demographics fatigued by algorithmic recommendations. Target podcast studios seeking platform independence through transparent RSS-based analytics and direct listener relationship tools. Position against walled-garden concentration by marketing editorial curation as a compliance-light alternative under EU transparency mandates.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier studios lack proprietary data assets to sustain CPM premiums against programmatic commoditization. Long-term viability favors targets with established parasocial audiences convertible to subscription revenue. Watch for inflection signals in FCC broadcast ownership rule enforcement that accelerate traditional radio talent migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Content Licensing | Spotify and Apple anchor listener retention through talent lock-in agreements. |
| AI Production Integration | Automated editing and synthetic voice cloning compress post-production timelines for studios. |
| Subscription Tier Expansion | Paywalled premium feeds capture margin pools from committed parasocial audiences. |
| Algorithmic Transparency Compliance | EU Digital Services Act mandates disclosure of recommendation ranking factors. |
| Social Media Clip Distribution | TikTok and YouTube Shorts drive full-episode conversion among fragmented attention. |
Research Methodology
Multiple input streams — executive interviews with podcast studio heads, platform strategy leads, and advertising technology vendors — were reconciled against secondary validation from FCC regulatory filings, EU Digital Services Act implementation guidance, and streaming platform financial disclosures. Bottom-up triangulation across content production cost structures and top-down analysis of advertising technology investment flows anchored market sizing.
Historical consumption pattern analysis cross-referenced against panel input from creator economy participants informed projection modeling. Segmentation dimensions spanned content genre, monetization model, distribution channel, and target audience demographics. CAGRs derived from trend extrapolation weighted by regulatory milestone timing and technology adoption curves. AI transcription deployment rates and subscription conversion benchmarks served as industry-specific forecast inputs across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for generative AI content production would alter the outlook. Forecasts reflect base-case assumptions regarding GDPR enforcement consistency and FCC broadcast rule stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Radio and Audio Media
Microphone Market
Radio and Audio Media
Voice Over New Radio Market
Radio and Audio Media
FM Transmitters Market
Radio and Audio Media
Audiobooks Market
Radio and Audio Media
Podcasting Market
Radio and Audio Media
Audio Mixing Console Market
Radio and Audio Media
Global 3D Audio Market
Radio and Audio Media
Podcast Hosting Services Market
Radio and Audio Media
Podcast Advertising Market
Radio and Audio Media
Radio Advertising Market
Radio and Audio Media
Internet Radio Market
Radio and Audio Media
Latin America Soundbar Market
Radio and Audio Media
Global Professional Audio Market
Radio and Audio Media
Digital Audio Market
Radio and Audio Media
Traditional Radio Advertising Market